
 Nutrition Therapy Market | 2026-2036
Nutrition Therapy Market Size, Share, and Industry Trends Forecast 2026-2036
Nutrition Therapy Market Outlook
Asset-light leasing models for enteral feeding equipment and home infusion pumps are rewriting competitive entry barriers across the nutrition therapy landscape. Fresenius Kabi leverages its vertically integrated parenteral nutrition manufacturing to dominate hospital procurement channels. Abbott Laboratories anchors its position through extensive R&D investment in disease-specific nutritional formulations. Baxter International competes through specialized intravenous lipid emulsion technologies that serve critical care segments.
Nutrition therapy encompasses the clinical application of medically formulated nutrients—amino acids, lipids, carbohydrates, vitamins, and trace elements delivered via enteral tubes or intravenous infusion—to treat or prevent malnutrition and support metabolic recovery in patients unable to consume adequate oral intake. These formulations require precise osmolarity control, sterility assurance, and compatibility testing to prevent adverse reactions during administration. Protein Supplements and Ready-to-Drink delivery modes command the largest revenue pools due to their convenience in hospital and homecare transitions, while Chronic Disease Management applications generate premium pricing through condition-specific clinical validation. Herbal Remedies occupy a smaller but expanding niche as regulatory frameworks gradually accommodate botanical evidence standards.
The FDA oversees medical food and enteral product safety through post-market surveillance and current Good Manufacturing Practice enforcement, while the EMA's Nutrition and Health Claims regulation shapes permissible marketing across European jurisdictions. The USDA's National Organic Program and FSSAI's functional food standards in India further fragment compliance requirements for multinational portfolios. Stakeholders must monitor evolving reimbursement codes from CMS and parallel agencies, as coverage determinations increasingly tie nutrition therapy access to demonstrated clinical outcomes rather than diagnostic category alone.
Market Dynamics
Hospital procurement consolidation and CMS reimbursement code expansion are compressing margins for standalone nutrition therapy suppliers while rewarding vertically integrated manufacturers with captive sterile compounding capabilities.
Growth Catalysts
- CMS Medical Nutrition Therapy Coverage:Expanded Medicare Part B reimbursement for diabetes and renal disease management is pulling eligible patients into supervised clinical nutrition programs across United States outpatient clinics.
- Enteral Feeding Pump Leasing:Asset-light equipment financing models are lowering capital barriers for home health agencies entering parenteral nutrition service lines.
- Clean Label Formulation Mandates:FDA's updated Nutrition Facts panel requirements are forcing manufacturers to reformulate with transparent ingredient sourcing and reduced additive loads.
Market Restraints
- Soybean Oil Input Volatility:Intravenous lipid emulsion production depends on refined soybean oil feedstock subject to agricultural commodity price swings and export restriction risks from major suppliers.
- Sterile Compounding Concentration:Hospital outsourcing of parenteral nutrition admixture preparation to 503B compounders creates single-point-of-failure exposure in regional supply networks.
- EMA Health Claims Friction:European pre-market authorization requirements for disease-specific medical foods extend product launch timelines by 18-36 months versus comparable United States pathways.
Strategic Opportunities
- India Functional Food Standards:FSSAI's evolving regulatory framework for clinical nutrition products is opening formal channel access for medical food categories previously confined to informal pharmacy distribution.
- Chronic Disease Management Applications:Condition-specific formulations for sarcopenia, cancer cachexia, and pulmonary failure command premium pricing through demonstrated clinical outcome data.
- AI-Driven Personalized Nutrition:Machine learning integration with continuous glucose monitoring and microbiome profiling is enabling real-time formulation adjustment for individual metabolic responses.
Industry Challenges
- Clinical Dietetics Talent Scarcity:Hospital nutrition departments face recruitment gaps for registered dietitian nutritionists credentialed in parenteral and enteral therapy administration protocols.
- Multi-Jurisdiction Compliance Burden:Simultaneous adherence to FDA cGMP, EMA MDR, and FSSAI functional food standards fragments quality management systems and extends audit cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Nutrition Therapy Market |
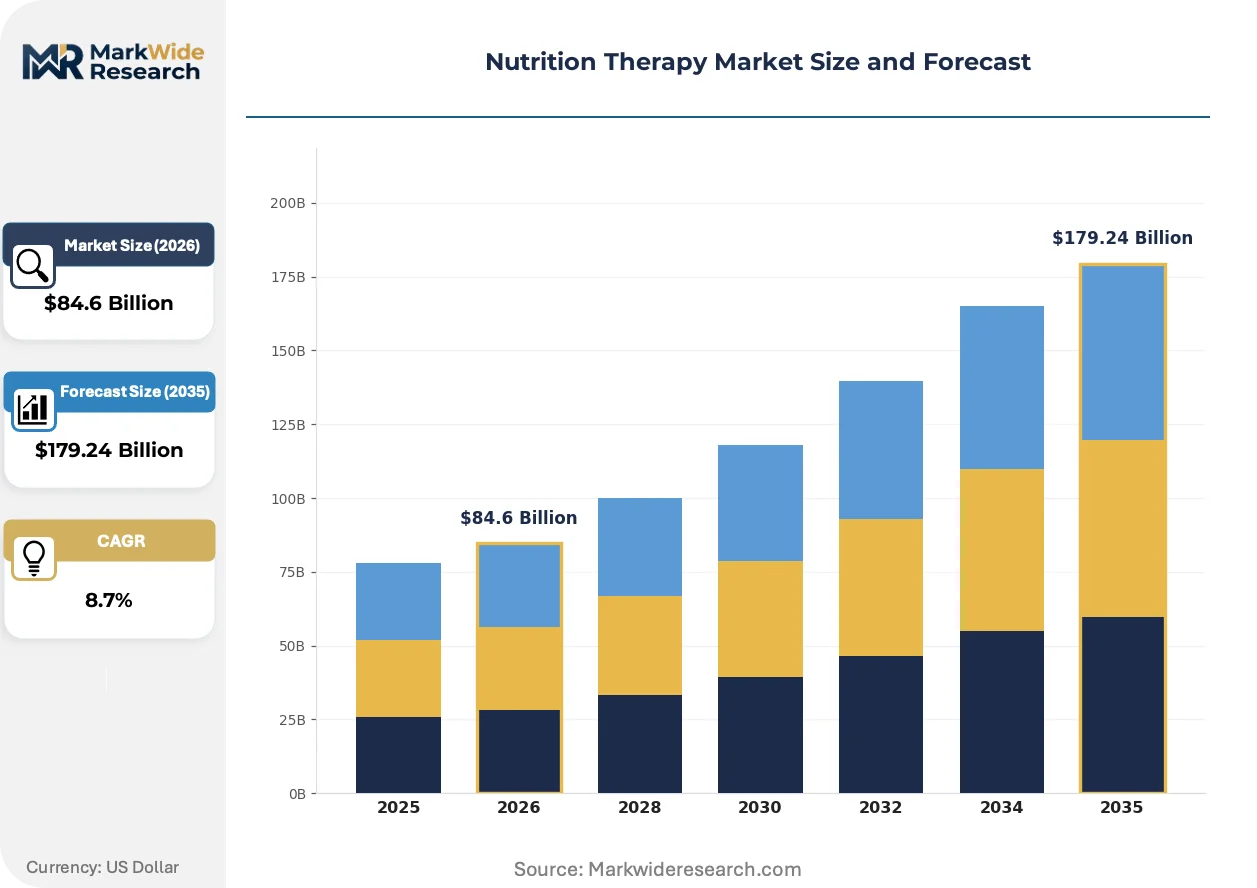
| Market Size in 2026 | $84.6 Billion |
| Market Size in 2035 | $179.24 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Protein Supplements, Vitamins, Herbal Remedies, Nutritional Bars Application: Weight Management, Sports Nutrition, Chronic Disease Management, Immune Support Delivery Mode: Powders, Liquids, Capsules, Ready-to-Drink End User: Hospitals, Athletic Organizations, Wellness Centers, Individuals |
| Companies Covered | Fresenius Kabi AG, Baxter International Inc., Abbott Laboratories, BASF SE, Ajinomoto Co., Inc., Nestlé Health Science, B. Braun SE, Arla Foods Ingredients Group P/S, Danone, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Nutrition Therapy Market Strategic Shifts
Precision compounding automation and real-time metabolic monitoring are collapsing the latency between patient assessment and customized nutrient delivery, shifting competitive advantage toward data-integrated service models.
Closed-system transfer devices for sterile parenteral nutrition admixture preparation are rendering obsolete open-bag compounding methods in hospital pharmacy cleanrooms. Large academic medical centers in the United States are mandating CSTD adoption for all high-risk sterile preparations. This technology compression is disqualifying smaller 503A compounders lacking capital for equipment upgrades.
REACH regulation amendments targeting persistent organic pollutants in medical device polymers are forcing enteral feeding tube manufacturers to reformulate PVC and DEHP plasticizers. European notified bodies are withholding CE marking for legacy material configurations. Suppliers with advanced biopolymer R&D programs are capturing redesign contracts from hospitals facing replacement mandates.
Hospital procurement departments are consolidating nutrition therapy purchasing into single-source agreements bundling enteral formulas, infusion pumps, and clinical support services. This concentration is displacing fragmented multi-vendor arrangements in United States health systems exceeding 500 beds. Integrated service contracts now predicate supplier selection on demonstrated readmission reduction metrics rather than unit pricing alone.
Nutrition Therapy Market Segmentation
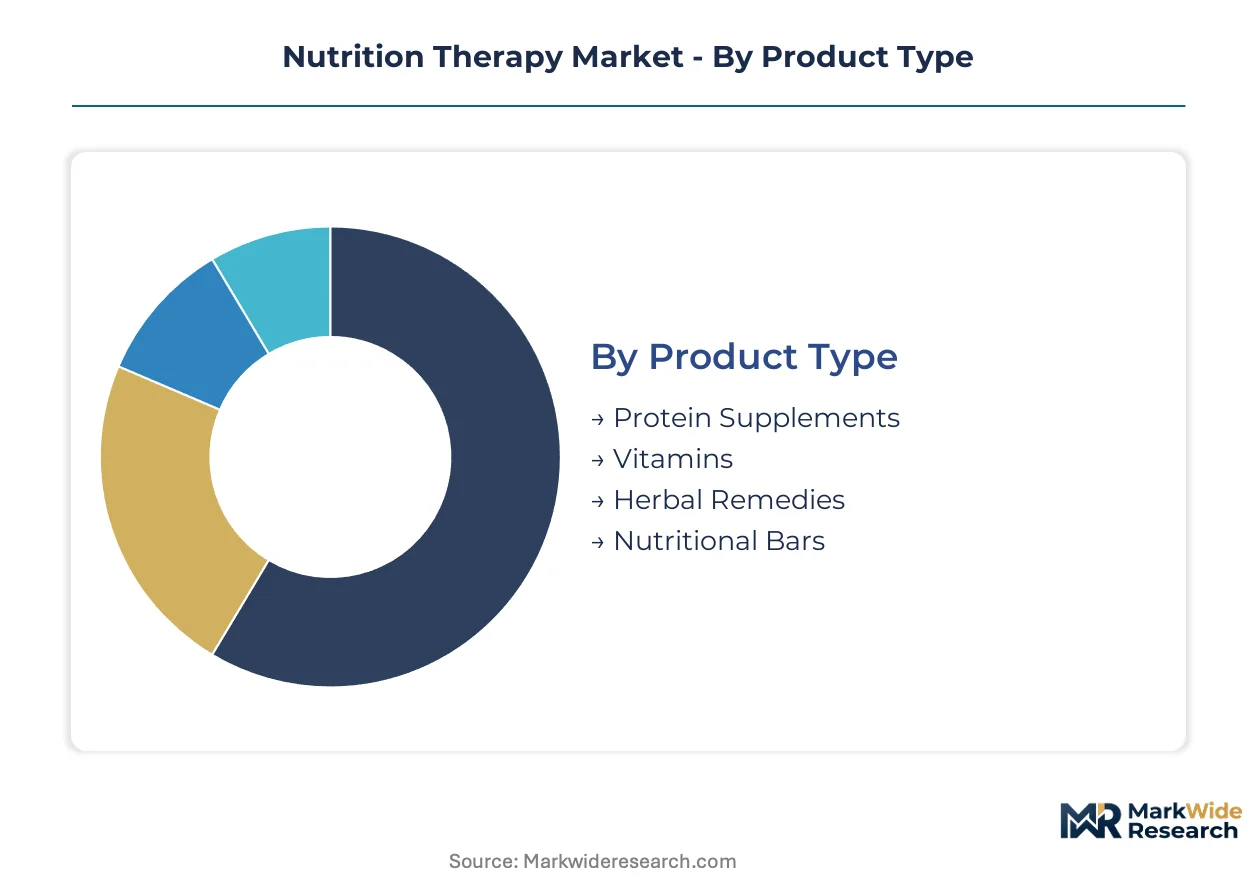
Segmentation in nutrition therapy reveals how formulation chemistry, administration route, and care setting interact to determine reimbursement eligibility and procurement patterns. Manufacturers configure product portfolios across these dimensions to match CMS coverage categories and hospital formulary requirements.
Product Type:
Cost tier stratification separates commodity macronutrients from condition-specific medical foods with clinical trial backing.
- Protein Supplements:Amino acid concentrates and hydrolyzed whey isolates deliver standardized nitrogen dosing for sarcopenia and post-surgical recovery protocols. Demand concentrates in United States skilled nursing facilities where CMS reimbursement ties protein provision to pressure ulcer prevention metrics.
- Vitamins:Micronutrient premixes address documented deficiencies in bariatric surgery and malabsorption syndromes with precise USP-grade potency certification. Hospital pharmacies in Germany and France prioritize vitamin formulations with EMA-authorized health claims for metabolic disorder management.
- Herbal Remedies:Botanical extracts with emerging clinical evidence for glycemic control and inflammation modulation occupy a regulatory gray zone between supplement and medical food categories.
- Nutritional Bars:Shelf-stable meal replacements with controlled glycemic index and complete amino acid profiles serve transition care from inpatient to home settings.
Protein Supplements holds installed capacity. Herbal Remedies is rotating up the share rankings.
Application:
Application segmentation maps directly to prescriber specialty and reimbursement code availability.
- Chronic Disease Management:Disease-specific formulations for diabetes, renal failure, and pulmonary disease carry medical food classification requiring FDA post-market surveillance and physician supervision. United States nephrology clinics drive volume through bundled payment models that include nutrition therapy.
- Weight Management:Very-low-calorie diets and meal replacement programs with structured behavioral support achieve durable outcomes in clinical versus commercial settings. Medicare Advantage plans in Florida and California have expanded coverage for medically supervised weight loss nutrition therapy.
- Sports Nutrition:Ergogenic aids and recovery formulations target athletic performance optimization with NSF Certified for Sport verification to prevent doping violations.
- Immune Support:Immunonutrition formulations with arginine, omega-3 fatty acids, and nucleotides target surgical and oncology patients with demonstrated infection risk reduction.
Chronic Disease Management commands premium positioning. Weight Management is climbing the fastest among application segments.
Delivery Mode:
Volume economics and sterility requirements create distinct manufacturing footprints across delivery formats.
- Ready-to-Drink:Aseptically processed liquid nutrition in tamper-evident packaging eliminates reconstitution errors and supports enteral tube feeding compatibility. United States long-term acute care hospitals specify ready-to-drink for ventilator-dependent patients to reduce aspiration risk.
- Powders:Spray-dried protein and carbohydrate blends offer cost-efficient bulk dosing with extended shelf stability for institutional procurement.
- Liquids:Concentrated enteral formulas requiring dilution provide flexible caloric density adjustment for pediatric and geriatric populations with fluid restrictions.
- Capsules:Encapsulated micronutrient and botanical delivery targets ambulatory patients with intact gastrointestinal function and preference for discrete dosing.
Ready-to-Drink holds installed capacity. Powders is rotating up the share rankings.
End User:
Customer type determines regulatory pathway, purchasing authority, and outcome accountability structure.
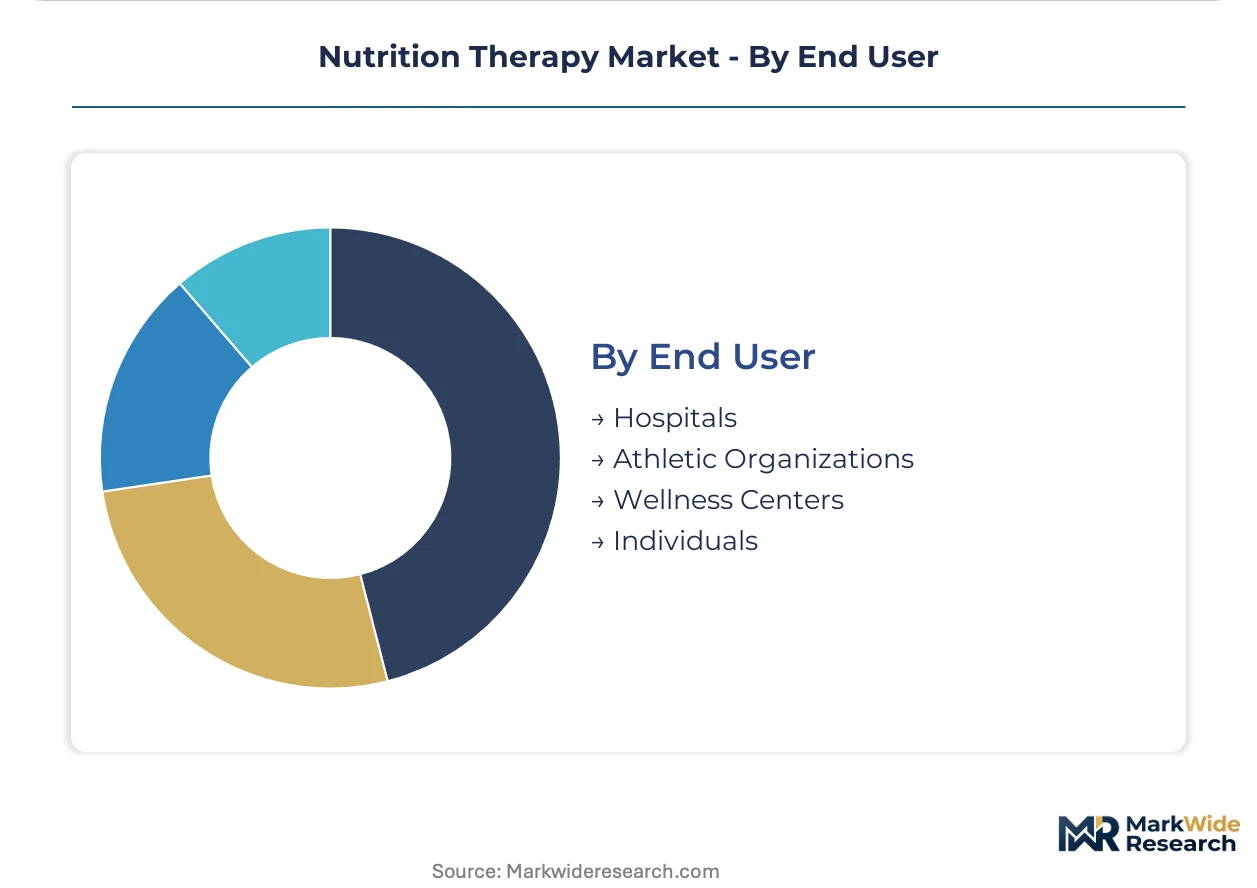
- Hospitals:Integrated health systems with centralized pharmacy and nutrition services negotiate formulary contracts based on readmission reduction data and supply chain reliability. Academic medical centers in Massachusetts and Texas mandate closed-system enteral delivery to prevent contamination events.
- Wellness Centers:Functional medicine and integrative health practices prescribe personalized nutrition protocols with laboratory monitoring of biomarker response.
- Athletic Organizations:Professional and collegiate sports programs source certified nutrition products through exclusive supplier agreements with batch-tested quality assurance.
- Individuals:Direct-to-consumer channels serve self-directed health optimization with subscription models for personalized supplement regimens.
Hospitals hold installed capacity. Wellness Centers is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Medicare reimbursement expansion for medical nutrition therapy is pulling patient volume into supervised clinical programs across multiple jurisdictions. Hospital procurement consolidation and regulatory divergence are reshaping competitive access by geography.
United States
CMS Medical Nutrition Therapy coverage for diabetes and renal disease management drives outpatient clinic demand. FDA post-market surveillance requirements for medical foods create compliance thresholds that favor established manufacturers. Academic medical centers in Massachusetts mandate closed-system enteral delivery protocols, displacing open-bag compounding methods.
Germany
Hospital pharmacy outsourcing to 503B compounders concentrates parenteral nutrition preparation in regional hubs. EMA Nutrition and Health Claims regulation shapes permissible marketing for disease-specific formulations. Industrial clusters in North Rhine-Westphalia host sterile compounding facilities serving cross-border hospital networks.
India
FSSAI functional food standards are formalizing channel access for medical nutrition categories previously confined to informal distribution. The country's national pharmaceutical regulator enforces quality benchmarks for enteral and parenteral products. Manufacturing concentrations in Maharashtra and Gujarat supply domestic hospital chains and export markets.
Japan
Aging demographics and extended hospital stays sustain demand for disease-specific nutritional formulations. PMDA oversees medical food safety through pre-market consultation pathways. Tokyo-based health systems integrate nutrition therapy into bundled payment models for chronic disease management.
United Kingdom
NHS procurement frameworks consolidate nutrition therapy purchasing into single-source agreements bundling formulas and clinical support. The country's national pharmaceutical regulator aligns with EMA standards for medical food classification. London teaching hospitals pilot AI-driven personalized nutrition protocols with real-time metabolic monitoring.
Nutrition Therapy Market Competitive Environment
On the supply side, the industry is consolidating around vertically integrated manufacturers with captive sterile compounding capabilities and hospital procurement channel dominance. Three archetypes define competitive positioning: pharmaceutical-grade compounders with parenteral expertise, diversified nutrition conglomerates with R&D scale, and specialized enteral equipment lessors with asset-light service models. M&A activity targets regional 503B compounders, while portfolio diversification into condition-specific medical foods represents the second dominant competitive vector.
Among the vertically integrated pharmaceutical compounders, Fresenius Kabi AG exemplifies the archetype through its in-house production of parenteral nutrition components. Baxter International Inc. and Abbott Laboratories occupy positions within the diversified nutrition technology tier, with the former representing specialized intravenous lipid emulsion capabilities and the latter anchoring disease-specific formulation development. These three entities collectively illustrate how supply-side concentration rewards manufacturers combining manufacturing scale with regulatory navigation expertise.
| Leading Market Players |
|---|
| Fresenius Kabi AG |
| Baxter International Inc. |
| Abbott Laboratories |
| BASF SE |
| Ajinomoto Co., Inc. |
| Nestlé Health Science |
| B. Braun SE |
| Arla Foods Ingredients Group P/S |
| Danone |
| Others |
Value Chain & Pricing Dynamics
Refined soybean oil concentration in Argentina and Brazil directly determines margin distribution across intravenous lipid emulsion manufacturers, with pharmaceutical-grade certification requirements capturing value downstream from commodity feedstock suppliers.
Pricing Analysis
Certification level creates the primary spread between pharmaceutical-grade parenteral formulations and standard enteral products, with FDA-grade sterile compounding commanding premiums over FSSAI-registered alternatives. Three-tier pricing structure separates medical food classifications from dietary supplements and commodity nutritionals, with volume scale discounts compressing margins for hospital GPO contracts. Pricing pressure stems from CMS reimbursement rate stagnation against input cost inflation, squeezing compounder profitability. Home health agencies exhibit highest price sensitivity due to thin Medicare margins, while academic medical centers prioritize supply reliability over unit cost.
Supply Chain Analysis
Extended payment terms from hospital procurement departments now stretch to 90-120 days, forcing compounders to rely on supply-chain finance facilities from institutional lenders. Manufacturing concentrates in the United States, Germany, and India, with sterile compounding facilities clustering near major hospital networks. Production draws from refined soybean oil, amino acid precursors, and USP-grade micronutrients, with single-source vulnerability concentrated in lipid emulsion feedstock. Tariff exposure on Chinese-sourced vitamins and minerals threatens cost stability. Distribution runs through 503B regional compounders, GPO contract channels, and direct hospital pharmacy relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The nutrition therapy market exhibits cyclical recovery characteristics driven by CMS reimbursement expansion for diabetes and renal disease management, pulling patient volume into supervised clinical programs.
For Market Incumbents: Entrench formulary position through captive sterile compounding capacity in North Rhine-Westphalia and Massachusetts corridor hospitals. Acquire regional 503B compounders facing CSTD equipment upgrade mandates to eliminate competitor supply options. Deepen backward integration into amino acid precursor manufacturing to offset soybean oil volatility exposure.
For New Entrants and Emerging Players: Establish a beachhead in India's FSSAI-compliant functional food segment before formal channel access fully consolidates. Target wellness center prescribing networks with AI-driven personalized nutrition platforms. Pursue white-label manufacturing partnerships with existing compounders lacking digital capabilities.
For Investors and Strategic Acquirers: Capital is best deployed toward mid-scale compounders with 503B registration and hospital GPO contract relationships. Long-term viability hinges on reimbursement policy continuity and clinical outcome data generation. Watch for CMS coverage expansion into sarcopenia and cancer cachexia as inflection signals for premium formulation demand.
| Strategic Initiative | Industry Significance |
|---|---|
| Closed-System Transfer Device Adoption | Academic medical centers in Massachusetts mandate CSTD protocols, eliminating open-bag compounders. |
| Backward Integration into Lipid Emulsion Feedstock | Captive soybean oil refining insulates margins from Argentine export restriction volatility. |
| AI-Driven Personalized Nutrition Platform | Continuous glucose monitoring integration enables real-time formulation adjustment for metabolic response. |
| FSSAI Registration Pathway Investment | Formal channel access in India captures medical food categories from informal pharmacy distribution. |
| Hospital System Partnership Consolidation | Single-source bundling contracts predicate supplier selection on readmission reduction metrics. |
Study Parameters
Cross-validation between hospital procurement database analysis and CMS reimbursement code tracking anchors the qualitative findings. Primary interviews with registered dietitian nutritionists, hospital pharmacy directors, 503B compounder operations managers, and GPO contract specialists were combined with secondary validation from FDA medical food registrations, EMA health claim submissions, FSSAI functional food notifications, and hospital formulary databases. Bottom-up volume modeling and top-down expenditure reconciliation triangulate market size estimates.
Calibration against historical reimbursement expansion patterns and sterile compounding capacity utilization informs the analytical framework across the projection horizon. Segmentation dimensions include product type, application, delivery mode, and end user, with regional regulatory clusters modeled separately. CAGRs derive from fitted trend extrapolation adjusted for policy intervention timing. Forecast inputs incorporate CMS coverage determination pipelines and 503B facility inspection outcomes.
Stress conditions across soybean oil price volatility, reimbursement rate revision, and regulatory approval timeline extension were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about policy continuity and clinical evidence accumulation. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nutritional Supplements
Asia-Pacific Arachidonic Acid Market
Nutritional Supplements
Nutritional Drink Market
Nutritional Supplements
Melatonin Supplements Market
Nutritional Supplements
Phytoceramide Supplement Market
Nutritional Supplements
Whey Protein Concentrate Market
Nutritional Supplements
United States Vitamin D Supplements Market
Nutritional Supplements
Calcium Market
Nutritional Supplements
Marine Hydrolyzed Collagen Market
Nutritional Supplements
Asia-Pacific Feed Prebiotics Market
Nutritional Supplements
Zinc Supplement Market
Nutritional Supplements
Nutritional Yeast Market
Nutritional Supplements
Food Supplement OEM and ODM Market
Nutritional Supplements
L Carnitine Market
Nutritional Supplements
Health Ingredients Market
Nutritional Supplements
Horehound Supplement Market
Nutritional Supplements
Calcium Supplements Market