
 Africa Beta Glucan Market | 2026-2036
Africa Beta Glucan Market Size, Share, and Industry Trends Forecast 2026-2036
Africa Beta Glucan Market Outlook
REACH-equivalent chemical safety standards is shifting the cost-of-entry calculus for beta glucan importers across African markets. Kerry Group leverages its regional distribution infrastructure to sustain supply chain continuity in Southern Africa. Koninklijke DSM N.V. anchors its position through specialized yeast-derived beta glucan production tailored to local pharmaceutical specifications. Tate & Lyle PLC competes by extending its ingredient portfolio into functional food applications for emerging African consumer markets.
Beta glucan comprises a class of naturally occurring polysaccharides found in yeast cell walls, cereal grains, and fungal sources, with beta-1,3/1,6-glucan configurations exhibiting the highest immunomodulatory activity and typically requiring aqueous alkaline extraction for pharmaceutical-grade purity. These compounds function primarily as biological response modifiers, enhancing macrophage activation and cytokine production in therapeutic and nutraceutical formulations. Powder formulations dominate current manufacturing output due to superior stability profiles and extended shelf life in tropical climates, while immune support applications generate the strongest margin pools as clinical validation expands across African healthcare systems. Direct sales channels to pharmaceutical manufacturers are maturing fastest, reflecting buyer consolidation and volume contracting preferences among institutional purchasers.
South Africa's Department of Health, Nigeria's National Agency for Food and Drug Administration and Control, and Kenya's Pharmacy and Poisons Board each enforce distinct purity and labeling requirements that fragment compliance costs across regional suppliers. The absence of harmonized pan-African standards forces manufacturers to maintain multiple product specifications, elevating operational complexity for cross-border trade. Stakeholders must monitor regulatory convergence initiatives under the African Continental Free Trade Area framework to anticipate when unified testing protocols will reshape competitive barriers.
Market Dynamics
REACH-equivalent chemical safety standards are recalibrating the cost-of-entry calculus for beta glucan importers across African markets, forcing suppliers to absorb elevated compliance expenditures or exit cross-border trade entirely.
Growth Catalysts
- South Africa's updated food additive regulations:Tightened purity thresholds for imported polysaccharides are filtering out substandard suppliers and consolidating demand around certified producers capable of pharmaceutical-grade extraction.
- Yeast-derived beta glucan production:Specialized fermentation infrastructure in Southern Africa is enabling localized manufacturing that bypasses import tariff structures and reduces cold-chain dependency for temperature-sensitive biologicals.
- Nigeria's nutraceutical manufacturing corridor:Concentrated formulation activity around Lagos is generating sustained pull for immune-support raw materials as domestic brands scale production for West African distribution networks.
Market Restraints
- Input cost volatility:Cereal grain feedstock prices fluctuate with regional drought cycles, compressing margin predictability for oat and barley-derived beta glucan processors.
- Supply concentration risk:Aqueous alkaline extraction capacity clusters in South Africa and Egypt, creating single-point-of-failure exposure for pharmaceutical-grade material access across Sub-Saharan markets.
- Regulatory fragmentation:Divergent purity and labeling requirements enforced by South Africa's Department of Health, Nigeria's National Agency for Food and Drug Administration and Control, and Kenya's Pharmacy and Poisons Board multiply compliance costs for cross-border suppliers.
Strategic Opportunities
- Kenya's underpenetrated pharmaceutical manufacturing base:Nascent vaccine adjuvant production and expanding local drug formulation create first-mover positioning for beta glucan suppliers establishing East African technical service capabilities.
- African Continental Free Trade Area regulatory convergence:Unified testing protocols under negotiation will eventually collapse multi-jurisdiction compliance burdens and enable standardized product specifications across member states.
- Direct-to-manufacturer distribution channels:Bypassing traditional ingredient distributors through captive technical sales teams allows margin capture and formulation partnership depth with institutional pharmaceutical purchasers.
Industry Challenges
- Pharmaceutical-grade certification timelines:Extended validation periods for GMP-compliant facilities delay market entry and tie up working capital for emerging African producers.
- Specialized extraction technician scarcity:Limited regional expertise in aqueous alkaline processing for beta-1,3/1,6-glucan configurations constrains capacity expansion and quality consistency.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Africa Beta Glucan Market |
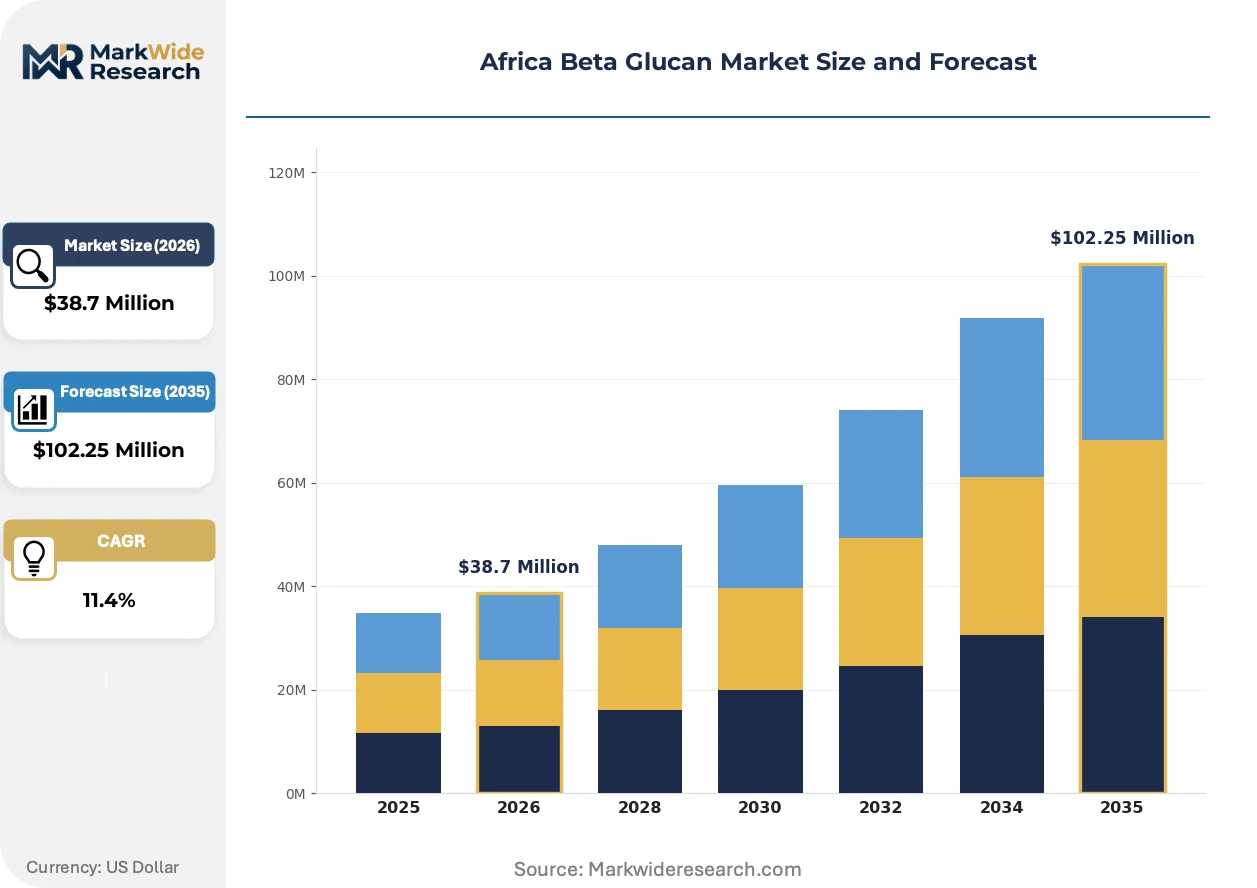
| Market Size in 2026 | $38.7 Million |
| Market Size in 2035 | $102.25 Million |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Powder, Liquid, Capsules, Tablets End User: Healthcare, Food and Beverage, Pharmaceuticals, Cosmetics Application: Immune Support, Cholesterol Management, Gut Health, Skin Care Distribution Channel: Online, Retail, Direct Sales, Distributors |
| Companies Covered | Kerry Group, Koninklijke DSM N.V., Tate & Lyle PLC, Lesaffre, Merck KGaA, Kemin Industries, Lallemand Inc., Alltech, Angel Yeast Co. Ltd, Others |
| Regions Covered | Africa: South Africa, Nigeria, Egypt, Kenya, Morocco, Ethiopia, Ghana, Algeria, Rest of Africa |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Africa Beta Glucan Market Strategic Shifts
Biotechnology-enabled production methods and shifting procurement architectures are compressing traditional supply hierarchies while elevating traceability and technical partnership expectations among African pharmaceutical formulators.
Microbial fermentation platforms for yeast-derived beta glucan are decentralizing production geography by enabling smaller-scale, distributed manufacturing facilities that reduce dependency on centralized extraction plants. Nigerian and Kenyan pharmaceutical formulators are adopting these systems at pilot scale to secure captive supply of immunomodulatory raw materials. This diffusion is compressing the traditional import-distributor-manufacturer value chain and enabling direct producer-buyer technical collaboration.
South Africa's Department of Health has tightened food additive purity thresholds for imported polysaccharides, forcing suppliers to upgrade analytical documentation and third-party certification portfolios. The regulatory pressure is elevating operational costs for uncertified traders while consolidating procurement relationships around established multinationals with existing compliance infrastructure. Pharmaceutical-grade beta glucan imports face the steepest documentation requirements, with raw material release timelines extending as local laboratories expand testing capacity.
Institutional pharmaceutical purchasers are consolidating ingredient procurement through volume contracting frameworks that bundle technical support, stability data, and regulatory documentation. This behavior shift is displacing spot-market purchasing through traditional distributors across Nigeria's Lagos manufacturing corridor and South Africa's Gauteng pharmaceutical cluster. The concentration of buyer power is compressing supplier margins while rewarding partners capable of integrated formulation support and pan-African regulatory navigation.
Africa Beta Glucan Market Segmentation
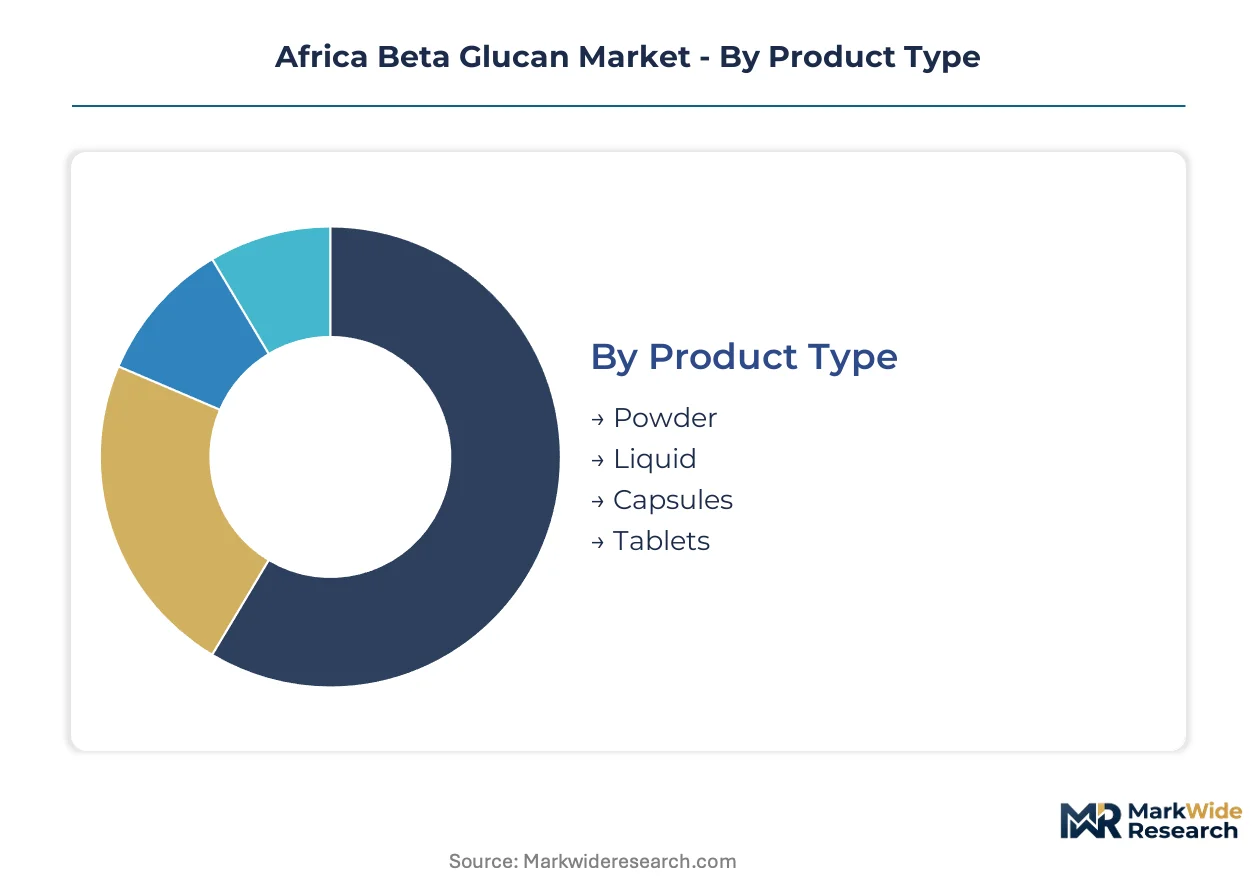
Beta glucan specifications diverge sharply across African markets, with tropical stability requirements and regulatory fragmentation driving format preferences. Procurement patterns concentrate around pharmaceutical-grade powder in South Africa and Nigeria, while direct sales channels capture institutional volume contracting.
Product Type:
Supply concentration in aqueous alkaline extraction infrastructure favors formats with extended shelf stability and lower cold-chain dependency across Sub-Saharan distribution networks.
- Powder:Dominates manufacturing output due to superior thermal stability profiles in tropical climates and compatibility with pharmaceutical-grade aqueous alkaline extraction protocols. Healthcare formulators in South Africa's Gauteng cluster specify powder for immune-support therapies requiring GMP-compliant material release.
- Liquid:Requires refrigerated logistics that constrain reach beyond major urban corridors, limiting adoption to Lagos and Johannesburg manufacturing facilities with captive cold-chain infrastructure. Nigeria's nutraceutical producers favor liquid for ready-to-drink formulation convenience despite higher distribution costs.
- Capsules:Appeals to direct-to-consumer nutraceutical brands targeting pharmacy retail in Kenya and Nigeria.
- Tablets:Compresses well with standard excipients but demands specialized tableting equipment rarely found outside South African contract manufacturers.
Powder absorbs the bulk of installed capacity; liquid is expanding most quickly among Nigerian beverage formulators.
End User:
Cost tier differentiation separates institutional pharmaceutical purchasers from price-sensitive food additive buyers, with certification requirements multiplying compliance expenditures at the premium end.
- Pharmaceuticals:Generates the strongest margin pools as clinical validation expands across African healthcare systems, with beta-1,3/1,6-glucan configurations specified for macrophage activation therapies. South Africa's Department of Health enforces the strictest purity thresholds, consolidating procurement around certified producers.
- Healthcare:Encompasses hospital and clinic procurement for patient immune support, with volume contracting frameworks displacing spot-market purchasing across Nigeria's Lagos corridor. Institutional buyers bundle technical support and stability data requirements.
- Food and Beverage:Faces compressed margins from cereal grain feedstock price volatility tied to regional drought cycles.
- Cosmetics:Represents nascent demand concentrated in South African premium skincare formulation.
Pharmaceuticals commands premium pricing tiers; healthcare is gaining share fastest through buyer consolidation.
Application:
Volume concentration tracks regulatory validation depth, with immune-support claims facing heightened scrutiny from Nigeria's National Agency for Food and Drug Administration and Control.
- Immune Support:Exhibits the highest immunomodulatory activity validation, driving pharmaceutical formulation partnerships and direct sales channel maturation. Yeast-derived beta glucan production in Southern Africa targets this application with specialized fermentation infrastructure bypassing import tariffs.
- Cholesterol Management:Relies on oat and barley-derived sources vulnerable to cereal grain feedstock price swings, compressing margin predictability for processors.
- Gut Health:Attracts Nigerian nutraceutical brands scaling West African distribution networks from Lagos manufacturing bases.
- Skin Care:Leverages beta glucan film-forming properties in South African cosmetic formulation.
Immune support anchors current revenue concentration; gut health shows the steepest expansion trajectory among domestic African brands.
Distribution Channel:
Customer type fragmentation separates institutional volume contractors from fragmented retail and e-commerce purchasers, with technical service capabilities determining supplier selection at the pharmaceutical tier.
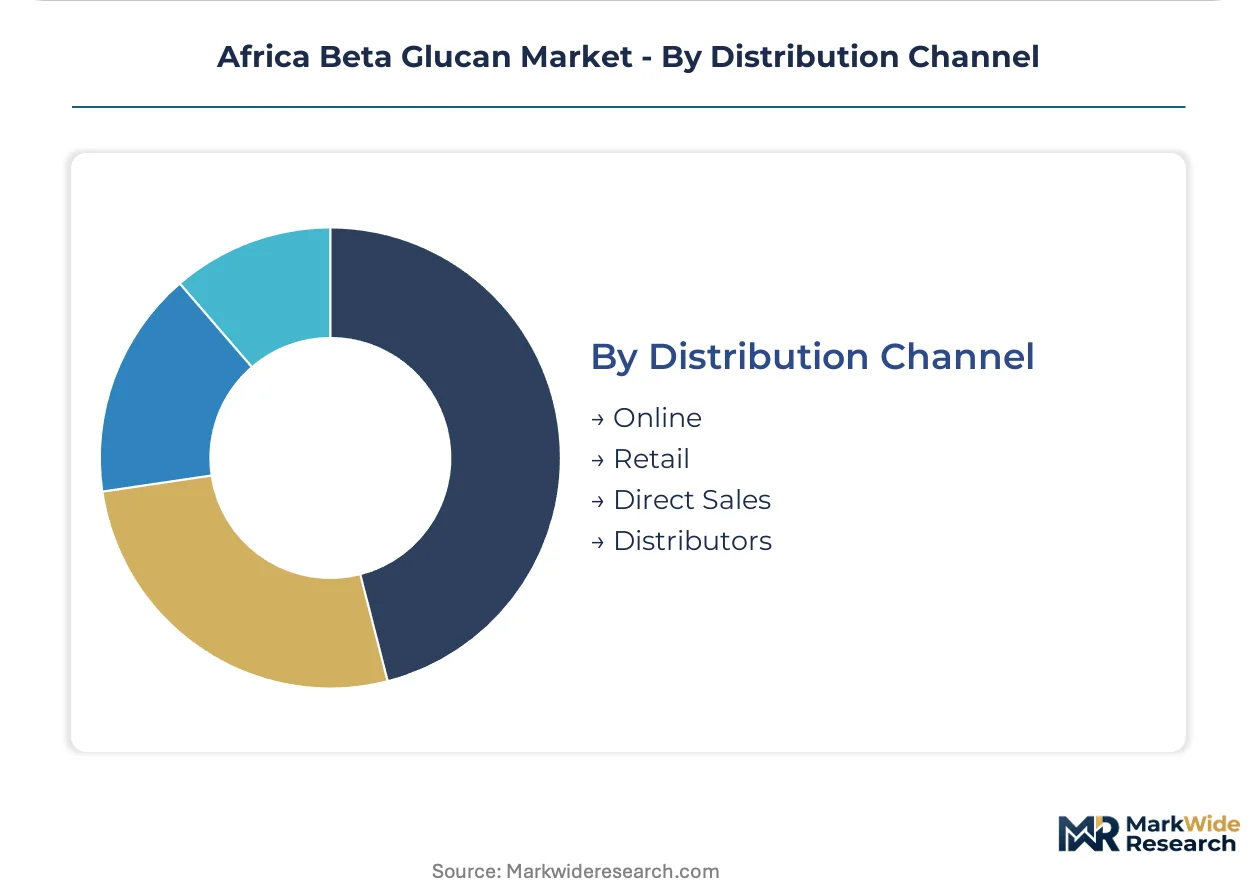
- Direct Sales:Captures pharmaceutical manufacturer procurement through captive technical sales teams enabling formulation partnership depth. Institutional purchasers in South Africa and Nigeria consolidate ingredient buying through bundled documentation and stability data packages.
- Distributors:Serves mid-tier nutraceutical and food manufacturers lacking specialized regulatory navigation expertise, though margins compress under multi-layer markups.
- Online:Reaches fragmented consumer supplement demand in urban Kenya and Nigeria with limited technical support.
- Retail:Channels finished capsules and tablets through pharmacy chains with variable cold-chain integrity.
Direct sales captures the largest contract values; online is climbing the fastest among emerging domestic brands.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand for beta glucan concentrates in pharmaceutical corridors across Lagos, Johannesburg, and Nairobi, with regulatory divergence fragmenting procurement patterns and elevating compliance costs for cross-border suppliers.
South Africa
Immune-support therapies drive pharmaceutical-grade beta glucan consumption in Gauteng's manufacturing cluster. The Department of Health enforces tightened purity thresholds for imported polysaccharides, filtering substandard suppliers from institutional procurement. Cape Town's expanding biotech infrastructure attracts fermentation-based production investments targeting regional distribution.
Nigeria
Nutraceutical formulators in Lagos generate sustained pull for yeast-derived beta glucan as domestic brands scale West African distribution networks. The National Agency for Food and Drug Administration and Control scrutinizes immune-support claims with heightened documentation requirements. Kano's emerging food processing hub experiments with cereal grain-sourced beta glucan for functional food applications.
Kenya
Nascent vaccine adjuvant production and local drug formulation create positioning opportunities for beta glucan suppliers establishing East African technical capabilities. The Pharmacy and Poisons Board maintains distinct labeling requirements that complicate cross-border product standardization. Nairobi's pharmaceutical manufacturing corridor consolidates ingredient procurement through volume contracting frameworks.
Egypt
Aqueous alkaline extraction capacity clusters around Cairo and Alexandria, creating single-point-of-failure exposure for pharmaceutical-grade material access across North African markets. The country's national pharmaceutical regulator aligns with broader African standards harmonization initiatives. The Suez Canal logistics corridor enables re-export positioning for Sub-Saharan distribution.
Ghana
Emerging nutraceutical brands in Accra tap regional distribution networks for immune-support formulations targeting West African consumer markets. The country's food and drug administration builds testing capacity for polysaccharide purity verification. Tema's port infrastructure facilitates import consolidation for landlocked neighboring markets.
Africa Beta Glucan Market Competitive Environment
European and North American producers anchor the premium pharmaceutical-grade tier; Asian fermentation specialists hold cost-advantaged positions in yeast-derived supply. The vendor base stratifies around certification depth, with GMP-compliant facilities commanding institutional procurement relationships. Three archetypes dominate: multinational ingredient platforms with pan-African distribution, regional fermentation specialists with captive technical capabilities, and commodity traders facing margin compression under purity threshold tightening. Competitive moves concentrate on regulatory documentation bundling and direct technical sales team deployment to bypass traditional distributor markups.
Within the multinational platform tier, Kerry Group and Koninklijke DSM N.V. exemplify archetypes combining regional distribution infrastructure with specialized production capabilities. Tate & Lyle PLC occupies a position representing portfolio diversification into functional food applications. These entities anchor competitive positioning through compliance infrastructure that absorbs elevated documentation requirements across South Africa, Nigeria, and Kenya.
| Leading Market Players |
|---|
| Kerry Group |
| Koninklijke DSM N.V. |
| Tate & Lyle PLC |
| Lesaffre |
| Merck KGaA |
| Kemin Industries |
| Lallemand Inc. |
| Alltech |
| Angel Yeast Co. Ltd |
| Others |
Value Chain & Pricing Dynamics
REACH-equivalent chemical safety standards gate both qualified supply and premium-tier pricing access, forcing beta glucan importers to absorb elevated compliance expenditures or cede institutional procurement relationships to certified competitors. This environmental mandate stratifies the market into documentation-heavy pharmaceutical-grade suppliers and price-pressured commodity traders facing margin compression.
Pricing Analysis
Lead-time-driven pricing angles dominate procurement negotiations, with pharmaceutical manufacturers paying premiums for validated short-lead inventory while spot-market liquid formats trade at discounts. Three-tier pricing structure across pharmaceutical-grade, food-additive, and feed-grade levels separates GMP-certified producers from standard-tier suppliers. Pricing pressure stems from cereal grain feedstock volatility tied to regional drought cycles, compressing margin predictability for oat and barley-derived processors. Food and beverage buyers exhibit highest price sensitivity; pharmaceutical formulators prioritize certification depth over unit cost.
Supply Chain Analysis
Freight cost differentials between refrigerated liquid and ambient-stable powder formats reshape distribution economics across Sub-Saharan networks. Supply concentrates in South Africa and Egypt for aqueous alkaline extraction capacity, with Nigerian and Kenyan formulators drawing from imported yeast-derived feedstock. Raw material dependencies rest on cereal grain availability, fermentation substrate quality, and pharmaceutical-grade solvent supplies. Single-point-of-failure exposure clusters around Cairo-Alexandria extraction infrastructure. Distribution runs through direct sales channels to institutional pharmaceutical purchasers, bypassing traditional distributor markups.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a cost-of-compliance story, with South Africa's Department of Health purity thresholds creating a barrier-to-entry moat that rewards certified incumbents while filtering uncertified traders from institutional procurement.
For Market Incumbents: Deploy regulatory documentation bundling as the primary lever to deepen pharmaceutical manufacturer relationships and defend against emerging fermentation-based competitors. Consolidate aqueous alkaline extraction capacity in Southern Africa to capture economies of scale while investing in GMP-compliant facility upgrades ahead of Nigeria's National Agency for Food and Drug Administration and Control enforcement tightening. Absorb compliance costs to maintain premium-tier positioning as purity thresholds escalate. For New Entrants and Emerging Players: Capture Kenya's nascent vaccine adjuvant production corridor through technical service capabilities that established multinationals have underinvested in. Target East African pharmaceutical manufacturing with microbial fermentation platforms enabling distributed, smaller-scale production bypassing import tariff structures. Build direct technical sales teams to displace distributor-dependent competitors in institutional volume contracting frameworks. For Investors and Strategic Acquirers: African Continental Free Trade Area regulatory convergence negotiations reaching implementation milestones is the leading indicator that unified testing protocols will collapse multi-jurisdiction compliance burdens and enable pan-African scale. Five-to-ten year viability favors acquiring regional fermentation specialists with captive technical capabilities and existing South African or Egyptian regulatory certifications. Monitor Nigeria's National Agency for Food and Drug Administration and Control enforcement intensity as the signal for when documentation-heavy market entry costs peak.| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Documentation Bundling | Consolidates institutional procurement relationships around compliant suppliers in South Africa's tightened purity environment. |
| Microbial Fermentation Platform Deployment | Enables Nigerian and Kenyan formulators to secure captive supply bypassing centralized extraction infrastructure. |
| Direct Technical Sales Team Buildout | Captures margin pools by displacing multi-layer distributor markups in Lagos and Johannesburg manufacturing corridors. |
| GMP-Compliant Facility Investment | Positions suppliers for pharmaceutical-grade certification ahead of Kenya's Pharmacy and Poisons Board enforcement escalation. |
| East African Technical Service Expansion | Creates first-mover positioning in Kenya's underpenetrated vaccine adjuvant production base. |
Study Parameters
Independent corroboration across pharmaceutical procurement directors, nutraceutical formulation managers, and regulatory affairs leads at beta glucan suppliers underwrites the qualitative findings. Secondary validation draws from South Africa's Department of Health regulatory filings, Nigeria's National Agency for Food and Drug Administration and Control documentation requirements, customs and trade data for polysaccharide imports, and SEC filings of listed ingredient suppliers. Bottom-up demand modeling triangulates against top-down market sizing across powder, liquid, capsule, and tablet format segments.
Comparable-period anchoring to historical pharmaceutical-grade pricing and volume trends shapes the projection framework across the analysis window. Segmentation dimensions include product type stability profiles, end-user certification tiers, application immunomodulatory validation depth, and distribution channel technical service intensity. CAGRs derive from regression analysis of input cost trajectories, regulatory enforcement timelines, and buyer consolidation patterns. Forecast inputs incorporate cereal grain feedstock price volatility indices and pan-African trade harmonization negotiation progress.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to African Continental Free Trade Area implementation delays, regional drought cycle severity, and pharmaceutical-grade laboratory testing capacity buildout rates. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nutritional Supplements
North America Collagen-Based Supplements Market
Nutritional Supplements
Propolis Market
Nutritional Supplements
Coral Calcium Market
Nutritional Supplements
Lithium Orotate Supplement Market
Nutritional Supplements
Asia-Pacific Dietary Supplement Market
Nutritional Supplements
Calcium Market
Nutritional Supplements
Global Protein Market
Nutritional Supplements
Europe Meal Replacement Products Market
Nutritional Supplements
Asia-Pacific Digestive Health Supplements Market
Nutritional Supplements
Longevity and Anti-Aging Brain Health Supplements Market
Nutritional Supplements
Smart Nutrition Scale Market
Nutritional Supplements
Green Supplement Market
Nutritional Supplements
Botanical Supplements Market
Nutritional Supplements
Global Nootropics Brain Supplements Market
Nutritional Supplements
Calcium HMB Market
Nutritional Supplements
Selenium Yeast Market