
 Microencapsulated Fish Oil Market | 2026-2036
Microencapsulated Fish Oil Market Size, Share, and Industry Trends Forecast 2026-2036
Microencapsulated Fish Oil Market Foresight
The capability gap between spray-drying infrastructure and fluidized-bed coating capacity is rotating investment toward specialized encapsulation technology. BASF SE leverages its pharmaceutical excipient portfolio to dominate high-purity omega-3 powder supply for European nutraceutical brands. Koninklijke DSM N.V. sustains R&D intensity in algal-fish oil hybrid encapsulation, anchoring its position in premium infant nutrition contracts. Clover Corporation specializes in powder-form microencapsulation for functional food integration, competing primarily in Asia-Pacific bakery and dairy applications.
Microencapsulated fish oil comprises omega-3 fatty acids—principally EPA and DHA—sealed within protective matrices of modified starch, gum arabic, or protein-based wall materials through spray-drying or coacervation, typically achieving particle sizes of 10-100 micrometers and oil loads of 20-50% by weight. This encapsulation shields polyunsaturated lipids from oxidation, masking fishy odor while enabling incorporation into aqueous food systems, infant formulas, and compressed tablets where unprotected oil would fail. Powder formats lead volume due to their stability in baked goods and dry beverage mixes, while softgel applications retain margin concentration in pharmaceutical-grade cardiovascular therapies. Functional foods represent the fastest-expanding application as bakery and dairy manufacturers seek clean-label omega-3 fortification without sensory degradation.
FDA GRAS notifications and EPA good manufacturing practice inspections govern US market entry for fish oil ingredients, while EFSA novel food authorizations and REACH chemical safety registrations constrain European suppliers to documented purity thresholds. The US FDA's evolving stance on structure-function claims for omega-3 cardiovascular benefits shapes label language and consumer communication strategies across supplement brands. Stakeholders must monitor how EFSA's tightening contaminant limits for heavy metals and oxidation markers will reshape supplier qualification criteria and testing cost structures across the value chain.
Market Dynamics
Fluidized-bed coating infrastructure scarcity is concentrating omega-3 powder production among pharmaceutical-grade encapsulation facilities in Germany and the Netherlands, locking out mid-tier suppliers from premium infant nutrition contracts.
Growth Catalysts
- EFSA novel food authorizations:Tightening purity benchmarks for omega-3 ingredients force suppliers to upgrade oxidation control systems, accelerating technical differentiation among encapsulation specialists.
- Infant formula fortification:Nutritional supplement brands source microencapsulated fish oil for senior nutrition and pediatric applications, creating stable demand anchors against commodity price swings.
- Spray-drying capability gaps:The rotation of investment toward specialized encapsulation technology is concentrating production around Hamburg and Frankfurt pharmaceutical clusters.
Market Restraints
- Ethylene oxide residue thresholds:REACH chemical safety registrations and EFSA tightening contaminant limits for heavy metals reshape supplier qualification criteria and testing cost structures.
- Algal oil substitution:Koninklijke DSM N.V. sustains R&D intensity in algal-fish oil hybrid encapsulation, threatening pure fish oil powder margins in premium positioning.
- Modified starch input volatility:Wall material costs fluctuate with agricultural commodity cycles, compressing encapsulation service margins during price spikes.
Strategic Opportunities
- Asia-Pacific bakery integration:Clover Corporation specializes in powder-form microencapsulation for functional food applications, competing in dairy and baked goods where clean-label omega-3 fortification remains underdeveloped.
- FDA GRAS notification pathways:The evolving US stance on structure-function claims for omega-3 cardiovascular benefits shapes label language strategies for supplement brands entering American retail.
- Coacervation-fluidized bed convergence:Hybrid encapsulation technologies enable higher oil loads and smaller particle sizes, opening pharmaceutical-grade compressed tablet applications.
Industry Challenges
- Pharmaceutical-grade certification timelines:EPA good manufacturing practice inspections and EMA documentation requirements extend product launch cycles by 18-24 months for new encapsulation facilities.
- Cross-functional talent scarcity:Lipid oxidation chemistry expertise combined with food engineering skills concentrates among German and Dutch technical universities, limiting facility expansion elsewhere.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Microencapsulated Fish Oil Market |
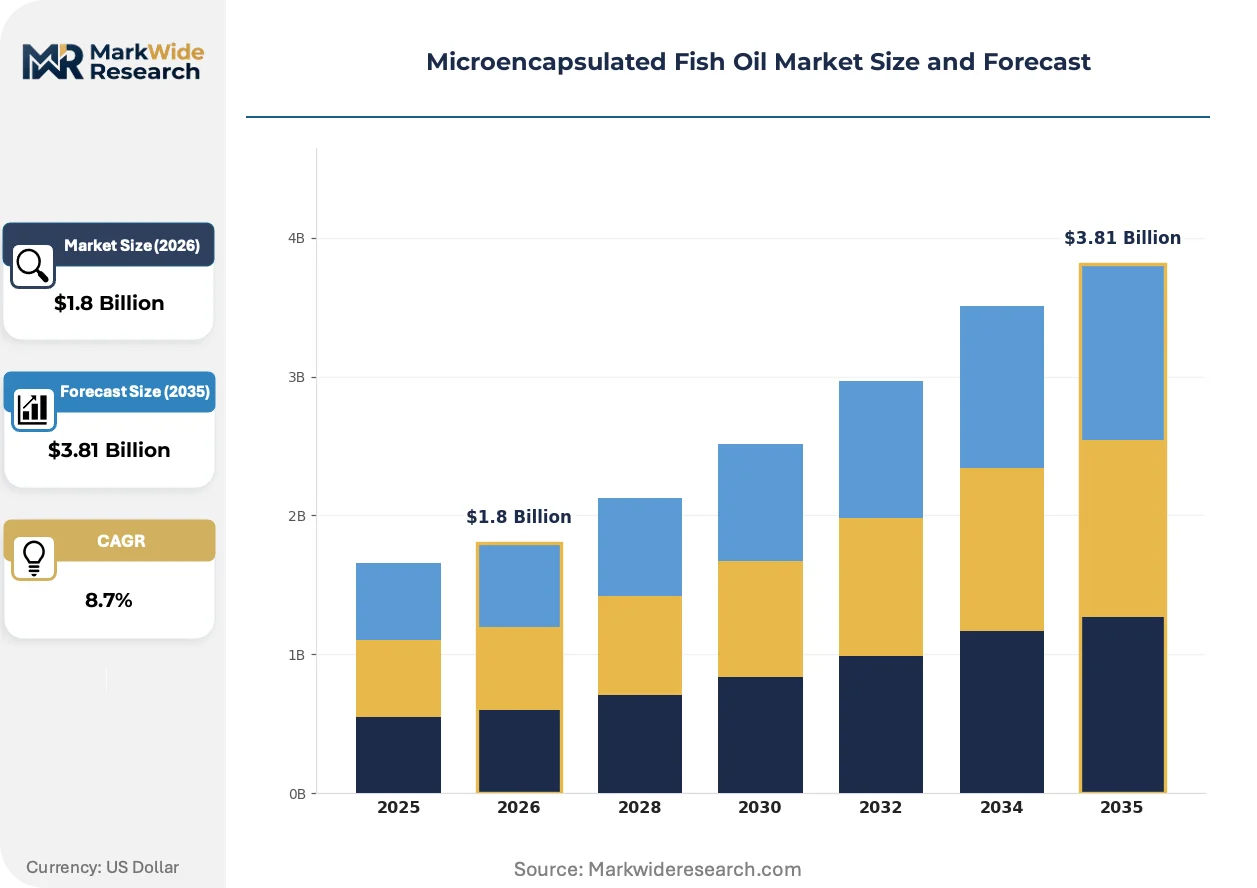
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Softgels, Liquid, Powder, Capsules Application: Nutritional Supplements, Functional Foods, Animal Feed, Pharmaceuticals End User: Healthcare Professionals, Consumers, Pet Owners, Manufacturers Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Pharmacies |
| Companies Covered | Stepan Specialty Products, Nordic Naturals, OLVEA Fish Oils, BASF SE, Koninklijke DSM N.V., Clover Corporation, Croda International, Aker BioMarine, Omega Protein, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Microencapsulated Fish Oil Market Shifts & Advancements
Encapsulation technology is splitting into two performance tiers, with pharmaceutical-grade specifications diverging sharply from commodity food-grade production. This technical schism is reshaping competitive positioning and investment patterns across the value chain.
Complex coacervation using gelatin-gum arabic wall systems is bifurcating the high-end segment from spray-dried starch-based powders. Infant formula manufacturers in Germany and the Netherlands specify sub-50 micrometer particle sizes with 40-50% oil loads, paying 3-4x commodity powder prices. This technical specification is compressing mid-tier encapsulation capacity into undifferentiated bakery and beverage mix applications.
REACH chemical safety registrations now mandate documented purity thresholds for heavy metals and oxidation markers that exceed prior industry norms. European suppliers face requalification costs that favor integrated pharmaceutical excipient portfolios. Premium infant nutrition contracts now require EFSA novel food authorization documentation as a baseline procurement filter.
Clean-label procurement is compressing synthetic antioxidant usage in favor of rosemary extract and tocopherol natural preservation systems. Bakery manufacturers in France and Italy now reject microencapsulated fish oil with BHT or TBHQ residues, switching suppliers to meet retailer sustainability scorecards. This specification shift is most visible in private-label functional food contracts where end-use brands pass formulation constraints upstream to encapsulation houses.
Microencapsulated Fish Oil Market Segmentation
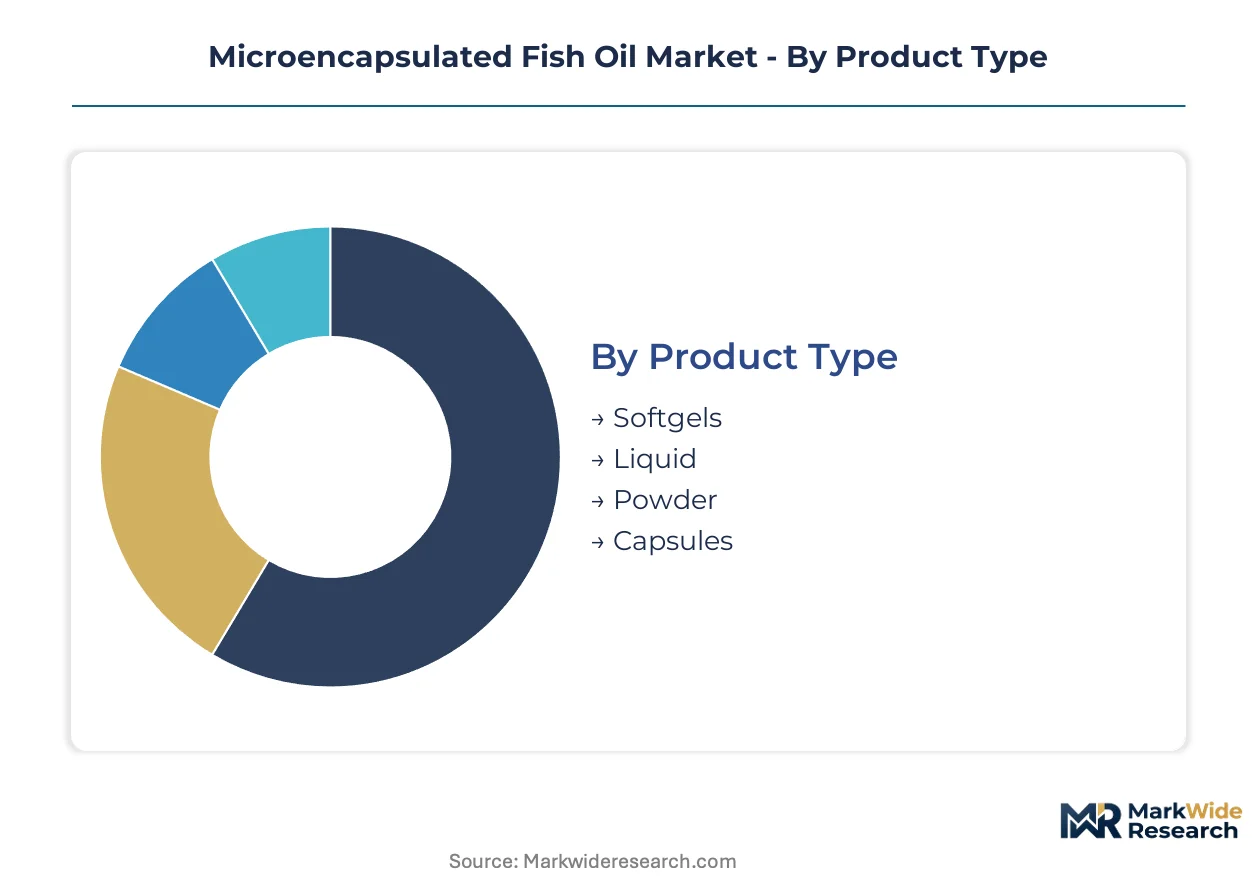
Encapsulation format dictates regulatory pathway and margin structure across the omega-3 value chain. Product type selection determines oxidation stability requirements, while application choice shapes wall material specifications and certification thresholds.
Product Type:
EFSA novel food authorizations and FDA GRAS notifications impose divergent purity benchmarks across physical formats, concentrating pharmaceutical-grade investment in higher-stability configurations.
- Powder:Spray-dried or fluidized-bed coated particles of 10-100 micrometers achieve 20-50% oil loads within modified starch or protein matrices. Bakery and dry beverage mix manufacturers in Germany specify powder for aqueous system integration without sensory degradation. Infant formula contracts in the Netherlands demand sub-50 micrometer particle sizes with documented oxidation stability.
- Softgels:Gelatin or plant-based shells containing liquid fish oil cores dominate pharmaceutical-grade cardiovascular therapies. Hamburg encapsulation facilities cluster production for premium positioning where EMA documentation requirements extend launch timelines. REACH chemical safety registrations mandate heavy metal thresholds that exceed prior industry norms for this format.
- Liquid:Emulsified oil concentrates serve functional food manufacturers requiring pumpable dosing systems. Clean-label procurement trends favor rosemary extract preservation over synthetic antioxidants.
- Capsules:Hard-shell two-piece configurations accommodate blended formulations with complementary nutraceuticals. Compression tablet applications require specialized coacervation-fluidized bed hybrid technologies.
Powder handles the majority of throughput; softgels is the fastest mover on share.
Application:
End-use specifications fragment the supply base between pharmaceutical excipient portfolios and commodity food-grade production.
- Functional Foods:Bakery and dairy manufacturers seek clean-label omega-3 fortification without fishy odor or oxidation off-notes. France and Italy lead rejection of BHT or TBHQ residues, switching suppliers to meet retailer sustainability scorecards. Private-label contracts pass formulation constraints upstream to encapsulation houses.
- Nutritional Supplements:Compressed tablets and dry beverage mixes demand spray-dried powder with 12-24 month shelf stability. Consumer communication strategies navigate FDA structure-function claim restrictions on cardiovascular benefits.
- Pharmaceuticals:EMA good manufacturing practice inspections govern cardiovascular therapy applications with documented purity thresholds. Algal-fish oil hybrid encapsulation threatens pure fish oil margins in premium positioning.
- Animal Feed:Pet food manufacturers specify lower oxidation markers for premium companion animal nutrition. Cost pressures favor commodity-grade spray-dried powders over pharmaceutical-grade alternatives.
Functional foods commands the steepest expansion trajectory; nutritional supplements anchors volume concentration.
End User:
Procurement authority concentrates among technically sophisticated buyers with documented quality systems.
- Manufacturers:Infant formula and functional food producers specify EFSA novel food authorization documentation as baseline procurement filters. Integrated pharmaceutical excipient portfolios favor integrated suppliers with REACH compliance documentation.
- Healthcare Professionals:Cardiovascular therapy prescriptions require pharmaceutical-grade softgels with EMA batch release certification. Prescription omega-3 products demand higher oxidation control than over-the-counter alternatives.
- Consumers:Direct-to-purchase behavior concentrates in online retail channels with label literacy around EPA/DHA ratios. Structure-function claim language shapes brand selection for cardiovascular positioning.
- Pet Owners:Premium companion animal nutrition drives demand for human-grade oxidation specifications. Veterinary recommendation channels favor encapsulated powder over liquid emulsions for dosing precision.
Manufacturers controls procurement volume; healthcare professionals is expanding most quickly on prescription positioning.
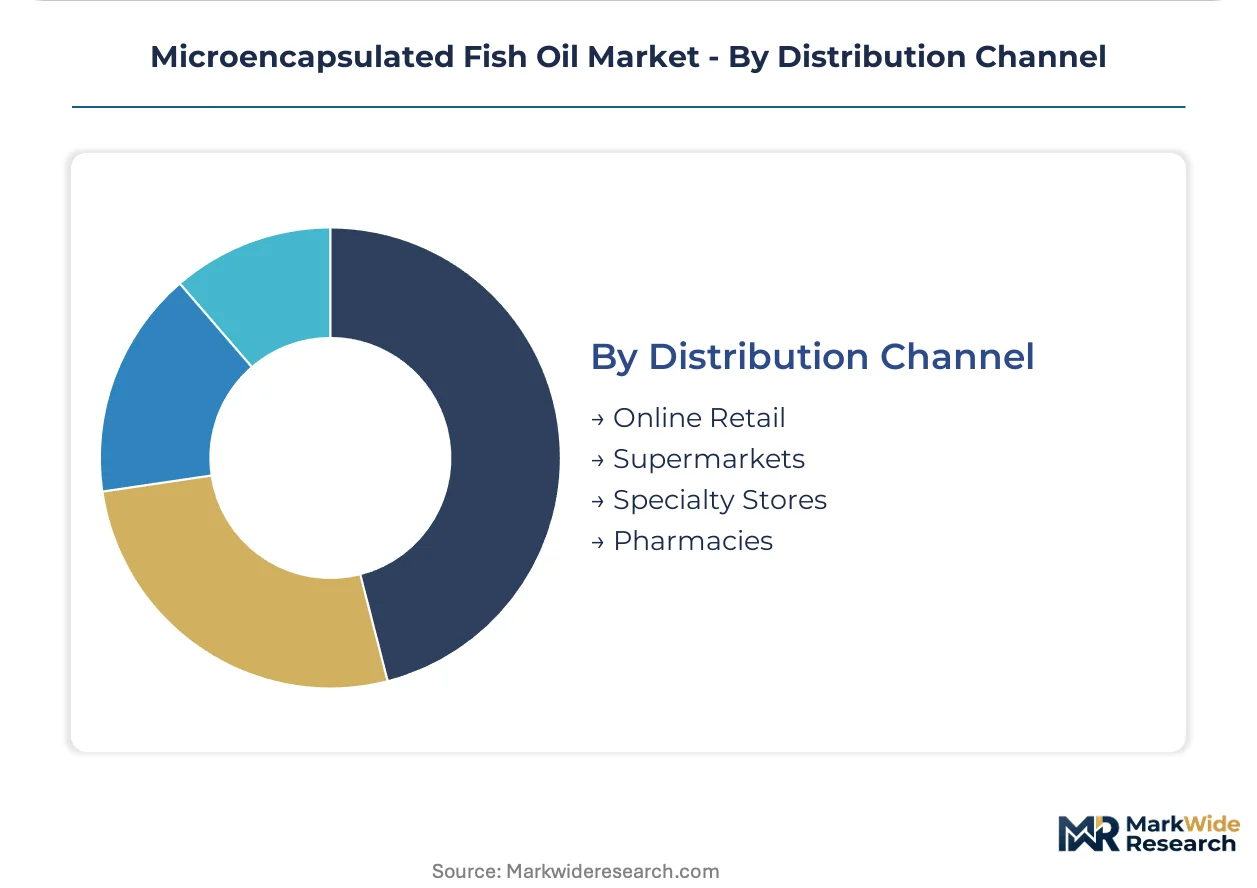
Distribution Channel:
Channel selection determines margin capture and regulatory exposure for finished goods.
- Pharmacies:Pharmaceutical-grade softgels and prescription omega-3 therapies require pharmacist counseling on cardiovascular indications. EMA documentation supports reimbursement eligibility in Germany and the Netherlands.
- Online Retail:Direct-to-consumer powder and capsule formats bypass traditional wholesale markups. FDA structure-function claim enforcement varies across e-commerce platforms.
- Specialty Stores:Premium positioning in sports nutrition and natural products channels favors clean-label rosemary extract preservation. Staff training requirements concentrate in German and Dutch retail clusters.
- Supermarkets:Private-label functional food integration demands commodity-grade powder at volume pricing. Retailer sustainability scorecards constrain synthetic antioxidant usage.
Pharmacies retains margin concentration; online retail is gaining share fastest on direct access models.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in German pharmaceutical-grade encapsulation clusters while cost-competitive production gravitates toward Asia-Pacific functional food manufacturers. EFSA novel food authorizations and REACH compliance documentation create asymmetric barriers to premium market entry. Regulatory stringency in Hamburg and Frankfurt facilities commands 3-4x commodity powder premiums.
Germany
Infant formula fortification and cardiovascular therapy applications anchor demand for sub-50 micrometer particle specifications. EMA good manufacturing practice inspections govern batch release certification for pharmaceutical-grade softgels. Hamburg and Frankfurt host concentrated fluidized-bed coating infrastructure that locks out mid-tier suppliers from premium contracts.
Netherlands
Pediatric nutrition manufacturers specify documented oxidation stability for algal-fish oil hybrid encapsulation. EFSA health claim requirements constrain label language for omega-3 cardiovascular positioning. Rotterdam-area facilities specialize in coacervation-fluidized bed convergence technologies for compressed tablet applications.
United States
Dry beverage mix and compressed tablet manufacturers drive spray-dried powder consumption for nutritional supplements. FDA GRAS notifications and EPA good manufacturing practice inspections govern market entry for fish oil ingredients. Structure-function claim restrictions shape consumer communication strategies across supplement brands.
France
Bakery and dairy manufacturers lead clean-label rejection of synthetic antioxidants in favor of rosemary extract preservation. REACH chemical safety registrations mandate heavy metal thresholds exceeding prior industry norms. Paris and Lyon functional food producers pass retailer sustainability scorecards upstream to encapsulation houses.
China
Functional food integration accelerates in bakery and dairy applications seeking aqueous system compatibility. SAMR food safety registrations and GB standards govern omega-3 ingredient import and domestic production. Yangtze River Delta encapsulation facilities compete on modified starch-based spray-dried powders for commodity applications.
Microencapsulated Fish Oil Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the microencapsulated fish oil value chain. Pharmaceutical-grade encapsulation concentrates among integrated excipient portfolios with documented REACH compliance, while commodity food-grade production fragments across regional spray-drying specialists. Three archetypes dominate: integrated chemical conglomerates with pharmaceutical excipient portfolios, dedicated nutrition ingredient specialists with R&D intensity in hybrid encapsulation, and regional powder-form specialists serving functional food integration. Competitive dynamics center on capacity expansion in fluidized-bed coating infrastructure and strategic partnerships for algal-fish oil hybrid technology access.
Among integrated chemical conglomerates, BASF SE and Koninklijke DSM N.V. exemplify divergent strategic positioning within premium-tier supply. BASF SE anchors pharmaceutical-grade omega-3 powder supply through its excipient portfolio integration, while Koninklijke DSM N.V. occupies a position in algal-fish oil hybrid R&D intensity. Clover Corporation represents the regional specialist archetype, sitting within Asia-Pacific functional food applications where clean-label fortification remains underdeveloped. These three entities collectively illustrate how encapsulation technology splits into performance tiers with sharply divergent investment requirements.
| Leading Market Players |
|---|
| Stepan Specialty Products |
| Nordic Naturals |
| OLVEA Fish Oils |
| BASF SE |
| Koninklijke DSM N.V. |
| Clover Corporation |
| Croda International |
| Aker BioMarine |
| Omega Protein |
| Others |
Supply & Pricing Matrix
Algal-fish oil hybrid encapsulation displacing pure fish oil formulations is redrawing supply geography toward Rotterdam-area R&D clusters while compressing pricing premiums for conventional omega-3 powders. This substitution dynamic simultaneously elevates EFSA novel food authorization costs for legacy suppliers and opens margin capture for integrated pharmaceutical excipient portfolios with documented REACH compliance.
Pricing Analysis
Customization-premium spreads separate pharmaceutical-grade fluidized-bed coated powders from commodity spray-dried alternatives. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade and particle size specifications, with infant formula manufacturers paying elevated rates for sub-50 micrometer configurations. Pricing pressure stems from algal oil substitution in premium positioning, compressing pure fish oil margins. Nutritional supplement brands exhibit highest price sensitivity, while pharmaceutical cardiovascular therapy buyers prioritize documented oxidation stability over unit cost.
Supply Chain Analysis
Germany and the Netherlands anchor pharmaceutical-grade encapsulation capacity, with Hamburg and Frankfurt hosting concentrated fluidized-bed coating infrastructure. Modified starch wall materials, gum arabic supplies, and gelatin matrices constitute critical input dependencies. Single-source vulnerability concentrates in German technical universities for lipid oxidation chemistry expertise. Distribution runs through integrated excipient portfolios serving infant formula manufacturers, with REACH documentation serving as procurement gatekeeper.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
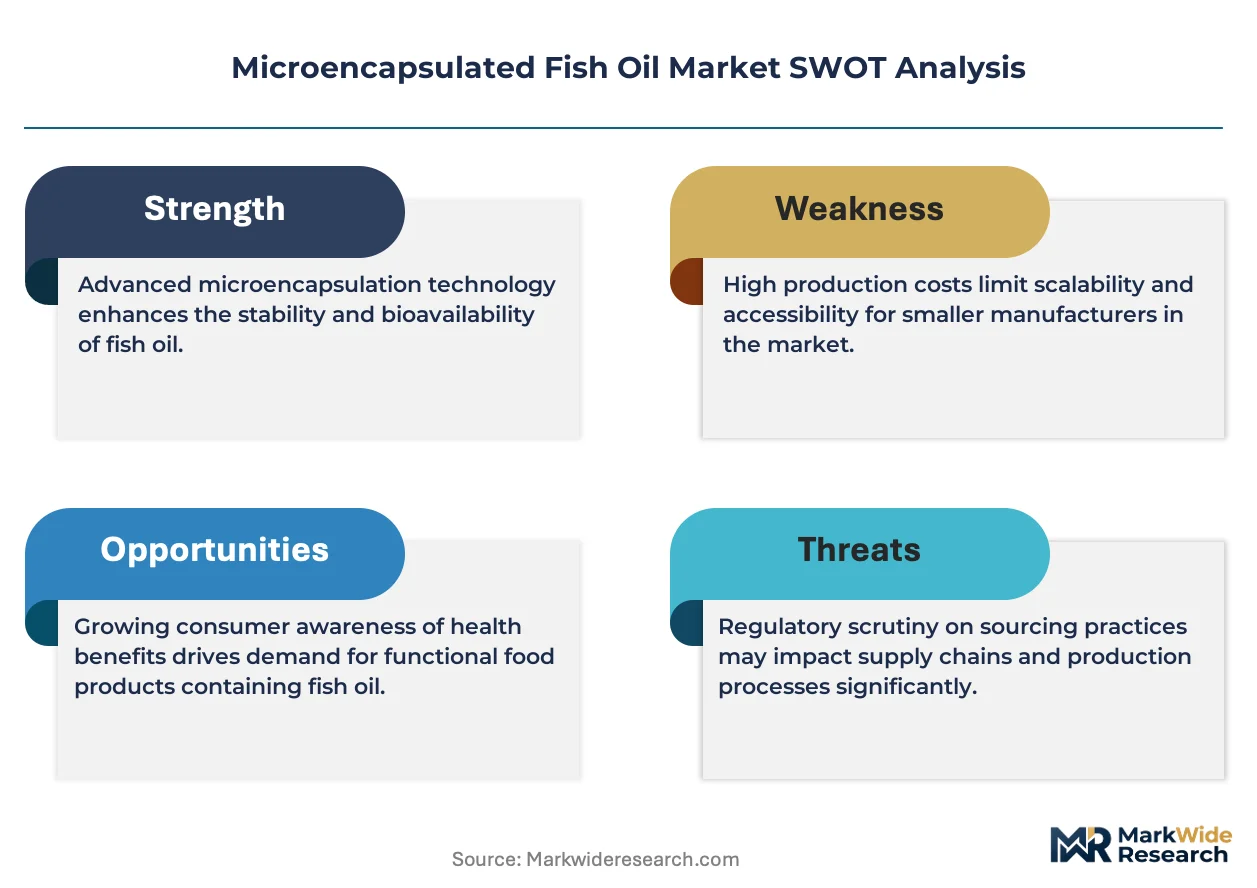
Fragmentation opportunity emerges as clean-label procurement splits the supply base between synthetic antioxidant-dependent commodity producers and rosemary extract-certified premium specialists, creating distinct competitive arenas with divergent investment requirements.
For Market Incumbents: Secure EFSA novel food authorization documentation as baseline procurement qualification before algal-fish oil hybrid technologies capture additional premium infant nutrition contracts. Backward integration into modified starch supply chains mitigates agricultural commodity volatility compressing encapsulation service margins.
For New Entrants and Emerging Players: Anchor in Asia-Pacific bakery and dairy applications where clean-label omega-3 fortification remains underdeveloped and Clover Corporation's powder-form specialization has not saturated functional food integration. Target coacervation-fluidized bed hybrid technology access through equipment partnerships rather than greenfield pharmaceutical-grade certification timelines.
For Investors and Strategic Acquirers: Capital is best deployed toward integrated chemical conglomerates with pharmaceutical excipient portfolios and documented REACH compliance, as regulatory stringency favors consolidated technical documentation over fragmented supplier bases. Watch EFSA tightening contaminant limits for heavy metals as inflection indicator for requalification cost structures favoring integrated players.
| Strategic Initiative | Industry Significance |
|---|---|
| EFSA Novel Food Authorization Investment | Documentation requirements now serve as baseline procurement filter for infant formula contracts. |
| Fluidized-Bed Coating Capacity Expansion | German pharmaceutical clusters lock out mid-tier suppliers from premium positioning. |
| Algal-Fish Oil Hybrid R&D Partnership | DSM's sustained intensity threatens pure fish oil margins in premium applications. |
| Clean-Label Antioxidant Transition | French and Italian bakery manufacturers reject BHT residues, switching supplier bases. |
| Asia-Pacific Functional Food Integration | Commodity spray-dried powders penetrate underdeveloped bakery and dairy fortification. |
Research Methodology
Two parallel data streams informed the analysis: primary interviews with encapsulation technology directors, infant formula procurement managers, pharmaceutical regulatory affairs leads, and functional food R&D heads; and secondary validation against EFSA novel food authorization databases, REACH chemical safety registrations, FDA GRAS notifications, and customs trade data for omega-3 ingredient flows. Bottom-up volume modeling triangulated with top-down value estimates across product type, application, and end user segmentation dimensions.
Across the analysis window, forecasts reflect analytical frameworks incorporating encapsulation format adoption curves, regulatory authorization timelines, and substitution dynamics between algal and fish oil sources. Modeled segmentation spans powder versus softgel versus liquid configurations, functional food versus pharmaceutical versus nutritional supplement applications, and manufacturer versus healthcare professional versus consumer procurement authority. CAGRs derived from regression analysis of historical authorization patterns and capacity expansion announcements.
Material uncertainties — EFSA contaminant limit revisions, ethylene oxide residue threshold adjustments, and algal oil cost parity achievements — sit outside the modeled envelope. Forecasts reflect assumptions around regulatory stability and input cost trajectories. Recalibration cycles align with material shifts in EFSA health claim requirements and REACH documentation thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nutritional Supplements
Vegan Protein Market
Nutritional Supplements
Chromium Picolinate Market
Nutritional Supplements
Europe Collagen Peptides Market
Nutritional Supplements
Nutritional Analysis Service Market
Nutritional Supplements
Global Hangover Rehydration Supplements Market
Nutritional Supplements
Italy Whey Protein Market
Nutritional Supplements
United States Vitamin D Supplements Market
Nutritional Supplements
Organic Whey Protein Market
Nutritional Supplements
Coral Calcium Supplements Market
Nutritional Supplements
Electrolyte Powder Market
Nutritional Supplements
Global Algal DHA and ARA Market
Nutritional Supplements
Vitamin Shot Market
Nutritional Supplements
Eggshell Membrane Powder Market
Nutritional Supplements
Middle-East and Africa Dietary Supplement Market
Nutritional Supplements
Marine Hydrolyzed Collagen Market
Nutritional Supplements
Sports Food Market