
 Lipid Nutrition Market | 2026-2036
Lipid Nutrition Market Size, Share, and Industry Trends Forecast 2026-2036
Lipid Nutrition Market Intelligence
The industry-wide shift toward sustainable algal and krill-based sources for Omega-3 fatty acids is consolidating supply chains around specialized producers. Koninklijke DSM N.V. leverages its advanced fermentation capabilities to lead in algal-derived lipids. BASF SE competes on a broad portfolio of both marine and plant-based lipids for diverse applications. Meanwhile, Aker BioMarine AS specializes in traceable, eco-harvested krill oil, controlling a significant portion of that specific niche.
Lipid nutrition involves the delivery of specific fatty acids, such as eicosapentaenoic acid (EPA) and docosahexaenoic acid (DHA), which are essential for cellular structure and metabolic signaling. These compounds provide functional health benefits beyond simple caloric energy. Omega-3 fatty acids continue to dominate the product landscape, driven by extensive clinical research. The infant nutrition and sports nutrition applications represent high-margin segments, contrasting with the more volume-driven functional food category.
Market access and product claims are governed by stringent regulatory frameworks. The US FDA sets standards for dietary supplements, while the European Food Safety Authority (EFSA) scrutinizes health claim substantiation. In China, the NMPA manages approvals for infant formula ingredients. Navigating the complex web of sourcing validation and regional claim approvals remains the central challenge for market participants.
Market Dynamics
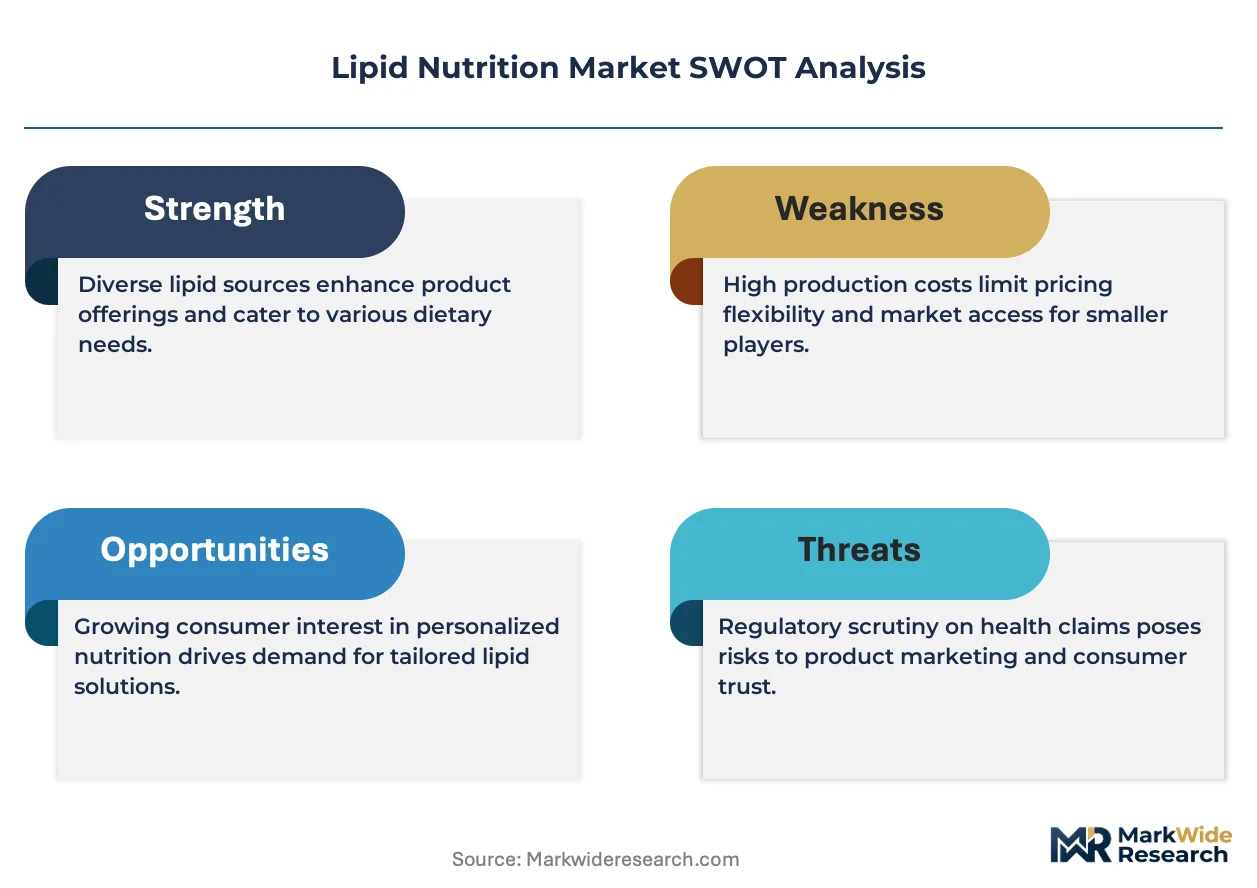
The market's structure is defined by the dual pressures of securing sustainable, non-marine lipid sources like algae and navigating divergent international regulatory frameworks for health claims, particularly from the EFSA in Europe and the FDA in the United States.
Growth Catalysts
- EFSA-Approved Health Claims:Specific, science-backed health claims for DHA and EPA, approved by the European Food Safety Authority, build consumer trust and enable premium product positioning in functional foods and supplements.
- Infant Nutrition Demand:The infant formula segment's focus on cognitive development, backed by regulations like those from China's NMPA, drives significant demand for high-purity DHA and other essential fatty acids.
- Algal Fermentation Technology:Advances in fermentation provide a scalable and vegetarian alternative to fish oil for Omega-3 production, bypassing marine supply volatility and appealing to new consumer segments.
Market Restraints
- High Purification Costs:The capital-intensive processes required to extract, purify, and concentrate specific fatty acids to meet pharmaceutical or infant-grade standards create significant cost barriers for new entrants.
- Marine Source Volatility:Reliance on marine sources like fish and krill exposes the supply chain to ecological pressures, fishing quotas, and climate-related fluctuations, leading to unpredictable input costs.
- Divergent Global Standards:The lack of harmonized regulations for novel lipid sources and health claims between jurisdictions like the US, EU, and China increases compliance costs and complicates global product launches.
Strategic Opportunities
- Personalized Nutrition Platforms:Integrating lipid profiles with biomarker testing offers an opportunity to develop customized supplements and functional foods, moving beyond one-size-fits-all formulations for specific health outcomes.
- Southeast Asian Market Entry:Rising disposable incomes and health awareness in countries like Vietnam and Indonesia present an underpenetrated market for fortified foods, especially in maternal and infant nutrition categories.
- Novel Lipid Delivery Systems:Developing microencapsulation and nanoemulsions can improve the stability and bioavailability of lipids in challenging food applications, unlocking new product categories in beverages and baked goods.
Industry Challenges
- Health Claim Substantiation:Generating the extensive clinical data required to substantiate new health claims for regulatory bodies like the EFSA or FDA is a lengthy and expensive process, delaying time-to-market for innovative products.
- Ensuring End-to-End Traceability:Verifying the origin and sustainability of raw materials, from krill eco-harvesting to non-GMO plant sources, demands complex certification and tracking systems to meet consumer expectations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Lipid Nutrition Market |
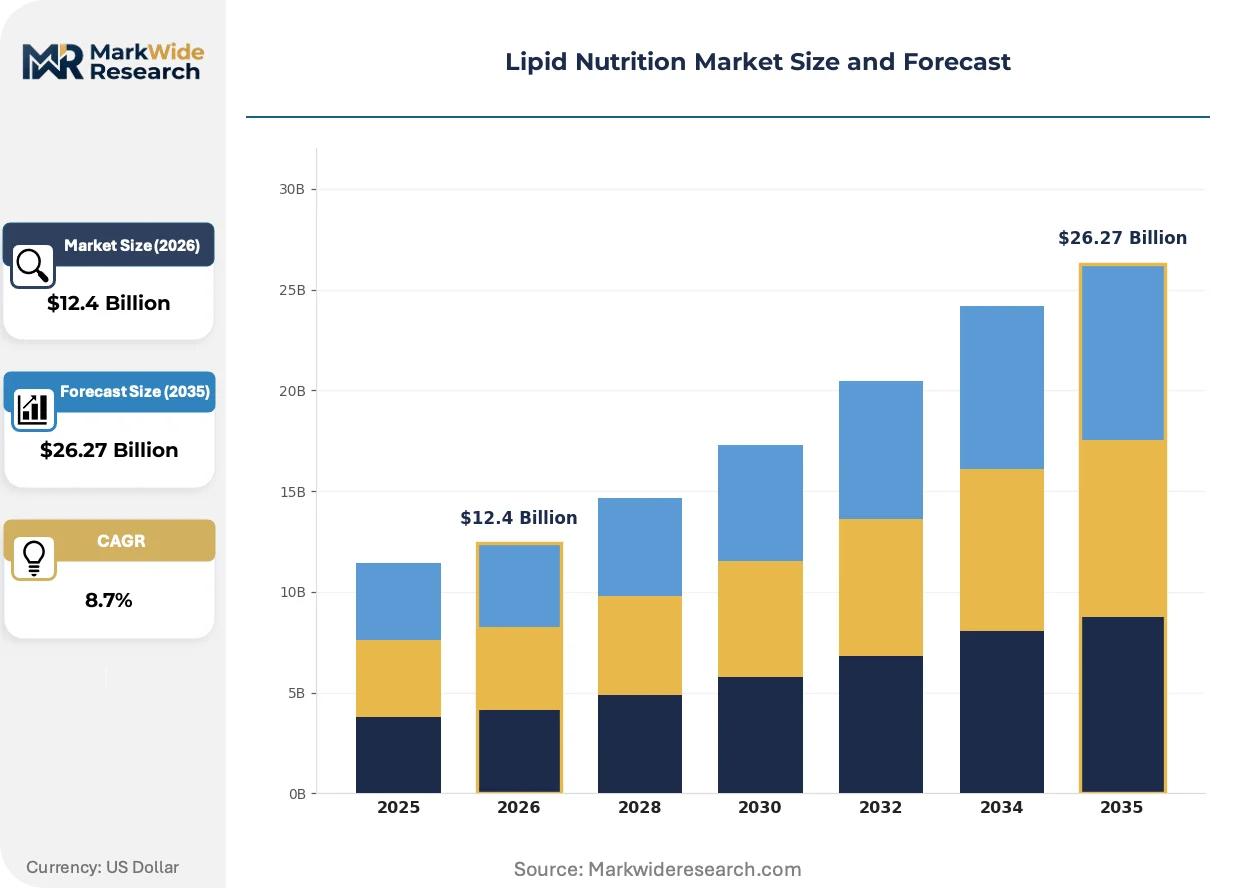
| Market Size in 2026 | $12.4 Billion |
| Market Size in 2035 | $26.27 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Omega-3 Fatty Acids, Medium Chain Triglycerides, Phospholipids, Sterols Application: Infant Nutrition, Clinical Nutrition, Sports Nutrition, Functional Food End User: Infant Formula Manufacturers, Healthcare Providers, Fitness Centers, Food & Beverage Companies Packaging Type: Bottles, Sachets, Blister Packs, Tubes |
| Companies Covered | Koninklijke DSM N.V., BASF SE, Cargill, Incorporated, Archer Daniels Midland Company, Croda International Plc, Nordic Naturals, Inc., Kerry Group plc, FMC Corporation, Aker BioMarine AS, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Lipid Nutrition Market Strategic Shifts & Innovations
Product development is shifting toward precision-targeted lipids derived from sustainable, non-traditional sources. This evolution addresses both consumer demand for ethical products and the industry's need for stable, high-purity supply chains independent of marine ecosystem pressures.
Advanced fermentation technology enables the cultivation of specific microalgae strains to produce high-purity DHA and EPA oils. The infant formula and vegetarian supplement segments are rapidly adopting these algal lipids to ensure consistency and avoid marine allergens. This technological capability is consolidating the upstream supply of high-value Omega-3s around a few specialized producers with proprietary fermentation expertise.
China’s National Medical Products Administration (NMPA) continues to enforce stringent GB standards for ingredients in infant and young child formula. These regulations mandate specific levels and purity for nutrients like DHA, effectively setting a high barrier for market entry. The infant nutrition category in China is most affected, with manufacturers prioritizing suppliers who can provide fully compliant and traceable lipid ingredients.
Consumer purchasing decisions are increasingly influenced by third-party sustainability and purity certifications on product labels. This disrupts traditional brand loyalty, with certifications like Friend of the Sea or the Non-GMO Project label becoming primary drivers of choice over established names. This trend is most visible in the dietary supplement aisle in North American and European retail channels.
Lipid Nutrition Market Segmentation
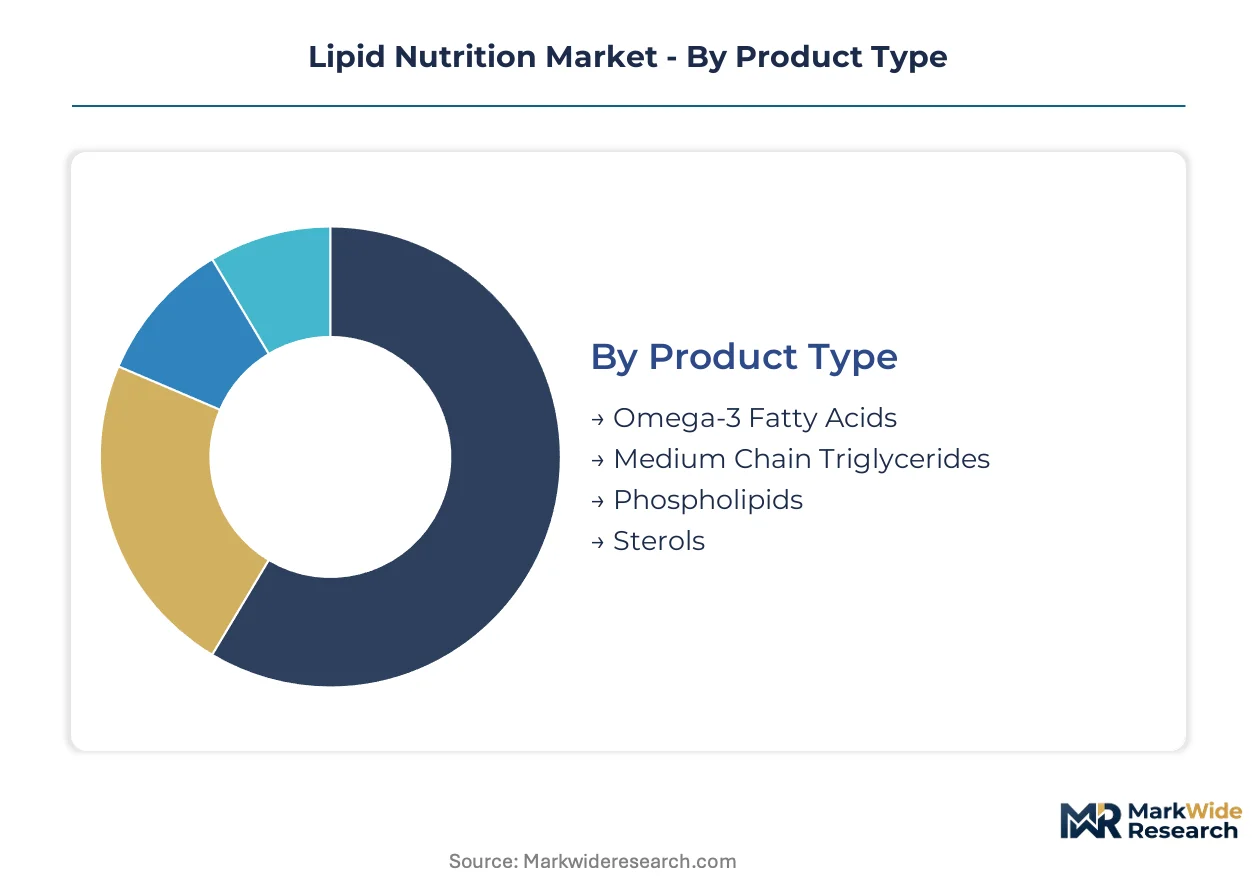
The Lipid Nutrition Market segments reveal distinct dynamics influencing product development, regulatory compliance, and market access strategies. Understanding these classifications allows market participants to tailor product formulations and distribution channels effectively.
Product Type:
Product differentiation across lipid nutrition ranges from highly standardized commodity ingredients to customized, high-purity fatty acid blends. This spectrum reflects diverse applications and regulatory requirements.
- Omega-3 Fatty Acids:These essential polyunsaturated fatty acids, including EPA and DHA, are crucial for neurological development and cardiovascular health. Demand for Omega-3s remains robust across North America and Europe, driven by extensive clinical research and EFSA-approved health claims.
- Medium Chain Triglycerides:Comprising fatty acids with 6-12 carbon atoms, MCTs offer rapid energy metabolism and are often derived from coconut or palm oils. The sports nutrition segment and ketogenic diet trends in the US and Germany significantly propel MCT consumption.
- Phospholipids:These complex lipids form cellular membranes and aid in nutrient absorption, often sourced from soy, egg yolks, or marine organisms.
- Sterols:Plant sterols and stanols are cholesterol-lowering compounds incorporated into functional foods and dietary supplements.
Leading the category by volume: Omega-3 Fatty Acids. Growing fastest: Medium Chain Triglycerides.
Application:
The application landscape for lipid nutrition highlights varying functional demands and consumer demographics, each requiring specific product attributes and regulatory considerations.
- Infant Nutrition:This segment demands ultra-high purity DHA and ARA for cognitive and visual development in infant formulas, particularly under stringent NMPA regulations in China. Manufacturers prioritize suppliers offering compliant and traceable ingredients.
- Functional Food:Lipid nutrition ingredients are incorporated into a wide array of everyday food items, such as fortified dairy, baked goods, and beverages, to deliver specific health benefits. European consumers increasingly seek functional foods with added Omega-3s, supported by EFSA approvals.
- Clinical Nutrition:Specialized lipid formulations support patients with specific dietary needs, including those recovering from surgery or managing chronic conditions.
- Sports Nutrition:Athletes and fitness enthusiasts consume lipids like MCTs and Omega-3s for energy, inflammation reduction, and muscle recovery.
The segment with the highest revenue contribution is Infant Nutrition, while Functional Food demonstrates the most rapid expansion.
End User:
Different end-user groups dictate distinct purchasing patterns, scale requirements, and preferences for ingredient forms and certifications, influencing supplier strategies.
- Infant Formula Manufacturers:These companies require high-volume, strictly regulated, and traceable lipid ingredients, primarily DHA, to meet global standards for infant development. China's NMPA standards heavily influence procurement decisions.
- Food & Beverage Companies:This diverse group integrates lipid ingredients into consumer products, seeking cost-effective and stable formulations that can withstand processing. European and North American food companies increasingly demand sustainable sourcing certifications.
- Healthcare Providers:Hospitals and clinics utilize lipid nutrition products for therapeutic diets and medical interventions, focusing on clinical efficacy and purity.
- Fitness Centers:These facilities often recommend or retail lipid-based supplements to support athletic performance and recovery among their clientele.
Infant Formula Manufacturers drive significant purchasing volume, and Food & Beverage Companies show strong potential for future growth.
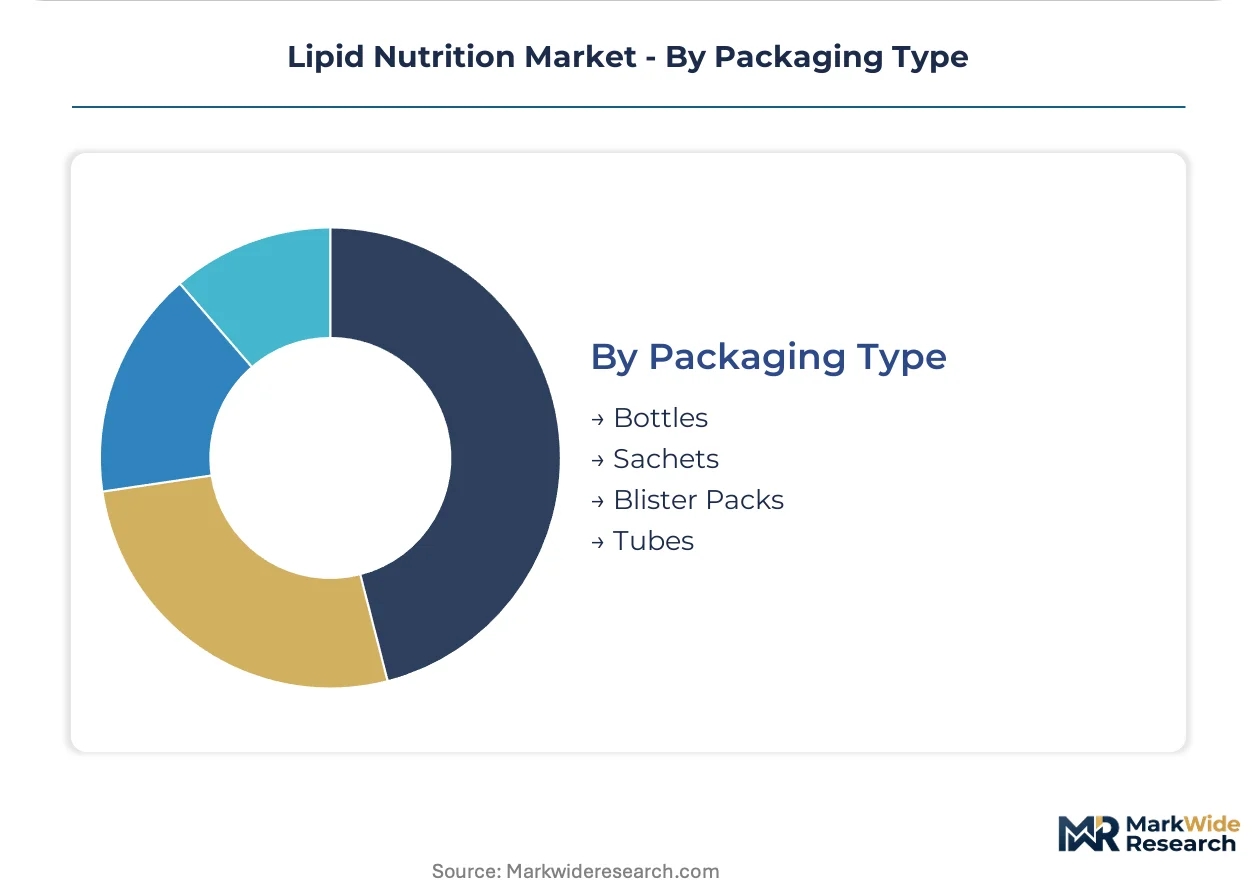
Packaging Type:
Packaging choices for lipid nutrition products directly impact product stability, shelf life, consumer convenience, and brand perception in diverse retail environments.
- Bottles:Widely used for liquid supplements and softgel capsules, bottles offer good protection and are prevalent in North American dietary supplement aisles.
- Sachets:Single-serve sachets provide convenience and precise dosing, particularly for powdered lipid ingredients or liquid concentrates.
- Blister Packs:Offering individual dose protection and extended shelf life, blister packs are common for sensitive lipid capsules and pharmaceutical-grade products.
- Tubes:Less common, tubes are sometimes used for specialized lipid creams or gels in topical applications.
Bottles maintain a dominant share, with Blister Packs experiencing notable uptake.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Netherlands' Wageningen Food Valley, a global hub for agri-food research, drives significant innovation in lipid nutrition ingredient development. This cluster influences product formulation across Europe. Research and development activities here address both sustainability and functional benefits.
United States
Consumer demand for personalized nutrition platforms and sports nutrition supplements drives lipid consumption in the United States. The US FDA sets stringent standards for dietary supplements, ensuring product safety and efficacy. California's biotech corridor, particularly around San Diego, sees active research into novel lipid delivery systems.
Germany
Germany exhibits strong demand for Medium Chain Triglycerides in sports nutrition and Omega-3s in functional foods. EFSA approvals significantly influence product claims and market acceptance within the country. Munich's food technology sector actively develops advanced lipid formulations for diverse applications.
China
China's infant nutrition segment represents a substantial market for high-purity DHA, driven by parental focus on cognitive development. The NMPA enforces stringent GB standards for infant formula ingredients, impacting sourcing decisions. Shanghai's pharmaceutical and food ingredient manufacturing hubs actively produce specialized lipid components.
Japan
Japan's aging population fuels demand for lipid nutrition products supporting healthy aging and cognitive function. The country's food safety regulations ensure ingredient quality and consumer trust in functional foods. Tokyo's research institutions lead innovations in lipid bioavailability and novel food applications.
Brazil
Brazil shows increasing demand for fortified foods and infant nutrition products due to rising health awareness. ANVISA regulates food supplements and ingredients, ensuring compliance with national health standards. São Paulo's robust food processing industry integrates lipid ingredients into a wide array of consumer goods.
Lipid Nutrition Market Key Industry Players
Premium-margin players sit above commodity-margin players across lipid purity and application specificity, reflecting varied investment in research and processing technologies. The market structure features specialized ingredient producers, diversified food ingredient suppliers, and consumer health brands. Companies pursue capacity expansion in sustainable sourcing, particularly for algal-derived lipids, and form strategic partnerships for market access and regulatory navigation.
Within the specialized ingredient producer archetype, Koninklijke DSM N.V., a Netherlands-based company, exemplifies leadership in advanced fermentation capabilities for algal-derived lipids, reflecting a focus on sustainable, high-purity sources for infant and vegetarian applications. BASF SE, a German corporation, represents a comprehensive portfolio spanning both marine and plant-based lipid solutions, catering to diverse industrial and consumer applications across functional foods and supplements. Aker BioMarine AS, a Norway-headquartered entity, anchors the traceable, eco-harvested krill oil niche, controlling a significant portion of that specific supply chain through its eco-harvesting practices and stringent quality controls.
| Leading Market Players |
|---|
| Koninklijke DSM N.V. |
| BASF SE |
| Cargill, Incorporated |
| Archer Daniels Midland Company |
| Croda International Plc |
| Nordic Naturals, Inc. |
| Kerry Group plc |
| FMC Corporation |
| Aker BioMarine AS |
| Others |
Cost & Logistics Intelligence
High-purity, certified ingredient divergence in the lipid nutrition market dictates distinct pricing for specialized producers and shapes supply chain configurations for niche applications. This bifurcation impacts both market access and competitive dynamics.
Pricing Analysis
Value-based pricing for high-purity DHA and EPA anchors pricing in the lipid nutrition market. Quality grade and specific regulatory certifications like EFSA approvals drive price differentiation. Pricing pressure stems from increasing competition in the functional food segment. Infant formula manufacturers are least price-sensitive, prioritizing compliance and purity, while functional food companies are more sensitive.
Supply Chain Analysis
Specialized technical workforce availability in the Netherlands and Germany supports advanced lipid processing capabilities. Raw material dependencies include microalgae strains and krill biomass. Supply chain risk involves marine source volatility due to fishing quotas and climate events. Distribution runs through a mix of direct sales to large manufacturers and ingredient distributors for smaller formulators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The lipid nutrition market represents a significant cost-of-compliance story. Strict regulations like China's NMPA GB standards for infant formula ingredients create a substantial barrier-to-entry moat for compliant players.
For Market Incumbents:Acquire advanced fermentation technology patents to counter marine source volatility. Consolidate specialized algal lipid producers to secure high-purity DHA supply. This strategy mitigates threats from emerging alternative lipid sources and strengthens intellectual property. Invest in new capacity in sustainable sourcing, particularly for algal-derived lipids, to meet future demand.
For New Entrants and Emerging Players:The price-point gap between premium, certified Omega-3s and generic supplements offers an entry opportunity. Target the Southeast Asian market with fortified functional foods, leveraging health awareness. Focus on novel lipid delivery systems like microencapsulation for beverages, offering a unique go-to-market angle. This approach bypasses direct competition with established infant nutrition suppliers.
For Investors and Strategic Acquirers:Re-rating potential sits with specialized ingredient producers given their proprietary fermentation capabilities. These companies offer long-term viability through control over sustainable, high-purity lipid supply. Acquisition targets include firms with strong intellectual property in algal technology or eco-harvested krill. Watch for increasing EFSA approvals for novel health claims as an inflection indicator for market expansion.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion for Algal Lipids | Secures stable, non-marine Omega-3 supply for infant nutrition manufacturers. |
| Sustainable Sourcing Certifications | Builds consumer trust and meets demand for ethical products in North America. |
| Partnerships for Market Access | Facilitates entry into regulated markets like China for high-purity DHA. |
| Novel Delivery System R&D | Unlocks new applications in beverages and baked goods, improving bioavailability. |
| Personalized Nutrition Platform Integration | Develops customized lipid supplements based on individual biomarker testing. |
Research Approach
Multi-period observation of regulatory approvals and product launch patterns anchored the trend analysis, supplemented by interviews. We engaged with R&D directors, procurement leads, and regulatory affairs specialists. Secondary validation involved data from EFSA, FDA filings, and NMPA GB standards. This approach facilitated bottom-up and top-down triangulation of market dynamics.
Segment weighting based on product type, application, and end-user informed the analytical framework. The model integrated regional regulatory landscapes and technology adoption rates across the analysis window. CAGRs were derived from historical data analysis and projected growth drivers. Forecast inputs included Omega-3 consumption trends and algal fermentation capacity expansions.
Inputs from public health authority reports and company disclosures were available through the study window; gaps in emerging market consumption data introduce uncertainty bands. Forecasts reflect assumptions regarding regulatory stability and technological advancements. Material deviation in global trade policies or raw material availability warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nutritional Supplements
Middle East and Africa Amino Acid in Dietary Supplements Market
Nutritional Supplements
Asia Pacific Nutraceuticals Market
Nutritional Supplements
Conjugated Linoleic Acid Market
Nutritional Supplements
Botanical Supplements Market
Nutritional Supplements
Australia Whey Protein Market
Nutritional Supplements
Global Adaptogens Market
Nutritional Supplements
Nutrient Dense Food Products Market
Nutritional Supplements
Omega-3 Products Market
Nutritional Supplements
Mineral Supplements Market
Nutritional Supplements
Energy Supplements Market
Nutritional Supplements
Diet Shakes Market
Nutritional Supplements
Global Proanthocyanidins Market
Nutritional Supplements
High-Concentrated Protein Market
Nutritional Supplements
Nutraceutical Flexible Packaging Market
Nutritional Supplements
South America Botanical Supplements Market
Nutritional Supplements
US Protein Supplements Market