
 Asia-Pacific Liver Cancer Diagnostics Market | 2026-2036
Asia-Pacific Liver Cancer Diagnostics Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Liver Cancer Diagnostics Market Outlook
Japan's PMDA reclassification of liquid biopsy assays is decoupling traditional tissue-based confirmation from reimbursement eligibility. Abbott Laboratories leverages its immunoassay manufacturing scale across Southeast Asian distribution hubs. F. Hoffmann-La Roche sustains R&D intensity in circulating tumor DNA platforms for hepatocellular carcinoma surveillance. Thermo Fisher Scientific anchors its regional position through localized kit production in Singapore.
Asia-Pacific liver cancer diagnostics encompasses laboratory and imaging modalities that detect, stage, and monitor hepatocellular carcinoma and cholangiocarcinoma through biomarker quantification, radiologic visualization, or histopathologic examination, typically requiring sensitivity thresholds below 0.1% variant allele frequency for circulating DNA applications. The primary commercial purpose is to enable curative-intent intervention through early-stage identification before Milan criteria thresholds are exceeded. Biomarker segments occupy the deepest margin pools due to recurring consumable pull-through and proprietary antibody lock-in. Imaging systems compete on throughput and AI-enhanced lesion characterization, while diagnostic kits concentrate volume in centralized reference laboratories across India and Vietnam.
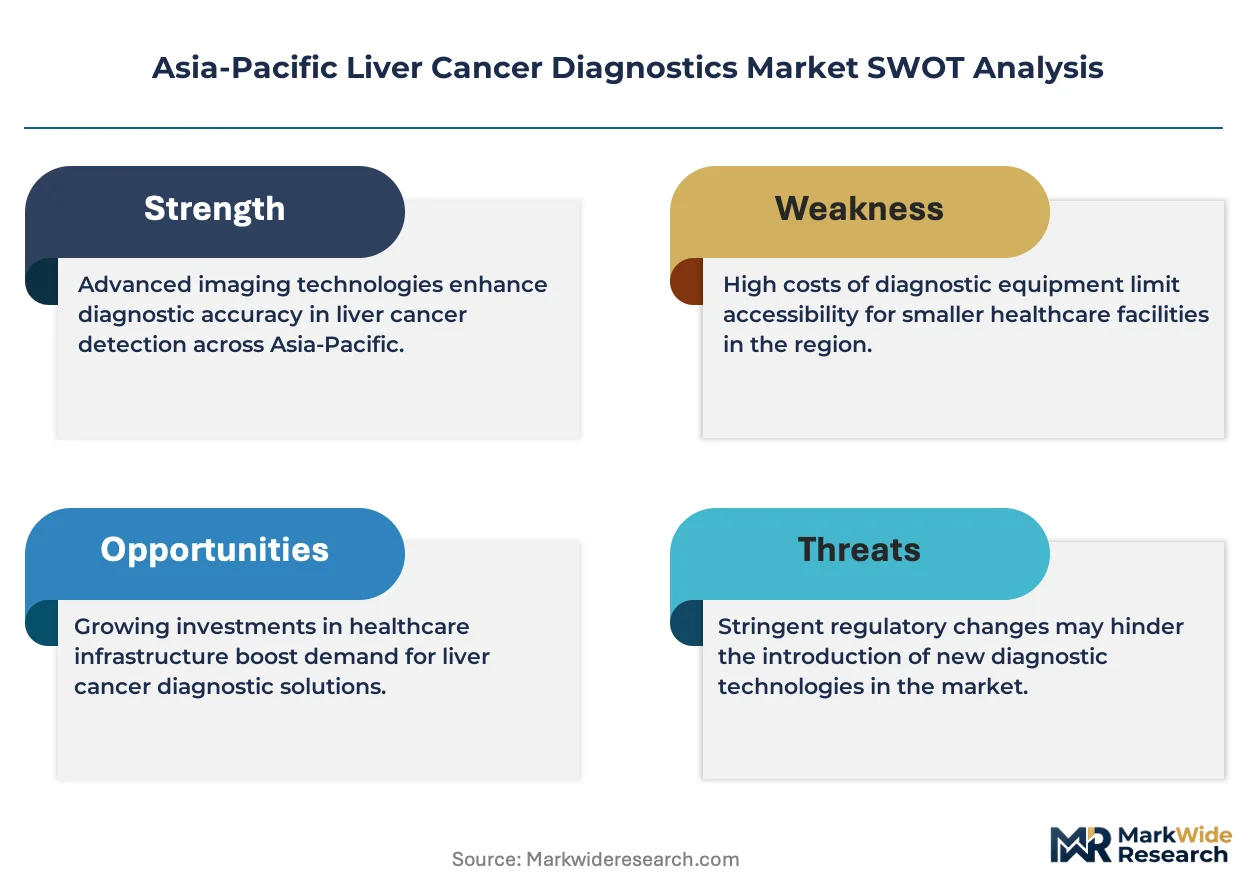
China's NMPA, Japan's PMDA, and Australia's TGA enforce divergent premarket clinical evidence standards that fragment product launch sequencing and prolong geographic expansion timelines for multinationals. India's CDSCO import licensing requirements for oncology diagnostics create additional market access friction for kit manufacturers without local manufacturing partners. Stakeholders must monitor harmonization negotiations between ASEAN medical device directives and national pharmacopeia standards to anticipate regulatory arbitrage opportunities.
Market Dynamics
China's NMPA accelerated approval pathways for companion diagnostics are compressing product registration timelines and forcing multinationals to resequence their Asia-Pacific launch strategies around tier-one hospital network procurement calendars.
Growth Catalysts
- Liquid biopsy assay reclassification:Japan's PMDA decoupling of tissue-based confirmation from reimbursement eligibility is expanding addressable patient pools for circulating tumor DNA platforms.
- Hospital-based molecular diagnostic expansion:Oncology departments across China's tier-one hospital networks are installing next-generation sequencing infrastructure to capture hepatocellular carcinoma surveillance revenue.
- Localized kit production:Singapore-based manufacturing hubs for diagnostic consumables are shortening replenishment cycles for centralized reference laboratories in Vietnam and India.
Market Restraints
- Import licensing friction:India's CDSCO requirements for oncology diagnostics create market access barriers for kit manufacturers lacking local manufacturing partnerships.
- Divergent clinical evidence standards:China's NMPA, Japan's PMDA, and Australia's TGA enforce incompatible premarket requirements that fragment geographic expansion timelines.
- Antibody supply concentration:Proprietary reagent lock-in for biomarker quantification concentrates margin capture among incumbent immunoassay suppliers.
Strategic Opportunities
- ASEAN regulatory harmonization:Negotiations between ASEAN medical device directives and national pharmacopeia standards may create arbitrage opportunities for early movers.
- AI-enhanced lesion characterization:Imaging system vendors are converging radiologic visualization with machine learning to differentiate throughput performance in Japan's specialized cancer centers.
- Cholangiocarcinoma surveillance:Underpenetrated diagnostic protocols for bile duct malignancies represent white space beyond hepatocellular carcinoma-dominated testing menus.
Industry Challenges
- Variant allele frequency sensitivity:Circulating DNA applications require sub-0.1% detection thresholds that strain laboratory quality control infrastructure and technician training pipelines.
- Legacy system integration:Hospital information system compatibility gaps complicate the deployment of integrated diagnostic workflows across China's fragmented healthcare IT landscape.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Liver Cancer Diagnostics Market |
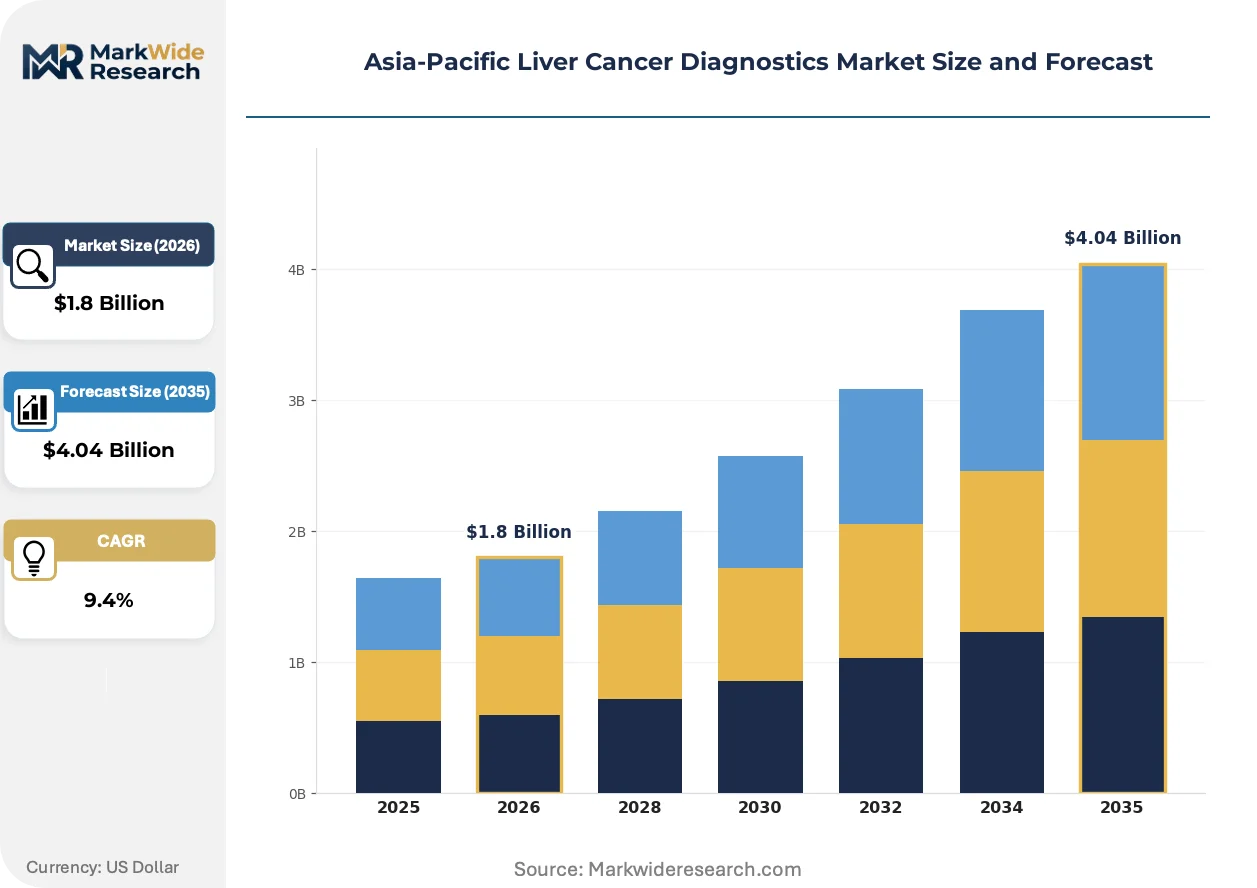
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.04 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Biomarkers, Imaging Systems, Diagnostic Kits, Liver Biopsy Supplies Technology: CT Scan, MRI, Ultrasound, Blood Tests End User: Hospitals, Diagnostic Centers, Research Laboratories, Oncology Clinics Application: Early Detection, Disease Monitoring, Treatment Efficacy, Preventive Screening |
| Companies Covered | Abbott Laboratories, F. Hoffmann-La Roche, Thermo Fisher Scientific, Qiagen, Sysmex Corporation, Hologic, Bio-Rad Laboratories, GE Healthcare, Philips Healthcare, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Liver Cancer Diagnostics Market Strategic Shifts
Diagnostic modality boundaries are dissolving as biomarker quantification converges with radiologic visualization and artificial intelligence, compressing the traditional sequencing of detection, staging, and monitoring workflows.
Next-generation sequencing-based liquid biopsy platforms are expanding into hepatocellular carcinoma surveillance applications previously dominated by ultrasound and AFP serology. Japan's specialized cancer centers are adopting these platforms for recurrence monitoring in resected patients, enabled by PMDA reimbursement reclassification. The technology is expanding into longitudinal patient management by enabling serial sampling without invasive tissue acquisition.
Australia's TGA is tightening premarket clinical evidence requirements for companion diagnostics, extending registration timelines for multinationals accustomed to FDA or CE-marking pathways. The industrial consequence is a bifurcation in product launch sequencing, with sponsors prioritizing China's NMPA or Japan's PMDA for initial Asia-Pacific market entry. High-complexity molecular diagnostic kits face the most pronounced compliance burden under these evolving standards.
Procurement centralization is consolidating purchasing authority within China's tier-one hospital network procurement consortia, displacing decentralized department-level reagent sourcing. This behavioral shift compresses vendor negotiation leverage and elevates volume-based pricing thresholds. The concentration is most visible in Shanghai and Beijing hospital clusters, where consolidated tenders now govern immunoassay consumable selection.
Asia-Pacific Liver Cancer Diagnostics Market Segmentation
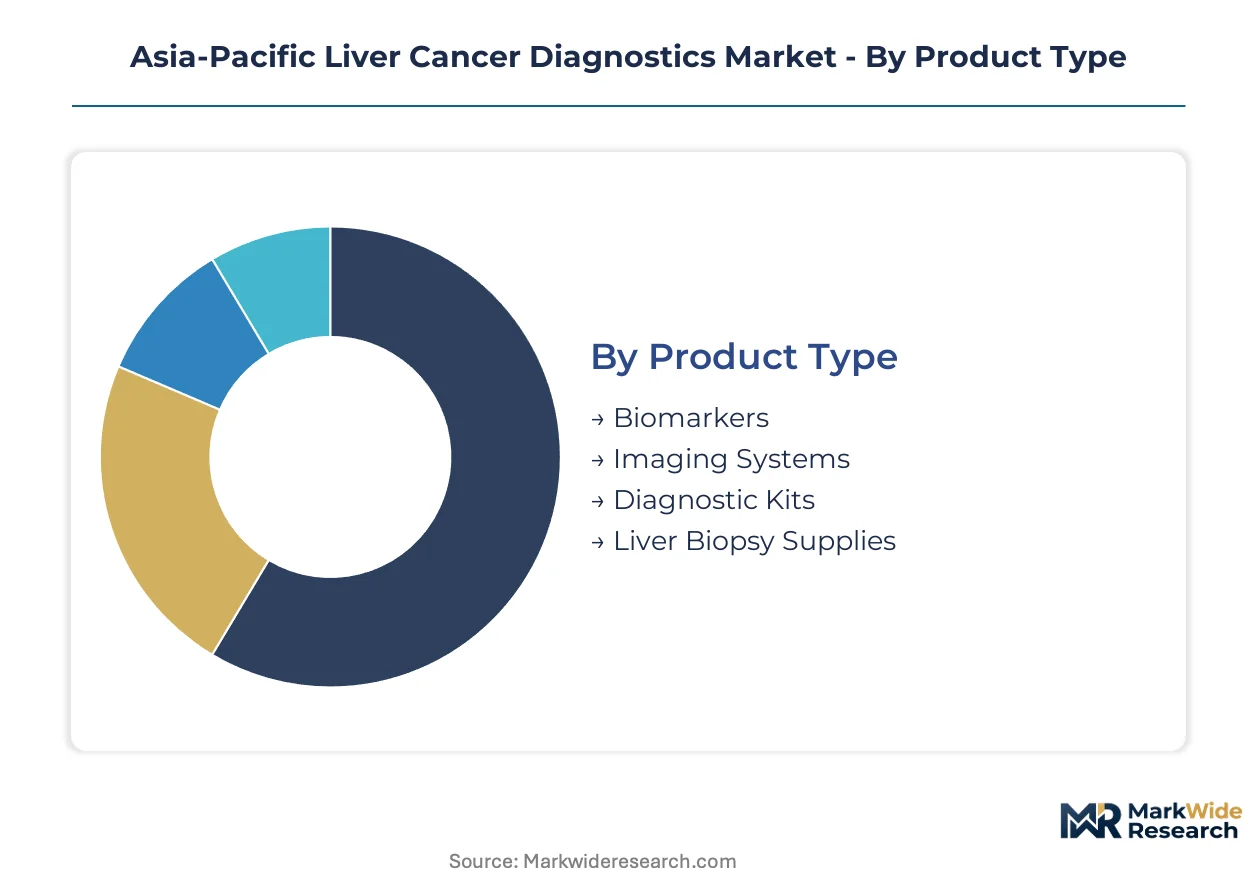
Segmentation in the Asia-Pacific liver cancer diagnostics market reveals how procurement centralization and technology substitution cycles reshape vendor priorities across biomarker platforms, imaging modalities, and care settings. Understanding these divisions exposes where margin pools concentrate and where infrastructure investments face the longest payback periods.
Product Type:
Upgrade cycles in molecular diagnostic infrastructure are accelerating replacement timelines for legacy immunoassay systems across China's tier-one hospital networks and Japan's specialized cancer centers.
- Biomarkers:Proprietary antibody-based quantification platforms deliver recurring consumable revenue through locked-in reagent contracts. Demand concentrates in centralized reference laboratories across Vietnam and India, where hepatocellular carcinoma surveillance protocols are expanding beyond traditional AFP serology.
- Imaging Systems:AI-enhanced lesion characterization capabilities differentiate CT and MRI platforms competing on throughput in high-volume oncology departments. Procurement decisions in Shanghai and Beijing hospital clusters now prioritize integrated radiologic visualization with machine learning overlays.
- Diagnostic Kits:Next-generation sequencing-based liquid biopsy kits are displacing tissue-based confirmation workflows enabled by Japan's PMDA reimbursement reclassification.
- Liver Biopsy Supplies:Invasive tissue acquisition tools face demand compression as circulating tumor DNA platforms expand into longitudinal patient management applications.
Biomarkers sit at the top of the volume ranking, with diagnostic kits climbing the fastest.
Technology:
Cost-tier differentiation separates premium imaging modalities from high-frequency screening tools, with reimbursement bandwidth determining adoption ceilings across national health systems.
- CT Scan:Contrast-enhanced computed tomography remains the staging workhorse for hepatocellular carcinoma characterization, with procurement concentrated in China's provincial hospital networks where throughput requirements exceed MRI capacity constraints.
- MRI:Magnetic resonance imaging with hepatobiliary contrast agents commands premium pricing in Japan's specialized cancer centers and Australia's tertiary referral hospitals, where lesion characterization precision drives curative-intent surgical planning.
- Ultrasound:Point-of-care abdominal sonography dominates preventive screening protocols in India's tier-two cities and Indonesia's district hospitals, constrained by operator-dependent variability that limits sensitivity for sub-centimeter lesions.
- Blood Tests:Serological panels and emerging circulating tumor DNA assays are gaining share fastest in surveillance applications, enabled by Singapore-based manufacturing hubs shortening replenishment cycles for Southeast Asian laboratories.
CT scan installations represent the largest installed base, though blood tests are expanding most quickly into longitudinal monitoring protocols.
End User:
Customer-type fragmentation creates divergent purchasing behaviors, with consolidated hospital procurement consortia displacing decentralized department-level sourcing in volume concentration zones.
- Hospitals:Oncology departments across China's tier-one networks are installing next-generation sequencing infrastructure to capture hepatocellular carcinoma surveillance revenue previously referred to external laboratories. Procurement centralization within Shanghai and Beijing hospital clusters compresses vendor negotiation leverage.
- Diagnostic Centers:Independent reference laboratories in Vietnam and India concentrate high-complexity molecular testing volume, requiring localized kit production to manage import licensing friction.
- Research Laboratories:Academic medical centers in Japan and Australia drive clinical evidence generation for companion diagnostic submissions to PMDA and TGA.
- Oncology Clinics:Specialized cancer treatment facilities prioritize integrated diagnostic workflows, though hospital information system compatibility gaps complicate deployment across China's fragmented healthcare IT landscape.
Hospitals command the deepest procurement volumes, while diagnostic centers are gaining share fastest through outsourced testing consolidation.
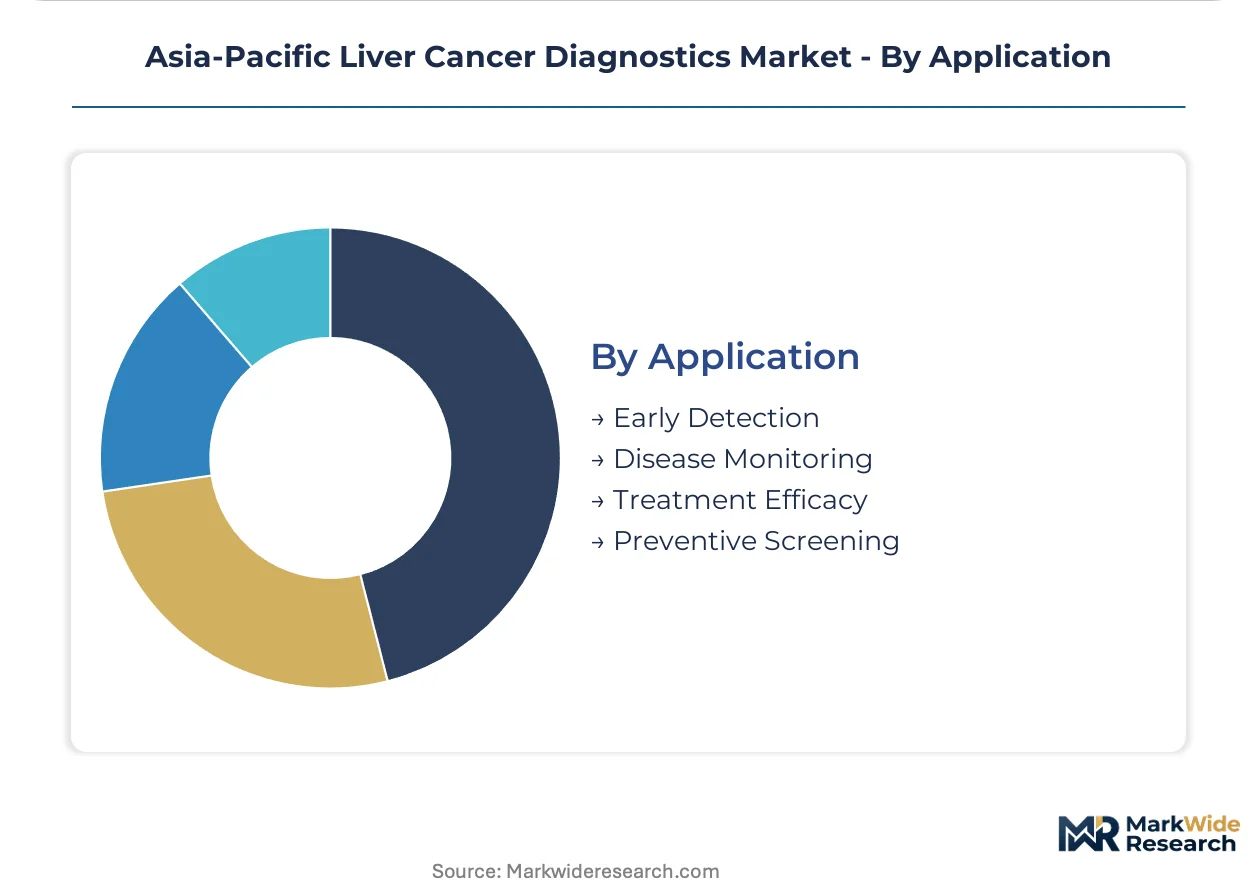
Application:
Maturity-stage differentiation separates established screening protocols from emerging surveillance applications, with technology substitution most advanced in recurrence monitoring segments.
- Early Detection:Ultrasound and AFP serology face displacement pressure from liquid biopsy platforms targeting Milan criteria thresholds before curative-intent intervention windows close. Japan's PMDA reclassification is accelerating this substitution in high-risk cirrhotic populations.
- Disease Monitoring:Circulating tumor DNA applications enable serial sampling without invasive tissue acquisition, expanding into post-resection recurrence surveillance across China's tier-one hospital networks.
- Treatment Efficacy:Companion diagnostic requirements for targeted therapies are tightening premarket clinical evidence standards under Australia's TGA, fragmenting product launch sequencing for multinationals.
- Preventive Screening:Population-scale hepatocellular carcinoma surveillance in high-prevalence regions remains underpenetrated, representing white space beyond symptomatic presentation protocols.
Disease monitoring holds the largest addressable patient pool, with early detection applications showing the steepest technology substitution trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized hepatology and oncology researchers cluster in Shanghai, Tokyo, and Singapore, anchoring molecular diagnostic innovation and clinical trial networks across the region.
China
China's tier-one hospital networks in Beijing and Shanghai are installing next-generation sequencing infrastructure for hepatocellular carcinoma surveillance. NMPA accelerated approval pathways for companion diagnostics compress registration timelines and force multinationals to resequence launch strategies around provincial procurement calendars. The Yangtze River Delta medical cluster concentrates demand for liquid biopsy platforms serving high-risk cirrhotic populations.
Japan
Japan's specialized cancer centers in Tokyo and Osaka are adopting circulating tumor DNA platforms for post-resection recurrence monitoring. PMDA reclassification of liquid biopsy assays decouples tissue-based confirmation from reimbursement eligibility, expanding addressable patient pools. The Kanto region anchors hepatobiliary contrast MRI deployment for curative-intent surgical planning.
India
India's centralized reference laboratories in Mumbai and Bangalore concentrate high-complexity molecular testing volume for hepatocellular carcinoma biomarker quantification. CDSCO import licensing requirements for oncology diagnostics create market access friction for kit manufacturers lacking local manufacturing partnerships. The Maharashtra-Gujarat corridor drives AFP serology and ultrasound screening penetration in tier-two cities.
Australia
Australia's tertiary referral hospitals in Sydney and Melbourne deploy premium MRI platforms with hepatobiliary contrast agents for lesion characterization precision. TGA tightening of premarket clinical evidence requirements for companion diagnostics extends registration timelines, bifurcating product launch sequencing. The New South Wales-Victoria cluster generates clinical evidence for PMDA and TGA submissions.
Singapore
Singapore-based manufacturing hubs shorten replenishment cycles for diagnostic consumables serving Vietnam and Indian laboratories. Localized kit production addresses import licensing friction while capturing economies of scale for Southeast Asian distribution. The city-state's biopharma infrastructure anchors regional supply chain coordination for circulating tumor DNA reagents.
Asia-Pacific Liver Cancer Diagnostics Market Competitive Environment
The competitive structure tilts toward multinational conglomerates with immunoassay manufacturing scale and specialized molecular diagnostic platform developers. Incumbent suppliers leverage proprietary antibody lock-in to capture recurring consumable revenue, while imaging system vendors differentiate on AI-enhanced lesion characterization throughput. Three archetypes dominate: scale-driven immunoassay manufacturers, precision oncology platform specialists, and integrated diagnostic workflow providers. Competitive moves concentrate on localized production partnerships and regulatory pathway optimization across NMPA, PMDA, and TGA jurisdictions.
Among scale-driven immunoassay manufacturers, Abbott Laboratories exemplifies the archetype through its Southeast Asian distribution hub network. F. Hoffmann-La Roche occupies a position representing precision oncology platform development, while Thermo Fisher Scientific anchors the integrated diagnostic workflow tier through Singapore-based manufacturing. These three entities collectively illustrate how competitive positioning fragments across manufacturing scale, R&D intensity, and supply chain localization vectors in the regional market.
| Leading Market Players |
|---|
| Abbott Laboratories |
| F. Hoffmann-La Roche |
| Thermo Fisher Scientific |
| Qiagen |
| Sysmex Corporation |
| Hologic |
| Bio-Rad Laboratories |
| GE Healthcare |
| Philips Healthcare |
| Others |
Value Chain & Pricing Dynamics
Multinational conglomerates with Singapore-based manufacturing footprints anchor supply-side discipline, compressing procurement timelines for tier-one hospital networks while extracting premium pricing through proprietary reagent lock-in. Their control over antibody supply chains feeds directly into tiered service bundling that separates consumable contracts from capital equipment sales.
Pricing Analysis
Bundled service contracts dominate premium tiers, unbundled per-test pricing prevails in economy segments. Three-tier pricing structure across premium, standard, and economy levels separates AI-enhanced imaging platforms from conventional CT installations from basic ultrasound screening. Pricing pressure stems from procurement centralization within China's hospital consortia, which compresses vendor negotiation leverage. Diagnostic centers in Vietnam and India exhibit highest price sensitivity due to import licensing friction, while Japan's specialized cancer centers accept premium positioning for PMDA-reimbursed liquid biopsy platforms.
Supply Chain Analysis
Dual-sourcing requirements from China's tier-one hospital networks mandate multi-supplier qualification for critical reagents, fragmenting single-source dependencies. Manufacturing concentrates in Singapore, China, and Japan, with Singapore-based hubs shortening replenishment cycles for Southeast Asian laboratories. Supply chains draw from specialized antibody producers, hepatobiliary contrast agents, and next-generation sequencing consumables. Single-source vulnerability concentrates in proprietary immunoassay reagents. Distribution runs through centralized reference laboratories in Vietnam and India, with direct-to-hospital channels dominating premium imaging system deployment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in this market rests on consumable pull-through acceleration and AI-enhanced imaging premiumization, with cost compression in Singapore-based manufacturing enabling tier-one hospital penetration.
For Market Incumbents: Lock in proprietary antibody supply through captive production or exclusive partnerships, securing reagent lock-in against emerging platform developers. Deepen integration into China's hospital information system infrastructure to complicate displacement by substitute liquid biopsy workflows. Prioritize NMPA companion diagnostic pathway optimization to compress registration timelines versus multinationals dependent on FDA or CE-marking sequences. For New Entrants and Emerging Players: Tier-two diagnostic centers in India's Maharashtra-Gujarat corridor represent the most penetrable buyer archetype, underserved by incumbent kit manufacturers lacking local manufacturing partnerships. Cholangiocarcinoma surveillance protocols offer white space beyond hepatocellular carcinoma-dominated testing menus. Go-to-market execution should anchor on CDSCO import licensing navigation through Singapore-based toll manufacturing partnerships. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-cap platform developers with PMDA-submitted liquid biopsy assays but pre-revenue China NMPA positioning. Long-term viability over the next decade hinges on regulatory pathway diversification across NMPA, PMDA, and TGA jurisdictions. The signal to watch is ASEAN medical device directive harmonization progress, which would unlock arbitrage opportunities for early movers with pre-qualified manufacturing footprints.| Strategic Initiative | Industry Significance |
|---|---|
| NMPA Accelerated Approval Pathway | Compresses registration timelines for companion diagnostics in China's tier-one hospital networks. |
| PMDA Liquid Biopsy Reimbursement Strategy | Expands addressable patient pools by decoupling tissue confirmation from eligibility. |
| Singapore Manufacturing Localization | Shortens replenishment cycles for Vietnam and India reference laboratories. |
| AI-Enhanced Lesion Characterization Development | Differentiates imaging platform throughput in Japan's specialized cancer centers. |
| Hospital System Partnership | Secures procurement consortia positioning in Shanghai and Beijing clusters. |
Study Parameters
Coverage spans China, Japan, India, Australia, and Singapore, with primary inputs from each market's regulatory and procurement stakeholders. The approach combines primary interviews with molecular diagnostic platform developers, hospital procurement committee members, regulatory affairs specialists at NMPA and PMDA, and GPO contracts managers with secondary validation from NMPA filings, PMDA reimbursement bulletins, ClinicalTrials.gov hepatocellular carcinoma surveillance studies, and hospital procurement database extracts. Bottom-up test volume modeling and top-down market sizing triangulate across data streams.
Rate-of-change decomposition separates volume growth from pricing trajectory across the projection horizon. The analytical framework models segmentation by product type, technology modality, end-user category, and application stage, with regional regulatory cluster as an additional dimension. CAGRs derive from test volume elasticity to hepatocellular carcinoma incidence trends, reimbursement bandwidth expansion, and technology substitution cycles in surveillance protocols. Forecast inputs include NMPA approval velocity, PMDA reclassification timing, and CDSCO import licensing clearance rates.
Underlying measurement precision varies by segment; biomarker quantification and imaging system installation data carry tighter precision than emerging liquid biopsy platform adoption curves. Forecasts reflect assumptions around regulatory pathway stability, reimbursement reclassification timing, and hospital procurement centralization momentum. Deviation in ASEAN harmonization negotiations or NMPA accelerated approval criteria would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oncology Diagnostics
Bladder Cancer Detection Kit Market
Oncology Diagnostics
Asia-Pacific Pancreatic Cancer Therapeutics and Diagnostics Market
Oncology Diagnostics
Personalized Medicine Biomarkers Market
Oncology Diagnostics
Global Hemato Oncology Testing Market
Oncology Diagnostics
Oncology Blood Testing Market
Oncology Diagnostics
Non-Hodgkin Lymphoma Diagnostics Market
Oncology Diagnostics
Glioma Diagnosis and Treatment Market
Oncology Diagnostics
Middle East and Africa Colorectal Cancer Diagnostics Market
Oncology Diagnostics
US Pancreatic Cancer Diagnostics Market
Oncology Diagnostics
Europe Bladder Cancer Therapeutics and Diagnostics Market
Oncology Diagnostics
Bladder Cancer Diagnostics Market
Oncology Diagnostics
Early-Stage Lung Cancer Diagnostics Therapy Market
Oncology Diagnostics
Middle East and Africa Bladder Cancer Therapeutics and Diagnostics Market
Oncology Diagnostics
Global Bladder Cancer Therapeutics and Diagnostics Market
Oncology Diagnostics
Cancer Biopsy Market
Oncology Diagnostics
Asia Pacific Multi-Cancer Early Detection Market