
 Subcutaneous Immunoglobulin Market | 2026-2036
Subcutaneous Immunoglobulin Market Size, Share, and Industry Trends Forecast 2026-2036
Subcutaneous Immunoglobulin Market Outlook
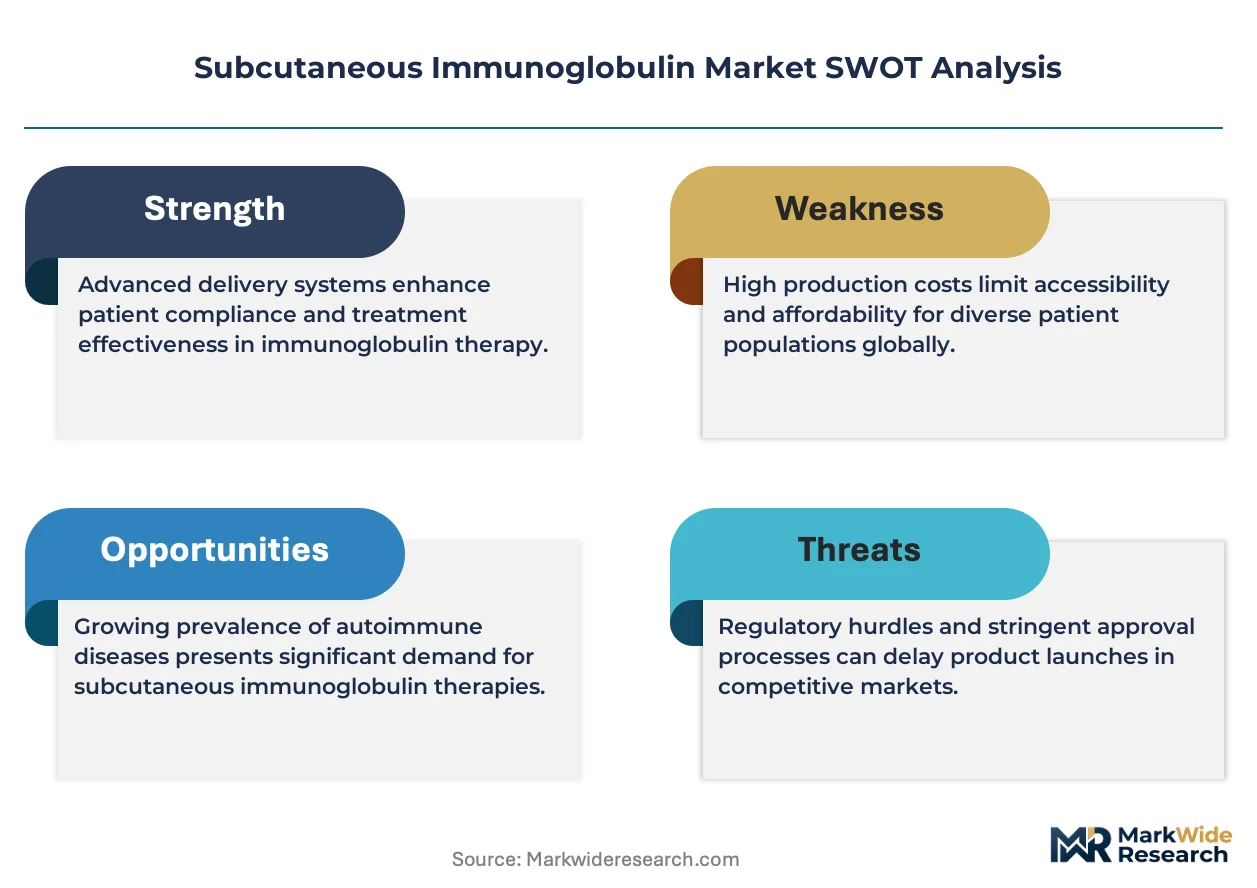
The gap between premium plasma-derived formulations and commodity immunoglobulin products is repositioning how manufacturers allocate R&D budgets. CSL Behring leverages its vertically integrated plasma collection network to sustain cost advantages across high-purity IgG lines. Takeda Pharmaceutical Company Limited anchors its position through specialized neurological disorder applications, while Grifols competes aggressively on manufacturing scale in the European supply base.
Subcutaneous immunoglobulin comprises purified human immunoglobulin G antibodies formulated for administration beneath the skin, typically at concentrations of 10-20% protein in solutions stabilized with L-proline or glycine for subcutaneous infusion over 1-2 hours. Its primary purpose is to deliver antibody replacement therapy in primary immunodeficiency and autoimmune neuromuscular conditions without requiring clinical infrastructure. The therapy area dimension shows immunodeficiency applications occupying the largest revenue pool, though autoimmune disorders represent the fastest-expanding category as off-label use broadens. Homecare delivery is displacing hospital-based administration, with specialty pharmacies capturing margin from the channel shift.
The FDA enforces Current Good Manufacturing Practice standards for plasma fractionation, while the EMA's Committee for Medicinal Products for Human Use reviews immunoglobulin submissions under centralized procedures. These frameworks elevate barriers for new entrants and protect incumbent quality premiums. Stakeholders must monitor how biosimilar regulatory pathways evolve for plasma-derived biologics, as this will determine whether price compression or brand loyalty defines the next competitive phase.
Market Dynamics
Homecare administration is compressing the role of infusion centers as patients master self-injection techniques with 20% concentrated formulations, forcing manufacturers to redesign packaging for refrigerator-stable unit doses and specialty pharmacies to build cold-chain logistics for direct-to-patient delivery.
Growth Catalysts
- FDA Plasma Purity Mandates:Tightened viral inactivation standards for immunoglobulin products are elevating quality premiums and accelerating facility upgrades across fractionation plants.
- Primary Immunodeficiency Prevalence:Expanded newborn screening programs in the United States are identifying antibody-deficient patients earlier, extending therapy initiation timelines.
- L-proline Stabilization Chemistry:Improved protein stability at room temperature is enabling longer infusion intervals and reducing patient adherence barriers.
Market Restraints
- Plasma Collection Bottlenecks:Dependence on US-based donor centers creates supply vulnerability when collection volumes fluctuate seasonally or during public health disruptions.
- EMA Centralized Review Timelines:Extended marketing authorization procedures for plasma-derived biologics delay European market entry by 18-24 months relative to US approvals.
- Intravenous Immunoglobulin Substitution:Hospital-based IVIG retains reimbursement advantages in several EU member states, slowing subcutaneous conversion rates.
Strategic Opportunities
- Neurological Autoimmune Expansion:CIDP and myasthenia gravis applications represent underpenetrated therapy areas with limited approved alternatives.
- Specialty Pharmacy Direct Distribution:Bypassing hospital outpatient departments captures margin from channel consolidation and improves patient data capture.
- Japanese Aging Demographics:PMDA fast-track pathways for rare disease therapies position subcutaneous immunoglobulin for accelerated uptake among elderly immunodeficient patients.
Industry Challenges
- Plasma Fractionation Expertise Scarcity:Specialized biochemical engineers with viral inactivation experience command premium compensation and limited mobility between facilities.
- Legacy Hospital Contract Renegotiation:Existing IVIG purchasing agreements with group purchasing organizations create switching friction for subcutaneous alternatives.
- Cold-Chain Integrity Verification:Temperature excursion documentation requirements for home delivery impose last-mile logistics complexity on specialty pharmacy networks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Subcutaneous Immunoglobulin Market |
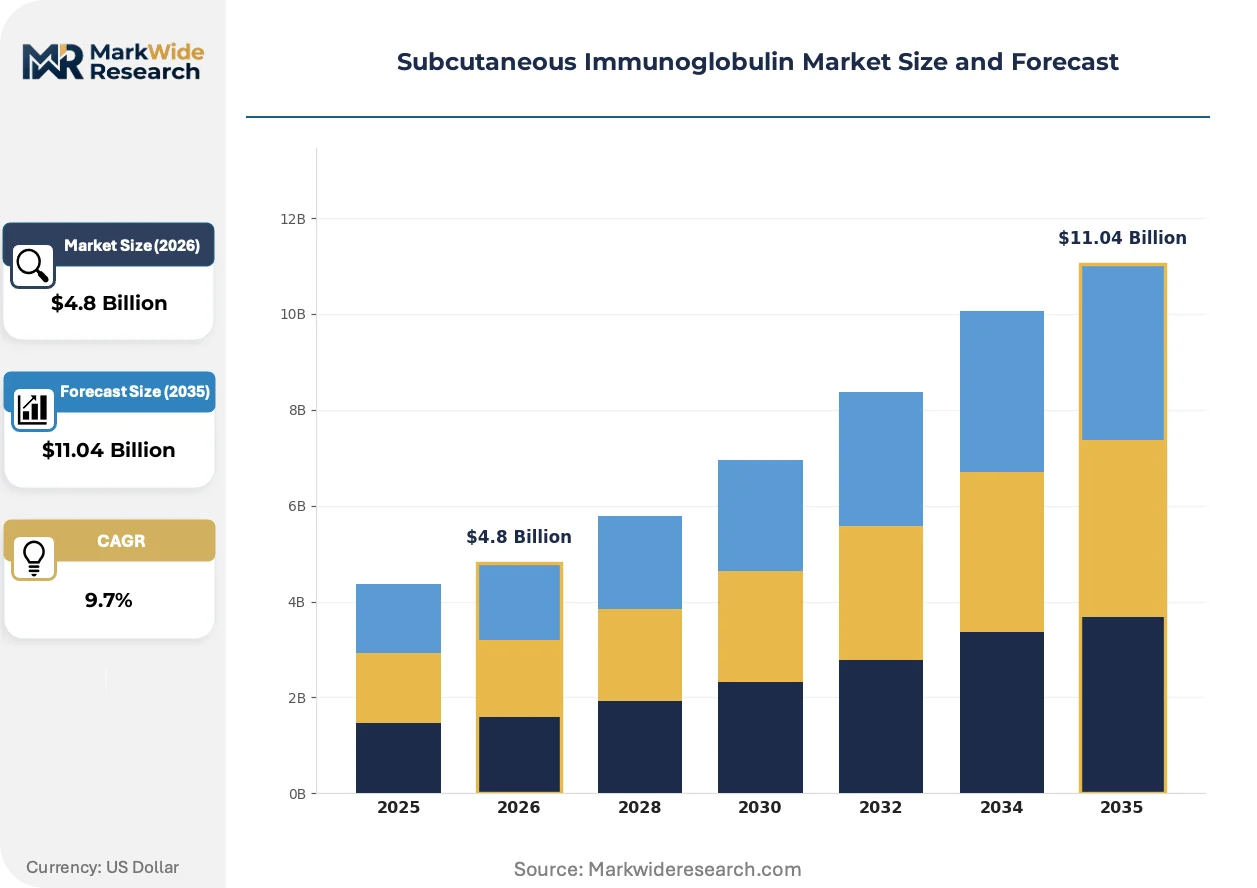
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $11.04 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: IgG, IgA, IgM, IgE Therapy Area: Immunodeficiency, Autoimmune Disorders, Inflammatory Conditions, Neurological Disorders Delivery Mode: Intravenous, Subcutaneous, Intramuscular, Oral End User: Hospitals, Clinics, Homecare, Specialty Pharmacies |
| Companies Covered | Octapharma, Biotest AG, Takeda Pharmaceutical Company Limited, Johnson & Johnson, Pfizer Inc., CSL Behring, Kedrion Biopharma, ADMA Biologics, Grifols, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Subcutaneous Immunoglobulin Market Strategic Shifts
Formulation science and patient-administration interfaces are converging to reduce treatment burden, while regulatory frameworks on both sides of the Atlantic recalibrate purity thresholds and reimbursement logic.
Recombinant hyaluronidase co-formulation is integrating with standard immunoglobulin products to accelerate subcutaneous absorption rates and reduce infusion site volumes. Neurology and immunology practices in Germany and the United States are piloting these enhanced formulations for CIDP patients with limited subcutaneous tissue availability. This enzyme-assisted delivery technology is integrating hospital-grade efficacy into home-based administration protocols, compressing the clinical infrastructure required for effective therapy.
EMA's revised guideline on plasma-derived medicinal products now mandates enhanced prion removal validation for all new immunoglobulin submissions, effective across centralized procedures. Fractionators must demonstrate nanofiltration performance below 15 nanometers or deploy alternative orthogonal viral clearance methods. High-dose subcutaneous products with extended administration intervals face the steepest compliance burden, as protein concentration complicates impurity clearance validation.
Patients with primary immunodeficiency are consolidating prescription fulfillment through vertically integrated specialty pharmacy platforms that bundle medication with nursing support and adherence monitoring. This channel concentration displaces traditional retail pharmacy and hospital outpatient dispensing in the United States, where payers increasingly require mandatory specialty pharmacy enrollment for biologic coverage. The shift is most visible among commercial insurance populations in California and Texas, where integrated delivery networks have captured majority market share.
Subcutaneous Immunoglobulin Market Segmentation
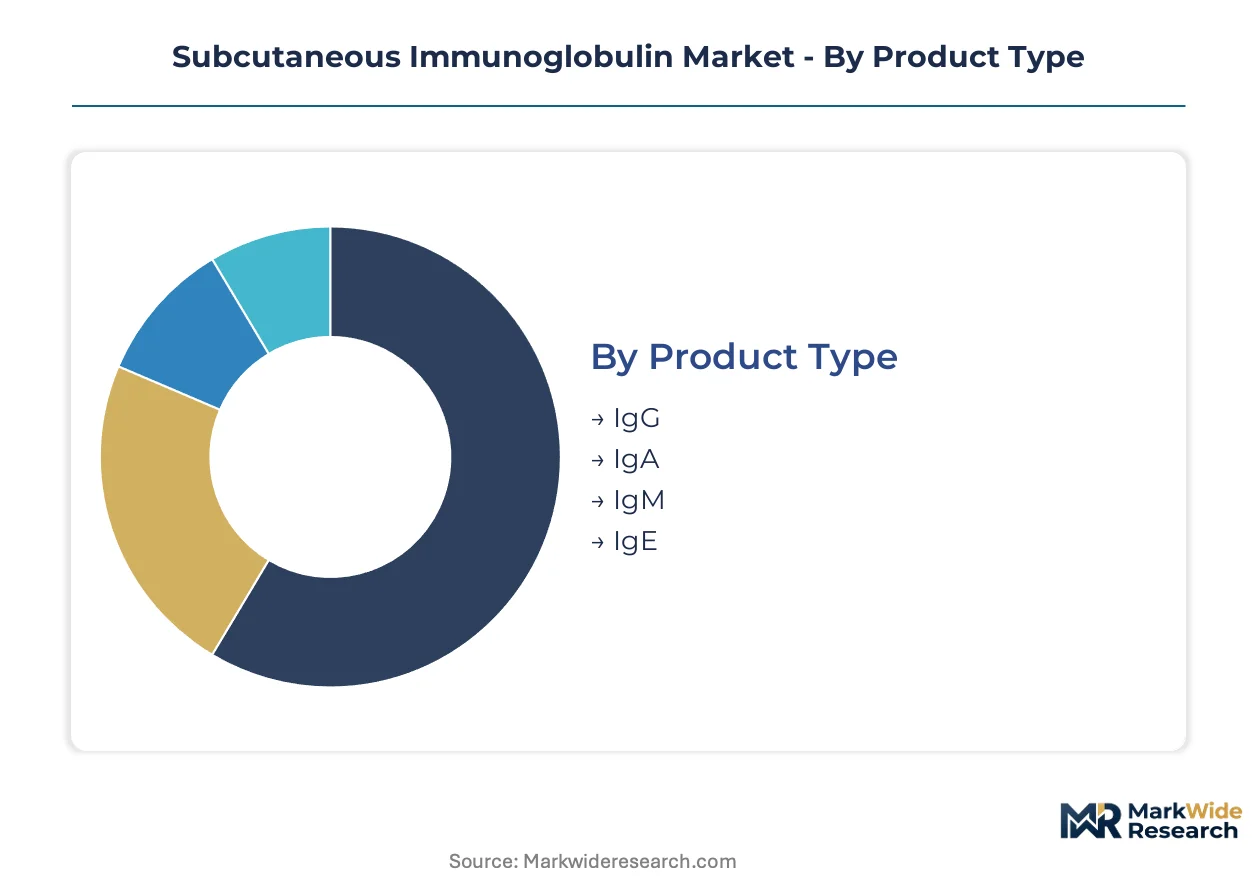
Subcutaneous immunoglobulin manufacturers calibrate formulation portfolios against therapy-specific dosing regimens and administration settings. Segmentation clarity determines which purity grades and concentration formats justify dedicated production lines versus flexible multi-purpose fractionation.
Product Type:
IgG formulations dominate upgrade cycles as clinicians shift patients from intravenous to subcutaneous protocols with higher protein concentrations.
- IgG:Purified immunoglobulin G antibodies at 10-20% protein concentration serve as the primary replacement therapy for antibody-deficient patients. United States specialty pharmacies now capture the majority of IgG volume as homecare administration displaces hospital-based infusion.
- IgA:Selective IgA deficiency applications require specialized formulations with trace IgA removal for patients who develop anti-IgA antibodies. European demand concentrates in Germany and France where newborn screening programs identify selective deficiencies earlier.
- IgM:Pentameric immunoglobulin M concentrates address rare early complement pathway disorders with acute infection prophylaxis requirements.
- IgE:Allergen-specific immunoglobulin E therapies remain experimental with limited commercial fractionation dedicated to this isotype.
Volume placements concentrate in IgG; the faster expansion belongs to IgA as diagnostic protocols improve.
Therapy Area:
Cost tier differentiation separates prophylactic immunodeficiency maintenance from high-dose autoimmune intervention protocols.
- Immunodeficiency:Primary antibody deficiency syndromes require lifelong replacement with 0.4-0.6g/kg monthly dosing. United States commercial payers now mandate specialty pharmacy fulfillment for these chronic therapies, compressing hospital outpatient revenue.
- Autoimmune Disorders:Chronic inflammatory demyelinating polyneuropathy and myasthenia gravis applications use higher 2g/kg induction doses. Japanese PMDA fast-track designations are accelerating approval timelines for these neurological indications.
- Inflammatory Conditions:Dermatomyositis and systemic lupus erythematosus represent off-label use categories with variable reimbursement acceptance across European markets.
- Neurological Disorders:Multifocal motor neuropathy and stiff-person syndrome command premium pricing due to limited therapeutic alternatives and orphan disease designation eligibility.
Revenue concentrates in immunodeficiency maintenance; autoimmune neurology is climbing the fastest as CIDP protocols convert from intravenous to subcutaneous administration.
Delivery Mode:
Application-specific administration routes determine cold-chain requirements and patient training intensity for each channel.
- Intravenous:Hospital and infusion center administration retains reimbursement advantages in several EU member states despite patient preference for home-based alternatives. Germany's outpatient clinic networks still favor IVIG for complex neurological dosing.
- Subcutaneous:Weekly or biweekly self-administration with 20% concentrated formulations reduces treatment burden. California and Texas integrated delivery networks have captured majority market share through mandatory specialty pharmacy enrollment.
- Intramuscular:Limited to specific prophylactic applications with lower protein requirements and higher local reaction rates.
- Oral:No clinically effective oral immunoglobulin absorption exists; this segment comprises research-stage mucosal delivery programs.
Patient volumes concentrate in subcutaneous delivery; intravenous retains the steepest expansion trajectory only in markets with reimbursement rigidities.
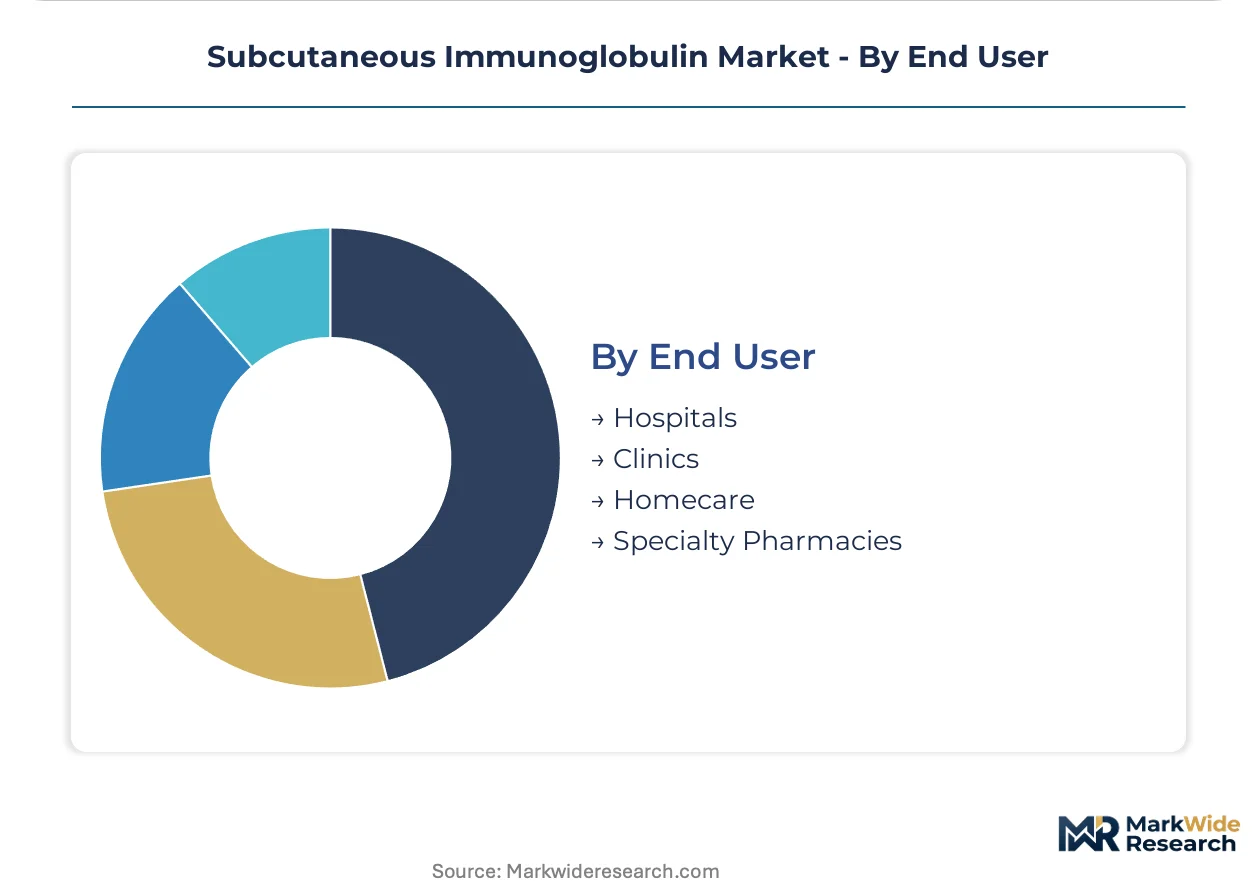
End User:
Customer type segmentation tracks the margin migration from hospital purchasers to vertically integrated specialty pharmacy platforms.
- Hospitals:Academic medical centers retain complex neurological induction dosing and patients with vascular access limitations. EMA centralized review timelines delay European hospital formulary additions by 18-24 months relative to US approvals.
- Clinics:Private infusion centers face margin compression as patients master self-injection techniques and migrate to homecare.
- Homecare:Direct-to-patient delivery with refrigerator-stable unit doses now dominates primary immunodeficiency maintenance. FDA viral inactivation mandates elevate quality premiums that homecare patients accept for convenience gains.
- Specialty Pharmacies:Vertically integrated platforms bundle medication with nursing support and adherence monitoring, displacing traditional retail pharmacy in US commercial insurance populations.
Prescription volume concentrates in specialty pharmacy channels; homecare is gaining share fastest as self-administration training protocols standardize.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Greater Philadelphia anchors plasma fractionation capacity with CSL Behring's vertically integrated collection network serving specialty pharmacy channels nationwide. FDA viral inactivation mandates drive facility upgrades across US production bases.
United States
Newborn screening expansion in California and Texas identifies primary immunodeficiency patients earlier, extending therapy initiation timelines. FDA tightened Current Good Manufacturing Practice standards for plasma-derived products in 2023. Specialty pharmacy networks in the Northeast Corridor capture majority market share through mandatory payer enrollment requirements.
Germany
Outpatient clinic networks in Bavaria and North Rhine-Westphalia retain IVIG preference for complex neurological dosing protocols. EMA centralized review timelines delay subcutaneous immunoglobulin formulary additions by 18-24 months versus US approvals. Berlin-based fractionators navigate enhanced prion removal validation requirements under revised EMA guidelines.
Japan
Aging demographics in the Kanto region accelerate demand for home-based administration among elderly immunodeficient patients. PMDA fast-track pathways for rare disease therapies compress approval timelines for CIDP applications. Osaka-based neurology practices pilot hyaluronidase co-formulation for patients with limited subcutaneous tissue availability.
France
ANSM oversight of plasma-derived biologics maintains stringent batch release protocols for Paris-region distribution centers. Selective IgA deficiency screening programs in Île-de-France identify specialized formulation requirements earlier in patient lifecycles. Lyon-based hospital networks negotiate legacy IVIG purchasing agreements that create switching friction for subcutaneous alternatives.
United Kingdom
NHS England specialty pharmacy frameworks consolidate immunoglobulin procurement through national tender mechanisms. MHRA post-Brexit regulatory autonomy enables accelerated review pathways for stabilized formulations. London academic medical centers retain complex induction dosing for multifocal motor neuropathy patients with limited therapeutic alternatives.
Subcutaneous Immunoglobulin Market Competitive Environment
Premium-margin players sit above commodity-margin players across purity-grade and concentration-format dimensions, with quality premiums widening under tightening FDA viral inactivation standards. The vendor base clusters around three strategic archetypes: vertically integrated plasma collectors with captive fractionation capacity, specialized neurological disorder application developers, and scale-driven European supply base operators. Dominant competitive moves include backward integration into plasma collection networks and capacity expansion for 20% concentrated formulations serving homecare channels.
Within the integrated plasma collector tier, CSL Behring and Grifols occupy positions exemplifying cost advantages across high-purity IgG production lines. Takeda Pharmaceutical Company Limited anchors the specialized application archetype through neurological disorder focus. These three entities represent distinct competitive vectors: Australian-origin vertical integration, Spanish-origin European manufacturing scale, and Japanese-origin rare disease regulatory acceleration.
| Leading Market Players |
|---|
| Octapharma |
| Biotest AG |
| Takeda Pharmaceutical Company Limited |
| Johnson & Johnson |
| Pfizer Inc. |
| CSL Behring |
| Kedrion Biopharma |
| ADMA Biologics |
| Grifols |
| Others |
Value Chain & Pricing Dynamics
Captive plasma collection networks anchor both supply security and pricing power across high-purity immunoglobulin lines, with CSL Behring's vertically integrated donor centers in the United States creating cost advantages that commodity fractionators cannot replicate. This backward integration into source plasma insulates premium manufacturers from donor volume volatility while justifying quality premiums under tightening FDA viral inactivation mandates.
Pricing Analysis
Outcome-based pricing anchors immunoglobulin contracts to clinical response metrics in neurological autoimmune applications, with CIDP protocols commanding the steepest premiums due to limited therapeutic alternatives. Pricing stratifies across premium, standard, and economy tiers based on protein concentration purity and FDA certification grade, while cost compression in standard-grade IgG intensifies as biosimilar pathways mature. Hospital purchasing committees demonstrate the highest price sensitivity, whereas specialty pharmacy direct distribution absorbs moderate premiums for convenience and adherence bundling.
Supply Chain Analysis
Cold-chain logistics costs consume disproportionate margin in direct-to-patient delivery, with temperature excursion documentation requirements imposing last-mile complexity on specialty pharmacy networks. Plasma supply concentrates in United States donor centers, with secondary collection nodes in Germany and Austria supporting European fractionation capacity. Raw material dependencies include source plasma, L-proline stabilization chemistry, and recombinant hyaluronidase enzyme feedstocks. Single-source vulnerability in US plasma collection creates supply risk during public health disruptions. Distribution runs through vertically integrated specialty pharmacy platforms that displace hospital outpatient dispensing.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Plasma fractionation expertise scarcity is accelerating consolidation as FDA purity mandates force facility upgrades that weaker players cannot finance, compressing the vendor base toward integrated collectors with captive donor networks.
For Market Incumbents: Lock in plasma supply through long-term donor center contracts and captive collection network expansion in Texas and California, where newborn screening expansion extends patient identification timelines. Accelerate 20% concentrated formulation capacity to capture homecare channel migration before reimbursement differentials erode. Defend against intravenous immunoglobulin substitution in EU markets by piloting hyaluronidase co-formulation for neurological indications with limited subcutaneous tissue availability. For New Entrants and Emerging Players: Specialty pharmacy partnerships offer the fastest channel access for subscale fractionators lacking GPO contracts with hospital systems. Target Japanese neurological autoimmune applications where PMDA fast-track pathways compress approval timelines relative to EMA centralized review. Pursue selective IgA deficiency formulations in France and Germany, where diagnostic protocol improvements create specialized demand underserved by commodity IgG producers. For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by integrated plasma collectors seeking geographic capacity expansion or neurological application expertise. Five-to-ten year viability favors fractionators with demonstrated nanofiltration below 15 nanometers and established specialty pharmacy relationships. Watch EMA biosimilar pathway rulings for plasma-derived biologics as the inflection signal determining whether price compression or brand loyalty defines the next competitive phase.| Strategic Initiative | Industry Significance |
|---|---|
| Plasma Collection Network Expansion | Captive donor centers in Texas and California insulate supply security against seasonal collection volatility. |
| 20% Concentrated Formulation Scale-Up | Higher protein concentrations enable extended infusion intervals that reduce patient adherence barriers. |
| Hyaluronidase Co-Formulation Development | Enzyme-assisted absorption technology compresses clinical infrastructure for home-based CIDP administration. |
| Specialty Pharmacy Direct Distribution | Bypassing hospital outpatient departments captures margin from channel consolidation and improves adherence data capture. |
| EMA Prion Removal Validation | Demonstrating nanofiltration performance below 15 nanometers secures marketing authorization under revised guidelines. |
Study Parameters
Multi-period observation of FDA submission timelines, EMA centralized review durations, and specialty pharmacy enrollment rates anchored the trend analysis, supplemented by interviews with plasma fractionation executives, regulatory affairs leads at major manufacturers, formulary directors at US payers, and procurement managers at German hospital networks. Secondary validation drew from FDA Current Good Manufacturing Practice guidance documents, EMA Committee for Medicinal Products for Human Use assessment reports, ClinicalTrials.gov immunoglobulin protocol registrations, and CMS Medicare Part B reimbursement data. Bottom-up patient population estimates triangulated against top-down manufacturer revenue disclosures.
Segment-weighting approaches modeled therapy area splits between immunodeficiency maintenance and autoimmune neurology, product type concentration across IgG purity grades, delivery mode transition from intravenous to subcutaneous administration, and end-user channel migration toward specialty pharmacy platforms. CAGRs were derived from patient volume trajectories, dosing regimen evolution, and pricing tier dynamics across the projection horizon. Forecast inputs incorporated newborn screening expansion timelines, PMDA fast-track designation patterns, and EMA prion removal validation requirements.
Caveats apply where EMA biosimilar pathway rulings, FDA viral inactivation standard revisions, or plasma collection disruption events could materially shift the outlook. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Europe Parenteral Lipid Emulsion Market
Pharmaceuticals
Collagenase Clostridium Histolyticum Market
Pharmaceuticals
Latin America Sodium-Glucose Cotransport-2 (SGLT-2) Inhibitor Market
Pharmaceuticals
Europe Sodium-Dependent Glucose Cotransporter 2 Market
Pharmaceuticals
Global Desmopressin Market
Pharmaceuticals
Global Respiratory Drug Market
Pharmaceuticals
Organ Transplant Rejection Medications Market
Pharmaceuticals
Medical Grade Sodium Hyaluronate Market
Pharmaceuticals
Male Hypogonadism Market
Pharmaceuticals
Global Pharmaceutical Traceability Market
Pharmaceuticals
Europe FMD Vaccine Market
Pharmaceuticals
Estonia Pharmaceutical Market
Pharmaceuticals
Empty Capsules Market
Pharmaceuticals
US Generic Injectables Pharmaceutical Contract Manufacturing Market
Pharmaceuticals
Europe Alpha-Glucosidase Inhibitors Market
Pharmaceuticals
Traumatic Brain Injury Drugs Market