
 Latin America Biguanide Market | 2026-2036
Latin America Biguanide Market Size, Share, and Industry Trends Forecast 2026-2036
Latin America Biguanide Market Foresight
Maintenance contracts for therapeutic monitoring software is shifting how pharmaceutical distributors monetize biguanide portfolios in Latin America. Sanofi leverages its established insulin co-marketing infrastructure to bundle metformin adherence programs across Brazilian pharmacy chains. Merck & Co., Inc. anchors regional supply through its manufacturing partnerships with Argentine API producers. Boehringer Ingelheim International GmbH differentiates via fixed-dose combination strategies that pair biguanides with SGLT2 inhibitors.
Biguanides constitute a class of oral hypoglycemic agents characterized by a guanide-derived core structure that suppresses hepatic gluconeogenesis and enhances peripheral insulin sensitivity. Metformin dominates the product type landscape as the first-line therapy for Type 2 Diabetes across Latin American formularies, while extended-release tablets capture expanding share due to improved gastrointestinal tolerability profiles. The Therapy Area segmentation reveals Type 2 Diabetes as the mature revenue base, with Polycystic Ovary Syndrome representing the fastest-growing off-label utilization corridor where margin pools concentrate in specialty clinic channels.
ANVISA governs biguanide registration and bioequivalence certification in Brazil, while COFEPRIS enforces GMP inspections for Mexican manufacturing facilities, and INVIMA oversees import licensing for Colombian distributors. These regulators collectively elevate quality thresholds that filter out substandard generic entrants and redirect procurement toward validated suppliers. Stakeholders must monitor pending harmonization initiatives across Mercosur pharmacopeia standards that could unify dissolution testing protocols and reshape competitive access dynamics.
Market Dynamics
ANVISA's updated bioequivalence requirements for generic biguanides are compressing supplier margins while redirecting procurement toward validated manufacturers across Brazilian public health networks.
Growth Catalysts
- Type 2 Diabetes prevalence:Rising diagnosis rates across Brazilian public health networks are expanding prescription volumes for first-line metformin therapies.
- ANVISA harmonization initiatives:Pending Mercosur pharmacopeia standardization is dissolving cross-border regulatory friction for validated suppliers.
- Extended-release formulations:Improved gastrointestinal tolerability profiles are capturing share in Mexico's hospital procurement systems.
Market Restraints
- API supply concentration:Argentine active pharmaceutical ingredient producers face input cost volatility from imported chemical precursors.
- COFEPRIS inspection backlog:Extended GMP certification timelines for Mexican manufacturing facilities are constraining capacity expansion.
- SGLT2 inhibitor substitution:Fixed-dose combination therapies pairing biguanides with newer drug classes are fragmenting standalone metformin demand.
Strategic Opportunities
- Polycystic Ovary Syndrome corridors:Off-label utilization in Colombian specialty clinic channels represents an underpenetrated margin pool.
- Centralized tender digitization:Mexico's hospital procurement systems are migrating toward electronic auction platforms that favor extended-release suppliers.
- Therapeutic monitoring convergence:Adherence program bundling with insulin co-marketing infrastructure is rewriting distributor monetization models.
Industry Challenges
- Bioequivalence study capacity:Brazilian contract research organizations face talent scarcity in biostatistics and clinical pharmacology functions.
- Legacy formulation integration:Immediate-release metformin manufacturers struggle to reconfigure production lines for extended-release tablet specifications.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Latin America Biguanide Market |
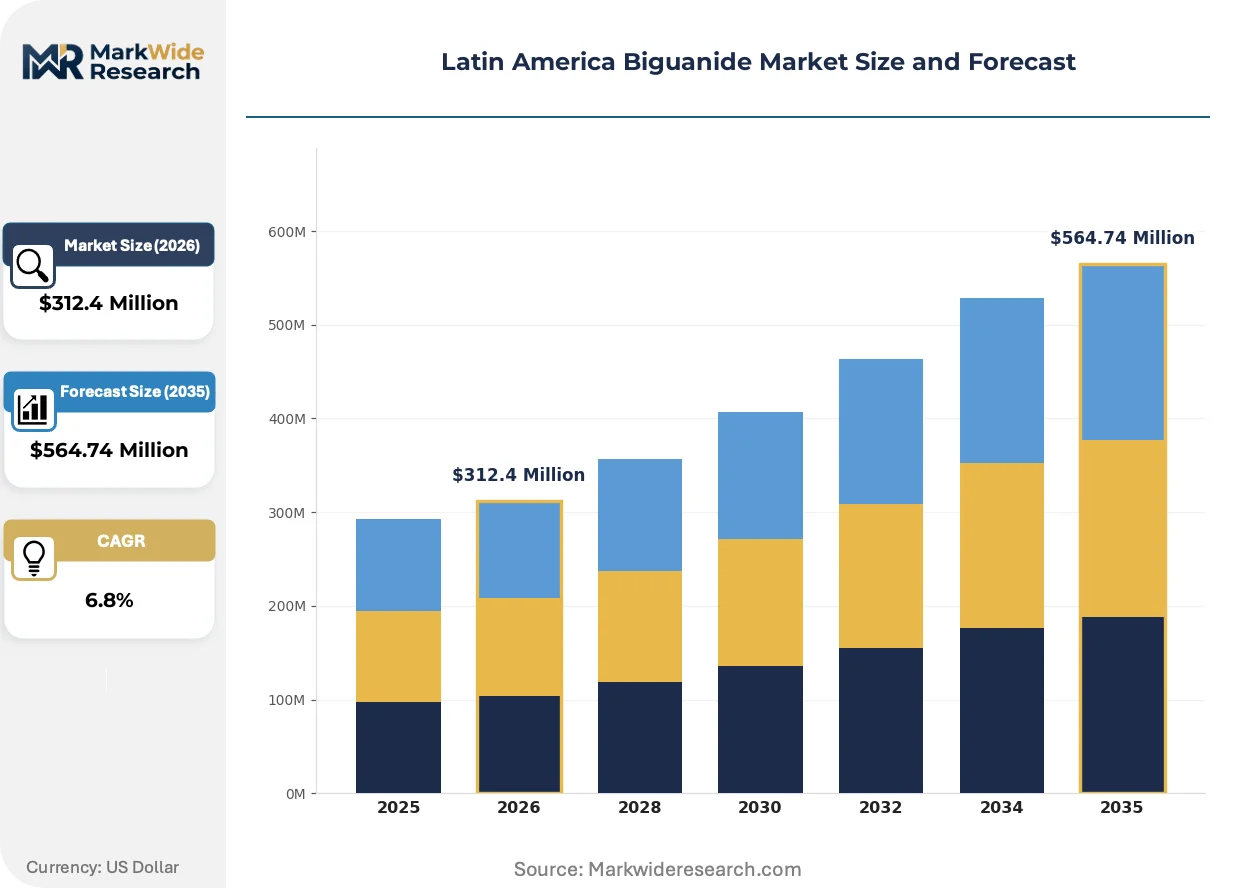
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $564.74 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Metformin, Phenformin, Buformin, Proguanil Therapy Area: Type 2 Diabetes, Polycystic Ovary Syndrome, Obesity Management, Antimalarial Treatment End User: Hospitals, Specialty Clinics, Research Laboratories, Community Pharmacies Formulation Type: Tablets, Extended-Release Tablets, Oral Solutions, Injectable Solutions |
| Companies Covered | Sanofi, Merck & Co., Inc., Bristol-Myers Squibb Company, GlaxoSmithKline plc, Boehringer Ingelheim International GmbH, Glenmark Pharmaceuticals Ltd., Takeda Pharmaceutical Company Limited, Teva Pharmaceutical Industries Ltd., Cipla Ltd., Others |
| Regions Covered | Latin America: Brazil, Mexico, Argentina, Colombia, Chile, Peru, Rest of Latin America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Latin America Biguanide Market Shifts & Advancements
Formulation science and regulatory digitization are compressing traditional competitive advantages while elevating quality-validation capabilities as the primary barrier to market access.
Extended-release matrix technologies are rewriting gastrointestinal tolerability benchmarks for biguanide therapies. Mexican hospital procurement systems are prioritizing these formulations in centralized tenders. The shift is compressing immediate-release tablet margins while rewarding suppliers with validated modified-release capabilities.
COFEPRIS is accelerating GMP inspection digitization through remote audit protocols for Mexican manufacturing facilities. The policy reduces certification timelines from eighteen to twelve months for compliant sites. Argentine API producers are investing in real-time documentation systems to qualify for expedited review.
Hospital procurement consolidation across Brazilian state health networks is compressing supplier rosters to three-to-five validated manufacturers per region. Electronic tender platforms are displacing traditional distributor relationships in São Paulo and Minas Gerais. The concentration is most visible in southeastern states where unified purchasing coalitions now dominate volume allocation.
Latin America Biguanide Market Segmentation
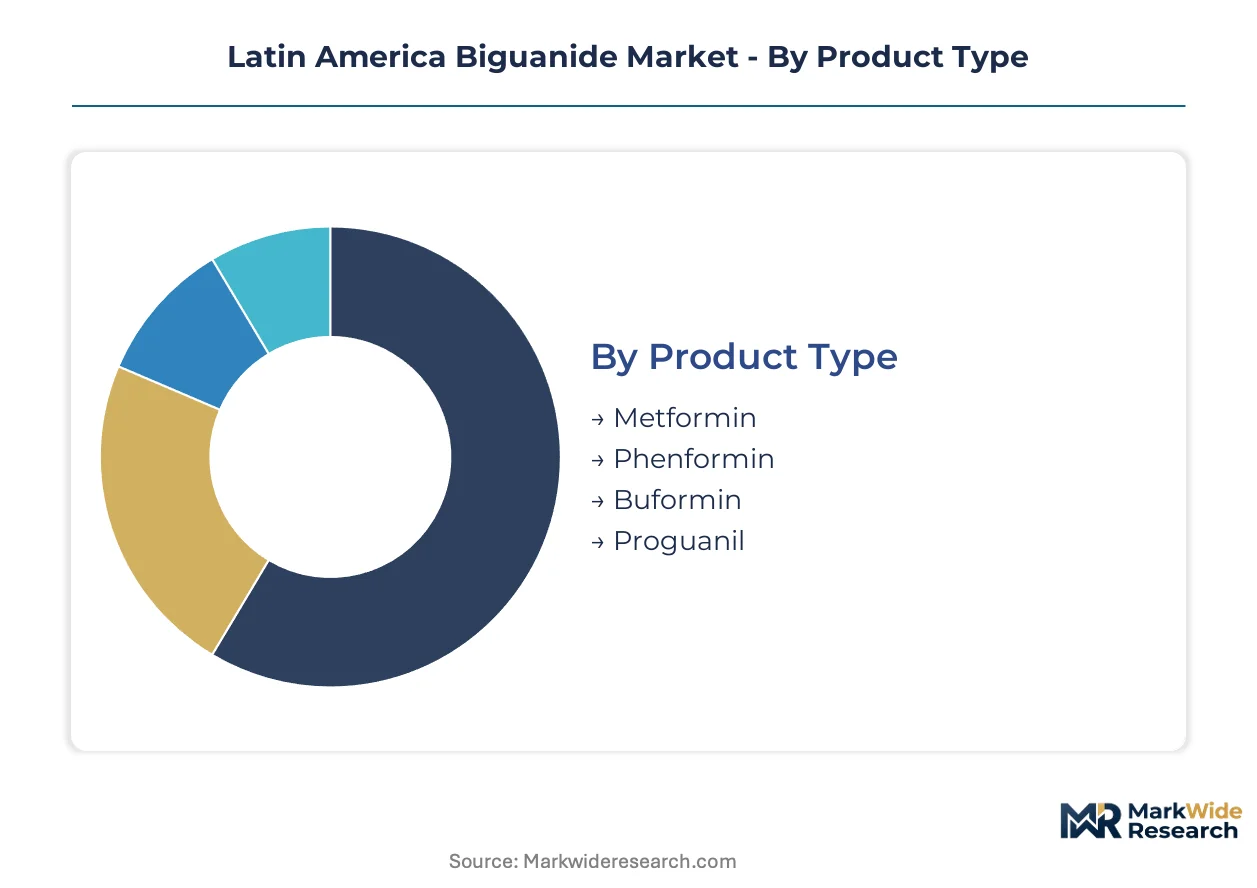
Biguanide segmentation in Latin America reflects divergent clinical priorities across public health networks and private channels. Formulation specifications and therapy-area targeting determine access to procurement tenders and specialty clinic margins.
Product Type:
Active ingredient chemistry dictates manufacturing complexity and regulatory pathway requirements across Brazilian and Mexican production sites.
- Metformin:The guanide-derived biguanide suppresses hepatic gluconeogenesis through AMPK pathway activation. Brazilian public health networks concentrate prescription volumes here as first-line Type 2 Diabetes therapy, with ANVISA bioequivalence standards filtering supplier rosters toward validated manufacturers.
- Phenformin:The lipophilic biguanide carries elevated lactic acidosis risk profiles that have restricted regulatory approval in major Latin American markets. Demand concentrates in niche research laboratory channels and legacy antimalarial compounding operations where risk-benefit calculations differ from standard diabetes protocols.
- Buformin:Short-acting biguanide with rapid renal clearance characteristics sees limited utilization in Argentine hospital formularies.
- Proguanil:Cycloguanil prodrug deployed primarily for malaria chemoprophylaxis in Colombian and Peruvian endemic zones.
Mature deployment sits with Metformin across diabetes protocols. Newer deployment is concentrated in Proguanil for vector-borne disease management corridors.
Therapy Area:
Clinical application scope determines reimbursement tier placement and prescriber specialty concentration across Latin American health systems.
- Type 2 Diabetes:Established therapeutic category anchoring public procurement volumes in Mexico's hospital systems and Brazilian SUS networks. Centralized tender mechanisms favor extended-release formulations with demonstrated gastrointestinal tolerability advantages.
- Polycystic Ovary Syndrome:Off-label utilization corridor where insulin-sensitizing effects drive prescription in Colombian and Chilean specialty reproductive endocrinology clinics. Margin pools concentrate outside public reimbursement frameworks.
- Obesity Management:Emerging prescriber interest in metabolic syndrome protocols, particularly within Mexican private insurance networks.
- Antimalarial Treatment:Proguanil-atovaquone combinations serve Brazilian and Colombian border health posts in Amazon basin regions.
Revenue concentration sits with Type 2 Diabetes across public tenders. Steepest expansion trajectory is visible in Polycystic Ovary Syndrome specialty channels.
End User:
Channel structure shapes pricing realization and compliance program requirements for biguanide suppliers.
- Hospitals:Centralized procurement systems in São Paulo and Mexico City metropolitan areas drive volume concentration toward extended-release tablet suppliers with validated cold-chain capabilities.
- Specialty Clinics:Reproductive endocrinology and diabetes specialty practices in Bogotá and Santiago de Chile generate premium pricing for adherence-monitoring bundled offerings.
- Research Laboratories:Academic medical centers in Buenos Aires and Rio de Janeiro source reference standards and comparator products for bioequivalence studies.
- Community Pharmacies:Brazilian pharmacy chains represent the primary dispensing node for immediate-release metformin maintenance prescriptions.
Volume concentration sits with Hospitals through tender aggregation. Margin expansion concentrates in Specialty Clinics.
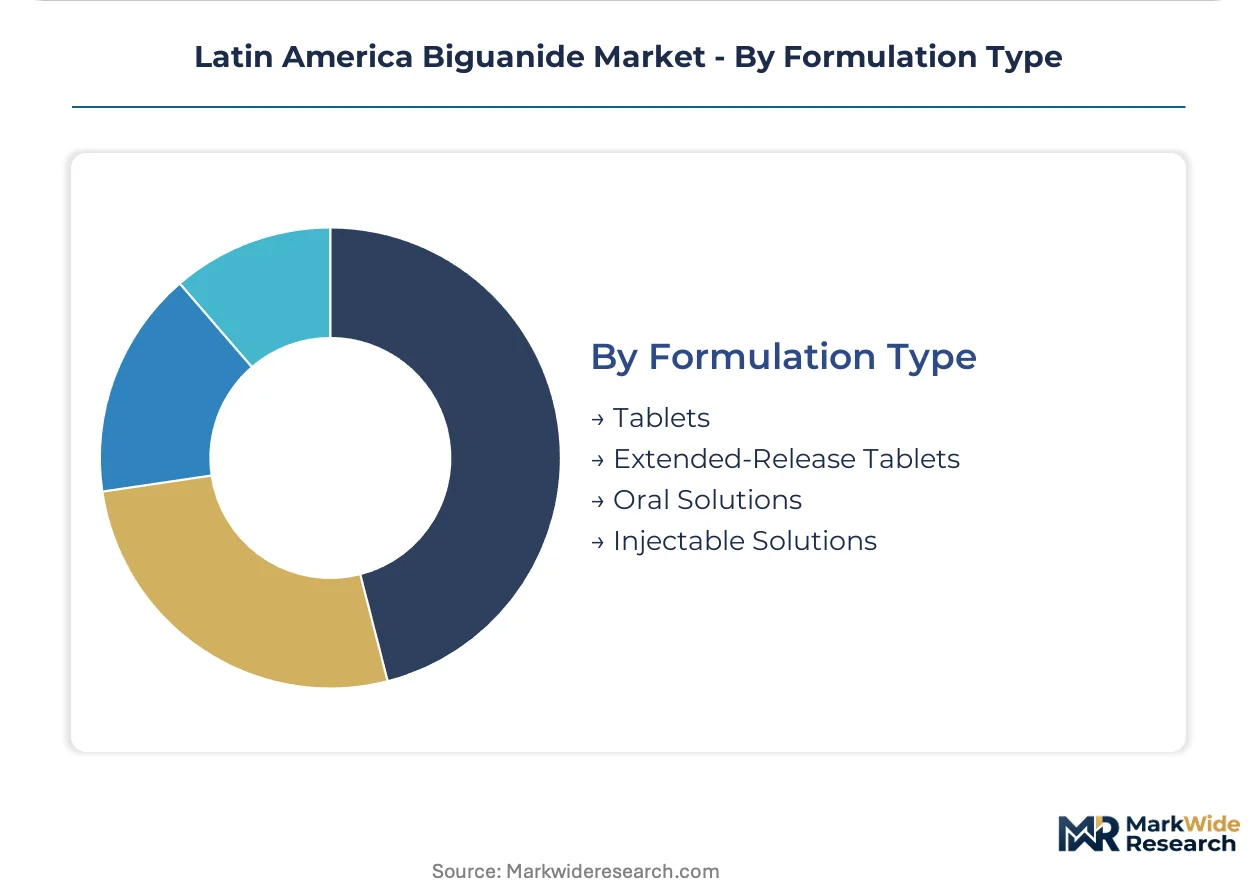
Formulation Type:
Delivery technology specifications determine manufacturing capital requirements and bioequivalence study burden.
- Extended-Release Tablets:Hydrophilic matrix systems enable controlled metformin release that reduces gastrointestinal adverse events. Mexican COFEPRIS inspection protocols prioritize these formulations in hospital procurement scoring.
- Tablets:Immediate-release specifications dominate Brazilian community pharmacy dispensing due to cost minimization pressures within SUS reimbursement frameworks.
- Oral Solutions:Liquid formulations serve pediatric and geriatric populations with swallowing difficulties in Colombian clinic networks.
- Injectable Solutions:Parenteral biguanide preparations remain limited to research settings and veterinary applications across the region.
Procurement prioritization sits with Extended-Release Tablets in hospital systems. Manufacturing investment is concentrating in this specification tier.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Argentina concentrates active pharmaceutical ingredient production for the regional biguanide supply chain, while Brazil and Mexico dominate finished dosage consumption through their public health networks. This production-consumption divide shapes cross-border trade flows and regulatory interdependence across Latin America.
Brazil
ANVISA bioequivalence requirements filter supplier rosters toward validated manufacturers as SUS prescription volumes climb. São Paulo and Minas Gerais state health networks aggregate procurement through unified purchasing coalitions. Electronic tender platforms in southeastern states displace traditional distributor relationships.
Mexico
Hospital procurement systems in Mexico City metropolitan area prioritize extended-release formulations with demonstrated tolerability advantages. COFEPRIS GMP inspection digitization reduces certification timelines for compliant manufacturing sites. Jalisco and Nuevo León production clusters invest in real-time documentation systems.
Argentina
API producers face input cost volatility from imported chemical precursors while supplying regional finished dosage manufacturers. The national pharmaceutical regulator enforces dissolution testing protocols that align with pending Mercosur harmonization. Buenos Aires academic medical centers generate demand for bioequivalence reference standards.
Colombia
Specialty reproductive endocrinology clinics in Bogotá drive off-label biguanide utilization for polycystic ovary syndrome protocols. INVIMA import licensing requirements elevate quality thresholds for distributor qualification. Amazon basin border health posts source proguanil-atovaquone combinations for antimalarial deployment.
Chile
Private insurance networks in Santiago metropolitan area generate premium pricing for adherence-monitoring bundled offerings. The national health technology assessment body evaluates fixed-dose combination therapies pairing biguanides with newer drug classes. Specialty clinic concentration in capital districts shapes margin pool distribution.
Latin America Biguanide Market Competitive Landscape
Top-tier vendors anchor hospital procurement networks, while mid-scale generic specialists compete on bioequivalence validation speed. The supplier base stratifies across three tiers: multinational pharmaceutical conglomerates with insulin co-marketing infrastructure, regional generic houses with ANVISA-certified manufacturing partnerships, and API-to-finished-dosage integrators. Consolidation pressure intensifies as electronic tender platforms compress supplier rosters. Strategic moves center on fixed-dose combination portfolio expansion and therapeutic monitoring software bundling.
Within the multinational tier, Sanofi leverages established distribution infrastructure across Brazilian pharmacy chains, while Boehringer Ingelheim International GmbH occupies a position emphasizing combination therapy strategies. Merck & Co., Inc. anchors regional supply security through Argentine manufacturing partnerships. These three exemplify divergent archetypes: co-marketing bundling, formulation innovation, and upstream supply integration.
| Leading Market Players |
|---|
| Sanofi |
| Merck & Co., Inc. |
| Bristol-Myers Squibb Company |
| GlaxoSmithKline plc |
| Boehringer Ingelheim International GmbH |
| Glenmark Pharmaceuticals Ltd. |
| Takeda Pharmaceutical Company Limited |
| Teva Pharmaceutical Industries Ltd. |
| Cipla Ltd. |
| Others |
Supply & Pricing Matrix
Certification-grade divergence between ANVISA-validated manufacturers and unvalidated generic suppliers manifests in pricing power concentration and procurement channel bifurcation across Brazilian and Mexican health networks. Extended-release formulation premiums reward suppliers with bioequivalence certification while immediate-release commoditization squeezes margins in distributor-heavy channels.
Pricing Analysis
Margin tightening in immediate-release metformin traces to electronic tender aggregation across São Paulo and Minas Gerais state health networks. Three-tier pricing structure across extended-release premium, validated-standard, and economy-immediate formulations reflects ANVISA certification status and gastrointestinal tolerability profiles. Cost compression accelerates as hospital procurement digitization favors volume-scale suppliers with validated manufacturing partnerships. Public network buyers exhibit highest price sensitivity, while Colombian specialty reproductive clinics show lowest sensitivity for adherence-bundled offerings.
Supply Chain Analysis
Direct-to-hospital channels handle extended-release formulation demand from Mexico City and São Paulo metropolitan procurement coalitions. Argentine API producers anchor upstream supply for regional finished dosage manufacturers, drawing from imported chemical precursors that face input cost volatility. Brazilian and Mexican manufacturing clusters concentrate downstream capacity, with logistics chokepoints at COFEPRIS and ANVISA certification bottlenecks. Distribution runs through electronic tender platforms that displace traditional pharmaceutical distributor relationships in southeastern Brazilian states.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Extended-release matrix technology is displacing immediate-release formulations as the clinical standard across Latin American hospital formularies, compressing legacy manufacturer margins while elevating bioequivalence-validated competitors.
For Market Incumbents: Deploy therapeutic monitoring software bundling to lock in adherence revenue streams as SGLT2 inhibitor fixed-dose combinations threaten standalone metformin volumes. Sanofi and Boehringer Ingelheim archetypes should deepen Argentine API manufacturing partnerships to secure supply chain control against input cost volatility from imported chemical precursors. Prioritize ANVISA certification maintenance as bioequivalence study capacity scarcity filters competitor entry. For New Entrants and Emerging Players: Technology-first extended-release formulation capabilities open procurement access in Mexico's digitizing hospital tender systems. Target Colombian specialty reproductive endocrinology clinics for off-label polycystic ovary syndrome protocols where margin pools concentrate outside public reimbursement frameworks. Pursue white-label manufacturing partnerships with established Argentine API producers to bypass COFEPRIS inspection backlogs. For Investors and Strategic Acquirers: Re-rating potential sits with ANVISA-certified generic houses given pending Mercosur pharmacopeia harmonization that will dissolve cross-border regulatory friction. Long-term viability hinges on backward integration into API production or captive supply agreements with Argentine chemical precursor networks. Monitor COFEPRIS GMP inspection digitization completion rates as inflection indicator for Mexican manufacturing capacity expansion timing.| Strategic Initiative | Industry Significance |
|---|---|
| Bioequivalence Certification Investment | ANVISA validation unlocks Brazilian SUS procurement volumes and filters substandard competitors from tender participation. |
| Extended-Release Manufacturing Scale-Up | Hydrophilic matrix production capacity captures Mexican hospital procurement prioritization and gastrointestinal tolerability premiums. |
| API Supply Agreement | Argentine chemical precursor partnerships insulate finished dosage manufacturers from import cost volatility and currency exposure. |
| Therapeutic Monitoring Software Launch | Adherence program bundling rewrites distributor monetization models and creates recurring revenue alongside insulin co-marketing. |
| Specialty Clinic Channel Partnership | Reproductive endocrinology relationships in Bogotá and Santiago access off-label polycystic ovary syndrome margin pools outside public tenders. |
Research Methodology
Document review covered ANVISA registration filings, COFEPRIS GMP inspection records, and Brazilian SUS procurement databases, complemented by interviews with regulatory affairs leads at generic manufacturers, hospital procurement managers in São Paulo and Mexico City, formulary directors at Colombian specialty clinics, and Argentine API production executives. Secondary validation drew from customs trade data, pharmaceutical industry association reports, and SEC 10-K disclosures from listed multinational suppliers. Bottom-up prescription volume modeling triangulated against top-down market sizing from public health expenditure records.
Segmentation outputs across product type, therapy area, formulation specification, and end-user channel fed into growth trajectory projections across the analysis window. CAGRs derived from historical prescription volume trends, diabetes prevalence epidemiology, and regulatory approval pipeline velocity. Forecast inputs incorporated ANVISA bioequivalence study completion rates, COFEPRIS inspection digitization timelines, and SGLT2 inhibitor substitution elasticity assumptions.
Forecast precision tightens around the base case; tail outcomes carry wider variance under ANVISA regulatory enforcement shifts or Argentine chemical precursor import disruption scenarios. Practitioners should monitor Mercosur pharmacopeia harmonization progress and COFEPRIS remote audit protocol adoption rates for early signals of competitive access dynamics.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Leflunomide Market
Pharmaceuticals
Global Viral Vaccines Market
Pharmaceuticals
Global Lidocaine Market
Pharmaceuticals
Global Female Contraceptive Market
Pharmaceuticals
Hyperphosphatemia Market
Pharmaceuticals
Global Histone Deacetylase Inhibitors Market
Pharmaceuticals
Lidocaine Ointment Market
Pharmaceuticals
Cortisone Market
Pharmaceuticals
Antiviral Immunoglobulin Market
Pharmaceuticals
Medical Grade Sodium Hyaluronate Market
Pharmaceuticals
Hydrocortisone Market
Pharmaceuticals
Asia-Pacific Gastrointestinal Drugs Market
Pharmaceuticals
Global Immunosuppressant Drugs Market
Pharmaceuticals
Asia Pacific SGLT2 Inhibitors Market
Pharmaceuticals
Short-Acting Insulin Market
Pharmaceuticals
Unit Dose Manufacturing Market