
 Stomach Cancer Drugs Market | 2026-2036
Stomach Cancer Drugs Market Size, Share, and Industry Trends Forecast 2026-2036
Stomach Cancer Drugs Market Analytics
Biopharmaceutical manufacturing in Japan and South Korea is consolidating around antibody-drug conjugate production for gastric malignancies. F. Hoffmann-La Roche leverages its diagnostic-drug pairing strategy to anchor HER2-targeted therapy positioning. Bristol-Myers Squibb Company competes through checkpoint inhibitor combinations, while Daiichi Sankyo specializes in novel cytotoxic payloads with enhanced tumor selectivity.
Stomach cancer drugs comprise systemic therapeutic agents designed to interrupt gastric carcinoma cell proliferation, including monoclonal antibodies, platinum-based alkylating agents, and PD-1/PD-L1 inhibitors administered via intravenous infusion with dosing calibrated to patient performance status and biomarker expression. Immunotherapy now commands premium positioning as first-line metastatic treatment, while targeted therapy retains durable margin pools in HER2-positive subsets. Chemotherapy remains the volume backbone across locally advanced stages where biomarker-directed options remain limited.
FDA breakthrough therapy designation, EMA conditional marketing authorization, and Japan's PMDA sakigake designation collectively compress regulatory timelines and shape competitive entry sequencing. These frameworks reward biomarker-enriched trial designs, tilting R&D investment toward companion diagnostic-linked submissions. Stakeholders must monitor evolving PD-L1 expression thresholds and CLDN18.2 assay standardization as these biomarker definitions will determine formulary access and prescribing algorithms.
Market Dynamics
Accelerated FDA and EMA approval pathways for biomarker-enriched oncology trials are compressing development timelines and reshaping competitive entry sequencing across gastric malignancy therapeutics.
Growth Catalysts
- Breakthrough Therapy Designation:FDA's expedited review framework rewards companion diagnostic-linked submissions, tilting R&D investment toward HER2 and CLDN18.2 assay development.
- Adjuvant Immunotherapy Expansion:Tertiary hospital oncology departments are broadening checkpoint inhibitor protocols into perioperative settings for resectable gastric cancer.
- Biomarker Assay Standardization:Japan's PMDA sakigake designation incentivizes domestic pharmaceutical manufacturers to pioneer novel cytotoxic payloads with enhanced tumor selectivity.
Market Restraints
- Platinum Salt Input Volatility:Oxaliplatin and cisplatin supply concentration in Chinese active pharmaceutical ingredient manufacturers creates price instability for alkylating agent backbones.
- Reimbursement Compression:China's National Healthcare Security Administration centralized procurement is forcing price concessions on PD-1 inhibitors despite clinical differentiation.
- Biomarker Testing Fragmentation:Inconsistent PD-L1 expression thresholds across CLIA laboratories in the United States generate prescribing uncertainty and formulary access delays.
Strategic Opportunities
- Antibody-Drug Conjugate White Space:South Korean biopharmaceutical contract manufacturers possess underutilized capacity for HER2-directed cytotoxic conjugation chemistry.
- First-Line Metastatic Positioning:EMA conditional marketing authorization creates early revenue windows for novel PD-1/CTLA-4 combinations before full approval.
- Companion Diagnostic Integration:Diagnostic-drug pairing strategies enable premium pricing capture in HER2-positive subsets where assay-linked prescribing algorithms dominate.
Industry Challenges
- Immuno-Oncology Talent Scarcity:Biostatisticians proficient in adaptive trial design for biomarker-enriched gastric cancer studies command compensation premiums that strain mid-cap development budgets.
- Multi-Regional Regulatory Synchronization:Divergent CLDN18.2 assay validation requirements between FDA, EMA, and PMDA force redundant clinical bridging studies.
- Legacy Chemotherapy Manufacturing Reconfiguration:Contract manufacturers face capital intensity in retooling fill-finish lines from cytotoxic small molecules to temperature-sensitive biologics.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Stomach Cancer Drugs Market |
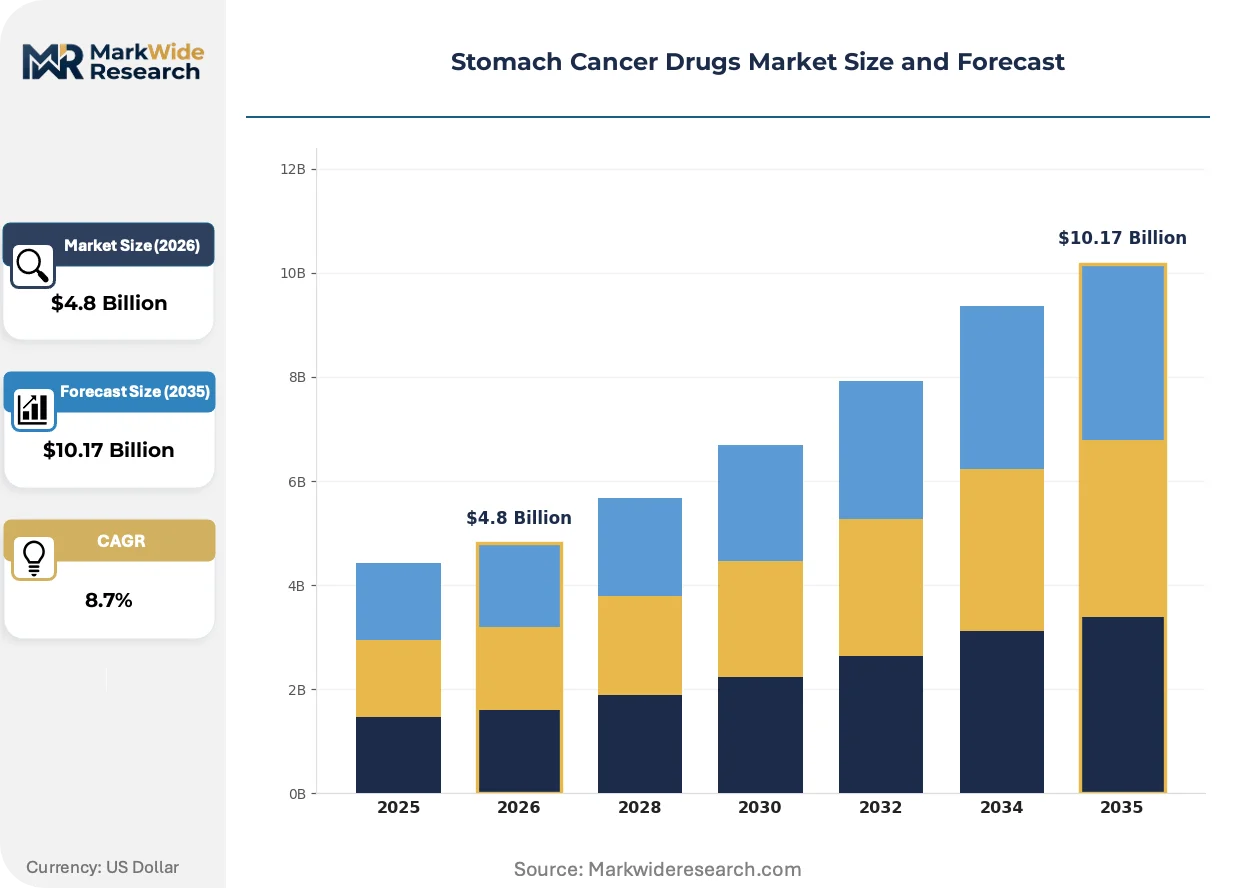
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Drug Type: Targeted Therapy, Chemotherapy, Immunotherapy, Hormonal Therapy Administration Route: Oral, Intravenous, Subcutaneous, Topical End User: Hospitals, Clinics, Cancer Research Centers, Homecare Treatment Stage: Early Stage, Locally Advanced, Metastatic, Recurrence |
| Companies Covered | F. Hoffmann-La Roche, Merck & Co., Inc., Bristol-Myers Squibb Company, Pfizer Inc., Eli Lilly and Company, Novartis AG, AstraZeneca plc, Daiichi Sankyo, Celltrion Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Stomach Cancer Drugs Market Evolving Landscape
CLDN18.2-targeted monoclonal antibodies and next-generation antibody-drug conjugates are rewriting therapeutic positioning in gastric malignancies, compressing the window between biomarker discovery and commercial deployment.
CLDN18.2-directed monoclonal antibody technology is rewriting competitive dynamics in first-line metastatic gastric cancer. Oncology departments at tertiary hospitals in Japan and the United States are adopting CLDN18.2 immunohistochemistry screening at diagnostic workup. This biomarker-driven patient segmentation is compressing enrollment timelines for combination therapy trials and displacing chemotherapy-alone standards in select populations.
EMA's conditional marketing authorization framework for oncology medicines is accelerating post-approval confirmatory study obligations. Pharmaceutical developers are structuring Phase II single-arm trials with biomarker enrichment to satisfy accelerated pathways. Gastric cancer indications with high unmet need and limited existing targeted options are experiencing the most pronounced regulatory timeline compression.
Centralized procurement models for oncology medicines are consolidating purchasing power among national payers. China's National Healthcare Security Administration and Japan's Central Social Insurance Medical Council are displacing hospital-level formulary autonomy with single-negotiation price mechanisms. This concentration is most visible in PD-1 inhibitor categories where multiple entrants have eroded differentiated positioning.
Stomach Cancer Drugs Market Segmentation
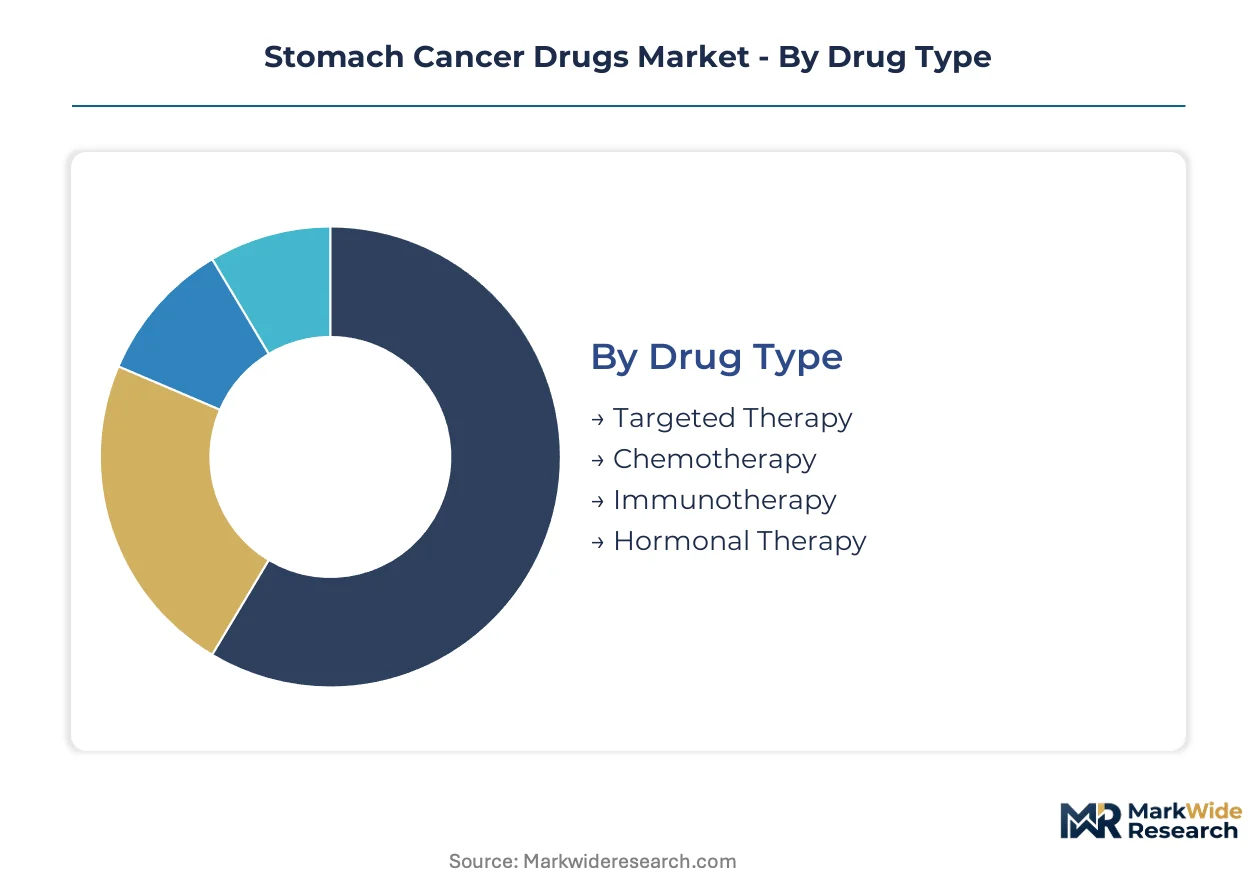
Biomarker-driven patient stratification is fragmenting the stomach cancer drugs market into discrete prescribing algorithms. Each segment carries distinct margin profiles, reimbursement codes, and manufacturing requirements that shape competitive entry decisions.
Drug Type:
Supply concentration tilts toward biologics manufacturing infrastructure in Japan and South Korea, where antibody-drug conjugate capacity constrains global availability of advanced therapeutics.
- Targeted Therapy:HER2-directed monoclonal antibodies and CLDN18.2 inhibitors dominate premium pricing tiers. Demand concentrates in tertiary oncology departments across the United States and Japan where companion diagnostic-linked prescribing algorithms determine formulary access.
- Immunotherapy:PD-1/PD-L1 checkpoint inhibitors command first-line metastatic positioning. China's National Healthcare Security Administration centralized procurement is compressing margins despite clinical differentiation in biomarker-enriched populations.
- Chemotherapy:Platinum-based alkylating agents remain the volume backbone for locally advanced stages.
- Hormonal Therapy:Limited application in gastric malignancies restricts manufacturing scale.
Today's leader: Immunotherapy. Tomorrow's challenger: Targeted Therapy.
Administration Route:
Cost tier differentiation separates hospital-based infusion services from emerging oral alternatives that promise patient convenience and reduced healthcare system burden.
- Intravenous:Monoclonal antibodies and antibody-drug conjugates require temperature-controlled cold chain logistics. Infusion center capacity constraints in Japan and South Korea limit patient throughput for checkpoint inhibitor regimens.
- Oral:Tyrosine kinase inhibitors and selected chemotherapy agents enable home administration. China's expanding retail pharmacy network for oncology medicines is accelerating dispensing channel migration away from hospital outpatient departments.
- Subcutaneous:Emerging delivery format for monoclonal antibodies seeking reduced infusion chair time.
- Topical:Negligible relevance in gastric malignancy systemic treatment.
Intravenous infusion retains volume dominance. Oral formulations are climbing the fastest as reimbursement frameworks adapt to patient-centric delivery models.
End User:
Customer type fragmentation reflects divergent purchasing authority between centralized hospital procurement and decentralized homecare reimbursement pathways.
- Hospitals:Tertiary oncology departments anchor immunotherapy and targeted therapy demand. Japan's Central Social Insurance Medical Council price negotiations determine formulary inclusion for novel agents before hospital-level prescribing can commence.
- Cancer Research Centers:Early-phase trial enrollment concentrates in academic medical centers across the United States and Japan. FDA breakthrough therapy designation pathways reward biomarker-enriched study designs that originate in these settings.
- Clinics:Community oncology practices handle stable chemotherapy maintenance regimens.
- Homecare:Oral agent administration is expanding beyond institutional settings.
Hospitals control premium therapeutic access. Cancer Research Centers determine tomorrow's standard of care through trial design influence.
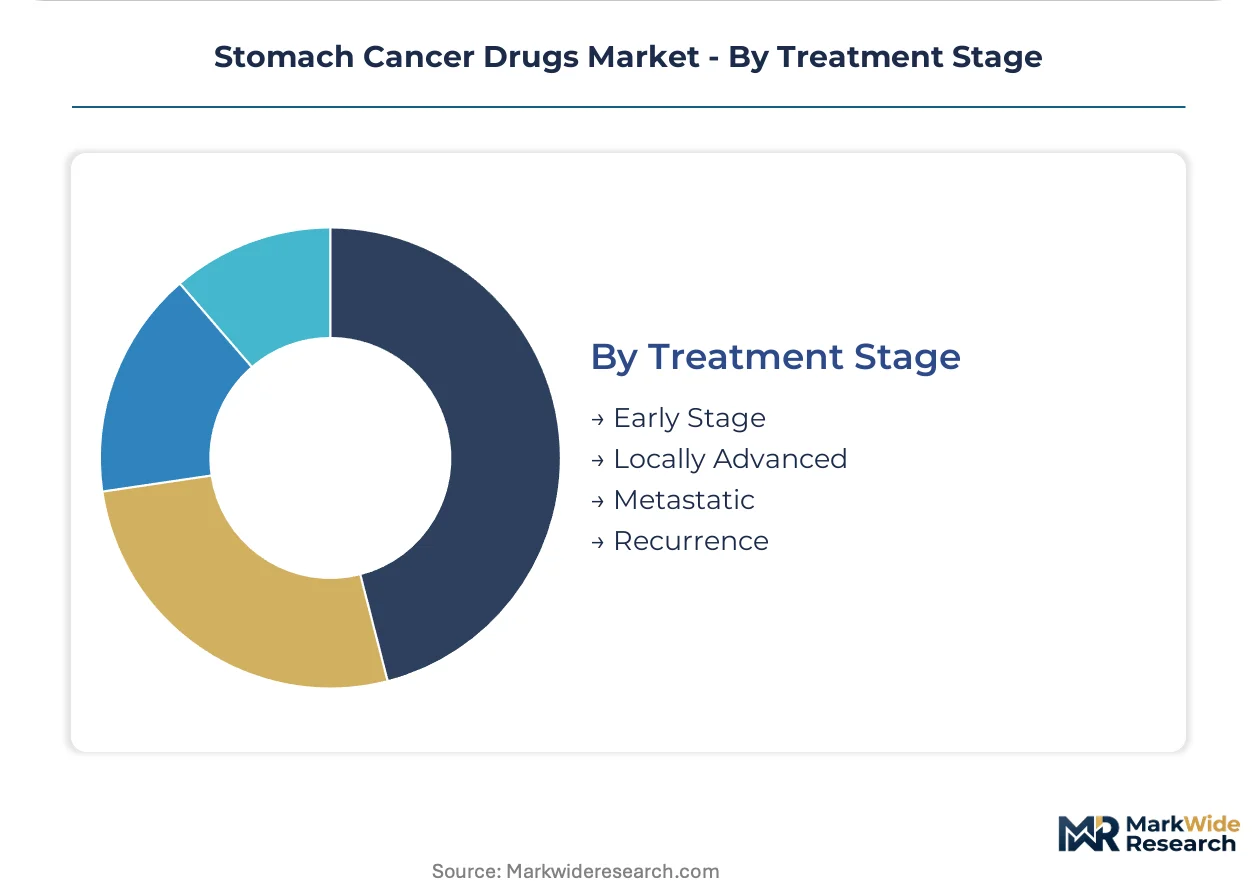
Treatment Stage:
Maturity gradients separate well-established adjuvant chemotherapy protocols from experimental perioperative immunotherapy combinations seeking regulatory approval.
- Metastatic:First-line combination regimens generate the highest per-patient revenue. PD-1 inhibitor plus chemotherapy standards in the United States and Japan are displacing platinum-doublet alone in PD-L1 positive populations.
- Locally Advanced:Perioperative checkpoint inhibitor trials are reshaping resectable gastric cancer management. EMA conditional marketing authorization creates early revenue windows before full approval in European markets.
- Early Stage:Adjuvant chemotherapy following surgical resection remains protocolized but biomarker-poor.
- Recurrence:Salvage therapy selection depends on prior exposure and emerging resistance mechanisms.
Metastatic treatment captures current value pools. Locally Advanced applications show steepest expansion trajectory as perioperative immunotherapy protocols mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Japan's gastric cancer incidence rate doubles that of the United States, yet both markets converge on premium immunotherapy pricing. China's centralized procurement apparatus compresses margins even as patient volumes expand. South Korea and Germany anchor manufacturing and regulatory innovation respectively.
United States
FDA breakthrough therapy designation accelerates checkpoint inhibitor approvals for metastatic gastric adenocarcinoma. The agency's Project Optimus initiative reshapes dose-finding studies for antibody-drug conjugates. Boston's Longwood Medical Area and Houston's Texas Medical Center anchor Phase I/II trial enrollment for CLDN18.2-directed combinations.
Japan
PMDA sakigake designation grants priority review to domestic developers of novel cytotoxic payloads. The Central Social Insurance Medical Council maintains premium reimbursement for biomarker-linked therapies despite budget constraints. Osaka's pharmaceutical corridor concentrates antibody-drug conjugate manufacturing capacity for regional supply.
China
NMPA conditional approval pathways compress timelines for PD-1 inhibitors in gastric malignancies. The National Healthcare Security Administration's volume-based procurement forces price concessions exceeding fifty percent for oncology biologics. Shanghai's Zhangjiang Hi-Tech Park hosts contract development organizations specializing in gastric cancer biomarker assays.
South Korea
MFDS fast-track designation rewards innovative manufacturing processes for monoclonal antibodies. The Ministry of Health and Welfare expands rare disease coverage to include HER2-positive gastric cancer subsets. Seoul's Songdo biocluster attracts multinational fill-finish investments for temperature-sensitive biologics.
Germany
EMA conditional marketing authorization enables early access to perioperative immunotherapy combinations. The Federal Joint Committee's early benefit assessment mandates cost-effectiveness thresholds for novel gastric cancer agents. Munich's biotechnology hub specializes in companion diagnostic development for CLDN18.2 immunohistochemistry standardization.
Stomach Cancer Drugs Market Competitive Landscape
Swiss and American pharmaceutical conglomerates anchor the premium tier; Japanese and South Korean specialists hold differentiated positions in cytotoxic payload innovation. Market structure concentrates around three strategic archetypes: diagnostic-drug pairing integrators, checkpoint inhibitor combination developers, and antibody-drug conjugate manufacturers. Consolidation pressures intensify as tertiary hospital formulary slots contract. Vertical integration into companion diagnostic assets represents the dominant competitive maneuver, followed by capacity expansion in East Asian biologics manufacturing.
Within the diagnostic-anchored tier, F. Hoffmann-La Roche exemplifies integrated therapeutic development. Bristol-Myers Squibb Company and Merck & Co., Inc. occupy positions defined by checkpoint inhibitor portfolio breadth. Daiichi Sankyo represents the specialized archetype of novel payload engineering. These entities collectively illustrate how competitive positioning stratifies across biomarker-linked prescribing algorithms and manufacturing scale requirements.
| Leading Market Players |
|---|
| F. Hoffmann-La Roche |
| Merck & Co., Inc. |
| Bristol-Myers Squibb Company |
| Pfizer Inc. |
| Eli Lilly and Company |
| Novartis AG |
| AstraZeneca plc |
| Daiichi Sankyo |
| Celltrion Inc. |
| Others |
Value Network & Pricing Analysis
China's National Healthcare Security Administration centralized procurement for PD-1 inhibitors forces pharmaceutical manufacturers to reconfigure production economics around volume-scaled biologics manufacturing rather than premium-margin specialty positioning.
Pricing Analysis
Distributor margins for intravenous oncology biologics compress as hospital procurement consolidates around national tender mechanisms. Three-tier pricing structure across premium, standard, and economy levels separates HER2-directed antibody-drug conjugates from platinum-based chemotherapy backbones from oral tyrosine kinase inhibitors. Cost compression in the PD-1 inhibitor category is intensifying because multiple domestic Chinese entrants have eroded clinical differentiation. Community oncology practices exhibit highest price sensitivity; tertiary hospital oncology departments anchored to academic medical centers show lowest sensitivity due to formulary autonomy and biomarker-linked prescribing protocols.
Supply Chain Analysis
Workforce availability for aseptic fill-finish operations in antibody-drug conjugate manufacturing constrains capacity expansion in Japan and South Korea despite demand acceleration. Active pharmaceutical ingredient production for platinum salts concentrates in Chinese chemical manufacturers, while biologics drug substance manufacturing anchors in Japanese and South Korean facilities. Supply chain risk centers on single-source vulnerability for CLDN18.2 assay reagents and companion diagnostic components. Distribution runs through hospital outpatient infusion centers for intravenous agents and expanding retail pharmacy networks for oral formulations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
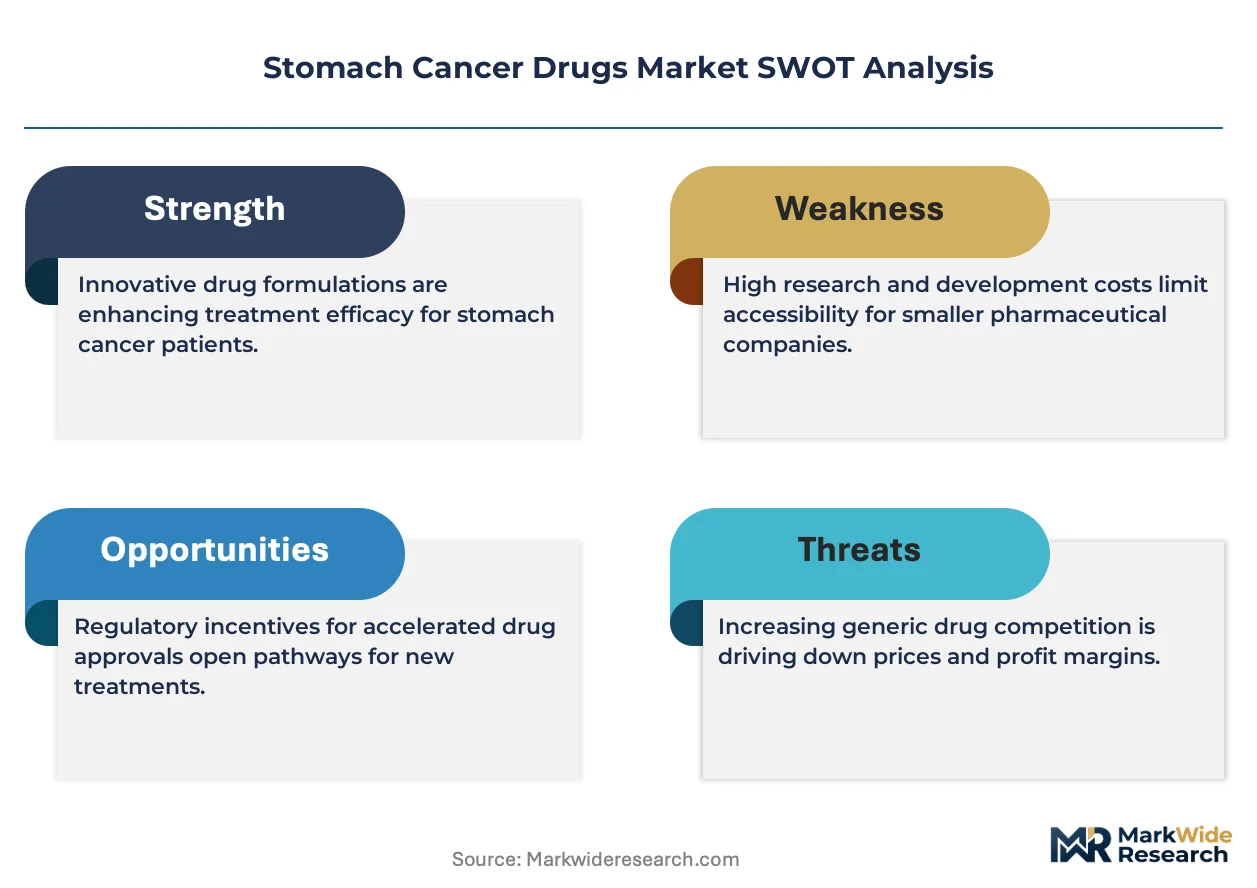
The stomach cancer drugs market functions as a stable compounder where biomarker-enriched trial designs and accelerated regulatory pathways sustain durable revenue expansion across therapeutic generations.
For Market Incumbents: Cement diagnostic-drug pairing dominance by deepening backward integration into companion diagnostic assets for CLDN18.2 and HER2 assay standardization. Expand fill-finish capacity in South Korea's Songdo biocluster to capture regional demand for temperature-sensitive biologics. The threat of centralized procurement erosion demands preemptive volume-scale positioning before tender mechanisms mature. For New Entrants and Emerging Players: Direct-to-hospital digital procurement platforms offer bypass routes around entrenched distributor relationships in China's volume-based procurement environment. Target perioperative immunotherapy combinations for resectable gastric cancer as the most penetrable application where regulatory timelines compress and clinical unmet need remains acute. Pursue EMA conditional marketing authorization pathways to generate early revenue windows before full approval. For Investors and Strategic Acquirers: Asymmetric upside sits with mid-cap antibody-drug conjugate specialists possessing novel cytotoxic payload platforms and East Asian manufacturing partnerships. The five-to-ten year viability window favors entities with biomarker-linked pipeline depth over pure-play checkpoint inhibitor developers. Watch CLDN18.2 immunohistochemistry assay standardization across FDA, EMA, and PMDA as the signal indicating inflection toward commercial scalability.| Strategic Initiative | Industry Significance |
|---|---|
| Companion Diagnostic Integration | Diagnostic-drug pairing strategies enable premium pricing capture in HER2-positive patient subsets. |
| Antibody-Drug Conjugate Manufacturing Scale-Up | East Asian biologics capacity expansion addresses global supply constraints for advanced cytotoxic conjugates. |
| Accelerated Regulatory Pathway Navigation | FDA breakthrough therapy and EMA conditional authorization compress development-to-commercialization timelines. |
| Perioperative Immunotherapy Trial Expansion | Adjuvant checkpoint inhibitor protocols in resectable gastric cancer open new addressable patient populations. |
| Biomarker Assay Standardization Investment | CLDN18.2 and PD-L1 assay harmonization determines formulary access across tertiary hospital systems. |
Research Methodology
Direct dialogue with drug development executives, regulatory affairs leads, formulary directors, and hospital procurement managers grounded this analysis in operational reality. Secondary validation drew from FDA filings, EMA submissions, ClinicalTrials.gov records, and formulary databases. Bottom-up patient-flow modeling and top-down pharmaceutical revenue triangulation converged on segment-level estimates.
Top-down market sizing anchored in published oncology drug revenue disclosures and national health expenditure patterns, while bottom-up builds aggregated patient incidence, treatment rate, and therapy cost assumptions. Segmentation dimensions spanned drug type, administration route, end user, and treatment stage across regional regulatory clusters. CAGRs emerged from curve-fitting historical approval velocity and penetration trajectories, with biomarker prevalence rates and reimbursement policy shifts serving as key forecast inputs.
The model assumes a particular technology adoption path; alternative pathways for CLDN18.2-targeted monoclonal antibodies would alter the outlook if biomarker testing fragmentation persists. Forecasts reflect documented assumptions about regulatory timeline compression and centralized procurement expansion. Material deviation in PD-L1 expression threshold harmonization or platinum salt supply stability warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Topical Drugs CDMO Market
Pharmaceuticals
Atopic Dermatitis Drugs Market
Pharmaceuticals
Cortisone Market
Pharmaceuticals
Global Plasma Derived Therapy Market
Pharmaceuticals
Fibroblast Activation Protein Inhibitors Market
Pharmaceuticals
Small Molecules Contract Development and Manufacturing Organization Market
Pharmaceuticals
Global Rx to OTC Switches Market
Pharmaceuticals
Over-The-Counter (OTC) Analgesics Market
Pharmaceuticals
Global Prophylactic HIV Drugs Market
Pharmaceuticals
Global PD-1 and PD-L1 Inhibitors Market
Pharmaceuticals
Gonorrhea Therapeutics Market
Pharmaceuticals
Anti-Vascular Endothelial Growth Factor Therapeutics Market
Pharmaceuticals
Microparticle Injectables Market
Pharmaceuticals
Istradefylline API Market
Pharmaceuticals
Ocular Drug Delivery System Market
Pharmaceuticals
Global Atosiban Market