
 Paracetamol IV Market | 2026-2036
Paracetamol IV Market Size, Share, and Industry Trends Forecast 2026-2036
Paracetamol IV Market Intelligence
Hospital procurement consolidation is repositioning how Paracetamol IV suppliers engage institutional buyers across major markets. Fresenius Kabi anchors its position through captive manufacturing of premixed infusion bags and vertical control over sterile fill-finish capacity. Pfizer competes via specialized hospital channel partnerships that sustain formulary placement in acute care settings.
Paracetamol IV refers to the intravenous formulation of acetaminophen, typically supplied as a 10 mg/mL sterile aqueous solution in 100 mL vials or premixed bags for direct infusion, designed to achieve rapid therapeutic plasma concentrations when oral or rectal administration is contraindicated. Single dose presentations dominate current volume, while premixed solutions command premium positioning due to reduced pharmacy compounding burden and lower contamination risk. Among applications, postoperative pain management represents the mature revenue base, whereas cancer pain protocols represent the fastest-growing utilization corridor as oncology units integrate multimodal analgesia.
FDA sterility guidelines, EMA GMP Annex 1 revisions, and USP Chapter 797 compounding standards collectively shape manufacturing investment and product qualification timelines for Paracetamol IV entrants. These frameworks elevate barrier-to-entry economics, particularly for facilities supplying premixed solutions requiring validated aseptic processing. Stakeholders must monitor evolving pharmacopeial harmonization between FDA and EMA regarding endotoxin limits and particulate specifications, as divergence would fragment approval pathways and duplicate validation costs.
Market Dynamics
Hospital procurement consolidation is compressing supplier margins and forcing Paracetamol IV manufacturers to restructure channel economics around formulary access and volume commitments rather than unit pricing.
Growth Catalysts
- Postoperative multimodal analgesia protocols:Surgical units in the United States and Germany now mandate IV acetaminophen as first-line therapy, embedding the product into standardized care pathways.
- EMA GMP Annex 1 revisions:Stricter aseptic processing standards for sterile parenterals are accelerating facility upgrades that favor established manufacturers with validated barrier isolator technology.
- Oncology pain management expansion:Cancer treatment centers are adopting IV acetaminophen for breakthrough pain control, creating new utilization corridors beyond surgical recovery.
Market Restraints
- API supply concentration:Active pharmaceutical ingredient production clusters in India and China, exposing formulators to geopolitical friction and import inspection backlogs.
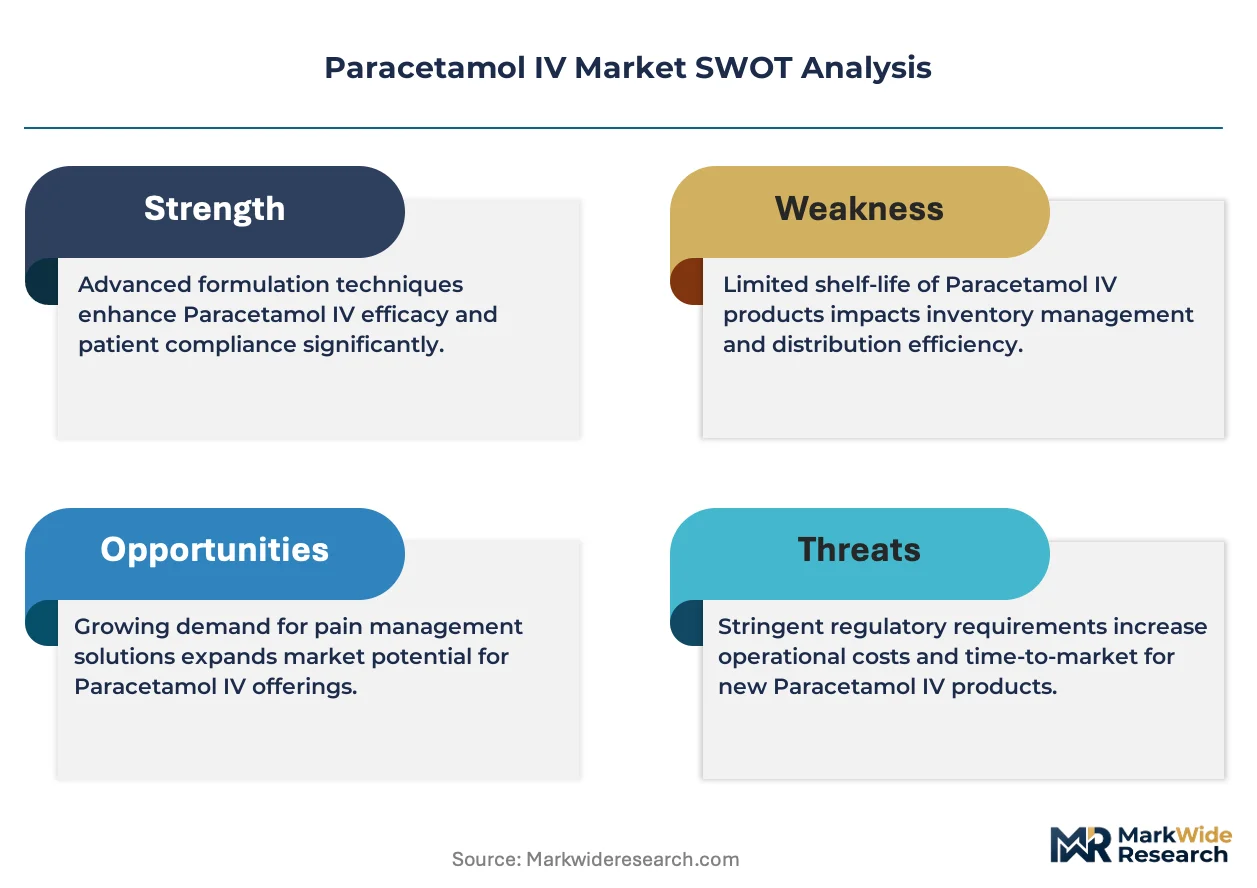
- FDA sterility validation costs:Premixed bag qualification requires extensive media fill studies and endotoxin testing protocols that consume 18-24 month approval timelines.
- Oral acetaminophen substitution:Cost-conscious payers in ambulatory settings favor enteral formulations when swallowing function permits, capping IV penetration in non-critical care.
Strategic Opportunities
- Pediatric oncology units:Underpenetrated demand for weight-based dosing precision in Japan and South Korea creates openings for specialized vial presentations.
- Prefilled syringe formats:Emergency medicine and prehospital care segments are adopting ready-to-administer presentations that reduce dosing errors and pharmacy labor.
- US 340B Drug Pricing Program:Eligible hospitals gain access to discounted acquisition costs, incentivizing formulary expansion for covered outpatient infusion services.
Industry Challenges
- Aseptic processing technician scarcity:Qualified personnel for isolator operation and environmental monitoring are in short supply across North American and European manufacturing hubs.
- Legacy vial-to-bag conversion complexity:Hospital pharmacies with entrenched compounding workflows face operational friction when transitioning to premixed solutions requiring cold chain storage.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Paracetamol IV Market |
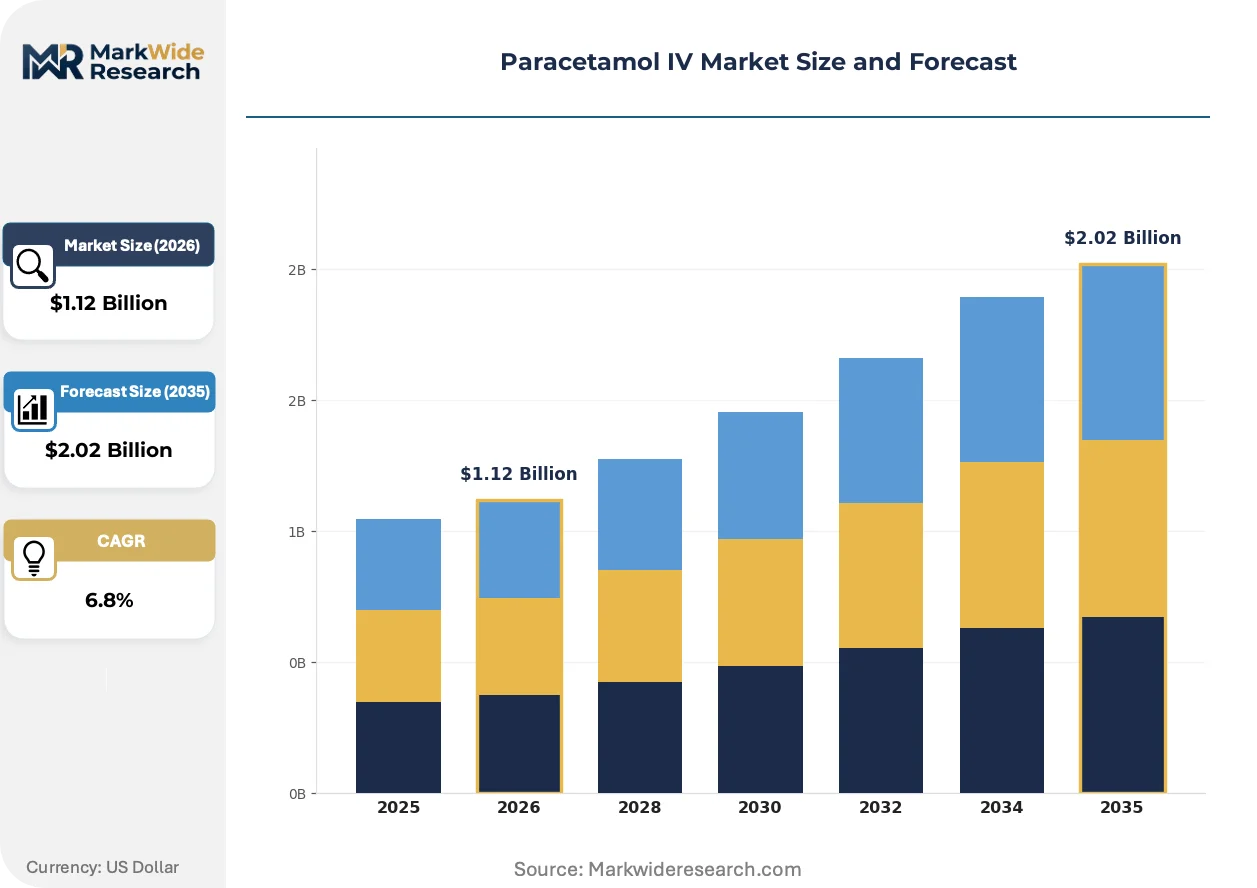
| Market Size in 2026 | $1.12 Billion |
| Market Size in 2035 | $2.02 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single Dose, Multi Dose, Injectable, Premixed Solution Application: Postoperative Pain, Cancer Pain, Fever Management, Acute Pain End User: Hospitals, Clinics, Home Care, Surgical Centers Delivery Mode: Injection, Infusion, Continuous Delivery, Bolus |
| Companies Covered | Mallinckrodt Pharmaceuticals, Pfizer Inc., Fresenius Kabi AG, Baxter International Inc., Aurobindo Pharma Ltd., Hikma Pharmaceuticals PLC, B. Braun Melsungen AG, Teva Pharmaceutical Industries Ltd., Sanofi, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Paracetamol IV Market Strategic Shifts & Innovations
Closed-system transfer devices and barrier isolator technology are redefining sterile manufacturing economics, while procurement centralization is compressing traditional channel structures.
Ready-to-administer premixed infusion bags are integrating into hospital automation infrastructure, including smart pump compatibility and barcode medication administration systems. Large academic medical centers in Germany and the United States are adopting these formats at accelerating pace, displacing traditional vial-and-compound workflows. This integration is compressing pharmacy labor costs and reducing contamination risk events, reshaping supplier value propositions around supply security rather than unit price.
EMA GMP Annex 1 revisions mandating continuous viable particle monitoring are forcing sterile fill-finish facilities to install real-time environmental sensing systems. Manufacturers serving European markets must validate isolator integrity across entire batch cycles, extending qualification timelines and elevating capital requirements. Small-volume parenteral specialists with legacy open-filling lines face the steepest compliance burden, while integrated manufacturers with captive barrier technology capture preferential supply agreements.
Group purchasing organization consolidation is concentrating buying power among three dominant intermediaries in the United States, compressing supplier margins and demanding sole-source contracts with guaranteed volume floors. Hospital systems are unbundling pharmacy distribution from clinical service contracts, creating direct procurement relationships with manufacturers for high-volume parenterals. This restructuring is most visible in integrated delivery networks across Texas, California, and the Northeast corridor, where formulary decisions now sit with centralized supply chain executives rather than individual pharmacy directors.
Paracetamol IV Market Segmentation
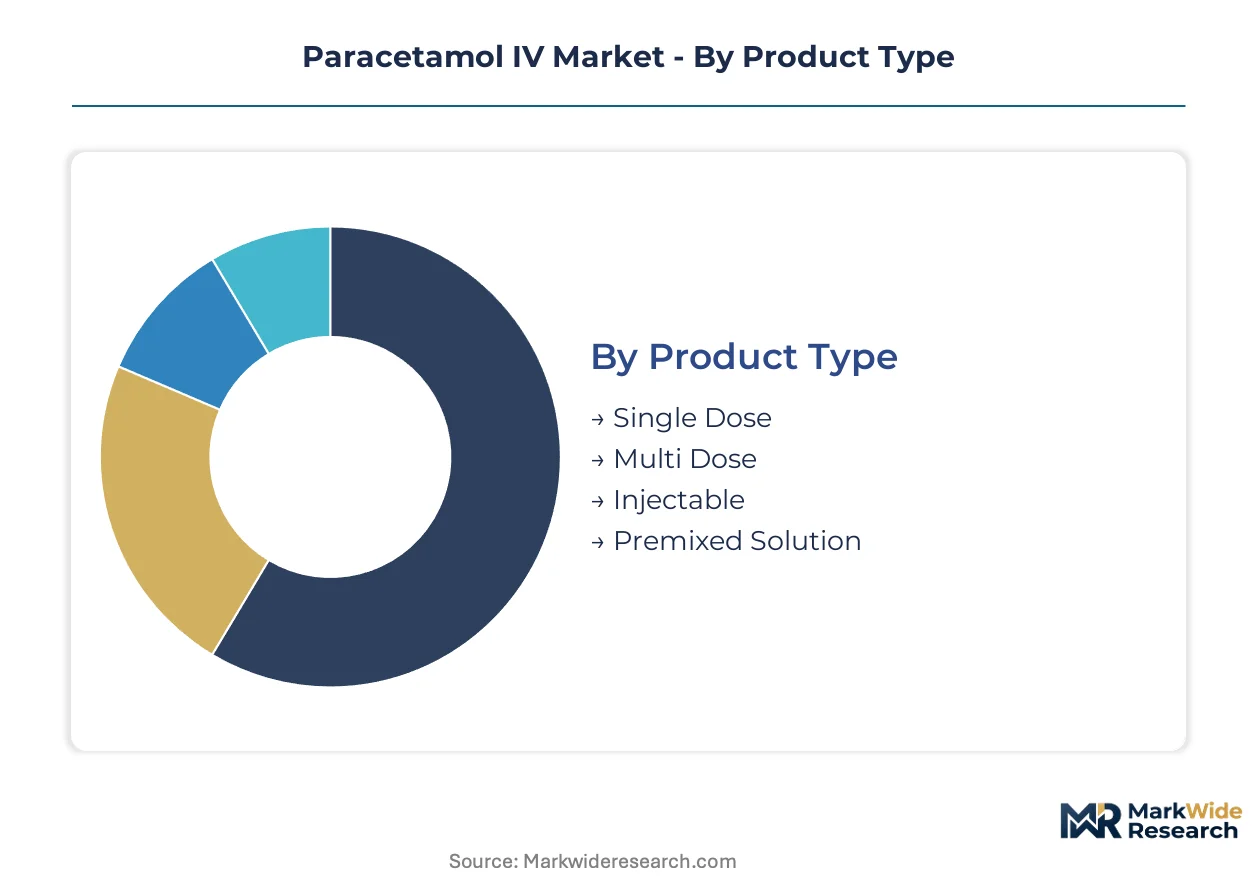
Paracetamol IV market segmentation reveals distinct value capture patterns across formulation formats, clinical settings, and administration protocols. Product configuration and delivery mode choices directly determine manufacturing complexity, regulatory pathway length, and procurement channel access.
Product Type:
Standalone vial presentations dominate current procurement volumes, while premixed formats embed deeper into automated hospital infrastructure requiring validated cold chain integration.
- Single Dose:Sterile 100 mL vials containing 1000 mg acetaminophen in aqueous solution, designed for immediate compounding into infusion bags. Demand concentrates in United States academic medical centers where pharmacy-controlled preparation maintains formulary control.
- Premixed Solution:Ready-to-administer 100 mL infusion bags with validated sterility and extended stability, eliminating compounding steps. German hospital systems and United States integrated delivery networks are adopting these formats fastest, driven by USP Chapter 797 compliance burden reduction and smart pump integration requirements.
- Multi Dose:Larger volume presentations with antimicrobial preservatives for repeated withdrawals, serving cost-sensitive institutional buyers with high patient throughput.
- Injectable:Concentrated ampoule formats requiring dilution prior to administration, retaining niche placement in emergency medicine and prehospital care settings.
Volume placements concentrate in single dose vials; the faster expansion belongs to premixed solutions.
Application:
Cost tier stratification separates mature surgical applications from emerging oncology protocols with distinct reimbursement and clinical evidence requirements.
- Postoperative Pain:Established multimodal analgesia protocols in surgical units mandate IV acetaminophen as first-line therapy, creating predictable demand baselines tied to procedural volumes.
- Cancer Pain:Breakthrough pain management in oncology units requires rapid-onset formulations with flexible dosing intervals. United States cancer treatment centers and Japanese university hospitals are expanding utilization fastest, supported by opioid-sparing clinical guidelines.
- Fever Management:Critical care and emergency department applications where enteral route contraindication necessitates parenteral antipyretic therapy.
- Acute Pain:Trauma and emergency medicine applications requiring rapid therapeutic plasma concentrations without oral absorption delays.
Revenue concentration sits with postoperative protocols; cancer pain applications are climbing the fastest.
End User:
Customer type determines procurement sophistication, with hospital system consolidation creating tiered supplier access patterns.
- Hospitals:Large inpatient facilities with centralized pharmacy operations, formulary committees, and group purchasing organization contracts representing the dominant volume channel.
- Surgical Centers:Ambulatory surgery facilities with streamlined procurement and preference for premixed formats minimizing pharmacy infrastructure investment.
- Clinics:Outpatient infusion centers with mixed capabilities, often dependent on hospital system affiliation for supply access.
- Home Care:Emerging channel requiring specialized infusion nursing support and patient training protocols, currently limited by reimbursement complexity.
Procurement volume aggregates in hospitals; surgical centers are gaining share fastest through outpatient migration.
Delivery Mode:
Margin structure varies sharply across administration protocols, with continuous infusion requiring specialized pump compatibility and bolus formats competing on pharmacy labor efficiency.
- Infusion:Controlled administration via infusion pumps over 15 minutes, the standard protocol for postoperative and cancer pain management requiring precise delivery rates.
- Bolus:Rapid push administration for emergency and breakthrough pain scenarios, demanding concentrated formulations and clinician training.
- Injection:Manual syringe administration in settings without pump infrastructure, retaining placement in resource-limited environments.
- Continuous Delivery:Extended infusion protocols for refractory pain, requiring specialized pump programming and monitoring capabilities.
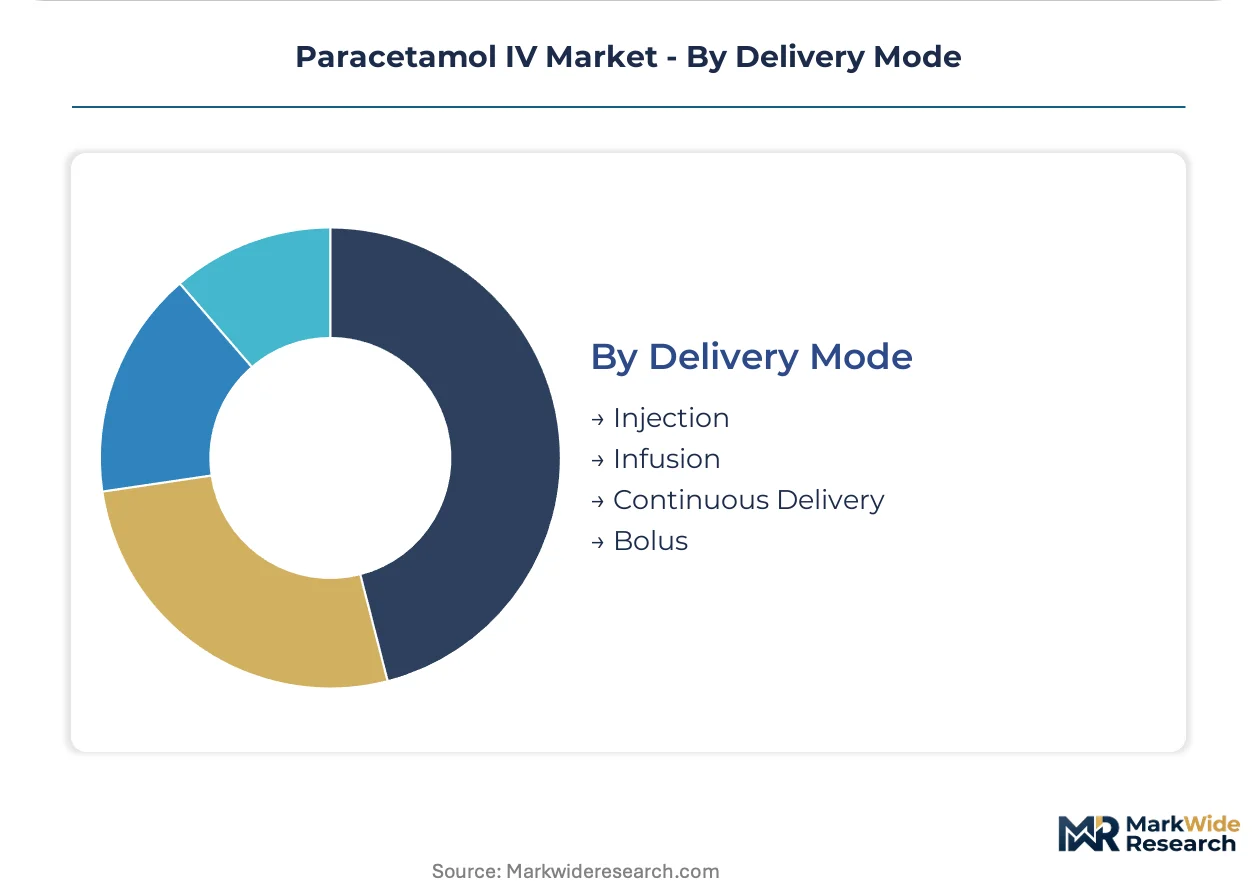
Standard infusion captures the volume base; continuous delivery protocols show the steepest expansion trajectory in palliative care settings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand for Paracetamol IV concentrates in surgical corridors of the United States, Germany, and Japan, where institutional procurement power and multimodal analgesia protocols sustain premium pricing for sterile parenteral formulations.
United States
Academic medical centers in Texas, California, and the Northeast corridor drive volume through standardized postoperative pain protocols that embed IV acetaminophen as first-line therapy. The FDA's sterility validation requirements for premixed solutions create extended approval timelines that favor established manufacturers with validated barrier isolator technology. Hospital procurement consolidation through dominant group purchasing organizations concentrates buying power among integrated delivery networks, compressing supplier margins and demanding sole-source contracts with volume guarantees.
Germany
University hospitals in Bavaria and North Rhine-Westphalia anchor European demand through opioid-sparing surgical guidelines that mandate IV acetaminophen placement in multimodal regimens. EMA GMP Annex 1 revisions mandating continuous viable particle monitoring force facility upgrades that accelerate manufacturer consolidation around isolator-equipped production sites. The Frankfurt-Rhine-Main pharmaceutical cluster hosts sterile fill-finish specialists capturing preferential supply agreements with hospital systems transitioning from vial-and-compound to premixed bag workflows.
Japan
Cancer treatment centers in Tokyo and Osaka are expanding IV acetaminophen utilization fastest among Asia-Pacific markets, driven by breakthrough pain management protocols in oncology units. PMDA sterility standards for parenteral formulations align closely with EMA requirements, enabling European manufacturers to leverage existing validation packages for market entry. Pediatric oncology units in Kansai represent underpenetrated demand for weight-based dosing precision, creating openings for specialized vial presentations with calibrated concentration gradients.
India
Active pharmaceutical ingredient production clusters in Hyderabad and Ahmedabad supply global formulators, exposing the market to geopolitical friction and import inspection backlogs at destination ports. CDSCO manufacturing facility inspections for export-oriented sterile parenteral plants have intensified, elevating compliance costs for facilities serving regulated markets. Domestic hospital demand remains limited by cost-conscious procurement favoring oral acetaminophen where enteral administration remains viable, capping IV penetration outside critical care settings.
United Kingdom
NHS England's centralized procurement for high-volume parenterals compresses supplier margins while embedding IV acetaminophen into national surgical care pathways. MHRA post-Brexit regulatory divergence from EMA creates duplicate validation requirements for manufacturers seeking concurrent UK and EU market access. The London-Oxford-Cambridge life sciences corridor hosts hospital pharmacy automation specialists driving adoption of premixed bag formats compatible with smart pump infrastructure and barcode medication administration systems.
Paracetamol IV Market Key Industry Players
United States and European producers anchor the premium-tier supply base; Indian and Chinese API specialists hold upstream positions in the value chain. The vendor base fragments across formulation capabilities, with integrated manufacturers possessing captive sterile fill-finish capacity commanding preferential hospital contracts. Three archetypes dominate: diversified pharmaceutical conglomerates with hospital channel infrastructure, sterile parenteral specialists with barrier isolator technology, and API-forward integrators seeking downstream formulation capture. Competitive positioning hinges on formulary access secured through group purchasing organization relationships and validated aseptic processing capacity.
Within the diversified pharmaceutical tier, Pfizer Inc. and Sanofi occupy positions defined by hospital channel partnerships and acute care formulary placement. Fresenius Kabi AG exemplifies the sterile parenteral specialist archetype through vertical control over premixed infusion bag manufacturing and fill-finish capacity. Among API-integrated competitors, Aurobindo Pharma Ltd. and Hikma Pharmaceuticals PLC represent manufacturers with backward integration into active pharmaceutical ingredient production and forward push into regulated-market formulation qualification. These five entities collectively illustrate the competitive spectrum from upstream chemical synthesis through downstream sterile drug product supply.
| Leading Market Players |
|---|
| Mallinckrodt Pharmaceuticals |
| Pfizer Inc. |
| Fresenius Kabi AG |
| Baxter International Inc. |
| Aurobindo Pharma Ltd. |
| Hikma Pharmaceuticals PLC |
| B. Braun Melsungen AG |
| Teva Pharmaceutical Industries Ltd. |
| Sanofi |
| Others |
Cost & Logistics Intelligence
Captive sterile fill-finish capacity anchors pricing power for Paracetamol IV manufacturers serving regulated markets, with backward integration into barrier isolator technology separating premium-tier suppliers from commodity API traders. Hospital procurement consolidation through dominant group purchasing organizations compresses margins for non-integrated players while rewarding manufacturers with validated aseptic processing infrastructure.
Pricing Analysis
High-volume single-dose vials trade at compressed margins while premixed infusion bags capture premium positioning through reduced pharmacy labor and USP Chapter 797 compliance value. Price differentiation rests on sterility assurance level and validated cold chain stability, with FDA-tier certifications commanding substantial premia over standard GMP offerings. Pricing pressure stems from sole-source contract demands by integrated delivery networks seeking guaranteed volume floors. Surgical centers exhibit acute price sensitivity due to outpatient reimbursement constraints, whereas academic medical centers prioritize supply security over unit cost.
Supply Chain Analysis
Dual-sourcing requirements from hospital systems and group purchasing organizations mandate multi-supplier qualification for critical parenterals, forcing formulators to qualify backup API streams and secondary fill-finish sites. Active pharmaceutical ingredient production clusters in India and China feed global formulation networks, with Hyderabad and Ahmedabad serving as primary supply nodes for acetaminophen base. Supply chain risk centers on import inspection backlogs at destination ports, particularly for facilities without prior FDA or EMA establishment inspection history. Distribution runs through pharmaceutical wholesalers and direct manufacturer agreements with integrated delivery networks, bypassing traditional distributor tiers for high-volume hospital contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Paracetamol IV market consolidation is accelerating as EMA GMP Annex 1 compliance costs force subscale manufacturers toward exit, creating acquisition opportunities for well-capitalized players with barrier isolator infrastructure.
For Market Incumbents: Acquire captive sterile fill-finish capacity in Germany or the United States to secure preferential supply agreements with consolidating hospital systems. Lock in long-term API offtake contracts with Hyderabad-based manufacturers before CDSCO inspection intensity triggers supply disruptions. Defend formulary placement by embedding premixed bag formats into smart pump compatibility protocols that raise switching costs for competitors. For New Entrants and Emerging Players: Oncology-focused group purchasing organizations represent the most penetrable channel for specialized vial presentations with weight-based dosing precision. Target pediatric oncology units in Japanese university hospitals where incumbent coverage remains thin and PMDA sterility alignment with EMA standards enables rapid regulatory pathway leverage. Build clinical evidence packages around opioid-sparing outcomes to support reimbursement discussions with cancer treatment center pharmacy directors. For Investors and Strategic Acquirers: Exit pathways concentrate in trade sales to diversified pharmaceutical conglomerates seeking hospital channel infrastructure. Long-term viability favors sterile parenteral specialists with validated isolator technology and established group purchasing organization relationships over API-forward integrators facing downstream formulation qualification delays. Watch FDA sterility guidance harmonization with EMA endotoxin limits as the signal for accelerated manufacturer consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Barrier Isolator Capacity Expansion | EMA GMP Annex 1 revisions mandate continuous viable particle monitoring, advantaging early movers with validated infrastructure. |
| Premixed Bag Format Conversion | US hospital automation integration with smart pump compatibility raises formulary stickiness and compresses pharmacy labor costs. |
| Pediatric Oncology Dosing Development | Weight-based precision vials address underpenetrated demand in Japanese and South Korean cancer treatment centers. |
| API Supply Backward Integration | Captive acetaminophen production insulates formulators from geopolitical friction and CDSCO inspection backlogs. |
| Group Purchasing Organization Sole-Source Contracting | Volume guarantees with dominant intermediaries secure channel access as procurement centralization concentrates buying power. |
Research Approach
Independent corroboration across hospital pharmacy directors, sterile manufacturing quality heads, and group purchasing organization contract managers underwrites the qualitative findings in this study. Primary interviews with regulatory affairs leads at formulation companies and formulary access specialists at integrated delivery networks were cross-referenced against FDA establishment inspection records, EMA GMP inspection deficiency databases, and USP Chapter 797 revision comment filings. Secondary validation drew from hospital procurement databases, GPO contract disclosure filings, and CMS Medicare Part B reimbursement data. Bottom-up volume estimates from individual facility utilization patterns were reconciled with top-down market sizing derived from trade flow analysis and API production capacity assessments.
Comparable historical periods spanning pre-pandemic baseline, supply disruption volatility, and post-consolidation stabilization anchored the forecast window calibration across the projection horizon. The analytical framework modeled demand trajectories by product format, clinical application, end-user facility type, and regional regulatory cluster. CAGRs were derived from segmented growth rate differentials applied to base year volume allocations, with oncology pain management expansion and premixed solution adoption curves serving as primary demand drivers. Pricing assumptions incorporated observed contract structures from disclosed GPO agreements and estimated pharmacy labor cost savings from automation-ready formats.
Caveats apply where FDA sterility guideline divergence from EMA standards, sudden API import inspection intensity shifts, or hospital merger integration delays could materially shift the outlook. Deviation in group purchasing organization consolidation pace or barrier isolator technician availability would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Articaine Hydrochloride Market
Pharmaceuticals
Global Raloxifene Hydrochloride Market
Pharmaceuticals
Non-Alcoholic Steatohepatitis Drugs Pipeline Market
Pharmaceuticals
Hyoscine Market
Pharmaceuticals
Europe G-CSF/PEG-G-CSF Market
Pharmaceuticals
Tramadol Drug Market
Pharmaceuticals
Europe Diabetes Drugs Market
Pharmaceuticals
Australia Schizophrenia Drugs Market
Pharmaceuticals
RNA-Targeted Small Molecules Market
Pharmaceuticals
Middle East and Africa Vaccines Market
Pharmaceuticals
Hydrocortisone Market
Pharmaceuticals
Selective Serotonin Reuptake Inhibitors Market
Pharmaceuticals
Opioid Analgesics Market
Pharmaceuticals
Artificial Intelligence in Drug Screening Market
Pharmaceuticals
Global Atherosclerosis Drugs Market
Pharmaceuticals
Europe Small Molecule Sterile Injectable Drugs Market