
 Anticancer Drugs Market | 2026-2036
Anticancer Drugs Market Size, Share, and Industry Trends Forecast 2026-2036
Anticancer Drugs Market Intelligence
Direct-to-hospital procurement models, bypassing traditional wholesalers for high-cost biologics, is reshaping competitive positioning among leading manufacturers. Bristol-Myers Squibb Company leverages its powerful portfolio of immunotherapies to secure preferential contracts with large oncology clinic networks. Roche sustains its market leadership through significant R&D investment in personalized medicine and companion diagnostics for global markets. Pfizer Inc. differentiates with a broad portfolio that spans both innovative biologics and established cytotoxic agents.
Anticancer drugs encompass pharmacological agents specifically designed to inhibit or destroy neoplastic cells. These compounds function through diverse mechanisms like interfering with DNA replication, blocking cell signaling pathways, or modulating the host immune response. Biological Response Modifiers represent the fastest-growing drug type, driven by scientific breakthroughs in immuno-oncology. While the intravenous administration route remains dominant for many therapies, oral agents gain share due to improved patient convenience and adherence.
Market access is heavily governed by regulatory bodies like the US FDA and the European Medicines Agency (EMA), which set stringent efficacy and safety standards for new drug approvals. In parallel, China's NMPA and Japan's PMDA are accelerating review processes for innovative oncology drugs to address pressing unmet medical needs. Navigating evolving reimbursement landscapes and demonstrating clear pharmacoeconomic value will be critical for commercial success.
Market Dynamics
The fundamental market dynamic is the scientific and commercial pivot towards targeted therapies and immuno-oncology. This shift away from broad-spectrum cytotoxic agents is altering R&D priorities, manufacturing requirements, and the pharmacoeconomic arguments necessary for securing reimbursement from payers like the US FDA and EMA.
Growth Catalysts
- Regulatory Acceleration:The US FDA's breakthrough therapy and accelerated approval pathways shorten development timelines for drugs addressing serious conditions, encouraging investment in novel oncology treatments.
- Companion Diagnostics:The co-development of companion diagnostic tests enables the precise identification of patient populations most likely to respond to a targeted therapy, increasing efficacy and driving adoption.
- Emerging Market Demand:An aging population and expanding public health insurance coverage in countries like China are creating a substantial new patient base for both innovative and established anticancer drugs.
Market Restraints
- Manufacturing Complexity:The production of biologic drugs, such as monoclonal antibodies, involves highly complex and costly cell culture and purification processes, limiting the number of qualified manufacturers.
- Stringent Reimbursement Hurdles:Payers and health technology assessment bodies globally are implementing stricter pharmacoeconomic evaluations, demanding substantial evidence of a drug's value over existing treatments.
- Cold Chain Logistics:Many advanced biologic therapies are temperature-sensitive and require an uninterrupted cold chain from manufacturing to administration, creating significant logistical and cost barriers.
Strategic Opportunities
- Oral Biologics Development:Creating oral formulations for drugs currently administered intravenously presents a significant opportunity to improve patient convenience, adherence, and quality of life, opening new market segments.
- AI in Drug Discovery:Leveraging artificial intelligence and machine learning algorithms can dramatically accelerate the identification of novel drug targets and candidates, reducing R&D costs and timelines.
- Underserved Geographies:Expanding commercial and clinical trial operations into markets in Southeast Asia and Latin America, where cancer incidence is rising, offers long-term growth potential.
Industry Challenges
- Specialized Talent Scarcity:A global shortage of skilled personnel, including immuno-oncologists, bioprocess engineers, and regulatory affairs specialists, constrains the pace of research and manufacturing scale-up.
- Intellectual Property Disputes:The landscape for novel modalities like cell and gene therapies is fraught with complex patent disputes, creating commercial uncertainty for developers and investors.
- Interoperability of Health Data:The lack of standardized electronic health records and genomic data formats across different healthcare systems impedes the large-scale research needed for personalized medicine.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Anticancer Drugs Market |
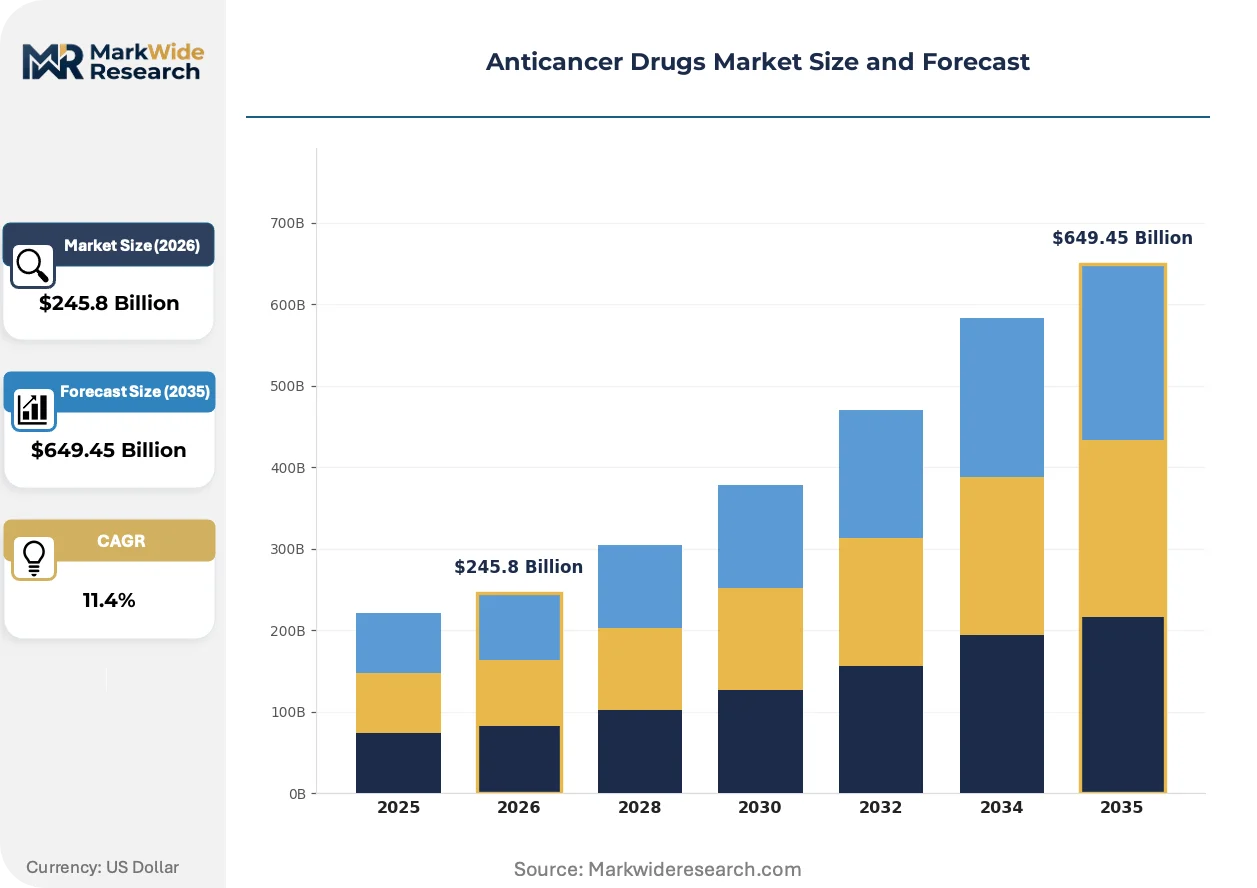
| Market Size in 2026 | $245.8 Billion |
| Market Size in 2035 | $649.45 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Drug Type: Alkylating Agents, Antimetabolites, Plant Alkaloids, Hormonal Agents, Biological Response Modifiers Therapy Area: Carcinoma, Sarcoma, Lymphoma, Leukemia, Melanoma End User: Oncology Clinics, Cancer Research Institutes, Specialty Hospitals, Diagnostic Laboratories Administration Route: Oral, Intravenous, Intramuscular, Subcutaneous, Topical |
| Companies Covered | Roche, Bristol-Myers Squibb Company, Merck & Co., Inc., Johnson & Johnson, Gilead Sciences, Pfizer Inc., Novartis AG, Amgen Inc., AstraZeneca, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Anticancer Drugs Market Strategic Shifts & Innovations
The convergence of genomic science, data analytics, and novel biological engineering is defining the next generation of anticancer therapies. This evolution is not only producing more effective treatments but also challenging traditional models of clinical development, regulatory approval, and commercialization.
Digital twin technology is gaining traction in preclinical and clinical research. These computational models of tumors or patients simulate biological responses to new drug candidates. Pharmaceutical R&D departments and clinical research organizations are the primary adopters, and the technology is virtualizing parts of the trial process, aiming to reduce costs and shorten development timelines.
Regulatory frameworks like the European Medicines Agency's PRIME scheme are expediting access for promising new medicines. The program offers early and enhanced scientific and regulatory dialogue to developers of drugs targeting significant unmet medical needs. This support particularly benefits smaller biotech firms developing novel treatments for rare cancers, helping them navigate the complex EU approval pathway more efficiently.
A notable shift in demand is the move toward value-based agreements between drug manufacturers and payers. This model disrupts traditional fee-for-volume purchasing by linking reimbursement for high-cost therapies directly to their observed effectiveness in patients. This trend is most advanced in European countries with single-payer health systems and large integrated delivery networks in the United States.
Anticancer Drugs Market Segmentation
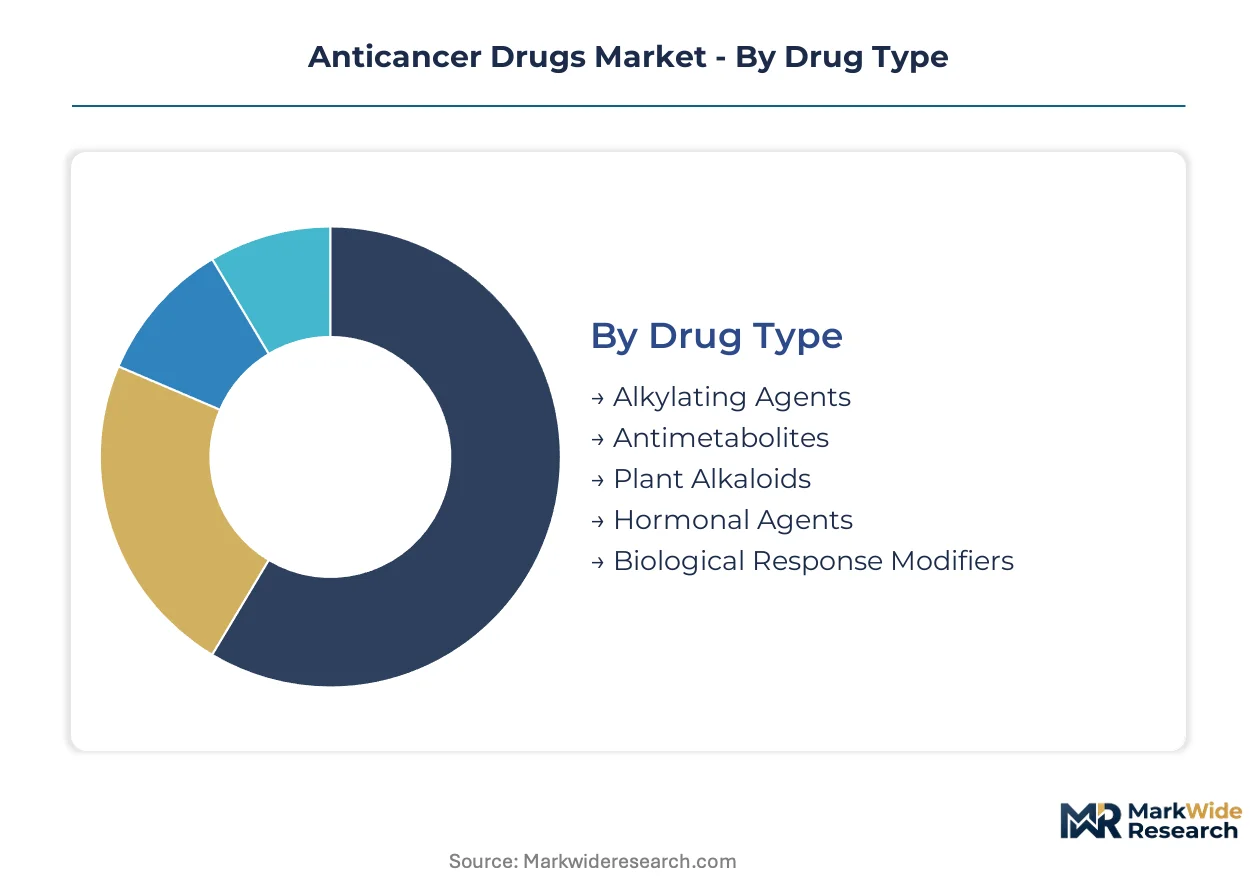
The anticancer drugs market is segmented across diverse criteria, reflecting the complex nature of cancer treatment and drug delivery. Understanding these segments helps manufacturers tailor product development and market access strategies. Each segment addresses specific patient needs or operational requirements within the global oncology landscape.
Drug Type:
The after-sales service intensity for anticancer drugs varies significantly by drug type, influencing storage, administration support, and patient monitoring requirements.
- Alkylating Agents:These drugs interfere directly with DNA replication by adding an alkyl group to DNA, preventing cancer cells from reproducing. They are widely used in various cancer types, with demand remaining consistent in both established and emerging markets due to their broad-spectrum efficacy.
- Antimetabolites:These compounds mimic natural substances required for cell metabolism, thereby blocking cell growth and division.
- Plant Alkaloids:Derived from natural plant sources, these drugs disrupt cell division by interfering with microtubule formation.
- Hormonal Agents:These therapies block hormone production or action, effectively slowing the growth of hormone-sensitive cancers.
- Biological Response Modifiers:These agents leverage the body's immune system to fight cancer cells, often through complex mechanisms like checkpoint inhibition or CAR T-cell therapy. Demand concentrates in specialty hospitals and advanced oncology clinics, driven by scientific breakthroughs in immuno-oncology and personalized medicine.
Alkylating Agents hold a significant share due to their long-standing use and broad applicability; momentum sits with Biological Response Modifiers.
Therapy Area:
The application of anticancer drugs is highly specific to the therapy area, dictating treatment protocols and drug efficacy profiles.
- Carcinoma:This segment encompasses cancers originating in epithelial cells, such as lung, breast, prostate, and colon cancers, representing the most prevalent cancer type globally. Demand for carcinoma treatments is widespread across all healthcare settings, driven by high incidence rates and diverse therapeutic needs.
- Sarcoma:This category includes rare cancers that arise in bone and soft tissues, often requiring multidisciplinary treatment approaches.
- Lymphoma:These cancers originate in the lymphatic system, affecting various immune cells and demanding tailored immunotherapy strategies.
- Leukemia:These are cancers of the blood-forming tissues, including bone marrow and the lymphatic system, requiring specialized and often intensive treatment regimens. Demand is concentrated in specialized hematology-oncology centers, supported by continuous advancements in targeted therapies and stem cell transplantation.
- Melanoma:A serious form of skin cancer, melanoma treatment has seen significant breakthroughs with novel immunotherapies.
The Therapy Area segment exhibits diverse treatment landscapes, with Melanoma treatments expanding most quickly due to immunotherapy innovations.
End User:
The customer type for anticancer drugs influences procurement models and the complexity of drug administration.
- Oncology Clinics:Providing outpatient cancer care, including chemotherapy and immunotherapy infusions, these clinics focus on patient convenience and continuity of care. Demand for a broad range of anticancer drugs is significant, supported by increasing patient preference for ambulatory treatment settings.
- Cancer Research Institutes:These institutions focus on drug discovery, clinical trials, and understanding cancer biology, consuming drugs for research purposes.
- Specialty Hospitals:These facilities offer comprehensive cancer care, including complex surgeries, radiation, and advanced biologic therapies, often serving as referral centers. Demand for high-cost biologics and specialized treatments is concentrated here, driven by the administration of complex therapies and the need for intensive patient monitoring.
- Diagnostic Laboratories:These facilities utilize specific agents for companion diagnostics and biomarker testing, crucial for personalized medicine.
The Specialty Hospitals segment dominates consumption for advanced therapies, while Oncology Clinics show significant growth potential for routine treatments.
Administration Route:
The margin profile for anticancer drugs is often influenced by the administration route, reflecting manufacturing complexity and patient convenience.
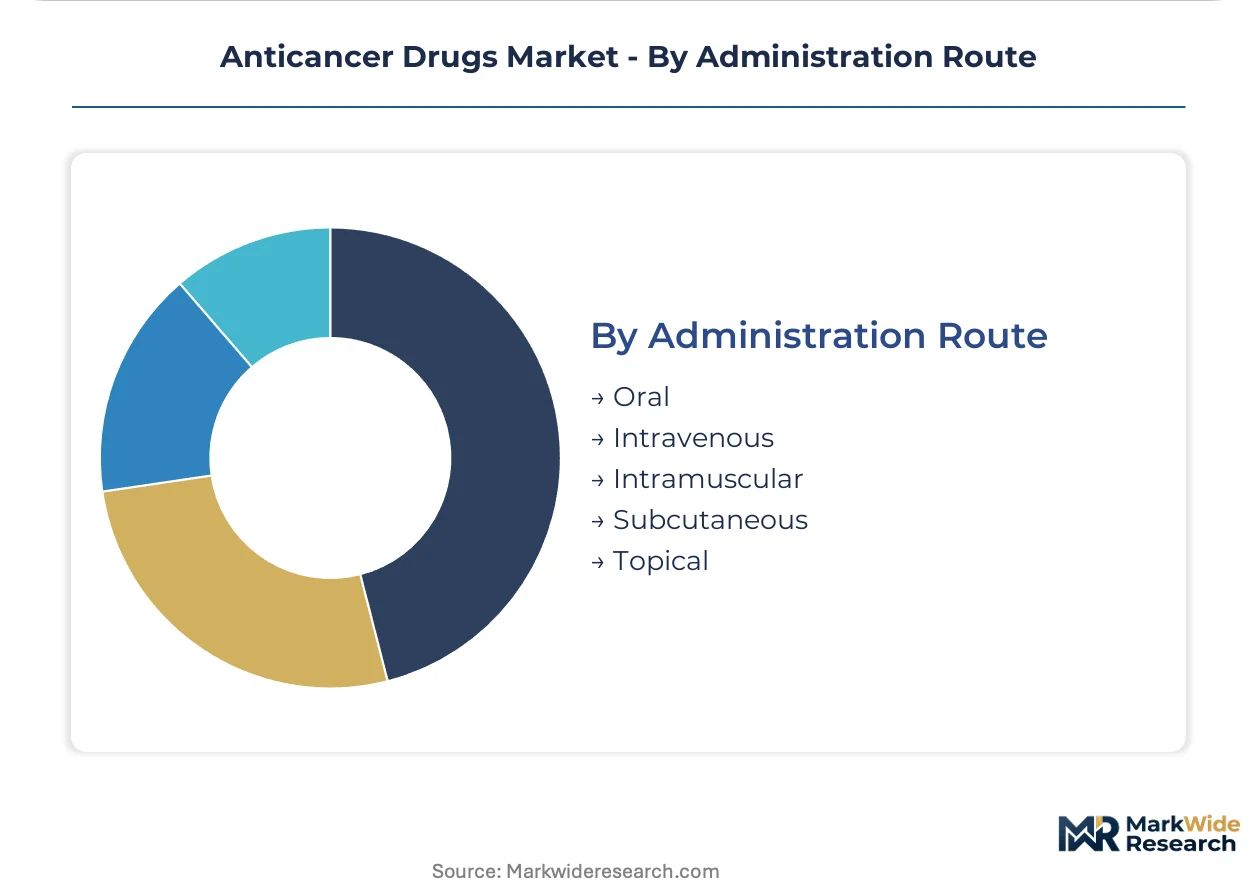
- Oral:These agents are taken by mouth, offering significant patient convenience and the potential for at-home administration, improving adherence and quality of life. Demand for oral anticancer drugs is gaining share across global markets, driven by patient preference and advancements in drug formulation.
- Intravenous:Administered directly into a vein, this route ensures rapid and complete systemic drug delivery, crucial for many high-potency biologics and cytotoxic agents. The intravenous route remains dominant for complex therapies in hospital and clinic settings, supported by established infrastructure and precise dosing control.
- Intramuscular:Injections into muscle tissue provide a slower, sustained release of medication, suitable for certain hormonal therapies.
- Subcutaneous:Administered under the skin, this route offers a less invasive alternative to intravenous infusions for some biologic agents.
- Topical:Applied directly to the skin, topical agents are primarily used for localized skin cancers or precancerous lesions.
The market exhibits a clear preference for Intravenous administration, though Oral agents are rapidly gaining traction due to patient convenience.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regional pricing power for anticancer drugs varies significantly. Established markets like the United States command higher prices due to advanced infrastructure. Conversely, markets such as China prioritize broad access through expanded insurance, influencing drug affordability.
United States
The United States market exhibits robust demand for novel anticancer therapies, fueled by high cancer prevalence. The US FDA's breakthrough therapy designation shortens development timelines, encouraging pharmaceutical investment. Boston's biotech cluster actively drives discovery and commercialization of new immuno-oncology agents.
China
China's demand for anticancer drugs expands due to an aging demographic and increasing public health insurance access. The NMPA streamlines review processes for innovative oncology drugs, addressing unmet medical needs. Shanghai's Zhangjiang Hi-Tech Park attracts capital for cancer drug research and biopharmaceutical production.
Germany
Germany showcases strong demand for high-value anticancer therapies, supported by a well-funded healthcare system and personalized treatment focus. The European Medicines Agency (EMA) ensures rigorous safety and efficacy standards for new drug approvals. Munich's vibrant biotech ecosystem fosters co-development of targeted therapies and companion diagnostics.
Japan
Japan faces a significant burden from an aging population, driving demand for effective anticancer treatments. The PMDA expedites approval of innovative oncology drugs, aiming to meet critical medical needs. Tokyo's numerous pharmaceutical research centers lead development of advanced cancer therapies and clinical applications.
Brazil
Brazil experiences growing demand for anticancer drugs due to increasing cancer incidence and improving healthcare accessibility. ANVISA manages approval and post-market surveillance of oncology pharmaceuticals. São Paulo's leading medical centers are expanding clinical trial infrastructure for novel cancer treatments.
Anticancer Drugs Market Key Industry Players
Platform integrators command the system tier; component specialists sit upstream, focusing on specific drug classes. The anticancer drugs market exhibits a tiered structure, with a few large pharmaceutical companies dominating the high-value biologics segment. Strategic archetypes include diversified pharmaceutical giants, specialized biotech innovators, and generics manufacturers. Dominant competitive moves involve significant R&D investment in novel therapies and strategic partnerships for market access.
Among the global pharmaceutical leaders, Roche exemplifies a strategy focused on sustained market leadership through significant research and development in personalized medicine and companion diagnostics for global markets. Bristol-Myers Squibb Company occupies a position anchored by a powerful portfolio of immunotherapies, enabling preferential contracts with large oncology clinic networks. Pfizer Inc. represents a diversified approach, with a broad portfolio that spans both innovative biologics and established cytotoxic agents, catering to a wide range of therapeutic needs. These companies demonstrate varying strategies to maintain and expand their presence in the competitive anticancer drugs market.
| Leading Market Players |
|---|
| Roche |
| Bristol-Myers Squibb Company |
| Merck & Co., Inc. |
| Johnson & Johnson |
| Gilead Sciences |
| Pfizer Inc. |
| Novartis AG |
| Amgen Inc. |
| AstraZeneca |
| Others |
Cost & Logistics Intelligence
Undercapacity in specialized biomanufacturing facilities across Europe and the United States drives both supplier behavior and pricing posture for advanced anticancer biologics. This limited production capability incentivizes long-term contracts and influences the cost structure of novel therapies.
Pricing Analysis
Configured-to-order pricing for personalized medicine, such as CAR T-cell therapies, commands a significant premium over standard drug formulations. Value-based agreements increasingly define the dominant pricing model, linking reimbursement directly to patient outcomes. Brand premium and the level of after-sales service, including patient support programs, are critical price differentiation drivers. Pricing pressure stems from stringent reimbursement hurdles imposed by payers like the European Medicines Agency (EMA). Integrated delivery networks in the United States often exhibit the least price sensitivity due to their focus on comprehensive patient care.
Supply Chain Analysis
Upstream feedstock for complex biologics, including cell culture media and recombinant proteins, primarily sources from specialized manufacturers in the United States and Germany. Geographic supply concentration for active pharmaceutical ingredients (APIs) also lies heavily in China and India. Single-source vulnerability for proprietary cell lines represents a significant structural risk within the biopharmaceutical supply chain. Distribution runs through a hybrid model, combining direct-to-hospital procurement for high-cost biologics and traditional wholesaler channels for established cytotoxic agents.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The anticancer drugs market is undergoing a cyclical recovery, primarily driven by accelerated regulatory approvals and a robust pipeline of innovative therapies.
For Market Incumbents: Entrench core market share by continuously investing in next-generation immunotherapies and targeted agents. Diversify R&D pipelines to mitigate risks from emerging gene therapy entrants and potential biosimilar competition. Leverage existing relationships with large oncology clinic networks to secure preferential contracts and enhance market access.
For New Entrants and Emerging Players: Niche patient populations with rare cancers represent the most penetrable entry point for novel oncology drugs. Focus on developing companion diagnostics to enable precise patient selection and demonstrate superior efficacy. A go-to-market angle emphasizing pharmacoeconomic value in underserved geographies can accelerate adoption.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upwards across the biologics and cell therapy sub-segments, signaling significant future growth potential. Seek out specialized biotech innovators with strong intellectual property portfolios in immuno-oncology or AI-driven drug discovery platforms. Monitor the pace of regulatory acceleration from the US FDA and China's NMPA as a key inflection indicator for investment opportunities.
| Strategic Initiative | Industry Significance |
|---|---|
| Clinical Trial Advancement | Accelerates market entry for novel therapies, demonstrating efficacy in specific patient populations. |
| Regulatory Approval Pathway | Secures market access through expedited programs, reducing development timelines and costs. |
| Manufacturing Scale-Up | Ensures sufficient supply of complex biologics to meet growing global patient demand. |
| Pipeline Diversification | Mitigates risk by expanding therapeutic areas and drug modalities beyond current offerings. |
| Strategic Partnerships | Enhances market penetration and leverages complementary expertise for R&D and commercialization. |
Research Approach
Findings reconcile primary fieldwork against secondary review of regulatory filings, clinical trial databases, and scientific literature. This involved detailed discussions with drug development executives, regulatory affairs leads, formulary directors, and hospital procurement managers. Both bottom-up and top-down triangulation methods were employed to ensure data accuracy and consistency across all market segments.
The forecast inputs considered market size, growth rates, and competitive dynamics across the analysis window. Segmentation dimensions modeled included drug type, therapy area, end user, and administration route, alongside regional regulatory clusters. Compound annual growth rates were derived through a robust analytical framework that integrated historical trends with projected scientific breakthroughs and healthcare spending patterns.
Practitioners should monitor shifts in reimbursement policies and the emergence of new therapeutic modalities for early signals of market revision. Forecasts reflect assumptions documented at the time of analysis. Cross-checking against national cancer registries and health technology assessment reports is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Guanethidine Market
Pharmaceuticals
Global Ebola Virus Vaccine Market
Pharmaceuticals
Ophthalmic Drug Delivery Systems Market
Pharmaceuticals
Germany Diabetes Drugs Market
Pharmaceuticals
PAP and Paracetamol Market
Pharmaceuticals
Global Antiemetics Market
Pharmaceuticals
Alkylating Agents Market
Pharmaceuticals
Global Anti Epileptic Drugs for Pediatrics Market
Pharmaceuticals
Global Bendamustine Injection Market
Pharmaceuticals
Meperidine Drugs Market
Pharmaceuticals
Adrenocorticotropic Hormone [ACTH] Market
Pharmaceuticals
Africa Generic Pharmaceutical Market
Pharmaceuticals
Global Diphtheria Vaccine Market
Pharmaceuticals
Antidepressant Drugs Market
Pharmaceuticals
Global Self-Administered Drugs Market
Pharmaceuticals
Italy Opioids Market