
 Roasted Snacks Market | 2026-2036
Roasted Snacks Market Size, Share, and Industry Trends Forecast 2026-2036
Roasted Snacks Market Outlook
India is rewriting competitive dynamics in roasted snacks as domestic production capacity expands to serve both local consumption and export demand. PepsiCo Inc. leverages its Kurkure and Nutriblitz platforms to dominate urban distribution networks, while Haldiram's sustains family-format packaging leadership across tier-two and tier-three cities. Blue Diamond Growers anchors premium almond roasting through controlled California supply chains that extend into Asian markets.
Roasted snacks are dry-heat processed nut and seed products typically finished at temperatures between 120°C and 180°C, with moisture content reduced below 4 percent to achieve shelf stability and flavor development through Maillard browning reactions; their primary commercial purpose is delivering portable, shelf-stable protein and healthy fat alternatives to fried or extruded snack formats. Almond and cashew segments occupy the highest margin pools due to raw material scarcity and premium positioning in gift and travel-retail channels. Pouch packaging is displacing rigid canisters in online retail as fulfillment economics favor lighter, crush-resistant formats that reduce shipping cube and damage rates.
FDA nutrition labeling mandates and FSSAI fortification guidelines are reshaping permissible sodium and additive profiles, forcing manufacturers to reformulate coatings and seasoning systems to maintain clean-label claims. The EU's F-Gas Regulation indirectly affects roasting equipment procurement as thermal efficiency standards tighten for industrial ovens and dryers. Stakeholders must monitor how dual carbon goals in China and India's PLI scheme for food processing alter capital equipment sourcing and export competitiveness.
Market Dynamics
Clean-label reformulation pressure is compressing formulation cycles as sodium-heavy coatings face simultaneous FDA labeling mandates and FSSAI fortification guidelines. Manufacturers must rebuild seasoning systems without sacrificing shelf stability or Maillard flavor development.
Growth Catalysts
- FDA Nutrition Facts Labeling:Mandatory sodium disclosure is accelerating clean-label R&D investment. Reformulated low-sodium coatings now command premium positioning in corporate cafeteria procurement.
- India PLI Scheme for Food Processing:Capital equipment subsidies are expanding domestic roasting capacity. New oven installations in Gujarat and Maharashtra are displacing imported machinery.
- Maillard Reaction Control:Precision temperature profiling technology is enabling consistent browning without acrylamide formation. Almond and cashew processors are retrofitting batch roasters with automated thermal sensors.
Market Restraints
- Almond Supply Concentration:California drought cycles create raw material volatility. Blue Diamond Growers and select cooperatives control over 80 percent of premium kernel supply.
- EU F-Gas Regulation:Thermal efficiency mandates for industrial ovens are extending equipment replacement timelines. European processors face 15-20 percent capex premiums for compliant roasting lines.
- Moisture Barrier Limitations:Biodegradable films lack the oxygen transmission rates of metallized polyester. Clean-label packaging claims conflict with shelf-life requirements in humid climates.
Strategic Opportunities
- Corporate Cafeteria Channel:Health-conscious millennials in tech and finance campuses are creating dedicated clean-label SKUs. Procurement contracts now specify roasted nut minimums in wellness program tiers.
- India Tier-Two Cities:Haldiram's family-format dominance leaves white space for single-serve premium positioning. Urban snack consumption growth in Lucknow and Indore outpaces metro saturation.
- Pouch Packaging Convergence:Crush-resistant flexible formats are migrating from online retail into travel and gift channels. Lighter shipping cubes reduce last-mile costs by 12-18 percent versus rigid canisters.
Industry Challenges
- Flavor Chemist Shortage:Clean-label seasoning development requires specialists who can replace synthetic enhancers with natural umami sources. Recruitment competition from plant-based meat sectors is compressing talent pipelines.
- Acrylamide Testing Bottlenecks:FSSAI and FDA sampling protocols create 6-8 week certification delays. Third-party labs in India and the US are at capacity for roasted nut matrix validation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Roasted Snacks Market |
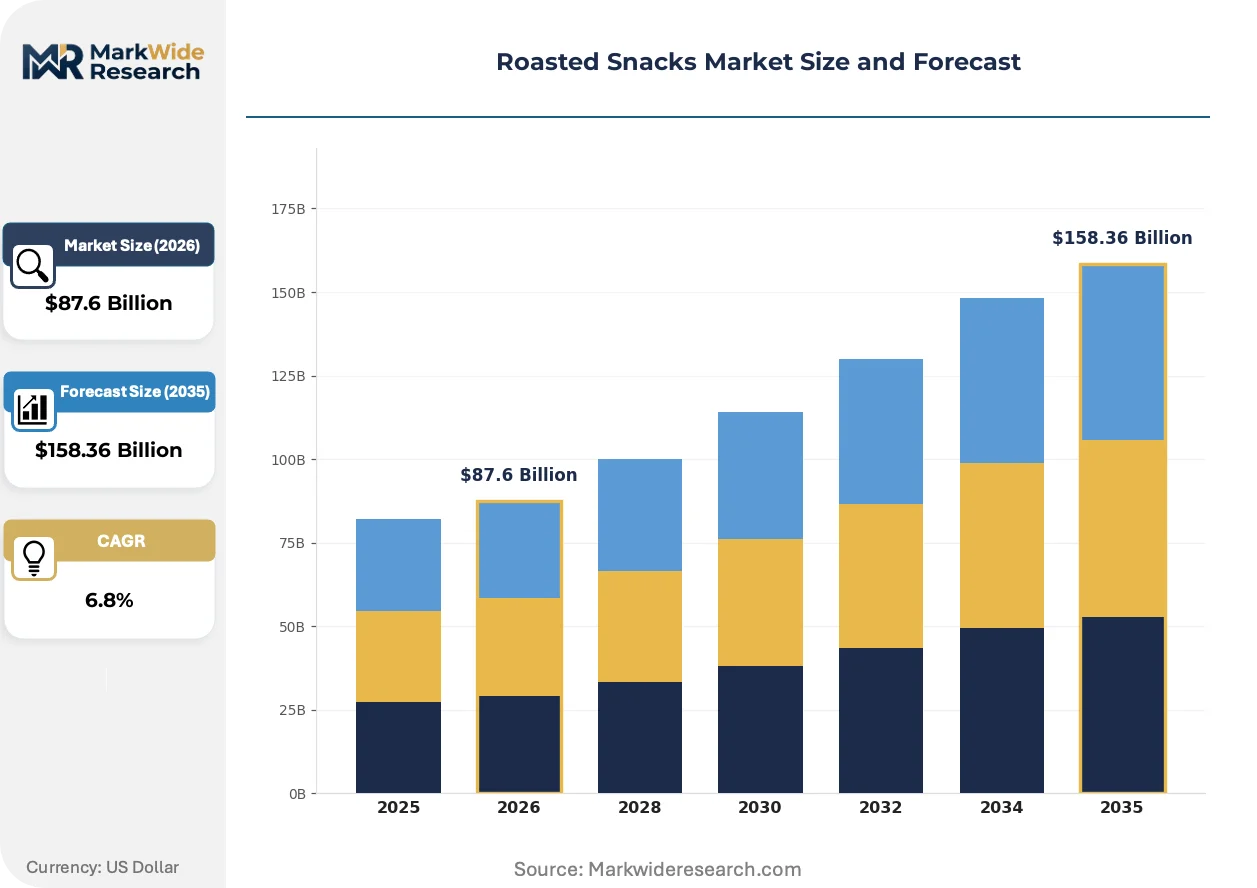
| Market Size in 2026 | $87.6 Billion |
| Market Size in 2035 | $158.36 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Peanuts, Cashews, Almonds, Sunflower Seeds Flavor Profile: Spicy, Sweet, Savory, Herb & Garlic Packaging Type: Bags, Canisters, Pouches, Jars Distribution Channel: Supermarkets, Online Retailers, Convenience Stores, Wholesale |
| Companies Covered | General Mills Inc., Calbee, Inc., PepsiCo Inc., Blue Diamond Growers, Intersnack Group, Nestlé SA, Conagra Brands Inc., Haldiram's, Mondelēz International, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Roasted Snacks Market Strategic Shifts
Thermal processing technology and packaging material science are converging to solve the clean-label shelf-life paradox. Regulatory pressure on sodium and additive disclosure is forcing simultaneous innovation across formulation, equipment, and supply chain verification.
Infrared roasting systems are migrating from artisanal nut processors into mid-scale commercial installations. These systems use electromagnetic radiation rather than convective hot air, cutting roasting time by 40 percent while preserving heat-sensitive tocopherols. Mid-tier co-packers in California and Gujarat are retrofitting gas-fired drum roasters with catalytic infrared emitters to meet corporate buyer energy intensity specifications.
REACH and the EU F-Gas Regulation are tightening volatile organic compound limits on roasting exhaust and refrigerant choices for post-roast cooling. European equipment manufacturers are integrating thermal oxidizers and ammonia-based cooling loops as standard configurations. Export-oriented processors in India must certify compliance to access German and Dutch retail channels, adding 8-12 weeks to equipment commissioning timelines.
Direct-to-pantry subscription models are fragmenting traditional distributor relationships in premium nut segments. Millennials in US coastal metros and Indian tech hubs are bypassing retail entirely for curated roasted snack assortments. These buyers prioritize origin traceability and small-batch roasting dates over brand recognition, compressing manufacturer margin structures while enabling premium pricing for verified clean-label claims.
Roasted Snacks Market Segmentation
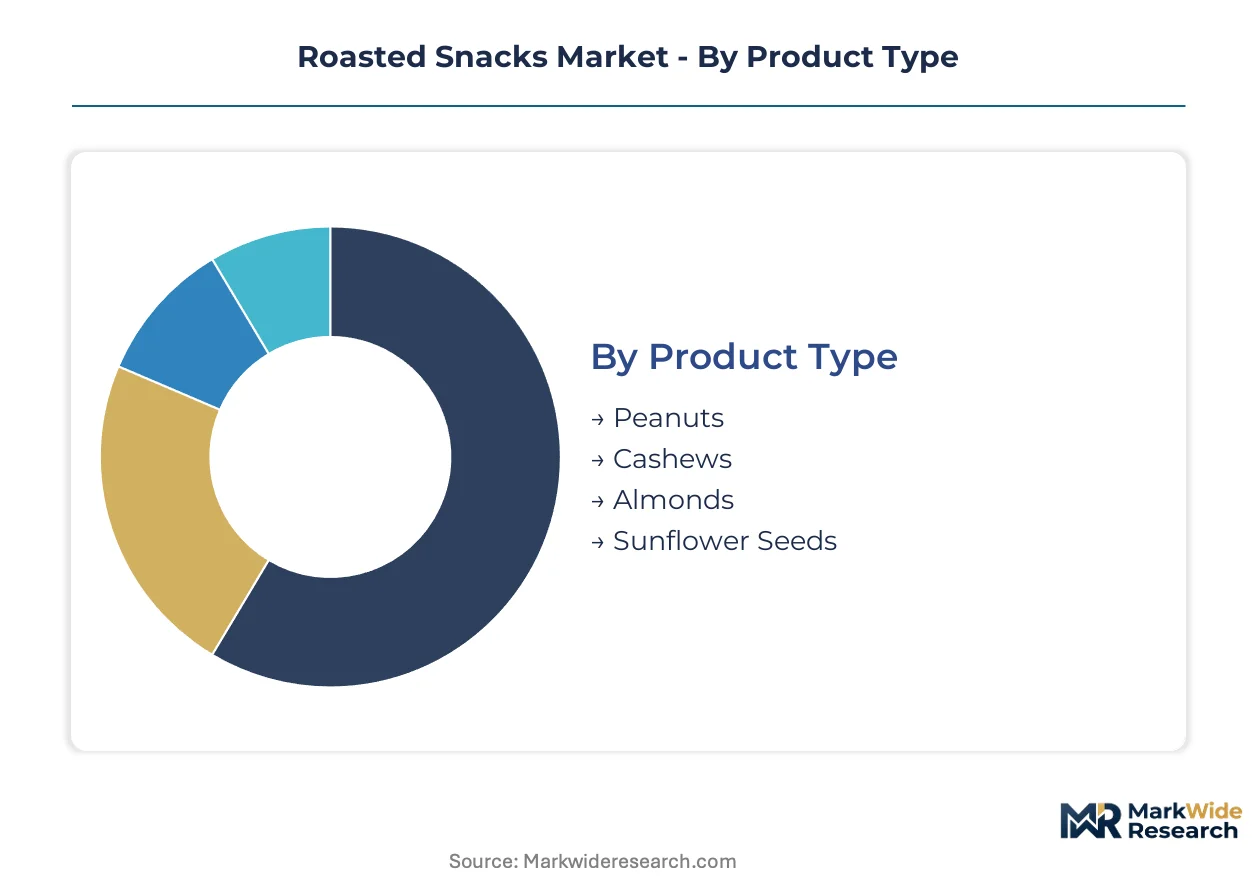
Segmentation in roasted snacks reveals how procurement specifications, thermal processing requirements, and channel economics fragment addressable demand. Manufacturers must align capacity investments against the tension between premium margin pools and volume throughput channels.
Product Type:
Mature tree nuts dominate revenue concentration while emerging seed categories expand ingredient diversification.
- Almonds:California-sourced kernels roasted at 140-160°C deliver premium tocopherol retention and Maillard browning control. Corporate cafeteria procurement in US tech campuses specifies almond minimums for wellness program tiers, though drought-driven supply volatility constrains contract security.
- Cashews:Vietnam and India-origin kernels command the highest unit margins due to labor-intensive shelling requirements and gift-channel positioning. Demand concentrates in Indian urban markets where cashew roasting displaces traditional fried snacks during festival gifting seasons.
- Peanuts:Runner and Virginia varieties anchor mass-market volume through convective roasting efficiency and oil stability.
- Sunflower Seeds:Ukrainian and Russian origin supply chains are rebuilding around Argentine alternatives for oilseed roasting feedstock.
Almonds handle the majority of throughput; sunflower seeds are the fastest mover on share.
Flavor Profile:
Cost tier stratification separates clean-label premium positioning from conventional seasoning systems.
- Savory:Salt-forward formulations face simultaneous FDA sodium disclosure mandates and FSSAI fortification guidelines, forcing yeast extract and mushroom powder substitutions for umami depth without synthetic enhancers.
- Spicy:Capsicum and black pepper heat profiles dominate Indian tier-two city consumption, where Haldiram's family formats compete with emerging single-serve premium positioning in Lucknow and Indore.
- Sweet:Honey and jaggery coatings require moisture barrier packaging upgrades to prevent stickiness and clumping.
- Herb & Garlic:Dehydrated allium and rosemary applications carry higher raw material costs but support clean-label claims in European export channels.
Savory commands volume leadership; herb & garlic is expanding most quickly on premium positioning.
Packaging Type:
Volume-to-weight economics and damage resistance requirements reshape format selection across channel mix.
- Pouches:Metallized polyester and emerging biodegradable laminates reduce shipping cube by 12-18 percent versus rigid alternatives. Online retail fulfillment economics favor crush-resistant flexible formats that withstand last-mile handling intensity.
- Canisters:Rigid paperboard and composite cylinders retain gift-channel dominance but face displacement as pouch technology improves oxygen transmission rate performance.
- Bags:Pillow and stand-up configurations balance cost efficiency with shelf presence in supermarket gravity-feed displays.
- Jars:Glass and PET rigid containers sustain premium positioning in travel retail and corporate gifting segments.
Pouches handle the majority of throughput; jars are climbing the fastest on premium channel expansion.
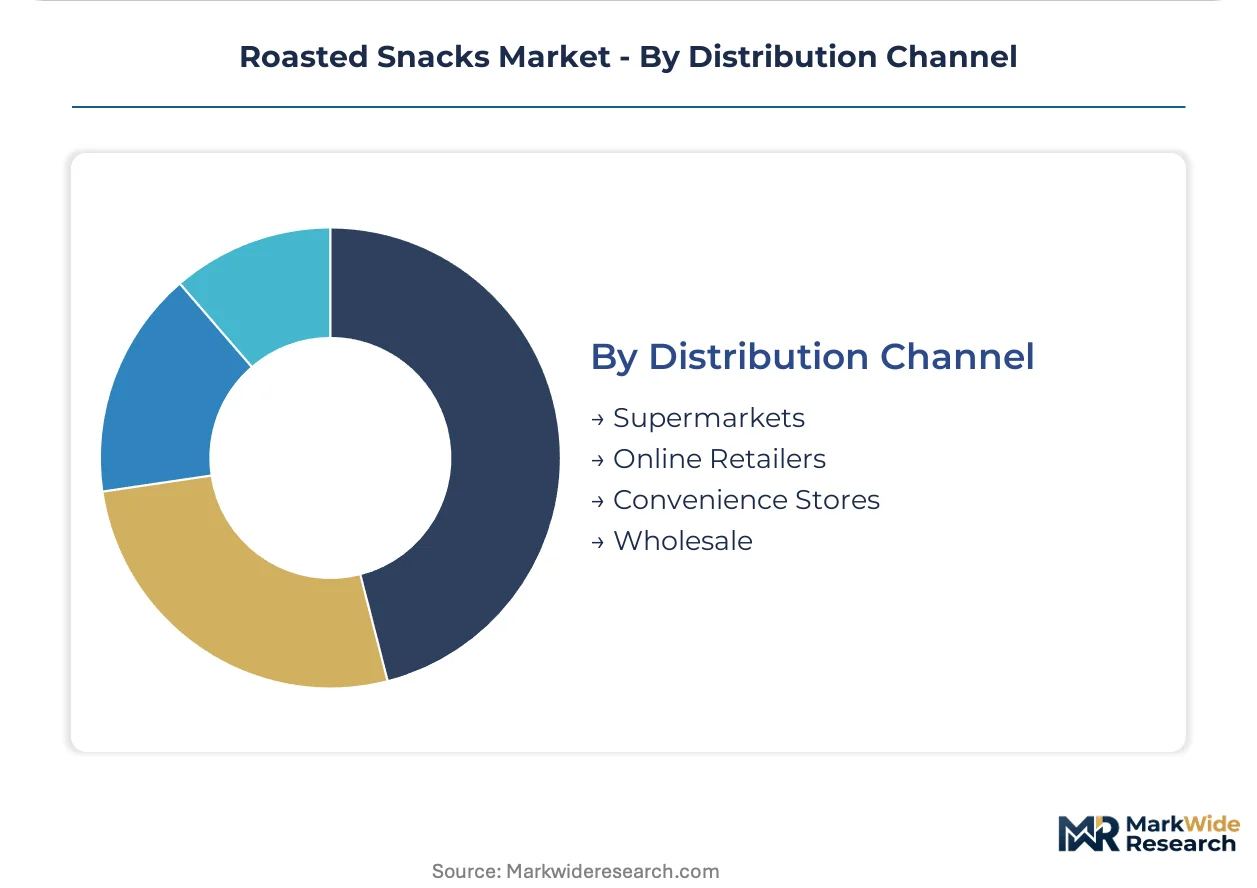
Distribution Channel:
Customer type fragmentation separates institutional procurement specifications from impulse-driven retail dynamics.
- Supermarkets:Planogram negotiations and slotting fees concentrate shelf access among PepsiCo and Haldiram's portfolios, though private-label roasted nut programs are expanding in European and North American banners.
- Online Retailers:Direct-to-pantry subscription models bypass traditional distributor relationships, with millennials in US coastal metros and Indian tech hubs prioritizing origin traceability and small-batch roasting dates over brand recognition.
- Convenience Stores:Single-serve price points and high-velocity turnover favor peanut and sunflower seed SKUs with extended ambient shelf life.
- Wholesale:Bulk roasted kernel supply to foodservice and co-manufacturing channels requires HACCP and FSSAI certification for institutional buyer compliance.
Supermarkets retain volume leadership; online retailers are gaining share fastest on subscription model penetration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Oakland anchors California almond exports to Asian markets, while the Jawaharlal Nehru Port Trust funnels Indian roasted snack shipments toward Middle Eastern retail channels. These maritime gateways shape procurement geography across the value chain.
United States
Corporate cafeteria procurement in Silicon Valley and Manhattan specifies clean-label roasted nut minimums for wellness program tiers. FDA sodium disclosure mandates accelerate reformulation investment in California processing facilities. The Central Valley roasting corridor from Fresno to Modesto concentrates almond thermal processing capacity serving both domestic and export demand.
India
Urban snack consumption in Lucknow and Indore displaces traditional fried alternatives with roasted cashew and peanut formats. FSSAI fortification guidelines reshape permissible additive profiles for seasoning systems. Gujarat and Maharashtra oven installations expand domestic roasting capacity under PLI scheme capital equipment subsidies.
Germany
REACH compliance and EU F-Gas Regulation thermal efficiency mandates extend equipment replacement timelines for industrial roasting lines. ECHA volatile organic compound limits on roasting exhaust tighten processor environmental obligations. The Baden-Württemberg equipment manufacturing cluster supplies catalytic infrared retrofit systems to mid-scale European processors.
China
Dual carbon goals alter capital equipment sourcing decisions for thermal processing installations in Shandong and Jiangsu provinces. SAMR food safety sampling protocols create certification delays for roasted nut matrix validation. The Yangtze River Delta concentrates domestic almond and cashew roasting capacity serving both local consumption and re-export demand.
Vietnam
Labor-intensive cashew shelling operations anchor kernel supply for premium gift-channel positioning in Asian markets. The country's national food safety regulator enforces HACCP certification for export-oriented roasting facilities. The Binh Phuoc processing cluster expands raw cashew roasting capacity to serve Indian and Chinese downstream demand.
Roasted Snacks Market Competitive Environment
Platform integrators command the system tier; component specialists sit upstream in ingredient and equipment supply. The vendor base organizes around three strategic archetypes: diversified CPG conglomerates with roasted snack divisions, regional family-owned processors with heritage distribution networks, and agricultural cooperative structures controlling raw material origination. Dominant competitive moves include portfolio diversification into clean-label sub-brands and backward integration into controlled supply chains for premium kernel procurement.
Among diversified CPG conglomerates, PepsiCo Inc. and Nestlé SA exemplify platform-scale positioning across multiple snack categories and geographies. Haldiram's occupies a distinctive position as a family-owned processor with entrenched distribution in Indian tier-two and tier-three cities. Blue Diamond Growers represents agricultural cooperative structures that anchor premium almond roasting through captive California supply chains.
| Leading Market Players |
|---|
| General Mills Inc. |
| Calbee, Inc. |
| PepsiCo Inc. |
| Blue Diamond Growers |
| Intersnack Group |
| Nestlé SA |
| Conagra Brands Inc. |
| Haldiram's |
| Mondelēz International, Inc. |
| Others |
Value Chain & Pricing Dynamics
The Port of Oakland to Jawaharlal Nehru Port Trust corridor carries California almond shipments to Indian roasting facilities, where freight cost fluctuations compress margins for mid-tier processors while enabling premium pricing for controlled-origin supply chains serving corporate cafeteria procurement.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates gift-channel cashew assortments from mass-market peanut SKUs and clean-label almond subscriptions. Price differentiation rests on California kernel grade certification and FSSAI fortification compliance tier. Pricing pressure stems from drought-driven almond supply volatility forcing contract renegotiations. Corporate cafeteria buyers show lowest price sensitivity; convenience store channels face highest volume-driven compression.
Supply Chain Analysis
Contract manufacturing concentrates in Gujarat and Maharashtra oven installations under PLI scheme subsidies, with Vietnam and California anchoring raw cashew and almond kernel supply respectively. Critical inputs draw from California cooperative structures, Vietnamese shelling operations, and Indian domestic peanut sourcing. Single-source vulnerability runs through California drought-exposed almond procurement. Distribution runs through PepsiCo and Haldiram's controlled urban networks alongside direct-to-pantry subscription bypass.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Roasted snack procurement fragmentation creates white-space niches as millennial wellness priorities splinter demand across clean-label subscription, corporate cafeteria minimums, and tier-two city premium positioning.
For Market Incumbents: Pre-empt infrared roasting technology adoption by retrofitting California and Gujarat batch facilities with automated thermal sensors before FSSAI acrylamide testing bottlenecks tighten. Lock tier-two Indian distribution through exclusive family-format shelf placement against Haldiram's heritage network erosion. Backward integration into controlled California almond supply hedges drought volatility threatening contract security.
For New Entrants and Emerging Players: Lucknow and Indore urban consumption growth outpaces metro saturation, creating single-serve premium positioning white space against Haldiram's bulk-format dominance. Target direct-to-pantry subscription models in Indian tech hubs and US coastal metros where origin traceability commands premium over brand recognition. Lead with small-batch roasting date transparency and clean-label certification to bypass established distributor relationships.
For Investors and Strategic Acquirers: Agricultural cooperative structures with captive California supply chains represent the most defensible acquisition archetype as almond concentration intensifies. Long-term viability hinges on water rights security and controlled kernel origination rather than brand equity. Monitor California groundwater regulation enforcement as inflection signal for supply cost restructuring.
| Strategic Initiative | Industry Significance |
|---|---|
| Clean-Label Reformulation Investment | Yeast extract and mushroom powder substitutions satisfy FDA sodium disclosure without synthetic enhancers. |
| Infrared Roasting Retrofit | Catalytic emitter installation cuts energy intensity 40 percent while preserving tocopherol content for corporate buyers. |
| Backward Integration into Kernel Supply | Controlled California almond origination hedges drought-driven contract renegotiation risk. |
| Direct-to-Pantry Subscription Launch | Millennial bypass of traditional distribution enables premium pricing for verified small-batch roasting dates. |
| Tier-Two Distribution Expansion | Lucknow and Indore shelf placement captures urban snack growth outpacing metro saturation. |
Study Parameters
A standing panel of roasting facility operations managers, corporate cafeteria procurement officers, FSSAI compliance consultants, and almond cooperative supply planners provided ongoing calibration against secondary validation through FDA labeling rule dockets, FSSAI fortification guideline publications, PLI scheme equipment subsidy records, and EU F-Gas Regulation compliance databases. Bottom-up capacity installations in Gujarat and Maharashtra triangulated against top-down trade flow analysis through Oakland and Jawaharlal Nehru ports.
Scenario-bracketing framed projections across clean-label adoption velocity, drought cycle severity, and corporate wellness program penetration. Segmentation dimensions modeled include nut type, flavor profile, packaging format, distribution channel, and thermal processing technology tier. CAGRs derived from installed capacity trajectories, import-export flow shifts, and procurement contract renewal patterns across the analysis window. Almond supply volatility and acrylamide testing capacity constraints served as industry-specific forecast sensitivity inputs.
The forecast holds incumbent behavior within observed patterns; aggressive moves by agricultural cooperatives into direct retail channels or technology entrants into infrared equipment supply would shift outcomes. Quarterly review of California groundwater adjudication proceedings, FSSAI testing lab queue lengths, and corporate cafeteria RFP issuance rates is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Snacks
Grass-Fed Jerkies Market
Snacks
Kids Snacks Market
Snacks
Healthy Snacks Market
Snacks
Australia Snack Bar Market
Snacks
United States Snack Bar Market
Snacks
Fruit Jerky Market
Snacks
Asia-Pacific Cereal Bar Market
Snacks
North America Baked Chips Market
Snacks
Specialty Snacks Market
Snacks
Roasted Corn Market
Snacks
Cheese Snacks Market
Snacks
Snack Products Market
Snacks
Low Calorie Granola Market
Snacks
Argentina Snack Bar Market
Snacks
UAE Cereal Bar Market
Snacks
US Potato Chips Market