
 Refrigerated Snacks Market | 2026-2036
Refrigerated Snacks Market Size, Share, and Industry Trends Forecast 2026-2036
Refrigerated Snacks Market Outlook
Asset-light leasing models for cold-storage infrastructure are reconfiguring competitive entry barriers, allowing regional brands to scale without capital-heavy distribution builds. General Mills leverages its captive refrigerated logistics network to sustain national coverage of fresh snack lines. Conagra Brands anchors its position through backward integration into protein processing. Nestle S.A. differentiates via specialized dairy-based formulations that command shelf space in premium retail channels.
Refrigerated snacks comprise perishable food items requiring continuous temperature control between one and five degrees Celsius from production through consumption, preserving microbial safety, texture integrity, and nutrient retention for immediate or near-term consumption. Cheese and yogurt segments dominate current shelf space allocation, while fresh cut fruits represent the fastest-growing product type as health-positioned snacking accelerates. Single-serve packaging controls the highest margin pool due to portion-premium pricing and impulse-purchase velocity, though eco-friendly formats are gaining traction as retailer sustainability mandates tighten.
The FDA enforces Hazard Analysis Critical Control Point protocols and cold-chain documentation standards that shape manufacturing investments and liability exposure for refrigerated snack producers. USDA grading requirements for dairy and meat components further constrain formulation flexibility and supplier qualification. Stakeholders must monitor evolving state-level extended producer responsibility laws for packaging, as these will determine which material formats retain distribution access across major retail networks.
Market Dynamics
Cold-chain traceability mandates from the FDA are compressing legacy packaging formats while forcing capital redeployment toward sensor-enabled logistics infrastructure. Food service operators now demand lot-level temperature documentation as a procurement prerequisite.
Growth Catalysts
- FSMA Rule 204:The FDA's enhanced recordkeeping requirements for high-risk foods are accelerating RFID adoption across refrigerated snack distribution networks.
- Urban convenience retail:Dense metropolitan corridors in the United States are expanding refrigerated grab-and-go shelf space as commuter snacking patterns intensify.
- Active packaging:Oxygen-scavenging films and time-temperature indicators are extending viable distribution radius for regional fresh snack brands.
Market Restraints
- Dairy input volatility:Fluid milk price swings constrain margin predictability for cheese-dominant snack lines.
- Refrigerated logistics concentration:Third-party cold storage capacity clusters in coastal port zones, limiting inland market access.
- Extended producer responsibility laws:State-level packaging recovery mandates in California and New York are disqualifying multi-layer plastic formats from retail distribution.
Strategic Opportunities
- Fresh-cut vegetable snacking:Underdeveloped shelf space in Midwestern US retail presents white space beyond fruit-dominated assortments.
- Direct-store-delivery digitization:Route-optimization platforms are enabling micro-regional brands to bypass traditional warehouse distribution.
- USDA BioPreferred program:Federal procurement preferences for biobased packaging materials create incentive alignment for compostable tray formats.
Industry Challenges
- HACCP certification timelines:New facility qualification periods stretch 18-24 months, delaying geographic expansion for emerging brands.
- Cold-chain talent scarcity:Refrigeration technician and quality assurance specialist shortages constrain operational scaling in secondary markets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Refrigerated Snacks Market |
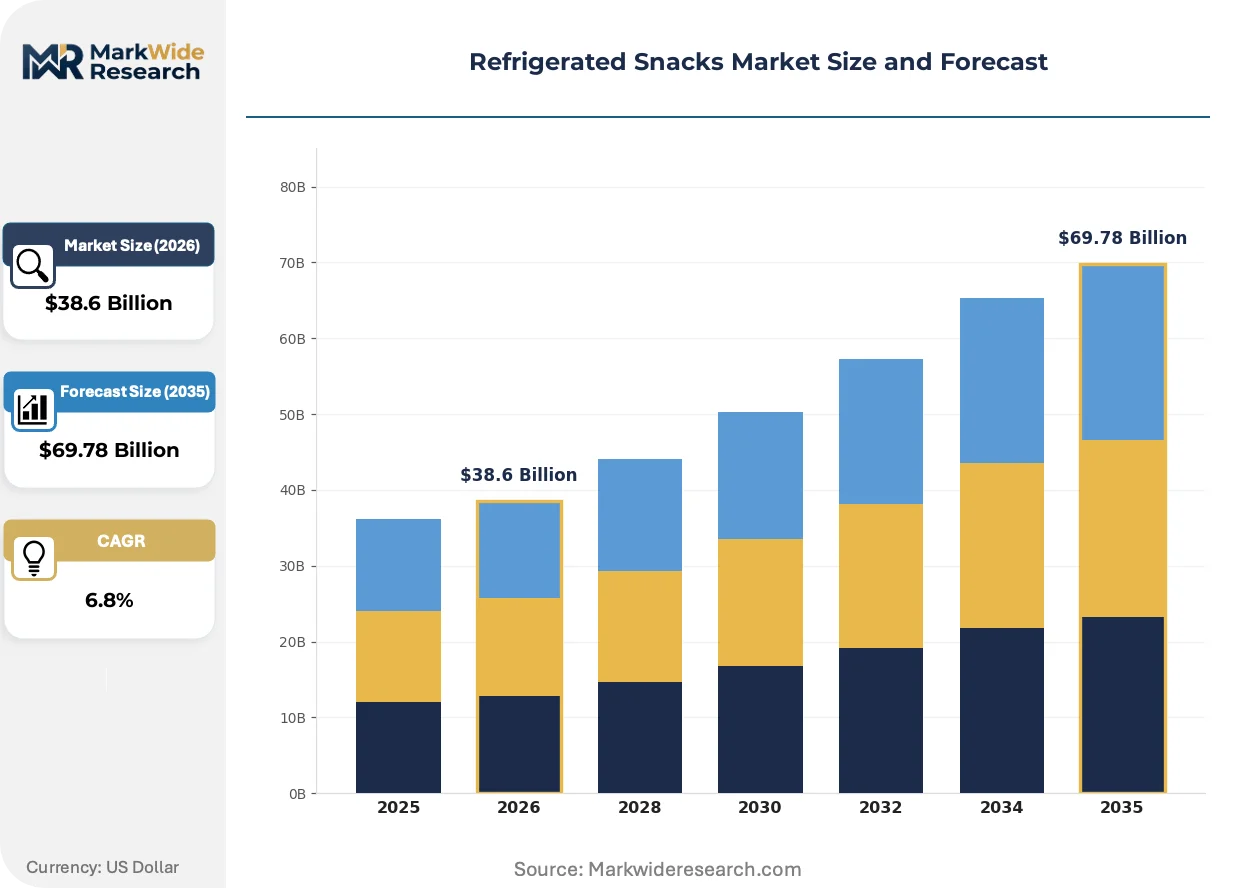
| Market Size in 2026 | $38.6 Billion |
| Market Size in 2035 | $69.78 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cheese, Yogurt, Deli Meats, Fresh Cut Fruits Packaging Type: Single Serve, Multi-Serve, Bulk, Eco-Friendly End User: Retail Consumers, Food Service Outlets, Catering Companies, Institutions Distribution Channel: Supermarkets, Convenience Stores, Online Retail, Vending Machines |
| Companies Covered | General Mills, Conagra Brands, Nestle S.A., Mars Incorporated, Danone S.A., Mondelez International, The Kraft Heinz Company, Hormel Foods Corporation, PepsiCo, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Refrigerated Snacks Market Strategic Shifts
Refrigerated snack production is converging with precision fermentation and smart logistics to compress freshness windows while expanding distribution reach. Three forces are reconfiguring competitive position.
Smart active packaging embedded with NFC temperature loggers is collapsing the information gap between production and point-of-sale. Retailers including Kroger and Whole Foods Market are mandating these sensors for private-label fresh snack suppliers. The technology is collapsing liability exposure for temperature excursions while enabling dynamic pricing based on remaining shelf life.
The FDA's Food Traceability Final Rule is compelling enterprise resource planning upgrades across mid-sized processors. Compliance costs are diverting R&D budgets toward documentation systems rather than product innovation. Dairy-forward snack categories face the steepest adaptation curves due to multi-ingredient supplier networks.
Corporate cafeteria and college campus food service operators are consolidating procurement through group purchasing organizations. These intermediaries are squeezing brand-level margins while favoring suppliers with national refrigerated distribution coverage. The concentration is most pronounced in the Northeast and Mid-Atlantic metropolitan corridors where contract values exceed $50 million annually.
Refrigerated Snacks Market Segmentation
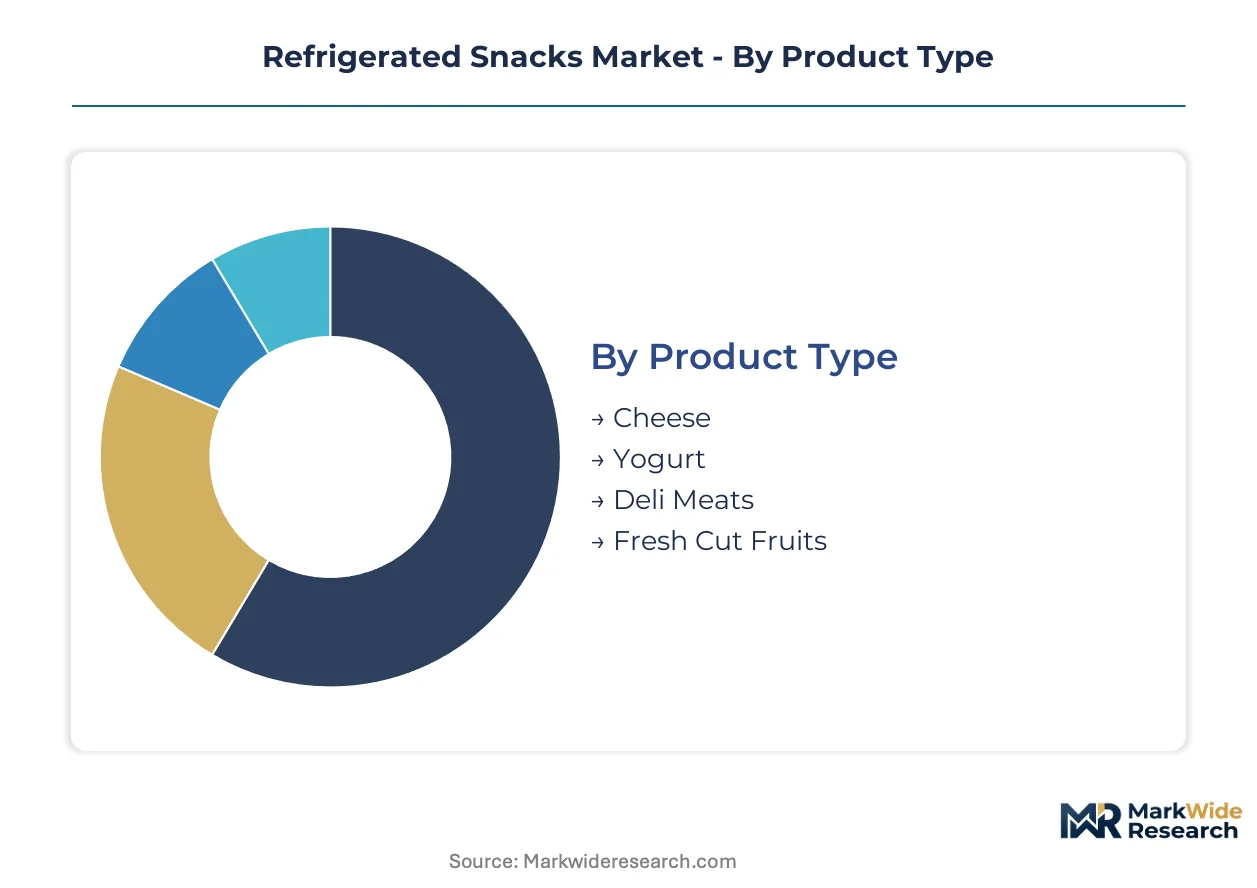
Refrigerated snack segmentation reveals divergent margin profiles across temperature-sensitive formats. Product chemistry and packaging geometry determine cold-chain investment intensity, while end-user concentration shapes route-to-market economics.
Product Type:
Mature dairy formats anchor current shelf space allocation while emerging fresh produce lines capture health-positioned demand.
- Cheese:Aged and fresh cheese varieties require precise humidity control alongside temperature management. Convenience stores in dense urban corridors drive velocity for string cheese and portion-controlled wedges. Dairy input cost swings compress margin predictability for processors.
- Fresh Cut Fruits:Melon, berry, and apple assortments demand modified atmosphere packaging to arrest enzymatic browning. College campus food service operators in the United States are expanding procurement of grab-and-go fruit cups as wellness mandates intensify. Short shelf windows constrain distribution radius without active packaging intervention.
- Yogurt:Greek and drinkable formats dominate dairy-based snacking with live culture stability requirements.
- Deli Meats:Sliced turkey and ham snack packs carry USDA inspection compliance burdens that extend supplier qualification timelines.
Cheese retains volume leadership; fresh cut fruits hold the steepest expansion curve.
Packaging Type:
Cost tier stratification separates premium convenience formats from economy bulk offerings, with sustainability premiums emerging as a distinct pricing layer.
- Single Serve:Individual portions in rigid trays or flexible pouches command impulse-purchase premiums at convenience store checkout. Portion-controlled geometry minimizes food safety liability for institutional feeders. Higher per-ounce pricing offsets cold-chain spoilage risk.
- Eco-Friendly:Compostable trays and bio-based films align with California and New York extended producer responsibility mandates. Kroger and Whole Foods Market are delisting multi-layer plastic alternatives for private-label fresh snacks. Material cost premiums run 15-25% above conventional formats.
- Multi-Serve:Family-size configurations target warehouse club channels with lower per-unit packaging burden.
- Bulk:Food service totes and institutional tubs minimize packaging cost for high-volume catering accounts.
Single serve commands absolute margin dollars; eco-friendly formats are climbing the fastest as retailer sustainability gates tighten.
End User:
Application concentration varies sharply between impulse-driven individual consumption and planned procurement for away-from-home feeding.
- Food Service Outlets:Corporate cafeterias and quick-service restaurants demand lot-level temperature documentation under FDA FSMA Rule 204. Group purchasing organizations in the Northeast are consolidating procurement through $50 million-plus annual contracts. Speed-of-service pressures favor pre-portioned formats that reduce labor touchpoints.
- Retail Consumers:Urban commuters in metropolitan United States corridors drive grab-and-go velocity at convenience stores and small-format supermarkets. Premium positioning for fresh snacking supports trade-up from shelf-stable alternatives.
- Catering Companies:Event-based demand concentrates in wedding and corporate hospitality segments with high visibility for brand placement.
- Institutions:K-12 schools and healthcare facilities face USDA commodity program constraints and therapeutic diet specifications.
Food service outlets concentrate procurement volume; retail consumers sustain the most fragmented brand competition.
Distribution Channel:
Geography of demand clusters determines refrigeration infrastructure deployment, with urban density enabling distinct channel economics.
- Convenience Stores:Dense metropolitan corridors in Chicago, New York, and Los Angeles support dedicated refrigerated display investment. Commuter snacking patterns concentrate purchase occasions in morning and evening dayparts. Limited shelf space favors high-velocity SKUs with rapid inventory turns.
- Online Retail:Direct-to-home delivery requires insulated packaging and gel pack logistics that add $3-5 per order fulfillment cost. Amazon Fresh and Instacart are expanding refrigerated snack assortment as last-mile cold-chain reliability improves.
- Supermarkets:Traditional grocery maintains broadest assortment depth across all product types and packaging formats.
- Vending Machines:Micro-market and smart cooler formats are penetrating office and university settings with cashless payment integration.
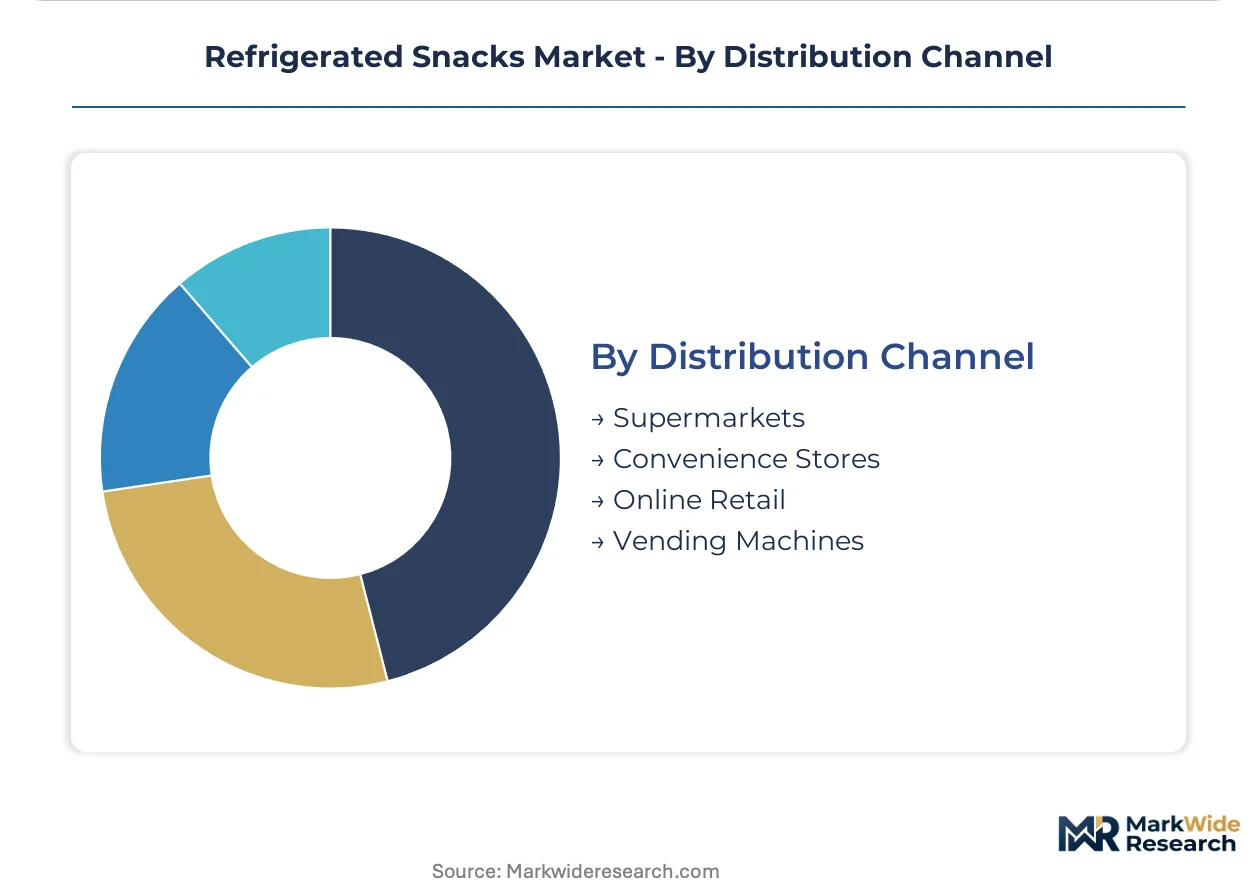
Convenience stores dominate transaction frequency; online retail is gaining share fastest as fulfillment economics approach parity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA cold-chain traceability mandates are accelerating infrastructure investment across major consumption corridors. Urban density and commuter snacking patterns concentrate demand in metropolitan clusters with established refrigerated logistics networks.
United States
Convenience culture and premium fresh snacking habits drive category velocity in urban retail corridors from New York to Los Angeles. The FDA's Food Safety Modernization Act requirements for lot-level documentation shape procurement standards for food service operators. The Chicago metropolitan area anchors Midwestern distribution with expanding refrigerated grab-and-go shelf space at commuter rail terminals.
Germany
Discounter retail formats and strong dairy consumption traditions sustain refrigerated snack penetration in metropolitan Rhine-Ruhr and Bavarian corridors. EFSA labeling requirements and national packaging ordinances under the EU Green Deal constrain multi-layer plastic formats. The Munich-Stuttgart corridor concentrates precision logistics infrastructure for temperature-sensitive fresh food distribution.
Japan
Convenience store density in Tokyo-Osaka corridors supports sophisticated chilled ready-to-eat snacking cultures with short replenishment cycles. METI energy efficiency standards for commercial refrigeration equipment shape cold-chain infrastructure investment decisions. The Kanto region's kombini network maintains industry-leading inventory velocity for single-serve dairy and fresh-cut formats.
United Kingdom
Meal-deal culture at urban convenience outlets drives refrigerated snack attachment rates in London and Southeast commuter zones. Extended producer responsibility regulations and plastic packaging taxes accelerate format transitions toward fiber-based trays. The Midlands distribution triangle anchors national cold-storage capacity for fresh food manufacturers.
France
Fromagerie traditions and strong dairy processing infrastructure support premium positioned refrigerated snacking in Paris and Lyon metropolitan areas. EFSA dairy safety protocols and national origin labeling requirements constrain supplier qualification timelines. The Île-de-France region concentrates food service procurement through centralized catering contracts for corporate and institutional accounts.
Refrigerated Snacks Market Competitive Environment
On the supply side, the industry is consolidating around integrated processors with captive cold-chain infrastructure and national distribution coverage. Tiered competitive positioning separates multinational packaged food conglomerates from regional fresh specialists and private-label suppliers. Strategic archetypes include backward-integrated protein processors, dairy-forward formulation specialists, and asset-light brand marketers leveraging third-party logistics. Dominant competitive moves center on direct-store-delivery network expansion and sustainable packaging format transitions ahead of retailer compliance deadlines.
Among North American packaged food conglomerates, General Mills, Conagra Brands, and Nestle S.A. occupy positions spanning the competitive spectrum. General Mills exemplifies the logistics-integrated archetype through captive refrigerated distribution networks sustaining national fresh snack coverage. Conagra Brands represents backward integration into protein processing as a margin defense mechanism against dairy input volatility. Nestle S.A. anchors the premium dairy-based formulation tier with specialized products commanding shelf space in high-velocity retail channels.
| Leading Market Players |
|---|
| General Mills |
| Conagra Brands |
| Nestle S.A. |
| Mars Incorporated |
| Danone S.A. |
| Mondelez International |
| The Kraft Heinz Company |
| Hormel Foods Corporation |
| PepsiCo |
| Others |
Value Chain & Pricing Dynamics
Fluid milk futures clustering in Chicago Mercantile Exchange trading floors concentrate margin volatility downstream for cheese-dominant snack processors. Cold-chain infrastructure ownership patterns determine who captures value: asset-heavy operators command route premiums while third-party logistics users absorb pass-through fuel and refrigeration surcharges.
Pricing Analysis
Certification level creates the primary spread across refrigerated snack tiers, with USDA organic and animal welfare-approved dairy inputs commanding shelf-space premiums at Whole Foods Market and Sprouts Farmers Market. Three-tier pricing structure across premium, standard, and economy levels separates single-serve active-packaged formats from conventional multi-serve tubs. Cost compression in conventional cheese sticks is intensifying because fluid milk price swings transmit directly to processor margins. Institutional food service buyers exhibit highest price sensitivity due to group purchasing organization contract structures, while urban convenience store shoppers show lowest elasticity for impulse-positioned premium singles.
Supply Chain Analysis
Extended payment terms from Kroger and Albertsons squeeze working capital for mid-sized dairy processors, forcing supply-chain finance facility adoption. Manufacturing concentrates in Wisconsin, California, and New York, with protein processing drawing from Corn Belt feedlot supply zones and Central Valley dairy cooperatives. Raw material dependencies rest on fluid milk, active packaging films, and compostable tray substrates. Single-source vulnerability in third-party cold storage clustering around Chicago O'Hare and Los Angeles port corridors threatens inland distribution reach. Distribution runs through direct-store-delivery networks for fresh velocity, supplemented by warehouse consolidation for multi-serve formats.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Scarcity of HACCP-certified production capacity and refrigeration technician labor pools constrains how quickly emerging brands can replicate national coverage. The capability gap favors incumbents with captive infrastructure but creates acquisition targets for well-capitalized entrants.
For Market Incumbents: Entrench market position through backward integration into dairy processing cooperatives, insulating margin exposure to fluid milk volatility. Expand direct-store-delivery digitization in secondary Midwestern markets before regional specialists consolidate route density. FDA FSMA Rule 204 compliance investment represents the critical certification lever for food service contract retention. For New Entrants and Emerging Players: Fresh-cut vegetable snacking in Midwestern retail corridors represents the most penetrable entry point, with underdeveloped shelf space beyond fruit-dominated assortments. USDA BioPreferred program alignment enables federal procurement channel access with lower competitive intensity. Route-optimization platform partnerships offer the most viable go-to-market angle to bypass capital-heavy warehouse distribution builds. For Investors and Strategic Acquirers: Capital is best deployed toward mid-sized processors with HACCP-qualified facilities and established direct-store-delivery networks in underserved geographies. Long-term viability hinges on cold-chain infrastructure ownership rather than brand equity alone. Watch for state-level extended producer responsibility law expansion as the signal indicating which packaging-format investments will retain retail distribution access.| Strategic Initiative | Industry Significance |
|---|---|
| Direct-Store-Delivery Digitization | Route-optimization platforms enable micro-regional brands to bypass traditional warehouse distribution economics. |
| Sustainable Packaging Transition | Compostable tray adoption ahead of California and New York EPR deadlines secures retail shelf access. |
| Backward Integration into Dairy Processing | Captive milk supply insulates margin predictability against CME futures volatility for cheese-forward lines. |
| Smart Active Packaging Deployment | NFC temperature loggers satisfy Kroger and Whole Foods Market mandates while enabling dynamic shelf-life pricing. |
| Fresh-Cut Vegetable Line Extension | White space beyond fruit-dominated assortments captures health-positioned demand in Midwestern retail corridors. |
Study Parameters
The analysis maps cheese, yogurt, fresh-cut fruit, and deli meat segments, each validated through cold-chain logistics directors, retail category buyers, food service procurement officers, and dairy cooperative managers. Primary fieldwork combined structured interviews with secondary validation through FDA FSMA guidance documents, USDA dairy market statistics, customs cold-storage facility records, and Nielsen retail audit data. Bottom-up volume modeling and top-down expenditure reconciliation ensured cross-verification across the analysis window.
Assumptions held fixed include current FDA cold-chain traceability requirements and existing state-level extended producer responsibility law coverage, while dairy input cost trajectories and refrigerated logistics capacity expansion varied across scenarios. Segmentation dimensions modeled encompass product chemistry, packaging geometry, end-user concentration, and distribution channel infrastructure intensity. CAGRs derived from historical velocity patterns projected against urban convenience retail expansion curves and food service procurement consolidation trends.
Practitioners should monitor fluid milk futures volatility, EPR law adoption in additional states, and RFID sensor cost curves for early signals of forecast deviation. Forecasts reflect assumptions about regulatory stability and cold-chain infrastructure investment continuity. Macroeconomic recession compressing away-from-home food expenditure, regulatory acceleration of packaging format bans, or breakthroughs in ambient-stable fresh preservation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Snacks
Nutritional Bar Market
Snacks
North America Potato Chips Market
Snacks
Marshmallow Market
Snacks
Low Calorie Dip Market
Snacks
Organic Chips Market
Snacks
Middle East Snack Bar Market
Snacks
Global Tortilla Chips Market
Snacks
Organic Snacks Market
Snacks
Snack Subscription Market
Snacks
China Snack Bar Market
Snacks
United Kingdom Snack Bar Market
Snacks
Non-Potato Veggie Chips Market
Snacks
Seaweed Snacks Market
Snacks
Nachos Market
Snacks
South Africa Snack Bar Market
Snacks
Allergy-Free Snacks Market