
 Europe Snacks Market | 2026-2036
Europe Snacks Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Snacks Market Foresight
On-the-go consumers is bifurcating demand away from traditional family pantry stocking across Europe. PepsiCo Inc. leverages its direct-store-delivery infrastructure to dominate impulse channels in transit hubs and convenience formats. Mondelez International Inc. differentiates through premium chocolate snack portfolios calibrated to German and French taste preferences. Intersnack Group GmbH anchors its position with deep regional manufacturing scale in savory categories.
Europe snacks encompass processed, ready-to-eat food items typically consumed between meals, manufactured through baking, frying, extrusion, or dry-roasting processes with moisture content below ten percent to ensure shelf stability and portability. Their primary commercial purpose centers on delivering convenient, portion-controlled consumption occasions across retail, foodservice, and vending channels. Savory profiles lead absolute volume across the continent, though spicy variants capture the fastest growth in Southern European markets where heat-forward innovation accelerates. Pouch packaging commands margin pools through resealability and sustainability credentials, while bag formats sustain volume dominance in price-sensitive retail tiers.
EFSA nutrient profiling rules and EU Green Deal sustainability mandates reshape permissible formulations and packaging substrates across member states. Germany's Bundesamt für Verbraucherschutz und Lebensmittelsicherheit enforces stricter sodium and trans-fat ceilings than southern counterparts, creating uneven compliance burdens. France's ANSES contributes additive safety assessments that filter into EU-wide EFSA opinions. Stakeholders must monitor whether pending EU-wide harmonized front-of-pack labeling will force reformulation cycles before national implementation diverges further.
Market Dynamics
EFSA's nutrient profiling criteria and EU Green Deal packaging mandates are compressing permissible formulation spaces while rerouting capital toward reformulation and substrate innovation.
Growth Catalysts
- EU Green Deal packaging mandates:Recyclable and biodegradable substrate requirements are accelerating investment in mono-material pouches and paper-based alternatives across member states.
- Urban transit infrastructure:Expanded rail and metro networks in Germany, France, and the Netherlands are creating high-frequency impulse purchase touchpoints for on-the-go formats.
- Extrusion technology advancement:Twin-screw extrusion improvements enable cleaner-label savory snacks with reduced sodium and fat while maintaining texture profiles.
Market Restraints
- Sunflower oil price volatility:Black Sea supply disruptions and EU agricultural policy shifts create margin compression for fried snack categories dependent on this input.
- German BVL enforcement stringency:Stricter sodium and trans-fat ceilings than southern EU counterparts force dual formulation runs, elevating compliance costs.
- Fresh prepared food substitution:Refrigerated grab-and-go alternatives in convenience retail are capturing occasion share from ambient shelf-stable snacks.
Strategic Opportunities
- Poland and Romania penetration:Modern trade expansion and rising disposable incomes in these markets offer first-mover advantages for premium private-label positioning.
- EFSA front-of-pack harmonization:Pending Nutri-Score or equivalent mandatory labeling creates reformulation service opportunities for ingredient suppliers.
- Direct-to-vending channel innovation:Smart vending with cashless payment and real-time inventory telemetry opens unmanned retail in transit and workplace locations.
Industry Challenges
- Clean-label R&D talent scarcity:Formulation chemists capable of replacing artificial preservatives and flavor enhancers with natural alternatives command premium compensation.
- Packaging line reconfiguration capex:Transitioning from multi-layer laminates to recyclable mono-materials requires substantial equipment investment with extended payback periods.
- Cross-border regulatory divergence:Varying national implementation timelines for EU-wide directives create inventory and labeling complexity for pan-European portfolios.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Snacks Market |
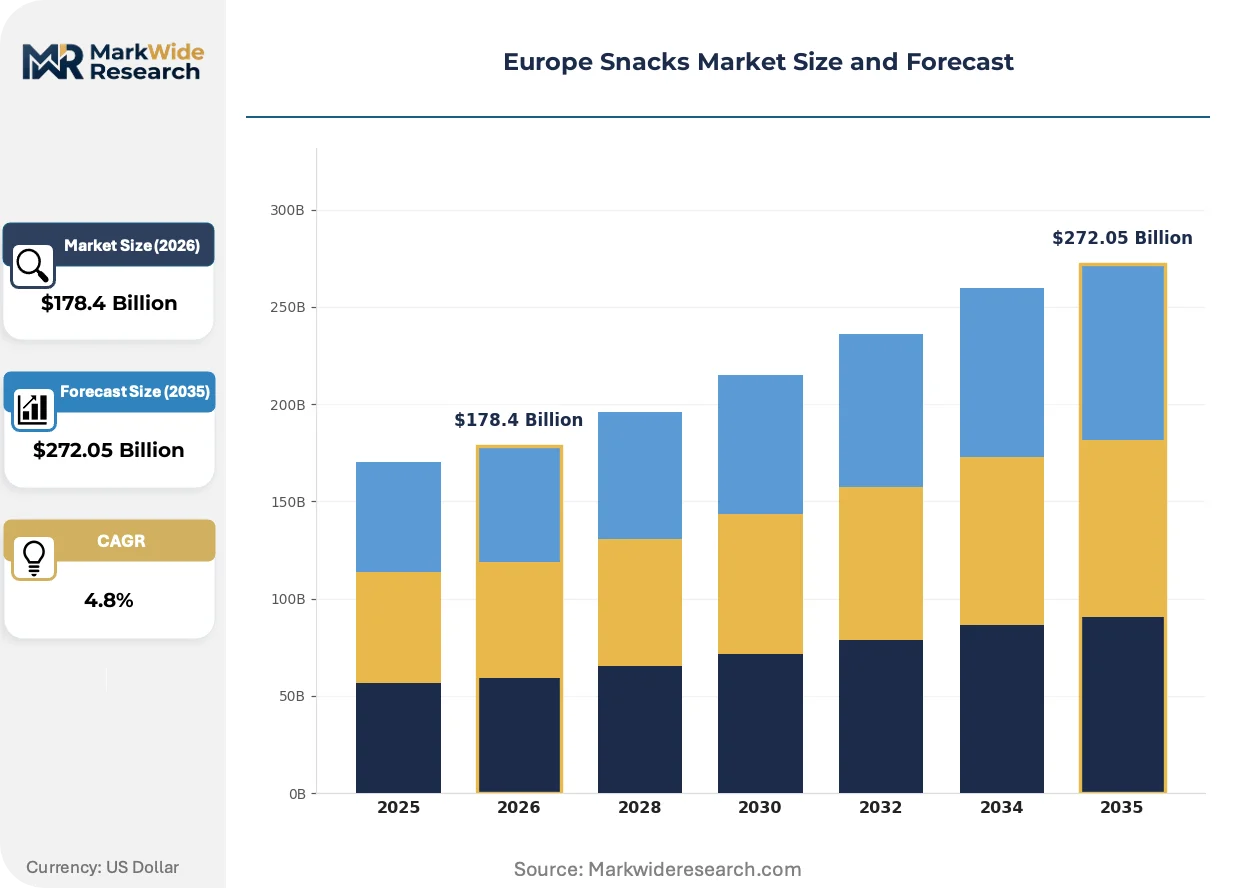
| Market Size in 2026 | $178.4 Billion |
| Market Size in 2035 | $272.05 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Chips, Popcorn, Nuts, Pretzels Flavor Profile: Savory, Sweet, Spicy, Mixed Packaging Type: Bags, Boxes, Tins, Pouches End User: Children, Adults, Families, On-the-Go Consumers |
| Companies Covered | Mars Inc., Intersnack Group GmbH, PepsiCo Inc., Unilever PLC, Ferrero SpA, Nestlé S.A., General Mills Inc., Orkla ASA, Mondelez International Inc., Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Snacks Market Shifts & Advancements
Reformulation pressures and substrate innovation are fragmenting competitive advantage away from scale economics toward technical compliance and speed-to-shelf capabilities.
Pulse-based extrusion is bifurcating the savory snack landscape. Fava bean and lentil flours enable elevated protein and fiber claims while maintaining crunch texture. Health-positioned buyers in Germany and the Netherlands are adopting these alternatives at pace. This technology is bifurcating margin pools between legacy potato and corn bases and premium-priced pulse alternatives.
EFSA's evolving nutrient profiling framework is tightening permissible health and nutrition claims. Manufacturers must substantiate reformulated products through clinical or compositional evidence before marketing. Savory categories with historically high sodium content face the steepest compliance burdens, accelerating stealth reduction programs.
Workplace micro-market formats are displacing traditional vending in corporate campuses and logistics hubs. These unattended retail stations offer broader assortment, fresh adjacencies, and data-driven replenishment. France and Belgium demonstrate the fastest penetration of this channel, compressing conventional vending operator margins.
Europe Snacks Market Segmentation
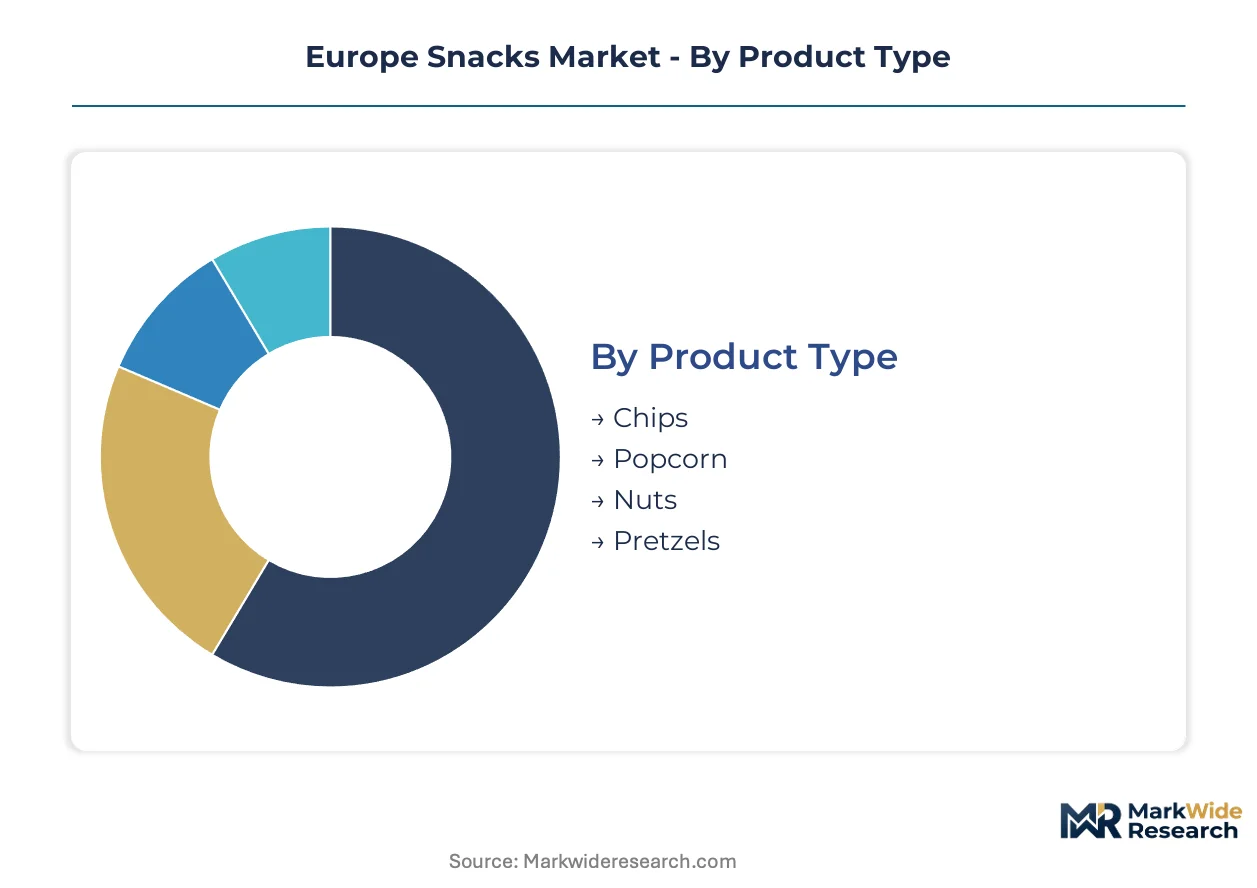
Segmentation in the Europe Snacks Market reveals how reformulation pressures and channel fragmentation are reshaping competitive advantage. Manufacturers must align portfolio architecture with distinct occasion-based demand clusters and tightening EFSA nutrient profiling thresholds.
Product Type:
Chips face the most acute substitution threat from fresh prepared alternatives in German and French convenience retail, while popcorn and nuts leverage health-positioning to defend shelf space.
- Chips:Potato and corn-based fried or baked slices with moisture content below seven percent. German demand concentrates in private-label premium tiers where reduced-sodium formulations command price premiums despite BVL enforcement complexity.
- Popcorn:Exploded corn kernels with oil or dry coatings enabling clean-label positioning. Netherlands and Belgium buyers are adopting air-popped and lightly seasoned variants fastest as workplace micro-market penetration accelerates.
- Nuts:Dry-roasted or raw tree nuts and peanuts with minimal processing. German and French markets show strong demand for portion-controlled packs in transit channel vending.
- Pretzels:Wheat-based baked knots with alkaline treatment delivering distinctive texture. Southern European markets favor compact formats for on-the-go consumption.
Chips anchor the volume base while popcorn gains share at the steepest rate.
Flavor Profile:
Margin concentration follows reformulation difficulty, with savory profiles requiring the most sodium reduction investment and spicy variants capturing occasion expansion.
- Savory:Salt, cheese, and herb-based seasonings dominating absolute consumption. German BVL sodium ceilings force stealth reduction programs that elevate R&D costs for market leaders.
- Spicy:Chili, paprika, and pepper-forward heat profiles. Spanish and Italian buyers are adopting these variants fastest as regional taste preferences shift toward bolder sensory experiences.
- Sweet:Sugar or alternative-sweetener coatings on popcorn, nuts, or extruded bases. French and Belgian markets show concentration in evening consumption occasions.
- Mixed:Combination profiles blending savory, sweet, and heat elements. German urban consumers are driving trial through premium private-label innovation.
Savory formats retain the largest revenue pool while spicy profiles expand most quickly across Southern Europe.
Packaging Type:
EU Green Deal substrate mandates are compressing margin pools differently across formats, with multi-layer laminates facing forced obsolescence.
- Pouches:Flexible multi-layer or emerging mono-material structures with resealability features. German and Dutch markets concentrate demand for recyclable mono-material alternatives as EFSA packaging rules tighten.
- Bags:Single-use flexible packaging dominating price-sensitive retail tiers. Volume concentrates in Eastern European modern trade expansion.
- Boxes:Rigid paperboard containers for premium gifting or multi-serve formats. French seasonal demand peaks drive concentration.
- Tins:Metal containers for premium nuts and specialty items. German Christmas and holiday occasions anchor this segment.
Bags sustain volume leadership while pouches capture the steepest share gains through sustainability credentialing.
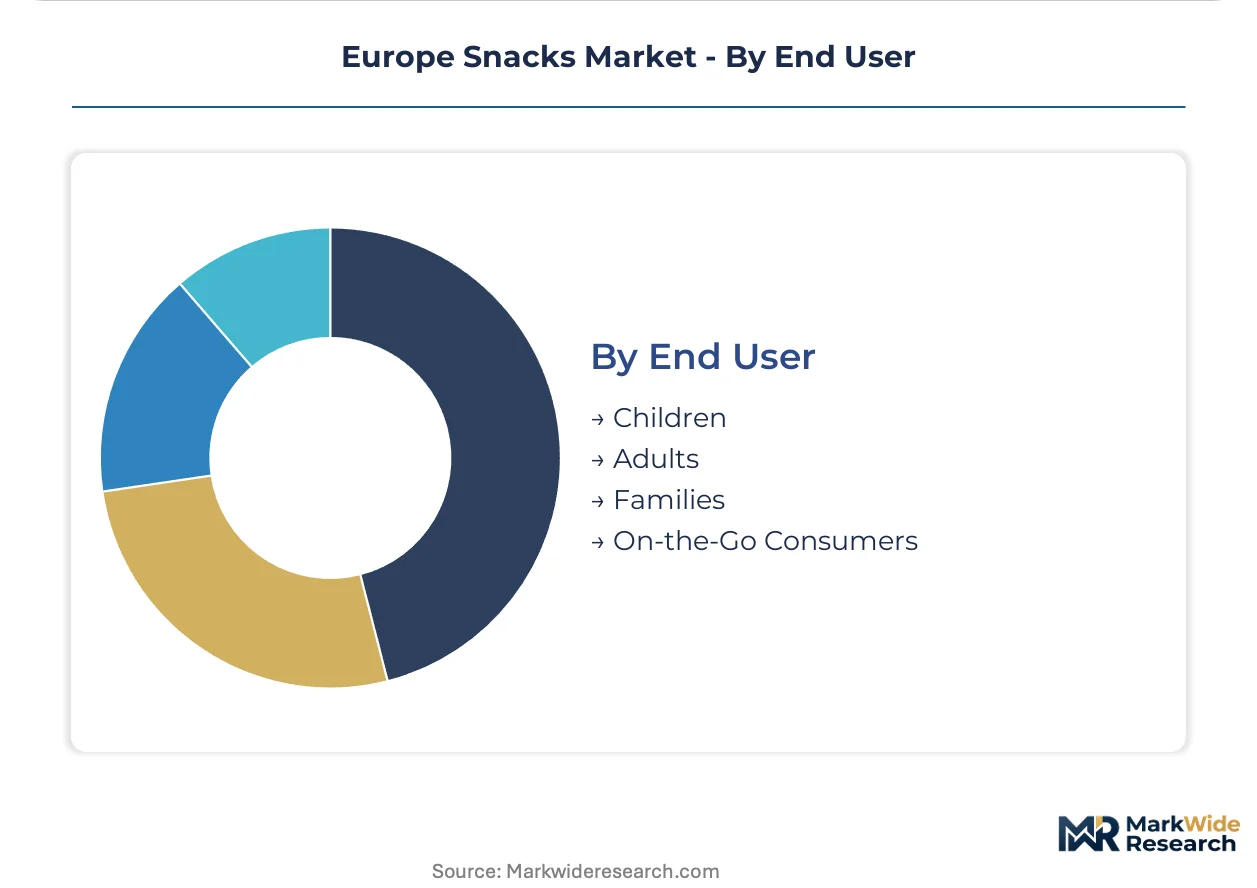
End User:
Occasion fragmentation is bifurcating channel strategy, with family pantry stocking declining against individual impulse purchase growth.
- On-the-Go Consumers:Individual portion seekers prioritizing portability and immediate consumption. German rail and metro network expansion creates the densest impulse touchpoint concentration.
- Adults:Health-conscious buyers seeking protein-forward or reduced-sodium options. Netherlands and Belgium workplace micro-markets concentrate this demand.
- Families:Multi-serve purchasers for household pantry stocking. French hypermarket channels retain this segment despite share erosion.
- Children:Portion-controlled formats with regulatory-constrained formulation spaces. German BVL additive restrictions create compliance complexity.
Families retain the broadest revenue base while on-the-go consumers climb the fastest as transit infrastructure expands.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Rhine-Alpine freight corridor underwrites Germany's dominance in European snack distribution, connecting Rotterdam's port to Milan's manufacturing belt with high-frequency rail service that compresses lead times for ambient goods.
Germany
Urban snacking frequency and premium private-label penetration outpace neighboring markets, driven by dense transit hub networks in Berlin, Munich, and Hamburg. The Bundesamt für Verbraucherschutz und Lebensmittelsicherheit enforces stricter sodium and trans-fat ceilings than southern EU counterparts, forcing dual formulation runs. The Cologne-Düsseldorf corridor concentrates savory snack manufacturing capacity where stealth sodium reduction programs absorb R&D investment.
France
Evening consumption occasions and seasonal gifting demand anchor premium chocolate and nut segments, with Parisian convenience retail expanding fastest. ANSES contributes additive safety assessments that filter into EU-wide EFSA opinions, elevating compliance preparation costs. The Lyon-Grenoble cluster hosts workplace micro-market innovation where unattended retail stations displace conventional vending.
Netherlands
Air-popped popcorn and lightly seasoned variants gain share fastest as workplace micro-market penetration accelerates in Amsterdam and Rotterdam. The national food safety authority aligns with EFSA nutrient profiling criteria ahead of mandatory implementation. The Randstad logistics hub enables just-in-time replenishment of transit channel impulse formats across Benelux.
Spain
Spicy flavor profiles capture the steepest growth as regional taste preferences shift toward bolder sensory experiences in Madrid and Barcelona. Spanish implementation of EU Green Deal packaging mandates runs ahead of southern counterparts, accelerating mono-material pouch adoption. The Valencia corridor concentrates extrusion technology investment for heat-forward innovation.
Poland
Modern trade expansion and rising disposable incomes offer first-mover advantages for premium private-label positioning in Warsaw and Kraków. Pending EU-wide harmonized front-of-pack labeling creates inventory complexity before national divergence hardens. The Łódź manufacturing belt attracts capacity expansion targeting Eastern European price-sensitive tiers.
Europe Snacks Market Competitive Landscape
Concentration sits with diversified multinational food conglomerates that leverage pan-European distribution infrastructure and direct-store-delivery networks. The vendor base spans three tiers: scale-driven mass-market players with impulse channel dominance, premium-positioned chocolate and nut specialists, and regional savory manufacturers with deep local formulation expertise. Strategic moves center on reformulation service partnerships with ingredient suppliers and packaging line reconfiguration for EU Green Deal compliance.
Among diversified packaged food conglomerates, Mars Inc., Nestlé S.A., and Unilever PLC exemplify the scale archetype that dominates mass-market shelf space and vending channel access. These entities occupy positions defined by cross-category portfolio breadth and pan-European procurement leverage rather than snack-specific specialization. Regional savory specialists such as Intersnack Group GmbH anchor competitive positioning through manufacturing density in German-speaking markets and private-label contract relationships with modern trade retailers.
| Leading Market Players |
|---|
| Mars Inc. |
| Intersnack Group GmbH |
| PepsiCo Inc. |
| Unilever PLC |
| Ferrero SpA |
| Nestlé S.A. |
| General Mills Inc. |
| Orkla ASA |
| Mondelez International Inc. |
| Others |
Supply & Pricing Matrix
Sunflower oil displacement by rapeseed and palm oil alternatives is redrawing ingredient sourcing maps from Black Sea origins toward Benelux and Southeast Asian supply nodes while compressing margin structures for fried snack categories.
Pricing Analysis
Volume-discount tiering structures separate premium pulse-based extruded snacks from standard potato and corn bases from economy private-label tiers. Price differentiation hinges on sodium reduction certification under BVL thresholds and clean-label positioning. Cost compression in the economy tier is intensifying as sunflower oil volatility feeds through to contract renegotiations. Family pantry buyers exhibit highest price sensitivity while on-the-go transit channel purchasers accept portability premiums.
Supply Chain Analysis
Port congestion at Rotterdam and Hamburg is elevating inbound logistics costs for edible oils and specialty starches sourced from Black Sea and Asian trade lanes. Manufacturing concentrates in Germany, Poland, and the Netherlands where extrusion and packaging infrastructure clusters. Raw material procurement draws from Ukrainian sunflower, French wheat, and Southeast Asian palm oil suppliers. Single-source vulnerability in sunflower oil creates formulation disruption risk. Distribution runs through direct-store-delivery networks for impulse channels and palletized shipment for modern trade retail.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Reformulation service partnerships represent a service-attach opportunity expanding faster than base ingredient supply as manufacturers seek external sodium reduction and clean-label expertise.
For Market Incumbents: Consolidate manufacturing footprint in the Cologne-Düsseldorf corridor to capture scale economies in stealth sodium reduction programs. Deepen backward integration into pulse flour milling to secure fava bean and lentil supply chains against price volatility. Channel control through direct-store-delivery infrastructure defends impulse placement against private-label encroachment.
For New Entrants and Emerging Players: Organic and EU Green Deal packaging certification fast-tracks unlock shelf space in Dutch and German workplace micro-markets where sustainability credentials command placement. Poland and Romania modern trade expansion offers the most penetrable geography for premium private-label positioning. A co-manufacturing partnership with established extrusion operators accelerates speed-to-shelf without capital-intensive line investment.
For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors reformulation-capable mid-cap specialists with established retailer relationships. Long-term viability across the next decade rests on regulatory compliance speed rather than scale alone. Acquisition targets should demonstrate proven EFSA nutrient profiling navigation and mono-material packaging line conversion. The signal to watch is BVL enforcement stringency spreading to southern EU member states, which would force system-wide reformulation demand. Outcomes outside this envelope would require model recalibration.
| Strategic Initiative | Industry Significance |
|---|---|
| Reformulation Partnership | External sodium reduction expertise accelerates BVL compliance for savory market leaders. |
| Mono-Material Packaging Conversion | EU Green Deal substrate mandates force equipment reconfiguration with extended payback periods. |
| Pulse-Based Extrusion Scale-Up | Fava bean and lentil flour capacity captures protein-forward positioning in German health segments. |
| Workplace Micro-Market Expansion | Unattended retail stations in France and Belgium displace conventional vending operator margins. |
| Direct-to-Vending Channel Innovation | Smart vending with cashless payment opens unmanned retail in German transit infrastructure. |
Research Methodology
Cross-validation between primary interviews with category buyers at German and French retailers, formulation directors at savory snack manufacturers, and packaging procurement leads anchors the qualitative findings against secondary validation. Secondary sources include EFSA nutrient profiling opinions, BVL enforcement bulletins, EU Green Deal packaging directive texts, and Nielsen retail audit data for snack category velocity. Bottom-up demand modeling and top-down market sizing triangulate volume estimates.
Sensitivity analysis across sunflower oil price scenarios, BVL sodium ceiling enforcement timelines, and EU front-of-pack labeling implementation dates stress-tests projection stability. Segmentation dimensions include product type, flavor profile, packaging substrate, and end-user occasion across the modeling period. CAGRs derive from historical trajectory analysis adjusted for regulatory inflection points. Industry-specific forecast inputs incorporate extrusion technology adoption curves and workplace micro-market penetration rates by metropolitan area.
Decision-makers should treat outputs as directional under assumptions of continued EFSA nutrient profiling tightening and EU Green Deal packaging mandate adherence; material deviation in regulatory timelines or agricultural input costs would warrant model refresh. Specific risk factors include Black Sea supply disruption extension, German BVL enforcement spreading to neighboring authorities, and fresh prepared food substitution acceleration in convenience retail. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Snacks
North America Savory Snacks Market
Snacks
Candy and Snack Food Pouches Market
Snacks
Seafood Snacks Market
Snacks
Low Calorie Snacks Market
Snacks
Salty Puffed Snacks Market
Snacks
India Energy Bar Market
Snacks
Fried Potato Chips Market
Snacks
Flexible Plastic Snack Food Packaging Market
Snacks
Italy Snack Bar Market
Snacks
Brazil Snack Bar Market
Snacks
Europe Popcorn Market
Snacks
Dried Fruit Snacks Market
Snacks
Seaweed Snacks Market
Snacks
Global Vegetable Chips Market
Snacks
Middle East and North Africa Extruded Snack Food Market
Snacks
Global Protein Snack Market