
 Asia Pacific Tortilla Market | 2026-2036
Asia Pacific Tortilla Market Size, Share, and Industry Trends Forecast 2026-2036
Asia Pacific Tortilla Market Analysis
Recurring delivery and replenishment subscription models for foodservice operators is rebalancing how tortilla volumes move through the Asia Pacific channel. Gruma SAB de CV leverages its nixtamalization expertise to anchor supply relationships with large-scale restaurant chains across the region. PepsiCo Inc competes through its extensive salty-snack distribution infrastructure, which extends into tortilla chip and wrap adjacencies. Mission Foods specializes in refrigerated and frozen tortilla formats that sustain longer shelf-life claims in humid climates.
Tortillas in the Asia Pacific context are thin, circular flatbreads produced from nixtamalized corn masa or wheat flour dough, pressed and baked on hot surfaces to achieve flexible texture suitable for wrapping, folding, or grilling applications. Corn tortillas retain dominant volume share due to lower input costs and established processing knowledge, while whole wheat tortillas are gaining traction among health-positioned retail lines where fiber content and clean-label claims differentiate shelf placement. Flour tortillas occupy the mature core of foodservice procurement, though margin pools are shifting toward flavored and specialty grain variants as operators seek menu distinction.
FSSAI in India enforces additive limits and packaging standards for processed flatbreads, while Australia's FSANZ governs nutritional labeling and allergen declarations that directly affect import eligibility and retail placement. Japan's Ministry of Health, Labour and Welfare maintains strict quarantine and ingredient verification protocols for corn-derived food imports, shaping supplier documentation burdens. Stakeholders must monitor evolving shelf-life labeling harmonization across ASEAN member states, where divergent national standards currently fragment cross-border product registration.
Market Dynamics
Quick-service restaurant chains across Southeast Asia are consolidating procurement volumes through centralized distribution agreements, compressing supplier margins while demanding extended shelf-life specifications and regional logistics coverage from tortilla manufacturers.
Growth Catalysts
- Urban foodservice corridor expansion:Melbourne and Sydney operators are deepening Mexican cuisine penetration through dedicated kitchen formats that standardize tortilla-based menu architecture across multiple locations.
- FSSAI labeling mandates:India's tightened ingredient disclosure requirements for packaged flatbreads are accelerating clean-label reformulation investments among domestic processors seeking retail shelf placement.
- Nixtamalization process refinement:Automated lime-cooking and stone-grinding systems are reducing per-unit labor inputs while preserving the alkaline flavor profile that distinguishes authentic corn tortilla production.
Market Restraints
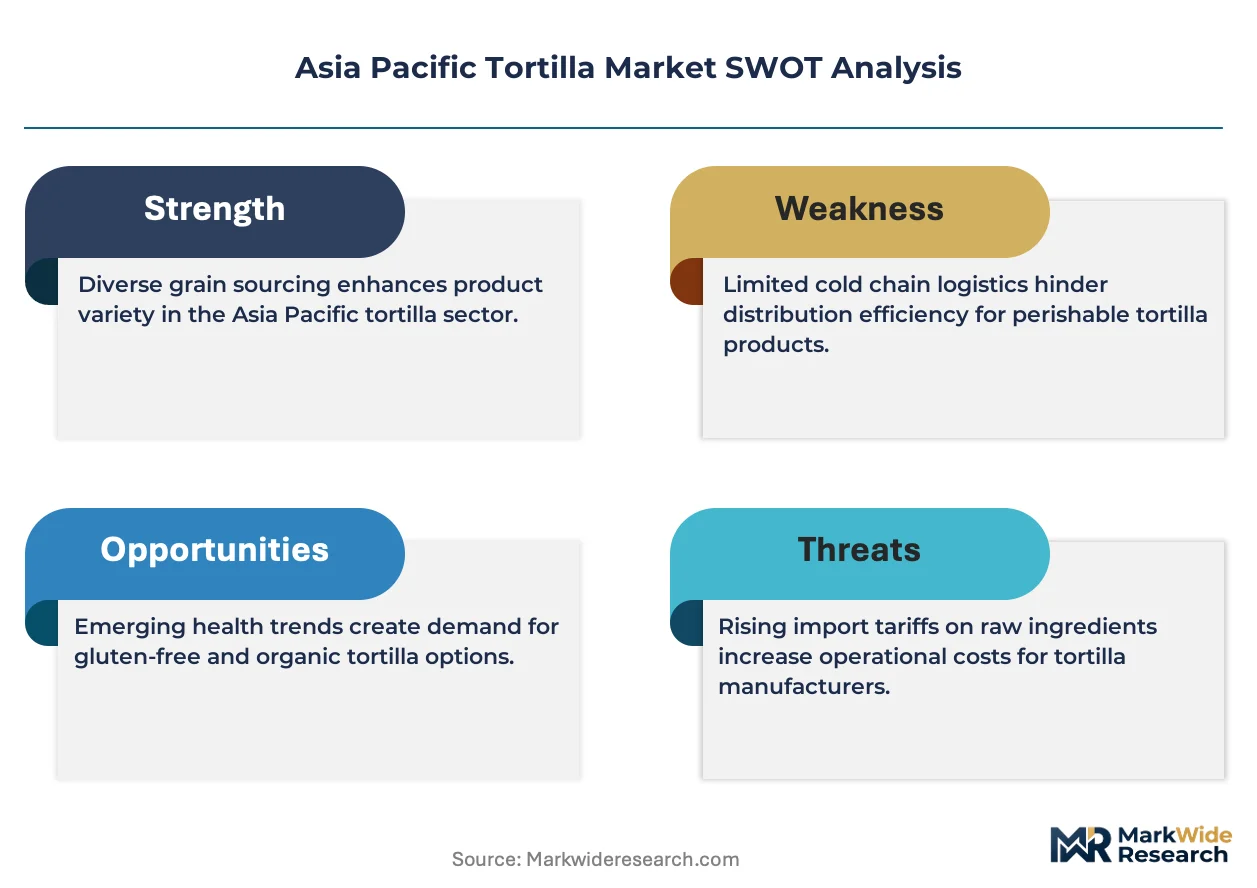
- Corn input cost volatility:Weather-driven fluctuations in Australian and Indian maize harvests create margin compression for masa-dependent producers lacking forward-contract coverage.
- Import quarantine complexity:Japan's Ministry of Health, Labour and Welfare maintains strict verification protocols for corn-derived food imports that extend documentation timelines and increase compliance overhead for foreign suppliers.
- Fresh bread substitution:Traditional flatbreads including naan, roti, and paratha retain dominant household consumption share in South Asian markets where tortilla familiarity remains limited.
Strategic Opportunities
- Vietnamese foodservice underpenetration:Ho Chi Minh City and Hanoi present white-space expansion potential for tortilla-based fast-casual formats targeting younger urban demographics with limited incumbent competition.
- Subscription replenishment models:Recurring delivery contracts for restaurant operators are rebalancing volume flows through direct manufacturer relationships that bypass traditional wholesale intermediaries.
- ASEAN shelf-life harmonization:Emerging alignment discussions across member states could reduce cross-border product registration fragmentation and streamline regional supply chain configuration.
Industry Challenges
- Humidity-controlled distribution infrastructure:Maintaining refrigerated and frozen tortilla integrity across tropical Southeast Asian logistics networks requires capital-intensive cold-chain investments that strain mid-scale processor balance sheets.
- Multi-jurisdictional compliance staffing:Navigating simultaneous FSSAI, FSANZ, and Japan MHLW documentation requirements demands specialized regulatory affairs personnel that smaller manufacturers struggle to retain.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia Pacific Tortilla Market |
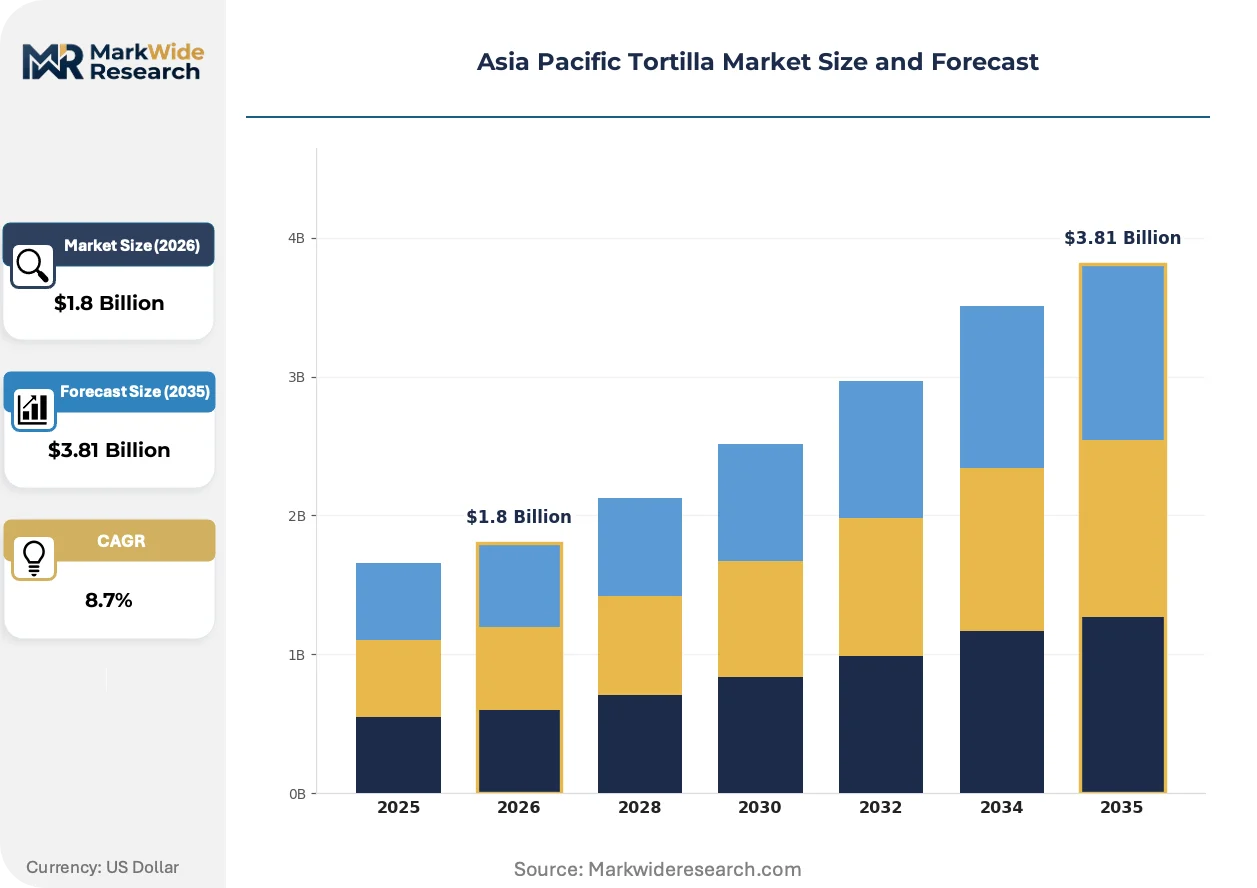
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Corn Tortillas, Flour Tortillas, Whole Wheat Tortillas, Flavored Tortillas End User: Restaurants, Food Service, Retail, Bakery Packaging Type: Plastic Bags, Paper Bags, Pouches, Boxes Distribution Channel: Supermarkets, Online Retail, Convenience Stores, Wholesale |
| Companies Covered | PepsiCo Inc, Azteca Foods, Gruma SAB de CV, Mission Foods, La Tortilla Factory, Grupo Bimbo, Ole Mexican Foods, Catallia Mexican Foods, General Mills Inc, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia Pacific Tortilla Market Emerging Trajectories
Processing technology and procurement architecture are converging to reshape how tortilla volumes move through Asia Pacific channels, with implications for shelf-life extension, distribution reach, and buyer-supplier contracting structures.
Modified atmosphere packaging systems with high-barrier film laminates are extending ambient tortilla shelf life from days to weeks without chemical preservatives. Quick-service chains in Australia's eastern seaboard are adopting these formats at scale for centralized kitchen commissaries. This technology is decentralizing production geography by enabling longer-haul distribution from fewer manufacturing nodes.
FSANZ nutritional labeling reforms are tightening allergen declaration requirements for wheat-based tortillas entering Australian retail. Importers must now verify gluten content thresholds and cross-contamination protocols through accredited laboratory testing. Frozen and refrigerated tortilla segments face the steepest compliance cost escalation as they target health-positioned supermarket placements.
Foodservice operators are consolidating purchase volumes through group procurement platforms that aggregate demand across multiple restaurant brands. These digital intermediaries are displacing traditional broadline distributors in Singapore and Bangkok metropolitan markets. The shift is most visible among mid-scale Mexican-themed chains seeking price transparency and direct manufacturer relationships.
Asia Pacific Tortilla Market Segmentation
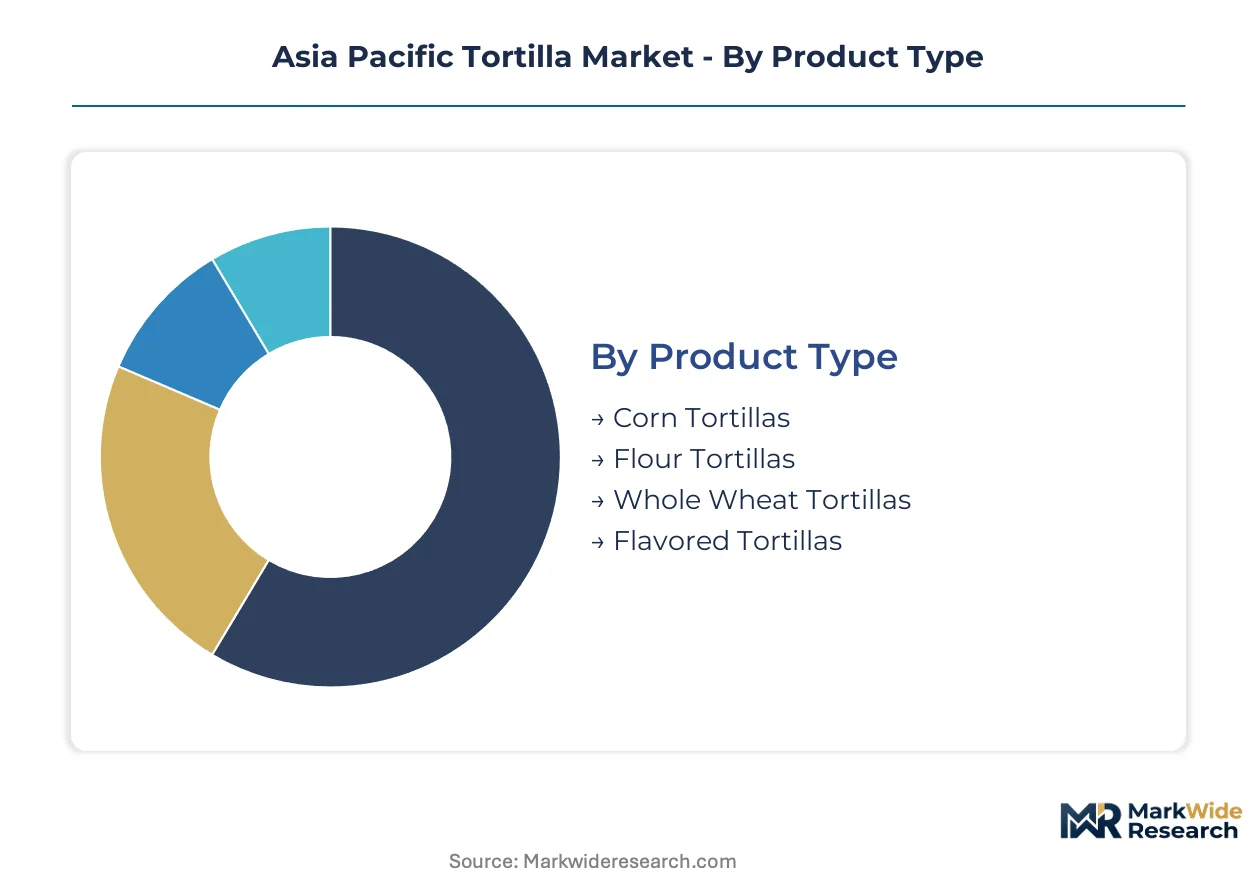
Segmentation in the Asia Pacific tortilla market reveals how capital deployment, regulatory exposure, and channel access fragment opportunity across distinct product formats and buyer configurations. Understanding these divisions allows suppliers to align manufacturing investments with the specific shelf-life, labeling, and logistics requirements of each segment.
Product Type:
Capital intensity varies sharply across production technologies, with nixtamalization infrastructure demanding the heaviest upfront equipment outlays while ambient-capable flour lines offer lower barriers to entry.
- Corn Tortillas:Nixtamalized masa production requires lime-cooking vats, stone-grinding mills, and humidity-controlled conditioning rooms. Australian quick-service chains in Melbourne and Sydney source these for authentic menu positioning, though Japan's MHLW import verification protocols constrain foreign supplier participation.
- Flour Tortillas:Wheat-based dough sheeting and hot-press baking lines achieve faster throughput with simpler equipment. India's FSSAI mandates on additive limits and packaging standards shape reformulation priorities for domestic processors seeking retail placement.
- Whole Wheat Tortillas:Fiber-forward positioning targets health-conscious Australian supermarket shoppers under FSANZ nutritional labeling frameworks.
- Flavored Tortillas:Spinach, tomato, and chipotle variants command menu differentiation premiums in Southeast Asian foodservice corridors.
Flour tortillas absorb the bulk of installed capacity; whole wheat tortillas are expanding most quickly.
End User:
Buyer concentration patterns determine contract structures, with centralized procurement platforms aggregating volumes differently across restaurant groups than fragmented retail channels.
- Restaurants:Quick-service chains across Southeast Asia consolidate tortilla procurement through group purchasing platforms that displace traditional broadline distributors. Singapore and Bangkok operators leverage these digital intermediaries for price transparency and direct manufacturer relationships.
- Food Service:Centralized kitchen commissaries in Australia's eastern seaboard adopt modified atmosphere packaging formats at scale, enabling longer-haul distribution from fewer manufacturing nodes.
- Retail:Supermarket placement requires navigating FSSAI disclosure mandates in India and FSANZ allergen declarations in Australia.
- Bakery:In-store tortilla production remains limited to premium positioning in urban Australian food halls.
Food service channels dominate volume flows; restaurant procurement through digital platforms is climbing the fastest.
Packaging Type:
Material selection directly governs shelf-life extension capabilities and compliance with multi-jurisdictional labeling mandates across the region's fragmented regulatory landscape.
- Plastic Bags:High-barrier film laminates with modified atmosphere systems extend ambient shelf life from days to weeks without chemical preservatives, supporting centralized production models.
- Paper Bags:Breathable formats suit high-turnover foodservice operations where rapid consumption cycles reduce spoilage risk.
- Pouches:Stand-up configurations with resealable closures target retail consumers in Australian and Indian supermarkets.
- Boxes:Bulk corrugated formats serve wholesale distribution into restaurant commissaries and bakery operations.
Plastic bag formats capture the majority of packaging investment; pouch configurations are gaining share fastest in premium retail lines.
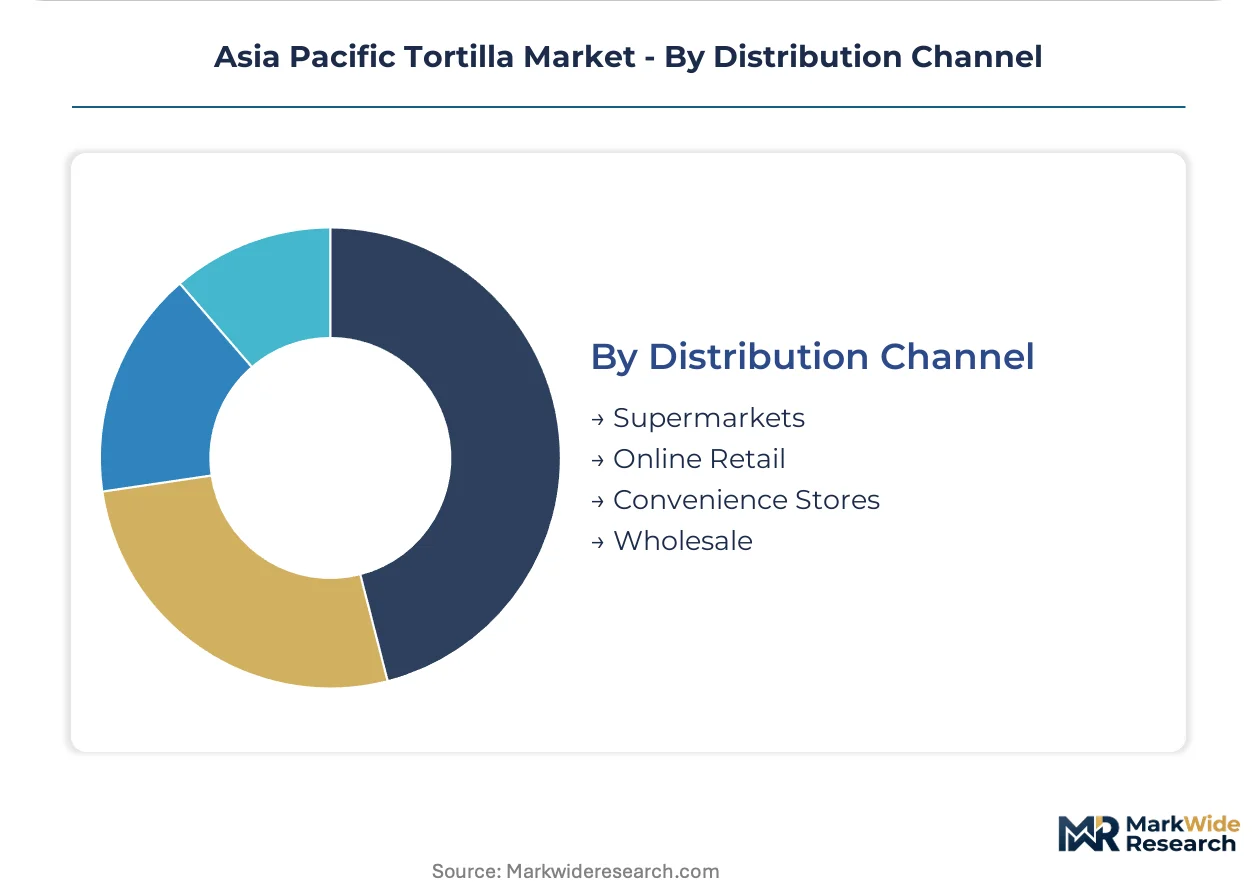
Distribution Channel:
Channel selection determines geographic reach and regulatory touchpoints, with each pathway imposing distinct documentation burdens for cross-border product registration.
- Supermarkets:FSANZ nutritional labeling reforms in Australia tighten allergen declaration requirements, with frozen and refrigerated segments facing steepest compliance cost escalation for health-positioned placements.
- Online Retail:Direct-to-consumer platforms bypass traditional wholesale intermediaries, though cold-chain integrity requirements strain logistics configurations in tropical Southeast Asian climates.
- Convenience Stores:Ambient-stable formats with extended shelf-life claims dominate this channel's limited refrigeration infrastructure.
- Wholesale:Traditional broadline distributors retain foothold in smaller metropolitan markets where digital procurement platforms have not yet penetrated.
Supermarket channels anchor established volume; online retail is expanding most quickly as subscription replenishment models proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production capacity concentrates in Australia and India, while consumption growth accelerates across Southeast Asian urban corridors. Domestic processors in India and Australia supply regional foodservice chains, though import dependency persists for specialized corn masa formats in Japan.
Australia
Melbourne and Sydney foodservice corridors drive demand for authentic corn tortillas in dedicated Mexican kitchen formats. FSANZ nutritional labeling reforms tighten allergen declaration requirements for wheat-based imports. Sydney's eastern seaboard commissaries adopt modified atmosphere packaging for centralized production models serving multi-location chains.
India
Domestic processors reformulate toward clean-label positioning to secure retail placement under FSSAI disclosure mandates. The regulator's additive limits and packaging standards shape ingredient sourcing decisions for packaged flatbreads. Maharashtra and Gujarat house emerging production clusters targeting foodservice procurement in Mumbai and Ahmedabad metropolitan markets.
Japan
Import-dependent operators source corn-derived tortillas through verified suppliers meeting MHLW quarantine protocols. The Ministry of Health, Labour and Welfare extends documentation timelines for foreign masa processors. Tokyo and Osaka foodservice operators maintain limited but stable procurement relationships with compliant regional exporters.
Vietnam
Ho Chi Minh City and Hanoi present underpenetrated expansion potential for fast-casual tortilla formats targeting younger demographics. National food safety frameworks govern import registration without the fragmentation seen in multi-jurisdictional ASEAN markets. Urban food courts in District 1 and District 7 host early-format experimentation with minimal incumbent competition.
Thailand
Bangkok quick-service chains consolidate procurement through digital group purchasing platforms displacing traditional distributors. The country's food and drug administration maintains additive standards for processed grain products. Central kitchen commissaries in the Bangkok metropolitan area standardize tortilla specifications across expanding regional chain footprints.
Asia Pacific Tortilla Market Vendor Landscape
Top-tier vendors anchor supply relationships with large-scale restaurant chains, while mid-scale regional processors compete on reformulation agility and local regulatory navigation. Market structure tilts toward consolidation among nixtamalization specialists and diversified snack-food conglomerates with distribution infrastructure. Strategic archetypes include masa-process technology holders, refrigerated-format specialists, and salty-snack distributors extending into wrap adjacencies. Dominant competitive moves encompass centralized procurement platform partnerships and humidity-controlled cold-chain capacity expansion.
Within the nixtamalization-specialist tier, Gruma SAB de CV and Mission Foods exemplify equipment-heavy production archetypes leveraging lime-cooking expertise. PepsiCo Inc occupies a position representing snack-food distribution extension into tortilla chip and wrap categories. These three entities anchor distinct competitive vectors: authentic process credibility, refrigerated-format shelf-life leadership, and salty-snack channel leverage respectively.
| Leading Market Players |
|---|
| PepsiCo Inc |
| Azteca Foods |
| Gruma SAB de CV |
| Mission Foods |
| La Tortilla Factory |
| Grupo Bimbo |
| Ole Mexican Foods |
| Catallia Mexican Foods |
| General Mills Inc |
| Others |
Supply Flow & Price Mechanics
Nixtamalization specialists concentrated in Australia's eastern seaboard and India's western production corridors create labor-cost differentials that widen spreads between premium authentic-masa tiers and commodity flour alternatives. These workforce pools anchor pricing power for equipment-heavy processors while compressing margins for standardized wheat-based competitors.
Pricing Analysis
Margin tightening in foodservice procurement reflects quick-service chains consolidating volumes through digital group purchasing platforms. Three-tier pricing structure across premium, standard, and economy levels separates nixtamalized corn formats with extended shelf-life claims from basic flour tortillas and private-label imports. Price differentiation hinges on FSANZ allergen certification tiers and humidity-controlled logistics coverage. Smaller metropolitan operators show highest price sensitivity; centralized commissaries in Melbourne and Sydney absorb premium positioning costs for menu authenticity.
Supply Chain Analysis
FSANZ, FSSAI, and Japan MHLW certification requirements gate supplier participation across the region's fragmented regulatory landscape. Production concentrates in Australia, India, and Thailand, with corn masa processing anchored in Australian urban corridors and wheat-based lines scaling in Maharashtra and Gujarat. Raw material flows draw from Australian and Indian maize harvests, Thai wheat imports, and specialty lime supplies for nixtamalization. Single-source vulnerability concentrates in humidity-sensitive distribution legs across tropical Southeast Asian logistics networks. Distribution runs through centralized commissaries serving multi-location chains, with subscription replenishment models displacing traditional wholesale intermediaries in Singapore and Bangkok.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Modified atmosphere packaging technology is displacing legacy ambient formats, enabling centralized production from fewer manufacturing nodes while extending shelf-life claims without chemical preservatives. This transition favors capital-intensive processors with cold-chain infrastructure over fragmented regional bakeries.
For Market Incumbents: Lock in group purchasing platform partnerships with quick-service chains before digital intermediaries consolidate buyer power further. Expand humidity-controlled distribution capacity into Ho Chi Minh City and Hanoi corridors to preempt new entrant positioning. Defend against fresh bread substitution in South Asian markets by emphasizing wrap-format convenience in foodservice channels.
For New Entrants and Emerging Players: Vietnamese fast-casual operators targeting younger urban demographics present the most penetrable white-space opportunity, with minimal incumbent competition in District 1 and District 7 food courts. Pursue clean-label reformulation investments to secure retail placement under tightening FSSAI disclosure mandates. Lead with direct manufacturer relationships bypassing traditional wholesale markups.
For Investors and Strategic Acquirers: Re-rating potential sits with nixtamalization specialists possessing MHLW-compliant documentation given Japan's import verification bottlenecks. Long-term viability favors equipment-heavy producers with backward integration into lime-cooking and stone-grinding systems over commodity flour processors. Watch for ASEAN shelf-life harmonization alignment as the inflection signal for regional supply chain consolidation plays.
| Strategic Initiative | Industry Significance |
|---|---|
| Cold-Chain Capacity Expansion | Humidity-controlled logistics networks preserve tortilla integrity across tropical Southeast Asian distribution legs. |
| Modified Atmosphere Packaging Adoption | High-barrier film laminates extend ambient shelf life from days to weeks without chemical preservatives. |
| Regulatory Certification Investment | FSSAI, FSANZ, and MHLW compliance documentation gates import eligibility and retail placement across multi-jurisdictional markets. |
| Subscription Replenishment Model Launch | Recurring delivery contracts rebalancing volume flows through direct manufacturer relationships bypass wholesale intermediaries. |
| Backward Integration into Nixtamalization | In-house lime-cooking and stone-grinding capacity preserves authentic flavor profiles while reducing per-unit labor inputs. |
Methodological Framework
Trade databases, food safety regulator filings, and quick-service chain procurement disclosures formed the secondary backbone for volume and value estimation. Primary interviews with tortilla production plant managers, foodservice procurement leads at restaurant chains, cold-chain logistics operators, and FSSAI regulatory affairs specialists validated segment assumptions. Bottom-up triangulation across manufacturer capacity assessments and top-down reconciliation against channel flow data anchored the analytical framework.
Bottom-up modeling built product-type, end-user, and distribution channel segments independently before cross-referencing against regional consumption patterns. The projection horizon spans corn versus flour format splits, refrigerated versus ambient packaging configurations, and digital platform versus traditional wholesale channel shares. CAGRs derived from segment-level growth drivers including urban foodservice corridor expansion, clean-label reformulation investments, and subscription replenishment adoption curves across the analysis window.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to corn input cost volatility and ASEAN regulatory harmonization progress. Model outputs reflect assumptions on quick-service chain expansion rates, cold-chain infrastructure investment cycles, and import quarantine protocol stability. A model refresh is warranted upon material change in FSSAI or MHLW disclosure requirements.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Snacks
Europe Snack Pellets Market
Snacks
Forti Flakes Market
Snacks
Trail Mix Market
Snacks
South Korea Snack Bar Market
Snacks
UAE Cereal Bar Market
Snacks
South America Energy Bar Market
Snacks
Snack Food Packaging Market
Snacks
Europe Energy Bar Market
Snacks
Allergy-Free Snacks Market
Snacks
Seaweed Snacks Market
Snacks
Seafood Snacks Market
Snacks
Pretzels (Savory Snacks) Market
Snacks
Organic Snack Food Market
Snacks
Protein Crisps Market
Snacks
Granola Market
Snacks
Germany Snack Bar Market