
 North America Bacon Market | 2026-2036
North America Bacon Market Size, Share, and Industry Trends Forecast 2026-2036
North America Bacon Market Analytics
Consolidation among quick-service restaurant chains is realigning procurement volumes across the North American bacon supply base. Tyson Foods Inc. leverages vertical integration from hog production through processing to secure volume commitments with national buyers. Hormel Foods Corporation anchors its position through specialized cured-meat expertise and direct-to-foodservice distribution networks. Smithfield Foods, Inc. dominates fresh and smoked bacon output through large-scale Midwest processing complexes.
North American bacon comprises pork belly sections cured with salt, nitrites, and seasonings, then smoked or air-dried to achieve specified moisture-to-protein ratios and shelf stability for commercial food preparation. Streaky bacon, distinguished by alternating fat and muscle layers, leads retail and foodservice volume due to its crisping performance and flavor release during cooking. Uncured processing methods, relying on natural nitrate sources such as celery powder, represent the fastest-expanding segment as operators respond to clean-label preferences. Supermarket distribution channels sustain the largest revenue pool, though online retail is capturing incremental share through subscription meat-box platforms.
USDA Food Safety and Inspection Service oversight mandates pathogen controls and labeling accuracy, while FDA sodium guidance pushes reformulation toward reduced-salt curing brines. Canadian Food Inspection Agency standards for imported pork products create compliance thresholds that filter smaller international suppliers from cross-border trade. Stakeholders must monitor evolving nitrite-labeling debates and state-level animal-welfare statutes that could reshape sourcing geography and curing chemistry.
Market Dynamics
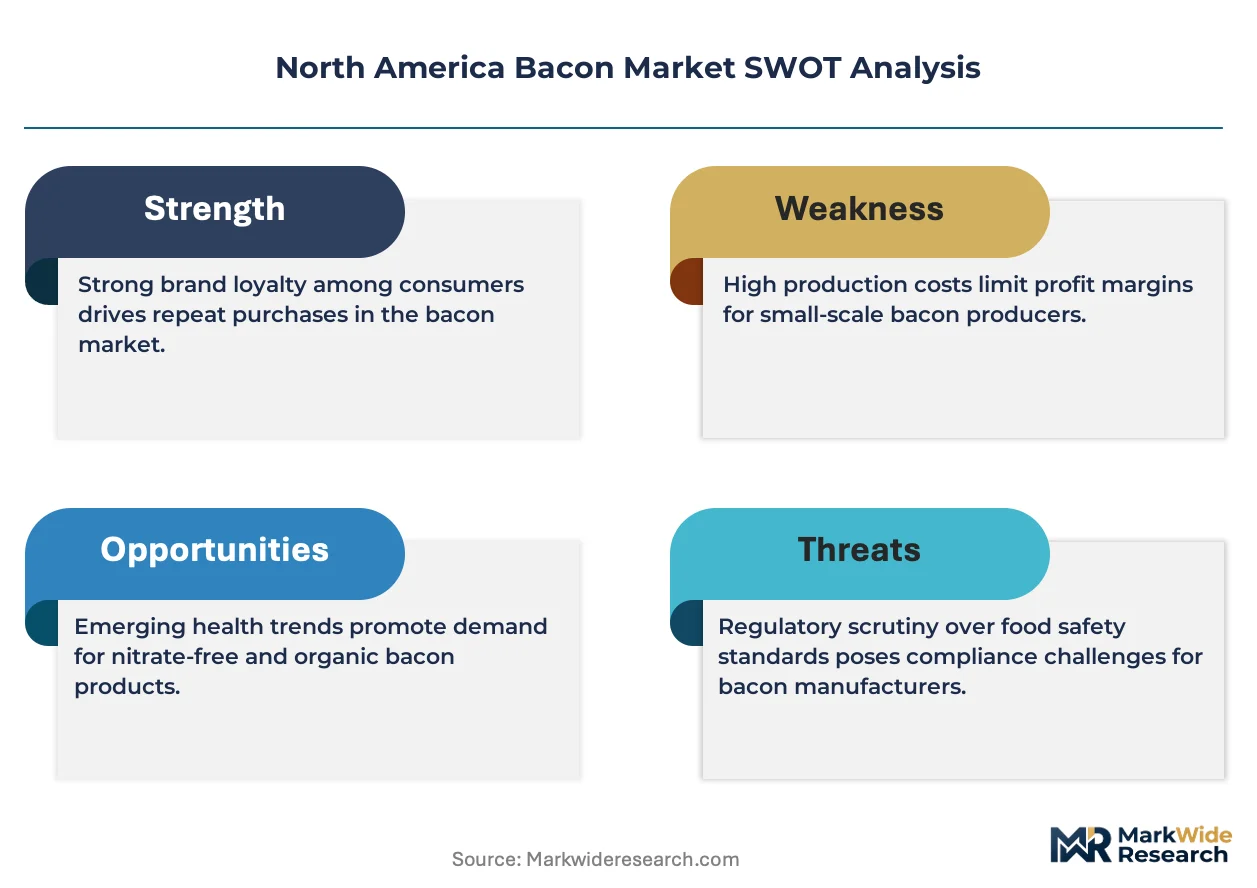
USDA sodium-reduction guidance and FDA labeling mandates are compressing formulation margins while quick-service restaurant procurement consolidation concentrates volume leverage among fewer national buyers.
Growth Catalysts
- Clean-label processing:Natural nitrate sources from celery powder and sea salt are displacing synthetic nitrites in premium product lines. Foodservice operators across Ontario and the American Midwest are reformulating menus to capture health-conscious diners.
- Quick-service restaurant expansion:Breakfast-all-day platforms at major chains are embedding bacon as a cross-daypart protein anchor. This operational model is standardizing bacon specifications across franchise networks.
- FSMA modernization:The FDA Food Safety Modernization Act preventive controls framework is accelerating pathogen-reduction investments. Processing facilities are adopting environmental monitoring systems to meet supply-chain verification requirements.
Market Restraints
- Feed grain cost volatility:Corn and soybean price swings in the American Midwest directly transmit to hog production economics. Margins compress when feed costs spike without corresponding protein price recovery.
- Midwest processing concentration:Iowa, Minnesota, and Illinois host disproportionate slaughter and curing capacity. Weather disruptions or labor shortages at these nodes cascade through national supply.
- Plant-based substitution:Pea-protein and mycelium bacon analogs are capturing trial among flexitarian consumers. Retail shelf space allocation is tightening for traditional pork products in coastal urban markets.
Strategic Opportunities
- Subscription meat-box channels:Direct-to-consumer platforms are bypassing traditional retail markups. Artisanal smokehouses in Vermont and Quebec are building recurring revenue through curated monthly shipments.
- Canadian provincial expansion:Alberta and British Columbia foodservice markets remain underpenetrated relative to Ontario. Regional distributors are seeking exclusive supply partnerships with USDA-inspected processors.
- Carbon-labeling convergence:Life-cycle assessment tools and blockchain traceability are merging to verify production claims. Early adopters are positioning for anticipated federal procurement preferences.
Industry Challenges
- Cured-meat expertise attrition:Master curers and smokehouse operators are aging out of the workforce without sufficient apprenticeship pipelines. Knowledge transfer gaps threaten consistency in small-batch premium segments.
- Dual-jurisdiction compliance:Cross-border suppliers must simultaneously satisfy USDA FSIS and Canadian Food Inspection Agency protocols. Documentation burdens slow product launches and increase legal exposure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Bacon Market |
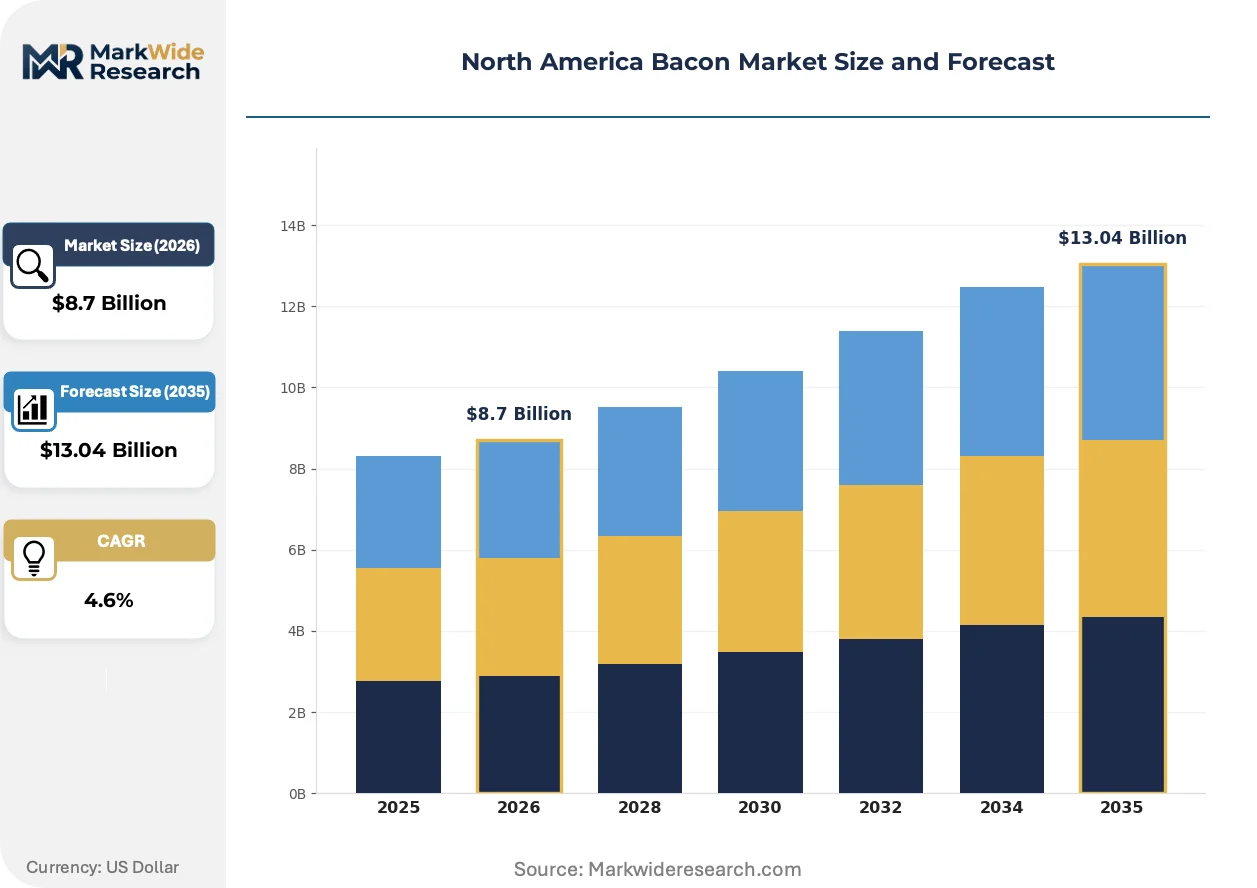
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $13.04 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Streaky, Back, Lardons, Pancetta Distribution Channel: Supermarkets, Online Retail, Convenience Stores, Wholesalers End User: Restaurants, Households, Food Service, Catering Processing Method: Smoked, Cured, Fresh, Uncured |
| Companies Covered | Hormel Foods Corporation, Tyson Foods Inc., The Kraft Heinz Company, Fresh Mark Inc., Sugar Creek Packing Co., Smithfield Foods, Inc., WH Group Limited, JBS SA, Seaboard Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Bacon Market Evolving Landscape
Processing automation and alternative-curing chemistry are compressing production timelines while reformulating shelf-stable products. These shifts are redrawing competitive boundaries between commodity and specialty tiers.
High-pressure processing technology is unifying pathogen elimination with clean-label positioning. Mid-scale processors in Wisconsin and Pennsylvania are retrofitting lines to extend refrigerated shelf life without synthetic preservatives. This capability is unifying foodservice safety requirements with retail premium pricing.
The FDA Guidance for Industry on Voluntary Sodium Reduction Targets is forcing reformulation across cured-meat categories. Manufacturers are experimenting with potassium chloride blends and flavor-enhancing yeast extracts to maintain sensory profiles. Quick-service chains are responding with phased sodium specifications in procurement contracts.
Foodservice distributors are consolidating purchasing through national account structures that bypass regional brokers. Broadline operators like Sysco and US Foods are imposing uniform specification sheets on bacon suppliers. This concentration is most visible in the American Southeast, where casino and stadium catering contracts demand volume consistency at price points that marginalize artisanal producers.
North America Bacon Market Segmentation
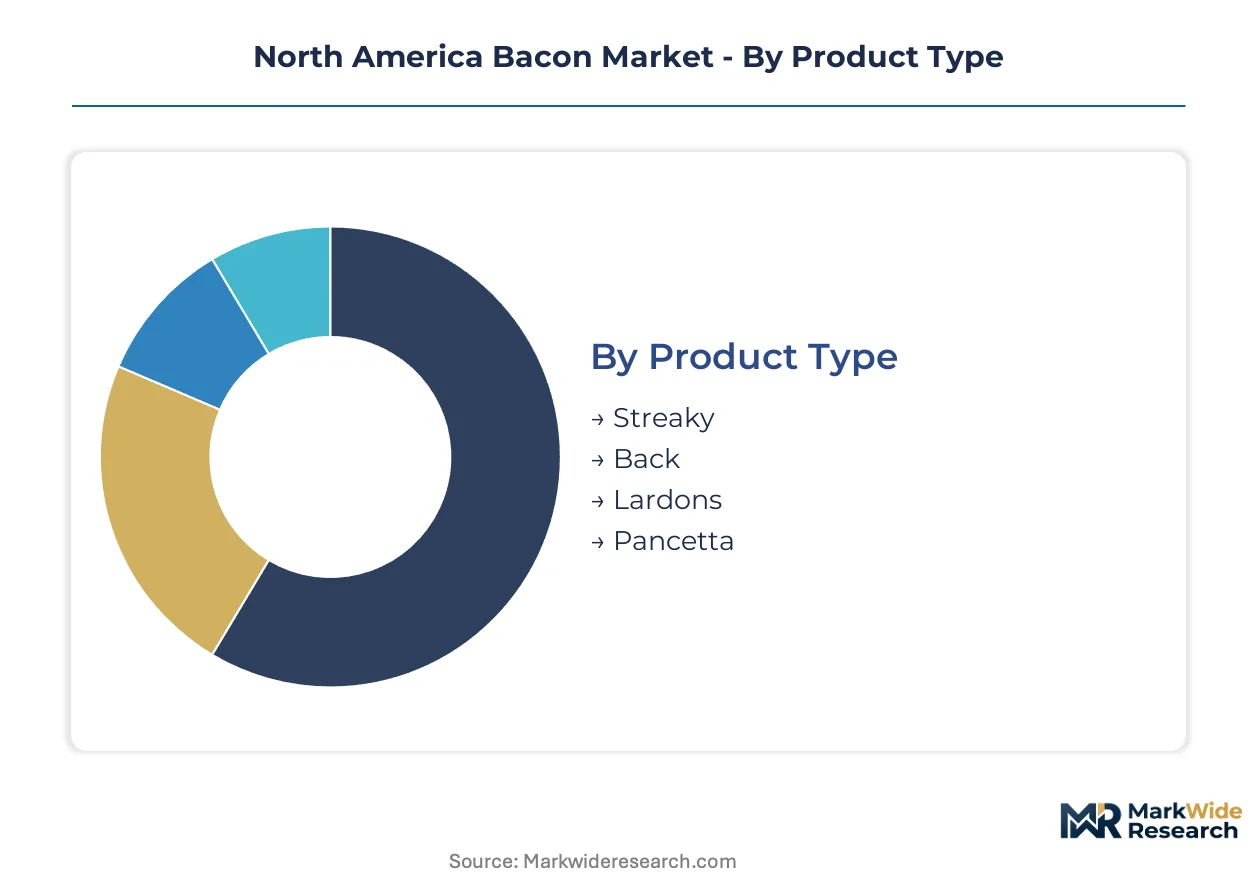
Bacon market segmentation reveals distinct compliance footprints across product categories. Each segment carries specific USDA FSIS inspection protocols, FDA labeling mandates, or Canadian Food Inspection Agency import requirements that reshape formulation economics and cross-border trade feasibility.
Product Type:
USDA moisture-to-protein ratio standards and CFIA cured-meat specifications apply unevenly across belly cuts, with streaky bacon facing the most stringent labeling scrutiny due to its retail dominance.
- Streaky:Alternating fat and muscle layers from pork belly deliver superior crisping performance. Quick-service restaurants across the American Midwest specify this cut for breakfast-all-day platforms, driving volume concentration despite sodium-reduction reformulation costs.
- Back:Leaner loin cuts with lower fat content appeal to health-conscious Canadian households in Ontario and British Columbia. CFIA nutritional labeling requirements here push manufacturers toward cleaner curing brines.
- Lardons:Diced bacon pieces for salad and bistro applications carry lower per-unit inspection burdens.
- Pancetta:Italian-style unsmoked belly requires specialized USDA import documentation for domestic processors.
Leading the category by volume: Streaky. Growing fastest: Back.
Distribution Channel:
Channel selection determines cold-chain investment intensity and margin capture, with direct-to-consumer platforms bypassing traditional retail markups entirely.
- Supermarkets:Dominant revenue pool sustaining refrigerated case placement fees and promotional slotting costs. Chains like Kroger and Loblaws impose uniform specification sheets that filter smaller USDA-inspected processors.
- Online Retail:Subscription meat-box platforms in Vermont and Quebec build recurring revenue through curated monthly shipments. FSMA preventive controls documentation becomes a competitive differentiator for these direct channels.
- Convenience Stores:Pre-cooked shelf-stable formats face compressed margins from grab-and-go pricing expectations.
- Wholesalers:Broadline operators consolidate purchasing through national account structures that marginalize regional smokehouses.
Supermarkets capture the largest revenue base. Online retail climbs fastest as subscription models mature.
End User:
User type dictates specification complexity, with foodservice operators imposing the most demanding pathogen-reduction and portion-consistency requirements.
- Restaurants:Independent operators and franchise networks across Alberta and the American Southeast standardize bacon specifications for cross-daypart menu integration. USDA FSIS HACCP compliance is non-negotiable for these high-volume buyers.
- Food Service:Casino and stadium catering contracts demand volume consistency at price points that strain artisanal producers. Sysco and US Foods broadline structures concentrate leverage among fewer national suppliers.
- Households:Retail consumers in coastal urban markets show rising trial of plant-based analogs, tightening traditional pork shelf space.
- Catering:Event-based demand fluctuates seasonally with wedding and corporate calendar cycles.
Restaurants anchor volume procurement. Food service exhibits the steepest expansion trajectory as institutional contracts consolidate.
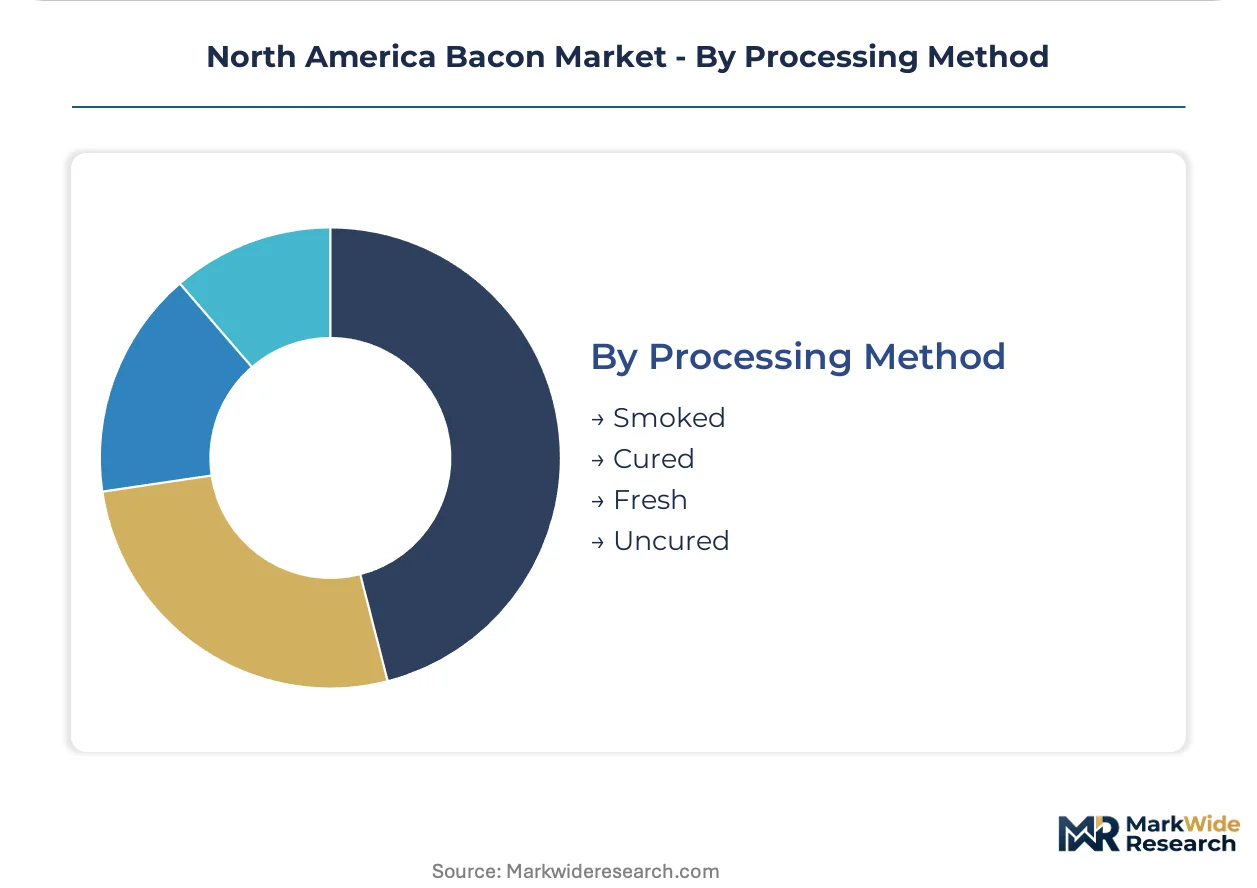
Processing Method:
Method selection determines nitrite-labeling exposure and shelf-life extension costs, with uncured formats commanding premium positioning despite higher input expenses.
- Uncured:Celery powder and natural nitrate sources displace synthetic nitrites for clean-label positioning. FDA sodium guidance accelerates adoption among health-conscious operators in Ontario and British Columbia.
- Smoked:Traditional hardwood smokehouse processing in Wisconsin and Pennsylvania commands artisanal premiums. Master curer expertise attrition threatens consistency in this segment.
- Cured:Conventional salt and nitrite brines face margin compression from potassium chloride reformulation experiments.
- Fresh:Unprocessed belly cuts for immediate use carry shortened logistics windows and spoilage risk.
Smoked methods retain volume leadership. Uncured processing gains share fastest on clean-label momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Quick-service restaurant procurement concentrates in the American Midwest and Ontario province, while underpenetrated markets in Alberta and British Columbia present expansion vectors for regional distributors seeking USDA-inspected supply partnerships.
United States
Breakfast-all-day platforms at national chains embed bacon as a cross-daypart protein anchor across the American Southeast and Midwest. USDA FSIS inspection protocols mandate pathogen controls and labeling accuracy that reshape formulation economics. Iowa, Minnesota, and Illinois host disproportionate slaughter and curing capacity where weather disruptions cascade through national supply.
Canada
Ontario province anchors foodservice demand through casino and stadium catering contracts demanding volume consistency. Canadian Food Inspection Agency standards for imported pork products filter smaller international suppliers from cross-border trade. Alberta and British Columbia markets remain underpenetrated relative to Ontario, with regional distributors seeking exclusive supply partnerships.
Mexico
Expanding quick-service restaurant networks in Mexico City Metro and Nuevo León drive incremental bacon procurement from US processors. Mexican federal sanitary regulations align with USDA equivalence agreements for pork trade. Northern Border States processing facilities handle cross-border logistics for fresh belly shipments.
North America Bacon Market Competitive Landscape
Midwest producers anchor the commodity tier; Vermont and Quebec specialists hold artisanal positioning. The vendor base separates into three functional layers: vertically integrated packers controlling hog supply through processing, mid-scale smokehouses leveraging regional brand equity, and emerging direct-to-consumer platforms bypassing traditional retail markups. Dominant competitive moves include backward integration into captive hog production and geographic expansion into underpenetrated Canadian provincial markets.
Within the integrated-packer tier, Tyson Foods Inc., Hormel Foods Corporation, and Smithfield Foods, Inc. exemplify scale-driven archetypes. Tyson Foods Inc. occupies a position reflecting upstream control over protein supply chains. Hormel Foods Corporation represents specialized cured-meat expertise anchored in direct-to-foodservice distribution networks. Smithfield Foods, Inc. sits within the large-scale Midwest processing complex model dominating fresh and smoked bacon output.
| Leading Market Players |
|---|
| Hormel Foods Corporation |
| Tyson Foods Inc. |
| The Kraft Heinz Company |
| Fresh Mark Inc. |
| Sugar Creek Packing Co. |
| Smithfield Foods, Inc. |
| WH Group Limited |
| JBS SA |
| Seaboard Corporation |
| Others |
Value Network & Pricing Analysis
High-pressure processing technology adoption simultaneously compresses pathogen-reduction timelines and concentrates capital requirements among mid-scale processors in Wisconsin and Pennsylvania. This production-method transition favors operators with balance-sheet capacity to retrofit lines, reshaping cost economics while squeezing smaller smokehouses from premium refrigerated segments.
Pricing Analysis
Volume leadership in streaky bacon segments trades against margin compression from sodium-reduction reformulation costs. Three-tier pricing structure across premium uncured, standard smoked, and economy fresh levels differentiates by curing chemistry and shelf-life extension. Pricing pressure stems from quick-service restaurant procurement consolidation concentrating leverage among national buyers. Foodservice distributors exhibit highest price sensitivity due to contract-based volume commitments, while subscription meat-box consumers accept premium positioning for clean-label credentials.
Supply Chain Analysis
Reverse-logistics flows for refrigerated bacon returns and temperature-compromised shipments concentrate cost exposure at Midwest distribution nodes. Hog production draws from Iowa, Minnesota, and Illinois slaughter capacity, with curing operations tethered to these processing complexes. Corn and soybean price volatility transmits directly to feed cost structures. Single-source vulnerability runs through concentrated Midwest geography where weather disruptions cascade nationally. Distribution runs through broadline operators imposing uniform specification sheets that marginalize regional artisanal smokehouses.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The North America bacon market sits in a curing-chemistry transition phase. Celery powder and natural nitrate sources are displacing synthetic nitrite brines as FDA sodium guidance accelerates clean-label reformulation.
For Market Incumbents: Anchor defensive positioning through backward integration into captive hog production in Iowa and Minnesota to secure volume commitments against feed cost volatility. Invest in high-pressure processing retrofit capacity to unify pathogen controls with clean-label shelf-life extension, countering plant-based substitution threats from pea-protein analogs.
For New Entrants and Emerging Players: FDA Guidance for Industry on Voluntary Sodium Reduction Targets in the United States opens a window for premium uncured positioning targeting health-conscious households in Ontario and British Columbia. Target underpenetrated Alberta foodservice markets through direct partnerships with regional distributors seeking USDA-inspected supply alternatives to incumbent broadline structures.
For Investors and Strategic Acquirers: Exit pathways concentrate in mid-scale smokehouse acquisitions by integrated packers seeking artisanal brand equity and regional distribution access. Long-term viability favors operators with demonstrated FSMA preventive controls documentation and carbon-labeling traceability infrastructure. Monitor state-level animal-welfare statute adoption as inflection indicator for sourcing geography reshaping.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Hog Production | Captive supply secures volume commitments against Midwest feed grain price volatility. |
| High-Pressure Processing Retrofit | Pathogen elimination without synthetic preservatives unifies foodservice safety with retail premium positioning. |
| Clean-Label Reformulation | Celery powder curing chemistry captures health-conscious consumers in Ontario and British Columbia. |
| Direct-to-Consumer Subscription Launch | Vermont and Quebec smokehouses bypass retail markups through curated monthly meat-box shipments. |
| Carbon-Labeling Traceability Investment | Blockchain-verified life-cycle assessment positions operators for anticipated federal procurement preferences. |
Research Methodology
Multi-period observation of quick-service restaurant procurement volumes, sodium-reduction reformulation adoption rates, and clean-label SKU expansion anchored the trend analysis, supplemented by interviews with smokehouse operations managers, USDA FSIS compliance officers, broadline distribution category buyers, and quick-service restaurant supply chain directors. Secondary validation drew from FDA guidance documents, USDA livestock slaughter statistics, Canadian Food Inspection Agency import protocols, and Nielsen retail audit data. Bottom-up processor capacity modeling and top-down foodservice demand estimation were triangulated against cross-border trade flows.
Input-output matrices mapped hog production volumes through curing capacity utilization to end-use consumption across the analysis window. Segmentation dimensions modeled include product type, processing method, distribution channel, and end-user category with geographic regulatory cluster overlays. CAGRs were derived from trend extrapolation of volume and value indicators. Forecast inputs incorporated feed grain futures curves and quick-service restaurant expansion pipelines.
Caveats apply where feed grain price spikes, labor disruptions at Midwest processing nodes, or accelerated plant-based substitution adoption could materially shift the outlook. Practitioners should monitor CFIA import protocol adjustments and state-level animal-welfare statute progression for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Meat Products
Brisket Market
Meat Products
Beef Jerky Market
Meat Products
United States Bacon Market
Meat Products
Low Fat Sausage Market
Meat Products
Bahrain Poultry Meat Market
Meat Products
Reduced Fat Meat Market
Meat Products
Europe Canned Meat Market
Meat Products
Organic Beef Meat Market
Meat Products
India Poultry Meat Market
Meat Products
Saudi Arabia Goat Meat and Cheese Market
Meat Products
Middle East Poultry Meat Market
Meat Products
China Processed Meat Market
Meat Products
North America Processed Meat Market
Meat Products
Oman Poultry Meat Market
Meat Products
Chicken Fat Market
Meat Products
India Edible Meat Market