
 Low Fat Sausage Market | 2026-2036
Low Fat Sausage Market Size, Share, and Industry Trends Forecast 2026-2036
Low Fat Sausage Market Analysis
Lean pork trim is decoupling from traditional high-fat formulations as processors reformulate recipes with poultry isolates and soluble fiber systems. Cargill Incorporated leverages its integrated protein supply chain to control input costs across multiple species. Hormel Foods Corp. sustains brand loyalty through disciplined sodium and fat reduction in its flagship retail lines. Tyson Foods Inc. anchors North American volume with scaled turkey-sausage production at its Arkansas processing complex.
Low fat sausage denotes emulsified or coarse-ground meat products containing substantially reduced lipid content, typically achieved through lean-muscle selection, mechanical separation, and inclusion of water-binding hydrocolloids to preserve succulence. The category serves health-conscious consumers seeking protein with moderated saturated-fat intake. Turkey and chicken formulations lead volume in North American retail, while pork variants retain dominance in European chilled cases where taste familiarity commands premium positioning. Vacuum-seal packaging captures the fastest growth as shelf-life extension reduces retail shrink and supports e-commerce fulfillment.
The USDA Food Safety and Inspection Service sets maximum fat-to-lean ratios and labeling standards that directly constrain recipe architecture and marketing claims. The FDA Nutrition Labeling and Education Act mandates disclosure formats that shape consumer comparison behavior at point of purchase. The EU Food Information to Consumers Regulation imposes equivalent transparency requirements across member states, creating compliance complexity for exporters. Stakeholders must monitor evolving front-of-pack warning systems and sodium threshold proposals that could force accelerated reformulation cycles.
Market Dynamics
Lean-muscle extraction technologies and soluble fiber binding systems are decoupling low-fat sausage formulation from traditional high-fat pork trim dependence, compressing reformulation cycles and reshaping processor procurement patterns across multiple species.
Growth Catalysts
- EU Food Information to Consumers Regulation:Mandatory front-of-pack disclosure formats accelerate clean-label reformulation investments as processors compete on transparency credentials.
- Turkey and chicken isolates:Poultry protein extraction advances enable fat-content reduction below 10% while preserving emulsion stability and bite texture.
- Germany's chilled retail channel:Discounters and full-service supermarkets expand dedicated low-fat meat sections, creating shelf-space velocity for reformulated pork variants.
Market Restraints
- Lean pork trim supply concentration:European slaughterhouse consolidation in Denmark and the Netherlands creates input cost volatility for processors dependent on specific lean-muscle grades.
- USDA fat-to-lean ratio enforcement:FSIS labeling standards constrain recipe architecture flexibility, forcing dual-formulation production lines for compliant and non-compliant variants.
- Plant-based sausage substitution:Pea and mycoprotein analogs capture trial purchases from health-motivated flexitarians, compressing category expansion potential.
Strategic Opportunities
- United States e-commerce fulfillment:Vacuum-seal shelf-life extension enables direct-to-consumer subscription models bypassing traditional retail slotting fees.
- United Kingdom sodium threshold proposals:Anticipatory reformulation toward 1.4g salt per 100g positions brands for preemptive regulatory compliance and public health partnership status.
- Hydrocolloid-cultured fat convergence:Oleogel systems mimicking animal fat mouthfeel unlock premium positioning for ultra-lean formulations previously rejected on sensory grounds.
Industry Challenges
- Emulsion chemistry expertise scarcity:Formulation of stable low-fat batters requires protein functionality knowledge concentrated among aging meat science specialists, constraining R&D throughput.
- Dual-line capital requirements:Parallel production of standard and reduced-fat variants demands segregated grinding, blending, and stuffing equipment, elevating facility investment thresholds.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Low Fat Sausage Market |
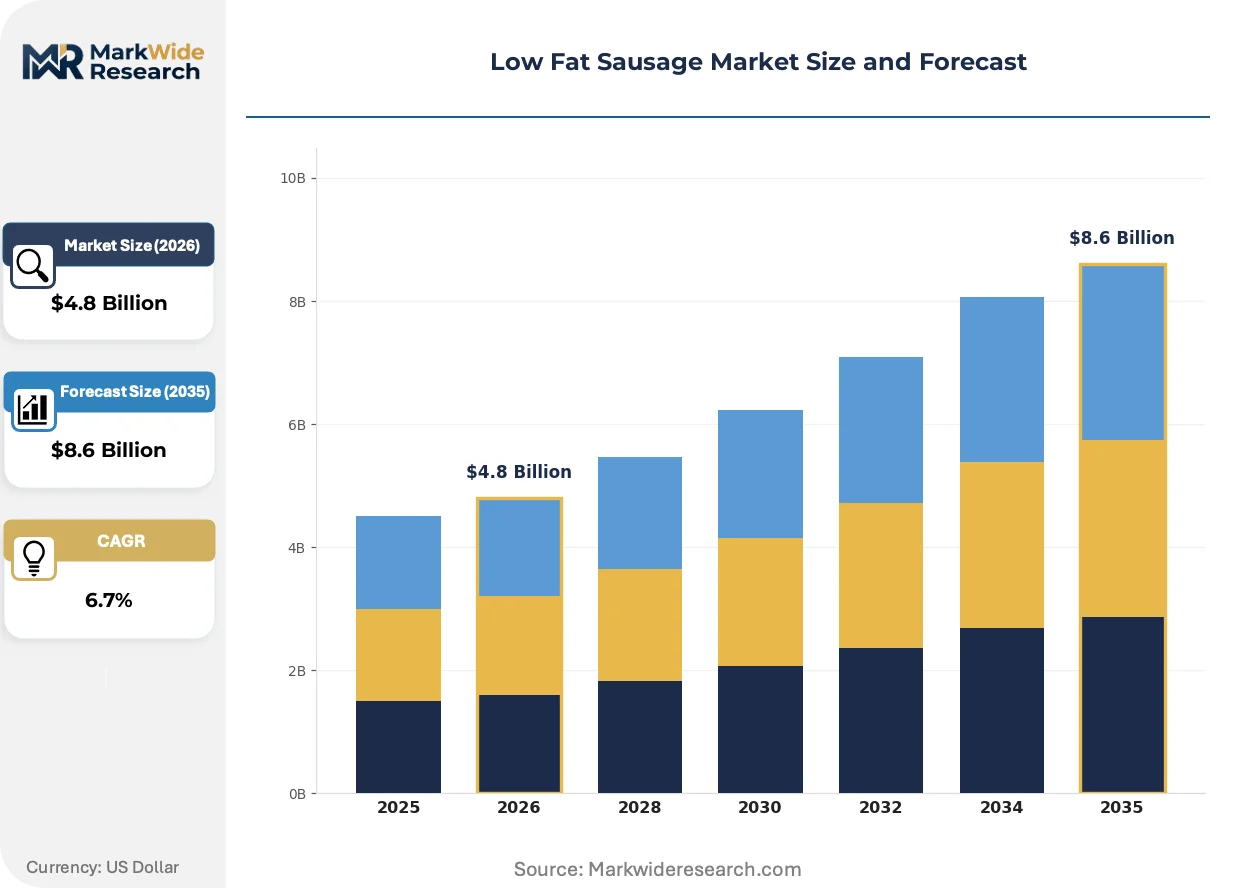
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pork, Turkey, Chicken, Beef Flavor Profile: Smoky, Spicy, Herb, Original Packaging Type: Vacuum Seal, Tray Pack, Casing, Bulk Distribution Channel: Supermarkets, Online Retail, Specialty Stores, Wholesalers |
| Companies Covered | Cargill Incorporated, Hormel Foods Corp., Tyson Foods Inc., Atria Plc, Beyond Meat, Nestlé S.A., Johnsonville LLC, ELPOZO ALIMENTACIÓN S.A., WH Group Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Low Fat Sausage Market Emerging Trajectories
Active reformulation is compressing the gap between health claims and sensory performance, with binding technologies and packaging advances converging to reset consumer expectations for reduced-fat meat products.
High-pressure processing systems are automating pathogen reduction in vacuum-sealed low-fat sausages, eliminating thermal pasteurization quality degradation. Premium retail brands in the United States and Germany adopt HPP for clean-label positioning without preservative inclusion. This technology is automating shelf-life extension from weeks to months, enabling inventory centralization and reducing retail shrink penalties.
REACH restrictions on phosphate additives are compelling European processors to substitute potassium and calcium-based alternatives in water-binding applications. The industrial consequence is reformulation complexity as alternative salts alter flavor profiles and require sensory rebalancing. German and British chilled pork sausage lines face the steepest adaptation curves, with some processors accelerating sodium-reduction programs to offset phosphate removal taste impacts.
Subscription meal-kit procurement is fragmenting traditional retail concentration as direct-to-consumer channels capture trial-oriented households. This model disrupts supermarket category management and slotting-fee economics, replacing them with data-rich customer relationships and predictable demand forecasting. The United States exhibits the most visible channel rotation, with turkey-sausage SKUs dominating protein-inclusive kit configurations.
Low Fat Sausage Market Segmentation
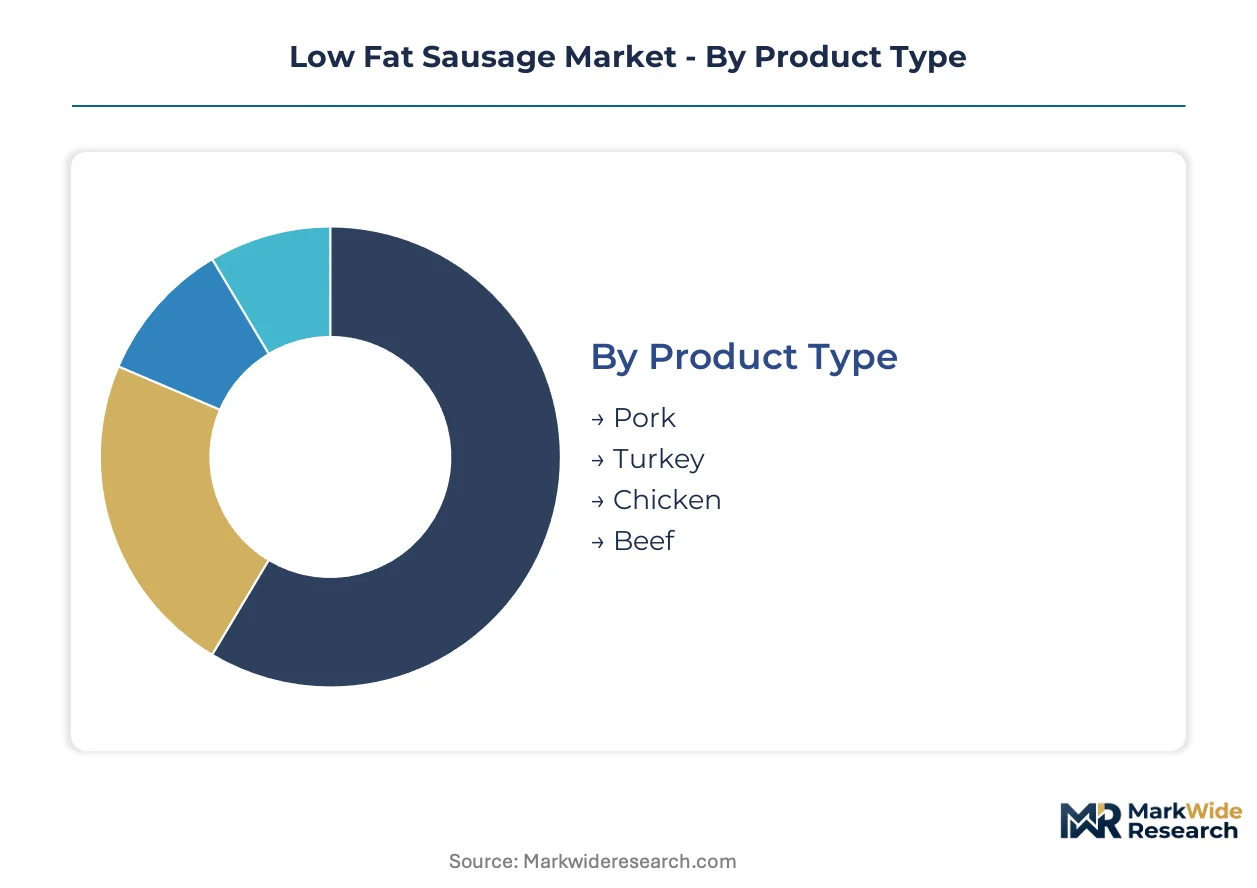
Segmentation in the low-fat sausage category reveals how protein sourcing, sensory engineering, and logistics infrastructure shape procurement decisions. Each dimension carries distinct margin profiles and regulatory exposure that processors must navigate.
Product Type:
Customization intensity varies from commodity poultry isolates to heritage pork formulations requiring precise lean-muscle grading.
- Pork:European chilled cases favor lean pork variants where mechanical separation achieves sub-10% fat content while preserving emulsion stability. German and British discounters drive volume through reformulated breakfast links that meet FSA sodium thresholds.
- Turkey:North American retail concentration centers on Arkansas and Minnesota processing complexes where scaled production of 7% fat turkey sausage anchors private-label programs. Vacuum-seal shelf-life extension supports e-commerce subscription penetration.
- Chicken:Poultry isolates enable aggressive fat reduction through lean-breast extraction combined with soluble fiber binding systems.
- Beef:Lean trim from grass-fed programs commands premium positioning in specialty retail channels with stringent fat-to-lean ratio labeling.
Most installed capacity flows through Turkey. Expansion is steepest in Chicken.
Flavor Profile:
Flavor investment correlates with channel margin—premium positioning demands differentiated sensory signatures while private-label competes on base protein cost.
- Smoky:Liquid smoke and natural wood-smoking systems dominate premium positioning in United States and German retail, where clean-label claims require preservative-free smoke delivery. High-pressure processing enables extended shelf life without thermal degradation of volatile compounds.
- Spicy:Capsicum extract and fermented pepper pastes concentrate demand in Southwestern United States and Mexican-influenced markets where heat tolerance shapes repeat purchase behavior.
- Herb:Sage, rosemary, and thyme formulations retain European dominance where traditional sausage recipes undergo fat reduction without botanical profile alteration.
- Original:Base seasoning platforms serve cost-sensitive retail tiers and foodservice portion-control applications with minimal R&D overhead.
Volume concentrates in Original. Value expansion is fastest in Smoky.
Packaging Type:
Packaging technology determines shelf-life extension capability and channel accessibility, with capital requirements scaling dramatically across formats.
- Vacuum Seal:Multi-layer barrier films combined with high-pressure processing extend refrigerated shelf life from 21 to 90 days, enabling centralized distribution and direct-to-consumer fulfillment. German and United States premium brands adopt this format for clean-label positioning without preservative inclusion.
- Tray Pack:Modified atmosphere packaging with CO2/N2 flushing dominates mass retail in the United Kingdom and France where overwrap transparency supports visual quality assessment at point of purchase.
- Casing:Collagen and cellulose casings serve foodservice and butcher-channel fresh sausage requiring cooking performance and snap texture.
- Bulk:Foodservice and industrial ingredient supply rely on chub packs and totes for portion-control manufacturing and further processing applications.
Tray Pack holds the largest installed base. Vacuum Seal is gaining share fastest.
Distribution Channel:
Channel selection determines pricing architecture and customer data access, with traditional retail slotting fees colliding against subscription economics.
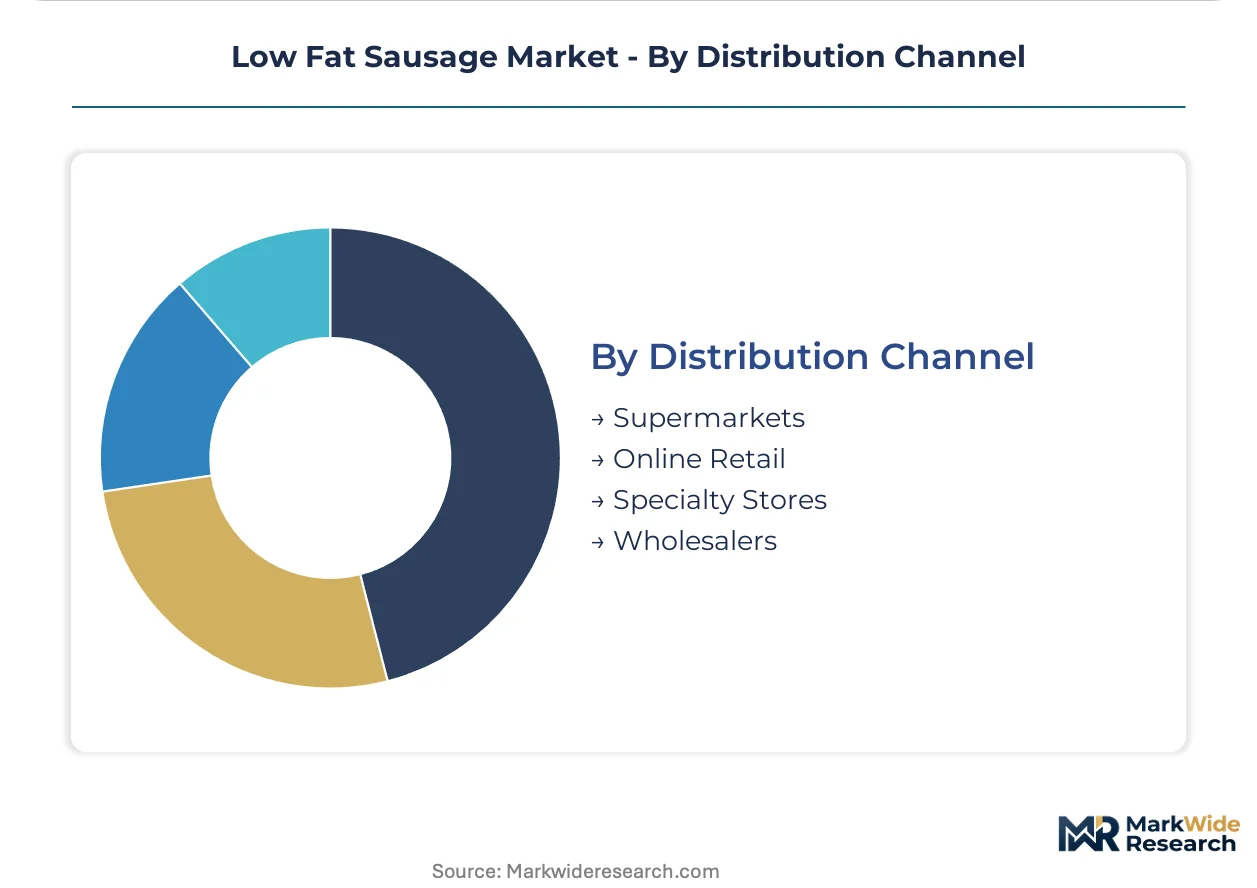
- Supermarkets:United States and German full-service retailers command category management authority through slotting fees and planogram placement, concentrating volume in perimeter meat cases and dedicated health-food sections. Discounter expansion in the United Kingdom compresses margin through private-label concentration.
- Online Retail:Direct-to-consumer subscription models bypass traditional retail economics, leveraging vacuum-seal shelf-life extension for centralized fulfillment. United States meal-kit procurement fragments demand through data-rich customer relationships.
- Specialty Stores:Natural and organic channels in California and New York metropolitan areas favor heritage pork and grass-fed beef variants with third-party certification.
- Wholesalers:Broadline distribution serves foodservice and institutional accounts with portion-controlled formats and bulk pricing tiers.
Supermarkets retain the dominant throughput position. Online Retail shows the steepest trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Arkansas processing complexes anchor North American turkey-sausage production, while German chilled retail channels concentrate European demand for reformulated pork variants. Regulatory divergence across the USDA, EU Food Information to Consumers Regulation, and national sodium threshold proposals shapes regional formulation strategies. Industrial clusters in Minnesota, the United Kingdom, and Spain concentrate specialized capacity for lean-muscle extraction and vacuum-seal packaging integration.
United States
Meal-kit subscription procurement and direct-to-consumer channels drive demand fragmentation beyond traditional supermarket slotting economics. The USDA Food Safety and Inspection Service enforces fat-to-lean ratio labeling standards that constrain recipe architecture flexibility. Arkansas and Minnesota processing complexes anchor scaled turkey-sausage production for private-label and branded retail programs.
Germany
Discounter expansion and full-service supermarket chilled-section growth create shelf-space velocity for reformulated breakfast links. The EU Food Information to Consumers Regulation mandates front-of-pack disclosure formats that accelerate clean-label reformulation investments. North Rhine-Westphalia and Bavaria concentrate industrial sausage processing capacity serving domestic and export markets.
United Kingdom
Anticipatory sodium-reduction programs target 1.4g salt per 100g thresholds ahead of formal regulatory mandates. The Food Standards Agency monitors compliance pathways that influence processor reformulation timelines. Midlands and Yorkshire processing clusters specialize in heritage pork variants with mechanical fat separation for premium chilled retail positioning.
Spain
Traditional pork sausage consumption patterns undergo gradual displacement as health-conscious segments trial reduced-fat alternatives. ELPOZO ALIMENTACIÓN S.A. anchors domestic production capacity with integrated lean-muscle sourcing from Murcia and Aragon slaughterhouse networks. Catalonia and Madrid metropolitan retail channels experiment with vacuum-seal packaging for extended shelf-life premium positioning.
Denmark
Slaughterhouse consolidation creates input cost volatility for processors dependent on specific lean-pork-trim grades. Danish Veterinary and Food Administration standards align with EU baseline requirements while permitting national sodium threshold experimentation. Jutland processing clusters supply lean-muscle inputs to German and British reformulation programs.
Low Fat Sausage Market Vendor Landscape
Portfolio diversification dominates the current landscape as processors balance standard and reduced-fat production lines. The vendor base organizes around three strategic archetypes: integrated protein conglomerates with multi-species supply chains, branded consumer goods specialists with disciplined reformulation programs, and plant-based analog disruptors capturing flexitarian trial. Competitive intensity concentrates on M&A activity for lean-muscle extraction technology and strategic partnerships for hydrocolloid binding system access.
Within the integrated protein tier, Cargill Incorporated and Tyson Foods Inc. exemplify scale-driven supply chain control across poultry and pork species. Hormel Foods Corp. occupies a branded specialist position with sustained investment in sodium and fat reduction for retail loyalty. These three companies represent distinct competitive vectors: captive raw material sourcing, manufacturing scale, and brand equity preservation.
| Leading Market Players |
|---|
| Cargill Incorporated |
| Hormel Foods Corp. |
| Tyson Foods Inc. |
| Atria Plc |
| Beyond Meat |
| Nestlé S.A. |
| Johnsonville LLC |
| ELPOZO ALIMENTACIÓN S.A. |
| WH Group Limited |
| Others |
Supply Flow & Price Mechanics
Lean pork trim futures and poultry isolate spot markets cascade through processor procurement decisions into three-tier pricing structure across premium, standard, and economy levels. Cost volatility in Danish and Dutch slaughterhouse networks compresses margins at the standard tier while vacuum-seal shelf-life extension commands premium positioning in United States and German retail channels.
Pricing Analysis
Input-cost pass-through from lean-muscle grades and hydrocolloid binding systems stratifies pricing across premium heritage pork, standard reformulated poultry, and economy private-label tiers. Price differentiation hinges on sodium threshold compliance certification and brand equity in chilled retail placement. Pricing pressure stems from plant-based sausage substitution capturing flexitarian trial purchases. Discounter private-label programs exhibit highest price sensitivity while specialty organic channels demonstrate inelastic demand for third-party certified variants.
Supply Chain Analysis
Refrigerated freight cost escalation between Arkansas processing complexes and coastal distribution hubs reshapes procurement geography for North American turkey-sausage volume. Supply concentrates in the United States, Germany, and Denmark where lean-pork-trim extraction and poultry-isolate production anchor upstream capacity. Raw material dependencies rest on lean-muscle grades, soluble fiber systems, and collagen casing inputs. Single-source vulnerability in Danish slaughterhouse consolidation elevates input cost volatility. Distribution runs through supermarket perimeter meat cases, direct-to-consumer subscription fulfillment, and broadline foodservice wholesalers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a regulatory compounder where EU Food Information to Consumers Regulation disclosure mandates and United Kingdom sodium threshold proposals accelerate reformulation investment cycles.
For Market Incumbents: Lock in captive supply of lean-pork-trim through backward integration into Danish and Dutch slaughterhouse networks or long-term offtake agreements. Defend shelf-space velocity by preemptively reformulating to 1.4g salt per 100g thresholds ahead of formal United Kingdom mandates. Channel control through direct-to-consumer subscription models mitigates slotting-fee erosion from discounter expansion. For New Entrants and Emerging Players: Launch via meal-kit subscription procurement channels where vacuum-seal shelf-life extension bypasses traditional retail barrier-to-entry costs. Target white-space in hydrocolloid-cultured fat convergence for ultra-lean premium positioning previously rejected on sensory grounds. Geographic white-space sits in Spain where traditional pork consumption patterns undergo gradual displacement by health-conscious segments. For Investors and Strategic Acquirers: Asymmetric upside sits with lean-muscle extraction technology specialists and hydrocolloid binding system innovators where emulsion chemistry expertise scarcity constrains R&D throughput. Long-term viability favors processors with dual-line flexibility for standard and reduced-fat variant production. Monitor United Kingdom Food Standards Agency sodium threshold formalization as inflection indicator for accelerated industry-wide reformulation capex.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Lean-Muscle Supply | Cargill's multi-species protein network demonstrates how captive raw material sourcing stabilizes input cost volatility against Danish slaughterhouse consolidation. |
| Direct-to-Consumer Subscription Launch | Vacuum-seal shelf-life extension enables Tyson Foods to bypass supermarket slotting fees through Arkansas-anchored centralized fulfillment infrastructure. |
| Preemptive Sodium-Reduction Reformulation | Hormel Foods positions for United Kingdom Food Standards Agency partnership status by targeting 1.4g salt per 100g ahead of regulatory mandates. |
| Hydrocolloid-Cultured Fat R&D Partnership | Oleogel systems mimicking animal fat mouthfeel unlock premium tier pricing for ultra-lean formulations previously rejected on sensory grounds. |
| High-Pressure Processing Capacity Addition | German premium brands adopt HPP for clean-label positioning without preservative inclusion, extending refrigerated shelf life from weeks to months. |
Methodological Framework
Bottom-up retail channel and foodservice procurement modeling reconciled against top-down protein processing capacity tracking forms the analytical core of this study. Primary interviews with meat science R&D directors, supermarket category buyers, meal-kit procurement managers, and regulatory affairs specialists at USDA FSIS and EU food safety agencies combined with secondary validation from Nielsen retail audit data, customs trade records, SEC processor filings, and EU Food Information to Consumers Regulation compliance databases. Triangulation between demand-side consumption patterns and supply-side production capacity ensures dimensional consistency across segmentation analysis.
Historical trendline analysis of turkey-sausage volume growth and reformulated pork variant adoption rates informs the projection framework across the analysis window. Segmentation dimensions modeled include protein source species, flavor profile investment tiers, packaging technology shelf-life tiers, and distribution channel economics. CAGRs derive from curve-fitting observed adoption velocities against regulatory milestone timing and technology cost reduction trajectories. Industry-specific forecast inputs incorporate hydrocolloid binding system cost curves and vacuum-seal packaging penetration rates.
Forecast precision tightens around the base case; tail outcomes carry wider variance under accelerated plant-based substitution scenarios or front-of-pack warning system implementations beyond current EU proposals. Forecasts reflect documented assumptions regarding sodium threshold enforcement timelines and lean-muscle grade availability. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Meat Products
Meat Mincers Market
Meat Products
Shark Meat Market
Meat Products
Beef Bouillon Market
Meat Products
Low-Fat Ham Market
Meat Products
United Arab Emirates Edible Meat Market
Meat Products
Meat Paste Market
Meat Products
Grass Fed Beef Market
Meat Products
Organic Halal Meat Market
Meat Products
Grassfed Jerky Market
Meat Products
Brisket Market
Meat Products
Europe Processed Meat Market
Meat Products
North America Processed Meat Market
Meat Products
Beef Fat Powder Market
Meat Products
Global Lab-Based Meat Market
Meat Products
Pork Meat Market
Meat Products
Mechanically Separated Meat Market