
 Europe Canned Meat Market | 2026-2036
Europe Canned Meat Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Canned Meat Market Foresight
Buyer concentration across European military and emergency supply channels is decoupling from traditional retail patterns, creating parallel procurement ecosystems with distinct specification requirements. Danish Crown A.M.B.A. leverages its integrated pork supply chain to dominate Nordic defense contracts, while Zwanenberg Food Group anchors shelf-stable poultry output for Dutch and Belgian retail discounters. Vion Food Group competes through specialized halal and antibiotic-free processing lines that satisfy divergent institutional and consumer standards.
Canned meat comprises thermally processed animal proteins sealed in hermetic containers to achieve commercial sterility, typically utilizing retort temperatures between 116°C and 121°C to eliminate Clostridium botulinum spores and ensure multi-year shelf stability without refrigeration. The product type dimension shows poultry outpacing red meat variants as health-conscious reformulation and lower input costs reshape margin pools across Central European production. Packaging type dynamics reveal metal can formats sustaining dominance in military and long-duration emergency applications, while flexible pouches gain traction in camping and expedition retail segments where weight reduction commands premium positioning.
EMA food contact material regulations and EU F-Gas restrictions on industrial cooling systems constrain processing equipment choices and facility upgrade timelines across member states. REACH chemical compliance and CE marking requirements for thermal processing machinery shape cross-border equipment procurement and plant certification costs for producers. Stakeholders must monitor evolving EU packaging waste directives and national deposit-return schemes that threaten to impose circularity costs on single-use metal formats while creating first-mover advantages for recyclable pouch innovations.
Market Dynamics
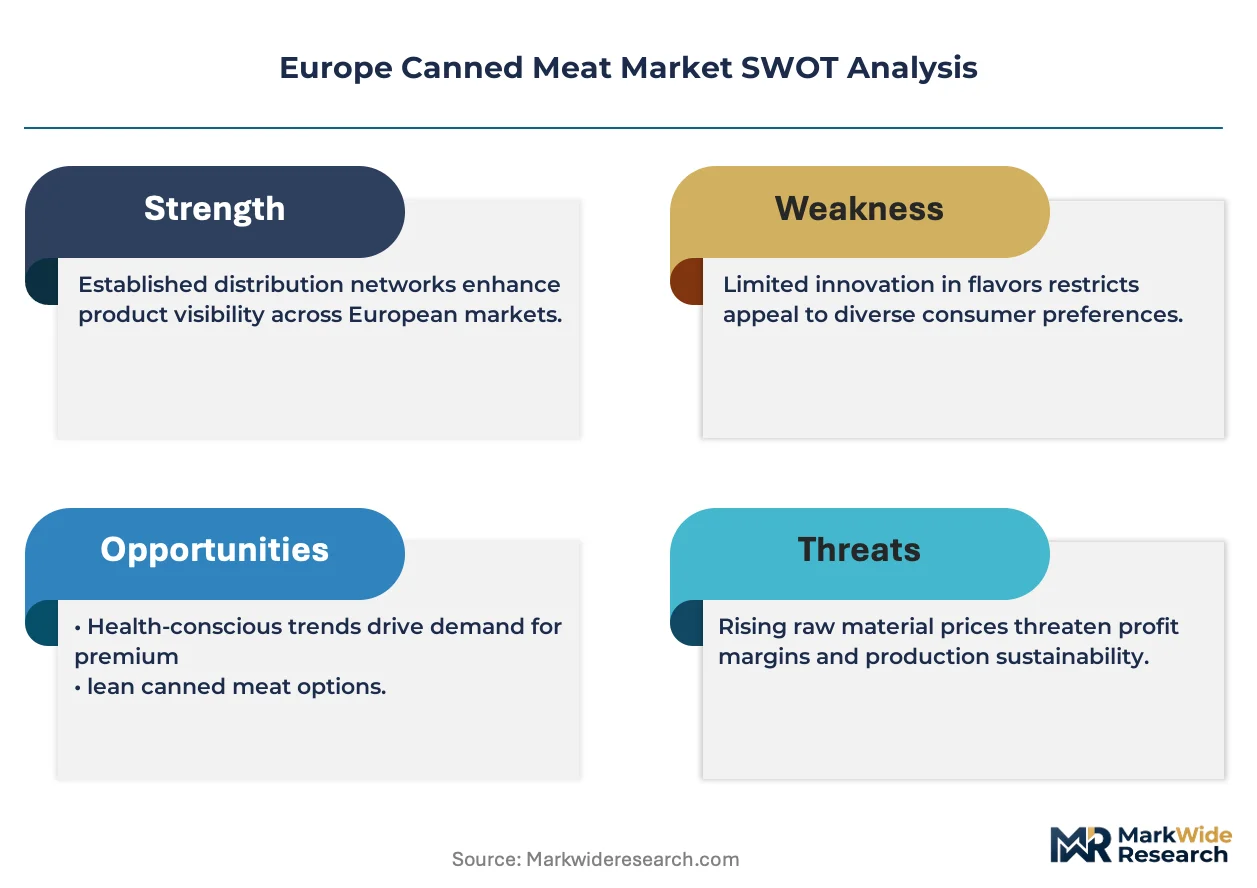
Bundeswehr stockpiling and discount retail consolidation in Germany are forcing parallel procurement ecosystems with incompatible specification requirements. Military buyers demand multi-year shelf stability and hermetic integrity, while Aldi and Lidl prioritize cost-per-kilogram and rapid inventory turns.
Growth Catalysts
- EU Green Deal Farm to Fork strategy:Animal welfare mandates are accelerating antibiotic-free and higher-welfare processing line investments, creating premium positioning for compliant producers.
- NATO-aligned emergency preparedness:Military and civil defense stockpiling across Northern Europe is decoupling from retail demand cycles, generating countercyclical volume anchors.
- Poultry input cost advantages:Lower feed conversion ratios versus red meat are expanding margin pools for processors with dedicated avian supply chains.
Market Restraints
- EMA food contact material regulations:Compliance testing for migration limits and coating chemistries extends new product development timelines by months.
- EU F-Gas restrictions on industrial cooling:Retort and post-process cooling equipment upgrades face constrained refrigerant choices and higher capital costs.
- Metal can circularity costs:National deposit-return schemes and packaging waste directives threaten to impose end-of-life fees on single-use formats.
Strategic Opportunities
- Flexible pouch formats:Camping and expedition retail segments reward weight reduction with premium positioning, creating first-mover advantages for recyclable innovations.
- Halal and antibiotic-free specialization:Vion Food Group's dual-certification approach demonstrates how divergent institutional and consumer standards can be captured in unified production.
- Danish Crown's Nordic defense concentration:Integrated pork supply chains anchored in Denmark offer template for geographic contract clustering.
Industry Challenges
- REACH chemical compliance timelines:Substance of very high concern screenings for coating resins and sealants create unpredictable certification delays.
- Retort operator skill scarcity:Thermal process validation and botulinum lethality calculation expertise is concentrating among aging specialist workforces.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Canned Meat Market |
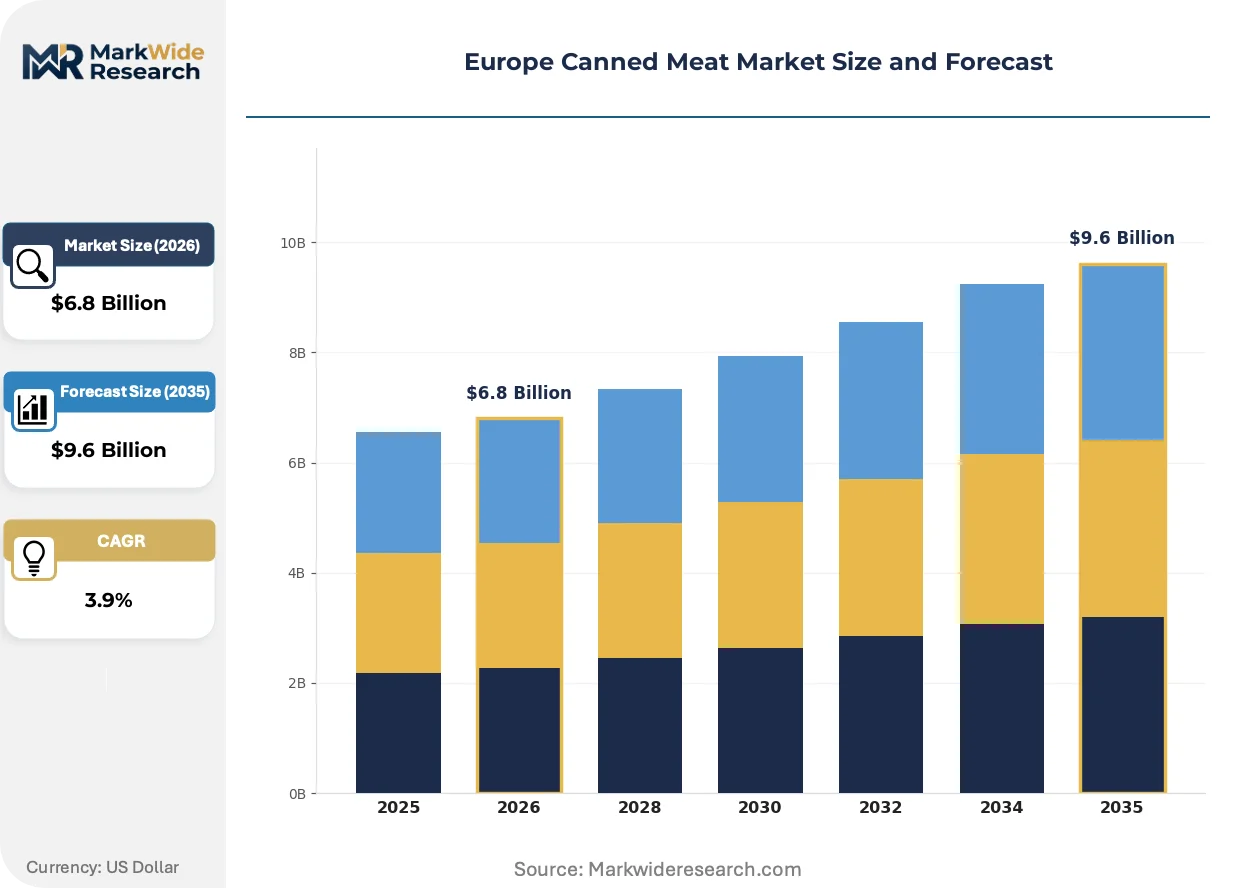
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $9.6 Billion |
| CAGR (2026 – 2036) | 3.9% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Beef, Pork, Poultry, Seafood Packaging Type: Metal Can, Glass Jar, Flexible Pouch, Tin Plate End User: Retail, Food Service, Military, Emergency Supplies Distribution Channel: Supermarket, Online Store, Convenience Store, Wholesale |
| Companies Covered | Danish Crown A.M.B.A., Zwanenberg Food Group, Vion Food Group, Bolton Group, Hormel Foods Corporation, Tyson Foods Inc., JBS Foods, WH Group Ltd, Pronas, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Canned Meat Market Shifts & Advancements
Retort pouch technology is compressing the century-long dominance of metal can formats by unifying shelf stability with weight reduction. Military buyers remain tethered to steel for extreme durability, but civilian outdoor recreation and emergency preparedness segments are accelerating adoption.
High-barrier multilayer films with aluminum oxide coatings are unifying oxygen and moisture protection in flexible formats. Dutch and Belgian discounters are piloting these for premium private-label lines. The structural consequence is a bifurcation where metal sustains institutional procurement while pouches capture retail premiumization.
EU F-Gas Regulation phase-down schedules are forcing refrigeration-dependent processing plants toward ammonia and CO2 cascade systems. German facilities face the steepest retrofit urgency due to older R404A infrastructure density. Meat processors with integrated rendering operations are recovering waste heat to offset cooling energy penalties.
Bundeswehr procurement officers are consolidating orders through centralized defense logistics agencies rather than regional commissaries. This buyer concentration is compressing supplier bases and extending contract durations. Danish and German producers with existing NATO quality certifications are capturing disproportionate share of consolidated volume.
Europe Canned Meat Market Segmentation
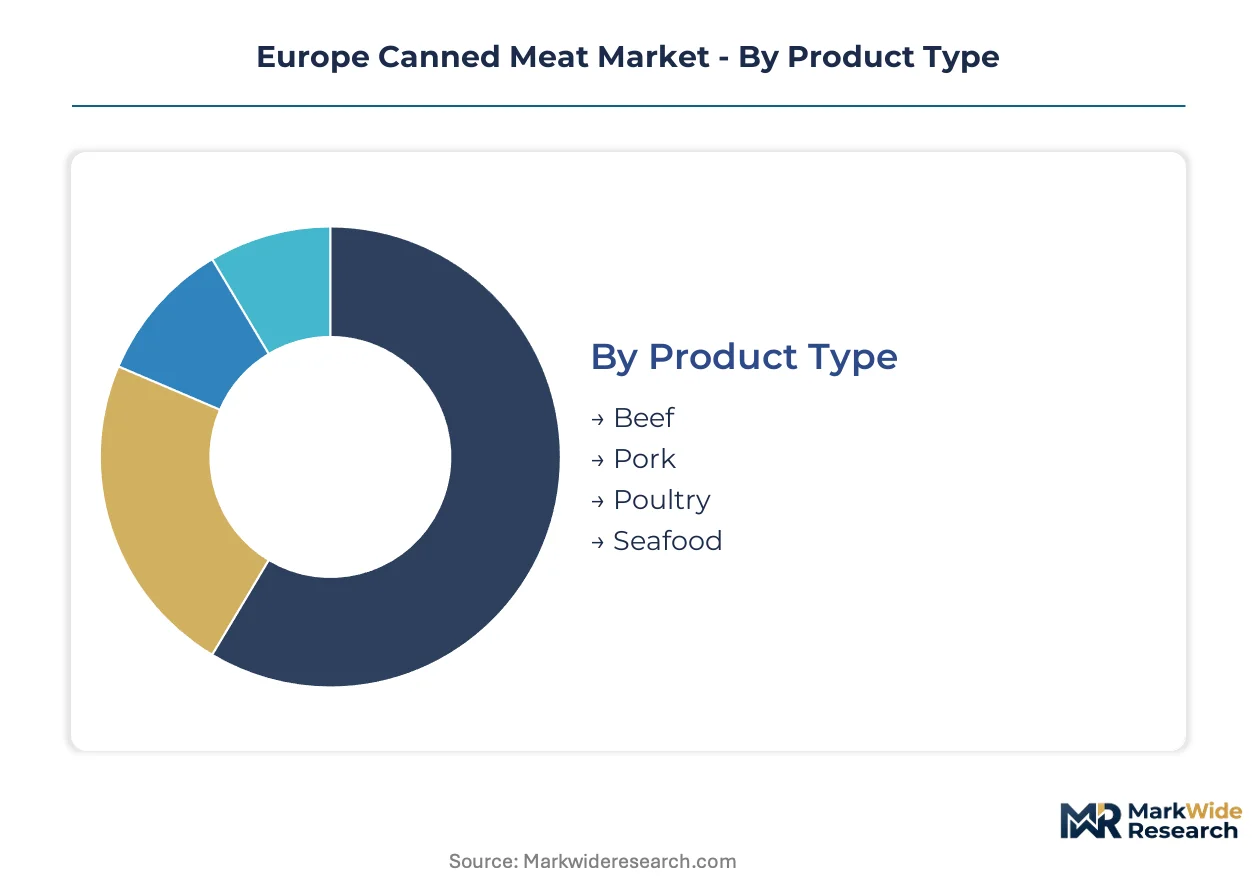
Specification divergence between institutional and retail buyers forces processors to maintain parallel production configurations. Each segment dimension carries distinct margin structures, certification requirements, and capacity allocation priorities that reshape competitive positioning across the value chain.
Product Type:
Customization intensity varies from commodity-grade bulk formats to welfare-certified premium lines, with input cost differentials driving portfolio rebalancing.
- Poultry:Lower feed conversion ratios versus red meat variants compress unit economics while accommodating antibiotic-free and higher-welfare processing mandates. German discount retail consolidation and Dutch retail discounters concentrate volume procurement for private-label canned chicken and turkey lines.
- Pork:Danish Crown A.M.B.A.'s integrated supply chain dominates Nordic defense contracts through hermetically sealed long-life formats meeting NATO shelf-stability specifications. Bundeswehr stockpiling absorbs substantial output from specialized retort facilities.
- Beef:Premium positioning in halal-certified and organic segments serves divergent institutional and consumer standards.
- Seafood:Tuna and mackerel variants sustain Mediterranean retail demand with established supply relationships.
Most installed capacity flows through Pork. Expansion is steepest in Poultry.
Packaging Type:
Cost tier separation between capital-intensive metal formats and emerging flexible alternatives creates divergent investment horizons for processors.
- Metal Can:Steel and aluminum hermetic containers sustain dominance in military and long-duration emergency applications where extreme durability and multi-year shelf stability are non-negotiable. Bundeswehr procurement through centralized defense logistics agencies reinforces format lock-in for NATO-aligned contracts.
- Flexible Pouch:High-barrier multilayer films with aluminum oxide coatings unify oxygen and moisture protection while delivering weight reduction critical for camping and expedition retail segments. Dutch and Belgian discounters pilot these for premium private-label lines.
- Tin Plate:Traditional format retains presence in heritage brand portfolios and specific export markets.
- Glass Jar:Premium positioning in gourmet retail channels where visual product inspection commands price premiums.
Metal Can commands the largest share of dedicated production assets. Flexible Pouch is gaining share fastest among format investments.
End User:
Customer type fragmentation splits procurement between cyclical retail demand and countercyclical institutional anchors with incompatible specification requirements.
- Military:NATO-aligned emergency preparedness across Northern Europe decouples from retail demand cycles, generating volume anchors through multi-year contracts with stringent hermetic integrity and botulinum lethality validation requirements.
- Retail:Aldi and Lidl prioritize cost-per-kilogram and rapid inventory turns, forcing processors to optimize for throughput rather than shelf-life extension.
- Emergency Supplies:Civil defense stockpiling in Germany and Nordic nations creates parallel procurement ecosystem with specifications overlapping military standards.
- Food Service:Institutional catering channels absorb commodity-grade output with less stringent packaging durability requirements.
Military contracts anchor the most predictable volume commitments. Retail channels show the steepest margin compression pressure.
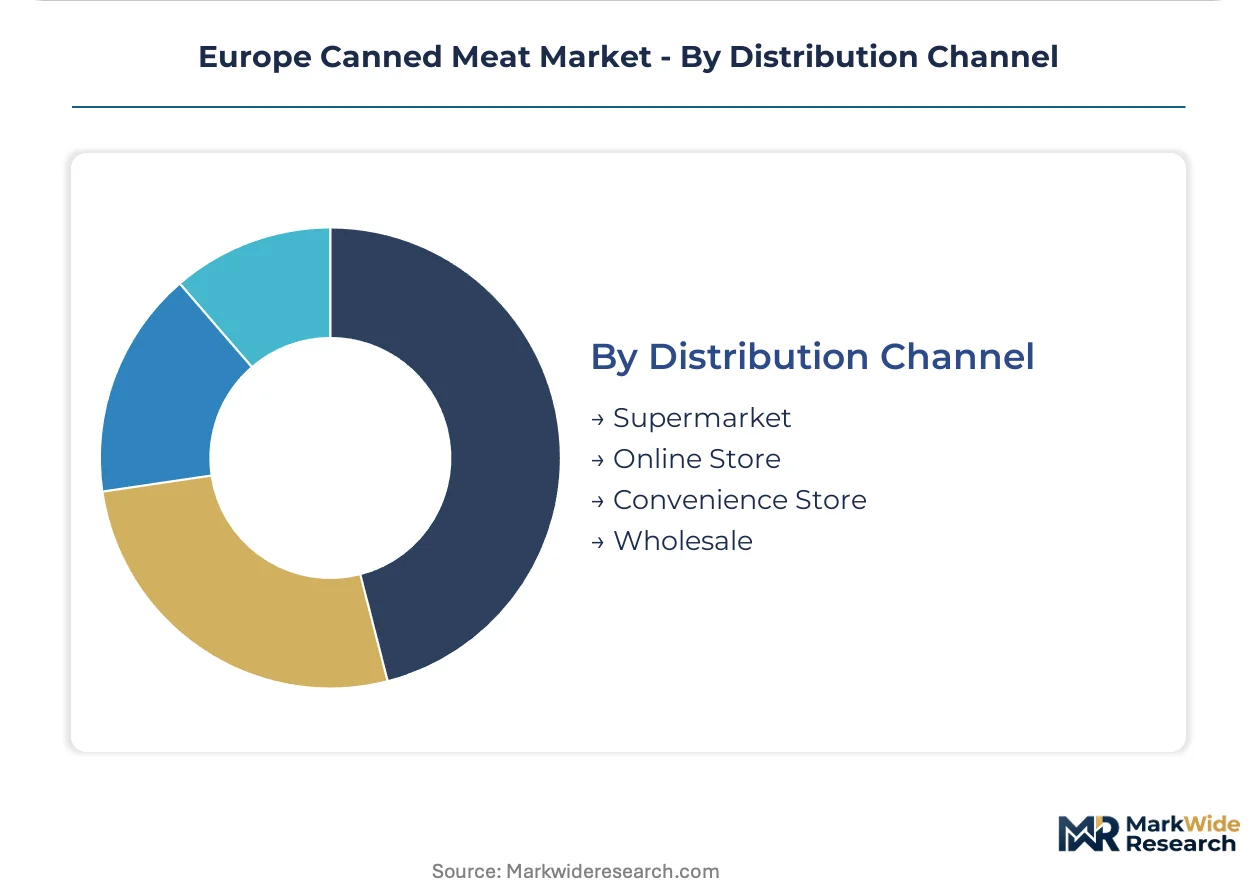
Distribution Channel:
Geographic concentration of buying power determines route-to-market economics, with channel-specific logistics investments creating switching costs.
- Supermarket:German discount retail consolidation concentrates volume through Aldi and Lidl networks, compressing supplier bases and extending payment terms while demanding private-label capacity allocation.
- Wholesale:Military and emergency supply procurement flows through centralized defense logistics agencies rather than regional commissaries, extending contract durations and quality certification requirements.
- Online Store:Direct-to-consumer channels for camping and expedition segments reward premium positioning and specialized format innovation.
- Convenience Store:Impulse-oriented single-serve formats serve urban consumption patterns with higher per-unit margins but lower volume throughput.
Supermarket channels absorb the largest volume flows. Online Store expansion is climbing the fastest among distribution investments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany commands larger procurement volumes than France, yet both operate under divergent channel pressures that reshape production allocation across their processing bases.
Germany
Bundeswehr stockpiling and Aldi-Lidl discount consolidation generate incompatible specification demands. EU F-Gas Regulation phase-down schedules force retort cooling retrofits toward ammonia systems. Lower Saxony and North Rhine-Westphalia host specialized facilities supplying centralized defense logistics agencies with multi-year shelf-stable formats.
France
Retail premiumization and heritage brand preservation sustain glass jar demand for gourmet channels. ANSM food contact material oversight tightens coating chemistry approvals. The Brittany and Pays de la Loire clusters concentrate seafood canning operations serving established Mediterranean supply relationships.
Netherlands
Dutch discounters pilot high-barrier flexible pouches for private-label premium lines. ECHA REACH compliance timelines extend coating resin certifications unpredictably. Eindhoven-Brabant processing corridors anchor poultry supply chains optimized for antibiotic-free mandates.
Denmark
Nordic defense contracts concentrate through integrated pork supply chains serving NATO-aligned emergency preparedness. Danish Crown leverages hermetic sealing capabilities validated for botulinum lethality standards. Copenhagen-Aarhus production corridors dominate long-life format output for military procurement.
Spain
Mediterranean tuna and mackerel variants sustain established retail demand with stable supply relationships. EMA migration limit testing constrains new coating introductions. Galicia and Andalusia maintain seafood processing clusters with heritage equipment configurations.
Europe Canned Meat Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across procurement channels with irreconcilable specifications. Market structure tilts toward consolidation as Bundeswehr buyer concentration compresses supplier bases and extends contract durations. Three archetypes dominate: integrated livestock-processor hybrids, specialized halal-antibiotic-free operators, and discount retail private-label suppliers. Competitive moves concentrate on capacity reconfiguration for dual certification lines and geographic clustering around defense logistics hubs.
Among Nordic-anchored integrated operators, Danish Crown A.M.B.A. exemplifies livestock-processor hybrid structures optimized for defense channel concentration. Vion Food Group occupies a position within the specialization tier, representing dual-certification capabilities that bridge institutional and consumer standard divergence. Zwanenberg Food Group anchors the private-label supply archetype, sitting within Dutch-Belgian discount retail procurement networks where cost-per-kilogram optimization dominates supplier selection criteria.
| Leading Market Players |
|---|
| Danish Crown A.M.B.A. |
| Zwanenberg Food Group |
| Vion Food Group |
| Bolton Group |
| Hormel Foods Corporation |
| Tyson Foods Inc. |
| JBS Foods |
| WH Group Ltd |
| Pronas |
| Others |
Supply & Pricing Matrix
Backward integration into livestock supply anchors both cost predictability and pricing power for Nordic and German processors serving NATO defense contracts. Danish Crown's captive pork supply and Vion's controlled antibiotic-free herds insulate against feed volatility while commanding premium positioning in military procurement channels where hermetic integrity specifications override cost-per-kilogram sensitivity.
Pricing Analysis
Capacity additions in Germany are reshaping price floors for discount retail private-label lines as Aldi and Lidl consolidate procurement volumes. Three-tier pricing structure across premium, standard, and economy levels separates welfare-certified organic from commodity-grade and military-specification outputs. Cost compression in economy tiers is intensifying because poultry input advantages compress margins for red meat processors. Discount retail buyers exhibit highest price sensitivity, while Bundeswehr procurement officers prioritize shelf-stability validation over unit cost.
Supply Chain Analysis
Direct-to-military channels handle consolidated defense logistics demand through centralized procurement agencies rather than regional commissaries. Supply concentrates in Denmark, Germany, and the Netherlands, with Danish Crown's integrated pork operations and Dutch poultry processors anchoring regional output. Raw material flows draw from specialized feed operations, hermetic coating chemistries, and high-barrier film substrates. Single-source vulnerability sits with concentrated retort equipment suppliers facing ECHA REACH compliance delays. Distribution runs through defense logistics hubs for institutional buyers and discount retail networks for consumer channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Europe Canned Meat Market reads as a late-cycle quality story as EU Green Deal Farm to Fork mandates shift procurement toward antibiotic-free and higher-welfare specifications that reward certified producers with pricing power.
For Market Incumbents: Anchor NATO contract clustering through geographic proximity to defense logistics hubs in Lower Saxony and Copenhagen-Aarhus corridors. Deepen captive supply control over antibiotic-free livestock herds to satisfy divergent institutional and consumer certification demands. Retort operator skill scarcity threatens production continuity; secure specialist workforce pipelines through technical training partnerships.
For New Entrants and Emerging Players: Begin with flexible pouch formats for camping and expedition retail segments where weight reduction commands premium positioning and incumbent metal-can investments create white space. Target Dutch and Belgian discounters piloting high-barrier multilayer films for private-label premium lines. Pursue halal-antibiotic-free dual certification as the fastest-penetrable positioning bridging institutional and consumer standards.
For Investors and Strategic Acquirers: Roll-up economics work for mid-cap specialists with NATO quality certifications because Bundeswehr buyer concentration compresses supplier bases and extends contract durations. Focus on processors with integrated rendering operations recovering waste heat to offset EU F-Gas cooling retrofit costs. Watch EMA food contact material migration limit rulings as inflection indicators for coating chemistry substitution costs.
| Strategic Initiative | Industry Significance |
|---|---|
| Flexible Pouch Format Investment | High-barrier multilayer films with aluminum oxide coatings capture camping segment premium positioning. |
| Dual Certification Line Expansion | Halal-antibiotic-free processing satisfies divergent Bundeswehr and retail welfare mandates simultaneously. |
| Defense Logistics Hub Proximity | Geographic clustering around centralized NATO procurement agencies secures multi-year volume anchors. |
| EU F-Gas Cooling Retrofit | Ammonia and CO2 cascade systems replace R404A infrastructure ahead of phase-down deadlines. |
| Retort Operator Training Pipeline | Specialist workforce development addresses botulinum lethality calculation expertise concentration risks. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with retort facility managers, defense procurement officers at centralized logistics agencies, discount retail category buyers, and ECHA compliance consultants with secondary validation. Bottom-up capacity assessments triangulated against top-down demand modeling using EU customs trade data, Bundeswehr procurement disclosures, EMA coating chemistry approvals, and REACH substance registrations.
Segment-weighting approaches applied differential growth assumptions across product type, packaging format, and end-user dimensions over the projection horizon. Poultry expansion rates, metal-can durability premiums in military channels, and flexible pouch adoption curves in outdoor recreation segments informed volume trajectories. CAGRs derived from historical elasticity patterns and regulatory-driven specification shifts rather than extrapolated trend lines.
Several conditions sit outside the modeled scope, including abrupt NATO defense budget reallocations, accelerated EU packaging waste directive implementations, and feed commodity price shocks beyond historical volatility bands. Forecasts reflect assumptions about Farm to Fork compliance timelines and F-Gas retrofit completion rates that warrant periodic stress-testing of base assumptions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Meat Products
Beef Bouillon Market
Meat Products
Oman Poultry Meat Market
Meat Products
US Meat Market
Meat Products
United States Bacon Market
Meat Products
Global Lab-Based Meat Market
Meat Products
United States Red Meat Market
Meat Products
South Africa Processed Meat Market
Meat Products
Grass Fed Beef Market
Meat Products
Beef Extract Market
Meat Products
Chicken Buckets Market
Meat Products
Europe Meat Products Market
Meat Products
Kosher Beef Market
Meat Products
Middle-East and Africa Animal-Based Meat and Dairy Products Market
Meat Products
Meat-Based FPP Market
Meat Products
Edible Offal Market
Meat Products
Mexico Meat Products Market