
 Saudi Arabia Goat Meat and Cheese Market | 2026-2036
Saudi Arabia Goat Meat and Cheese Market Size, Share, and Industry Trends Forecast 2026-2036
Saudi Arabia Goat Meat and Cheese Market Analytics
Plant-based fat alternatives in processed goat cheese formulations is decoupling traditional butterfat dependency from production costs. Almarai Company leverages its integrated dairy infrastructure to control chilled distribution across the Kingdom. Savencia Fromage & Dairy anchors its Gulf position through specialty cheese expertise adapted to local palates. Al Safi Danone competes on scale in standardized fresh goat milk segments.
Saudi Arabia goat meat and cheese encompasses fresh and processed caprine proteins alongside artisanal and industrial dairy outputs derived from goat milk, typically processed at temperatures between 72°C and 85°C for pasteurization to ensure microbiological safety for human consumption. The category serves protein procurement for household kitchens, restaurant supply chains, and institutional food service across the Kingdom. Fresh meat and goat cheese lead volume contribution within product type segmentation, while specialty stores and supermarkets dominate distribution channel value capture due to refrigeration reliability and consumer trust in provenance verification. The organic price tier shows the fastest expansion trajectory as Saudi consumers prioritize clean-label claims and halal-certified sourcing transparency.
SFDA governs dairy safety standards and slaughterhouse hygiene protocols, while SASO enforces packaging and labeling requirements for domestic and imported goat products. These frameworks elevate compliance costs for smaller herders but create structured market access for certified processors with cold-chain documentation. Stakeholders must monitor evolving halal certification reciprocity agreements and water tariff adjustments affecting feed crop economics in Najd-based farming clusters.
Market Dynamics
SFDA's updated dairy safety protocols are compressing cold-chain compliance timelines for domestic processors while hospitality procurement in Riyadh and Jeddah accelerates goat cheese menu integration. This regulatory tightening intersects with feed-crop water tariff pressures in Najd farming clusters to reshape processor margin structures.
Growth Catalysts
- Central Region consumption concentration:Per-capita goat meat demand in Riyadh Province exceeds all other Saudi provinces, anchoring volume pull for domestic herders and integrated processors.
- SFDA pasteurization mandates:Enforcement of 72°C–85°C thermal processing standards for microbiological safety is standardizing domestic production quality and elevating consumer trust in local provenance.
- Hospitality menu diversification:Restaurant operators across Jeddah and Riyadh are expanding goat cheese procurement for premium positioning in competitive foodservice markets.
Market Restraints
- Feed-crop water cost volatility:Najd-based herders face escalating irrigation tariffs for alfalfa and fodder cultivation, compressing margins at the primary production tier.
- Cold-chain infrastructure gaps:Peripheral provinces lack reliable chilled distribution networks, limiting market access for small-scale processors without Almarai-scale logistics.
- Butterfat cost dependency:Traditional goat cheese formulations remain exposed to milk-fat price swings that plant-based fat alternatives have not yet fully neutralized for artisanal producers.
Strategic Opportunities
- Eastern Province underpenetration:Dammam and Khobar foodservice markets show lower goat protein saturation than Riyadh, creating whitespace for specialty store expansion.
- Organic certification tier:Clean-label and halal-certified sourcing transparency commands premium positioning as Saudi consumers prioritize provenance verification.
- SASO labeling convergence:Unified packaging standards for domestic and imported products reduce compliance fragmentation for multi-source processors.
Industry Challenges
- Veterinary skill scarcity:Caprine health management expertise concentrates in Riyadh-based agricultural universities, leaving peripheral herders dependent on itinerant specialists.
- Halal certification reciprocity delays:Cross-border slaughter protocol recognition with GCC neighbors creates documentation friction for importers seeking streamlined customs clearance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Saudi Arabia Goat Meat and Cheese Market |
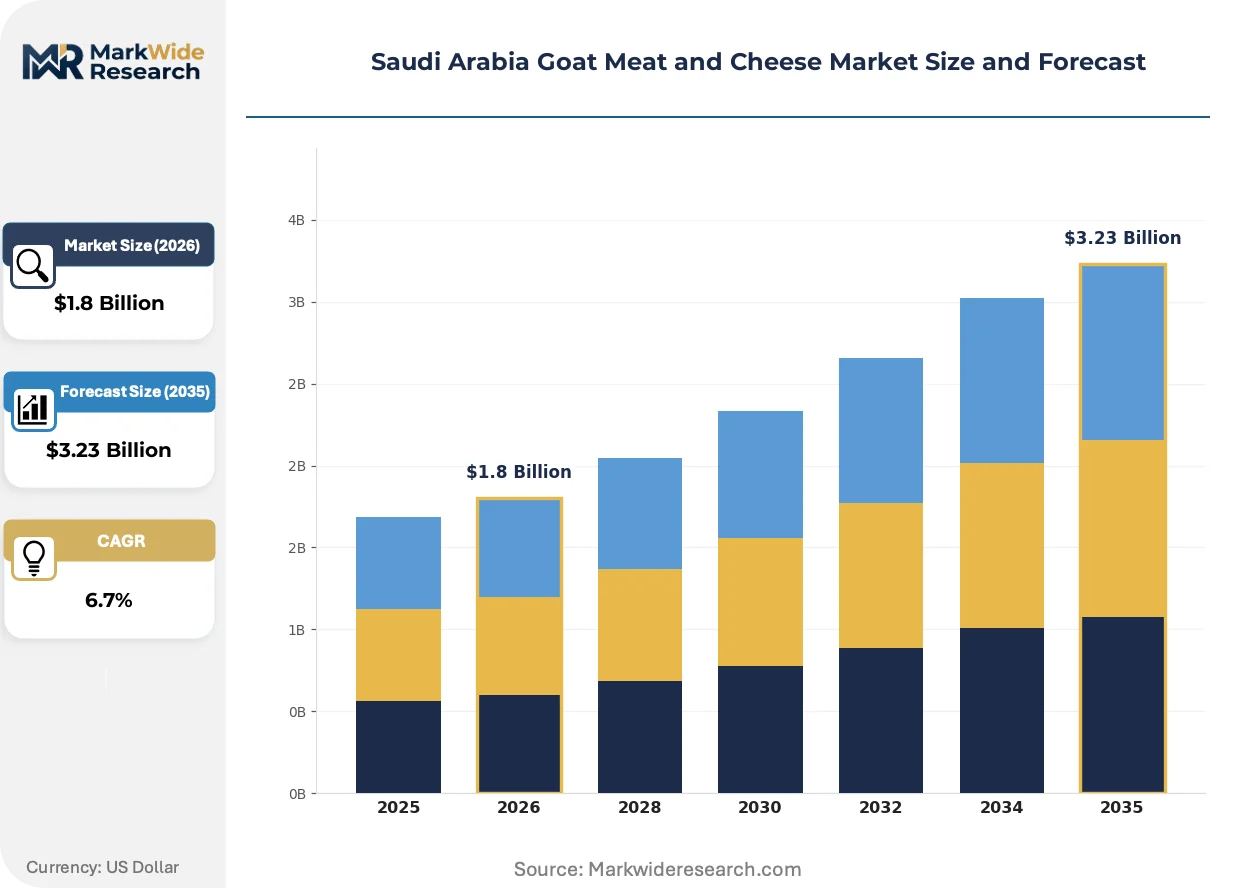
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fresh Meat, Processed Meat, Goat Cheese, Feta Cheese Distribution Channel: Supermarkets, Online Retail, Farmers' Markets, Specialty Stores End User: Households, Restaurants, Cafes, Food Service Price Tier: Premium, Mid-Range, Budget, Organic |
| Companies Covered | Savencia Fromage & Dairy, Al Safi Danone, Almarai Company, Arla Foods, Al-Berri United Food Co. Ltd, Lactalis Group, Al-Kabeer Group, White Gold Goat Dairy, NADEC, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Saudi Arabia Goat Meat and Cheese Market Evolving Landscape
Processing technology and procurement patterns are restructuring competitive advantage across Saudi goat protein value chains. Three forces dominate the current transformation.
High-pressure processing (HPP) is overtaking conventional thermal pasteurization for premium fresh goat cheese segments. Boutique processors in Riyadh's industrial zones are adopting HPP to extend shelf life without flavor degradation. This technology is compressing the window between farm-gate collection and retail placement for temperature-sensitive artisanal products.
SFDA's phased implementation of electronic traceability systems is mandating batch-level documentation from slaughterhouse to retail shelf. Domestic processors must retrofit legacy record-keeping infrastructure or face market access restrictions. Fresh meat distributors in the Central Region are investing earliest due to higher inspection frequency and consumer litigation exposure.
Direct sourcing contracts between hospitality groups and Najd herding cooperatives are displacing traditional auction-market procurement. Restaurant chains in Jeddah now specify breed, feed regimen, and slaughter timing in procurement specifications. This pattern is most visible in premium steakhouse and farm-to-table concepts where menu storytelling requires verifiable supply chain narratives.
Saudi Arabia Goat Meat and Cheese Market Segmentation
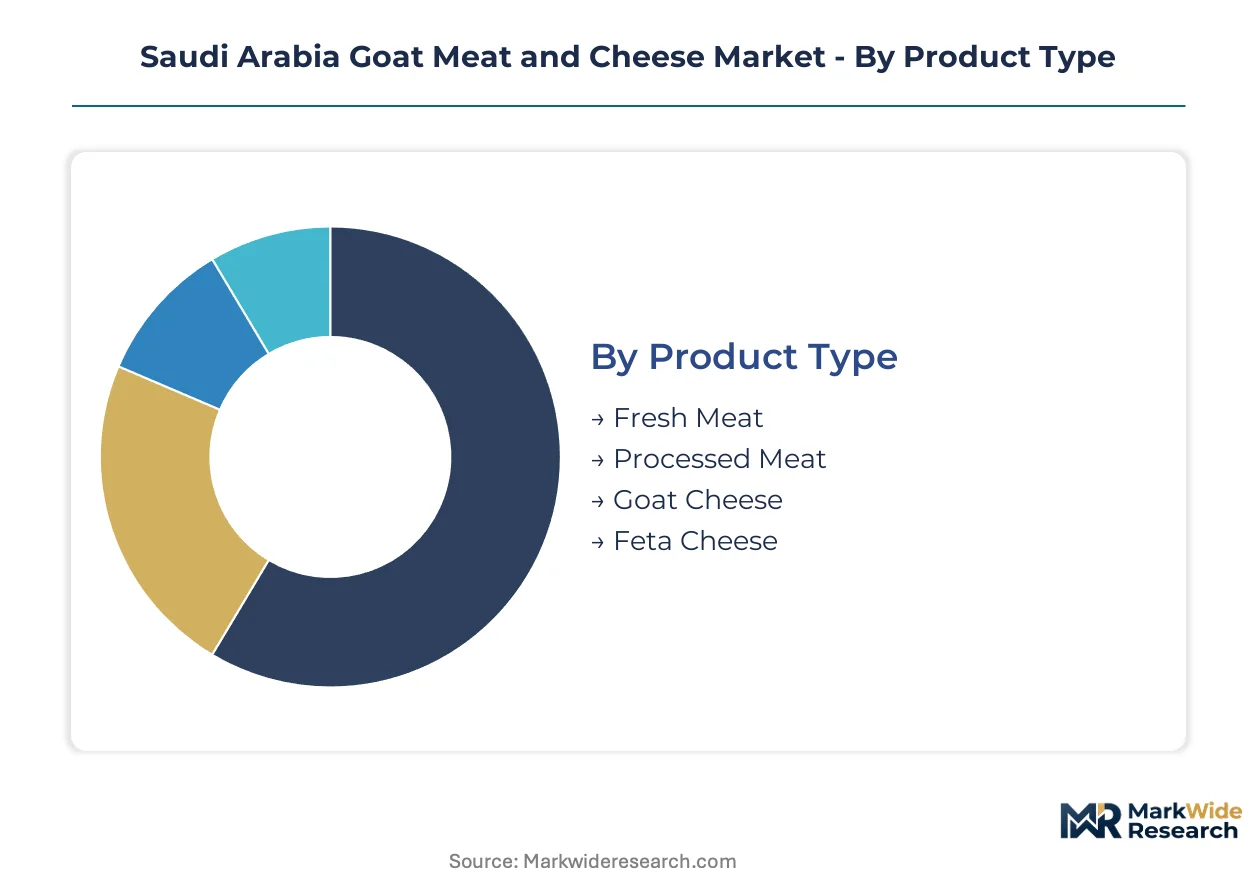
Segmentation in Saudi Arabia's goat protein market reveals how procurement decisions split between price-sensitive household staples and premium hospitality sourcing. Understanding these divides exposes where cold-chain investment and halal certification command pricing power.
Product Type:
Buyers choose based on kitchen application and shelf-life requirements, with fresh formats dominating home cooking and processed alternatives serving institutional scale.
- Fresh Meat:Unprocessed caprine carcasses and cuts sold within 48-72 hours of slaughter, requiring strict SFDA slaughterhouse hygiene compliance. Households in Riyadh Province drive the bulk of procurement, though Najd herders face margin pressure from alfalfa irrigation tariffs.
- Goat Cheese:Pasteurized milk curds processed at 72°C-85°C thermal thresholds, spanning soft chèvre to aged varieties. Hospitality operators across Jeddah and Riyadh are expanding menu integration for premium positioning, with HPP technology extending shelf life for boutique processors.
- Processed Meat:Cured, smoked, or mechanically separated caprine products with extended stability. Industrial kitchens in institutional food service favor these for inventory predictability.
- Feta Cheese:Brined white cheese with crumbly texture, traditionally sheep-dominant but increasingly goat-milk based. Specialty stores in Khobar and Dammam show rising interest as Eastern Province palates diversify.
Volume sits with Fresh Meat; growth tilts toward Goat Cheese.
Distribution Channel:
Channel selection hinges on refrigeration reliability and provenance verification, with trust in cold-chain documentation determining where premium products flow.
- Supermarkets:Temperature-controlled retail networks with SASO-compliant labeling and batch traceability. The Central Region's hypermarket density anchors volume, though peripheral provinces lack equivalent chilled distribution reach.
- Specialty Stores:Curated outlets emphasizing artisanal sourcing and halal certification transparency. Riyadh's upscale districts concentrate demand for organic-tier goat cheese with verifiable Najd cooperative provenance.
- Online Retail:E-commerce platforms with last-mile cold-chain partnerships. Jeddah's tech-forward consumer base is adopting fastest for recurring fresh meat subscriptions.
- Farmers' Markets:Direct herder-to-consumer sales with minimal intermediation. Seasonal concentration around religious holidays drives spikes, though SFDA electronic traceability mandates are raising compliance barriers.
Supermarkets capture transaction volume; Specialty Stores are climbing the fastest on margin expansion.
End User:
End-use segmentation tracks preparation complexity and procurement scale, from individual household portions to centralized restaurant supply.
- Households:Individual consumers purchasing for home cooking, with preference skewing toward fresh meat in Riyadh Province and processed formats where cold-chain gaps persist. Budget and mid-range tiers dominate this segment.
- Restaurants:Full-service dining establishments specifying breed, feed regimen, and slaughter timing in direct Najd cooperative contracts. Premium steakhouses and farm-to-table concepts in Jeddah lead this procurement pattern.
- Food Service:Institutional caterers and centralized kitchen operations requiring standardized portioning and extended shelf stability. Processed meat and feta cheese see concentration here.
- Cafes:Coffee-focused establishments with limited food preparation, favoring pre-portioned goat cheese for pastry and sandwich applications. Urban Riyadh and Jeddah clusters show highest adoption.
Households anchor absolute volume; Restaurants show the steepest expansion trajectory on menu diversification.
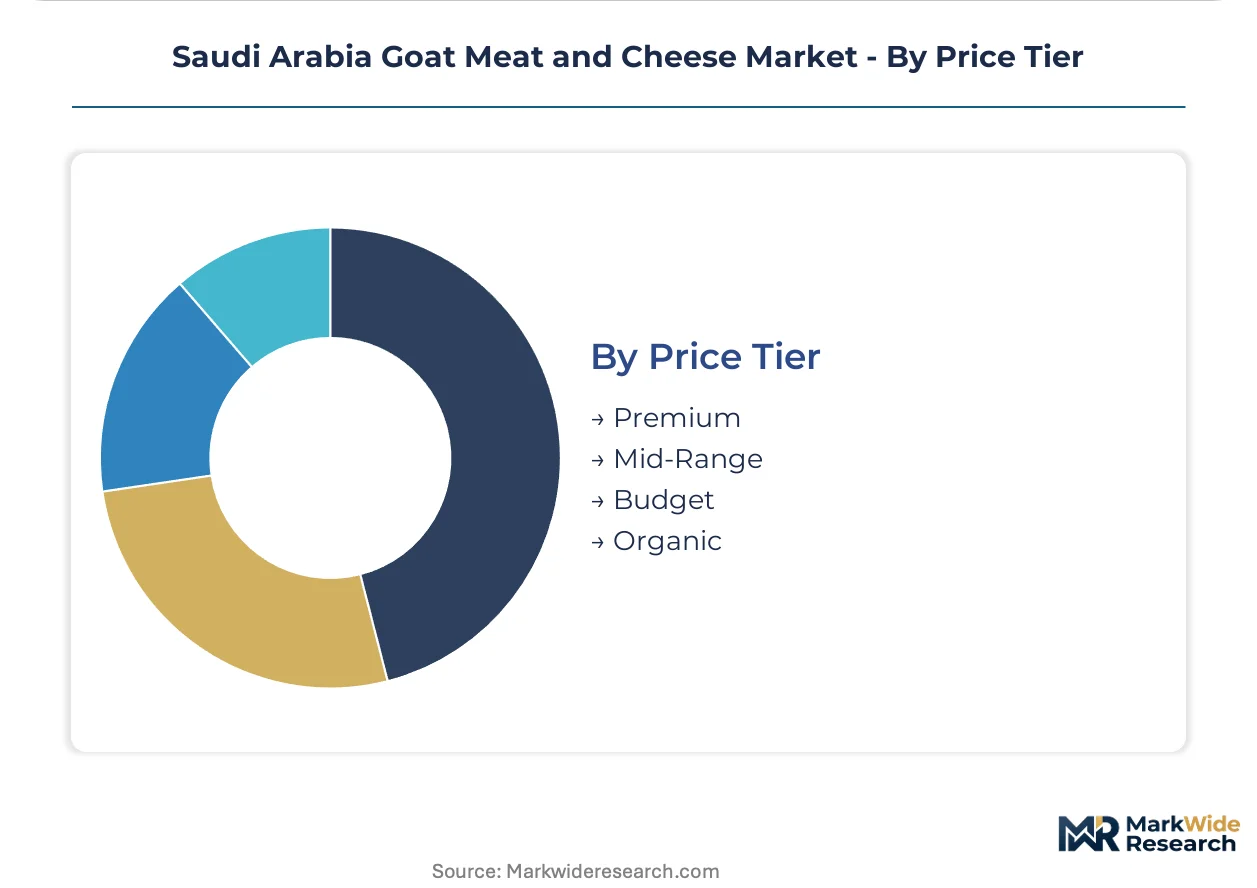
Price Tier:
Pricing stratification reflects certification grade and supply chain transparency, with organic premiums widening as consumer scrutiny intensifies.
- Organic:Products carrying third-party clean-label and halal-certified sourcing verification. Saudi consumers prioritizing provenance transparency are driving premium positioning, with specialty stores capturing margin.
- Premium:High-grade fresh meat and artisanal goat cheese with documented Najd herding cooperative origin. Hospitality procurement in Riyadh and Jeddah concentrates here for menu storytelling requirements.
- Mid-Range:Standardized products meeting SFDA pasteurization and hygiene baselines without extensive provenance documentation. Supermarket distribution dominates this tier.
- Budget:Price-optimized offerings with minimal processing and shorter shelf windows. Peripheral provinces with cold-chain infrastructure gaps see concentration here.
Mid-Range holds current volume share; Organic is gaining share fastest on consumer preference shifts.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Per-capita goat meat consumption concentrates in Riyadh Province above all other Saudi provinces, anchoring domestic demand pull for Najd-based herders and integrated processors. Hospitality procurement in Jeddah and Khobar is accelerating goat cheese menu integration as restaurant operators compete on premium positioning. SFDA enforcement of dairy safety protocols and electronic traceability mandates is reshaping compliance requirements across all production zones.
Riyadh
Household kitchens and restaurant supply chains drive the bulk of fresh meat procurement, with hypermarket density supporting volume distribution. SFDA pasteurization mandates at 72°C–85°C thermal thresholds standardize domestic production quality for processors serving this zone. The Riyadh industrial corridor hosts boutique cheese operations adopting high-pressure processing technology to extend shelf life without flavor degradation.
Eastern Province
Dammam and Khobar foodservice markets show lower goat protein saturation than the Central Region, creating whitespace for specialty store expansion. Water tariff adjustments for alfalfa irrigation affect feed-crop economics in peripheral farming clusters supplying this zone. Direct sourcing contracts between hospitality groups and herding cooperatives are displacing traditional auction-market procurement in premium steakhouse segments.
Western Region
Jeddah's tech-forward consumer base is adopting online retail fastest for recurring fresh meat subscriptions with last-mile cold-chain partnerships. SASO labeling requirements for domestic and imported products elevate compliance costs for smaller herders seeking market access. Farm-to-table concepts in upscale districts specify breed, feed regimen, and slaughter timing in procurement specifications for menu storytelling.
NEOM Northwest
Emerging urban development is attracting early-stage food infrastructure investment with cold-chain reliability requirements. The zone lacks established veterinary expertise for caprine health management, creating dependency on itinerant specialists from Riyadh-based agricultural universities. Hospitality pre-commitments for premium goat cheese supply are testing processor capacity to meet documentation standards for verifiable provenance.
Saudi Arabia Goat Meat and Cheese Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated dairy conglomerates controlling chilled distribution networks and artisanal processors competing on provenance verification. The market structure tilts toward scale-driven players with captive logistics infrastructure, though boutique operations capture margin in organic certification tiers. Three archetypes dominate: vertically integrated dairy majors with Kingdom-wide cold-chain coverage, cooperative-affiliated herders supplying direct hospitality contracts, and import-reliant distributors bridging specialty store gaps. Competitive moves concentrate on backward integration into Najd herding cooperatives and technology licensing for high-pressure processing systems.
Within the integrated dairy tier, Almarai Company leverages its distribution infrastructure to control retail placement across temperature-sensitive categories. Savencia Fromage & Dairy anchors its Gulf position through specialty cheese expertise adapted to local hospitality procurement requirements. Al Safi Danone occupies the scale-driven end of standardized fresh goat milk segments, competing on volume throughput rather than artisanal positioning. These three represent divergent strategic bets on how Saudi consumer preferences for halal-certified sourcing transparency will evolve across price tiers.
| Leading Market Players |
|---|
| Savencia Fromage & Dairy |
| Al Safi Danone |
| Almarai Company |
| Arla Foods |
| Al-Berri United Food Co. Ltd |
| Lactalis Group |
| Al-Kabeer Group |
| White Gold Goat Dairy |
| NADEC |
| Others |
Value Network & Pricing Analysis
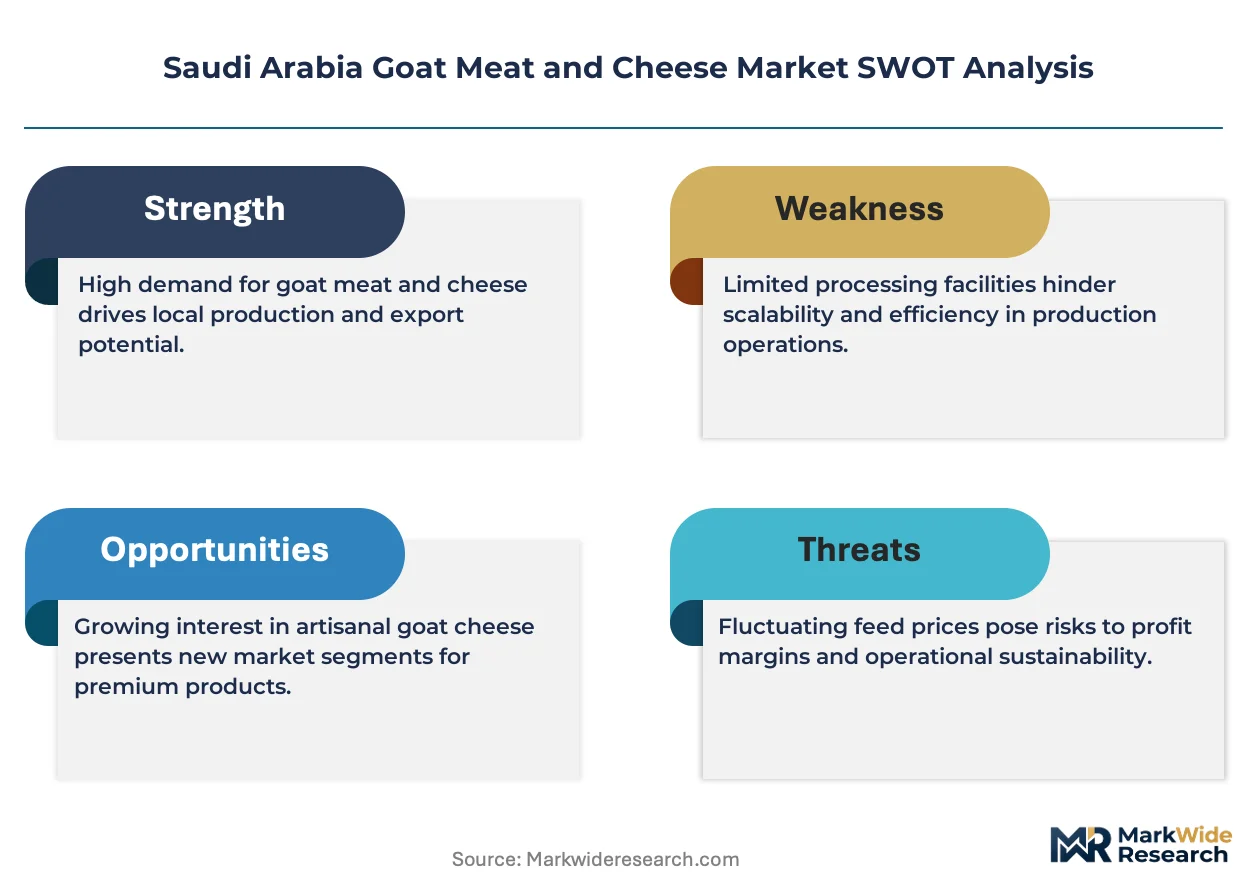
Organic-halal certification divergence separates premium goat cheese from commodity fresh meat across Saudi Arabia, with the former commanding margin multiples through verifiable Najd cooperative provenance while the latter faces compression from alfalfa irrigation tariffs and auction-market liquidity. This bifurcation feeds directly into supply chain configuration: certified processors invest in Almarai-scale cold-chain documentation to capture hospitality procurement premiums, while herders without such infrastructure remain tethered to spot-market volatility.
Pricing Analysis
Volume-margin splits sharply across the Saudi goat protein landscape, with budget-tier fresh meat transacting on thin spreads in Riyadh's hypermarket channels while organic goat cheese achieves substantial markups through specialty store positioning. Pricing stratifies across premium, standard, and economy tiers based on SFDA traceability compliance depth and halal certification reciprocity documentation. Cost compression in the budget tier is intensifying because Najd water tariff adjustments for feed-crop irrigation are transferring upstream to processor gate prices. Households in peripheral provinces exhibit highest price sensitivity due to cold-chain infrastructure gaps, whereas Jeddah hospitality groups demonstrate lowest sensitivity when procurement specifications include breed and feed regimen verification.
Supply Chain Analysis
Dual-sourcing requirements from hospitality procurement teams are mandating multi-supplier qualification across Najd herding cooperatives and integrated dairy majors, reducing single-source dependency for premium goat cheese volumes. Geographic supply concentration rests on Saudi domestic production for fresh meat, with import reliance from Australia and New Zealand for chilled goat carcass shortfalls during religious demand spikes. Raw material dependencies center on alfalfa fodder cultivation, veterinary pharmaceutical inputs for caprine health management, and HPP technology licensing for boutique cheese processors. Single-source vulnerability concentrates in the Central Region's chilled distribution backbone, where Almarai-scale logistics capacity remains limited to a handful of operators. Distribution runs through supermarket networks with SASO-compliant batch traceability for mid-range tiers, while specialty stores and direct hospitality contracts capture premium flows.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
SFDA's phased electronic traceability mandates are constructing a cost-of-compliance moat that favors incumbent processors with legacy infrastructure retrofit capacity, effectively raising barrier-to-entry thresholds for unaffiliated herders and import-reliant distributors lacking batch-level documentation systems.
For Market Incumbents: Deploy cold-chain capacity expansion in the Eastern Province to preempt specialty store whitespace capture, while accelerating backward integration into Najd herding cooperatives to secure verifiable provenance for hospitality direct-sourcing contracts. Threat from boutique HPP-equipped processors in Riyadh's industrial corridor demands defensive certification investment in organic-halal tier positioning. Channel control through captive supermarket placement agreements remains the priority lever for volume defense. For New Entrants and Emerging Players: Capture Eastern Province foodservice underpenetration in Dammam and Khobar through farm-to-table restaurant partnerships specifying breed and feed regimen transparency, bypassing auction-market procurement patterns dominant in the Central Region. The most penetrable segment sits with premium steakhouse concepts seeking menu storytelling differentiation. Go-to-market execution should emphasize direct herding cooperative contracts with documented slaughter timing compliance. For Investors and Strategic Acquirers: Re-rating potential sits with mid-scale processors possessing HPP technology licensing and existing SFDA traceability infrastructure given accelerating hospitality procurement requirements for extended-shelf-life artisanal products. Long-term viability over the five-to-ten year window favors operators with upstream cooperative affiliation and downstream cold-chain partnerships. The signal to watch is SFDA enforcement intensity on electronic batch documentation, which would accelerate consolidation toward compliant players.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Najd Herding Cooperatives | Captures verifiable provenance documentation required by Jeddah hospitality procurement specifications. |
| High-Pressure Processing Technology Licensing | Extends shelf life for artisanal goat cheese without thermal degradation, unlocking premium positioning. |
| Eastern Province Cold-Chain Infrastructure Buildout | Addresses distribution gaps preventing small-scale processor market access outside Central Region. |
| Organic-Halal Certification Investment | Commands margin multiples as Saudi consumers prioritize clean-label sourcing transparency verification. |
| Direct Hospitality Sourcing Contract Negotiation | Displaces auction-market procurement with breed-specific, feed-regimen-verified supply agreements. |
Research Methodology
SFDA regulatory filings, SASO packaging standards documentation, and Saudi customs trade records formed the secondary backbone, supplemented by primary interviews with Najd herding cooperative managers, hospitality procurement directors in Riyadh and Jeddah, boutique cheese processors adopting HPP systems, and supermarket category buyers managing chilled distribution networks. Bottom-up and top-down triangulation cross-validated volume estimates across these stakeholder perspectives.
Bottom-up modeling anchored the analytical lens, with top-down macroeconomic cross-checks applied across the analysis window. Segmentation dimensions modeled include product type, distribution channel, end user, and price tier, with additional granularity on regional consumption patterns within Saudi Arabia. CAGRs were derived from trend extrapolation of historical procurement data and regulatory implementation timelines. Industry-specific forecast inputs incorporated water tariff adjustment scenarios for Najd alfalfa cultivation and SFDA traceability mandate compliance adoption curves.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to halal certification reciprocity negotiations with GCC neighbors and veterinary skill migration patterns from Riyadh-based agricultural universities. Deviation in SFDA enforcement intensity on electronic traceability would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Meat Products
North America Processed Poultry Meat Market
Meat Products
Canned Chicken Market
Meat Products
Mexico Meat Products Market
Meat Products
Asia-Pacific Red Meat Market
Meat Products
India Edible Meat Market
Meat Products
Saudi Arabia Red Meat Market
Meat Products
Saudi Arabia Edible Meat Market
Meat Products
Canned Pork Market
Meat Products
United States Frozen Meat Market
Meat Products
Vegan Meatball Market
Meat Products
Reconstituted Meat Market
Meat Products
Chicken Fat Market
Meat Products
Brisket Market
Meat Products
Beef Bouillon Market
Meat Products
Global Poultry Meat Market
Meat Products
Meat Tenderizer Market