
 India Poultry Meat Market | 2026-2036
India Poultry Meat Market Size, Share, and Industry Trends Forecast 2026-2036
India Poultry Meat Market Foresight
Contract labor shortages in live-bird handling and processing are redrawing competitive boundaries across the India poultry meat sector. Suguna Foods Private Limited leverages its vertically integrated contract farming network to secure steady broiler supply across southern states. Godrej Agrovet Limited anchors its position through advanced feed-milling capacity and breeder farm infrastructure. Venky's (India) sustains market presence via integrated hatchery-to-retail operations and specialized vaccine production.
India poultry meat encompasses broiler chicken, layer spent hens, duck, and turkey carcasses processed for human consumption, with broilers typically reaching processing weight within 35-42 days through controlled-environment farming. The product serves as the dominant animal protein source for households, restaurants, and food processors seeking cost-effective, halal-compliant meat with standardized cut specifications. Broilers occupy the volume core of the market, while foodservice channels capture expanding margin pools as quick-service chains scale standardized procurement. Vacuum packaging and tray packs are gaining traction in modern retail as cold-chain reliability improves in tier-two cities.
FSSAI antibiotic residue standards, the Bureau of Indian Standards (BIS) grading protocols, and state-level livestock development board regulations collectively shape product safety benchmarks and market access conditions for poultry integrators. Compliance costs favor large-scale operations with in-house veterinary and laboratory capabilities, accelerating consolidation among organized players. Stakeholders must monitor evolving state-level slaughterhouse licensing requirements and cold-chain subsidy programs to anticipate capacity expansion timing and geographic redistribution of processing assets.
Market Dynamics
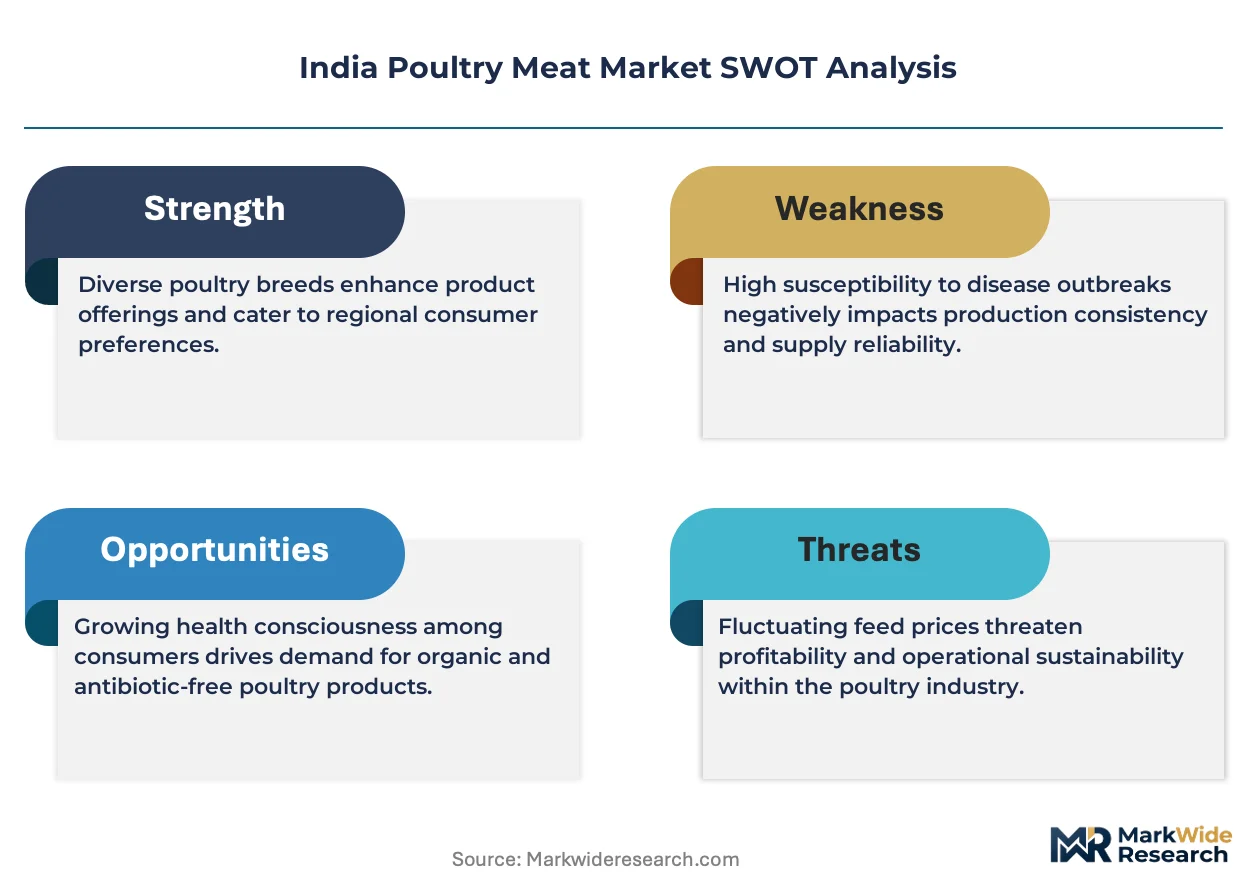
FSSAI antibiotic residue limits are compressing production timelines across the India poultry meat sector, forcing integrators to rebuild veterinary protocols and laboratory infrastructure ahead of enforcement deadlines.
Growth Catalysts
- Urban protein transition:Quick-service restaurants in Mumbai, Hyderabad, and Bangalore are scaling standardized broiler procurement as household consumption shifts from red meat to poultry.
- Cold-chain subsidy programs:State-level livestock development boards in Maharashtra and Telangana are financing refrigerated transport capacity, reducing post-harvest losses for contract farming networks.
- Controlled-environment farming:Automated climate systems in breeder operations are shortening broiler grow-out cycles while improving feed conversion ratios.
Market Restraints
- Maize and soybean meal volatility:Feed input costs swing with monsoon-dependent domestic harvests and import parity pricing, squeezing integrator margins during drought cycles.
- Grandparent stock import dependence:India's breeder pyramid relies on constrained supply lines from the United States and Europe, creating genetic supply risk during trade disruptions.
- Slaughterhouse licensing fragmentation:State-level municipal authorities operate divergent approval timelines, blocking centralized processing scale-up in Uttar Pradesh and Bihar.
Strategic Opportunities
- Untapped Northeast corridor:Assam and Meghalaya show rising per-capita poultry consumption without organized cold-chain presence, creating first-mover advantages for integrators building regional hatcheries.
- Halal-certified export channels:Middle Eastern buyers are qualifying Indian slaughterhouses under new FSSAI-export alignment protocols, opening premium-margin segments.
- Blockchain traceability integration:Retail chains in Pune and Chennai are piloting farm-to-fork tracking systems, rewarding compliant integrators with shelf-space guarantees.
Industry Challenges
- Veterinary pathology talent scarcity:Qualified poultry disease specialists concentrate around Hyderabad and Bangalore, leaving northern contract farms dependent on itinerant consultants.
- Legacy wet-market infrastructure:Live-bird auction yards in tier-three cities resist cold-chain conversion, trapping volume in low-margin, unorganized channels.
- Biosecurity capex burdens:FSSAI-mandated laboratory upgrades and all-in-all-out housing systems require capital deployment that smallholders cannot access.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Poultry Meat Market |
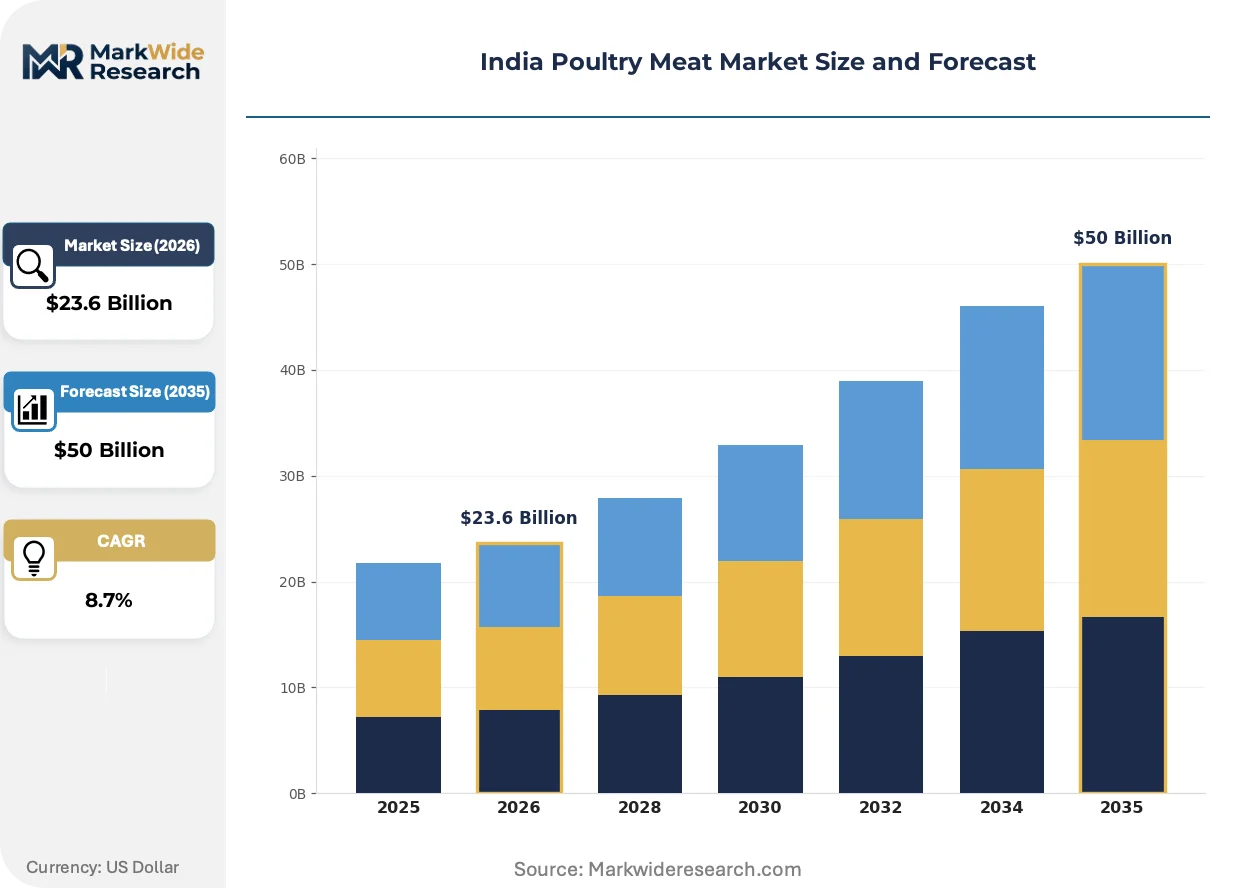
| Market Size in 2026 | $23.6 Billion |
| Market Size in 2035 | $50 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Broilers, Layers, Ducks, Turkeys Distribution Channel: Retail, Wholesale, E-commerce, Foodservice End User: Households, Restaurants, Catering Services, Food Processors Packaging Type: Vacuum Pack, Tray Pack, Canned, Bulk |
| Companies Covered | Skylark Hatcheries Private Limited, Srinivasa Farms Pvt. Ltd., Suguna Foods Private Limited, IB Group, VH Group, Godrej Agrovet Limited, Sneha Farms Pvt. Ltd., Simran Farms Limited, Venky's (India), Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Poultry Meat Market Shifts & Advancements
Automation and regulatory digitization are compressing operational timelines across Indian poultry operations, while shifting procurement patterns reconfigure buyer-supplier power balances.
Automated weighing and grading systems are replacing manual bird handling in large processing plants. Venky's and Godrej Agrovet are deploying computer-vision sorting at their Telangana facilities, cutting labor exposure to live-bird handling. This hardware is miniaturizing to serve mid-scale integrators in tier-two cities, democratizing precision that previously required enterprise-scale capex.
FSSAI's 2024 antibiotic residue surveillance expansion is mandating batch-level testing documentation. Integrators must now maintain electronic veterinary records traceable to individual feed mill batches. Southern states with pre-existing laboratory infrastructure are absorbing compliance costs faster than northern regions, widening the organized-unorganized competitive gap.
Quick-service chains are consolidating supplier relationships around multi-year volume commitments with quality-price indexing. KFC India and Domino's Pizza are reducing their active vendor counts in favor of dedicated supply agreements with integrators owning captive breeder farms. This concentration is most visible in Karnataka, where two integrators now supply over half of Bangalore's foodservice channel volume.
India Poultry Meat Market Segmentation
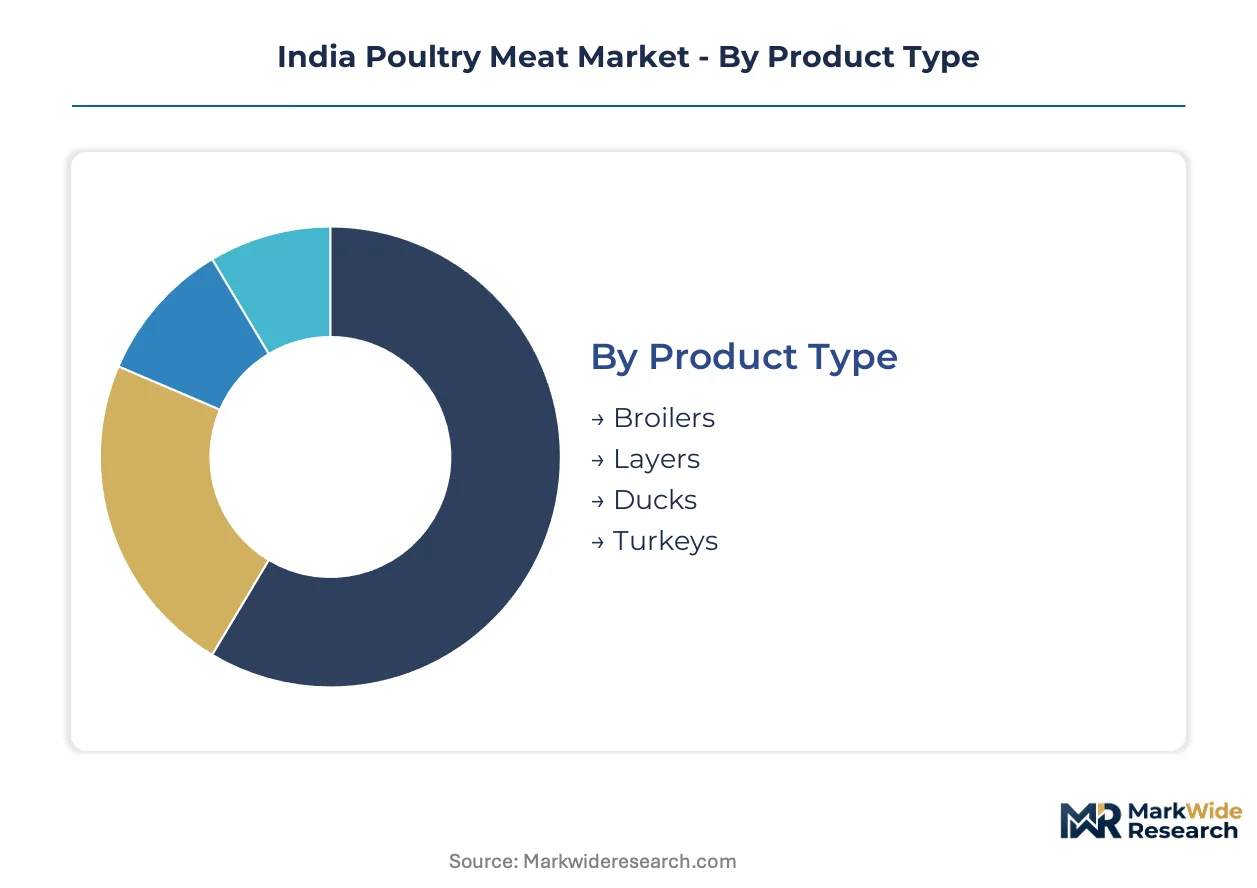
Segmentation in the India poultry meat market reveals how production systems, procurement channels, and consumption formats diverge across state-level regulatory environments and urbanization gradients. Understanding these divisions exposes where cold-chain investments and FSSAI compliance costs concentrate competitive advantage.
Product Type:
Domestic consumption dominates broiler and layer segments, while duck and turkey production serve niche export corridors and premium urban retail.
- Broilers:Birds raised to processing weight in 35-42 day cycles through controlled-environment farming, supplying standardized halal-compliant cuts to quick-service chains in Mumbai, Hyderabad, and Bangalore. Maharashtra and Telangana integrators capture margin through captive breeder farms and automated climate systems.
- Layers:Spent hens processed for lower-value meat applications, with demand concentrating in institutional catering and processed food manufacturing. Karnataka's layer belt around Bangalore feeds both domestic households and neighboring state wholesale markets.
- Ducks:Concentrated in Kerala and West Bengal wet markets, with limited organized processing penetration.
- Turkeys:Seasonal demand from urban hotels and expatriate consumers, negligible contract farming integration.
Broilers hold the largest share; momentum sits with layer-integrated operations as spent-hen processing upgrades expand.
Distribution Channel:
Channel structure reflects the tension between legacy wet-market infrastructure and capital-intensive cold-chain buildout across tier-two cities.
- Retail:Modern trade formats in Pune and Chennai are piloting blockchain traceability systems, rewarding FSSAI-compliant integrators with shelf-space guarantees and multi-year volume commitments.
- Wholesale:Live-bird auction yards in tier-three cities resist cold-chain conversion, trapping volume in low-margin unorganized channels dependent on itinerant labor.
- E-commerce:Emerging in Bangalore and Delhi NCR with same-day delivery promises, constrained by last-mile refrigeration gaps.
- Foodservice:Quick-service chains are consolidating supplier relationships around dedicated supply agreements with integrators owning captive breeder farms, most visible in Karnataka where two integrators supply over half of Bangalore's channel volume.
Wholesale channels still move the most tonnage; foodservice is climbing the fastest as procurement standardization accelerates.
End User:
User categories map directly to protein format preferences and price sensitivity gradients across India's urban hierarchy.
- Households:Dominant volume sink, shifting from red meat to poultry in metropolitan areas as per-capita income rises and cooking time constraints tighten.
- Restaurants:Quick-service chains in Mumbai, Hyderabad, and Bangalore scale standardized broiler procurement with quality-price indexing clauses.
- Catering Services:Institutional buyers in southern states leverage pre-existing laboratory infrastructure to absorb FSSAI compliance costs faster than northern competitors.
- Food Processors:Demand standardized cut specifications for further-manufactured products, driving backward integration into captive processing capacity.
Households retain the dominant share; food processors are expanding most quickly as further-manufactured poultry applications multiply.
Packaging Type:
Packaging evolution tracks cold-chain reliability improvements and retail format modernization in state capitals beyond the traditional southern belt.
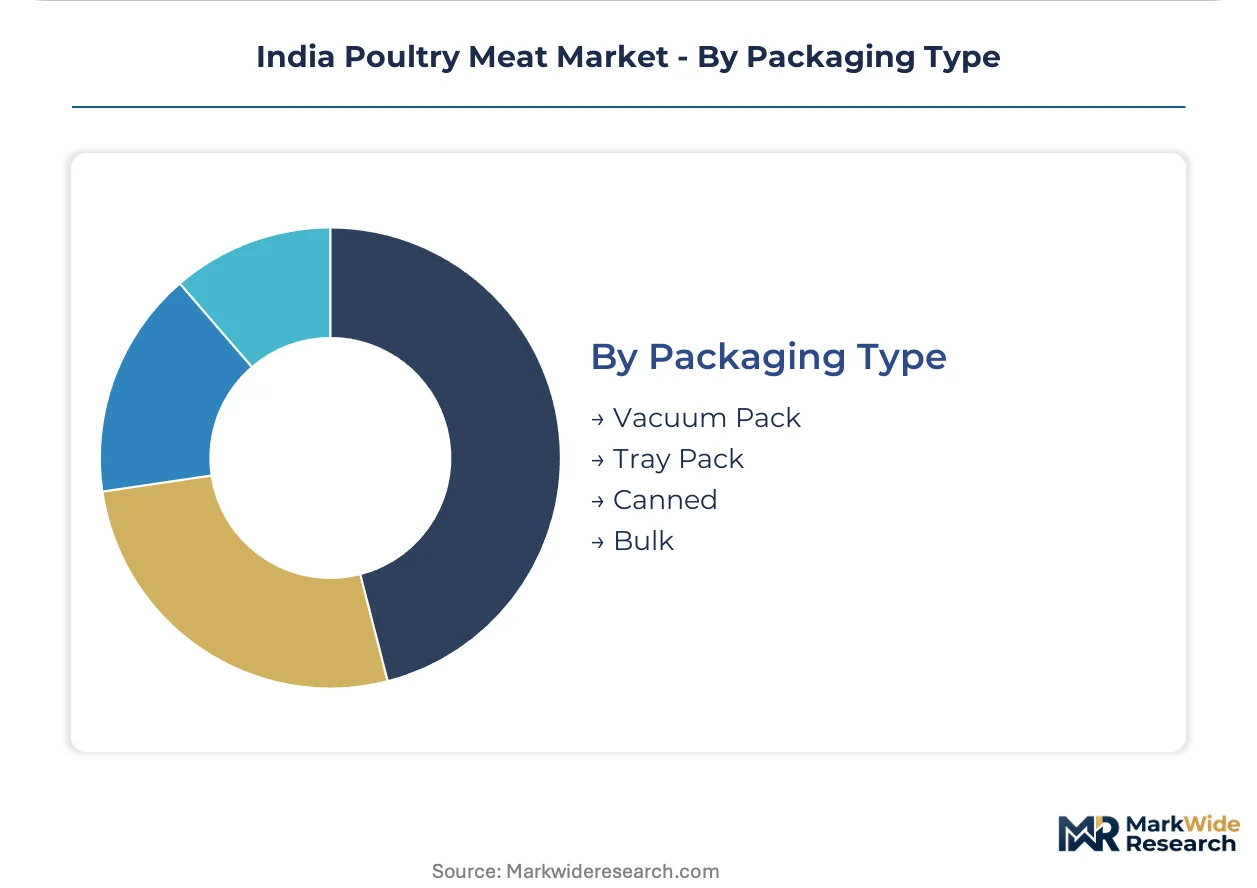
- Vacuum Pack:Extending shelf life for modern retail penetration in tier-two cities where refrigerated display case installation is accelerating.
- Tray Pack:Gaining traction in organized retail as consumer preference shifts toward pre-portioned, ready-to-cook formats in Pune and Chennai pilot programs.
- Canned:Limited to military and institutional procurement, constrained by consumer taste preferences.
- Bulk:Dominating wholesale and foodservice channels with minimal processing overhead, vulnerable to post-harvest loss in unrefrigerated transport.
Bulk packaging commands volume leadership; vacuum and tray formats together represent the steepest expansion trajectory as cold-chain subsidies reshape distribution economics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Maharashtra households favor pre-cut broiler portions from modern retail, while Telangana and Karnataka still route significant volume through live-bird wet markets, creating divergent cold-chain investment requirements across western and southern belts.
Maharashtra
Mumbai's quick-service chains drive standardized broiler procurement with strict halal-compliance protocols. The state livestock development board finances refrigerated transport capacity under cold-chain subsidy programs. Pune integrators pilot blockchain traceability systems, rewarding FSSAI-compliant suppliers with multi-year shelf-space guarantees.
Telangana
Hyderabad's foodservice density attracts dedicated supply agreements from integrators with captive breeder farms. FSSAI antibiotic residue surveillance expansion mandates batch-level testing documentation traceable to individual feed mill batches. Automated climate systems in Ranga Reddy district shorten broiler grow-out cycles while improving feed conversion ratios.
Karnataka
Bangalore's quick-service consolidation leaves two integrators supplying over half of foodservice channel volume. State-level laboratory infrastructure absorbs compliance costs faster than northern competitors. The layer belt around Bangalore feeds domestic households and neighboring state wholesale markets with spent-hen processing upgrades.
Tamil Nadu
Chennai retail chains pilot farm-to-fork tracking systems for vacuum-packed broiler portions. Contract farming networks cluster around urban consumption centers with organized cold-chain presence. Integrators deploy computer-vision sorting facilities to cut labor exposure to live-bird handling.
West Bengal
Kolkata wet markets resist cold-chain conversion, trapping volume in low-margin unorganized channels dependent on itinerant labor. Duck production concentrates in local wet markets with limited organized processing penetration. State-level municipal authorities operate divergent slaughterhouse approval timelines blocking centralized scale-up.
India Poultry Meat Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with scale advantages concentrating around captive breeder farms and in-house feed-milling capacity. The organized segment consolidates as FSSAI compliance costs favor operations with dedicated veterinary and laboratory capabilities. Three archetypes dominate: vertically integrated integrators controlling hatchery-to-retail operations, feed-focused conglomerates with backward integration into breeding stock, and regional specialists leveraging contract farming networks in single-state strongholds. Competitive dynamics center on multi-year volume commitments with quality-price indexing and geographic expansion through greenfield hatchery deployment.
Among southern-integrated specialists, Suguna Foods Private Limited and Venky's (India) exemplify the hatchery-to-retail archetype, while Godrej Agrovet Limited represents the diversified agribusiness model with feed-milling and breeder infrastructure spanning multiple states. These three anchors illustrate how compliance-ready laboratory capabilities and captive genetic supply lines are separating organized leaders from fragmented wet-market competitors.
| Leading Market Players |
|---|
| Skylark Hatcheries Private Limited |
| Srinivasa Farms Pvt. Ltd. |
| Suguna Foods Private Limited |
| IB Group |
| VH Group |
| Godrej Agrovet Limited |
| Sneha Farms Pvt. Ltd. |
| Simran Farms Limited |
| Venky's (India) |
| Others |
Supply & Pricing Matrix
Thirty-five to forty-two day broiler grow-out cycles compress inventory turns and tether pricing power to feed mill batch traceability under FSSAI surveillance expansion. Southern integrators with captive breeder farms extract margin premiums through multi-year offtake agreements, while northern contract farms face spot-market exposure to maize and soybean meal volatility.
Pricing Analysis
Contract-based long-term offtake dominates procurement between organized integrators and quick-service chains, with quality-price indexing clauses protecting margin during input cost spikes. Price differentiation hinges on FSSAI certification tier and captive breeder farm ownership, separating premium-compliant suppliers from economy-tier wet-market traders. Cost compression in the wholesale channel intensifies as state-level cold-chain subsidies reshape distribution economics. Households in tier-three cities show highest price sensitivity, while foodservice buyers in Bangalore and Mumbai absorb premiums for standardized halal-compliant cuts.
Supply Chain Analysis
Days-of-inventory compression at Hyderabad processing facilities reflects automated climate systems shortening grow-out cycles and reducing working capital requirements. Supply concentrates in Maharashtra, Telangana, and Karnataka, where contract farming networks cluster around urban consumption centers. The chain draws from grandparent stock imports, domestic maize harvests, and soybean meal shipments, exposing integrators to genetic supply risk during trade disruptions and monsoon-dependent feed input swings. Distribution runs through wholesale live-bird auction yards resisting cold-chain conversion, though modern retail formats in Pune and Chennai are piloting blockchain-tracked vacuum packs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The India poultry meat market is navigating a cyclical recovery as FSSAI antibiotic residue enforcement compresses production timelines and accelerates consolidation toward compliance-ready organized players.
For Market Incumbents: Secure captive breeder farm capacity to insulate margin from grandparent stock import disruptions and genetic supply risk. Deepen backward integration into automated climate systems and in-house veterinary laboratories to absorb batch-level testing documentation costs faster than fragmented wet-market competitors. Channel control through dedicated supply agreements with quick-service chains anchors volume visibility against spot-market volatility. For New Entrants and Emerging Players: Differentiate on halal-certified export channel development targeting Middle Eastern buyers qualifying Indian slaughterhouses under new FSSAI-export alignment protocols. Target the untapped Northeast corridor in Assam and Meghalaya, where rising per-capita poultry consumption lacks organized cold-chain presence. A first-mover greenfield hatchery deployment with regional contract farming networks captures margin before incumbent geographic expansion. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified agribusiness conglomerates seeking to monetize non-core poultry assets amid compliance cost concentration. Mid-scale integrators with pre-existing laboratory infrastructure in southern states offer viable acquisition profiles for platform consolidation. Watch state-level livestock development board subsidy announcements as inflection indicators for capacity expansion timing and geographic redistribution of processing assets.| Strategic Initiative | Industry Significance |
|---|---|
| Captive Breeder Farm Expansion | Reduces genetic supply risk from constrained grandparent stock import lines. |
| FSSAI Laboratory Infrastructure Investment | Enables batch-level antibiotic residue testing documentation traceable to feed mill batches. |
| Blockchain Traceability Integration | Rewards compliant integrators with shelf-space guarantees in modern retail chains. |
| Halal-Certified Export Channel Development | Opens premium-margin segments with Middle Eastern buyers under aligned protocols. |
| Automated Climate System Deployment | Shortens broiler grow-out cycles while improving feed conversion ratios in breeder operations. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with poultry integrator executives, veterinary laboratory directors, quick-service chain procurement managers, and state livestock development board officials; and secondary validation through FSSAI regulatory filings, Bureau of Indian Standards grading protocols, customs trade data on grandparent stock imports, and cold-chain subsidy program disclosures. Bottom-up volume modeling from state-level processing capacity and top-down demand triangulation from urban consumption center surveys were cross-referenced for convergence.
Across the projection horizon, the analytical framework modeled segmentation dimensions including product type, distribution channel, end user, packaging format, and state-level regulatory environment. CAGRs were derived from trend extrapolation of contract farming network expansion, quick-service chain procurement standardization, and cold-chain infrastructure buildout trajectories. Forecast inputs incorporated feed input cost volatility patterns, FSSAI enforcement timeline assumptions, and grandparent stock import supply line stability.
The analysis sits within stated boundaries; outcomes outside sustained monsoon-dependent maize harvest levels, stable grandparent stock import channels, and consistent FSSAI enforcement timelines would require recalibration. Forecasts reflect documented assumptions regarding state-level subsidy program continuity and quick-service chain penetration rates. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Meat Products
Meat Ingredients Market
Meat Products
Beef Jerky Market
Meat Products
Edible Offal Market
Meat Products
United States Animal Protein Market
Meat Products
Dehydrated Meat Products Market
Meat Products
Grassfed Jerky Market
Meat Products
United States Poultry Meat Market
Meat Products
Canned Chicken Market
Meat Products
Pork Belly Meat Market
Meat Products
Organic Lamb Market
Meat Products
North America Red Meat Market
Meat Products
Grass Fed Beef Market
Meat Products
Shark Meat Market
Meat Products
Meat Packaging Market
Meat Products
Germany Meat Products Market
Meat Products
United States Bacon Market