
 Oman Poultry Meat Market | 2026-2036
Oman Poultry Meat Market Size, Share, and Industry Trends Forecast 2026-2036
Oman Poultry Meat Market Insights
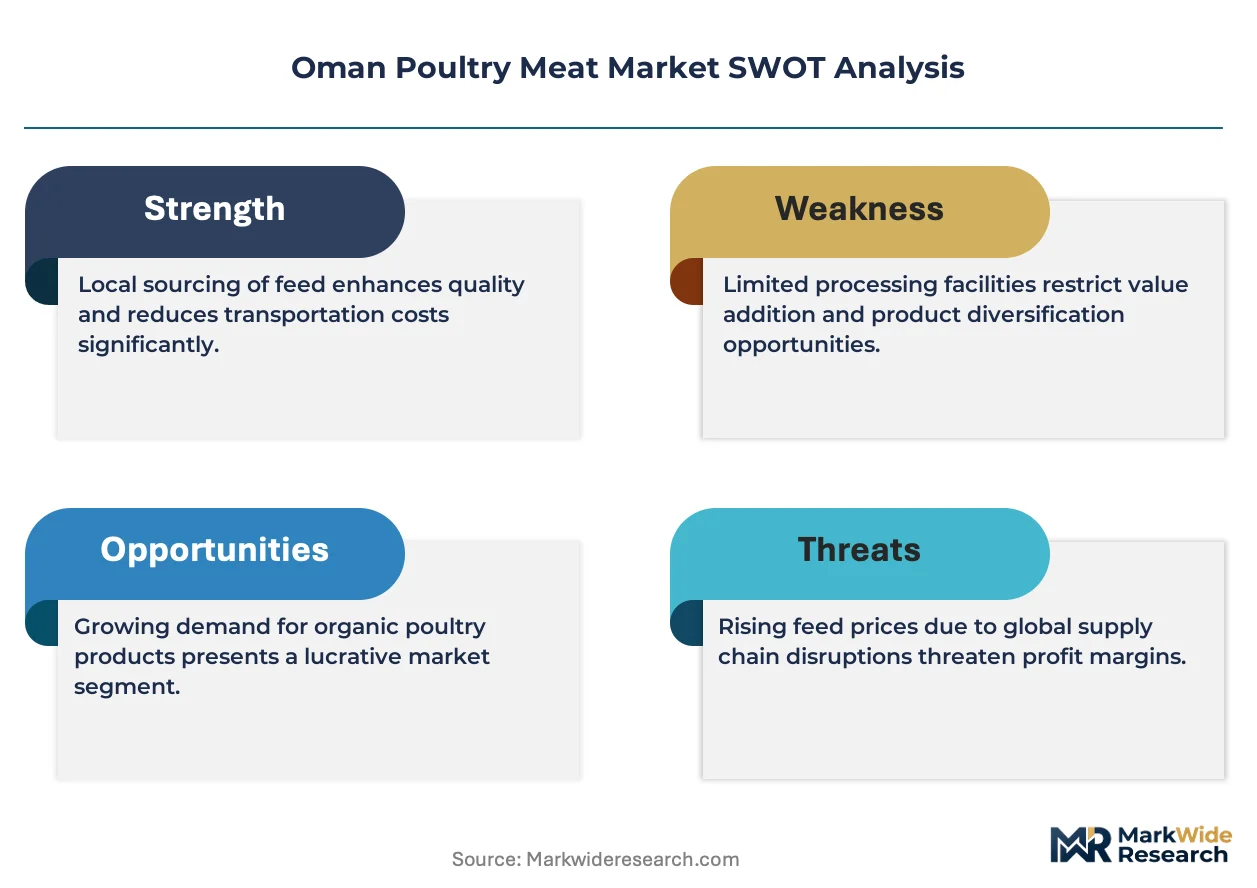
HACCP certification is rotating as the primary gating standard for processing plant licensing across Oman, disqualifying smaller facilities that lack hazard-control documentation. Almarai leverages its integrated feed-to-retail infrastructure to sustain shelf presence in major supermarket chains. Dhofar Poultry anchors southern supply through its Salalah-based operations, while A'Saffa Foods differentiates via frozen and value-added product lines.
Oman poultry meat encompasses broiler chicken and turkey products processed under controlled temperature chains for human consumption, with fresh whole birds typically held between 0°C and 4°C through slaughter, evisceration, and retail distribution to preserve microbial safety and organoleptic quality. The product serves as a staple protein source across household cooking, foodservice operations, and institutional catering throughout the Sultanate. Whole Chickens dominate volume throughput due to price accessibility and cultural preference for home butchering, while Chicken Breasts command premium positioning in supermarkets targeting health-conscious consumers. Online Retail represents the fastest-growing distribution channel as digital grocery platforms expand last-mile cold delivery capabilities.
Oman's Ministry of Agriculture and Fisheries enforces farm biosecurity and slaughterhouse hygiene standards that shape operational compliance costs and capital thresholds for market entry. The GCC Standardization Organization (GSO) harmonizes halal certification and labeling requirements across intra-GCC trade flows, directly affecting cross-border product eligibility. Stakeholders must monitor evolving feed import subsidy policies and water tariff structures that determine long-term production economics in Oman's arid climate.
Market Dynamics
The Ministry of Agriculture and Fisheries' escalating biosecurity protocols are compressing farm licensing timelines and raising capital thresholds for new entrants, concentrating production among operators capable of documenting hazard-control systems from feed sourcing through slaughter.
Growth Catalysts
- Tourism infrastructure expansion:Hotel and catering procurement volumes are accelerating as Muscat and Salalah add room inventory, pulling chilled poultry throughput through expanded cold chain nodes.
- GSO halal harmonization:Standardized certification across GCC borders is reducing cross-border friction for Omani processors seeking Saudi and UAE retail placement.
- Digital grocery platforms:Last-mile refrigerated delivery networks are extending fresh product reach beyond traditional supermarket catchments into interior governorates.
Market Restraints
- Feed import dependency:Local production economics hinge on subsidized soybean and corn shipments through Port Sultan Qaboos, exposing margins to freight rate volatility and currency fluctuation.
- Water tariff escalation:Arid-climate poultry operations face rising operational costs as municipal water pricing for agricultural use tightens under conservation mandates.
- Processing concentration:HACCP documentation requirements are disqualifying smaller slaughterhouses, narrowing viable supply to a handful of capital-intensive facilities.
Strategic Opportunities
- Dhofar Governorate underpenetration:Salalah-based supply anchors southern demand, but interior towns beyond the coastal corridor remain underserved by fresh distribution.
- Value-added product lines:Frozen marinated cuts and portion-controlled retail packs are capturing premium positioning in supermarket freezer aisles.
- Institutional catering contracts:Hospital and school feeding programs are consolidating procurement around certified suppliers with documented cold chain custody.
Industry Challenges
- Veterinary epidemiology expertise gap:Farm biosecurity audits require trained personnel capable of implementing pathogen surveillance protocols, a skill set scarce in the domestic labor pool.
- Slaughterhouse retrofit timelines:Existing facilities face 18-to-24-month compliance windows to install HACCP-compliant documentation systems and temperature monitoring infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Oman Poultry Meat Market |
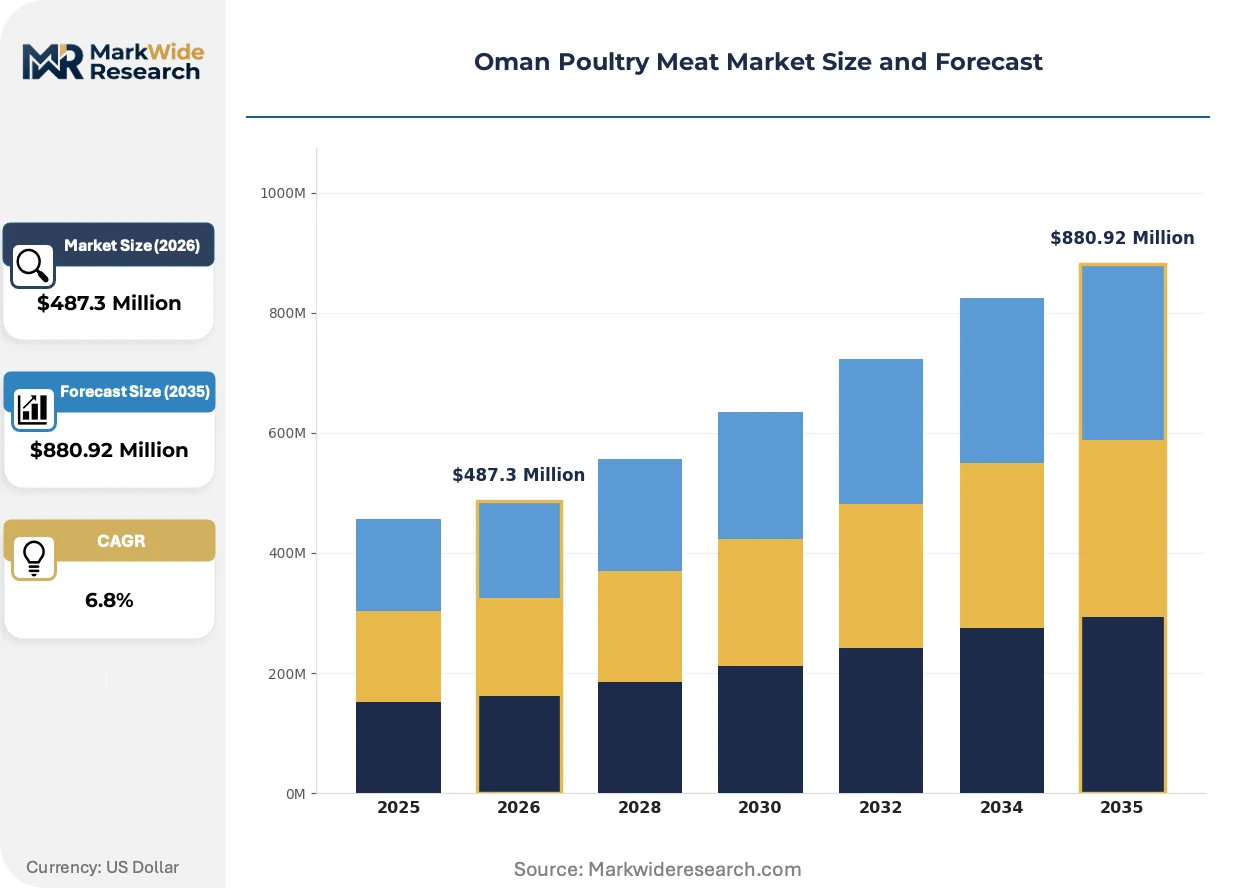
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $880.92 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Whole Chickens, Chicken Breasts, Chicken Thighs, Chicken Wings Distribution Channel: Supermarkets, Convenience Stores, Online Retail, Wholesalers End User: Households, Restaurants, Hotels, Catering Services Packaging Type: Tray Packs, Vacuum Packs, Canned, Frozen |
| Companies Covered | Al Zain Farms LLC, Almarai, A'Saffa Foods, The Savola Group, BRF S.A., Dhofar Poultry, Tanmiah Food Company, A’Namaa Poultry, Al Faaw Poultry Co LLC, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Oman Poultry Meat Market Trends and Innovations
Automation and digital traceability systems are penetrating Omani poultry operations, altering how farms document compliance and how retailers verify provenance for quality-conscious buyers.
Blockchain-enabled supply chain tracking is decomposing traditional paper-based halal certification and batch record systems. Major supermarket chains are piloting QR-code scanning that displays slaughter date, farm origin, and cold chain custody logs. This transparency infrastructure is compressing information asymmetry between processors and end consumers, forcing upstream documentation discipline.
Oman's Ministry of Agriculture and Fisheries is tightening farm licensing protocols through mandatory biosecurity audits and pathogen surveillance mandates. Operators must now submit documented feed source records and veterinary inspection logs before license renewal. Smaller family farms lacking administrative capacity are exiting, while integrated operators absorb their market share through contract growing arrangements.
Foodservice procurement is consolidating around suppliers capable of delivering pre-portioned, kitchen-ready cuts rather than whole birds requiring on-site butchering. Hotel chains in Muscat and resort properties along the Batinah Coast are specifying trimmed breast portions and standardized thigh cuts to reduce labor costs and plate waste. This specification shift favors processors with mechanical deboning and portioning equipment over traditional slaughter-only facilities.
Oman Poultry Meat Market Segmentation
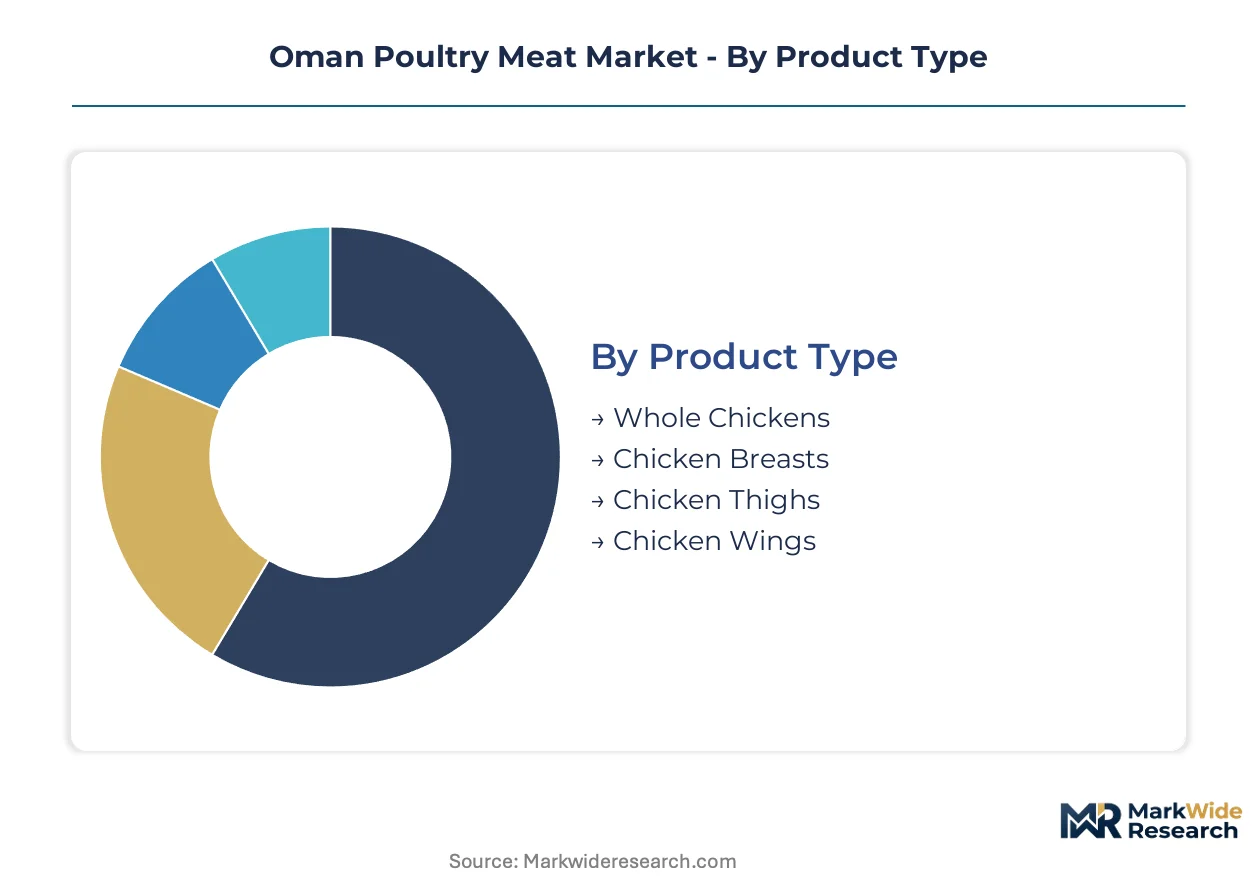
Segmentation in Oman's poultry meat market reveals how consumer behavior, distribution infrastructure, and regulatory requirements fragment demand across distinct product and channel configurations. Understanding these divisions exposes where substitution pressures from red meat and seafood concentrate, and where cold chain investments unlock incremental volume.
Product Type:
Substitution pressure from imported frozen fish and locally slaughtered goat meat weighs most heavily on undifferentiated whole bird offerings, while premium cuts defend share through convenience positioning.
- Whole Chickens:Fresh whole birds retain cultural preference for home butchering rituals and bulk cooking traditions. Demand concentrates in Muscat's traditional retail souqs and Batinah Coast household procurement where price sensitivity dominates protein selection.
- Chicken Breasts:Deboned breast portions target health-conscious consumers and foodservice operators seeking standardized protein inputs. Supermarket chains in Al Seeb and Al Khuwair are expanding chilled breast SKUs to capture fitness-oriented demographics and quick-service restaurant supply contracts.
- Chicken Thighs:Dark meat cuts serve slow-cooking applications and value-oriented household segments across interior governorates.
- Chicken Wings:Buffalo-style and marinated wing products supply casual dining outlets and delivery-focused cloud kitchens in urban clusters.
Whole Chickens anchors the volume base while Chicken Breasts gains share at the steepest rate.
Distribution Channel:
Channel economics stratify sharply by cold chain capital intensity, with last-mile refrigeration requirements determining which operators can sustain fresh product integrity.
- Supermarkets:Lulu Hypermarket, Carrefour, and local chains control chilled poultry throughput through dedicated meat counters and private label programs. Their procurement specifications are forcing upstream HACCP compliance among approved suppliers.
- Online Retail:Digital grocery platforms including Talabat Mart and local delivery services are building refrigerated fleet capacity to reach interior towns beyond traditional retail catchments. Salalah and Nizwa are seeing fastest platform penetration where supermarket density remains thin.
- Convenience Stores:Neighborhood groceries stock frozen and chilled portions for emergency purchase and small household replenishment.
- Wholesalers:Bulk distributors supply institutional buyers and independent restaurants through cash-and-carry formats concentrated in Rusayl Industrial Area.
Supermarkets dominate current value capture while Online Retail expands most quickly as logistics infrastructure matures.
End User:
User segmentation tracks the divergence between price-driven household procurement and specification-heavy foodservice contracting.
- Households:Family units across Muscat, Sohar, and Salalah drive baseline demand through weekly fresh chicken purchases, with preparation methods favoring whole birds for rice-based dishes.
- Hotels:International chain properties and resort developments along the Batinah Coast are consolidating procurement around pre-portioned, kitchen-ready cuts to reduce labor costs and plate waste.
- Restaurants:Independent eateries and quick-service operators source through wholesale channels with varying quality specifications.
- Catering Services:Institutional feeding programs for hospitals, schools, and corporate facilities require documented cold chain custody and halal certification compliance.
Households sustain the demand foundation while Hotels drives the steepest specification upgrade trajectory.
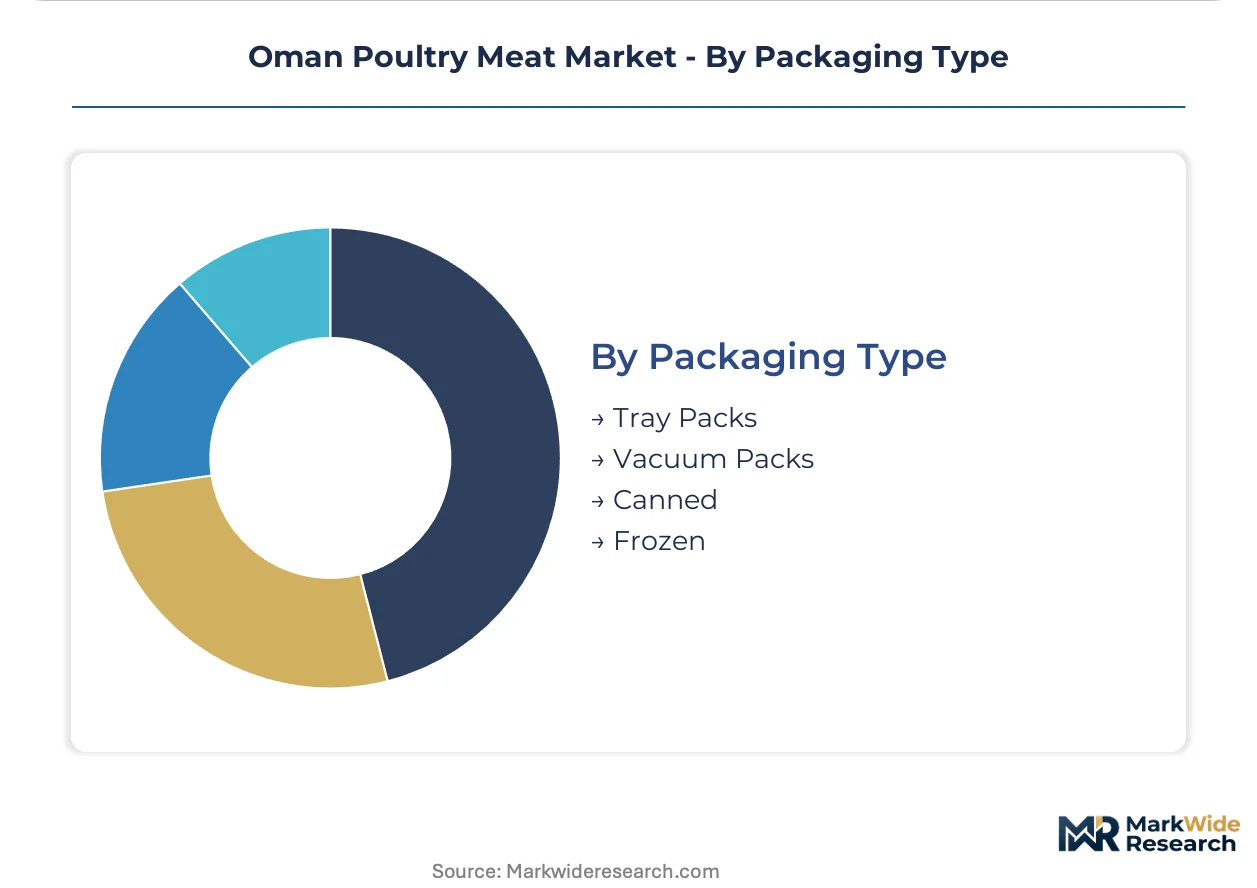
Packaging Type:
Packaging selection reflects the tension between shelf life extension and fresh product perception in consumer purchase decisions.
- Tray Packs:Modified atmosphere packaging dominates supermarket fresh counters, balancing visibility with three-to-five-day shelf stability under continuous refrigeration.
- Vacuum Packs:Barrier film configurations extend distribution radius for processors serving distant governorate markets beyond daily delivery range.
- Frozen:Blast-frozen whole birds and cuts stock retail freezer aisles and institutional procurement channels.
- Canned:Thermally processed poultry products serve niche emergency preparedness and export market segments.
Tray Packs commands the fresh volume position while Vacuum Packs climbs fastest as distribution networks stretch toward underserved interior regions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyer archetypes fragment sharply across Oman's sub-regions, with Muscat's hotel procurement desks demanding pre-portioned cuts while interior households sustain whole-bird traditions. Cold chain density and water access dictate where integrated operators can deploy capital-intensive facilities.
Muscat Governorate
International hotel chains and hypermarket procurement desks drive specification-heavy demand for deboned breast portions and standardized thigh cuts. The Ministry of Agriculture and Fisheries enforces HACCP documentation for all suppliers to capital foodservice accounts. Rusayl Industrial Area clusters processing facilities serving both retail and institutional channels with dedicated refrigerated distribution.
Batinah Coast
Dense household populations and traditional retail souqs sustain volume throughput of fresh whole birds for rice-based cooking traditions. Municipal water pricing for agricultural use is tightening under conservation mandates, pressuring farm economics. Sohar anchors northern supply with feed mill and slaughterhouse infrastructure positioned near Port Sultan Qaboos import corridors.
Dhofar Governorate
Salalah-based operations anchor southern supply, though interior towns beyond the coastal corridor remain underserved by fresh distribution networks. The Ministry's biosecurity audit requirements are compressing licensing timelines for new farm entrants. Coastal hotel developments around Salalah are replicating Muscat's procurement specifications for pre-portioned cuts.
Ad Dakhiliyah Governorate
Nizwa and interior towns demonstrate fastest digital grocery platform penetration where supermarket density remains thin. Online retail refrigerated delivery networks are extending fresh product reach beyond traditional retail catchments. Local wholesalers in Bahla and Nizwa supply independent restaurants through cash-and-carry formats with varying quality specifications.
Al Sharqiyah North
Sur and coastal towns balance household demand with emerging foodservice procurement from tourism infrastructure. Feed import dependency through Port Sultan Qaboos exposes margins to freight rate volatility and currency fluctuation. Contract growing arrangements are absorbing smaller family farms lacking administrative capacity for biosecurity documentation.
Oman Poultry Meat Market Competitive Landscape
Player mix skews toward integrated feed-to-retail conglomerates and regional specialists with captive distribution. Market structure concentrates among operators capable of documenting hazard-control systems from feed sourcing through slaughter. Three archetypes dominate: Saudi-backed integrated conglomerates with GCC-wide logistics, Omani domestic specialists with southern or northern geographic anchoring, and Brazilian exporters supplying frozen value-added lines. Competitive moves center on HACCP compliance certification and cold chain custody documentation for institutional contracts.
Within the integrated conglomerate tier, Almarai leverages its feed-to-retail infrastructure to sustain shelf presence in major supermarket chains. Among Omani domestic specialists, Dhofar Poultry anchors southern supply through its Salalah-based operations, while A'Saffa Foods occupies a position exemplifying frozen and value-added product differentiation. These operators represent the capital-intensive facility archetype that is absorbing market share as smaller family farms exit under documentation pressure.
| Leading Market Players |
|---|
| Al Zain Farms LLC |
| Almarai |
| A'Saffa Foods |
| The Savola Group |
| BRF S.A. |
| Dhofar Poultry |
| Tanmiah Food Company |
| A'Namaa Poultry |
| Al Faaw Poultry Co LLC |
| Others |
Pricing and Supply Chain Analysis
Feed grain substitution away from subsidized corn toward alternative protein sources simultaneously redraws procurement geography around Port Sultan Qaboos and compresses margin structures for operators lacking forward-contract coverage. This input volatility transmits directly into farm-gate pricing power, favoring integrated conglomerates with captive feed mills over standalone processors exposed to spot markets.
Pricing Analysis
Cost-plus contracts indexed to Brazilian soybean futures dominate processor-procurement relationships, insulating large operators from freight rate spikes while exposing smaller buyers to margin compression. Three-tier pricing structure across HACCP-certified premium, standard halal-compliant, and economy frozen tiers segments buyer willingness-to-pay. Pricing pressure stems from water tariff escalation under municipal conservation mandates, tightening operational economics for Batinah Coast farms. Households in traditional souqs exhibit highest price sensitivity, while Muscat hotel procurement desks prioritize specification compliance over unit cost.
Supply Chain Analysis
Brazil and Argentina anchor global feed grain supply for Omani poultry operations, with secondary sourcing from Black Sea corridors when freight economics permit. Local production draws from imported soybean meal, corn, and vitamin premix concentrates arriving through Port Sultan Qaboos. Single-source vulnerability concentrates in maritime chokepoints around the Strait of Hormuz, where geopolitical friction threatens feed delivery continuity. Distribution runs through cold chain nodes in Rusayl Industrial Area, with last-mile refrigerated fleets extending reach into interior governorates.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Oman's poultry market operates as a regulatory-moat story where HACCP documentation requirements create entrenched switching costs for institutional buyers. The Ministry of Agriculture and Fisheries' tightening biosecurity protocols cement incumbent advantages by raising capital thresholds for new facility licensing.
For Market Incumbents: Compound defensive positioning through backward integration into captive feed milling capacity, securing margin insulation against import price volatility. Accelerate HACCP certification coverage for secondary processing lines before the Ministry's compliance windows narrow further. Absorb smaller family farms through contract growing arrangements that transfer biosecurity documentation burden while retaining production volume. For New Entrants and Emerging Players: HACCP fast-track partnerships with established slaughterhouses offer the lowest-friction entry path for capital-constrained operators. Target Dhofar Governorate interior towns beyond Salalah's coastal corridor, where fresh distribution remains underdeveloped and digital grocery platforms are building refrigerated fleet capacity. Lead with value-added marinated cuts and portion-controlled retail packs to bypass whole-bird commodity competition dominated by integrated conglomerates. For Investors and Strategic Acquirers: Secondary-cycle assets sit with Saudi-backed integrated operators seeking GCC-wide logistics optimization. Five-to-ten-year viability hinges on water rights security and feed import subsidy continuity under fiscal consolidation pressures. Monitor Ministry of Agriculture and Fisheries licensing moratoria as the key inflection signal for supply-constrained pricing power.| Strategic Initiative | Industry Significance |
|---|---|
| HACCP Certification Investment | Unlocks institutional procurement contracts with Muscat hotel chains and hospital feeding programs. |
| Backward Integration into Feed Milling | Captures margin from soybean import through Port Sultan Qaboos to finished broiler production. |
| Digital Cold Chain Expansion | Extends fresh product reach into Nizwa and interior Dhofar towns beyond supermarket catchments. |
| Value-Added Product Line Launch | Captures premium positioning in supermarket freezer aisles with marinated and portion-controlled SKUs. |
| Contract Growing Arrangements | Absorbs exiting family farm production volume while centralizing biosecurity documentation compliance. |
Research Methodology
Operator-level perspectives from farm managers, slaughterhouse operations directors, supermarket category buyers, and hotel procurement executives anchored the qualitative base for this analysis. Primary fieldwork combined structured interviews across the value chain with secondary validation from Ministry of Agriculture and Fisheries licensing records, GCC Standardization Organization halal certification databases, and Port Sultan Qaboos customs trade data. Bottom-up volume estimates triangulated against top-down consumption models derived from household expenditure surveys and foodservice procurement patterns.
Sensitivity analysis tested forecast robustness across feed price volatility scenarios and water tariff escalation pathways over the projection horizon. Segmentation modeling incorporated product type, distribution channel, end-user category, and packaging format dimensions alongside regional governorate clusters. CAGRs were derived from trend extrapolation adjusted for documented regulatory phase-in schedules and infrastructure investment pipelines. Key forecast inputs included tourism room inventory expansion timelines and digital grocery platform refrigerated fleet deployment schedules.
Decision-makers should treat outputs as directional under assumptions of continued feed import subsidy stability and Ministry licensing protocol enforcement; material deviation in either would warrant model refresh. Recalibration cycles align with material shifts in biosecurity audit stringency and cold chain infrastructure deployment.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Meat Products
Europe Meat Products Market
Meat Products
Europe Edible Meat Market
Meat Products
Europe Processed Meat Market
Meat Products
South Africa Processed Meat Market
Meat Products
North America Processed Meat Market
Meat Products
Dehydrated Meat Products Market
Meat Products
Germany Meat Products Market
Meat Products
Beef Bone Broth Market
Meat Products
Chicken Fat Market
Meat Products
United States Edible Meat Market
Meat Products
Hams Market
Meat Products
Low Fat Sausage Market
Meat Products
United States Poultry Meat Market
Meat Products
Brazil Meat Products Market
Meat Products
Hot Dog and Sausages Market
Meat Products
Mechanically Separated Meat Market