
 Middle East Poultry Meat Market | 2026-2036
Middle East Poultry Meat Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East Poultry Meat Market Foresight
The foodservice vertical is broadening its share of poultry offtake as hotel and catering operations across the Gulf Cooperation Council scale output to serve rising tourism and event volumes. Almarai Company leverages its integrated feed-to-retail infrastructure to secure consistent chilled distribution across Saudi Arabia. Tanmiah Food Company sustains a vertically coordinated model that spans breeder farms and processing facilities in the kingdom. BRF S.A. competes through frozen product specialization tailored to Middle Eastern taste profiles and portion preferences.
Middle East poultry meat encompasses broiler chicken processed under halal slaughter protocols, with carcasses typically chilled to sub-4°C within two hours of processing to maintain shelf stability and microbial safety. The product serves as a primary animal protein source for households, foodservice operators, and institutional caterers across a region where per capita consumption exceeds most other meat categories. Whole chicken dominates retail channel volumes due to its price accessibility and versatility across traditional cooking methods. Chicken breast commands premium positioning in supermarkets and e-commerce platforms where health-conscious buyers prioritize lean protein content. The foodservice segment captures the fastest expansion trajectory as hotel chains and quick-service restaurants in Dubai, Riyadh, and Doha enlarge their poultry-forward menu offerings.
Saudi Food and Drug Authority and Emirates Authority for Standardization and Metrology enforce halal labeling and cold-chain compliance rules that determine market access for domestic and imported poultry. SFDA import quotas and local content incentives are redirecting procurement toward Saudi-bred supply, reshaping competitive dynamics for Brazilian and European exporters. Stakeholders must monitor evolving national food security mandates and biosecurity protocols that will determine which production models secure preferential placement in government-backed procurement programs.
Market Dynamics
Saudi Food and Drug Authority import quotas and local content mandates are redirecting procurement toward domestic broiler supply, compressing margins for Brazilian and European exporters while accelerating in-house production investments across the kingdom.
Growth Catalysts
- SFDA Local Content Incentives:Saudi Arabia's food security initiatives are accelerating domestic broiler production capacity expansion through subsidized land allocation and feed cost support.
- Quick-Service Restaurant Chains:Foodservice operators across the UAE and Saudi Arabia are enlarging poultry-forward menu offerings as consumer dining habits shift toward convenience and away-from-home consumption.
- Halal Traceability Technology:Blockchain-enabled supply chain tracking is tightening compliance documentation for slaughter certification and cold-chain integrity across Gulf Cooperation Council markets.
Market Restraints
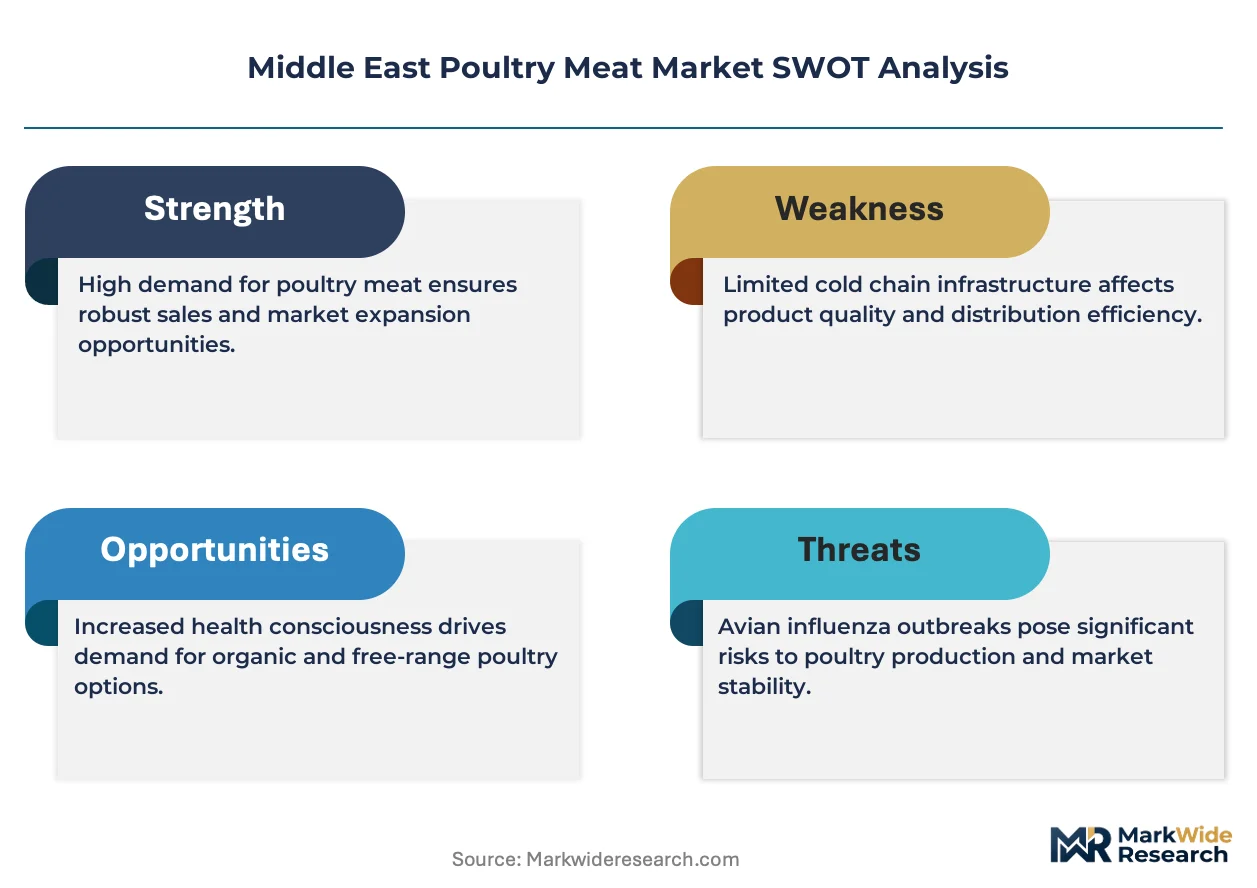
- Feed Input Volatility:Corn and soybean meal price swings in international commodity markets compress broiler farm margins and destabilize production cost forecasting.
- Import Concentration Risk:Brazilian suppliers dominate frozen poultry inflows, creating vulnerability to currency fluctuations and bilateral trade disputes.
- Biosecurity Protocol Friction:Avian influenza containment mandates enforced by national veterinary authorities periodically disrupt cross-border live bird and hatching egg movements.
Strategic Opportunities
- E-Commerce Chilled Distribution:Saudi Arabia's supermarket delivery platforms are opening direct-to-consumer channels for premium cut chicken previously confined to brick-and-retail.
- MOHAP Food Safety Modernization:UAE federal incentives for cold-chain infrastructure investment are lowering barriers for domestic processing facility expansion.
- Hotel and Catering Scale-Up:Tourism volume recovery in Dubai and Riyadh is driving institutional procurement contracts for portion-controlled poultry products.
Industry Challenges
- Veterinary Specialist Scarcity:Qualified farm biosecurity officers and slaughterhouse halal certifiers remain in short supply across Saudi Arabia's rapidly expanding production zones.
- Legacy ERP Integration:Family-owned processing operations struggle to synchronize new traceability software with decades-old inventory management systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East Poultry Meat Market |
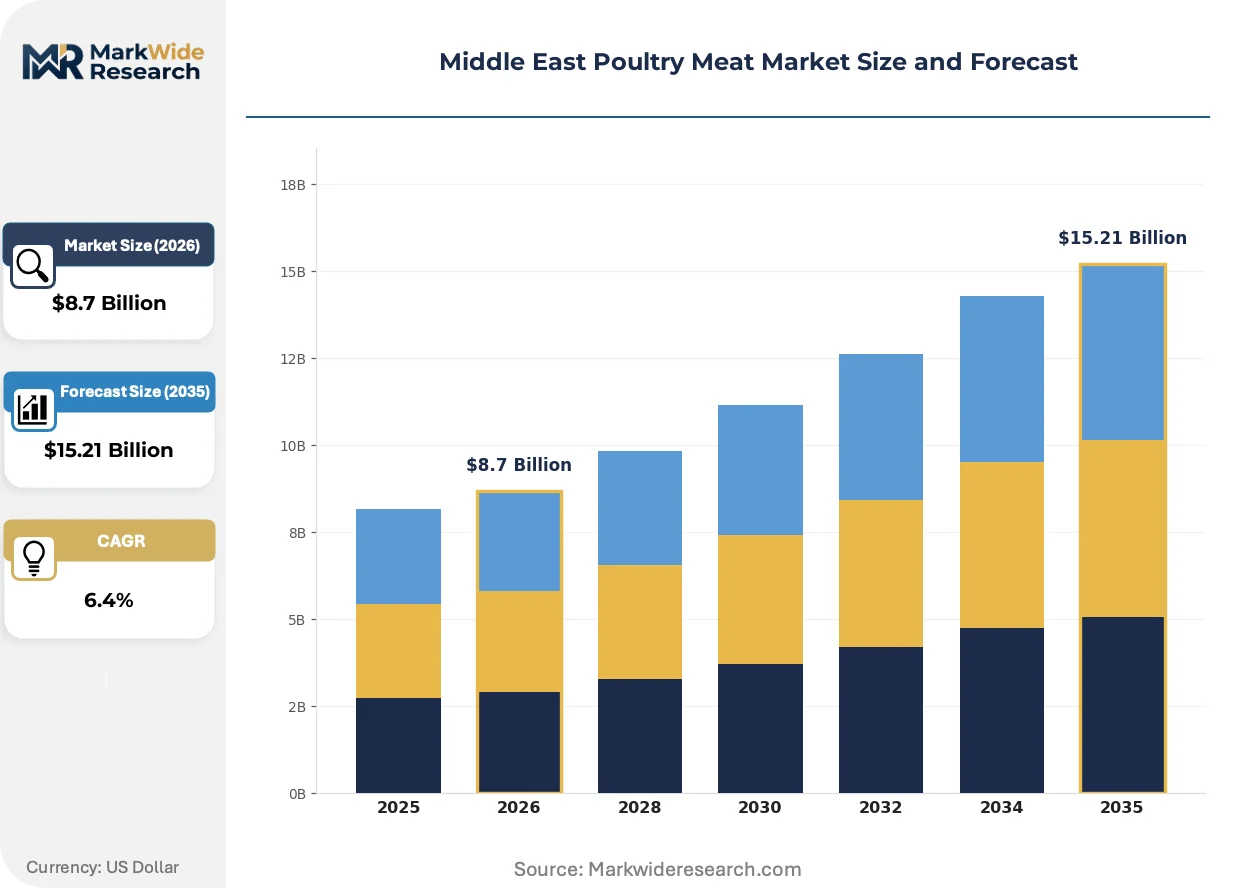
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.21 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Whole Chicken, Chicken Breast, Chicken Wings, Chicken Thighs Distribution Channel: Retail Stores, Foodservice, E-commerce, Direct Sales End User: Households, Restaurants, Hotels, Caterers Packaging Type: Bulk Packaging, Vacuum Sealed, Tray Packaging, Canned |
| Companies Covered | Tanmiah Food Company, The Savola Group, Almarai Company, Arabian Agricultural Services Company, JBS SA, BRF S.A., Al Islami Foods, Emirates National Food CC LLC, Al-Watania Poultry Company, Others |
| Regions Covered | Middle East: Saudi Arabia, UAE, Qatar, Israel, Kuwait, Oman, Bahrain, Iran, Iraq, Rest of Middle East |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East Poultry Meat Market Shifts & Advancements
Automation, regulatory digitization, and channel restructuring are converging to reshape how poultry moves from farm to plate across Middle Eastern markets.
Robotic deboning and portioning systems are automating labor-intensive processing steps that previously required skilled manual cutters. Saudi Arabia's largest integrated producers are deploying these lines to reduce dependence on expatriate workforce availability. The technology is automating throughput scaling while tightening yield consistency for breast and thigh products destined for foodservice clients.
SFDA and Emirates Authority for Standardization and Metrology are mandating digital halal certification registries with QR-code consumer verification. The policy shift forces exporters and domestic processors to upgrade documentation infrastructure or face market access suspension. Frozen product importers from Brazil and Europe are absorbing the highest compliance costs as they retrofit legacy labeling systems.
Quick-service restaurant procurement teams are consolidating supplier relationships toward single-source integrated producers capable of delivering chilled rather than frozen product. Hotel chains in Doha and Dubai are leading this specification change, trading inventory flexibility for shelf-life extension and menu quality consistency. The pattern is most pronounced in UAE foodservice, where centralized kitchen models demand predictable daily delivery cadences.
Middle East Poultry Meat Market Segmentation
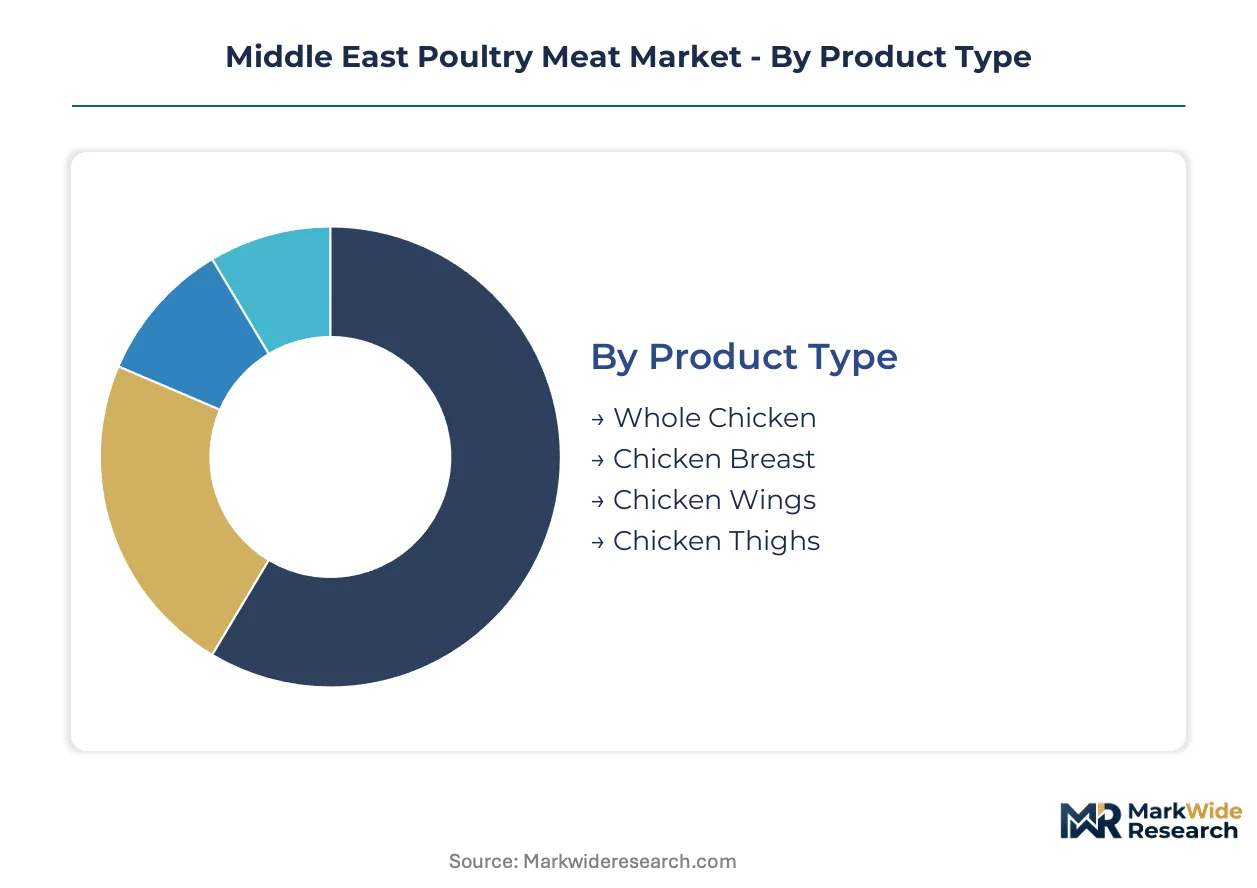
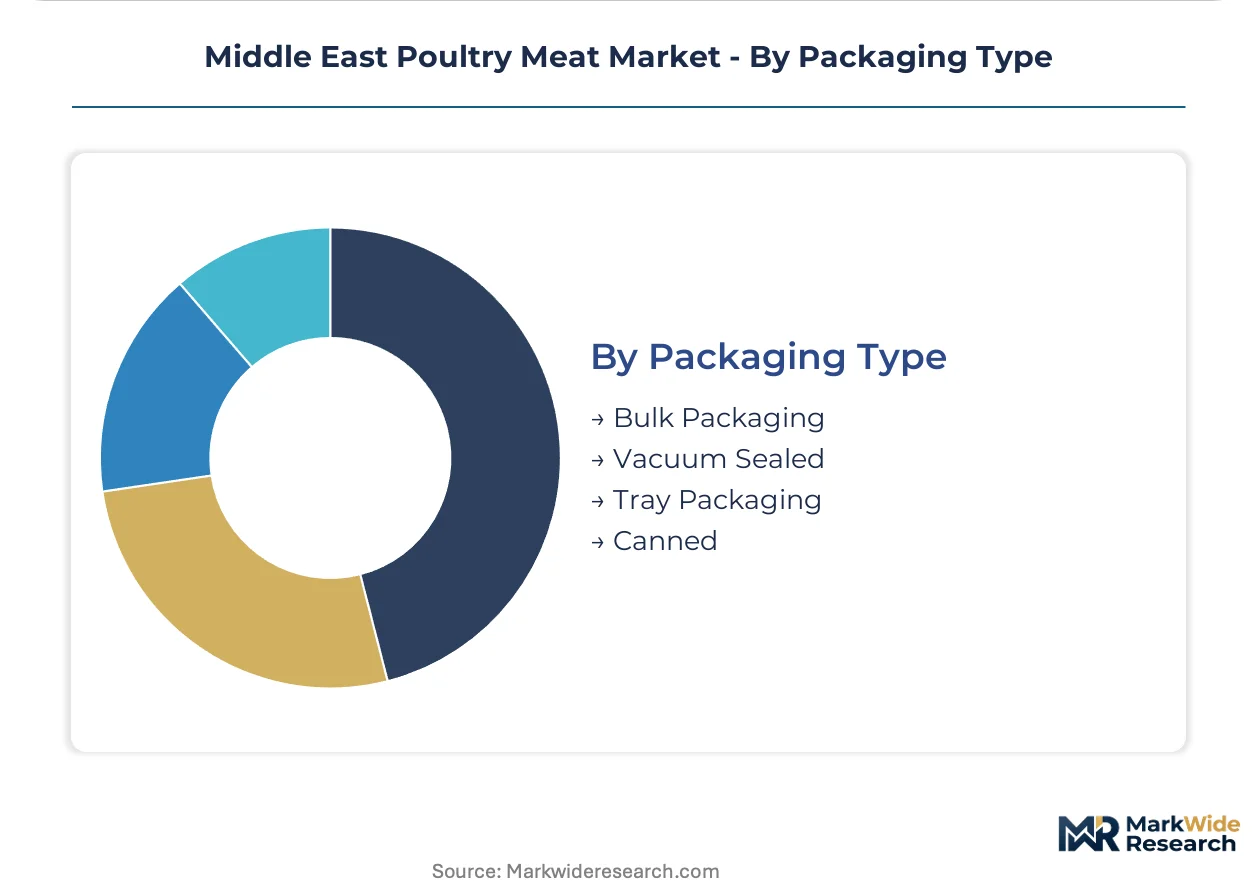
Poultry meat segmentation across the Middle East reflects divergent cold-chain capabilities, halal certification tiers, and channel-specific shelf-life requirements. Product form and packaging specifications determine which segments command premium positioning versus commodity volume plays.
Product Type:
Specification tiers separate minimally processed whole birds from precision-cut portions targeting foodservice portion control.
- Whole Chicken:Intact carcasses processed under halal protocols and chilled to sub-4°C within two hours post-slaughter. Demand concentrates in Saudi Arabian retail channels where price-sensitive households favor versatility across traditional cooking methods. Government food security subsidies on domestic broiler production reinforce volume positioning.
- Chicken Breast:Deboned, skinless cuts standardized for lean protein content and consistent portion weights. UAE supermarket and e-commerce platforms are capturing the steepest expansion trajectory as health-conscious buyers prioritize convenience and recipe flexibility. Premium pricing reflects higher processing yields and cold-chain investment.
- Chicken Wings:Jointed portions popular in quick-service restaurant appetizers and home entertaining. Saudi Arabia's expanding fast-food sector drives procurement scale.
- Chicken Thighs:Dark meat cuts preferred for moisture retention in extended cooking applications. Traditional caterers across the Gulf Cooperation Council sustain steady offtake.
Mature deployment sits with Whole Chicken. Newer deployment is concentrated in Chicken Breast.
Distribution Channel:
Channel selection determines temperature protocols, traceability documentation depth, and buyer relationship structures.
- Retail Stores:Supermarket and hypermarket networks with dedicated chilled poultry sections and halal certification displays. Saudi Arabia's domestic retail consolidation is accelerating as Almarai and Tanmiah expand proprietary store networks. Cold-chain infrastructure investments by the Saudi Food and Drug Authority are tightening compliance requirements for chilled display cases.
- Foodservice:Direct supply relationships with hotel chains, quick-service restaurants, and institutional caterers demanding portion-controlled, specification-grade product. Dubai and Riyadh hotel procurement teams are expanding poultry-forward menu offerings as tourism volumes recover. Daily delivery cadences and centralized kitchen models favor integrated producers with captive processing capacity.
- E-commerce:Platform-mediated home delivery of chilled and frozen cuts through Saudi supermarket apps and UAE grocery delivery services. Last-mile cold-chain reliability remains the binding constraint for premium cut expansion.
- Direct Sales:Processor-to-institution contracts bypassing intermediaries for high-volume catering and government procurement. Saudi food security programs are redirecting procurement toward domestic supply through direct tender mechanisms.
Established infrastructure sits with Retail Stores. Channel investment is flowing fastest into Foodservice.
End User:
User categories map to decision-making authority structures and specification complexity tolerance.
- Households:Individual consumers purchasing through retail or e-commerce for home meal preparation. Saudi Arabian households dominate regional consumption volumes due to population scale and per capita poultry preference.
- Restaurants:Independent and chain foodservice operators with standardized menu specifications and supplier audit requirements. UAE quick-service restaurant chains are consolidating supplier relationships toward single-source integrated producers.
- Hotels:International and domestic hotel groups with procurement teams demanding chilled product, halal blockchain traceability, and consistent portion weights. Dubai luxury hospitality properties are leading specification upgrades.
- Caterers:Event and institutional food providers with high-volume, price-sensitive procurement and bulk packaging preferences. Saudi government and corporate catering contracts are expanding with domestic production capacity.
Volume concentration sits with Households. Specification upgrading is advancing fastest in Hotels.
Packaging Type:
Packaging technology selection balances shelf-life extension against unit economics and regulatory labeling mandates.
- Bulk Packaging:Large-format containers for foodservice and institutional procurement with minimal unit processing. Saudi caterers and quick-service restaurant chains favor this format for cost efficiency in high-throughput operations.
- Vacuum Sealed:Oxygen-excluded barrier films extending chilled shelf life to 21+ days for retail premium positioning. UAE supermarket chains are expanding vacuum-sealed breast and thigh offerings as cold-chain reliability improves.
- Tray Packaging:Modified-atmosphere overwrap for retail display appeal with intermediate shelf-life performance. Saudi retail consolidation is driving standardization around tray formats with QR-code halal verification.
- Canned:Thermally processed shelf-stable product for emergency stockpiling and institutional reserve programs. Limited commercial significance outside government procurement.
Mainstream adoption sits with Bulk Packaging. Technology migration is advancing fastest in Vacuum Sealed.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
King Abdullah Economic City anchors poultry processing concentration through its dedicated food manufacturing zone and port logistics infrastructure.
Saudi Arabia
Government food security programs and subsidized feed allocations are accelerating domestic broiler capacity expansion. The Saudi Food and Drug Authority enforces strict halal certification and cold-chain compliance through digital tracking mandates. Riyadh and the Eastern Province host integrated production clusters where captive breeder farms supply adjacent processing facilities.
United Arab Emirates
Dubai's hospitality sector recovery and quick-service restaurant chain expansion are driving chilled poultry procurement scale. The Emirates Authority for Standardization and Metrology mandates blockchain-enabled halal traceability for all imported and domestic product. Abu Dhabi industrial zones concentrate secondary processing and portion-control operations serving hotel procurement teams.
Qatar
Hotel and catering operations tied to event tourism are enlarging specification-grade poultry offtake. The Ministry of Public Health enforces food safety modernization protocols aligned with Gulf Cooperation Council standards. Doha logistics corridors host cold-chain distribution hubs consolidating regional re-export flows.
Kuwait
Institutional catering contracts and retail consolidation are concentrating procurement toward integrated suppliers. The Public Authority for Food and Nutrition regulates import quotas and halal slaughter certification requirements. Shuwaikh industrial area clusters secondary processing facilities serving domestic supermarket networks.
Bahrain
Foodservice sector growth linked to hospitality investment is expanding chilled product demand. The National Health Regulatory Authority coordinates halal certification alignment with Saudi and UAE standards. Muharraq and Sitra zones concentrate cold storage and distribution infrastructure for cross-Gulf trade.
Middle East Poultry Meat Market Competitive Landscape
Top-tier vendors anchor integrated production, while mid-scale processors compete on regional specialization and import substitution. The competitive structure stratifies across three tiers: domestic integrated giants with captive feed-to-retail infrastructure, Brazilian and European exporters leveraging frozen product scale, and regional specialists focused on halal certification compliance. Strategic moves center on backward integration into breeder farm ownership and cold-chain infrastructure investment to displace frozen imports with chilled domestic supply.
Within the integrated domestic tier, Almarai Company and Tanmiah Food Company exemplify the feed-to-retail archetype through vertically coordinated operations spanning Saudi production zones. BRF S.A. represents the international frozen specialist segment, competing on portion-standardized products adapted to Middle Eastern taste profiles. These three anchors illustrate the competitive tension between import-dependent scale and domestic integration strategies reshaping procurement patterns across Gulf Cooperation Council markets.
| Leading Market Players |
|---|
| Tanmiah Food Company |
| The Savola Group |
| Almarai Company |
| Arabian Agricultural Services Company |
| JBS SA |
| BRF S.A. |
| Al Islami Foods |
| Emirates National Food CC LLC |
| Al-Watania Poultry Company |
| Others |
Supply & Pricing Matrix
SFDA cold-chain digitization mandates gate both qualified supply access and premium-tier pricing power across Saudi distribution networks. Chilled product commanding shelf-life premiums flows only through facilities meeting sub-4°C compliance thresholds, while frozen alternatives absorb margin compression in spot markets.
Pricing Analysis
Lead-time-driven pricing stratification rewards chilled delivery cadences with premium positioning against frozen spot inventory. Three-tier pricing structure across premium chilled, standard frozen, and economy bulk levels reflects halal certification grade and cold-chain integrity. Cost compression in frozen tiers is intensifying because Brazilian import concentration feeds currency vulnerability. Quick-service restaurant chains exhibit highest price sensitivity, while Dubai luxury hotels prioritize specification consistency over unit cost.
Supply Chain Analysis
Halal blockchain certification requirements enforced by Emirates Authority for Standardization and Metrology now gate market access for all imported and domestic product. Geographic supply concentration centers on Saudi Arabia, Brazil, and the UAE, with Brazilian frozen inflows feeding spot markets and Saudi integrated operations capturing chilled premium tiers. Feed input sourcing draws from international corn and soybean meal markets, while breeder stock genetics rest on European and North American grandparent supply. Single-source vulnerability runs through Brazilian frozen poultry concentration. Distribution runs through integrated producer captive networks, foodservice direct contracts, and supermarket retail channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a vertical-integration race where captive breeder farm ownership determines margin capture against import-dependent competitors. Players pursuing upstream control over grandparent genetics and hatchery operations secure supply security premiums.
For Market Incumbents: Hedge against Brazilian currency volatility by accelerating in-house broiler capacity expansion across Riyadh and Eastern Province production zones. Lock in long-term feed supply contracts before commodity price swings destabilize cost forecasting. SFDA local content mandates favor domestic supply, but veterinary specialist scarcity threatens biosecurity compliance.
For New Entrants and Emerging Players: Quick-service restaurant procurement teams represent the most penetrable channel partner type for chilled product specification conversion. Target UAE foodservice consolidation toward single-source integrated suppliers as hotel chains abandon frozen inventory flexibility. White-space opportunity sits in e-commerce chilled last-mile delivery infrastructure where platform reliability gaps persist. Go-to-market angle: blockchain-enabled halal traceability as procurement differentiator.
For Investors and Strategic Acquirers: SFDA import quota tightening is the leading indicator that domestic production capacity will command scarcity premiums over the coming decade. Acquisition target archetype: mid-scale Saudi processors with captive breeder farms and underutilized cold-chain infrastructure. Long-term viability hinges on backward integration depth rather than trading margin. Signal to monitor: government tender mechanisms redirecting institutional procurement toward domestic supply.
| Strategic Initiative | Industry Significance |
|---|---|
| Breeder Farm Acquisition | Captive grandparent supply secures genetic continuity against import biosecurity friction. |
| Cold-Chain Infrastructure Expansion | SFDA sub-4°C compliance investments unlock chilled premium pricing in retail channels. |
| Blockchain Traceability Deployment | Emirates Authority QR-code mandates force documentation upgrades for market access. |
| Feed Cost Hedging Programs | International commodity volatility protection stabilizes broiler farm margin forecasting. |
| Foodservice Direct Contracting | Dubai hotel procurement consolidation favors daily delivery cadence capabilities. |
Research Methodology
Independent corroboration across primary interviews with broiler farm operations managers, SFDA regulatory compliance officers, foodservice procurement directors, and cold-chain logistics specialists underwrites the qualitative findings. Secondary validation draws from Saudi Food and Drug Authority enforcement bulletins, Emirates Authority for Standardization and Metrology technical regulations, customs trade flow databases, and Gulf Cooperation Council veterinary authority avian influenza containment protocols. Bottom-up capacity assessments across Saudi production zones triangulate against top-down consumption estimates derived from retail channel audits.
Rate-of-change decomposition separates volume growth from price mix shifts across the projection horizon. Segmentation dimensions span product form, distribution channel, end-user category, and packaging technology tier. CAGRs derive from production capacity buildout trajectories, import quota evolution, and foodservice channel expansion rates. Industry-specific forecast inputs include breeder flock placement schedules and hotel occupancy recovery patterns in Dubai and Riyadh.
Caveats apply where avian influenza containment mandates, bilateral trade disputes, or feed commodity price spikes could materially shift the outlook. Forecasts reflect assumptions around SFDA local content incentive continuity and tourism volume recovery trajectories. A model refresh is warranted upon material change in government food security procurement program specifications.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Meat Products
North America Processed Meat Market
Meat Products
Europe Poultry Meat Market
Meat Products
Meat Market
Meat Products
Low Fat Beef Market
Meat Products
Meat Ingredients Market
Meat Products
United States Animal Protein Market
Meat Products
North America Canned Meat Market
Meat Products
Europe Canned Meat Market
Meat Products
Blended Meat Market
Meat Products
Brisket Market
Meat Products
Mechanically Separated Meat Market
Meat Products
US Meat Market
Meat Products
Beef Bouillon Market
Meat Products
Meat Emulsions Market
Meat Products
Meat Paste Market
Meat Products
United States Bacon Market