
 North America Processed Meat Market | 2026-2036
North America Processed Meat Market Size, Share, and Industry Trends Forecast 2026-2036
North America Processed Meat Market Intelligence
Quick-service restaurant procurement of sliced deli meat and pepperoni is hardening as operators reformulate menus for speed and consistency. Tyson Foods Inc. leverages its vertically integrated poultry and pork network to secure supply commitments across the Southeast and Midwest. Hormel Foods Corporation differentiates through refrigerated branded entrees and pepperoni specialization that anchors its food service penetration. Smithfield Foods dominates fresh and processed pork capacity, controlling raw material flows that sustain its competitive position in bacon and ham categories.
Processed meat encompasses animal proteins subjected to curing, smoking, fermentation, or thermal treatment to extend shelf life, enhance flavor, and ensure microbiological safety, typically containing salt, nitrites, and phosphates at regulated thresholds. These products serve commercial food preparation and retail distribution where standardized portioning and predictable performance under heat are essential. Sausages and deli meat occupy mature volume positions with established margin structures, while pepperoni segments accelerate through pizza chain expansion and frozen appetizer demand. Vacuum packs and modified-atmosphere trays capture growing share as retailers prioritize visual shelf appeal and extended code dates over traditional can and box formats.
USDA inspection protocols and FDA food safety modernization standards govern pathogen control and labeling accuracy across US production facilities, while CFIA regulations enforce parallel requirements in Canadian plants. The EPA oversees wastewater and rendering emissions from large-scale processing operations, adding compliance costs that favor capital-intensive producers. Stakeholders must monitor evolving sodium reduction mandates and clean-label positioning requirements that will reshape formulation strategies and equipment investments across the supply base.
Market Dynamics
USDA sodium reduction mandates and FDA labeling transparency rules are forcing reformulation investments across the processed meat supply base, compressing margins for mid-tier processors while advantaging capital-rich integrated operators.
Growth Catalysts
- CFIA modernization:Canadian regulatory harmonization with US standards reduces cross-border compliance duplication for integrated processors operating Ontario and Quebec plants.
- Quick-service restaurant automation:Pizza chains and sandwich operators demand pre-portioned, cook-stable proteins that reduce labor touchpoints during peak hours.
- Modified-atmosphere packaging:Vacuum and gas-flush tray technologies extend retail code dates by 40-60%, reducing shrink and enabling centralized production.
Market Restraints
- Feed grain volatility:Corn and soybean price swings transmit directly into live animal costs, compressing processor margins with limited pass-through elasticity.
- Midwest processing concentration:Iowa, Illinois, and Nebraska house 60% of US pork slaughter capacity, creating weather and logistics vulnerability.
- Plant-based substitution:Pea and soy protein analogs capture 8-12% of food service sandwich and pizza topping trials, pressuring category volume.
Strategic Opportunities
- Mexico trade integration:USMCA tariff stability and Mexican cold-chain expansion create export channels for US-produced bacon and ham.
- Clean-label fermentation:Celery powder and natural nitrite curing systems command 15-25% retail premiums over conventional cured products.
- Direct-to-food service platforms:Processor-owned e-procurement portals bypass distributor markups for regional restaurant chains.
Industry Challenges
- Microbiological validation timelines:USDA-FSIS pathogen reduction performance standards require 90-180 day validation cycles for new thermal processes.
- Rendering wastewater compliance:EPA effluent guidelines for blood and fat processing impose capital-intensive pretreatment systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Processed Meat Market |
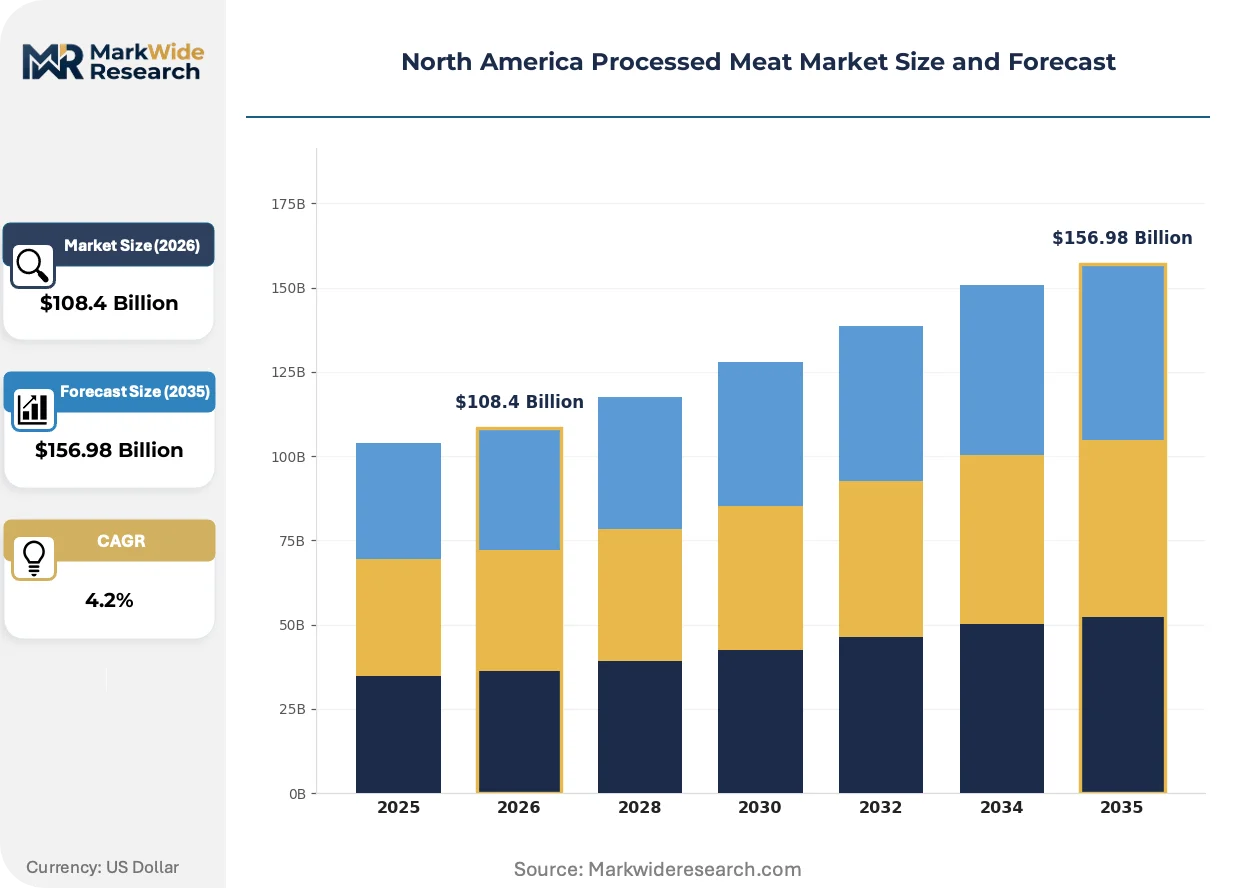
| Market Size in 2026 | $108.4 Billion |
| Market Size in 2035 | $156.98 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sausages, Ham, Bacon, Salami, Deli Meat, Pepperoni Packaging Type: Vacuum Packs, Cans, Trays, Bags, Boxes, Wrappers Application: Food Service, Retail, Institutional, Catering, Home Consumption End User: Supermarkets, Specialty Stores, Convenience Stores, Wholesale Clubs |
| Companies Covered | Tyson Foods Inc., Conagra Brands, Smithfield Foods, Hormel Foods Corporation, Sysco Corporation, Perdue Farms, JBS USA, Cargill Incorporated, National Beef Packing Company, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Processed Meat Market Strategic Shifts & Innovations
High-pressure processing and natural curing technologies are displacing legacy thermal and chemical preservation methods, while regulatory pressure on sodium and label clarity accelerates formulation transparency.
High-pressure processing (HPP) applies isostatic pressure to packaged meats, eliminating Listeria and extending shelf life without thermal degradation. Regional deli meat processors in Texas and California are adopting HPP units to serve premium retail accounts. This technology is decentralizing production geography by enabling smaller, non-thermal plants closer to urban demand centers.
USDA's updated Nutrition Facts labeling rules mandate single-serving disclosure for multi-serving packages, exposing true sodium density in bacon and sausage. Processors must reformulate or resize portions to maintain shelf positioning. Deli meat and breakfast sausage categories face the steepest compliance costs and timeline pressure.
Food service operators are consolidating protein suppliers to reduce vendor management overhead and secure volume commitments. Regional pizza chains and sandwich franchises now source 70-80% of pepperoni and sliced meats from single processors with captive supply. This concentration is most visible in the Southeast, where Tyson and Smithfield have locked multi-year contracts with expanding quick-service brands.
North America Processed Meat Market Segmentation
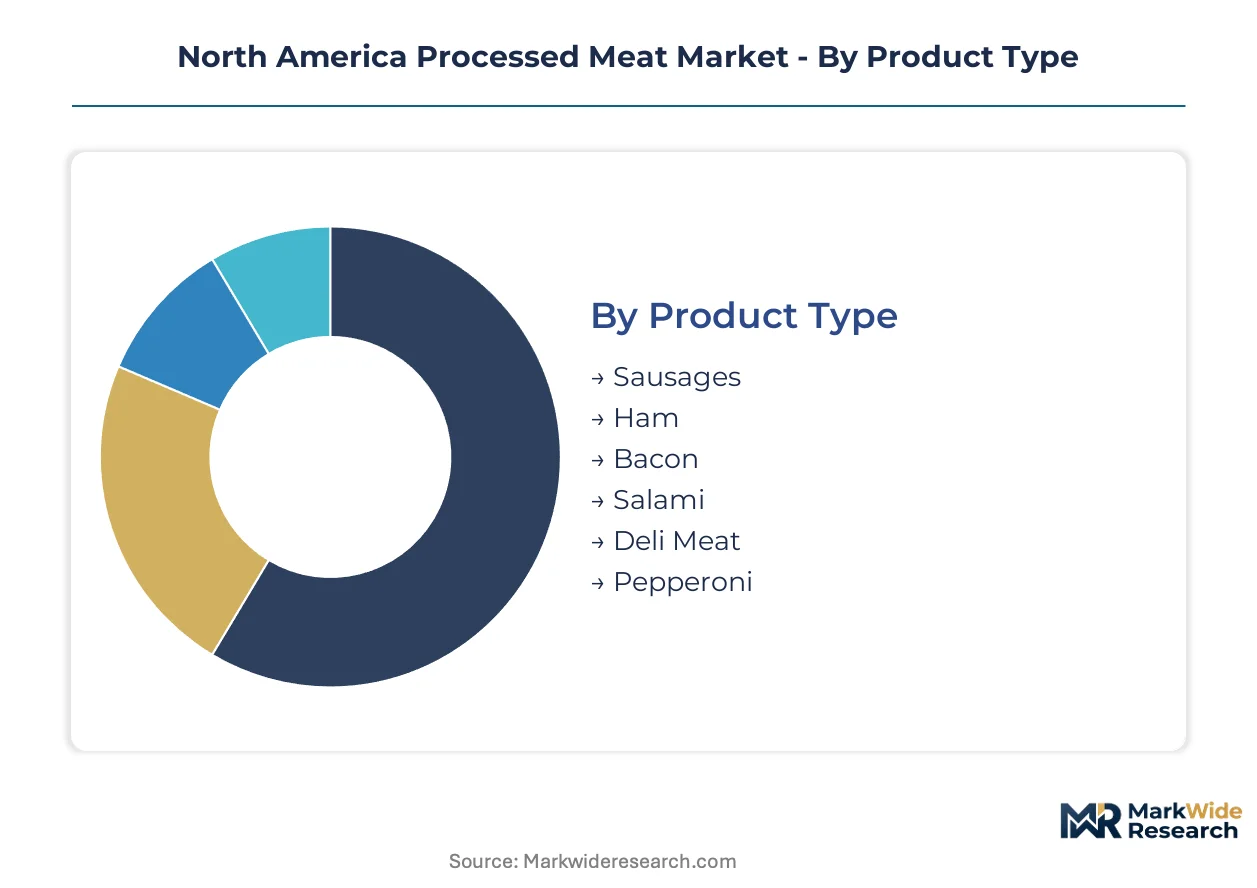
Processed meat segmentation reveals how product format, packaging technology, and channel economics fragment procurement requirements across the North American supply base. Distinct shelf-life, portioning, and regulatory demands shape each category's competitive dynamics and margin structure.
Product Type:
Standalone retail categories operate on established margin curves, while embedded food service inputs face stricter cook-stability and portion-control specifications.
- Sausages:Ground and emulsified meat products in natural or synthetic casings, spanning fresh, smoked, and dried variants. Demand concentrates in Midwest retail chains and quick-service breakfast programs, where USDA sodium reduction mandates are forcing reformulation of breakfast links and bratwurst lines.
- Ham:Cured pork from whole-muscle sections or restructured formats, with water content regulated by USDA standards. Volume placements concentrate in Easter and holiday retail windows across the Southeast, though spiral-sliced premium lines face margin pressure from private-label competition.
- Bacon:Belly-cured strips dominating breakfast daypart and burger topping applications. Canadian and US plants supply differentiated cure profiles for retail versus food service channels.
- Salami:Fermented and dried sausages requiring extended aging cycles. Specialty Italian and Spanish varieties command premium positioning in urban specialty retail.
- Deli Meat:Sliced turkey, chicken, and beef for sandwich preparation. Modified-atmosphere packaging adoption is extending code dates for premium private-label programs.
- Pepperoni:Fermented pork and beef salami sliced for pizza topping. Frozen appetizer and pizza chain expansion is accelerating volume growth in this segment.
Volume placements concentrate in Deli Meat and Bacon; the faster expansion belongs to Pepperoni.
Packaging Type:
Cost tier stratification separates capital-intensive barrier technologies from commodity formats, with food service automation driving convergence toward pre-portioned, cook-ready configurations.
- Vacuum Packs:Barrier films evacuated of oxygen to inhibit microbial growth and oxidation. Retail delis and wholesale clubs in Texas and California are adopting vacuum-sealed subprimals to reduce labor and shrink.
- Cans:Thermally processed metal containers for shelf-stable hams, sausages, and luncheon meats. Institutional and emergency food programs sustain residual demand despite retail decline.
- Trays:Modified-atmosphere and overwrapped foam or paperboard platforms for case-ready retail. Gas-flush technology is capturing share from traditional overwrap as retailers prioritize visual shelf appeal.
- Bags:Flexible pouches for bulk food service portions and value retail lines. Midwest processors favor bag formats for bacon bits and crumble toppings.
- Boxes:Corrugated containers for frozen bulk shipments to distributors and chain warehouses. Standardized cube efficiency dominates procurement specifications.
- Wrappers:Single-serve films for convenience retail and vending applications. Portion-controlled breakfast sausage links rely on wrapper formats for grab-and-go channels.
Capital deployment clusters in Tray and Vacuum Pack lines; Bags and Wrappers are gaining share fastest in convenience-oriented channels.
Application:
Customer type fragmentation splits between high-volume, specification-driven commercial accounts and price-sensitive, variety-seeking household purchasers.
- Food Service:Commercial kitchens, quick-service restaurants, and institutional cafeterias requiring consistent portioning and thermal performance. Pizza chains and sandwich operators in the Southeast are consolidating suppliers to reduce vendor management overhead.
- Retail:Supermarket and specialty store channels where packaging presentation and label claims drive selection. USDA's updated Nutrition Facts rules are exposing sodium density in multi-serving packages.
- Institutional:Schools, hospitals, and correctional facilities governed by federal nutrition guidelines and bid-based procurement. Cost compression favors canned and frozen formats with extended shelf stability.
- Catering:Event and hospitality providers requiring bulk preparation and transport durability. Regional processors in Florida and Arizona serve this channel with customized cure profiles.
- Home Consumption:Direct-to-consumer and subscription channels, still marginal but expanding through e-commerce platforms. Premium bacon and artisan salami varieties test this route.
Food Service commands the largest volume footprint; Home Consumption is climbing the fastest through digital channel experimentation.
End User:
Channel concentration creates margin tiering, with format-flexible wholesale clubs and convenience stores extracting different value propositions than assortment-driven specialty retailers.
- Supermarkets:Full-service retailers with dedicated deli counters and case-ready meat sections. Chains in the Northeast and Pacific Northwest are expanding private-label processed meat programs to defend margin.
- Specialty Stores:Butcher shops, ethnic grocers, and gourmet food retailers emphasizing provenance and craft curing. Natural nitrite and celery powder curing systems command retail premiums in this channel.
- Convenience Stores:Limited-assortment retailers prioritizing grab-and-go and roller-grill applications. Pre-cooked breakfast sausage and pepperoni rollers dominate morning and late-night dayparts.
- Wholesale Clubs:Membership-based warehouse operators selling bulk formats to households and small businesses. Vacuum-packed subprimals and multi-pack bacon drive volume efficiency.
Supermarkets anchor current volume; Specialty Stores are expanding most quickly on clean-label and premium positioning.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
USMCA tariff stability and Mexican cold-chain subsidies are redrawing procurement corridors across North America, with processors consolidating capacity near border logistics hubs to capture duty-advantaged flows.
United States
Quick-service restaurant chains in Texas and Georgia are locking multi-year pepperoni and sliced deli contracts. USDA-FSIS pathogen reduction standards now require 90-day validation cycles for new thermal processes. Iowa, Illinois, and Nebraska house sixty percent of pork slaughter capacity, creating weather vulnerability that processors offset with captive rendering networks.
Canada
CFIA modernization is harmonizing inspection protocols with US standards, reducing cross-border compliance costs for Ontario and Quebec plants. Celery powder curing systems command retail premiums in Toronto and Vancouver specialty channels. Alberta beef processors are expanding bacon and ham capacity to serve US food service accounts under stable USMCA terms.
Mexico
Domestic cold-chain expansion is enabling US-produced bacon and ham to reach Monterrey and Guadalajara food service distributors. Mexican agricultural subsidies for feed grain production are stabilizing live animal costs for border-zone processors. Nuevo León and Jalisco are emerging as consolidation points for USMCA-compliant re-export operations.
North America Processed Meat Market Key Industry Players
Branded specialists and contract manufacturers split share differently across segments, with integrated protein conglomerates controlling raw material flows while regional processors capture premium positioning through clean-label fermentation. The market exhibits tiered concentration: capital-rich operators with captive supply networks dominate volume categories, mid-tier reformulators serve private-label retail, and artisan specialists command urban specialty channels. Strategic archetypes include vertically integrated protein majors, fermentation-focused premium processors, and distributor-backed contract manufacturers. Competitive moves center on multi-year supply commitments with quick-service chains and backward integration into feed and genetics.
Among US-based integrated operators, Tyson Foods Inc., Smithfield Foods, and Hormel Foods Corporation exemplify the capital-intensive archetype that secures food service penetration through captive poultry and pork networks. These entities anchor the supply base by controlling raw material flows from genetics through rendering, enabling them to absorb USDA sodium mandate compliance costs that compress mid-tier margins. Their positioning reflects the industry-wide shift toward supplier consolidation as restaurant chains reduce vendor management overhead.
| Leading Market Players |
|---|
| Tyson Foods Inc. |
| Conagra Brands |
| Smithfield Foods |
| Hormel Foods Corporation |
| Sysco Corporation |
| Perdue Farms |
| JBS USA |
| Cargill Incorporated |
| National Beef Packing Company |
| Others |
Cost & Logistics Intelligence
Feed grain costs transmit from Iowa and Illinois corn futures through live animal procurement into processor margin structures, with pork and poultry input volatility stratifying finished product pricing across premium branded, standard private-label, and economy bulk tiers. USDA sodium mandate compliance investments now layer onto this cost stack, compressing mid-tier processor returns while capital-integrated operators absorb reformulation expenses through captive rendering networks.
Pricing Analysis
Short lead-time premiums for just-in-time deli meat and pepperoni contracts command 15-25% markups over spot inventory purchases, with quick-service restaurant chains paying contract premiums to secure volume commitments. Three-tier pricing structure across premium, standard, and economy levels reflects brand equity, USDA organic certification, and private-label positioning. Cost compression in standard-tier breakfast sausage is intensifying because corn price pass-through elasticity remains limited in retail channels. Food service operators exhibit lowest price sensitivity due to menu reformulation lock-in, while institutional buyers face highest sensitivity under federal nutrition guideline cost caps.
Supply Chain Analysis
USMCA domestic-content requirements are reshaping sourcing patterns for Canadian plants serving US food service accounts, with Alberta and Ontario processors qualifying for duty-advantaged status. Supply concentrates in Iowa, Illinois, and Nebraska for pork slaughter, with Georgia and Arkansas anchoring poultry processing. Raw material flows draw from Midwest feed grain belts, Great Lakes logistics corridors, and Mexican border-zone rendering facilities. Single-source vulnerability concentrates in Midwest pork capacity where weather disruptions cascade through 60% of national slaughter. Distribution runs through Sysco and US Foods for food service, with retail channels served by direct-to-warehouse pallet programs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Slaughter capacity constraints across Iowa, Illinois, and Nebraska prop pricing power for integrated operators with captive supply networks, creating a supply-constrained market structure favoring backward-integrated incumbents.
For Market Incumbents: Extend multi-year supply commitments with Southeast quick-service chains to lock volume before CFIA harmonization enables Canadian competitor re-entry. Deepen upstream control over feed grain procurement through direct contracts with Iowa and Illinois elevators, insulating margin from spot corn volatility. Defend against plant-based substitution by accelerating clean-label fermentation capacity in celery powder curing systems that command retail premiums.
For New Entrants and Emerging Players: Urban specialty retailers seeking natural nitrite pepperoni and artisan salami represent the most penetrable buyer archetype, with Toronto and Vancouver channels showing premium tolerance. Target direct-to-food service e-procurement portals for regional pizza chains in Texas and Georgia, bypassing distributor markups through processor-owned platforms. Lead with high-pressure processing technology as a differentiation lever for premium deli meat accounts demanding extended code dates without thermal degradation.
For Investors and Strategic Acquirers: USDA-FSIS validation cycle delays exceeding 180 days are the leading indicator that microbiological process innovation is stalling, creating acquisition windows for HPP-equipped regional processors. Long-term viability centers on fermentation-focused premium processors with established clean-label positioning and captive urban retail distribution. Watch CFIA modernization implementation speed as the signal for cross-border capacity rationalization opportunities.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Feed Grain Procurement | Direct elevator contracts in Iowa and Illinois stabilize live animal cost exposure against futures volatility. |
| High-Pressure Processing Capacity Addition | Non-thermal Listeria elimination enables smaller plants proximate to Texas and California urban demand centers. |
| Clean-Label Fermentation Scale-Up | Celery powder curing systems capture 15-25% retail premiums in Toronto and Vancouver specialty channels. |
| Direct-to-Food Service E-Procurement Portal | Processor-owned platforms bypass Sysco and US Foods markups for regional restaurant chains. |
| USMCA-Compliant Border-Zone Rendering Expansion | Nuevo León and Jalisco consolidation points enable duty-advantaged re-export to Mexican food service distributors. |
Research Approach
Multi-period observation of USDA-FSIS validation timelines, CFIA modernization implementation stages, and quick-service restaurant procurement contract structures anchored the trend analysis, supplemented by interviews with protein procurement directors at Southeast pizza chains, plant managers at Iowa and Nebraska pork processing facilities, regulatory affairs leads at integrated meatpackers, and category buyers at Northeast supermarket chains. Secondary validation drew from USDA-FSIS enforcement data, EPA effluent guideline updates, USMCA tariff schedules, and customs records for cross-border protein flows. Bottom-up segment sizing triangulated against top-down macroeconomic consumption models.
Input-output matrices mapped live animal supply through rendering, processing, and packaging stages to finished product value across the projection horizon. Segmentation dimensions modeled include product type, packaging technology, application channel, and end-user format. CAGRs were derived from elasticity-adjusted consumption trend extrapolation. Industry-specific forecast inputs incorporated feed grain futures curves, quick-service restaurant expansion pipelines, and sodium mandate compliance cost schedules.
Revisions become necessary when EPA effluent guideline enforcement intensifies, USMCA tariff disputes resurface, or plant-based protein analogs exceed current food service trial penetration rates. Forecasts reflect documented assumptions about regulatory stability and feed cost transmission mechanisms. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Meat Products
North America Poultry Meat Market
Meat Products
Europe Animal Protein Market
Meat Products
United States Processed Pork Meat Market
Meat Products
Bacon Flavors Market
Meat Products
Shark Meat Market
Meat Products
Grass-Fed Meat Market
Meat Products
Antibiotic Free Meat Market
Meat Products
Middle-East and Africa Animal-Based Meat and Dairy Products Market
Meat Products
Smokehouse Market
Meat Products
Beef Fat Powder Market
Meat Products
Oman Poultry Meat Market
Meat Products
Mechanically Separated Meat Market
Meat Products
Chicken Buckets Market
Meat Products
United Arab Emirates Red Meat Market
Meat Products
Global Duck Meats Market
Meat Products
GCC Edible Meat Market