
 India Edible Meat Market | 2026-2036
India Edible Meat Market Size, Share, and Industry Trends Forecast 2026-2036
India Edible Meat Market Foresight
Cold-chain distribution is rewriting how Indian consumers access fresh and frozen meat. Suguna Foods Private Limited leverages its integrated poultry operations across southern states to sustain supply consistency. Allanasons Private Limited anchors India's buffalo meat export channel through its vertically controlled abattoir network. Venky's India dominates the branded retail segment with frozen and chilled product lines stocked in modern trade outlets.
India edible meat comprises muscle tissue from bovine, ovine, porcine, and avian species processed under temperature-controlled conditions to retain organoleptic and nutritional integrity; the category serves protein requirements across retail households, food service operators, and institutional catering. Poultry leads product type volume given shorter production cycles and lower per-unit cost, while mutton commands premium positioning in northern and western markets. The food service customer type is expanding fastest as organized restaurants and cloud kitchens standardize procurement through wholesale and online retail channels.
FSSAI mandates HACCP-aligned licensing for all meat processing facilities, while BIS certification governs frozen product quality parameters under relevant Indian standards. State-level cattle slaughter regulations in Maharashtra and Karnataka create fragmented supply conditions that processors must navigate case by case. Stakeholders should monitor evolving state-level livestock movement restrictions and cold-chain infrastructure gaps that will determine which regions permit scaled meat processing expansion.
Market Dynamics
Cold-chain infrastructure gaps and FSSAI hygiene mandates are compressing margins for unorganized processors while concentrating volume among integrated operators with captive refrigeration networks.
Growth Catalysts
- Quick-service restaurant expansion:Organized chains in Maharashtra and Karnataka are standardizing procurement through wholesale channels, pulling volume from fragmented wet markets into temperature-controlled supply lines.
- FSSAI licensing alignment:Mandatory HACCP certification for meat processing units is filtering out sub-scale operators and clearing shelf space for compliant branded products in modern retail.
- Cloud kitchen proliferation:Food service aggregators in Uttar Pradesh are consolidating demand through centralized procurement platforms that favor frozen and chilled SKUs with consistent specification.
Market Restraints
- Feed cost volatility:Maize and soybean meal price swings directly compress poultry processor margins, with southern integrated operations bearing the brunt of input inflation.
- State-level slaughter fragmentation:Maharashtra and Karnataka cattle movement restrictions create supply discontinuities that force processors to maintain redundant sourcing relationships across state borders.
- Religious dietary substitution:Plant-based protein alternatives and dairy-based preparations compete for protein share in vegetarian-majority households, capping per-capita meat penetration in western markets.
Strategic Opportunities
- Eastern state cold-chain penetration:Odisha and West Bengal present white-space demand with underdeveloped organized retail meat infrastructure and rising urban income profiles.
- Export protocol alignment:BIS certification convergence with Middle Eastern import standards opens channel expansion for buffalo meat processors with abattoir traceability systems.
- Direct-to-institutional platforms:Hospital and corporate catering contracts are migrating to digital procurement portals that bypass traditional mandi intermediaries and capture volume at contracted pricing.
Industry Challenges
- Veterinary certification bottlenecks:Ante-mortem inspection capacity constraints at state slaughterhouses delay processing schedules and create carcass spoilage risk during peak demand windows.
- Refrigerated fleet fragmentation:Third-party logistics providers with non-standard temperature monitoring create compliance gaps that expose processors to FSSAI enforcement actions and retailer rejection.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Edible Meat Market |
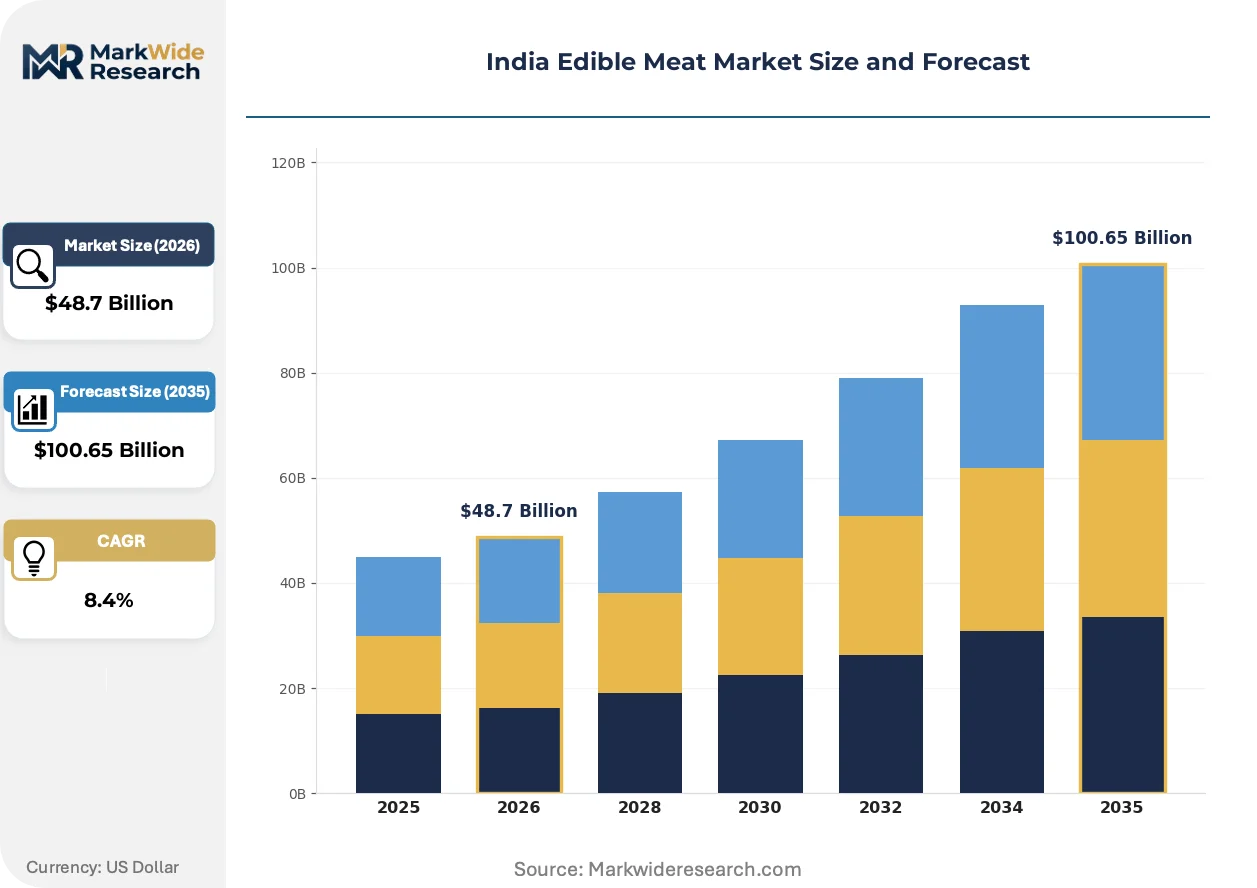
| Market Size in 2026 | $48.7 Billion |
| Market Size in 2035 | $100.65 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Beef, Poultry, Pork, Mutton Distribution Channel: Supermarkets, Local Markets, Online Retail, Wholesale Customer Type: Households, Restaurants, Food Service, Catering Packaging Type: Vacuum Sealed, Chilled, Frozen, Canned |
| Companies Covered | Allanasons Private Limited, Al Hamd Agro Food Products Private Limited, Suguna Foods Private Limited, Allana Group, Fair Exports India Private Limited, Venky's India, M. K. Overseas Private Limited, VH Group, HMA Agro Industries Limited, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Edible Meat Market Shifts & Advancements
Automation and regulatory digitization are compressing traditional processing timelines while procurement platforms rewire how institutional buyers source protein.
Controlled-atmosphere packaging is collapsing the shelf-life differential between chilled and frozen meat segments. Quick-service operators in Karnataka are adopting MAP-lined trays for retail display, enabling processors to shift volume from energy-intensive frozen storage to refrigerated distribution with lower working capital lockup. This compression is eroding the traditional premium commanded by frozen product stability.
FSSAI's digital licensing portal is accelerating compliance verification timelines for meat processing units. The mandate for real-time temperature logging during transport is forcing cold-chain operators to retrofit vehicle fleets with IoT monitoring devices. Smaller processors in Uttar Pradesh face disproportionate adaptation costs as they scale to meet modern retail audit requirements.
Aggregator-led procurement is consolidating food service demand into specification-driven contracts that displace spot-market purchasing. Cloud kitchens in Maharashtra are standardizing cut specifications and delivery windows through platform interfaces, compressing supplier bases to processors with consistent yield and traceability documentation. This behavioral shift is most visible in Mumbai and Bangalore metropolitan zones where kitchen density supports daily delivery cadences.
India Edible Meat Market Segmentation
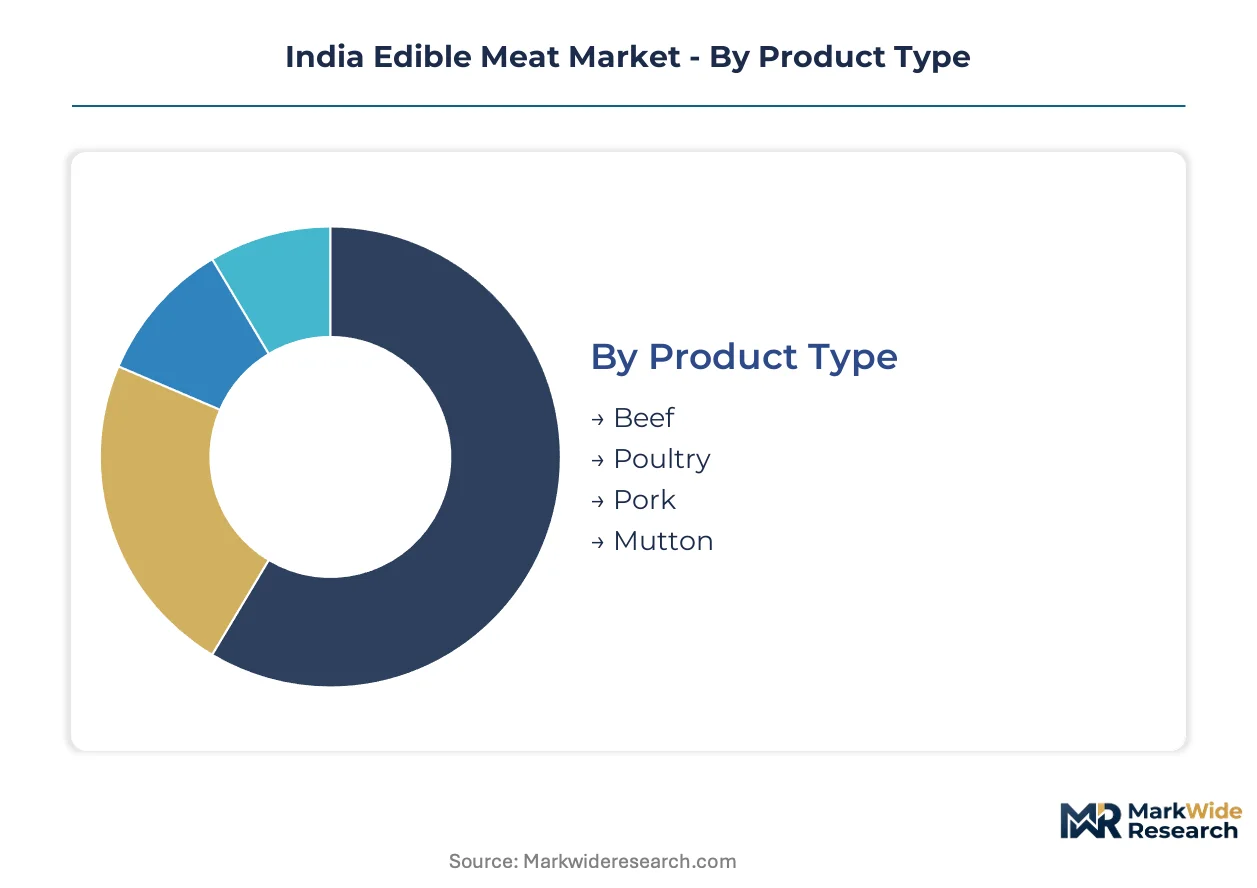
Segmentation in India's edible meat market exposes how protein procurement diverges across income tiers, operational scale, and cold-chain access. Each dimension reveals distinct margin structures and compliance burdens that reshape competitive positioning.
Product Type:
Cost tier stratification separates commodity protein from premium positioning across Indian consumption patterns.
- Poultry:Shorter production cycles and feed conversion efficiency make broiler chicken the volume anchor. Quick-service chains in Maharashtra and Karnataka standardize procurement around chilled cuts, pulling supply from wet markets into temperature-controlled channels.
- Beef:Buffalo meat dominates export protocol alignment with Middle Eastern markets, while domestic consumption concentrates in Kerala and northeastern states. FSSAI licensing mandates filter processing capacity toward integrated abattoir operators with captive cold storage.
- Mutton:Premium positioning in northern and western markets reflects longer production cycles and religious festival demand spikes.
- Pork:Niche consumption clusters in Goa, Nagaland, and Meghalaya with limited organized processing infrastructure.
Poultry commands the dominant share, while beef is closing the gap through export channel expansion.
Distribution Channel:
Supply concentration varies sharply between organized retail penetration and fragmented traditional trade.
- Wholesale:Cloud kitchen aggregators and quick-service chains in Mumbai and Bangalore consolidate procurement through specification-driven contracts. Platform interfaces standardize cut grades and delivery windows, compressing supplier bases to FSSAI-compliant processors.
- Supermarkets:Modern trade outlets in Delhi NCR and Hyderabad stock branded frozen and chilled lines with traceability documentation. Retail audit requirements disproportionately burden smaller processors adapting to real-time temperature logging mandates.
- Local Markets:Wet market dominance persists in tier-2 and tier-3 cities with limited cold-chain penetration.
- Online Retail:Emerging channel constrained by last-mile refrigeration gaps and veterinary certification bottlenecks.
Wholesale channels absorb the dominant volume flow, while supermarket penetration is climbing the fastest in metropolitan zones.
Customer Type:
Operational scale determines procurement sophistication and contract structure across protein buyers.
- Restaurants:Organized chains in Maharashtra and Karnataka are migrating from spot-market purchasing to contracted pricing with yield guarantees. Daily delivery cadences in dense metropolitan kitchen clusters favor processors with integrated cold-chain networks.
- Food Service:Aggregator-led platforms in Uttar Pradesh consolidate cloud kitchen demand into centralized procurement portals. Specification standardization displaces traditional mandi intermediaries.
- Households:Retail purchasing persists through fragmented local market relationships with limited brand loyalty.
- Catering:Institutional contracts for hospitals and corporate facilities increasingly bypass traditional intermediaries through digital procurement portals.
Restaurants hold the dominant procurement volume, while food service platforms are gaining share fastest through aggregator consolidation.
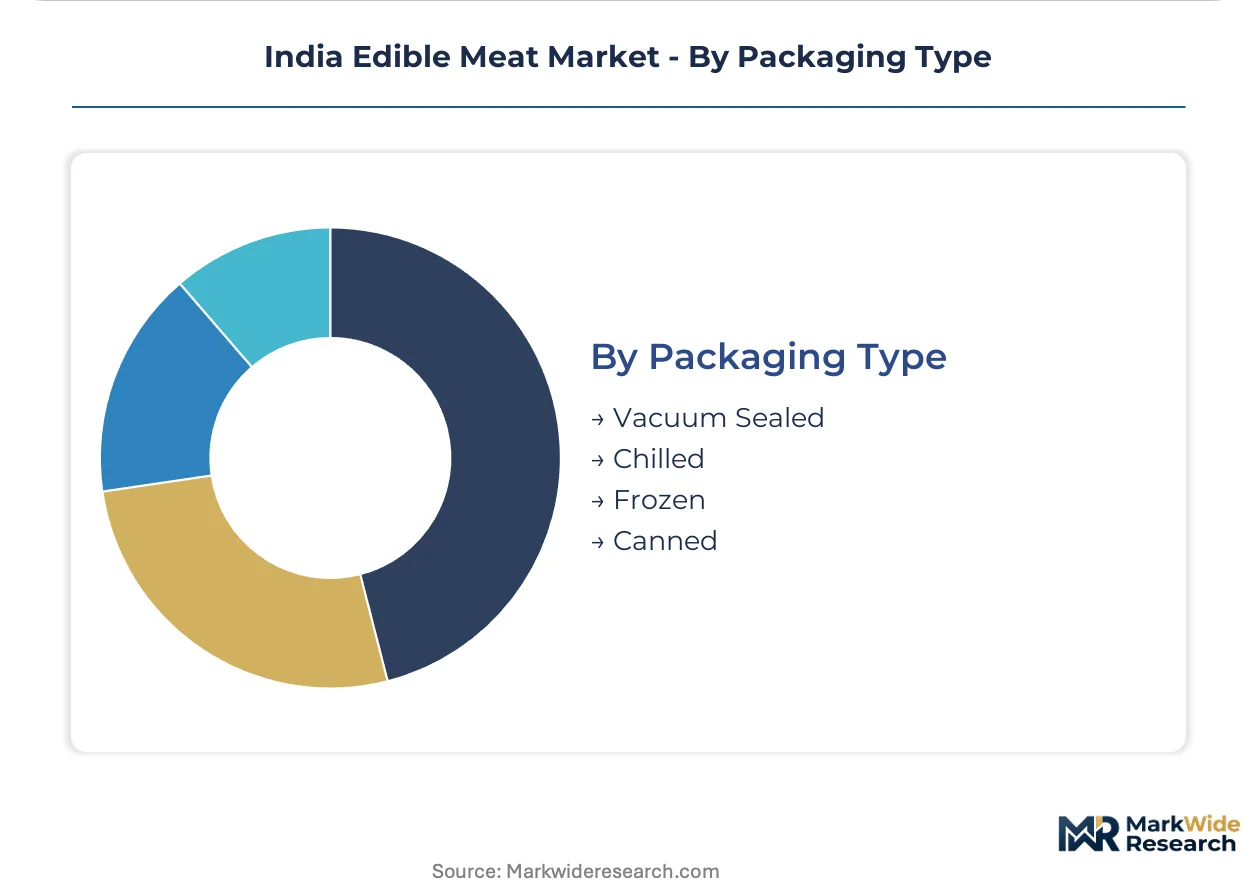
Packaging Type:
Technology maturity separates shelf-life extension capabilities across processing investment tiers.
- Frozen:Energy-intensive storage requirements lock working capital but enable inter-state movement despite veterinary certification delays. Traditional premium for stability erodes as controlled-atmosphere alternatives advance.
- Chilled:MAP-lined trays enable quick-service operators in Karnataka to shift volume from frozen storage to refrigerated distribution with lower capital intensity.
- Vacuum Sealed:Retail display optimization in modern trade outlets with extended shelf-life claims.
- Canned:Limited penetration concentrated in institutional emergency procurement and export buffer stocks.
Frozen formats retain the dominant share, though chilled packaging is expanding most quickly through quick-service adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Maharashtra commands pricing premiums through organized cold-chain density while Uttar Pradesh trades at spreads reflecting fragmented wet-market dominance. Karnataka's quick-service corridor extracts yield efficiencies unavailable in eastern supply zones. This asymmetry concentrates processor investment along western and southern logistics spines.
Maharashtra
Mumbai's quick-service chains and cloud kitchens drive chilled-cut procurement standardization through daily delivery contracts. FSSAI's HACCP licensing mandates filter sub-scale processors from modern retail channels. The Mumbai-Pune corridor anchors integrated poultry operations with captive refrigeration networks serving organized food service.
Karnataka
Bangalore's metropolitan kitchen density supports specification-driven procurement platforms consolidating aggregator demand. State-level cattle movement restrictions force processors to maintain redundant sourcing relationships across borders. The Bangalore-Mysore belt hosts controlled-atmosphere packaging adoption for retail-display chilled products.
Uttar Pradesh
Noida and Ghaziabad's cloud kitchen clusters migrate procurement from spot markets to centralized digital portals. FSSAI enforcement actions against non-compliant cold-chain operators accelerate formalization pressure. The NCR periphery concentrates buffalo meat processing aligned with export protocol requirements.
Tamil Nadu
Chennai's institutional catering contracts bypass traditional mandi intermediaries through direct procurement platforms. Feed cost volatility from maize and soybean meal inflation compresses southern integrated poultry margins. The Coimbatore-Salem corridor sustains broiler volume through contract farming arrangements with processor-tied cold storage.
West Bengal
Kolkata's rising urban income profiles outpace organized retail meat infrastructure development, creating white-space demand. Veterinary certification bottlenecks at state slaughterhouses delay processing schedules during festival demand spikes. The Kolkata metropolitan zone presents expansion opportunity for FSSAI-compliant processors with refrigerated distribution capability.
India Edible Meat Market Competitive Landscape
Vertically integrated processors and export-focused abattoir operators split the market along cold-chain capability lines. Concentration favors entities with captive refrigeration networks and FSSAI-compliant licensing portfolios. Three archetypes dominate: integrated poultry operators controlling feed-to-retail value chains, buffalo meat exporters with Middle Eastern protocol alignment, and branded retail specialists penetrating modern trade. Competitive moves center on backward integration into feed milling and cold-chain fleet expansion.
Among integrated poultry operators, Suguna Foods Private Limited and Venky's India exemplify archetypes differentiated by regional density versus branded retail penetration. Allanasons Private Limited anchors the export-specialist tier through vertically controlled abattoir networks. These entities represent strategic positioning around captive supply consistency, modern trade shelf access, and international protocol compliance rather than commodity spot-market participation.
| Leading Market Players |
|---|
| Allanasons Private Limited |
| Al Hamd Agro Food Products Private Limited |
| Suguna Foods Private Limited |
| Allana Group |
| Fair Exports India Private Limited |
| Venky's India |
| M. K. Overseas Private Limited |
| VH Group |
| HMA Agro Industries Limited |
| Others |
Supply & Pricing Matrix
The Mumbai-Pune corridor anchors integrated poultry operations whose captive cold-chain density translates directly into pricing power over fragmented wet-market competitors. FSSAI compliance costs and feed input volatility compress margins for sub-scale processors while concentrating margin capture among operators with backward integration into feed milling.
Pricing Analysis
Configured-to-order pricing for quick-service chains commands a 15-20% premium over standard wet-market rates, with specification-driven contracts standardizing cut grades and delivery windows. Three-tier pricing structure across premium branded retail, standard modern trade, and economy wet-market tiers reflects certification grade and cold-chain investment levels. Pricing pressure stems from maize and soybean meal cost volatility that squeezes southern integrated poultry margins. Quick-service chains exhibit lowest price sensitivity due to yield guarantee requirements, while household retail segments remain highly elastic to spot-market fluctuations.
Supply Chain Analysis
Upstream feedstock sourcing for Indian poultry operations draws from domestic maize belts in Karnataka and Andhra Pradesh alongside imported soybean meal shipments through Chennai and Visakhapatnam ports. Livestock procurement for buffalo meat exports hinges on cattle availability across Maharashtra, Uttar Pradesh, and Telangana with state-level movement restrictions fragmenting supply continuity. Single-source vulnerability concentrates in third-party refrigerated logistics where non-standard temperature monitoring exposes processors to FSSAI enforcement actions. Distribution runs through wholesale channels consolidating cloud kitchen and quick-service demand, bypassing traditional mandi intermediaries in metropolitan corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat story where regulatory entrenchment through FSSAI licensing creates sustainable competitive advantage. Mandatory HACCP certification and real-time temperature logging mandates erect barriers that favor incumbents with compliance infrastructure already deployed.
For Market Incumbents: Build regulatory compliance moats by accelerating FSSAI digital licensing portal adoption and retrofitting captive fleets with IoT temperature monitoring before enforcement windows tighten. Deepen upstream control over feed milling capacity in Karnataka and Andhra Pradesh to buffer maize price volatility that threatens southern integrated operations. Cloud kitchen aggregator consolidation represents the primary demand-side threat requiring contracted volume lock-in through specification guarantees. For New Entrants and Emerging Players: Eastern state cold-chain white-space in Odisha and West Bengal offers the most penetrable entry point, with Kolkata's rising urban income profiles outpacing organized retail meat infrastructure development. Hospital and corporate catering contracts migrating to digital procurement portals provide a direct institutional go-to-market angle that bypasses entrenched wet-market relationships and captures volume at contracted pricing with traceability documentation requirements. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors integrated operators with captive cold-chain networks over asset-light trading entities exposed to logistics fragmentation. Long-term viability across a 5-10 year window rests on backward integration depth and export protocol alignment with Middle Eastern markets. The signal to watch is state-level cattle slaughter regulation liberalization that would unlock buffalo meat processing capacity concentration in currently restricted corridors.| Strategic Initiative | Industry Significance |
|---|---|
| Cold-Chain Fleet Expansion | Captive refrigerated distribution locks in quick-service contract renewals in Mumbai and Bangalore corridors. |
| Feed Milling Backward Integration | In-house maize and soybean meal processing insulates poultry margins from commodity price volatility. |
| FSSAI Compliance Digitization | Real-time temperature logging infrastructure accelerates licensing timelines and blocks sub-scale competitors. |
| Export Protocol Alignment | BIS certification convergence with Middle Eastern standards opens channel expansion for buffalo meat processors. |
| Direct-to-Institutional Platforms | Digital procurement portals for hospital and corporate catering bypass traditional mandi intermediaries. |
Research Methodology
The analysis maps poultry, buffalo meat, mutton, and pork sub-sectors, each validated through primary interviews with meat processing unit operators, cold-chain logistics providers, quick-service procurement heads, and FSSAI licensing officers. Secondary validation drew from FSSAI regulatory filings, BIS certification databases, state-level livestock movement notifications, and customs export documentation. Bottom-up volume estimates from processor capacity utilization triangulated against top-down protein consumption surveys.
Assumptions held fixed include FSSAI enforcement intensity, state-level slaughter regulations, and feed cost volatility bands; scenarios varied cloud kitchen penetration rates and organized retail cold-chain expansion pace across the analysis window. Segmentation modeling covered product type, distribution channel, customer type, and packaging format dimensions with regional regulatory clusters treated as separate forecast strata. CAGRs derived from fitted growth curves calibrated to historical protein consumption elasticity against urban income trends.
Macroeconomic conditions sit as an overlay; deviation in rural income growth, feed commodity prices, or state-level regulatory liberalization would shift the trajectory materially. Cross-checking against National Sample Survey Office household consumption expenditure benchmarks is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Meat Products
Rendered Poultry Products Market
Meat Products
Qatar Poultry Meat Market
Meat Products
Grassfed Jerky Market
Meat Products
Low Fat Sausage Market
Meat Products
Europe Animal Protein Market
Meat Products
Global Red Meat Market
Meat Products
Kosher Beef Market
Meat Products
Europe Canned Meat Market
Meat Products
Meat Emulsions Market
Meat Products
Lab-Grown Meat Market
Meat Products
Meat Mincers Market
Meat Products
United States Poultry Meat Market
Meat Products
Meat Market
Meat Products
Saudi Arabia Goat Meat and Cheese Market
Meat Products
Vegan Meatball Market
Meat Products
Middle East Edible Meat Market