
 Organic Beef Meat Market | 2026-2036
Organic Beef Meat Market Size, Share, and Industry Trends Forecast 2026-2036
Organic Beef Meat Market Analysis
EU Green Deal agricultural standards are rebalancing the cost-of-entry calculus for organic beef producers seeking access to European retail channels. Tyson Foods Inc. leverages its vertically integrated feedlot network to secure certified organic grain supplies at scale. JBS S.A. competes through South American pasture-to-processing traceability systems that satisfy EU import documentation. Perdue Farms anchors its position with dedicated organic beef processing lines that reduce cross-contamination risk during slaughter and fabrication.
Organic beef meat denotes cattle raised on certified organic feed without synthetic hormones, antibiotics, or genetically modified organisms, with animals receiving year-round pasture access per USDA Organic and equivalent standards; the meat typically grades Choice or Select with marbling scores below Prime conventional counterparts, serving premium food service and retail channels where provenance verification commands price premiums. Ground beef dominates volume throughput in retail and food service channels due to its versatility and lower per-unit price point, while steaks capture disproportionate margin pools in direct-to-consumer and specialty butcher segments. Vacuum pack formats extend shelf life and reduce spoilage rates during cold chain distribution, making this packaging type the default for wholesale and export-oriented supply chains.
USDA Organic certification governs feed sourcing, pasture management, and processing segregation within the United States, while EFSA and national regulators across EU member states enforce equivalent standards through the EU Organic Regulation. BIS in India and equivalent bodies in emerging supply jurisdictions are developing national organic livestock standards that will determine future market access for exporters. Stakeholders must monitor divergence between pasture-based and grain-finished organic certification pathways, as consumer preference and regulatory interpretation of animal welfare standards continue to evolve without harmonization across major import markets.
Market Dynamics
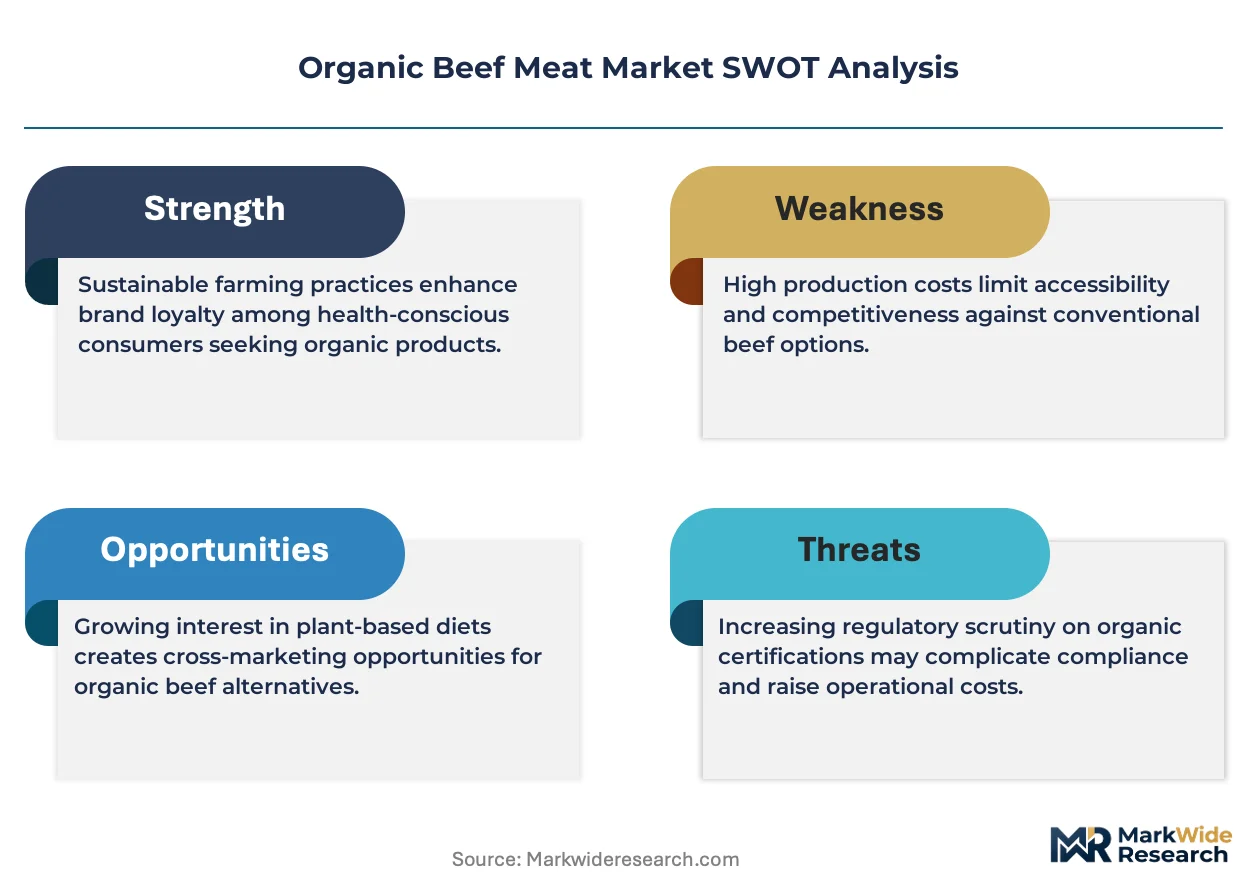
USDA Organic and EU Green Deal feed-access mandates are compressing finishing timelines while extending pasture requirements, forcing producers to choose between certification pathways with incompatible cost structures.
Growth Catalysts
- EU Green Deal agricultural standards:Tightening pasture-access rules for imported beef are accelerating certified organic herd conversions in Argentina and Australia to maintain European retail channel access.
- Premium food service procurement:Michelin-rated restaurants in Paris, New York, and Tokyo are mandating third-party organic certification for beef tenderloin and ribeye programs.
- Blockchain-enabled traceability:Distributed ledger systems tracking individual animal movement from birth through processing are reducing documentation friction for cross-border organic shipments.
Market Restraints
- Certified organic grain supply concentration:Domestic organic corn and soybean production in the United States remains insufficient, forcing reliance on Canadian and Argentine imports subject to currency and weather volatility.
- Technical limitation in marbling:Grass-finishing protocols under strict organic standards produce beef grading Select or low Choice, excluding producers from Prime-tier pricing pools.
- Regulatory friction from non-harmonized standards:USDA Organic permits 120-day grain finishing while EU organic regulations mandate 60% lifetime roughage minimum, blocking dual-certification efficiency.
Strategic Opportunities
- Direct-to-consumer subscription channels:E-commerce platforms shipping frozen organic beef boxes bypass conventional wholesale markups while capturing full retail margin.
- Cellular agriculture regulatory frameworks:FDA and USDA joint oversight protocols for cultivated meat create precedent for hybrid labeling that may expand consumer acceptance of novel protein categories.
- Carbon credit stacking on pasture operations:Soil carbon sequestration verification through Verra standards allows organic cattle ranchers in Brazil and Uruguay to monetize rotational grazing beyond beef sales.
Industry Challenges
- Cross-contamination risk management:Dedicated organic processing lines require capital expenditure for segregated slaughter and fabrication equipment that smaller packers cannot amortize.
- Veterinary protocol conflicts:Therapeutic antibiotic use bans under organic certification leave producers dependent on extended withdrawal periods and alternative treatments with variable efficacy.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Organic Beef Meat Market |
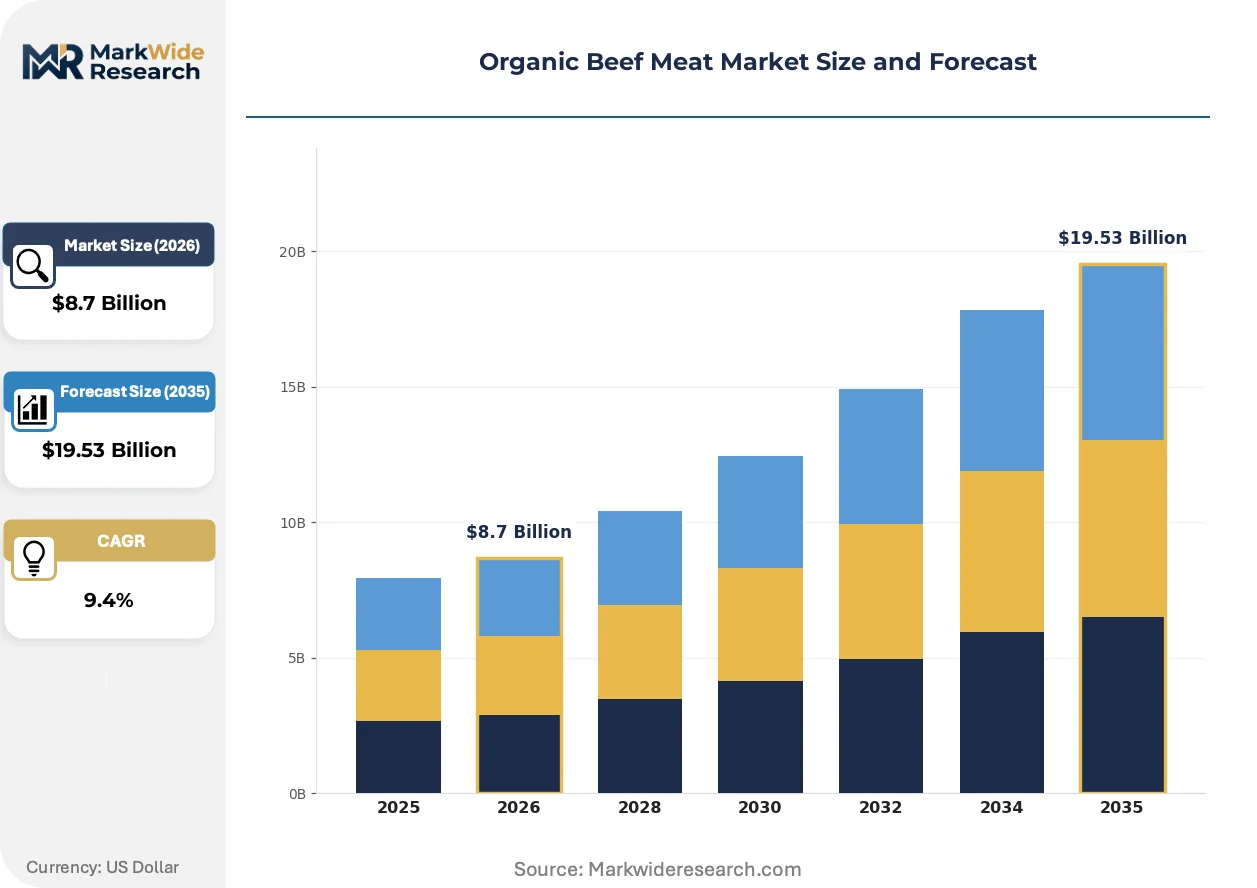
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $19.53 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ground Beef, Steaks, Roasts, Sausages End User: Restaurants, Retail Chains, Online Consumers, Butchers Distribution Channel: Direct Sales, Wholesale, E-commerce, Food Service Packaging Type: Vacuum Pack, Tray Pack, Canned, Bulk |
| Companies Covered | Tyson Foods Inc., Perdue Farms, JBS S.A., Verde Farms, Danish Crown, Eversfield Organic Ltd., Hormel Foods Corporation, Woolworths Group Limited, Meyer Natural Foods, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Organic Beef Meat Market Emerging Trajectories
Digital traceability infrastructure and alternative protein positioning are reshaping how organic beef producers differentiate against both conventional premium meat and emerging cellular agriculture competitors.
Blockchain-based provenance tracking is converging with radio-frequency identification ear tags to create immutable animal-level records from pasture to retail. Specialty butcher shops in Copenhagen and San Francisco are piloting QR-code-linked origin stories. This transparency infrastructure is compressing information asymmetry between distant producers and urban consumers.
EU Green Deal agricultural standards are tightening methane emission reporting requirements for livestock imports. The European Food Safety Authority is developing lifecycle assessment protocols that will penalize feedlot-finished organic beef against pasture-only alternatives. German and Dutch supermarket chains are already screening suppliers against preliminary carbon-intensity thresholds.
Certification-driven preference shifts are fragmenting wholesale procurement patterns. Large food service distributors in Chicago and London are unbundling organic and conventional beef SKUs into separate supplier relationships. This channel disintermediation is most visible in university and corporate cafeteria contracts where sustainability officers now hold veto power over protein sourcing decisions.
Organic Beef Meat Market Segmentation
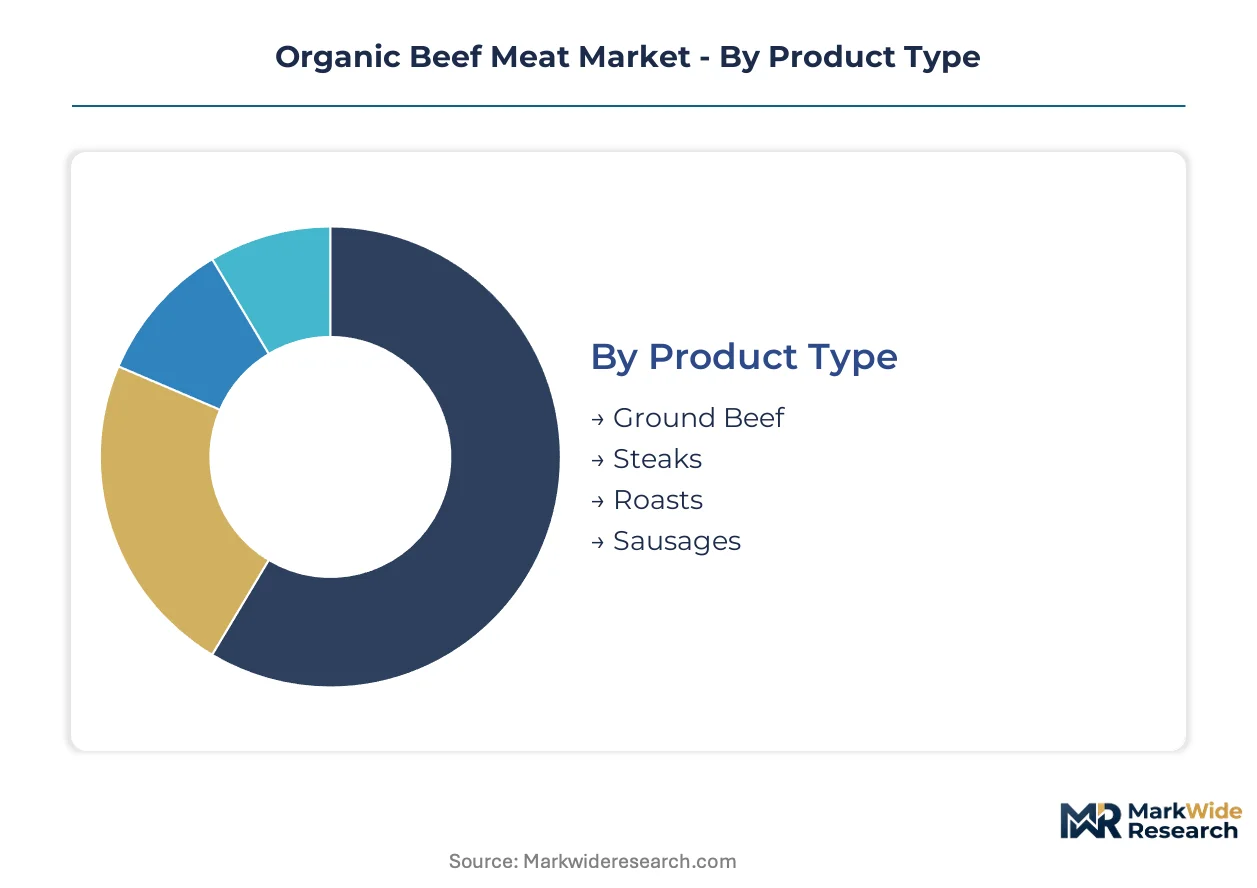
Segmentation in organic beef reveals how certification requirements and channel economics split procurement patterns. Each dimension exposes different margin structures and regulatory exposure for producers and distributors.
Product Type:
Supply concentration varies sharply across cuts, with grinding operations absorbing the majority of certified organic cattle throughput.
- Ground Beef:Trim and chuck blends dominate volume throughput in retail and food service channels due to versatility and lower per-unit price point. Mass-market grocers in the United States and Germany concentrate procurement here, constrained by EU Green Deal methane reporting thresholds that disadvantage grain-finished inputs.
- Steaks:Ribeye and tenderloin cuts capture disproportionate margin pools in direct-to-consumer and specialty butcher segments. Michelin-rated restaurants in Paris, New York, and Tokyo mandate third-party organic certification for these premium cuts, compressing available supply.
- Roasts:Chuck and round roasts serve institutional food service and meal-kit subscription channels with moderate price elasticity.
- Sausages:Processed organic beef links occupy niche positions in German and Austrian retail, limited by strict EFSA additive restrictions.
Ground beef absorbs the bulk of installed capacity; steaks are expanding most quickly.
End User:
Customer type determines certification stringency and traceability investment levels required for market access.
- Restaurants:Premium food service procurement now mandates third-party organic certification for beef programs. White-tablecloth establishments in Copenhagen and San Francisco pilot QR-code-linked origin stories, demanding blockchain-enabled traceability infrastructure.
- Retail Chains:German and Dutch supermarket chains screen suppliers against preliminary carbon-intensity thresholds, fragmenting wholesale procurement patterns into separate organic and conventional supplier relationships.
- Online Consumers:Direct-to-consumer subscription channels bypass conventional wholesale markups while capturing full retail margin through frozen beef box shipments.
- Butchers:Specialty butcher shops in Copenhagen and San Francisco anchor neighborhood-level provenance verification with animal-level record transparency.
Retail chains command the largest procurement volumes; online consumers show the steepest expansion trajectory.
Distribution Channel:
Channel selection dictates cold chain requirements and documentation friction for cross-border organic shipments.
- Direct Sales:Ranch-to-restaurant relationships eliminate intermediary margins but require producers to maintain USDA Organic processing segregation and EU import documentation capabilities.
- Wholesale:Large food service distributors in Chicago and London unbundle organic and conventional beef SKUs, creating separate supplier relationships with sustainability officer veto power over sourcing decisions.
- E-commerce:Frozen distribution platforms extend shelf life through vacuum pack formats, reducing spoilage rates during last-mile delivery.
- Food Service:University and corporate cafeteria contracts now require dedicated organic processing lines to reduce cross-contamination risk during slaughter and fabrication.
Wholesale channels handle the greatest tonnage; e-commerce is climbing the fastest.
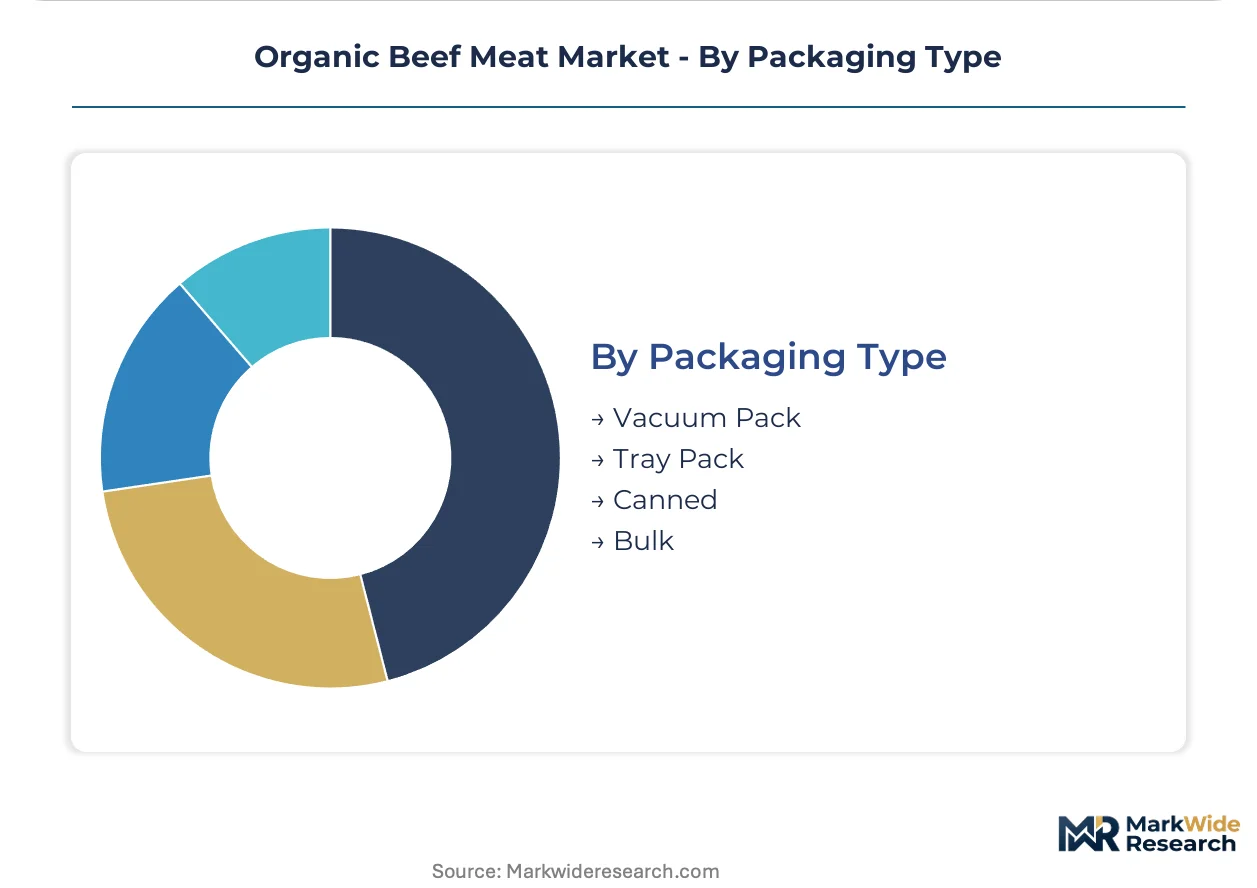
Packaging Type:
Packaging technology determines shelf-life extension and export market access for distant supply origins.
- Vacuum Pack:Barrier film formats extend shelf life and reduce spoilage rates during cold chain distribution, making this the default for wholesale and export-oriented supply chains from Australia and Argentina.
- Tray Pack:Modified atmosphere packaging serves fresh retail counters in domestic markets with shorter logistics cycles and higher turnover velocity.
- Canned:Thermally processed organic beef occupies emergency preparedness and military procurement niches with extended stability requirements.
- Bulk:Food service totes and combo bins minimize unit packaging costs for grinding operations and institutional buyers with immediate processing capabilities.
Vacuum pack dominates export infrastructure; tray pack leads domestic retail penetration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Premium restaurant procurement in Paris, New York, and Tokyo concentrates demand for certified organic tenderloin and ribeye cuts, while export-oriented finishing operations in Argentina, Australia, and the United States supply cross-border wholesale channels.
United States
Direct-to-consumer subscription channels and university cafeteria contracts drive procurement volume for USDA Organic certified ground beef and steaks. The USDA administers certification through accredited third-party agencies with strict feed-source verification and 120-day grain-finishing allowances. Tyson Foods anchors large-scale supply through vertically integrated feedlot networks in the Midwest and Southern Plains.
Germany
Discounters and supermarket chains in Berlin and Hamburg screen suppliers against preliminary carbon-intensity thresholds under EU Green Deal agricultural standards. EFSA develops lifecycle assessment protocols that penalize feedlot-finished organic beef against pasture-only alternatives. Bavarian and Lower Saxony processors invest in dedicated organic processing lines to serve export demand from Dutch and Danish retail buyers.
Argentina
European retail channel access accelerates certified organic herd conversions in the Pampas region to satisfy tightening pasture-access rules for imported beef. The national agricultural regulator enforces equivalency agreements with EU Organic Regulation standards for cross-border shipments. Buenos Aires province concentrates export-oriented finishing operations with blockchain-enabled traceability systems.
Australia
Vacuum-packed organic beef exports to Japan, South Korea, and the United States dominate throughput from Queensland and New South Wales cattle operations. The Department of Agriculture, Water and the Environment administers export certification aligned with USDA Organic and EU equivalency protocols. Melbourne and Sydney processors specialize in wholesale and food service distribution with cold chain infrastructure spanning Asia-Pacific markets.
France
Michelin-rated restaurants in Paris mandate third-party organic certification for beef programs, compressing available supply of premium cuts. The national organic regulator enforces EU Organic Regulation with 60 percent lifetime roughage minimums that block dual-certification with USDA standards. Auvergne-Rhône-Alpes and Provence-Alpes-Côte d'Azur ranchers supply regional butcher networks with pasture-only finishing protocols.
Organic Beef Meat Market Vendor Landscape
United States producers anchor one tier; South American and Australian specialists hold export-oriented positions with pasture-to-processing traceability systems. The vendor base splits between vertically integrated agribusiness conglomerates and mid-scale organic-only operators with dedicated certification pathways. Three archetypes dominate: scale-driven commodity suppliers, premium-tier provenance specialists, and direct-to-consumer subscription platforms. Capacity expansion in segregated organic processing lines and backward integration into certified grain supply represent the dominant competitive moves.
Within the scale-driven tier, Tyson Foods Inc. and JBS S.A. occupy positions that exemplify divergent geographic strategies—Tyson through North American feedlot integration, JBS through South American pasture-based traceability. Perdue Farms represents the mid-scale specialist archetype with dedicated organic processing infrastructure. These three entities illustrate how certification compliance and channel access separate competitive positioning in wholesale and food service procurement.
| Leading Market Players |
|---|
| Tyson Foods Inc. |
| Perdue Farms |
| JBS S.A. |
| Verde Farms |
| Danish Crown |
| Eversfield Organic Ltd. |
| Hormel Foods Corporation |
| Woolworths Group Limited |
| Meyer Natural Foods |
| Others |
Supply Flow & Price Mechanics
Organic corn and soybean futures traded on the Chicago Board of Trade cascade through feedlot cost structures into finished beef pricing tiers, compressing margins for grain-finished operators while pasture-based producers capture certification premiums. The divergence between USDA Organic and EU Green Deal feed-access mandates fragments procurement economics, forcing buyers to navigate incompatible cost structures across certification pathways.
Pricing Analysis
Ground beef absorbs volume throughput at compressed margins while steaks command disproportionate margin pools in direct-to-consumer channels. Three-tier pricing structure across premium, standard, and economy levels separates pasture-only EU-certified cuts from USDA Organic grain-finished product and conventional premium beef. Pricing pressure stems from certified organic grain supply concentration in Canada and Argentina, subject to currency and weather volatility. University cafeteria contracts exhibit highest price sensitivity; Michelin-rated restaurants in Paris and Tokyo show least sensitivity, mandating third-party certification regardless of cost.
Supply Chain Analysis
Certified organic grain supply rests on Canadian prairie producers and Argentine Pampas farmers, with Australian pasture operations providing roughage-dependent alternatives. Key inputs include organic corn, organic soybeans, and third-party certified mineral supplements. Single-source vulnerability concentrates in Midwestern organic feed processing facilities serving Tyson Foods and Perdue Farms networks. Distribution runs through vacuum-packed wholesale channels for export-oriented supply chains, with direct-to-consumer subscription platforms bypassing conventional markups.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Certified organic processing line capacity constraints prop pricing premiums across all tiers, creating a supply-constrained market structure where dedicated infrastructure investments yield sustained margin capture.
For Market Incumbents: Extend backward integration into certified organic grain supply to secure captive feed sources against Argentine and Canadian import volatility. Lock in long-term pasture leases in Queensland and New South Wales to satisfy EU Green Deal methane reporting thresholds. Cellular agriculture entrants threaten premium positioning; counter through blockchain-enabled traceability investments that cultivated meat cannot replicate. For New Entrants and Emerging Players: Blockchain-based provenance verification offers a technology-first wedge against established packers lacking animal-level transparency infrastructure. Target direct-to-consumer subscription channels in Germany and the Netherlands, where carbon-intensity screening fragments wholesale procurement and creates white-space for bypass relationships. Launch with QR-code-linked origin stories to capture urban consumer premiums in Copenhagen and San Francisco specialty butcher networks. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-scale organic-only operators with dedicated certification pathways in Australia's Queensland cattle belt. Five-to-ten year viability hinges on EU equivalency maintenance and carbon credit stacking monetization through Verra soil sequestration standards. Watch EU Green Deal lifecycle assessment protocol finalization as the inflection trigger that penalizes grain-finished against pasture-only supply.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Certified Feed Supply | Tyson Foods secures organic corn and soybean volumes against Argentine currency volatility. |
| Dedicated Organic Processing Line Investment | Perdue Farms reduces cross-contamination risk while capturing USDA Organic certification premiums. |
| Blockchain Traceability Implementation | JBS S.A. satisfies EU import documentation requirements through pasture-to-processing records. |
| Carbon Credit Stacking Program | Brazilian and Uruguayan ranchers monetize rotational grazing beyond beef sales through Verra verification. |
| Direct-to-Consumer Subscription Launch | E-commerce platforms capture full retail margin while bypassing conventional wholesale markups. |
Methodological Framework
Multi-period observation of certified organic cattle inventory, feed grain price indices, and EU import certification volumes anchored the trend analysis, supplemented by interviews with USDA-accredited certifiers, feedlot procurement managers, and EFSA regulatory affairs specialists. Secondary validation drew from USDA National Agricultural Statistics Service reports, EU Organic Regulation implementation guidance, Australian Department of Agriculture export certification databases, and customs trade records. Bottom-up cattle inventory modeling triangulated against top-down channel revenue estimates.
Segment-weighting across product type, end user, distribution channel, and packaging format dimensions shaped the analytical framework across the analysis window. CAGRs derived from logistic adoption curves for certification penetration and price elasticity modeling for grain-finished versus pasture-only segments. Industry-specific inputs included EU Green Deal methane reporting threshold development timelines and blockchain traceability infrastructure deployment rates in Argentine and Australian export operations.
Forecast precision tightens around the base case; tail outcomes carry wider variance under regulatory divergence between USDA Organic and EU Green Deal standards. Forecasts reflect assumptions regarding certification equivalency maintenance and organic grain supply stability. Feedlot disease outbreaks, trade policy shifts, or accelerated cellular agriculture regulatory approvals warrant ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Meat Products
Hot Dog and Sausages Market
Meat Products
Hams Market
Meat Products
Middle East Poultry Meat Market
Meat Products
Canned Chicken Market
Meat Products
North America Processed Meat Market
Meat Products
Meat Market
Meat Products
Organic Halal Meat Market
Meat Products
Bacon Slicers Market
Meat Products
North America Low Fat Sausage Market
Meat Products
Animal Protein Market
Meat Products
Germany Meat Products Market
Meat Products
Global Lab-Based Meat Market
Meat Products
Europe Animal Protein Market
Meat Products
Poultry Processing Meat Market
Meat Products
India Animal Protein Market
Meat Products
Beef Bone Broth Market