
 Beef Jerky Market | 2026-2036
Beef Jerky Market Size, Share, and Industry Trends Forecast 2026-2036
Beef Jerky Market Analytics
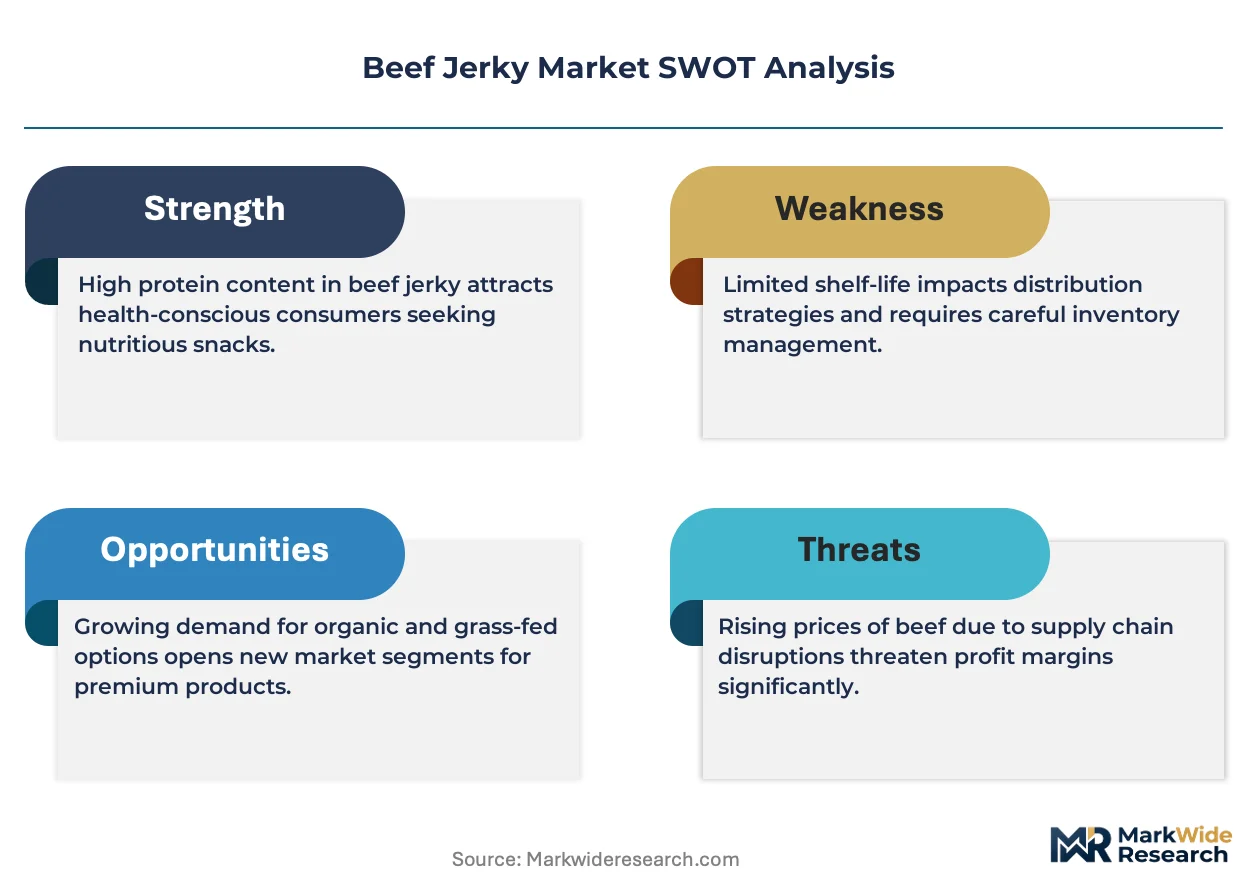
Australia is tilting toward expanded bovine processing capacity to serve export-ready dried-meat demand. Conagra Brands leverages its refrigerated-snacks infrastructure to sustain broad retail penetration across North American mass channels. Chomps competes through grass-fed positioning and clean-label formulations that anchor premium price points in natural grocery.
Beef jerky consists of thin strips of lean beef preserved through salt curing, dehydration, or low-temperature smoking to achieve moisture levels below 50 percent, yielding shelf-stable protein with extended ambient durability. The product serves commercial channels requiring portable, high-protein rations with minimal refrigeration dependency. Original and hickory smoked flavor profiles dominate mainstream velocity, while spicy formulations capture faster-turning placement in convenience and club formats. Resealable bags command disproportionate margin pools by reducing per-ounce packaging cost and driving repeat-purchase loyalty among retail consumers.
USDA FSIS inspection protocols and HACCP compliance requirements govern domestic production facility authorization, while FDA oversees imported jerky under the Food Safety Modernization Act's foreign supplier verification programs. These frameworks elevate capital barriers for new processing entrants and redirect import sourcing toward audited overseas suppliers. Stakeholders must monitor evolving sodium-reduction guidance from health agencies and corresponding reformulation investments that could reshape competitive cost structures.
Market Dynamics
Protein-forward snacking among outdoor enthusiasts is compressing traditional retail cycles and forcing shelf-space reallocation toward convenience channels with minimal refrigeration dependency. This demand migration is tightening compliance thresholds for imported product entry under USDA inspected-establishment requirements and FSIS labeling mandates.
Growth Catalysts
- FSIS Labeling Mandates:USDA inspection protocols are elevating capital barriers for new processing entrants, redirecting import sourcing toward audited overseas suppliers with verified HACCP compliance.
- Convenience Channel Expansion:Protein-forward snacking among outdoor enthusiasts is expanding shelf space in gas stations and travel centers, displacing traditional candy and chip placements.
- Resealable Packaging Technology:Advanced barrier film innovations are reducing per-ounce packaging cost and driving repeat-purchase loyalty among retail consumers through extended product freshness.
Market Restraints
- Beef Input Cost Volatility:Lean beef strip sourcing faces price pressure from competing protein demand and feed grain cost fluctuations, compressing processor margin pools.
- Import Concentration Risk:Foreign supplier verification programs under FDA's Food Safety Modernization Act are concentrating import sourcing among a narrow band of audited overseas suppliers.
- Sodium Reduction Technical Limitation:Health agency reformulation guidance requires alternative curing agents that alter shelf stability and taste profiles, demanding R&D investment without guaranteed consumer acceptance.
Strategic Opportunities
- Australian Processing Capacity:Expanded bovine processing infrastructure in Australia is creating export-ready dried-meat supply for North American and Asian market penetration.
- Natural Grocery Channel Innovation:Grass-fed and clean-label positioning is capturing premium velocity in specialty retail formats with higher margin capture than mass channels.
- EU Green Deal Alignment:Sustainability certification and carbon footprint labeling requirements are creating differentiation pathways for processors investing in renewable energy and regenerative sourcing.
Industry Challenges
- HACCP Certification Timeline:USDA FSIS facility authorization requires 12-18 month compliance verification periods, delaying market entry for new processing investments.
- Refrigerated Snacks Integration Complexity:Legacy mass retail distributors face technical hurdles integrating ambient-stable jerky SKUs with temperature-controlled product flows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Beef Jerky Market |
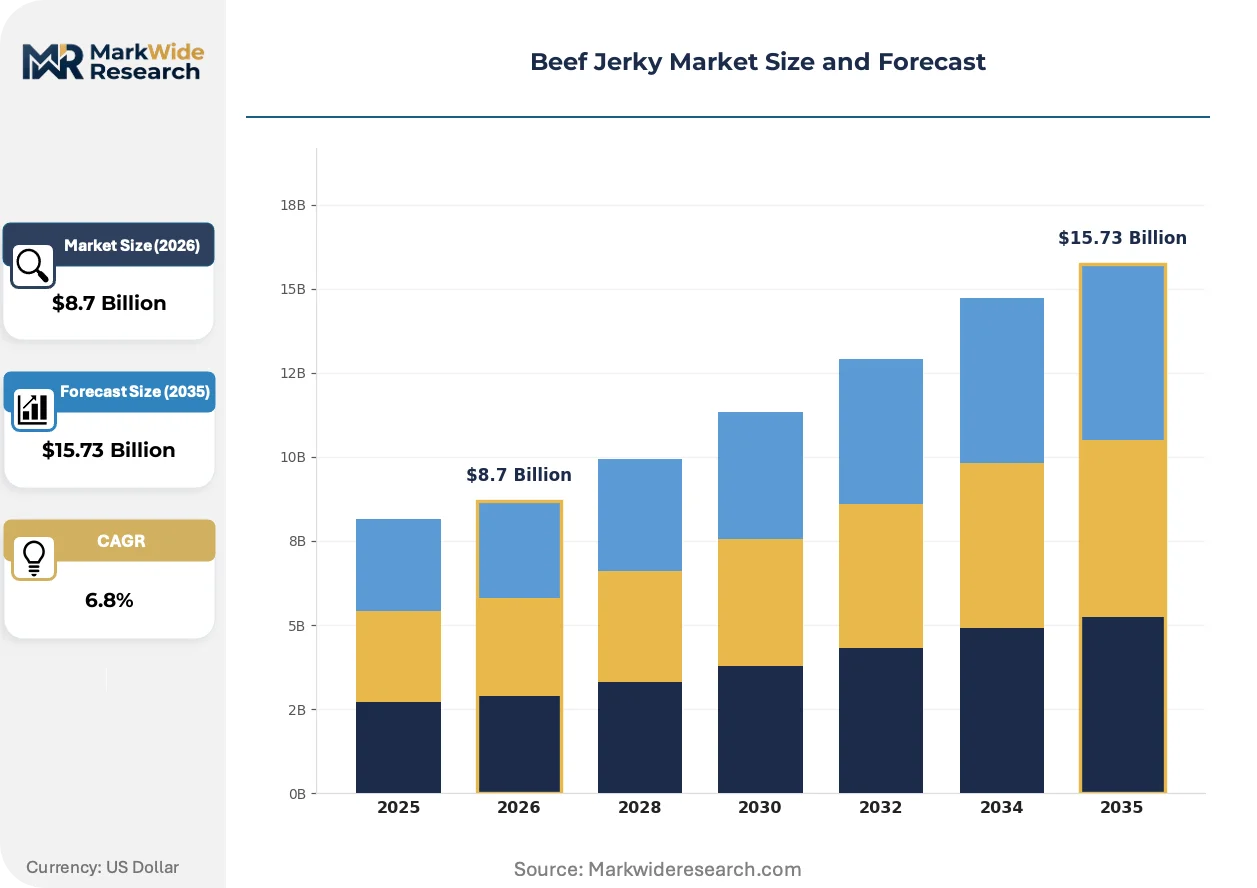
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Flavor Profile: Spicy, Teriyaki, Original, Hickory Smoked Packaging Type: Pouches, Canisters, Resealable Bags, Bulk Packs End User: Retail Consumers, Sports Teams, Outdoor Enthusiasts, Food Service Distribution Channel: Supermarkets, Convenience Stores, Online Retail, Specialty Stores |
| Companies Covered | Golden Island Jerky, Stoney Point Snacks, Conagra Brands, Werner Gourmet Meat Snacks, Jerky Junction, Cedar Creek Beef Jerky, Chomps, Mariani Foods, Country Archer Jerky, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Beef Jerky Market Evolving Landscape
Smart manufacturing and regulatory transparency requirements are compressing production cycles and redefining competitive advantage around traceability and formulation agility. These forces are reshaping how processors invest in technology and how retailers curate their protein snack assortments.
Radio-frequency identification and blockchain traceback systems are digitizing supply chain visibility from slaughterhouse to retail shelf. Premium jerky processors are adopting these tools fastest, responding to retailer demands for lot-level accountability. This digitizing of provenance data is compressing recall response times and enabling real-time inventory optimization.
EU Green Deal sustainability disclosure requirements and corresponding EFSA guidance on processed meat labeling are mandating carbon footprint declarations and regenerative sourcing verification. European retailers are demanding third-party audit documentation before contract renewal. Natural grocery chains in Germany and France are responding by delisting suppliers without certified sustainable beef sourcing.
Outdoor enthusiasts are consolidating purchases through direct-to-consumer subscription models and specialized e-commerce platforms, bypassing traditional brick-and-mortar discovery. This channel disintermediation is fragmenting brand loyalty and rewarding nimble craft processors with targeted digital marketing capabilities. The Pacific Northwest and Rocky Mountain states exhibit the fastest adoption of these subscription-based protein snack replenishment services.
Beef Jerky Market Segmentation
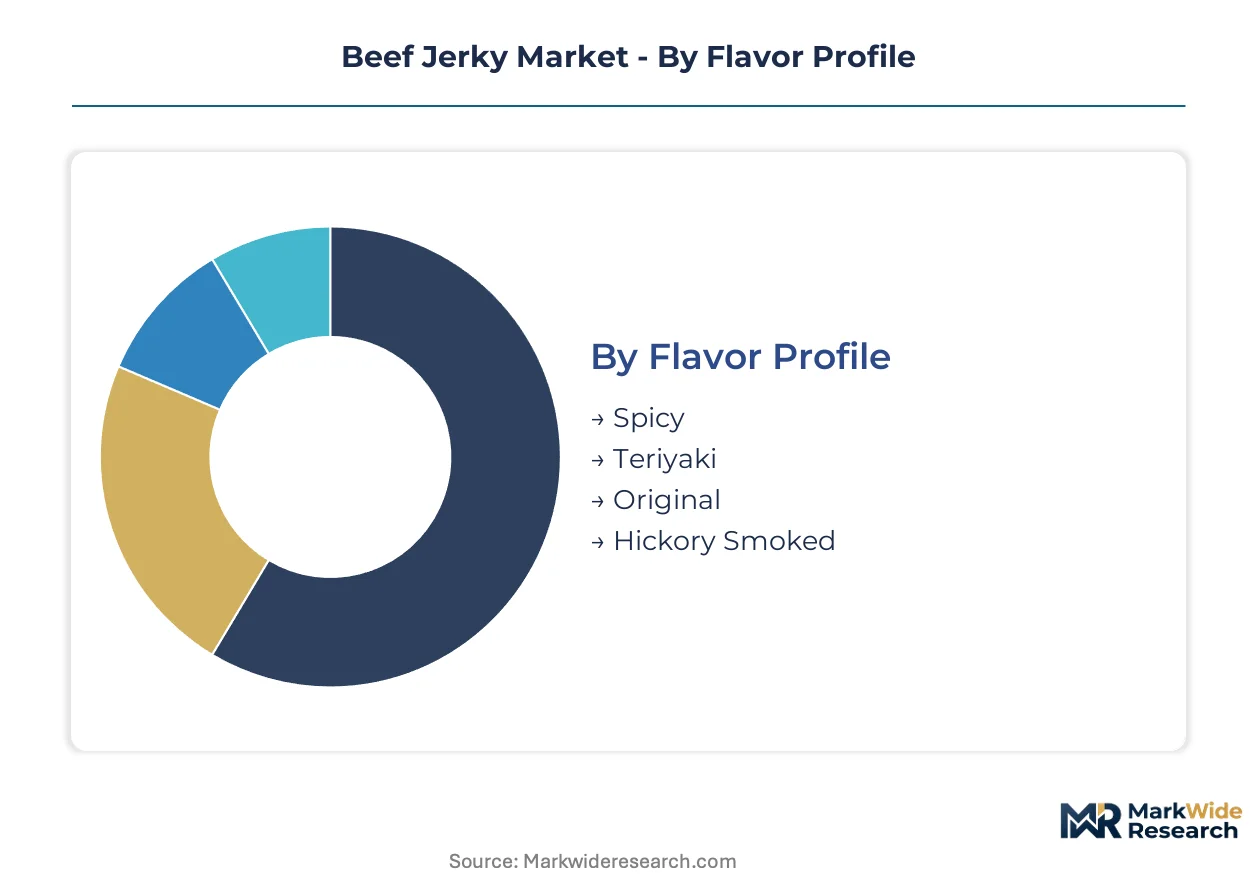
Beef jerky segmentation reveals how flavor innovation, packaging convenience, and channel accessibility create distinct margin pools across consumer occasions. Understanding these divides allows processors to align production capacity with the highest-velocity demand pockets.
Flavor Profile:
Mature mainstream profiles dominate shelf space while emerging formulations capture premium positioning and faster trial rates among younger demographics.
- Original:Unflavored cured beef strips with salt and minimal seasoning represent the baseline formulation with broadest demographic acceptance. Demand concentrates in mass retail channels across the United States where repeat purchase rates sustain inventory turns for legacy brands.
- Hickory Smoked:Slow-smoked strips with hardwood-derived phenolic compounds deliver the dominant mainstream flavor profile in North American convenience stores. Outdoor enthusiasts in the Rocky Mountain states and Pacific Northwest drive disproportionate velocity for this segment through gas station and travel center purchases.
- Spicy:Capsicum-infused formulations targeting heat-seeking consumers in club and convenience formats.
- Teriyaki:Soy-sugar marinated profiles with umami-forward taste positioning in Asian-American demographic clusters.
Original handles the majority of throughput; Spicy is the fastest mover on share.
Packaging Type:
Cost tier differentiation separates premium convenience formats from economy bulk positioning.
- Resealable Bags:Multi-layer barrier film pouches with zip-lock closures extend ambient shelf stability while enabling portion control. Sports teams and outdoor enthusiasts in the United States drive replenishment demand through direct-to-consumer channels where freshness assurance commands price premiums.
- Pouches:Single-serve flexible packaging dominates impulse purchase occasions in convenience stores and vending machines.
- Canisters:Rigid container formats for pantry storage and gift-oriented purchasing occasions.
- Bulk Packs:Large-format multi-pound packaging for food service procurement and institutional buyers.
Resealable Bags capture the highest margin per ounce; Pouches move the largest absolute volume.
End User:
Application-driven segmentation separates at-home consumption from away-from-home protein replenishment needs.
- Retail Consumers:Individual purchasers seeking shelf-stable protein snacks for household pantries and on-the-go consumption. Supermarket and online retail channels in the United States concentrate demand through subscription replenishment models and promotional stocking events.
- Outdoor Enthusiasts:Hikers, campers, and hunters requiring lightweight, non-perishable rations with minimal pack weight. This segment demands highest protein density per ounce and tolerates premium pricing for extended shelf life assurance.
- Sports Teams:Athletic programs and fitness facilities procuring portable protein for training nutrition.
- Food Service:Restaurants, bars, and hospitality operators incorporating jerky into appetizer menus or grab-and-go offerings.
Retail Consumers drive absolute revenue; Outdoor Enthusiasts deliver the steepest expansion trajectory.
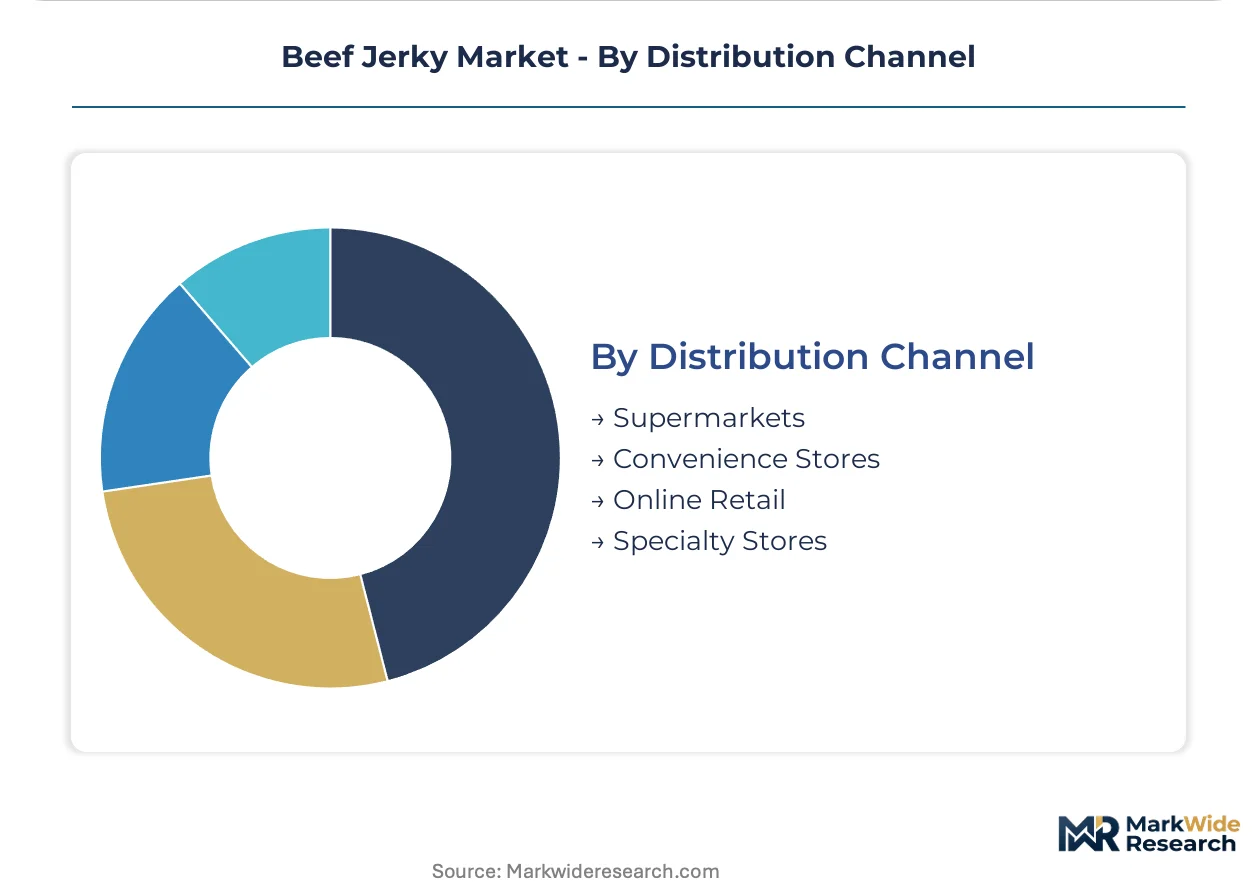
Distribution Channel:
Geography of purchase separates stock-up occasions from immediate consumption needs.
- Convenience Stores:Gas stations and travel centers with extended hours and minimal refrigeration infrastructure. FSIS labeling compliance and USDA establishment certification requirements govern product entry, favoring domestic processors with verified supply chain documentation.
- Supermarkets:Full-assortment grocers with dedicated snack aisles and promotional calendar integration.
- Online Retail:E-commerce platforms and brand-direct subscription services enabling flavor customization and bulk replenishment.
- Specialty Stores:Natural grocers, outdoor retailers, and craft food boutiques with curated premium assortments.
Convenience Stores handle the majority of throughput; Online Retail is climbing the fastest on share.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
USDA FSIS inspection protocols anchor the United States as the dominant geography, with protein-forward snacking demand reshaping retail shelf allocation across multiple continents. Regional expansion patterns diverge between established mass markets and emerging processing hubs seeking export-ready supply.
United States
Outdoor enthusiasts in the Rocky Mountain states and Pacific Northwest drive disproportionate velocity for hickory-smoked formulations through gas station and travel center purchases. USDA inspected-establishment requirements and FSIS labeling mandates tighten compliance thresholds for imported product entry, favoring domestic processors with verified HACCP documentation. Omaha, Nebraska hosts concentrated meat-processing infrastructure where legacy brands leverage refrigerated-snacks distribution networks for mass-channel penetration.
Australia
Export-ready dried-meat demand from North American and Asian buyers is accelerating bovine processing capacity expansion in Queensland and New South Wales. The country's national food safety regulator enforces strict export certification protocols aligned with destination market requirements. Processing clusters near Brisbane are investing in dehydration and low-temperature smoking infrastructure to capture premium positioning in international specialty retail.
Germany
EU Green Deal sustainability disclosure requirements and EFSA guidance on processed meat labeling are mandating carbon footprint declarations from importers and domestic processors alike. Natural grocery chains in Bavaria and Baden-Württemberg are delisting suppliers without certified sustainable beef sourcing documentation. Berlin-based craft food distributors are curating premium jerky assortments that emphasize regenerative sourcing verification and third-party audit trails.
Canada
Cross-border supply integration with United States mass retail channels sustains demand for USDA-compliant production from Alberta and Ontario processing facilities. Health Canada and the Canadian Food Inspection Agency enforce parallel inspection protocols that facilitate seamless export qualification. Calgary-area processors are expanding capacity to serve both domestic convenience store networks and United States club format buyers seeking bulk-pack procurement.
Japan
Umami-forward taste preferences in Tokyo and Osaka metropolitan areas create niche demand for teriyaki-marinated profiles among protein-snacking consumers. METI standards for processed meat imports require rigorous documentation of slaughterhouse origin and curing agent specifications. Nagoya-based food distributors are building relationships with audited overseas suppliers to secure shelf-stable protein placements in convenience store chains with extended freshness requirements.
Beef Jerky Market Competitive Landscape
Capability concentration sits with craft processors mastering clean-label formulations and grass-fed positioning; scale advantage sits with diversified food conglomerates leveraging refrigerated-snacks infrastructure for mass-channel penetration. The vendor base separates into three tiers: legacy mass-market brands, premium natural-grocery specialists, and regional craft processors with direct-to-consumer digital capabilities. Dominant competitive moves include portfolio diversification into alternative protein formats and strategic partnerships with audited overseas suppliers to secure compliant import sourcing.
Among United States-based processors, Conagra Brands exemplifies scale-driven mass-channel penetration, while Chomps occupies a position within the premium natural-grocery tier through grass-fed positioning. Golden Island Jerky represents the craft processor archetype with specialty retail focus. These three anchors illustrate how competitive positioning diverges between convenience store velocity, natural grocery margin capture, and direct-to-consumer subscription models.
| Leading Market Players |
|---|
| Golden Island Jerky |
| Stoney Point Snacks |
| Conagra Brands |
| Werner Gourmet Meat Snacks |
| Jerky Junction |
| Cedar Creek Beef Jerky |
| Chomps |
| Mariani Foods |
| Country Archer Jerky |
| Others |
Value Network & Pricing Analysis
Omaha's concentrated meat-processing infrastructure anchors North American jerky supply, with capacity utilization rates directly transmitting into processor pricing power against retail buyers. USDA FSIS certification requirements create captive supply relationships that insulate verified facilities from spot-market competition, compressing margin pools for unqualified entrants while sustaining premium capture for compliant operators.
Pricing Analysis
Domestic hickory-smoked formulations command price spreads over imported alternatives, reflecting FSIS compliance premiums and refrigerated-snacks distribution integration costs. Three-tier pricing structure across premium grass-fed, standard commodity-fed, and economy private-label levels separates clean-label positioning from mass-channel velocity plays. Pricing pressure stems from lean beef strip cost volatility, with feed grain fluctuations transmitting directly into processor margins. Club format buyers exhibit lowest price sensitivity due to volume procurement efficiencies, while convenience store operators face highest sensitivity from per-ounce shelf space economics.
Supply Chain Analysis
Contract manufacturing concentrates among USDA-inspected co-packers in Nebraska, Alberta, and Queensland, with facility certification timelines creating effective capacity rationing. Raw material flows draw from Australian grass-fed cattle operations, North American feedlot systems, and South American lean beef exporters. Single-source vulnerability runs through narrow bands of audited overseas suppliers under FDA foreign supplier verification programs. Distribution feeds from processor direct-to-retail relationships, third-party snack food distributors, and natural grocery warehouse networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a regulatory-moat defense story, where USDA FSIS certification entrenchment creates switching costs that lock retail buyers into verified supplier relationships. Network effects concentrate in refrigerated-snacks distribution infrastructure, where route density advantages compound across ambient-stable SKU integration.
For Market Incumbents: Insulate market position by deepening backward integration into grass-fed cattle sourcing in Australian processing clusters, securing captive supply against commodity price volatility. Expand HACCP-certified capacity in Queensland to capture Asian export demand growth while defending domestic shelf space against craft jerky entrants through resealable packaging technology refreshes.
For New Entrants and Emerging Players: German natural grocery chains present underpenetrated white space for EU Green Deal-aligned sustainability certification, where carbon footprint labeling requirements favor new entrants with regenerative sourcing stories. Target Berlin-based craft food distributors with third-party audit documentation and subscription-based direct-to-consumer replenishment models bypassing traditional retail slotting fee barriers.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors craft processors with digital-native customer acquisition capabilities and clean-label formulation expertise over legacy mass-market brands facing channel disintermediation. Long-term viability rests on subscription retention economics and specialty retail velocity capture. Monitor direct-to-consumer churn rates and natural grocery delisting patterns as inflection signals for portfolio rebalancing.
| Strategic Initiative | Industry Significance |
|---|---|
| Grass-Fed Supply Certification | Regenerative sourcing verification unlocks EU Green Deal-compliant placement in German natural grocery chains. |
| Resealable Packaging Technology Refresh | Barrier film innovation reduces per-ounce cost and drives repeat-purchase loyalty among outdoor enthusiasts. |
| Direct-to-Consumer Subscription Launch | Pacific Northwest and Rocky Mountain consumers exhibit fastest adoption of protein snack replenishment services. |
| Australian Processing Capacity Expansion | Queensland dehydration infrastructure captures export-ready dried-meat demand from North American and Asian buyers. |
| Blockchain Traceback Integration | Lot-level accountability compresses recall response times and satisfies retailer transparency requirements. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of USDA FSIS establishment databases, FDA import refusal records, and Nielsen retail audit data covering protein snack velocity. Primary interviews engaged brand managers at craft jerky processors, category buyers at natural grocery chains, supply planners at mass retail distributors, and regulatory affairs leads at co-packing facilities. Bottom-up triangulation across flavor profile, packaging type, and channel segmentation dimensions validates top-down market sizing derived from customs trade flows and refrigerated-snacks infrastructure capacity.
Forecast inputs span lean beef commodity price indices, convenience store shelf space reallocation trends, and FSIS certification pipeline backlogs across the projection horizon. Volume and value outputs model flavor profile adoption curves, packaging format margin capture, and regional regulatory cluster penetration. CAGRs derive from segment-level growth rate reconciliation against macro protein-forward snacking demand indicators and outdoor recreation participation trends.
Practitioners should monitor feed grain cost volatility, sodium-reduction guidance revisions, and subscription service churn benchmarks for early signals of forecast deviation. Quarterly review of USDA import establishment approvals, EU Green Deal audit documentation requirements, and direct-to-consumer customer acquisition costs is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Meat Products
Antibiotic Free Meat Market
Meat Products
Beef Liver Market
Meat Products
Western Europe Ready-To-Eat Meat Market
Meat Products
Meat Products Market
Meat Products
Middle-East and Africa Animal-Based Meat and Dairy Products Market
Meat Products
Reduced Fat Meat Market
Meat Products
Global Canned Meat Market
Meat Products
Meat Ingredients Market
Meat Products
North America Processed Pork Meat Market
Meat Products
Sausage Premixes Market
Meat Products
North America Canned Meat Market
Meat Products
Beef Fat Powder Market
Meat Products
Low-Fat Chorizo Market
Meat Products
United States Poultry Meat Market
Meat Products
Organic Eggs Market
Meat Products
Organic Meat Market