
 United States Bacon Market | 2026-2036
United States Bacon Market Size, Share, and Industry Trends Forecast 2026-2036
United States Bacon Market Analytics
Turkey bacon formulations are repositioning product economics across the category by reducing input cost volatility tied to pork belly cycles. Tyson Foods Inc. leverages vertical integration from feed operations through processing to stabilize margin exposure. Hormel Foods Corporation dominates branded retail shelf space with refrigerated and shelf-stable bacon portfolios. Smithfield Foods, Inc. anchors foodservice supply through dedicated portion-control programs for restaurant chains.
Bacon comprises cured and smoked pork belly strips, typically processed with sodium nitrite for preservation and color fixation, then sliced to specified thicknesses for retail or foodservice use. Uncured bacon leads retail growth as USDA FSIS labeling scrutiny pushes processors toward celery powder and natural curing agents. Sliced form occupies the largest volume share, while crumbled bacon captures premium positioning in food processing and quick-service applications. Restaurants represent the fastest-growing end user segment as breakfast-all-day menus and bacon-topped burgers expand.
USDA FSIS enforces pathogen reduction and labeling standards that dictate curing agent declarations and safe handling instructions. FDA oversees nutrition fact panels and sodium content claims that influence reformulation priorities. State-level California Proposition 12 compliance requirements are forcing supply chain restructuring for producers selling into that market. Stakeholders must monitor how animal welfare regulations and sodium reduction mandates simultaneously reshape input costs and product positioning.
Market Dynamics
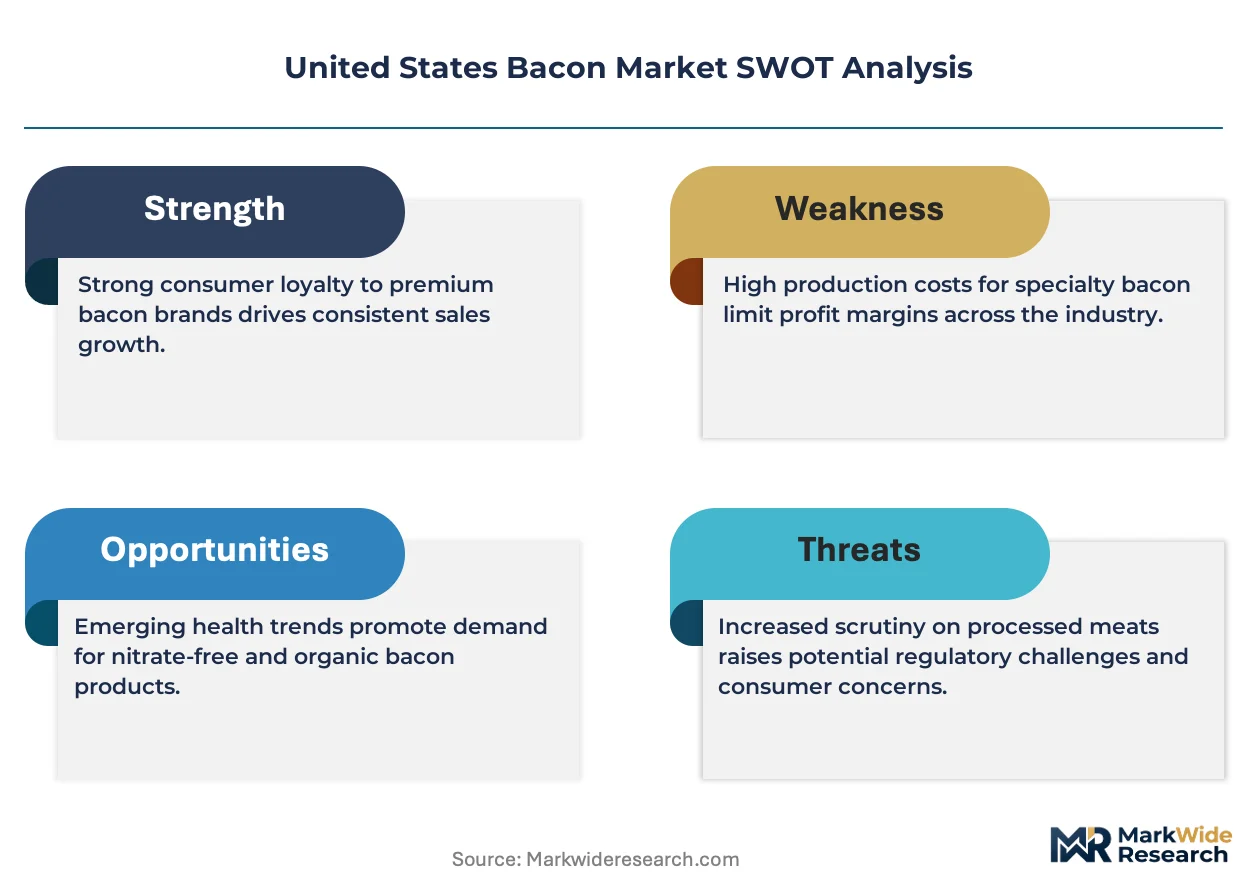
USDA FSIS labeling enforcement is compressing formulation flexibility across the United States bacon market, forcing processors to revalidate curing protocols and rewrite packaging claims as "uncured" definitions tighten.
Growth Catalysts
- Breakfast-all-day menu expansion:Quick-service chains are extending bacon placement beyond morning dayparts into burgers, sides, and limited-time offers, amplifying foodservice volume pull.
- California Proposition 12 compliance infrastructure:Investment in animal welfare tracking systems is unlocking access to the country's largest state market for prepared pork products.
- Celery powder curing validation:Natural curing agent suppliers are securing USDA process approvals that enable "no nitrite added" claims without synthetic additives.
Market Restraints
- Pork belly price volatility:Feed grain costs and herd cycle dynamics create margin compression that turkey bacon processors partially hedge but cannot eliminate.
- Southeast processing concentration:North Carolina and Iowa slaughter capacity dominates national supply, creating geographic vulnerability to weather and logistics disruptions.
- Sodium reduction mandates:FDA guidance on voluntary sodium targets is forcing reformulation investments that alter taste profiles and consumer acceptance curves.
Strategic Opportunities
- Crumbled bacon industrial applications:Food manufacturers supplying pizza chains and frozen entree producers represent an underpenetrated volume channel beyond sliced retail.
- Shelf-stable format expansion:Retort and aseptic processing advances are enabling ambient distribution into convenience stores and emergency preparedness retail.
- State-level animal welfare differentiation:Proposition 12-compliant supply chains command premium positioning in California and states adopting similar standards.
Industry Challenges
- FSIS label approval timelines:"Uncured" claim substantiation requires extended laboratory validation that delays product launches by 6-12 months.
- Legacy equipment retrofit costs:Sodium reduction and natural curing transitions demand smoker and brine system upgrades that strain mid-tier processor balance sheets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Bacon Market |
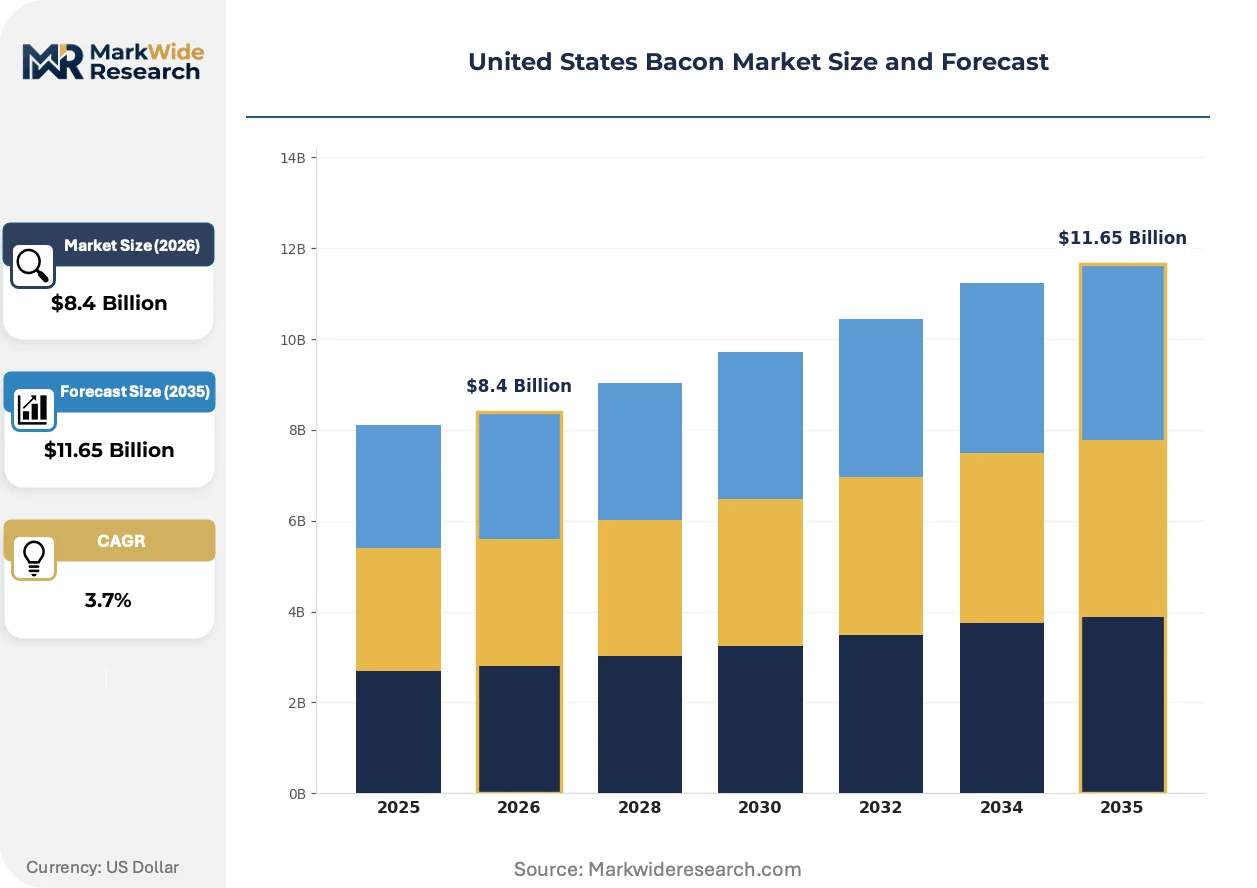
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $11.65 Billion |
| CAGR (2026 – 2036) | 3.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fresh Bacon, Smoked Bacon, Uncured Bacon, Turkey Bacon Distribution Channel: Supermarkets, Online Retail, Specialty Stores, Convenience Stores Form: Raw, Cooked, Sliced, Crumbled End User: Households, Restaurants, Food Processing, Catering Services |
| Companies Covered | Hormel Foods Corporation, Tyson Foods Inc., The Kraft Heinz Company, Smithfield Foods, Inc., Fresh Mark, Sugar Creek Packing, Oscar Mayer, Applegate Farms, LLC, Clemens Food Group, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Bacon Market Evolving Landscape
Processing technology and regulatory disclosure requirements are converging to reshape how bacon is formulated, labeled, and positioned across retail and foodservice channels in the United States.
High-pressure processing is integrating into cooked bacon operations to extend refrigerated shelf life without synthetic preservatives. Foodservice distributors adopting HPP-treated products are reducing shrink and expanding delivery radius to secondary markets. This technology is integrating food safety assurance with clean-label positioning that satisfies both operator risk management and consumer ingredient scrutiny.
USDA FSIS updated guidance on "natural" and "uncured" claims is eliminating vague marketing language from packaging. Processors must now disclose specific curing agents like cultured celery powder and their nitrate content equivalents. Smaller regional brands face disproportionate compliance burdens as label redesign and analytical testing costs scale inefficiently below volume thresholds.
Direct procurement relationships between restaurant chains and dedicated bacon programs are displacing traditional broadline distributor selection. Chains specify slice thickness, cook yield, and specular attributes in annual contracts that lock volume commitments. This pattern concentrates most visibly in the Southeast, where processing plants align with QSR headquarters clusters in Atlanta and Charlotte.
United States Bacon Market Segmentation
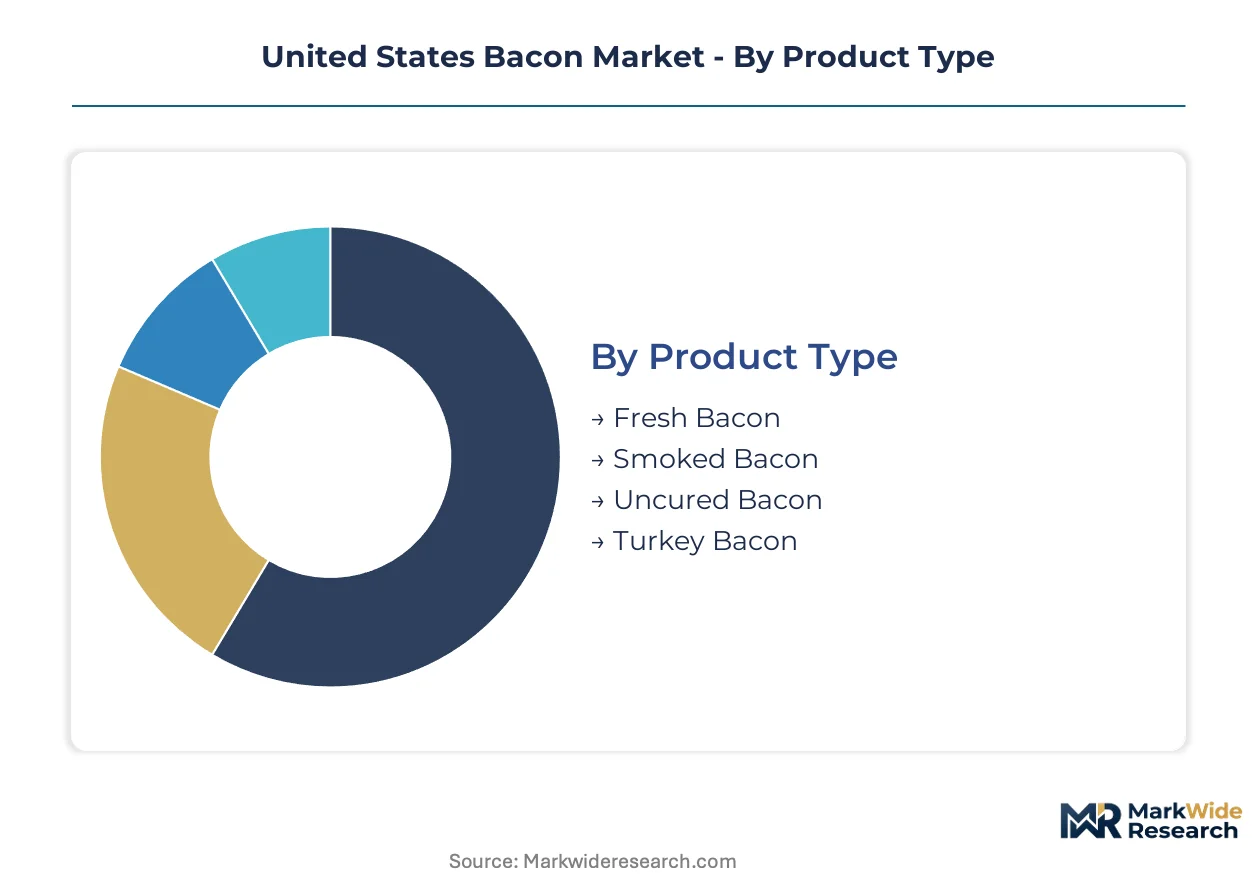
Bacon segmentation reveals how curing protocols, distribution economics, and end-use specifications create distinct competitive arenas. Each dimension carries unique margin profiles and regulatory exposure that reshape processor investment priorities.
Product Type:
Processing method and curing chemistry differentiate buyers by price sensitivity and label claim requirements.
- Fresh Bacon:Unsmoked pork belly sold refrigerated with minimal processing. Demand clusters in the Southeast among traditional retailers where consumers prioritize lower unit cost over extended shelf stability.
- Smoked Bacon:Hardwood-smoked strips with sodium nitrite curing represent the volume baseline. Foodservice distributors in North Carolina and Iowa specify smoke intensity and slice thickness in annual procurement contracts.
- Uncured Bacon:Celery powder and natural nitrate sources replace synthetic curing agents. USDA FSIS labeling scrutiny is forcing reformulation investments that elevate price points in California and Proposition 12-compliant markets.
- Turkey Bacon:Poultry-based alternative hedges pork belly cost volatility. Retail chains in the Midwest stock this format for health-positioned shoppers seeking reduced saturated fat.
Volume sits with Smoked Bacon; growth tilts toward Uncured Bacon.
Distribution Channel:
Channel selection determines pack size, temperature requirements, and trade promotion intensity.
- Supermarkets:Refrigerated case placement dominates household penetration. Kroger and Albertsons specify peg-thickness and private-label specifications that lock processor capacity months in advance.
- Online Retail:Frozen and shelf-stable formats expand delivery radius beyond cold-chain constraints. Amazon Fresh and Instacart partnerships are capturing suburban households outside traditional supermarket trade areas.
- Specialty Stores:Artisanal and heritage-breed positioning commands premium pricing. Whole Foods Market and regional co-ops require animal welfare documentation that filters supplier pools.
- Convenience Stores:Shelf-stable and microwave-ready portions target impulse purchase occasions. 7-Eleven and Circle K are expanding breakfast sandwich programs that specify pre-cooked bacon components.
Supermarkets anchor current volume; Online Retail is climbing the fastest.
Form:
Processing stage at point of sale dictates equipment requirements and margin capture.
- Raw:Unheated belly strips for home cooking and foodservice prep. Independent restaurants in Texas and Florida prefer this format for cook-yield control and cost management.
- Cooked:Fully prepared strips reduce labor and food safety liability. Quick-service chains specify moisture content and hold-time performance in their technical requirements.
- Sliced:Thickness-calibrated portions dominate retail packaging. Shingle-pack configurations occupy the largest refrigerated footprint in supermarket meat cases.
- Crumbled:Pre-cooked bits for salad bars, pizza toppings, and ingredient manufacturing. Frozen food processors in the Upper Midwest source this format for frozen entree assembly.
Sliced commands shelf presence; Crumbled is gaining share fastest in industrial channels.
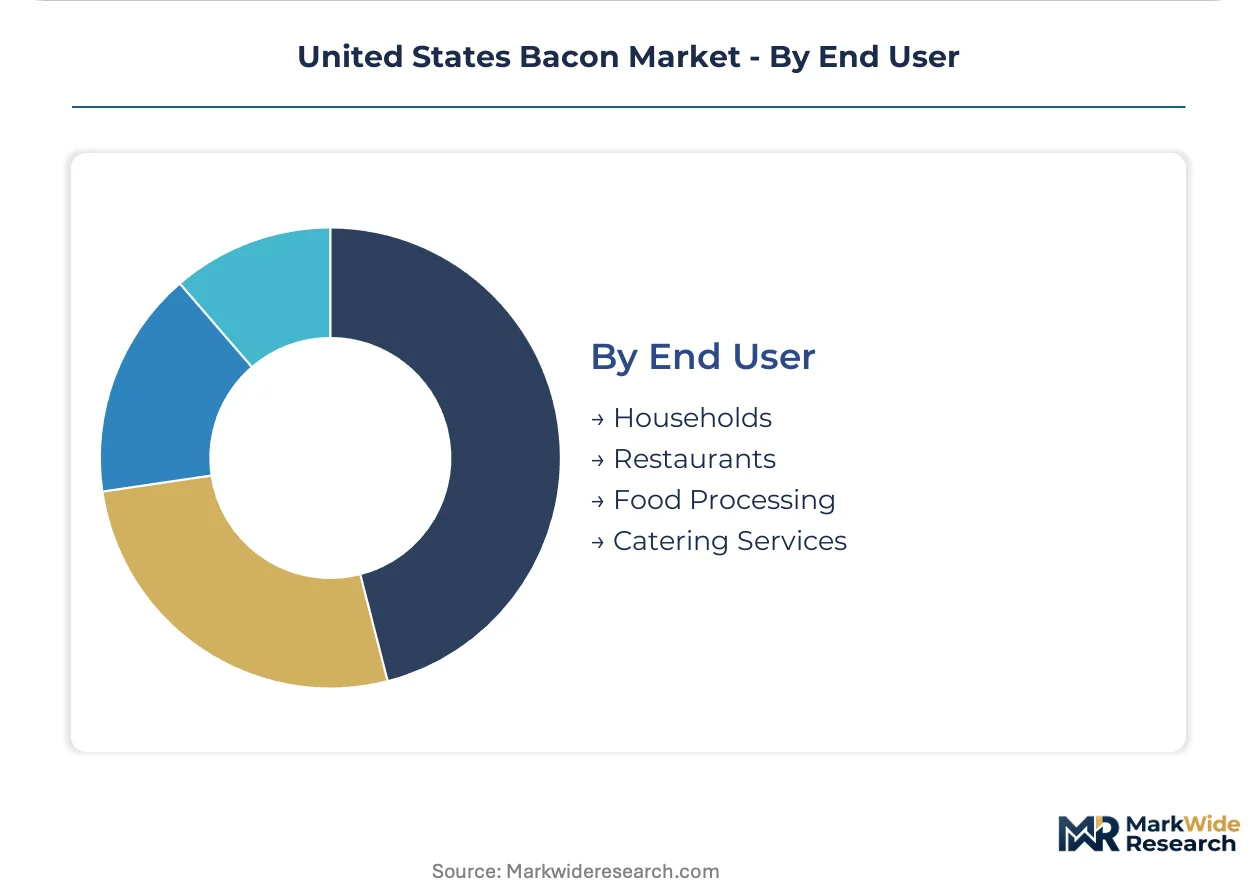
End User:
Volume scale and specification complexity separate household purchasers from institutional buyers.
- Households:Retail package consumers driving breakfast and occasional dinner usage. Bacon's placement in weekend brunch occasions sustains premium price acceptance despite inflation pressure.
- Restaurants:Quick-service and casual dining operators specifying cook-yield and hold-time performance. Breakfast-all-day menu expansion at McDonald's and Wendy's is amplifying portion-control demand.
- Food Processing:Ingredient buyers incorporating bacon into frozen entrees, soups, and snacks. Pizza manufacturers and ready-meal assemblers require consistent particle size and moisture specifications.
- Catering Services:Event and institutional foodservice requiring bulk preparation efficiency. Hotel breakfast programs and university dining contracts prioritize labor-minimizing pre-cooked formats.
Households anchor consumer revenue; Restaurants show the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand concentrates in the Southeast, where processing capacity and pork production clusters overlap with quick-service restaurant headquarters in Atlanta and Charlotte.
Southeast
North Carolina and Georgia anchor foodservice procurement through dedicated portion-control programs for restaurant chains. USDA FSIS labeling requirements for "uncured" claims are tightening ingredient disclosure standards for processors operating in this corridor. Charlotte and Raleigh-Durham processing plants align with QSR headquarters clusters, amplifying direct procurement relationships.
Midwest
Iowa slaughter capacity dominates national pork supply, creating geographic concentration in hog processing and feed grain logistics. State-level agricultural extension programs support herd cycle management that stabilizes input costs for regional processors. Des Moines and Sioux City processing clusters supply frozen and crumbled bacon formats to Upper Midwest food manufacturers.
California
Proposition 12 compliance requirements are forcing supply chain restructuring for producers selling into the country's largest state market. California Department of Food and Agriculture enforcement of animal welfare standards filters supplier pools for retail and foodservice channels. Los Angeles and San Francisco metropolitan areas command premium positioning for Proposition 12-compliant bacon products.
Southwest
Texas and Florida independent restaurants prefer raw bacon formats for cook-yield control and cost management in high-volume breakfast operations. State health department food safety regulations align with FDA oversight of nutrition fact panels and sodium content claims. Dallas-Fort Worth and Miami processing distribution hubs serve expanding breakfast-all-day menu placements in regional restaurant chains.
Pacific Northwest
Seattle and Portland metropolitan areas sustain demand for artisanal and heritage-breed positioning through specialty retail channels. State-level environmental regulations on processing wastewater influence plant location decisions for expansion-minded operators. Regional co-ops require animal welfare documentation that filters supplier pools toward smaller-scale, differentiated bacon producers.
United States Bacon Market Competitive Landscape
Vertical integration dominates the current landscape as processors seek margin stabilization through captive supply chains. The market exhibits tiered concentration with national branded portfolios, private-label suppliers, and regional processors occupying distinct competitive arenas. Three strategic archetypes define positioning: integrated protein conglomerates controlling feed-to-retail operations, branded refrigerated specialists commanding shelf space, and foodservice-dedicated processors anchoring restaurant supply contracts. M&A activity and capacity expansion in Proposition 12-compliant infrastructure represent the dominant competitive moves reshaping participant rankings.
Within the integrated protein tier, Tyson Foods Inc. and Smithfield Foods, Inc. exemplify scale-driven operators with upstream control over feed operations and processing capacity. Hormel Foods Corporation occupies a position in the branded refrigerated segment, anchoring retail shelf presence through portfolio breadth across curing protocols and format types.
| Leading Market Players |
|---|
| Hormel Foods Corporation |
| Tyson Foods Inc. |
| The Kraft Heinz Company |
| Smithfield Foods, Inc. |
| Fresh Mark |
| Sugar Creek Packing |
| Oscar Mayer |
| Applegate Farms, LLC |
| Clemens Food Group |
| Others |
Value Network & Pricing Analysis
Pork belly input costs cascade through three pricing strata, with feed grain volatility at Iowa and North Carolina hog operations compressing margins for standard-tier processors while Proposition 12-compliant supply chains sustain premium positioning in California retail channels.
Pricing Analysis
Volume sits with commodity smoked bacon sold through supermarket refrigerated cases, while margin concentrates in uncured and turkey bacon formats where USDA FSIS labeling compliance creates certification-grade price separation. Price differentiation stems from curing protocol complexity and animal welfare documentation depth, with synthetic nitrite-cured products facing downward pressure as natural curing agent suppliers secure process approvals. Quick-service restaurant chains exhibit lowest price sensitivity through annual volume commitments, while independent restaurants in Texas and Florida prioritize raw format unit economics.
Supply Chain Analysis
Hog supply rests on Iowa and North Carolina slaughter capacity, with feed grain inputs drawing from Midwest corn belt operations and breeding stock genetics tethered to domestic multiplier herds. Celery powder curing agents and natural smoke flavorings introduce single-source vulnerability as specialty ingredient suppliers consolidate. Tariff exposure on imported pork bellies from Canada and Mexico creates intermittent cost spikes. Distribution runs through temperature-controlled networks anchored at Southeast processing clusters, with foodservice distributors maintaining dedicated portion-control inventory for restaurant chain contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
USDA FSIS labeling enforcement has erected a cost-of-compliance barrier that filters regional processors from national retail distribution, with "uncured" claim substantiation timelines creating a 6-12 month moat protecting validated incumbents.
For Market Incumbents: To counter margin compression from pork belly price volatility, processors should deepen backward integration into feed operations and captive hog supply while retrofitting smokers and brine systems for sodium reduction compliance. Capacity addition in Proposition 12-compliant infrastructure secures California market access against supply chain restructuring demands. For New Entrants and Emerging Players: Artisanal buyers in Pacific Northwest specialty retail represent an underserved channel where heritage-breed positioning and animal welfare documentation command premium shelf placement. Direct procurement relationships with independent restaurant chains in Texas and Florida bypass broadline distributor concentration, with raw format supply offering lowest barrier to entry. For Investors and Strategic Acquirers: M&A activity targeting Proposition 12-compliant processing infrastructure is the leading indicator that animal welfare regulation will permanently reshape competitive rankings. Over the medium-term horizon, vertically integrated mid-cap specialists with validated natural curing protocols present acquisition profiles aligned with branded portfolio expansion strategies.| Strategic Initiative | Industry Significance |
|---|---|
| Proposition 12 Compliance Infrastructure | Unlocks California market access for prepared pork products against regulatory barriers. |
| Natural Curing Agent Validation | Secures USDA FSIS process approvals enabling "no nitrite added" retail claims. |
| High-Pressure Processing Integration | Extends refrigerated shelf life for foodservice distributors expanding delivery radius. |
| Crumbled Bacon Industrial Capacity | Captures underpenetrated volume from pizza chains and frozen entree manufacturers. |
| Shelf-Stable Format Development | Enables ambient distribution into convenience stores and emergency preparedness retail. |
Research Methodology
Document review covered USDA FSIS labeling guidance, FDA sodium reduction guidance, California Proposition 12 regulatory filings, and industry trade association reports, complemented by interviews with bacon processing plant managers, quick-service restaurant procurement directors, supermarket category buyers, and specialty retail meat coordinators. Secondary validation drew from customs records, SEC 10-K protein segment disclosures, and state agricultural extension hog cycle data. Bottom-up capacity utilization estimates triangulated against top-down retail scanner data across the analysis window.
Segmentation outputs modeled product type by curing protocol, distribution channel by temperature requirement, form by processing stage, and end user by specification complexity. CAGRs derived from regression against historical pork belly price cycles, breakfast-all-day menu expansion rates, and regulatory compliance cost trajectories. Forecast inputs incorporated feed grain futures curves and Proposition 12 adoption probability across additional states.
Revisions become necessary when animal welfare regulation expands beyond California, when FDA mandates mandatory rather than voluntary sodium targets, or when high-pathogenicity avian influenza disrupts turkey bacon supply. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Meat Products
Meat Tenderizer Market
Meat Products
Global Beef Market
Meat Products
India Edible Meat Market
Meat Products
GCC Edible Meat Market
Meat Products
Asia-Pacific Processed Meat Market
Meat Products
United States Animal Protein Market
Meat Products
Chicken Buckets Market
Meat Products
Meat Paste Market
Meat Products
United Arab Emirates Red Meat Market
Meat Products
Brisket Market
Meat Products
Meat Products Market
Meat Products
Kosher Beef Market
Meat Products
Qatar Poultry Meat Market
Meat Products
Ham Slicers Market
Meat Products
Reconstituted Meat Market
Meat Products
Canned Chicken Market