
 Global Automotive Hydraulics System Market | 2026-2036
Global Automotive Hydraulics System Market Size, Share, and Industry Trends Forecast 2026-2036
Global Automotive Hydraulics System Market Intelligence
China's industrial corridor is reconfiguring supply geography for automotive hydraulics as domestic foundries and precision machining clusters scale capacity for brake and steering components. Robert Bosch leverages its Stuttgart engineering base to sustain technology leadership in electro-hydraulic power steering modules for European OEM platforms. ZF Friedrichshafen anchors its competitive position through integrated brake system manufacturing that spans hydraulic actuation and electronic control units.
Automotive hydraulics systems transmit force through pressurized fluid circuits, typically operating at 150–350 bar in commercial brake applications and 70–140 bar in power steering assemblies, to enable precise mechanical control with minimal driver effort. Brake Systems occupy the largest margin pool given safety-critical certification requirements and OEM captive sourcing strategies, while Electro-Hydraulic technology leads growth as passenger vehicle electrification demands regenerative-compatible actuation architectures. Construction Equipment applications sustain above-average volume intensity per unit due to loader and excavator multi-circuit hydraulic demands.
NHTSA's FMVSS brake performance standards and the EU's CE marking directives under the EU Green Deal's emissions reduction framework shape product compliance thresholds for hydraulic system suppliers seeking transatlantic market access. China's MIIT enforces GB standards for commercial vehicle braking that force localization of hydraulic component testing and certification. Stakeholders must monitor how dual carbon goals in Beijing and Brussels recalibrate material specifications and fluid compatibility requirements for next-generation hydraulic architectures.
Market Dynamics
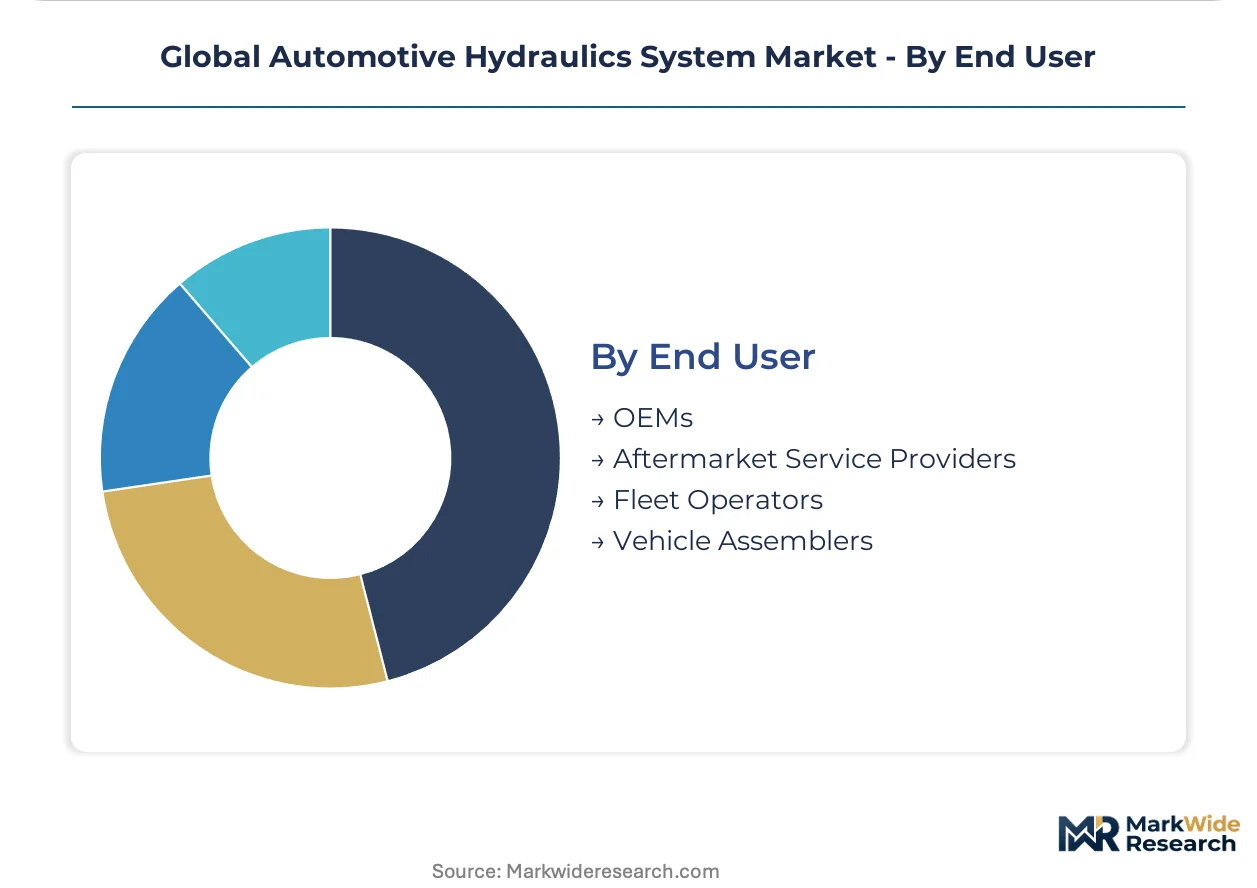
Electro-hydraulic architectures are compressing the addressable market for purely mechanical brake and steering systems as passenger vehicle electrification mandates force regenerative-compatible actuation designs.
Growth Catalysts
- FMVSS brake mandates:NHTSA's tightening commercial vehicle safety standards are forcing fleet-wide hydraulic brake retrofits across North American truck operators.
- Construction equipment multi-circuit demand:Loader and excavator OEMs in China are scaling localized hydraulic cylinder sourcing to serve domestic infrastructure buildouts.
- EU Green Deal emissions framework:The European Commission's fluid compatibility and material specification requirements are accelerating R&D investment in next-generation hydraulic architectures.
Market Restraints
- Specialized alloy input volatility:Precision-machined hydraulic components depend on nickel and chromium supply chains concentrated in Russian and South African mining corridors.
- Foundry capacity bottlenecks:Domestic Chinese casting clusters face quality certification gaps for brake system exports to regulated Western markets.
- Full-electric actuation substitution:Brake-by-wire and steer-by-wire platforms in premium German and Japanese passenger vehicles are displacing hydraulic circuits entirely.
Strategic Opportunities
- Indian commercial vehicle localization:BIS certification requirements and PLI scheme incentives are opening captive sourcing partnerships for hydraulic pump assemblies.
- Regenerative braking integration:Electro-hydraulic modules that blend friction and energy recovery functions are capturing design wins in Chinese EV platforms.
- Aftermarket service digitization:Predictive maintenance platforms using pressure sensor telemetry are creating recurring revenue streams for brake system distributors.
Industry Challenges
- Precision machining talent scarcity:350-bar commercial brake component manufacturing requires CNC programming expertise concentrated in Stuttgart and Nagoya engineering clusters.
- Dual certification timelines:Suppliers seeking simultaneous NHTSA FMVSS and EU CE marking face 18-24 month validation cycles for new hydraulic architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Automotive Hydraulics System Market |
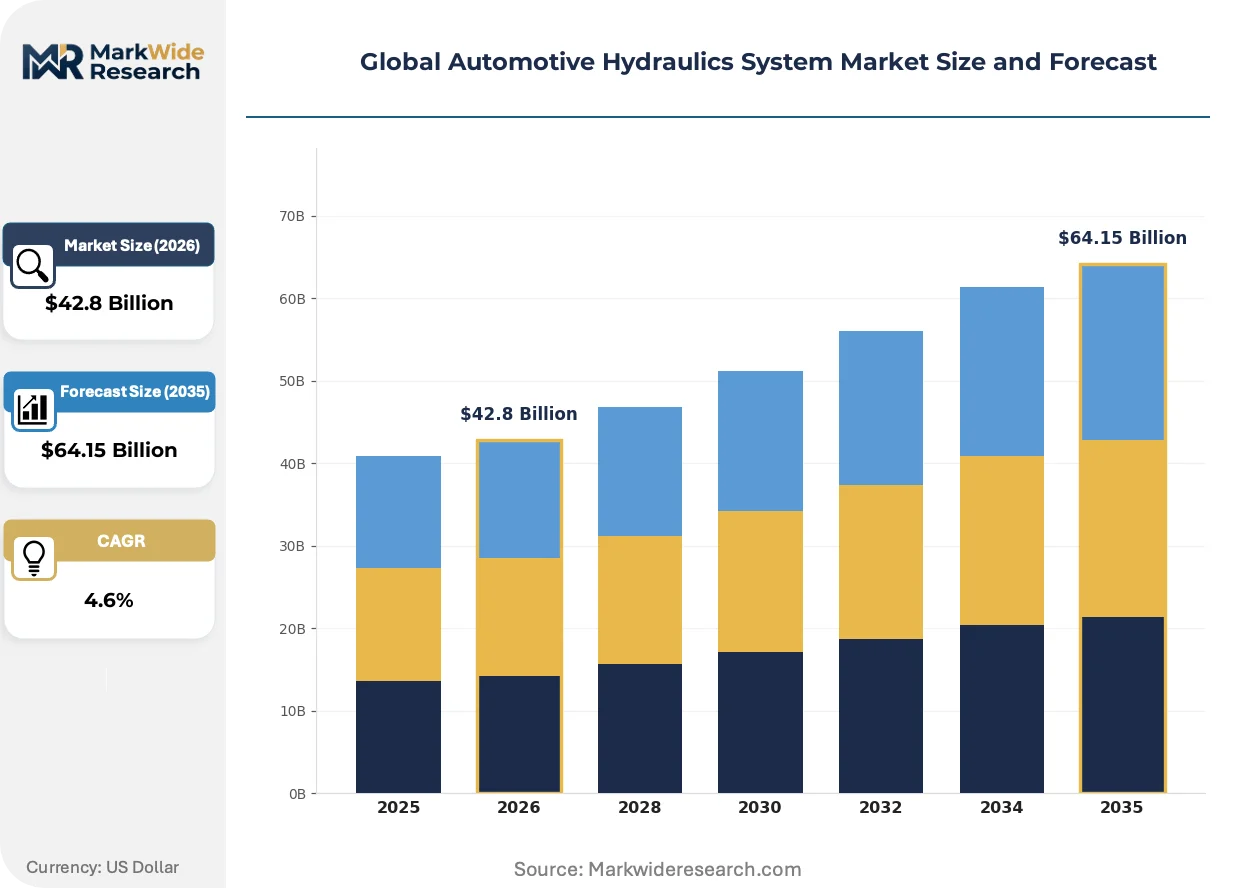
| Market Size in 2026 | $42.8 Billion |
| Market Size in 2035 | $64.15 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hydraulic Pumps, Hydraulic Cylinders, Power Steering Systems, Brake Systems, Suspension Systems Technology: Electro-Hydraulic, Load-Sensing, Proportional, Closed-Center, Open-Center Application: Passenger Vehicles, Commercial Trucks, Construction Equipment, Agricultural Machinery, Two-Wheelers End User: OEMs, Aftermarket Service Providers, Fleet Operators, Vehicle Assemblers |
| Companies Covered | Robert Bosch, ZF Friedrichshafen, Continental, Aisin, Hitachi Astemo, BorgWarner, Knorr-Bremse, Mando, Valeo, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Automotive Hydraulics System Market Strategic Shifts & Innovations
Fluid power architectures are fragmenting into specialized electro-mechanical hybrids as electrification mandates force coexistence between legacy hydraulic reliability and electronic control precision.
Electro-hydraulic power steering modules are hybridizing mechanical torque assistance with electric motor augmentation to enable lane-keeping and automated parking functions. German and Japanese passenger vehicle platforms are adopting these systems at production scale. The technology is hybridizing supplier value chains by forcing hydraulic specialists to source electronic control units and sensor arrays from tier-2 semiconductor vendors.
REACH substance restrictions and the EU F-Gas Regulation are banning specific hydraulic fluid formulations and compressing the approved materials list for European-market components. Industrial consequence includes accelerated bio-based synthetic fluid development by compounders serving automotive OEMs. Brake system suppliers with transatlantic exposure are dual-stocking fluid inventories to maintain CE marking compliance while serving less regulated export markets.
Fleet procurement departments are consolidating brake and steering system contracts under single-source electro-hydraulic integrators to reduce supplier management overhead. Independent hydraulic component distributors in North America are losing share to OEM-captive service networks offering bundled maintenance and telemetry monitoring. This concentration is most visible in California and Texas commercial trucking corridors where large fleet operators command volume-based pricing leverage.
Global Automotive Hydraulics System Market Segmentation
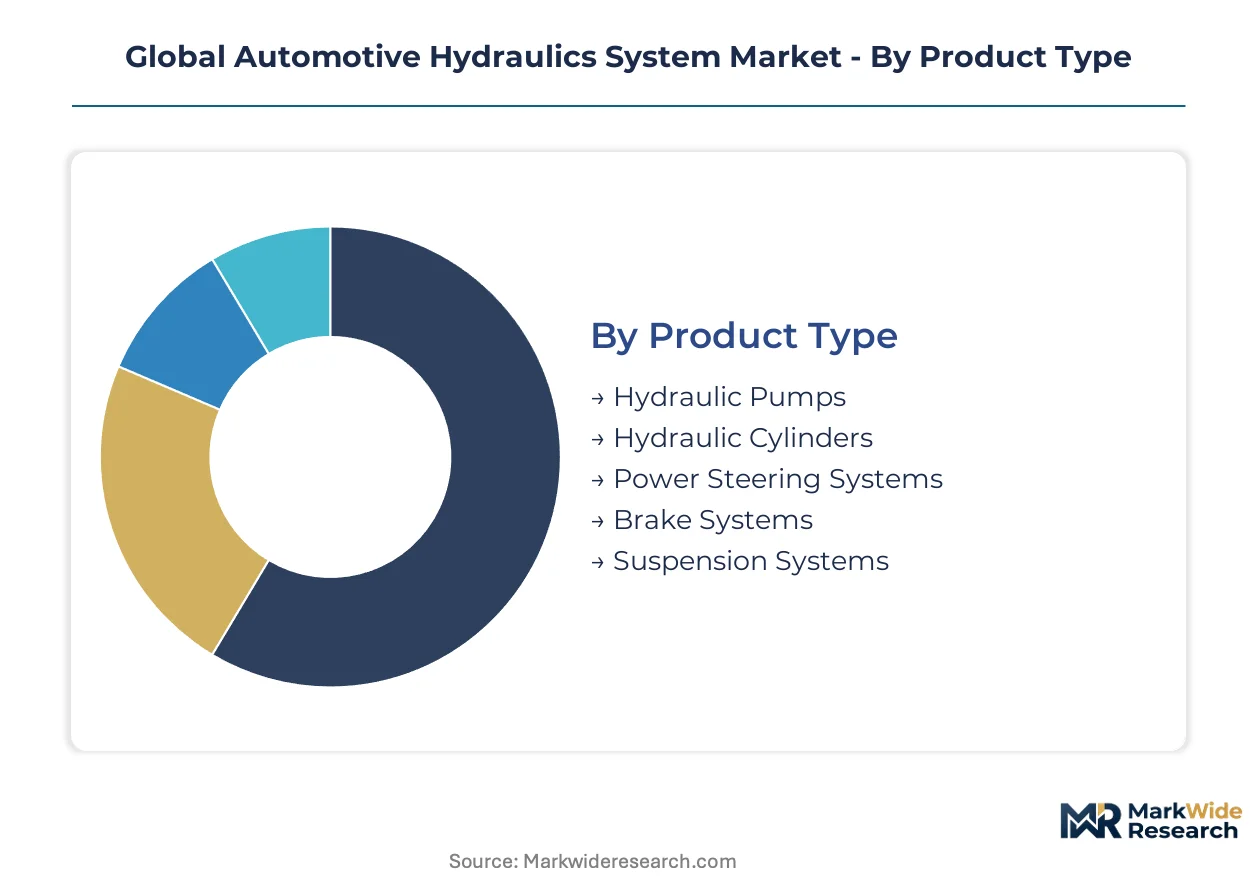
Automotive hydraulics segmentation reveals divergent replacement cycles across product categories, with brake and steering systems turning over every 7-10 years while construction equipment cylinders endure 15-20 year lifespans. Technology choices determine margin structure, as electro-hydraulic modules command premium pricing against mechanical alternatives.
Product Type:
Replacement cycles vary dramatically—brake systems and power steering assemblies turn over fastest due to safety-critical wear, while hydraulic cylinders in heavy equipment demonstrate extended service intervals.
- Hydraulic Pumps:These pressure-generating units convert mechanical rotation into fluid power at 150-350 bar for commercial brake circuits. Demand concentrates in Chinese foundry clusters serving domestic construction equipment OEMs, driven by infrastructure buildouts requiring localized pump sourcing.
- Hydraulic Cylinders:Linear actuators translate fluid pressure into mechanical force for loader and excavator lifting arms. German and Japanese precision machining clusters dominate high-pressure cylinder manufacturing for regulated Western markets, constrained by FMVSS certification requirements.
- Power Steering Systems:Hydraulic assist units reduce driver steering effort through pressurized fluid circuits operating at 70-140 bar.
- Brake Systems:Safety-critical actuation assemblies with the longest certification timelines and highest OEM captive sourcing rates.
- Suspension Systems:Damping and leveling hydraulics with niche adoption in premium passenger and commercial platforms.
Brake Systems dominate installed base. Hydraulic Cylinders are where expansion concentrates.
Technology:
Cost tiers separate legacy mechanical architectures from premium electro-hybrid systems, with proportional and load-sensing technologies occupying mid-market positioning between open-center economy and closed-center precision tiers.
- Electro-Hydraulic:Hybrid architectures blend hydraulic force transmission with electronic control precision for regenerative braking compatibility. German and Japanese passenger vehicle platforms are adopting these systems at production scale, driven by electrification mandates requiring energy recovery integration.
- Load-Sensing:Demand-responsive pressure regulation reduces pump energy consumption by matching output to actual circuit requirements. Construction equipment OEMs in China specify these systems for multi-implement excavators, constrained by foundry capacity bottlenecks for precision valve bodies.
- Proportional:Variable flow control enables precise actuator positioning for automated machinery functions.
- Closed-Center:Constant-pressure architectures for high-cycle industrial applications with continuous duty requirements.
- Open-Center:Basic flow-through designs for cost-sensitive agricultural and two-wheeler applications.
Electro-Hydraulic commands the steepest expansion trajectory. Open-Center retains volume leadership in emerging markets.
Application:
Volume intensity per unit varies by application, with construction equipment demanding 3-5 hydraulic circuits per machine versus single-circuit passenger vehicle systems.
- Passenger Vehicles:Brake and steering hydraulics are consolidating toward electro-hybrid architectures as electrification mandates force regenerative-compatible designs. German and Japanese platforms are displacing purely mechanical systems fastest.
- Commercial Trucks:Fleet operators across North America are retrofitting hydraulic brake systems under tightening FMVSS safety mandates. California and Texas corridors show concentrated procurement activity.
- Construction Equipment:Multi-circuit hydraulic demands from loaders and excavators sustain above-average component intensity per unit.
- Agricultural Machinery:Tractor and harvester hydraulics with seasonal utilization patterns and extended replacement cycles.
- Two-Wheelers:Basic brake hydraulics with high unit volumes and minimal electronic integration.
Commercial Trucks anchor current replacement demand. Passenger Vehicles are where technology migration accelerates.
End User:
Customer type determines procurement patterns, with OEMs pursuing captive integration strategies while fleet operators consolidate contracts under single-source electro-hydraulic integrators.
- OEMs:Original equipment manufacturers pursue vertical integration into hydraulic component manufacturing to secure supply certainty for brake and steering platforms. European and Japanese OEMs maintain Stuttgart and Nagoya engineering clusters for 350-bar precision machining.
- Aftermarket Service Providers:Independent distributors face share erosion as OEM-captive networks bundle maintenance with telemetry monitoring. North American commercial trucking corridors show this concentration most visibly.
- Fleet Operators:Large commercial vehicle fleets command volume-based pricing leverage for consolidated brake and steering contracts.
- Vehicle Assemblers:Contract manufacturers sourcing hydraulic subsystems from tier-1 integrators for regional assembly operations.
OEMs dominate value capture. Fleet Operators are where procurement consolidation is advancing fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Foundry capacity for precision-machined hydraulic components clusters in three distinct manufacturing corridors. Each geography shapes demand through divergent regulatory enforcement and infrastructure investment cycles.
United States
Commercial trucking fleets across California and Texas are retrofitting hydraulic brake systems under NHTSA's FMVSS safety mandates. The EPA's emissions enforcement framework indirectly pressures hydraulic fluid formulation standards. Detroit-area engineering clusters sustain 350-bar precision machining expertise for brake component manufacturing.
Germany
Passenger vehicle OEMs in Stuttgart and Munich are displacing mechanical brake architectures with electro-hydraulic regenerative-compatible designs. The KBA enforces EU F-Gas Regulation compliance for hydraulic fluid formulations. Baden-Württemberg's precision engineering corridor anchors electro-hydraulic power steering module development for European platforms.
China
Domestic construction equipment manufacturers in the Yangtze River Delta are scaling localized hydraulic cylinder sourcing for infrastructure buildouts. MIIT enforces GB standards for commercial vehicle braking that force localization of component testing. Shanghai and Jiangsu foundry clusters face quality certification gaps for brake system exports to regulated Western markets.
Japan
Passenger vehicle platforms in the Nagoya and Tokyo corridors are adopting electro-hydraulic architectures at production scale. METI's electrification mandates require regenerative-compatible actuation designs. Aichi Prefecture's engineering clusters concentrate CNC programming expertise for high-pressure hydraulic component manufacturing.
India
Commercial vehicle OEMs in Maharashtra and Tamil Nadu are localizing hydraulic pump assembly sourcing under BIS certification requirements. The PLI scheme incentivizes captive sourcing partnerships for automotive hydraulics. Pune and Chennai manufacturing corridors are scaling foundry capacity to serve domestic truck and bus production.
Global Automotive Hydraulics System Market Key Industry Players
Platform integrators command the system tier; component specialists sit upstream in a tiered supply structure. The vendor base separates into consolidated brake system suppliers with OEM-captive relationships and fragmented hydraulic component fabricators serving aftermarket channels. Three archetypes dominate: electro-hydraulic module integrators, precision-machined component specialists, and construction equipment hydraulic system providers. Competitive dynamics center on backward integration into foundry operations and strategic partnerships with semiconductor vendors for electronic control sourcing.
Among German-based system integrators, Robert Bosch and ZF Friedrichshafen occupy positions exemplifying the electro-hydraulic platform tier. Continental represents the diversified component-to-system spectrum. These three entities anchor the competitive structure through their Stuttgart and Hanover engineering bases, where precision machining expertise for 350-bar commercial brake applications concentrates.
| Leading Market Players |
|---|
| Robert Bosch |
| ZF Friedrichshafen |
| Continental |
| Aisin |
| Hitachi Astemo |
| BorgWarner |
| Knorr-Bremse |
| Mando |
| Valeo |
| Others |
Cost & Logistics Intelligence
Chinese foundry clusters for precision-machined hydraulic cylinders concentrate upstream capacity, anchoring margin capture for brake system integrators in Germany and Japan who command premium pricing through FMVSS and CE certification tiers. This geographic asymmetry between raw component supply and value-added system assembly creates tiered pricing power that favors vertically integrated OEM-captive suppliers over independent aftermarket distributors.
Pricing Analysis
FMVSS brake performance standards dictate the pricing tier structure across the North American commercial vehicle aftermarket, separating OEM-captive brake system suppliers from independent component distributors. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade and volume scale, with fleet operators commanding the steepest discounts through consolidated contract structures. Cost compression in the economy tier is intensifying because Chinese foundry exports face quality certification gaps for regulated Western markets. Aftermarket service providers demonstrate the highest price sensitivity, while OEM-captive integrators maintain pricing power through bundled telemetry and maintenance contracts.
Supply Chain Analysis
Shanghai and Jiangsu foundry clusters hold dominant contract-manufacturing capacity for hydraulic cylinder production serving domestic Chinese construction equipment OEMs. The supply chain draws from nickel and chromium feedstocks concentrated in Russian and South African mining corridors, with precision-machined valve bodies sourced from Stuttgart and Nagoya engineering clusters. Single-source vulnerability in semiconductor-dependent electro-hydraulic control modules creates exposure to tier-2 electronics sourcing constraints. Distribution runs through OEM-captive service networks in California and Texas commercial trucking corridors, displacing independent hydraulic component distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Electro-hydraulic architecture disruption is accelerating as passenger vehicle electrification mandates force regenerative-compatible actuation designs, compressing the addressable window for purely mechanical system suppliers. This technological inflection creates asymmetric opportunity for platform integrators with electronic control sourcing capabilities.
For Market Incumbents: Build certification moats through simultaneous NHTSA FMVSS and EU CE marking investment to extend 18-24 month validation timelines that block fast-follower competition. Deepen backward integration into foundry operations in Baden-Württemberg and Aichi Prefecture to secure 350-bar precision machining capacity against nickel supply volatility. Prioritize semiconductor vendor partnerships for electro-hydraulic control module sourcing as brake-by-wire substitution threatens hydraulic circuit demand in premium German and Japanese platforms. For New Entrants and Emerging Players: Indian commercial vehicle hydraulic pump assembly localization under BIS certification requirements and PLI scheme incentives represents the most penetrable entry point for tier-1 supplier partnerships. Aftermarket predictive maintenance platforms using pressure sensor telemetry offer white-space recurring revenue capture as fleet procurement departments consolidate contracts under single-source integrators. Target captive sourcing partnerships with Maharashtra and Tamil Nadu commercial vehicle OEMs rather than competing directly with entrenched European system integrators. For Investors and Strategic Acquirers: Capital is best deployed toward precision-machined component specialists with existing FMVSS certification and Stuttgart or Nagoya engineering presence, positioned for electro-hydraulic module integration. Long-term viability hinges on five-to-ten year electrification transition exposure, favoring suppliers with regenerative braking R&D pipelines over pure mechanical legacy portfolios. Monitor quarterly order flow from Chinese EV platforms for electro-hydraulic design wins as the inflection signal for technology migration velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Electro-Hydraulic Platform Integration | Combines hydraulic force transmission with electronic control precision for regenerative braking compatibility in German and Japanese EV platforms. |
| Foundry Capacity Expansion | Secures captive supply of 350-bar precision-machined brake components against nickel and chromium input volatility from Russian and South African corridors. |
| Dual Certification Investment | Simultaneous NHTSA FMVSS and EU CE marking creates 18-24 month competitive barriers for new hydraulic architecture validation. |
| Semiconductor Vendor Partnership | Sources electronic control units and sensor arrays from tier-2 vendors for electro-hydraulic power steering module production. |
| Aftermarket Telemetry Deployment | Predictive maintenance platforms using pressure sensor data create recurring revenue streams for brake system distributors in North American fleet corridors. |
Research Approach
The analysis maps hydraulic pumps, cylinders, brake systems, power steering assemblies, and electro-hydraulic modules, each validated through Tier 1 supplier procurement managers, OEM platform engineers, aftermarket distributors, and construction equipment OEM sourcing leads. Primary interview data triangulates against vehicle production databases, IHS Markit registration data, SEC filings from listed automotive suppliers, and customs trade records for hydraulic component flows. Bottom-up unit economics and top-down market sizing converge through cross-validation across stakeholder inputs.
Forecast assumptions hold regulatory enforcement timelines and electrification mandate schedules fixed while varying infrastructure investment cycles and raw material input costs across the projection horizon. Segmentation dimensions include product type, technology architecture, vehicle application, and end-user procurement pattern, with vehicle class and regional production cluster as automotive-specific overlays. CAGRs derive from regression analysis of historical adoption curves applied to electrification penetration scenarios, incorporating content-per-vehicle trajectories for electro-hydraulic modules and replacement cycle dynamics for commercial brake systems.
Macroeconomic conditions sit as an overlay; deviation in commercial vehicle fleet investment cycles, construction equipment infrastructure spending, or nickel and chromium commodity prices would shift the trajectory. Forecasts reflect documented assumptions regarding regulatory compliance timelines and technology substitution rates. Quarterly review of electro-hydraulic design win announcements, foundry capacity utilization in Yangtze River Delta clusters, and FMVSS certification submission volumes is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Parts
Philippines Automotive Lubricants Market
Automotive Parts
Global Automotive Gasket and Seal Market
Automotive Parts
Smoke Spill Motor Market
Automotive Parts
Global Automotive Brake Hose Market
Automotive Parts
South Africa Automotive Hydraulic Actuators Market
Automotive Parts
Passenger Car Wiper Blade Market
Automotive Parts
Thailand Passenger Vehicles Lubricants Market
Automotive Parts
Nigeria Automotive Engine Oils Market
Automotive Parts
Windshield Washer Fluid Market
Automotive Parts
Racing Vehicles Market
Automotive Parts
Automotive Canister Market
Automotive Parts
Global Plastics for Passenger Cars Market
Automotive Parts
North America Automotive AHSS Market
Automotive Parts
X-Arm Type Window Regulator Market
Automotive Parts
Europe Automotive Engine Oils Market
Automotive Parts
Industrial Shock Absorbers Market