
 Automotive Step Plate Market | 2026-2036
Automotive Step Plate Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Step Plate Market Analytics
Mexico's expanding automotive stamping capacity is reshaping North American step plate supply dynamics. Roadworks leverages its vertical integration into aluminum extrusion to control raw material costs across the aftermarket channel. RK Auto Accessories anchors its position through specialized custom plate fabrication for classic truck restoration segments. Iowa Customs dominates regional distribution through direct fleet relationships across the upper Midwest.
Automotive step plates are stamped or cast entry-assist components, typically fabricated from aluminum alloy 5052-H32 or 304 stainless steel with diamond-tread or serrated surface profiles, designed to provide slip-resistant footholds for vehicle cabin access. Their primary purpose spans commercial truck operator safety, passenger vehicle accessibility compliance, and fleet liability reduction. Stainless steel plates sustain premium pricing in severe-service applications where corrosion resistance determines replacement cycles, while aluminum variants capture volume in weight-sensitive OEM programs. Aftermarket Providers occupy the largest channel margin pool due to fragmented vehicle parc diversity and lower standardization barriers than Tier-1 Supplier contracts.
The US NHTSA Federal Motor Vehicle Safety Standards govern step projection and edge-radius limits to mitigate pedestrian impact trauma, while OSHA workplace-access regulations extend to commercial fleet step geometry in employer-operated vehicles. The EPA's evolving lightweighting mandates indirectly shape material substitution toward aluminum and composite alternatives as manufacturers pursue fuel-economy compliance. Stakeholders must monitor pending pedestrian-safety rulemakings in multiple jurisdictions to anticipate design-modification costs and retooling timelines for next-generation step plate architectures.
Market Dynamics
Fleet operators of heavy-duty commercial trucks are expanding step plate retrofits to meet upgraded cabin-access safety mandates issued by US NHTSA and corresponding EU pedestrian-safety frameworks, compressing design-modification timelines and retooling schedules for stamping and fabrication clusters.
Growth Catalysts
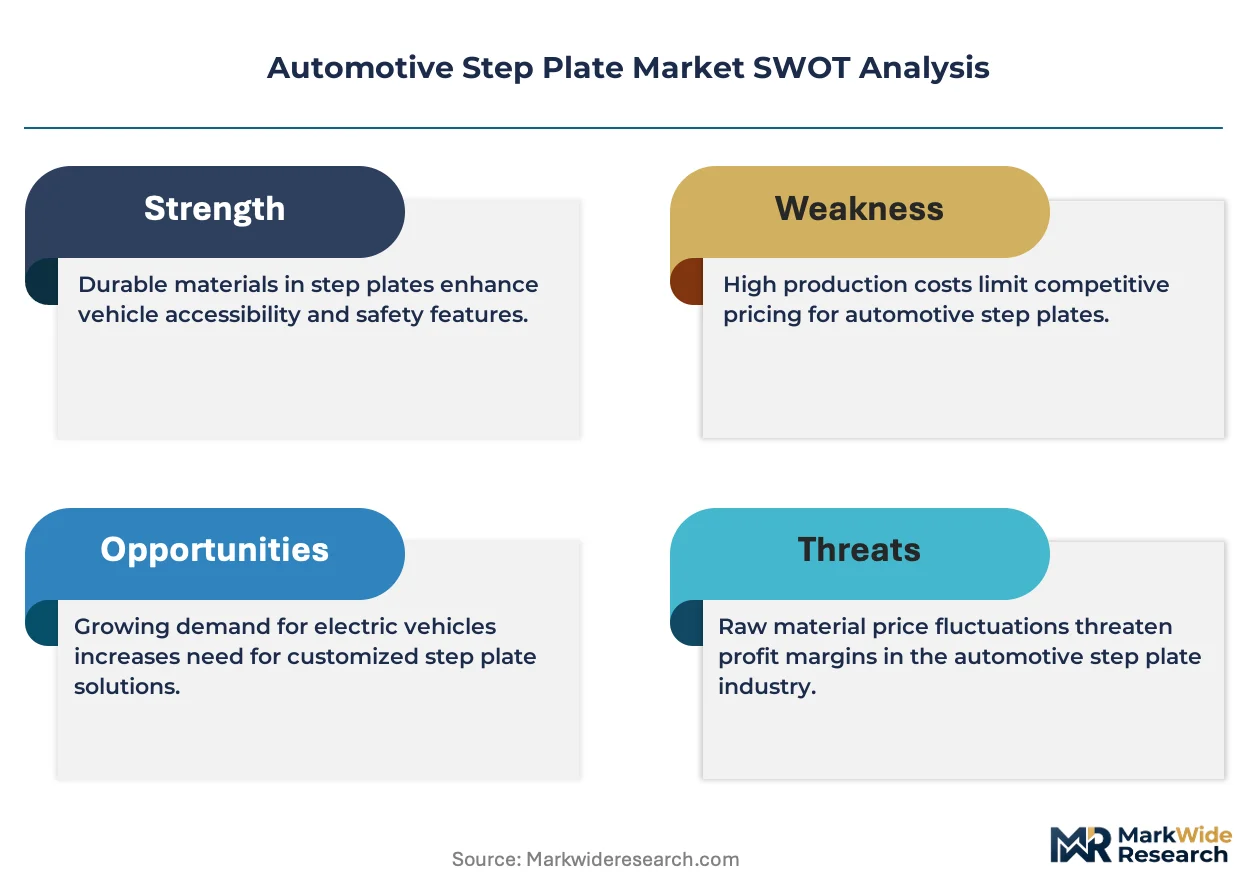
- NHTSA Pedestrian-Protection Rulemaking:The US Federal Motor Vehicle Safety Standards govern step projection and edge-radius limits, forcing OEM body-panel redesigns that incorporate larger, more robust step plate geometries.
- OSHA Workplace-Access Mandates:Commercial fleet operators face employer liability exposure under OSHA regulations extending to step geometry in employer-operated vehicles, accelerating aftermarket retrofit demand.
- Aluminum Extrusion Adoption:EPA lightweighting mandates indirectly drive material substitution toward aluminum alloy 5052-H32 variants as manufacturers pursue fuel-economy compliance through weight reduction.
Market Restraints
- Raw Material Cost Volatility:Aluminum alloy 5052-H32 and 304 stainless steel prices fluctuate with energy-intensive smelting costs, compressing margin pools for stamping operations serving price-sensitive aftermarket channels.
- Midwest Supply Concentration:Stamping and fabrication clusters concentrate in the US automotive supplier corridor, creating geographic vulnerability to regional labor disruptions or logistics bottlenecks.
- Pedestrian-Impact Geometry Constraints:Tightening EU pedestrian-safety frameworks limit design freedom for step-adjacent body panels, increasing engineering validation cycles and tooling amortization periods.
Strategic Opportunities
- Classic Truck Restoration Segment:Specialized custom plate fabrication for vintage vehicle restoration commands premium pricing and escapes commodity competition through bespoke design services.
- Direct Fleet Relationships:Upper Midwest fleet operators seek bypass distribution relationships with fabricators, disintermediating traditional aftermarket wholesale channels and capturing margin.
- Composite Material Convergence:Hybrid aluminum-composite step architectures emerge as EPA fuel-economy targets intensify, opening patent white space for lightweighting innovators.
Industry Challenges
- Die Engineering Talent Scarcity:Stamping tool and die design expertise concentrates among aging workforces in Michigan and Ohio supplier corridors, constraining capacity expansion timelines.
- Multi-Jurisdictional Certification Complexity:Pending pedestrian-safety rulemakings across US, EU, and emerging markets require parallel validation protocols, extending product launch cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Step Plate Market |
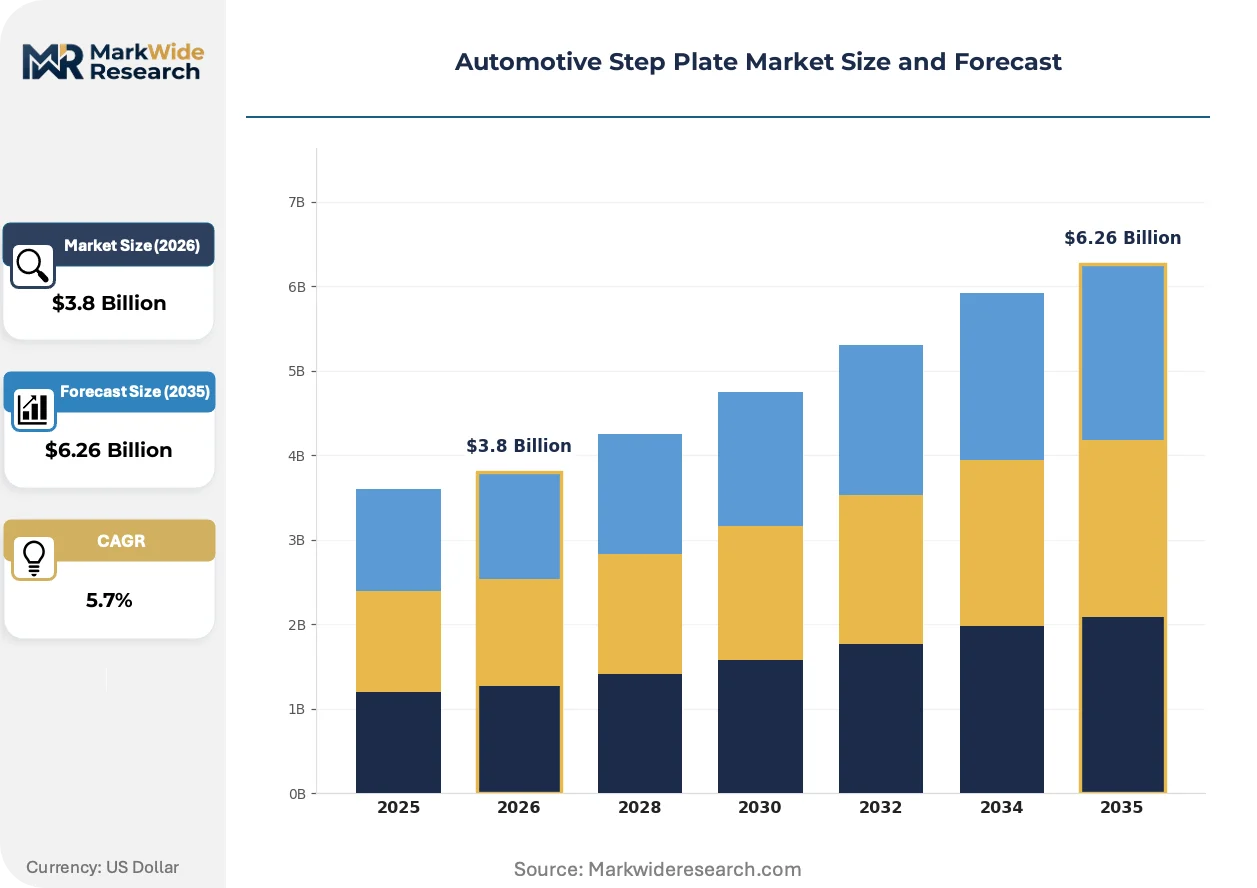
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.26 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Universal Plates, Custom Plates, Slip-Resistant Plates, Folding Plates Material: Aluminum, Stainless Steel, Plastic, Composite End User: OEMs, Aftermarket Providers, Tier-1 Suppliers, Vehicle Assemblers Installation Type: Surface Mounted, Flush Mounted, Retractable, Modular |
| Companies Covered | Roadworks, RK Auto Accessories, Iowa Customs, Roadsknz, Motorhunk, Brindle Products Inc., Dynacorn, Lifetime Nut Covers Inc., Classic Parts of America, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Step Plate Market Evolving Landscape
Stamping operations are digitizing quality assurance and die-maintenance protocols while regulatory pressure tightens impact-zone geometries and fleet procurement models bypass traditional distribution tiers.
Laser scanning and machine-vision systems are digitizing die-condition monitoring and first-article inspection workflows. Tier-1 stamping suppliers deploy these systems to compress defect detection cycles and reduce tooling downtime. The technology is digitizing quality assurance cost structures, shifting capital allocation from manual inspection labor toward predictive maintenance algorithms.
EU pedestrian-safety frameworks are tightening impact-zone geometry requirements for step-adjacent body panels. The regulation forces stamped-panel redesigns with larger radii and energy-absorbing structures. Commercial truck OEMs serving European markets accelerate aluminum substitution to meet dual objectives of pedestrian compliance and weight reduction.
Fleet procurement is consolidating vendor relationships and demanding direct contractual ties with stamping fabricators. Traditional aftermarket distributors face disintermediation as large Midwest fleet operators negotiate volume pricing and custom specifications. This pattern concentrates most visibly across Illinois, Iowa, and Wisconsin commercial trucking corridors where direct fleet-fabricator relationships displace wholesale channels.
Automotive Step Plate Market Segmentation
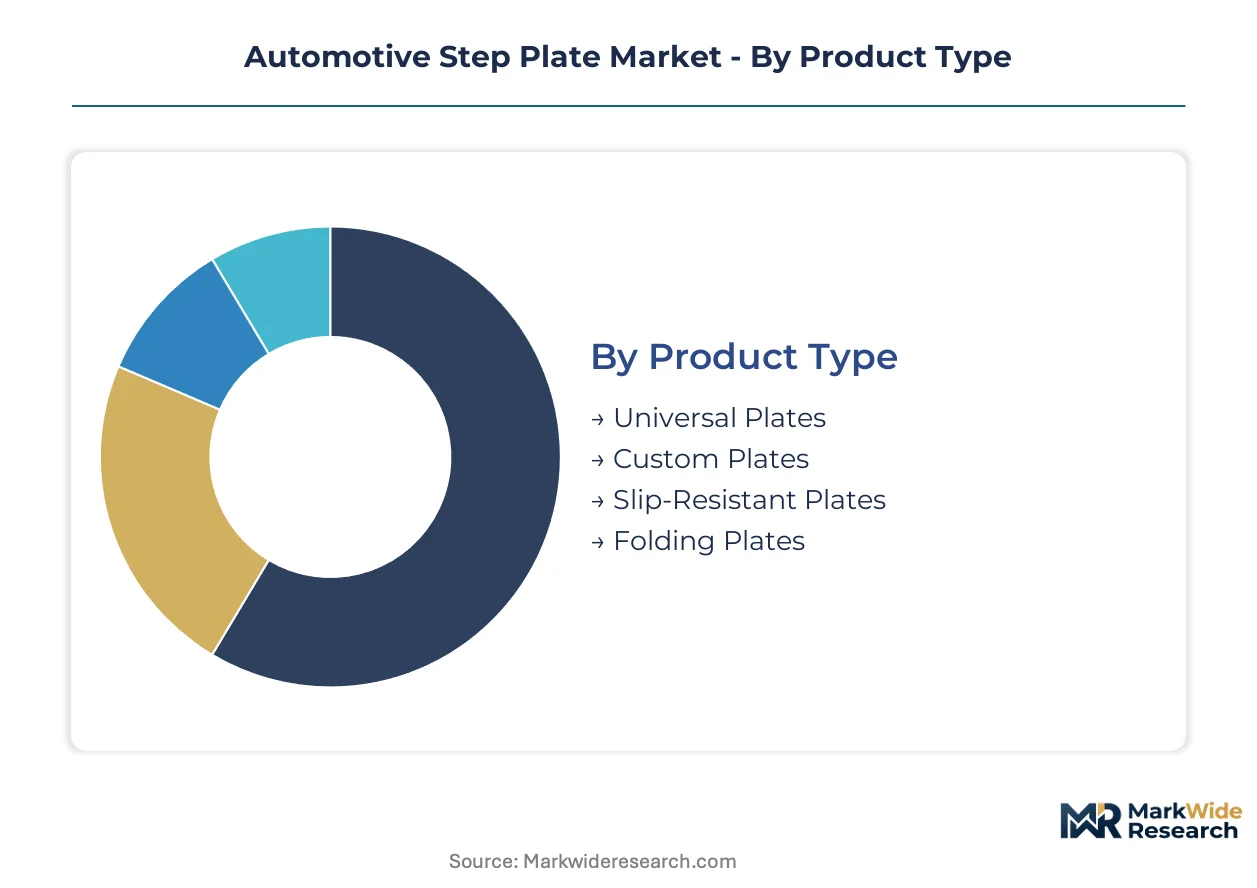
Automotive step plate segmentation reveals how material choices, installation methods, and channel strategies partition value capture across the supply chain. Product architecture and end-user procurement patterns determine margin distribution between standardized OEM supply and fragmented aftermarket customization.
Product Type:
Cost tier structures the product landscape, with pricing stratification separating commodity universal formats from engineered custom solutions.
- Universal Plates:Mass-produced stamped aluminum or steel plates with standardized mounting patterns serve high-volume fleet retrofit programs. Midwest stamping clusters supply these formats through wholesale distribution to price-sensitive commercial operators.
- Custom Plates:Bespoke fabrication accommodates non-standard cab geometries and classic truck restoration projects. Iowa Customs and RK Auto Accessories dominate this tier through direct fleet relationships and specialized design services.
- Slip-Resistant Plates:Diamond-tread or serrated surface profiles exceed OSHA workplace-access mandates for employer-operated commercial vehicles.
- Folding Plates:Hinged mechanisms retract against body panels to meet NHTSA pedestrian-protection edge-radius requirements.
Universal Plates commands the established base. The steepest expansion runs through Custom Plates.
Material:
Application severity and regulatory pressure divide material selection between corrosion-resistant premium grades and weight-optimized aluminum variants.
- Aluminum:Alloy 5052-H32 extrusions capture OEM volume through EPA lightweighting compliance. Roadworks controls raw material costs through captive aluminum extrusion capacity serving aftermarket channels.
- Stainless Steel:304-grade plates sustain premium pricing in severe-service mining and chemical transport fleets where corrosion resistance extends replacement cycles.
- Plastic:Polymer formulations address cost-constrained passenger vehicle segments with limited load-bearing requirements.
- Composite:Hybrid aluminum-composite architectures emerge as experimental platforms for next-generation pedestrian-impact compliance.
Aluminum dominates current volume. Stainless Steel retains the most defensible pricing power.
End User:
Customer type determines contract structure, with procurement consolidation reshaping channel relationships across direct and indirect supply paths.
- OEMs:Original equipment manufacturers specify step plates within integrated body-in-white programs, requiring Tier-1 stamping suppliers to meet NHTSA Federal Motor Vehicle Safety Standards for projection limits.
- Aftermarket Providers:Fragmented vehicle parc diversity supports the largest channel margin pool through lower standardization barriers and bypass distribution relationships with upper Midwest fleet operators.
- Tier-1 Suppliers:Stamping fabricators serving OEM programs face compressed design-modification timelines from tightening EU pedestrian-safety frameworks.
- Vehicle Assemblers:Final assembly operations integrate step plates into complete cab modules for commercial truck production.
Aftermarket Providers capture the widest margin spread. OEMs impose the most demanding certification requirements.
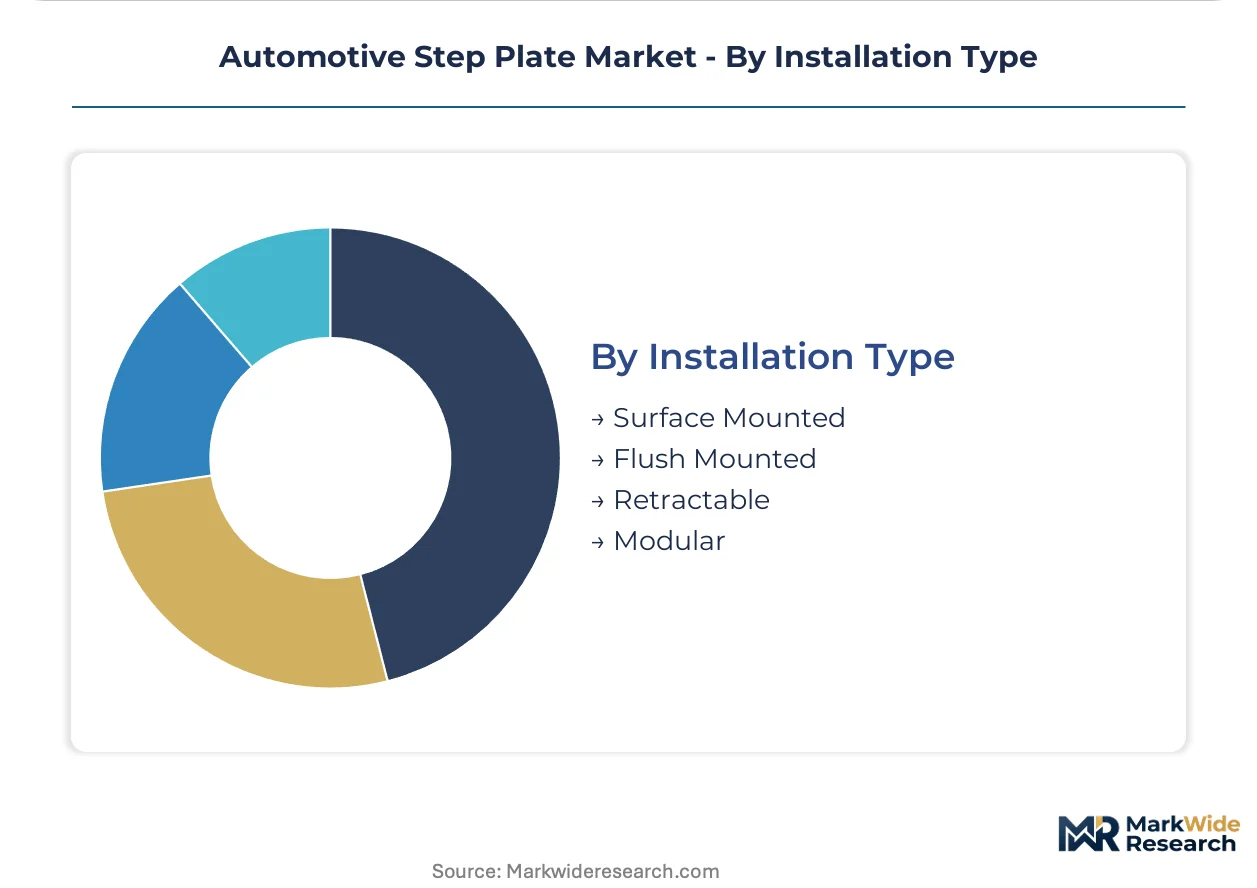
Installation Type:
Mounting geometry reflects regulatory constraints on pedestrian impact zones and fleet operator preferences for maintenance accessibility.
- Surface Mounted:External bracket systems simplify retrofit installation for fleet maintenance departments, dominating aftermarket retrofit demand across Illinois and Wisconsin commercial corridors.
- Flush Mounted:Recessed integration with body panels satisfies EU pedestrian-safety impact-zone geometry requirements, forcing stamped-panel redesigns with larger radii.
- Retractable:Deployable mechanisms stow during vehicle operation to minimize aerodynamic drag and pedestrian strike exposure.
- Modular:Interchangeable components enable rapid field replacement without complete plate removal, reducing fleet downtime.
Surface Mounted sustains aftermarket retrofit volume. Flush Mounted is gaining share fastest from regulatory compliance mandates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Stamping and fabrication capacity clusters heavily across the US Midwest automotive supplier corridor, with secondary concentrations emerging in Mexico's expanding automotive manufacturing belt and select European stamping centers serving commercial vehicle OEMs.
United States
Commercial fleet operators across Illinois, Iowa, and Wisconsin drive aftermarket retrofit demand through direct fabricator relationships. NHTSA Federal Motor Vehicle Safety Standards govern step projection and edge-radius limits for pedestrian protection. The Midwest supplier corridor concentrates die engineering expertise in Michigan and Ohio stamping clusters serving both OEM programs and aftermarket distribution networks.
Mexico
Expanding automotive stamping capacity near Monterrey and Mexico City reshapes North American supply dynamics for aluminum extrusion and stamped components. The country's automotive manufacturing integration under USMCA trade frameworks accelerates component localization requirements. Querétaro and Guanajuato industrial corridors attract Tier-1 stamping investments serving cross-border OEM assembly operations.
Germany
Commercial truck OEMs serving EU markets accelerate aluminum substitution to meet dual pedestrian-safety and lightweighting objectives. KBA vehicle type approval processes enforce EU pedestrian-impact framework compliance for step-adjacent body panel geometries. Baden-Württemberg and Bavaria stamping clusters specialize in high-precision automotive metal forming for premium commercial vehicle programs.
Canada
Ontario-based stamping operations supply integrated body-in-white programs for North American truck manufacturers. Transport Canada Motor Vehicle Safety Standards align with NHTSA pedestrian-protection thresholds for cross-border vehicle certification. The Windsor-Toronto industrial corridor maintains die maintenance and tooling capabilities supporting just-in-time OEM supply chains.
China
Domestic commercial vehicle manufacturers expand aluminum step plate adoption under MIIT fuel-economy compliance mandates for heavy-duty trucks. GB standards govern vehicle exterior protrusion limits affecting step geometry design parameters. Yangtze River Delta stamping clusters in Jiangsu and Zhejiang provinces scale capacity for both domestic OEM supply and export aftermarket channels.
Automotive Step Plate Market Competitive Landscape
Specialized custom fabricators and vertically integrated metal formers split the market between bespoke restoration services and high-volume fleet retrofit programs. The vendor base organizes around three strategic archetypes: captive aluminum extruders controlling raw material costs, regional distributors anchoring direct fleet relationships, and classic vehicle restoration specialists commanding premium pricing through design services. Competitive dynamics center on backward integration into aluminum supply and bypass distribution relationships disintermediating traditional wholesale channels.
Among North American fabricators, Roadworks exemplifies the captive supply archetype through upstream control over aluminum extrusion capacity serving aftermarket channels. Iowa Customs occupies a position within the direct fleet relationship tier, anchoring regional distribution across the upper Midwest through bypass procurement models. RK Auto Accessories represents the specialized restoration segment, sitting within the custom fabrication tier serving classic truck parc diversity outside commodity competition.
| Leading Market Players |
|---|
| Roadworks |
| RK Auto Accessories |
| Iowa Customs |
| Roadsknz |
| Motorhunk |
| Brindle Products Inc. |
| Dynacorn |
| Lifetime Nut Covers Inc. |
| Classic Parts of America |
| Others |
Value Network & Pricing Analysis
Midwest stamping cluster undercapacity is driving supplier selectivity toward long-term OEM contracts, compressing aftermarket availability and amplifying price premiums for spot aluminum alloy 5052-H32 purchases. Fleet procurement consolidation and NHTSA pedestrian-protection redesign costs are transmitting upstream, forcing fabricators to absorb tooling amortization or pass through to price-sensitive retrofit channels.
Pricing Analysis
NHTSA Federal Motor Vehicle Safety Standards dictate the pricing tier structure across OEM, fleet-direct, and aftermarket wholesale channels. Three-tier pricing structure across premium, standard, and economy levels separates stainless steel severe-service plates from aluminum OEM volume and polymer passenger vehicle formats. Price differentiation rests on certification grade and volume scale, with ISO-compliant Tier-1 contracts commanding premiums over uncertified aftermarket alternatives. Pricing pressure stems from raw material cost volatility in energy-intensive aluminum smelting. Aftermarket retrofit operators exhibit highest price sensitivity, while mining and chemical transport fleets prioritize corrosion resistance over unit cost.
Supply Chain Analysis
Contract manufacturing concentration sits with Michigan and Ohio stamping clusters serving integrated OEM programs, alongside Mexico's expanding Monterrey and Querétaro automotive corridors. Geographic supply concentration centers on the United States, Mexico, and Germany for precision metal forming. Raw material dependencies draw from primary aluminum smelters, 304 stainless steel mills, and diamond-tread surface treatment chemical suppliers. Supply chain risk manifests as single-source vulnerability in aging die engineering talent pools. Distribution runs through direct fleet-fabricator relationships disintermediating traditional wholesale channels across Illinois, Iowa, and Wisconsin commercial corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market sits at a platform-economics inflection where fleet telematics integration and predictive maintenance platforms are redefining step plate procurement from commodity hardware to connected vehicle ecosystem components.
For Market Incumbents: Harden backward integration into aluminum extrusion capacity to defend margin position against Roadworks' captive supply advantage. Consolidate die engineering talent through targeted recruitment in Michigan and Ohio corridors to offset workforce aging. Secure NHTSA pre-certification for next-generation pedestrian-impact geometries ahead of rulemaking finalization. For New Entrants and Emerging Players: Build out composite material capabilities targeting hybrid aluminum-composite architectures where patent white space remains open. Classic truck restoration segments offer lowest competitive density and highest pricing power. Pursue direct fleet relationships in upper Midwest commercial corridors bypassing established wholesale networks. For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-compliance infrastructure play because pedestrian-safety mandates are structurally expanding addressable market through mandatory retrofit cycles. Acquisition target archetype: regional fabricators with established fleet-direct relationships and ISO certification pathways. Monitor KBA and NHTSA rulemaking timelines as inflection signals for design-modification spending waves.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Aluminum Extrusion | Roadworks' captive supply model demonstrates margin control against spot price volatility in alloy 5052-H32. |
| Direct Fleet Relationship Development | Iowa Customs' bypass distribution across Illinois and Wisconsin corridors captures margin pool from wholesale disintermediation. |
| Pedestrian-Impact Certification Investment | EU KBA type approval and NHTSA FMVSS pre-compliance secure OEM program access ahead of rulemaking enforcement. |
| Composite Material R&D Partnership | Hybrid aluminum-composite architectures address dual EPA lightweighting and pedestrian-safety compliance objectives. |
| Die Engineering Talent Acquisition | Michigan and Ohio supplier corridor recruitment offsets aging workforce constraints on capacity expansion timelines. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with Tier-1 supplier procurement officers, OEM platform engineers, aftermarket distributors, fleet maintenance directors, and die engineering specialists; and secondary validation against vehicle production databases, NHTSA Federal Motor Vehicle Safety Standards filings, KBA type approval registries, aluminum alloy pricing indices, and customs trade records. Bottom-up and top-down triangulation cross-validated segment-level demand against aggregate market sizing.
Forecast inputs considered vehicle class, material substitution trajectory, regulatory compliance tier, OEM versus aftermarket channel mix, and regional production cluster dynamics across the projection horizon. CAGRs were derived from regression analysis of historical material adoption patterns and regulatory implementation schedules. Industry-specific forecast inputs included EPA lightweighting mandate stringency and EU pedestrian-safety framework phase-in timelines.
Stress conditions across aluminum price volatility, die engineering labor availability, and NHTSA rulemaking acceleration were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding regulatory implementation cadence and fleet replacement cycles. Quarterly review of KBA type approval volumes, Midwest stamping capacity utilization rates, and NHTSA Federal Register notices is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Parts
Norway Passenger Vehicles Lubricants Market
Automotive Parts
Oil Filter Market
Automotive Parts
Global All Wheel Drive Market
Automotive Parts
Automotive Hydraulic Filters Market
Automotive Parts
Industrial Brakes Market
Automotive Parts
Mobile Emission Catalysts Market
Automotive Parts
China Automotive Parts Magnesium Die Casting Market
Automotive Parts
Automotive Aluminium Extrusion Market
Automotive Parts
Passenger Car Wiper Blade Market
Automotive Parts
Global Intelligent Steering System Market
Automotive Parts
Automotive Coolant Pump Market
Automotive Parts
Automotive Engine Oil Coolant Market
Automotive Parts
Automotive Hoses Market
Automotive Parts
Automotive Adaptive Engine Mounts Market
Automotive Parts
Automatic Bus Door System Market
Automotive Parts
Electric Power Steering Market