
 Global Automotive Cylinder Liner Market | 2026-2036
Global Automotive Cylinder Liner Market Size, Share, and Industry Trends Forecast 2026-2036
Global Automotive Cylinder Liner Market Intelligence
The unbundling of complete engine block assemblies from individual component sales is decoupling aftermarket procurement from OEM-tied supply chains. This shift allows independent repair shops greater choice in sourcing replacement liners. Mahle GmbH leverages its comprehensive engine component portfolio to offer integrated solutions to both OEM and aftermarket channels. In contrast, ZYNP Corporation specializes in high-volume production for the domestic Chinese automotive market. Federal-Mogul LLC competes through its extensive global distribution network, ensuring wide availability for aftermarket suppliers and engine rebuilders.
An automotive cylinder liner is a cylindrical component inserted into an engine block to create the inner wall of a cylinder. It is manufactured to precise tolerances from materials like centrifugally cast iron to withstand extreme pressure and heat. The primary purpose is to provide a durable and replaceable wear surface for the piston rings, ensuring proper sealing and heat transfer. While cast iron liners dominate the market, demand for aluminum alloy and composite liners is rising for lightweighting in passenger vehicles. Wet cylinder liners, which are in direct contact with engine coolant, offer superior thermal management and are preferred in heavy-duty commercial vehicle applications.
Regulatory frameworks are a primary influence on product development and material selection. The US EPA’s stringent emission standards and Europe's Euro 7 regulations mandate significant reductions in particulate matter and NOx. These rules compel engine manufacturers to adopt advanced liner technologies, including specialized coatings and surface texturing, to optimize combustion and minimize friction. Supplier success now depends on aligning material science innovation with the specific thermal management and friction reduction requirements of next-generation engine platforms.
Market Dynamics
The market’s core dynamic is the material science divergence between lightweight passenger vehicles and durable heavy-duty trucks. This split is driven by distinct powertrain strategies and geographically varied emissions regulations like Europe's Euro 7 and US EPA standards.
Growth Catalysts
- Logistics Fleet Expansion:Rising e-commerce activity in India and China drives demand for new commercial vehicles, directly increasing consumption of durable wet cylinder liners for diesel engines.
- Stringent Emission Standards:Europe's Euro 7 regulations compel engine upgrades, boosting demand for liners with advanced surface coatings that reduce friction and oil consumption to meet new limits.
- Aftermarket Independence:The unbundling of complete engines allows independent repair networks in North America and Europe to source liners directly, bypassing traditional OEM-tied supply chains for service parts.
Market Restraints
- Raw Material Volatility:Price fluctuations in high-grade cast iron and aluminum alloys create significant margin pressure for manufacturers, especially those serving the price-sensitive aftermarket segment.
- BEV Proliferation Threat:The accelerating transition to battery electric vehicles in the passenger car segment represents a long-term structural decline for all internal combustion engine components, including liners.
- High-Precision Manufacturing Costs:The tight tolerances for modern liners demand substantial capital investment in centrifugal casting and CNC honing equipment, creating high barriers to entry for new competitors.
Strategic Opportunities
- Advanced Composite Materials:Developing metal matrix composite liners offers a performance advantage for high-output engines, creating an entry point into performance automotive and motorsport segments.
- Non-Automotive Applications:Adapting heavy-duty diesel liner technology for stationary power generation and marine propulsion engines opens new, less cyclical industrial revenue streams for manufacturers.
- Surface Technology Licensing:Patenting proprietary laser-honed surface texturing patterns that improve oil retention and reduce emissions can create a high-margin intellectual property business model.
Industry Challenges
- Skilled Machinist Shortage:A scarcity of technicians proficient in advanced CNC programming and metrology for precision grinding processes hinders production scaling and consistent quality control across the industry.
- Coating Application Complexity:Applying thermal spray coatings like plasma-transferred wire arc (PTWA) requires specialized, capital-intensive equipment and strict environmental controls, complicating production workflows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Automotive Cylinder Liner Market |
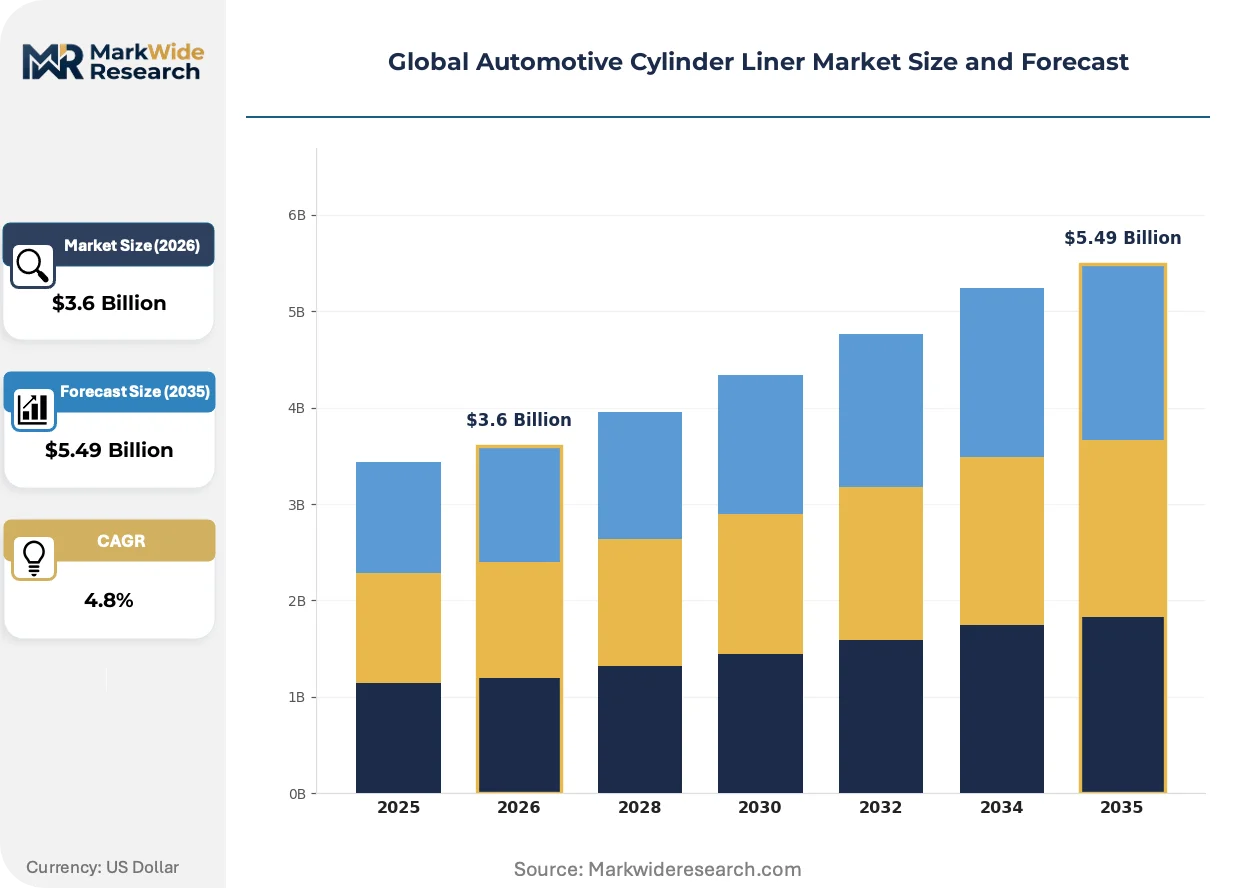
| Market Size in 2026 | $3.6 Billion |
| Market Size in 2035 | $5.49 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Dry Cylinder Liners, Wet Cylinder Liners, Composite Liners, Replacement Liners Material: Cast Iron, Aluminum Alloy, Steel Alloy, Nickel-based Alloy Application: Passenger Vehicles, Commercial Vehicles, Construction Equipment, Agricultural Machinery End User: OEM Manufacturers, Aftermarket Suppliers, Engine Rebuilders, Vehicle Maintenance Services |
| Companies Covered | TPR Co. Ltd, Cooper Corp, Mahle GmbH, Westwood Cylinder Liners Ltd, Darton International Inc., Tenneco, ZYNP Corporation, Federal-Mogul LLC, Nippon Piston Ring Co. Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Automotive Cylinder Liner Market Strategic Shifts & Innovations
Material science and surface engineering are adapting to simultaneous pressures for greater engine efficiency and extended operational life. Innovations focus on reducing parasitic losses and improving thermal management, particularly for commercial diesel engine platforms that face stricter emissions rules.
Additive manufacturing enables rapid prototyping of liner designs with intricate, optimized cooling channels. Research and development departments at engine OEMs and performance tuning firms are the primary adopters for creating test components. This capability is decentralizing design innovation away from solely large-scale foundries, allowing smaller, specialized engineering firms to contribute to next-generation engine development.
Implementation of the US EPA’s Greenhouse Gas Emissions Standards for heavy-duty vehicles compels significant improvements in overall engine efficiency. This regulation is forcing a move toward downsized, higher-pressure engines that require more robust and thermally efficient components. The heavy-duty truck segment is most affected, responding with increased adoption of advanced cast iron alloys and low-friction surface coatings for liners.
Fleet operators’ growing preference for remanufactured engines over new replacements is altering aftermarket supply dynamics. This shift disrupts the traditional one-way flow of new parts from manufacturers to service centers, creating demand for high-quality, standalone replacement liners suitable for the engine rebuilding process. The trend is most visible in North America and Europe, where total cost of ownership is a key procurement driver for commercial fleets.
Global Automotive Cylinder Liner Market Segmentation
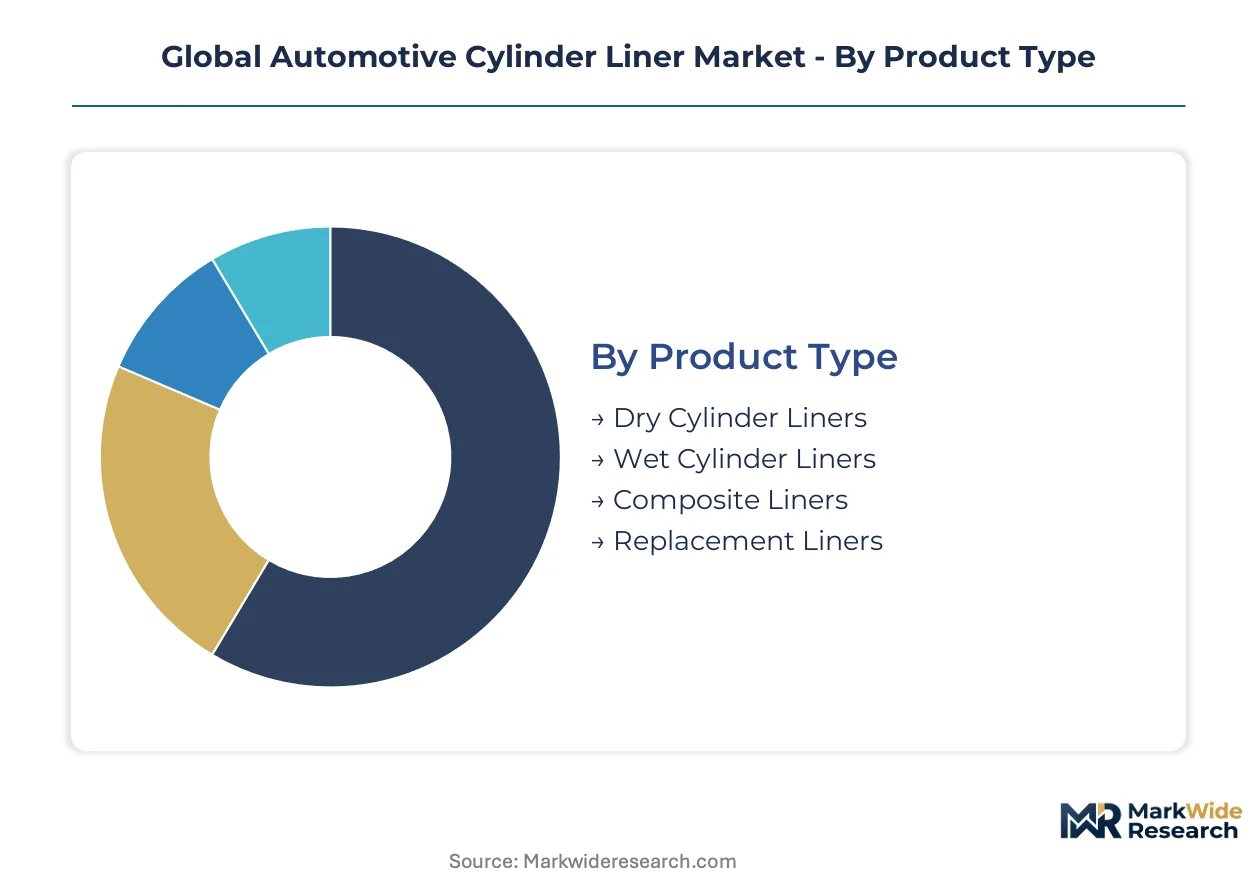
Understanding the Global Automotive Cylinder Liner Market through segmentation reveals distinct demand drivers and technological priorities across different product types, materials, applications, and end-user categories. This granular view highlights where innovation is critical and where established solutions maintain dominance, guiding strategic investment.
Product Type:
Purchasing decisions for cylinder liners frequently hinge on the specific engine design and thermal management requirements.
- Wet Cylinder Liners:These liners are in direct contact with engine coolant, providing superior thermal management for high-output and heavy-duty engines. Demand concentrates in commercial vehicles, driven by fleet expansion for logistics in China and India.
- Composite Liners:Manufactured from advanced materials like metal matrix composites, these liners offer significant lightweighting and enhanced wear resistance for performance engines. Adoption is growing in passenger vehicles, particularly in Europe, as manufacturers seek improved fuel efficiency.
- Dry Cylinder Liners:Inserted into the engine block without direct coolant contact, these are common in smaller, less thermally stressed engines. Production volumes remain high for cost-sensitive passenger vehicle segments in emerging markets.
- Replacement Liners:These components are specifically designed for aftermarket repair and engine rebuilding, catering to the longevity requirements of older vehicle fleets. Aftermarket demand is strong in North America and Europe.
Volume sits with Dry Cylinder Liners; growth tilts toward Composite Liners.
Material:
Application dictates the optimal material choice for cylinder liners, balancing durability and weight.
- Cast Iron:This traditional material offers excellent wear resistance and heat dissipation, making it ideal for heavy-duty diesel engines. It dominates the commercial vehicle segment, particularly in markets with stringent durability requirements like the US.
- Aluminum Alloy:Chosen for its lightweight properties, aluminum alloy liners contribute to overall vehicle weight reduction and improved fuel economy. Passenger vehicle manufacturers, especially those in Germany and Japan, increasingly specify these for smaller displacement engines.
- Steel Alloy:These materials provide enhanced strength and wear characteristics compared to standard cast iron, suitable for high-performance or high-stress engine applications. Specialized engine builders in Europe utilize steel alloys for durability.
- Nickel-based Alloy:Used in highly specialized or extreme performance engines, nickel-based alloys offer superior high-temperature strength and corrosion resistance. Niche automotive segments and motorsport applications adopt these materials.
Material innovation is driven by the need for enhanced thermal efficiency and reduced friction across all engine platforms.
Application:
Engine performance characteristics and operational demands define the specific cylinder liner requirements for various vehicle applications.
- Commercial Vehicles:This segment requires robust, durable cylinder liners capable of withstanding prolonged heavy-duty operation and high thermal loads. Logistics fleet expansion in India and China is a primary driver for wet cylinder liner consumption.
- Passenger Vehicles:Liners for passenger vehicles prioritize lightweighting, friction reduction, and fuel efficiency to meet evolving emissions standards. European and Japanese automotive OEMs focus on advanced coatings for these applications.
- Construction Equipment:Heavy-duty engines in construction machinery demand liners engineered for extreme durability and resistance to harsh operating conditions. Global infrastructure projects sustain demand for these resilient components.
- Agricultural Machinery:Engines in agricultural equipment operate under varying loads and often in dusty environments, requiring liners with high wear resistance and reliability. Modern farming practices in North America and Europe support this segment.
The commercial sector maintains robust demand for durable liners, while passenger car applications increasingly prioritize lightweight solutions.
End User:
Supply chain dynamics and procurement strategies heavily influence how different end-users acquire automotive cylinder liners.
- OEM Manufacturers:These companies integrate cylinder liners directly into new engine block assemblies during vehicle production. Mahle GmbH and ZYNP Corporation serve this segment by supplying components for initial vehicle builds.
- Aftermarket Suppliers:These entities distribute replacement liners through independent channels for vehicle repair and maintenance. Federal-Mogul LLC leverages its global network to serve this extensive market.
- Engine Rebuilders:Specialists in engine overhaul and refurbishment procure standalone cylinder liners to restore engine functionality. This segment thrives in North America and Europe due to the preference for remanufactured engines.
- Vehicle Maintenance Services:Independent workshops and dealership service centers source liners for routine engine repairs and component replacements. Availability through local distributors is critical for these service providers.
Aftermarket channels are expanding their sourcing independence, challenging the traditional OEM-centric supply model.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The global automotive cylinder liner market exhibits a significant production-consumption divide, with manufacturing hubs in Asia supplying diverse global demands. This geographic split influences material selection and technological investment across key regions. Stricter emission standards in developed markets drive innovation, while fleet expansion in emerging economies sustains high volume production.
China
Demand for commercial vehicles drives high-volume production of wet cylinder liners. The MIIT's focus on domestic automotive production fuels local manufacturing capacity. Major industrial clusters in the Yangtze River Delta concentrate on supplying both domestic and export markets.
India
Expanding logistics fleets and infrastructure projects sustain demand for robust cast iron liners. The PLI scheme encourages local manufacturing and technological upgrades within the automotive sector. Tamil Nadu's automotive hub, Chennai, remains a critical center for engine component production.
United States
Aftermarket independence and heavy-duty truck segment needs define liner procurement. US EPA standards for heavy-duty vehicles compel advanced liner technologies for emissions reduction. Detroit's automotive ecosystem continues to innovate in engine component design and material science.
Germany
Stringent Euro 7 emission regulations drive demand for lightweight composite and advanced coated liners. The KBA's oversight ensures compliance with environmental and safety standards for engine components. Bavaria's engineering firms specialize in high-performance engine development and material innovation.
Japan
Passenger vehicle lightweighting initiatives increase the specification of aluminum alloy liners. METI promotes research into high-efficiency engine components and advanced manufacturing techniques. The Tokyo-Nagoya corridor hosts numerous automotive OEMs and their specialized component suppliers.
Global Automotive Cylinder Liner Market Key Industry Players
The competitive structure tilts toward specialized component manufacturers, balancing scale and precision requirements. Several strategic archetypes operate, including large diversified engine component suppliers and niche high-performance material specialists. Dominant competitive moves involve strategic partnerships for technology development and continuous capacity expansion to meet global demand.
Within the diversified component supplier archetype, Mahle GmbH exemplifies a global presence across both OEM and aftermarket channels, offering integrated engine solutions. ZYNP Corporation, a China-based Co., Ltd., occupies a strong position in high-volume domestic production for the extensive Chinese automotive market, focusing on scale. Federal-Mogul LLC represents a global distribution powerhouse, anchoring wide availability for aftermarket engine rebuilders and service providers worldwide through its extensive network. These entities demonstrate the varied strategic approaches, from comprehensive portfolio integration to specialized volume manufacturing and broad aftermarket reach, that define the competitive landscape for automotive cylinder liners.
| Leading Market Players |
|---|
| TPR Co. Ltd |
| Cooper Corp |
| Mahle GmbH |
| Westwood Cylinder Liners Ltd |
| Darton International Inc. |
| Tenneco |
| ZYNP Corporation |
| Federal-Mogul LLC |
| Nippon Piston Ring Co. Ltd |
| Others |
Cost & Logistics Intelligence
Fleet operators' growing preference for remanufactured engines fundamentally alters aftermarket supply dynamics. This shift creates demand for high-quality, standalone replacement liners, influencing pricing structures away from OEM-tied bundles.
Pricing Analysis
Margin tightening across the automotive cylinder liner market reflects volatile raw material costs. Contract-based long-term offtake agreements characterize OEM pricing, while per-unit transactional models dominate the aftermarket. Price differentiation stems from precision tolerances and comprehensive after-sales service. The aftermarket segment demonstrates the highest price sensitivity, whereas heavy-duty commercial vehicle applications prioritize durability over cost.
Supply Chain Analysis
A scarcity of skilled machinists in manufacturing hubs like China, India, and Germany hinders consistent quality control for cylinder liners. The supply chain relies on high-grade cast iron and aluminum alloys. Raw material price volatility represents a significant structural risk for manufacturers. Distribution runs through a dual model, with direct OEM supply complemented by extensive independent aftermarket channels globally.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The automotive cylinder liner market is poised for consolidation, driven by the accelerating transition to battery electric vehicles. This long-term structural decline for internal combustion engine components will force out weaker, less innovative players.
For Market Incumbents: Lock in long-term supply agreements with commercial vehicle OEMs, leveraging established trust. Invest heavily in advanced material science, particularly composite liners and specialized coatings, to meet Euro 7 emission standards. This defends against the long-term threat of BEV proliferation by extending the viability of high-efficiency ICE platforms. Capacity expansion in key manufacturing hubs like India also strengthens market position.
For New Entrants and Emerging Players: Enter via specialized segments requiring advanced material science, such as performance automotive and motorsport applications. Target the market for advanced composite liners offering superior performance advantages. Licensing proprietary surface technology, like laser-honed texturing patterns, provides a high-margin intellectual property business model. This approach bypasses the capital-intensive high-volume production of traditional liners.
For Investors and Strategic Acquirers: The window for entry favors strategic acquirers seeking to consolidate market share and advanced material IP. Long-term viability for the next 5-10 years remains strong in the heavy-duty commercial vehicle segment, despite passenger car electrification. Target vertically integrated mid-cap specialists possessing proprietary surface engineering technologies or advanced composite material expertise. Watch the adoption rates of composite liners in new commercial engine platforms as a key inflection indicator.
| Strategic Initiative | Industry Significance |
|---|---|
| Advanced Material R&D | Develop lightweight aluminum alloy and composite liners for European passenger vehicle OEMs. |
| Non-Automotive Diversification | Adapt heavy-duty diesel liner technology for marine propulsion and stationary power generation engines. |
| Aftermarket Channel Expansion | Strengthen global distribution networks to serve independent engine rebuilders in North America and Europe. |
| Surface Technology Licensing | Monetize proprietary laser-honed surface texturing patterns for friction reduction and emission compliance. |
| Manufacturing Capacity Upgrade | Invest in centrifugal casting and CNC honing equipment to meet high-precision demands from US EPA standards. |
Research Approach
Document review covered vehicle production databases, IHS Markit registration data, and technical journals, complemented by interviews with industry stakeholders. Primary interviews engaged Tier 1 supplier procurement leads, OEM platform engineers, aftermarket distributors, and engine rebuilding specialists. This approach facilitated bottom-up data aggregation and top-down market validation. Secondary research further validated primary findings.
Volume and value forecasts were generated through an integrated analytical framework, combining historical data with future projections across the analysis window. Segmentation dimensions modeled included product type, material, application, end-user, and regional production clusters. Compound annual growth rates were projected by analyzing historical trends and demand drivers. Key inputs included vehicle production volumes and emission regulation timelines.
Forecast precision tightens around the base case; tail outcomes carry wider variance under rapid BEV adoption or unforeseen raw material supply disruptions. Forecasts reflect underlying macroeconomic and technological assumptions. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Parts
North America Automotive AHSS Market
Automotive Parts
Global Auto Parts and Accessories Market
Automotive Parts
Global Intelligent Steering System Market
Automotive Parts
Automotive Hydraulic Filter System Market
Automotive Parts
Camshaft Bearings Market
Automotive Parts
Automotive Surface Coated Brake Market
Automotive Parts
South Africa Automotive Parts Aluminium Die Casting Market
Automotive Parts
Gearshift Sleeves Market
Automotive Parts
Automotive Brake Fluid Market
Automotive Parts
Italy Automotive Airfilters Market
Automotive Parts
Electric Parking Brake Market
Automotive Parts
UK Automotive Parts Zinc Die Casting Market
Automotive Parts
China Passenger Vehicles Lubricants Market
Automotive Parts
Automotive Wheel Speed Sensor Tone Ring Market
Automotive Parts
Global Automotive Ignition Market
Automotive Parts
North America Automotive Parts Zinc Die Casting Market