
 Gym Wipes Market | 2026-2036
Gym Wipes Market Size, Share, and Industry Trends Forecast 2026-2036
Gym Wipes Market Analytics
Boutique fitness operators is redrawing procurement priorities across the hygiene supply chain. ERC Wiping Products leverages its manufacturing scale to serve large commercial gym networks with consistent volume commitments. 2XL Corporation specializes in antibacterial formulations that meet institutional standards for high-touch equipment sanitization. Performance Health anchors its position through direct relationships with physical therapy and rehabilitation centers that require medical-grade surface protocols.
Gym wipes are nonwoven or textile substrates pre-saturated with cleaning, disinfecting, or sanitizing solutions, typically formulated with quaternary ammonium compounds, alcohol blends, or plant-derived actives at concentrations ranging from 0.5% to 5% by weight, designed for single-use application on fitness equipment surfaces to reduce pathogen transmission between users. Antibacterial formulations dominate current procurement volumes due to their established efficacy claims against Staphylococcus aureus and Influenza A, while biodegradable substrates represent the fastest-growing product type as operators face waste diversion mandates and member sustainability expectations. Bucket packaging occupies the largest share of institutional contracts because of its dispensing efficiency in high-traffic floor areas, though pouch formats are gaining traction among boutique studios seeking flexible inventory management.
The EPA regulates disinfectant efficacy claims through its Office of Pesticide Programs, requiring registered products to meet specific kill-time standards against designated organisms before marketing to commercial fitness operators. OSHA's bloodborne pathogen standards influence wipe selection in facilities offering personal training or physical rehabilitation services where exposure risk elevates compliance obligations. State-level environmental regulations in California and New York are restricting volatile organic compound thresholds in cleaning formulations, compelling manufacturers to reformulate active ingredient profiles. Stakeholders must monitor evolving state chemical disclosure requirements and third-party certification programs that increasingly influence RFP scoring for multi-location gym contracts.
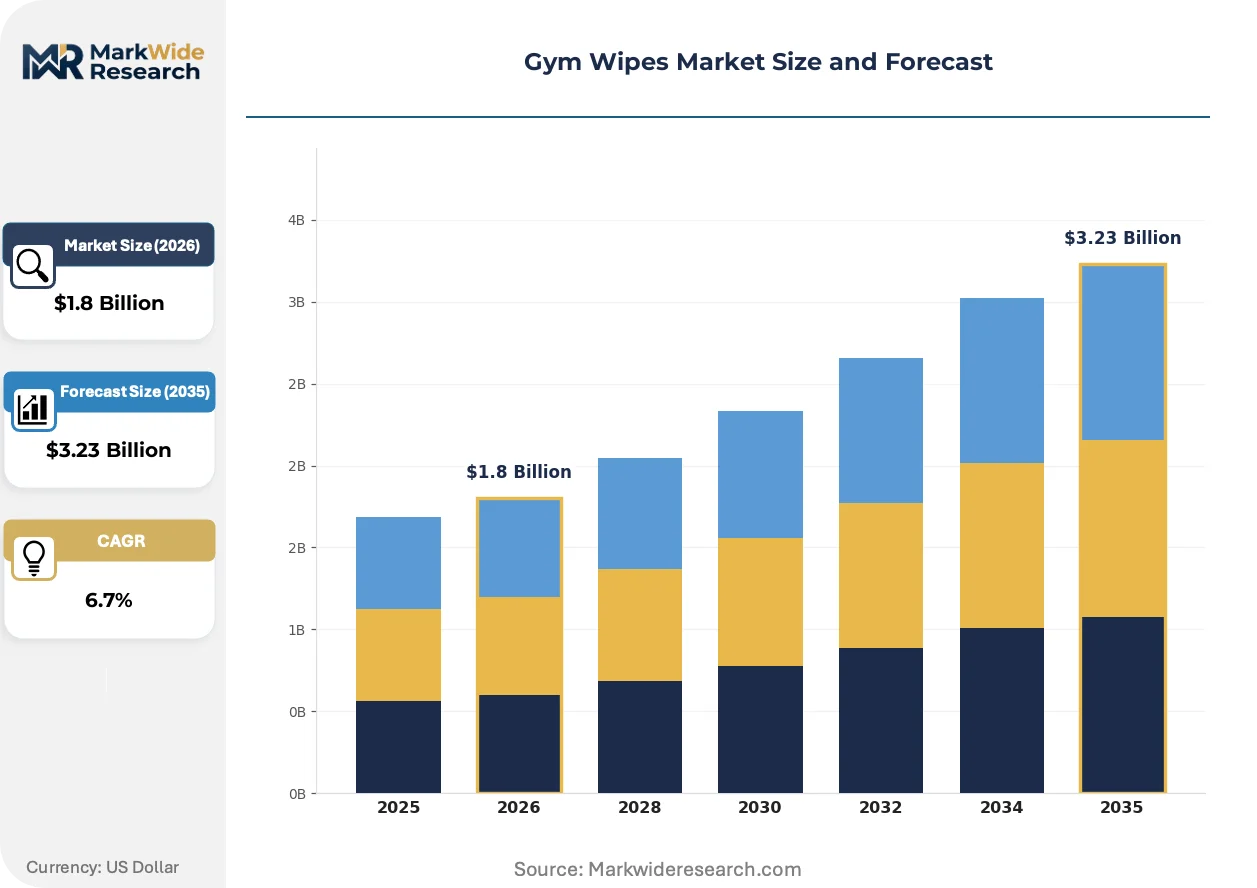
Market Dynamics
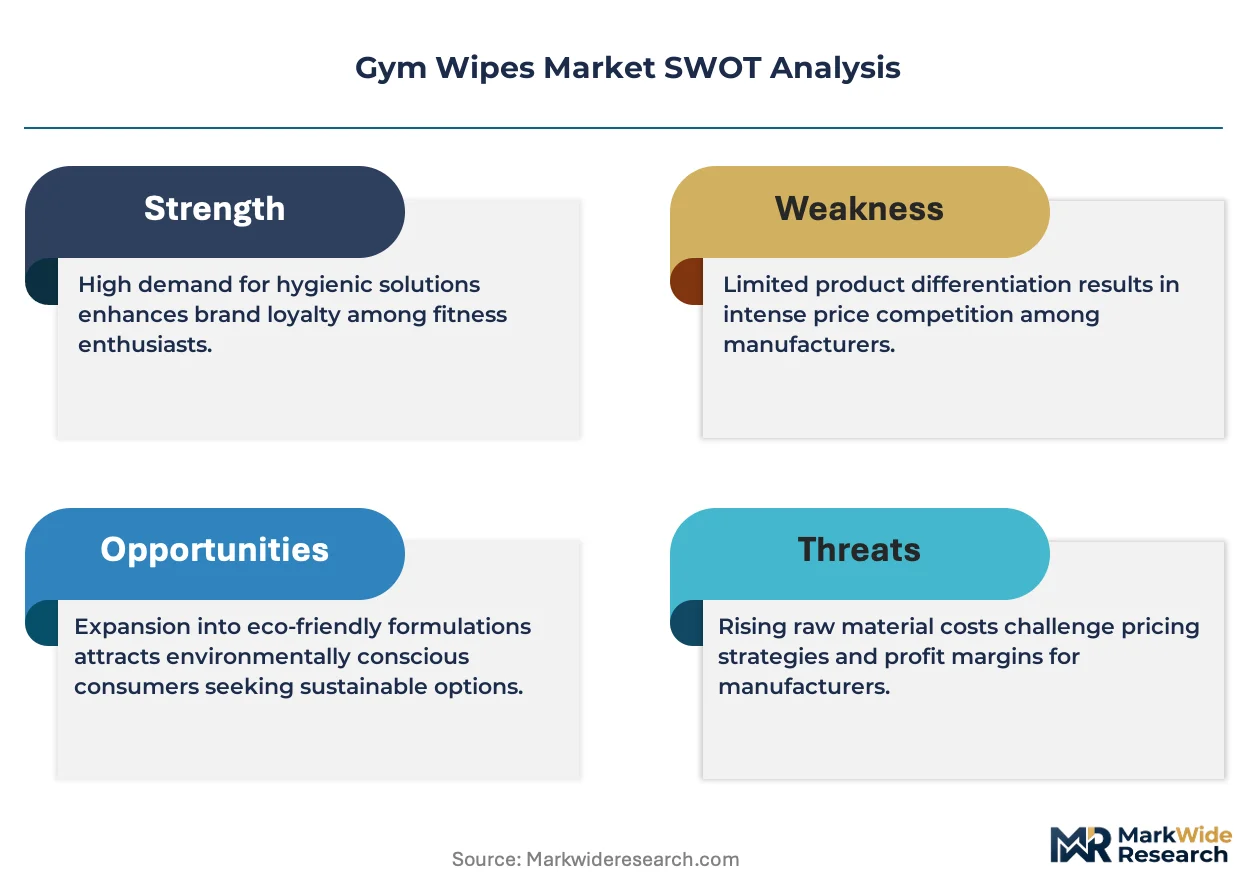
The EPA's emerging disinfectant efficacy requirements are forcing manufacturers toward reformulation while boutique fitness operators accelerate procurement cycles beyond traditional health club patterns.
Growth Catalysts
- California VOC restrictions:State-level environmental regulations in California and New York are compelling manufacturers to develop lower-emission formulations, opening premium positioning for compliant products.
- CrossFit box expansion:Boutique fitness studios are expanding hygiene budgets faster than legacy health clubs, creating concentrated demand for specialized wipe formats.
- Quaternary ammonium compound innovation:Advances in QAC stability at broader temperature ranges are extending product shelf life and reducing cold-chain logistics costs for distributors.
Market Restraints
- Isopropyl alcohol price volatility:Feedstock cost fluctuations for alcohol blends compress margin structures for mid-tier manufacturers without long-term supply contracts.
- Nonwoven substrate concentration:Supply of biodegradable cellulose substrates concentrates among Southeast Asian converters, exposing procurement to freight rate instability.
- EPA registration timelines:The Office of Pesticide Programs review cycles for new active ingredients extend 18-36 months, delaying product commercialization for reformulated offerings.
Strategic Opportunities
- Physical therapy vertical:Medical-grade surface protocols in rehabilitation centers remain underpenetrated relative to commercial gym saturation.
- Plant-derived active convergence:Combination of thymol-citric acid formulations with compostable substrates addresses dual sustainability and efficacy demands.
- Pouch format channel innovation:Flexible inventory management through pouch packaging creates entry points for direct-to-studio distribution models bypassing institutional distributors.
Industry Challenges
- Biodegradability certification complexity:Third-party compostability standards from BPI and TUV Austria require 6-12 month validation timelines that misalign with rapid product development cycles.
- Legacy dispenser incompatibility:Existing bucket-based infrastructure in large gym networks creates friction for thinner substrate formats optimized for pouch dispensing.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Gym Wipes Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Biodegradable, Antibacterial, Hypoallergenic, Textile Packaging Type: Bucket, Pack, Roll, Pouch Usage Frequency: Daily, Weekly, Occasional, Seasonal Distribution Channel: Online, Retail, Wholesale, Gym Supply |
| Companies Covered | ERC Wiping Products, Performance Health, 2XL Corporation, Universal Companies, Hangzhou Biogen Hygiene, Zogics, Texon Towel and Supply, Wipex Co., American Hygienics Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Gym Wipes Market Evolving Landscape
Formulation chemistry and substrate engineering are diverging along sustainability-performance axes as regulatory pressure intensifies and buyer segments fragment by operational scale.
Plant-derived active ingredient platforms are fragmenting the traditional QAC-alcohol dichotomy that has dominated institutional procurement. Thyme oil, citric acid, and lactic acid formulations are capturing shelf space in boutique studios prioritizing member-perceived safety over kill-time metrics. This fragmentation is compressing pricing power for legacy chemical suppliers while enabling premium positioning for botanical claim substantiation.
REACH chemical authorization procedures in Europe are tightening residual solvent thresholds for imported wipe substrates, forcing nonwoven converters to validate supply chain chemistry documentation. Manufacturers serving EU markets must now maintain substance volume tracking across Tier 2 and Tier 3 suppliers. Fitness operators with transatlantic locations are consolidating procurement specifications to meet the stricter European standard rather than maintaining dual formulation inventories.
Boutique studio buying collectives are displacing individual location purchasing through regional cooperative agreements that aggregate volume for manufacturer-direct relationships. These collectives bypass traditional janitorial supply distributors, compressing channel margins while demanding custom substrate sizes and private-label packaging. Sun Belt metropolitan clusters with high gym density are exhibiting the fastest cooperative formation rates, concentrating negotiation leverage among multi-brand studio operators.
Gym Wipes Market Segmentation
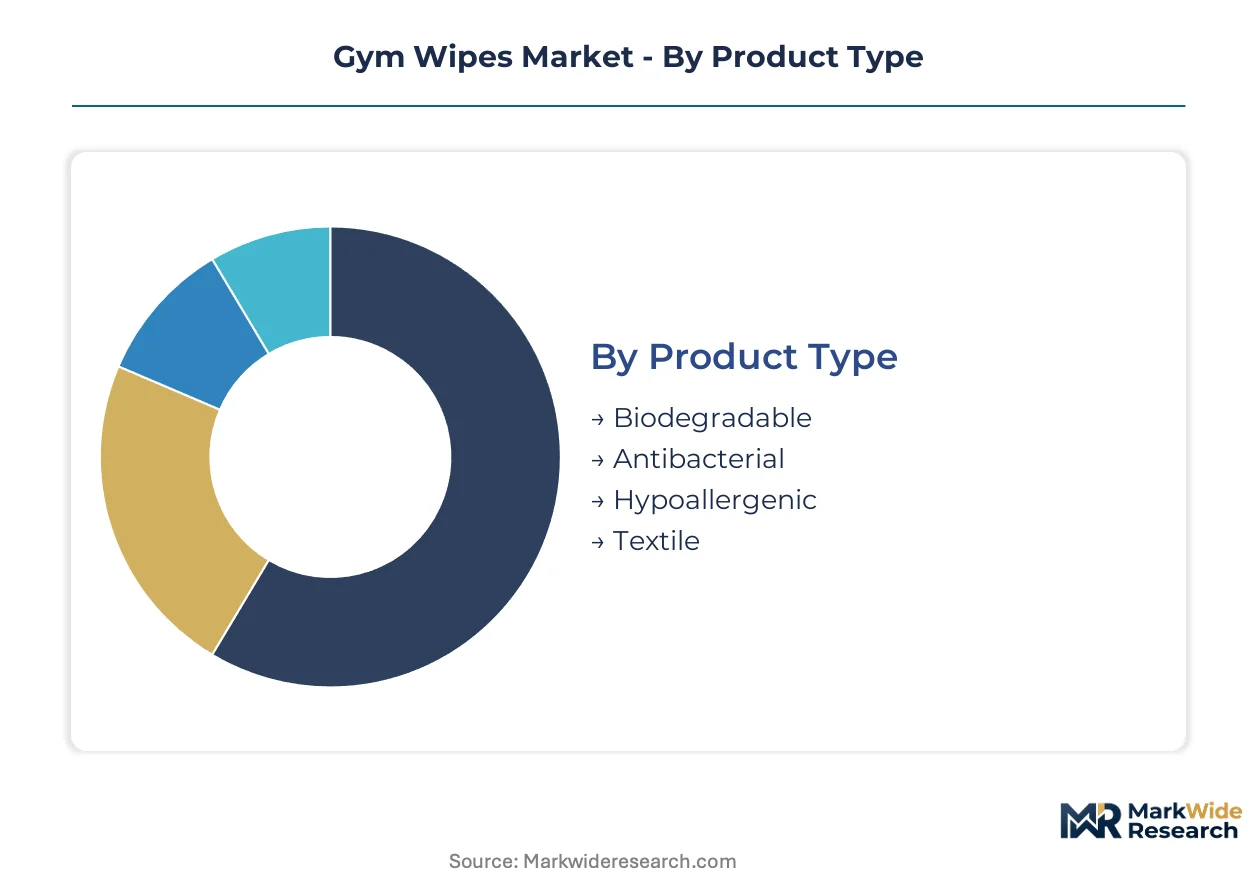
Gym wipe procurement fragments sharply across operational scales, with boutique studios and institutional networks diverging on substrate chemistry, packaging format, and compliance tier. Regulatory pressure from EPA efficacy mandates and state-level VOC restrictions is forcing buyers to match segment selection with specific certification requirements rather than defaulting to lowest unit cost.
Product Type:
EPA registration status and active ingredient disclosure requirements create tiered compliance obligations that separate institutional contracts from boutique studio procurement.
- Antibacterial:Formulations rely on quaternary ammonium compounds or alcohol blends at 0.5% to 5% concentration by weight, delivering established kill-time claims against Staphylococcus aureus and Influenza A. Large commercial gym networks in Sun Belt metropolitan areas concentrate procurement here due to liability exposure and member throughput demands.
- Biodegradable:Cellulose substrates paired with plant-derived actives target waste diversion mandates in California and New York, where operators face member sustainability expectations and composting infrastructure requirements. CrossFit boxes and boutique studios in these states are expanding procurement faster than legacy health clubs.
- Hypoallergenic:Fragrance-free formulations with reduced quaternary ammonium compound concentrations serve physical therapy and rehabilitation centers where OSHA bloodborne pathogen standards elevate skin sensitivity protocols.
- Textile:Reusable woven substrates with laundering specifications appeal to premium eco-conscious operators seeking to eliminate single-use waste streams entirely.
Antibacterial formulations handle the majority of throughput; biodegradable alternatives are gaining share fastest as state environmental regulations tighten.
Packaging Type:
Volume scale and dispenser infrastructure investment determine format selection, with large networks locked into legacy systems while agile entrants exploit flexible alternatives.
- Bucket:Institutional contracts favor this format for high-traffic floor dispensing efficiency, though existing infrastructure creates friction for substrate format innovation. Large gym networks with consistent volume commitments anchor demand here.
- Pouch:Flexible inventory management enables direct-to-studio distribution models that bypass traditional janitorial supply distributors. Boutique studio buying collectives in dense Sun Belt clusters are aggregating negotiation leverage through regional cooperative agreements.
- Pack:Pre-counted units support precise usage tracking and budget forecasting for mid-size operators with standardized cleaning protocols.
- Roll:Continuous dispensing suits automated or semi-automated equipment sanitization stations in high-end fitness facilities.
Bucket packaging dominates institutional contract value; pouch formats are expanding most quickly through boutique channel disruption.
Usage Frequency:
Member density and equipment sharing patterns dictate wipe consumption cadence, with regulatory exposure highest in continuous-use environments.
- Daily:High-throughput commercial gyms with shared equipment protocols require continuous availability to meet member hygiene expectations and reduce pathogen transmission liability.
- Weekly:Lower-traffic facilities or specialized studios with equipment assignment systems reduce consumption through controlled access models.
- Occasional:Personal training-focused operations with scheduled appointments rather than open gym access moderate usage through appointment-based equipment allocation.
- Seasonal:Outdoor fitness installations and pop-up training locations concentrate demand in temperate months, requiring inventory flexibility from distributors.
Daily usage absorbs the highest absolute volume; seasonal applications are climbing the fastest as outdoor and hybrid fitness formats proliferate.
Distribution Channel:
Channel selection reflects buyer scale and procurement sophistication, with consolidation pressure squeezing traditional intermediaries.
- Wholesale:Janitorial supply distributors serve legacy health club networks with established credit terms and consolidated SKU management, though margins compress as boutique collectives bypass this tier.
- Gym Supply:Specialized distributors with equipment expertise bundle wipe procurement with dispenser maintenance and compliance documentation, anchoring relationships with institutional buyers.
- Online:Direct manufacturer relationships through digital platforms enable smaller operators to access volume pricing previously reserved for large networks, particularly for pouch and pack formats.
- Retail:Big-box and specialty fitness retailers capture incidental and emergency replenishment demand from individual consumers and small independent studios.
Wholesale channels transact the highest institutional volume; gym supply specialists are capturing share fastest through bundled service differentiation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Los Angeles anchors trans-Pacific substrate supply chains for North American gym wipe manufacturers, while Rotterdam's container terminals serve equivalent functions for European converters sourcing Southeast Asian cellulose.
United States
Sun Belt metropolitan clusters including Phoenix, Dallas, and Miami concentrate boutique fitness expansion with elevated hygiene procurement budgets. EPA's Office of Pesticide Programs enforces disinfectant efficacy registration requirements that filter market entry for reformulated products. California's South Coast Air Quality Management District operates the nation's strictest VOC thresholds, compelling manufacturers to develop lower-emission quaternary ammonium compound alternatives for operators in Los Angeles and San Diego counties.
Germany
REACH chemical authorization procedures from ECHA tighten residual solvent thresholds for imported nonwoven substrates, forcing supply chain documentation upgrades. The country's fitness operator consolidation around McFit and John Reed clubs creates volume concentration for institutional contract bidding. Industrial converters in North Rhine-Westphalia's Ruhr corridor specialize in medical-grade wipe substrates serving rehabilitation centers across Düsseldorf and Cologne metropolitan zones.
China
Domestic gym chain expansion led by Lefit and Supermonkey drives substrate demand for equipment sanitization protocols. MIIT's GB standards for nonwoven hygiene materials establish baseline quality specifications that export-oriented manufacturers must exceed for EU and US market access. Zhejiang and Jiangsu province converters dominate cellulose substrate production, with Ningbo port infrastructure enabling cost-competitive export logistics to Southeast Asian boutique fitness markets.
United Kingdom
Post-pandemic hygiene expectations persist in London's premium studio segment, sustaining elevated wipe consumption rates above continental European averages. HSE guidance on workplace cleaning standards influences procurement specifications for corporate gym facilities in the Square Mile and Canary Wharf. Manchester and Birmingham regional chains are consolidating purchasing through cooperative agreements that bypass traditional janitorial distributors.
Australia
Outdoor and hybrid fitness format proliferation concentrates seasonal demand spikes in Queensland and New South Wales coastal metropolitan areas. TGA's disinfection product regulations create parallel registration requirements that delay product launches relative to US EPA timelines. Melbourne's boutique studio density in inner-northern suburbs generates concentrated demand for biodegradable substrate formats aligned with municipal composting infrastructure.
Gym Wipes Market Competitive Landscape
Concentration sits with mid-scale specialists rather than diversified chemical conglomerates, creating a tiered structure where manufacturing scale, formulation chemistry, and distribution channel control define competitive position. Three archetypes dominate: substrate-integrated converters with captive nonwoven supply, formulation-focused specialists with EPA registration expertise, and channel-optimized distributors with direct boutique studio relationships. Capacity expansion and private-label portfolio diversification represent the dominant competitive moves, with players adding pouch-format production lines and securing compostable substrate certifications.
Within the scale-driven tier, ERC Wiping Products occupies a position anchored by volume commitments from large commercial gym networks, while 2XL Corporation exemplifies the formulation-specialist archetype through its antibacterial product focus. Performance Health represents the medical-grade vertical, sitting within rehabilitation center supply chains that demand distinct compliance documentation. These three companies illustrate how competitive positioning fragments across operational scale and end-use specialization rather than consolidating around unified platform strategies.
| Leading Market Players |
|---|
| ERC Wiping Products |
| Performance Health |
| 2XL Corporation |
| Universal Companies |
| Hangzhou Biogen Hygiene |
| Zogics |
| Texon Towel and Supply |
| Wipex Co. |
| American Hygienics Corporation |
| Others |
Value Network & Pricing Analysis
EPA registration status gates both supplier qualification and price differentiation simultaneously, separating institutional-grade formulations with verified kill-time claims from unregistered alternatives that compete purely on unit cost. Boutique studios in California and New York absorb premium pricing for VOC-compliant formulations, while legacy health clubs leverage volume scale to compress per-wipe costs.
Pricing Analysis
Volume-discount tiering structures dominate institutional procurement, with large commercial gym networks commanding standard-tier pricing through consistent offtake commitments. Certification grade and geographic delivery cost differentiate tiers, with EPA-registered formulations carrying premium positioning over unregistered alternatives. Pricing pressure stems from isopropyl alcohol feedstock volatility, compressing margins for mid-tier manufacturers lacking long-term supply contracts. Boutique fitness operators exhibit lowest price sensitivity, prioritizing sustainability credentials and member-perceived safety over unit economics.
Supply Chain Analysis
Inventory lead times stretch longest for biodegradable cellulose substrates sourced through Southeast Asian converters, exposing distributors to freight rate instability. Manufacturing concentrates in China, Vietnam, and Indonesia for nonwoven production, with quaternary ammonium compounds and alcohol blends drawn from domestic US and European chemical suppliers. Single-source vulnerability concentrates in Zhejiang province substrate converters. Distribution runs through janitorial supply wholesalers for legacy networks, while boutique collectives increasingly bypass intermediaries for manufacturer-direct relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The gym wipes market represents a high-growth disruption as boutique fitness expansion collides with EPA efficacy mandates and state-level environmental regulations. This regulatory-technological inflection fragments procurement patterns and creates tiered competitive arenas.
For Market Incumbents: Fortify position through backward integration into biodegradable substrate supply and captive EPA registration expertise. Threats from boutique buying collectives and plant-derived formulation entrants demand defensive certification investment. Capacity addition in California-adjacent production hubs addresses VOC compliance and logistics cost compression.
For New Entrants and Emerging Players: Anchor in the physical therapy and rehabilitation vertical, where medical-grade surface protocols remain underpenetrated relative to commercial gym saturation. Pouch-format distribution models bypass entrenched wholesale channels. Direct-to-studio relationships through regional cooperative agreements unlock volume aggregation without legacy infrastructure investment.
For Investors and Strategic Acquirers: EPA's emerging disinfectant efficacy requirements reshape the acquisition landscape toward formulation-specialist targets with registration pipelines and compostable substrate certifications. Long-term viability favors players with dual sustainability-performance positioning. Watch boutique studio buying collective formation rates as inflection indicator for channel disruption velocity.
| Strategic Initiative | Industry Significance |
|---|---|
| Compostable Substrate Certification | BPI and TUV Austria validation opens California and New York procurement to premium positioning. |
| Pouch Format Production Line Addition | Flexible packaging capacity captures boutique studio demand bypassing institutional distributors. |
| Plant-Derived Formulation R&D | Thymol-citric acid platforms address dual sustainability and efficacy demands in eco-conscious segments. |
| Regional Cooperative Partnership | Sun Belt buying collective relationships aggregate negotiation leverage for manufacturer-direct contracts. |
| EPA Registration Pipeline Investment | Accelerated Office of Pesticide Programs navigation reduces commercialization delays for reformulated offerings. |
Research Methodology
A standing panel of gym operations directors, procurement managers at multi-location fitness networks, janitorial supply distributors, and EPA regulatory consultants provided ongoing calibration across the study period. Primary interviews with boutique studio owners and physical therapy center administrators combined with secondary validation from EPA Office of Pesticide Programs registration databases, OSHA bloodborne pathogen guidance documents, and state environmental agency VOC threshold filings. Bottom-up facility count modeling and top-down chemical consumption estimates triangulated volume projections.
Consistency checks against external benchmarks validated output plausibility across the projection horizon. Segmentation dimensions modeled include product type tier, packaging format, usage frequency cadence, and distribution channel structure, with regional regulatory cluster as an additional cross-cutting dimension. CAGRs derived from equipment sanitization protocol adoption curves and membership throughput assumptions, informed by fitness operator expansion plans and waste diversion mandate implementation timelines.
Material uncertainties — EPA registration timeline delays, feedstock price volatility, and cooperative buying collective formation rates — sit outside the modeled envelope. Forecasts reflect assumptions about regulatory enforcement intensity and boutique fitness expansion velocity. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
Global Surface Analysis Market
Others
South Asia Geosynthetics Market
Others
Asia-Pacific Programmatic Display Advertising Market
Others
Printed Leather Market
Others
Taiwan Retail Market
Others
Iran Commercial Vehicles Lubricants Market
Others
Agitation System Market
Others
North America Wiring Duct Market
Others
Industrial Air Purifiers Market
Others
Free Space Optics (FSO) Market
Others
Europe Air Separation Unit Market
Others
Digital Mortgage Software Market
Others
Aircraft Cameras Market
Others
Language Translation Device Market
Others
US Quantum Computing Market
Others
Hookah Tobacco Market