
 Cloud Advertising Market | 2026-2036
Cloud Advertising Market Size, Share, and Industry Trends Forecast 2026-2036
Cloud Advertising Market Analysis
Programmatic ad exchanges is rewriting how media inventory changes hands between buyers and sellers. Amazon Web Services anchors cloud infrastructure for real-time bidding stacks across North America and Europe. Google LLC dominates search advertising auctions through its integrated buy-side and sell-side technology. The Trade Desk specializes in independent demand-side platform access, competing against walled-garden alternatives.
Cloud advertising encompasses the delivery, targeting, measurement, and optimization of promotional content through internet-hosted infrastructure, typically operating on sub-100-millisecond latency thresholds for real-time auction participation. Its primary commercial purpose is to match advertiser budgets with addressable audiences across digital channels without on-premise hardware ownership. Search advertising and social media advertising represent the largest revenue pools, while video advertising registers the fastest structural ascent as connected television inventory migrates to programmatic pipes. The public cloud deployment model leads in scale, though hybrid cloud configurations are gaining traction among agencies managing sensitive client data.
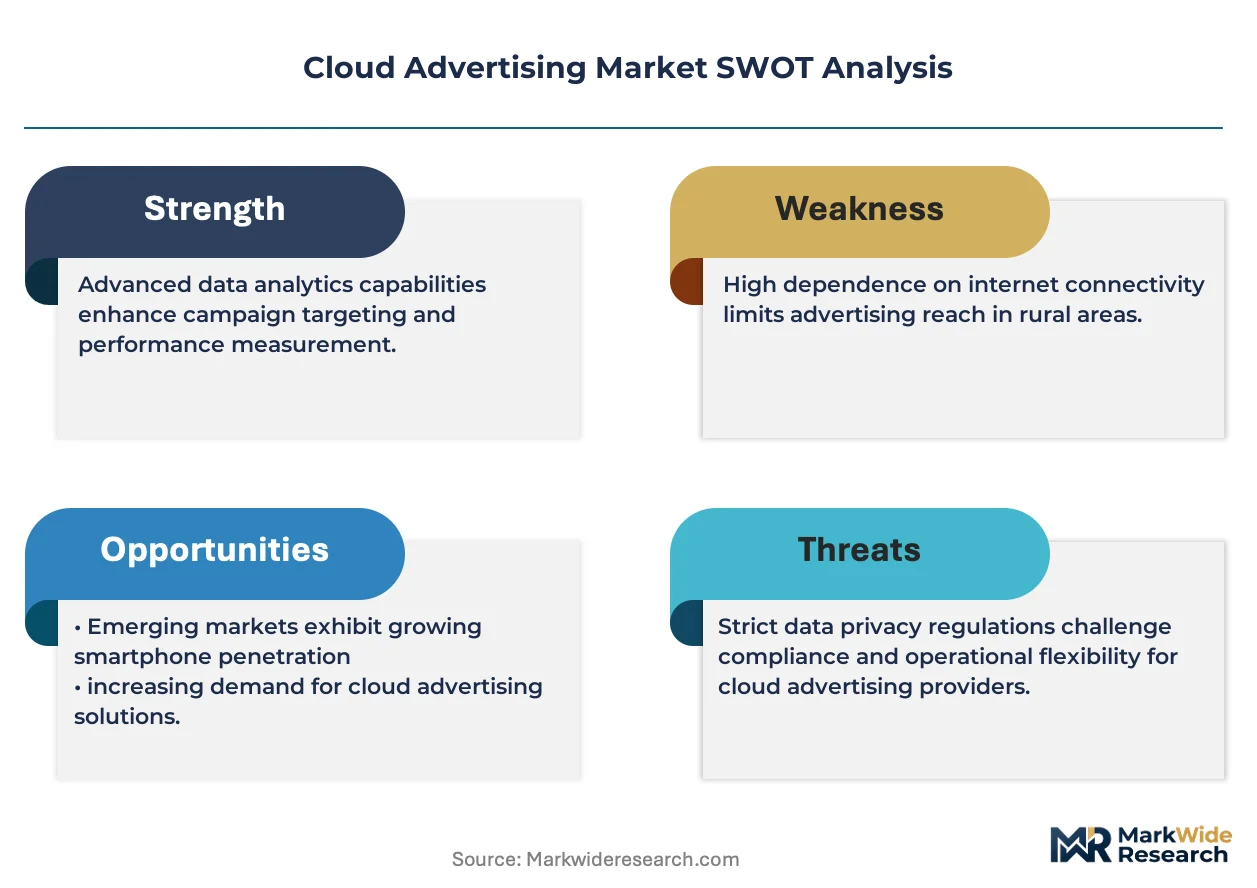
FCC guidelines on consumer privacy, GDPR consent frameworks in Europe, and the EU Digital Services Act content moderation obligations collectively raise compliance costs for cross-border campaigns. These regulations shape demand by forcing advertisers toward first-party data strategies and verified measurement partners. Stakeholders must monitor how antitrust scrutiny of ad-tech intermediaries reshapes platform pricing and data portability rules.
Market Dynamics
Real-time bidding infrastructure is compressing media transaction latency to sub-100-millisecond thresholds, forcing advertisers to restructure data pipelines and measurement workflows around cloud-native auction mechanics rather than traditional insertion-order workflows.
Growth Catalysts
- Connected Television Migration:Broadcast and cable inventory is flowing into programmatic pipes as publishers seek yield optimization. Advertisers gain addressable reach against previously linear-only audiences.
- GDPR Consent Frameworks:European privacy mandates are accelerating first-party data infrastructure investment. Brands are building direct consumer relationships to maintain targeting precision without third-party cookies.
- Hyperscaler Clustering:Demand concentrates in Northern Virginia, Seattle, and New York where AWS, Microsoft Azure, and Google Cloud operate adjacent data centers. Proximity reduces round-trip latency for auction participation.
Market Restraints
- Compliance Cost Escalation:FCC guidelines on consumer privacy and EU Digital Services Act obligations force cross-border campaigns to maintain parallel legal and technical stacks. Operational overhead rises with jurisdiction count.
- Platform Concentration Risk:Buy-side and sell-side technology stacks consolidate under a handful of vertically integrated operators. Advertisers face limited bargaining power on pricing and data portability terms.
- Measurement Fragmentation:Absence of unified viewability and attribution standards across walled gardens and open web degrades cross-platform performance comparison. Media mix modeling complexity increases.
Strategic Opportunities
- Retail Media Networks:First-party purchase data from grocery, electronics, and apparel retailers enables closed-loop attribution. CPG brands are redirecting search budgets toward on-site sponsored placements.
- Privacy-Enhancing Technologies:Differential privacy and secure multi-party computation allow cohort-based targeting without individual identification. Clean rooms are emerging as compliance-compatible collaboration venues.
- Audio and Podcast Programmatic:Digital audio inventory remains undermonetized relative to video and display. Dynamic ad insertion technology is unlocking addressable impressions in streaming music and spoken-word content.
Industry Challenges
- Specialized Talent Scarcity:Cloud advertising operations require fluency in both programmatic trading mechanics and data engineering. The intersection of these skill sets commands premium compensation and lengthens hiring cycles.
- Legacy System Integration:Enterprise advertisers maintain on-premise customer data platforms and financial reconciliation tools. API mismatches and schema incompatibilities delay cloud migration timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cloud Advertising Market |
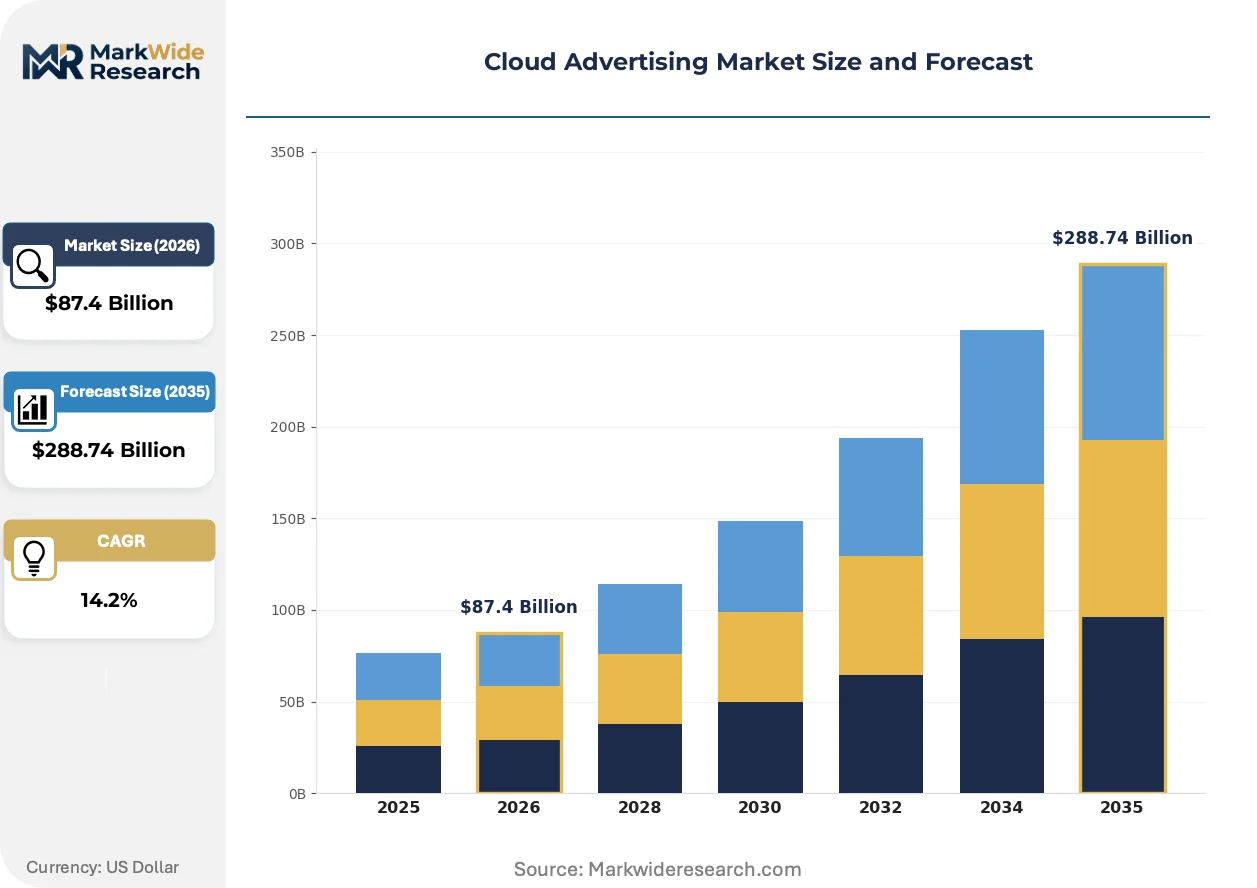
| Market Size in 2026 | $87.4 Billion |
| Market Size in 2035 | $288.74 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Display Advertising, Video Advertising, Search Advertising, Social Media Advertising Deployment Model: Public Cloud, Private Cloud, Hybrid Cloud, Multi-Cloud End User: Small Enterprises, Medium Enterprises, Large Corporations, Agencies Pricing Model: Pay-Per-Click, Cost-Per-Action, Subscription-Based, Pay-Per-Impression |
| Companies Covered | Adobe Inc., Salesforce Inc., Amazon Web Services Inc., Meta Platforms Inc., The Trade Desk Inc., Google LLC, Oracle Corporation, IBM Corporation, Microsoft Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cloud Advertising Market Emerging Trajectories
Artificial intelligence is restructuring how creative assets are generated, trafficked, and optimized across cloud advertising infrastructure. Three developments are compressing traditional workflows and redefining competitive advantage.
Generative creative tools are collapsing the production timeline between brief and live campaign. Retail and direct-to-consumer brands are deploying thousands of variant assets simultaneously, testing headline-image-offer combinations through automated multivariate frameworks. This compression is eliminating the traditional agency-studio handoff and reallocating budget toward media spend and algorithmic optimization.
The EU AI Act's risk classification framework is reshaping how automated decision-making systems deploy in European campaigns. High-risk applications in credit and employment advertising face mandatory conformity assessments and human oversight requirements. Advertisers operating across member states are segmenting their technology stacks to isolate EU traffic and maintain compliance without degrading performance elsewhere.
Outcome-based compensation structures are displacing traditional CPM and CPC pricing in verticals with measurable downstream transactions. Retail media platforms and performance marketing agencies are aligning fees with attributable sales rather than impression delivery. This shift is most pronounced in consumer packaged goods and financial services, where closed-loop measurement connects ad exposure to purchase or application completion.
Cloud Advertising Market Segmentation
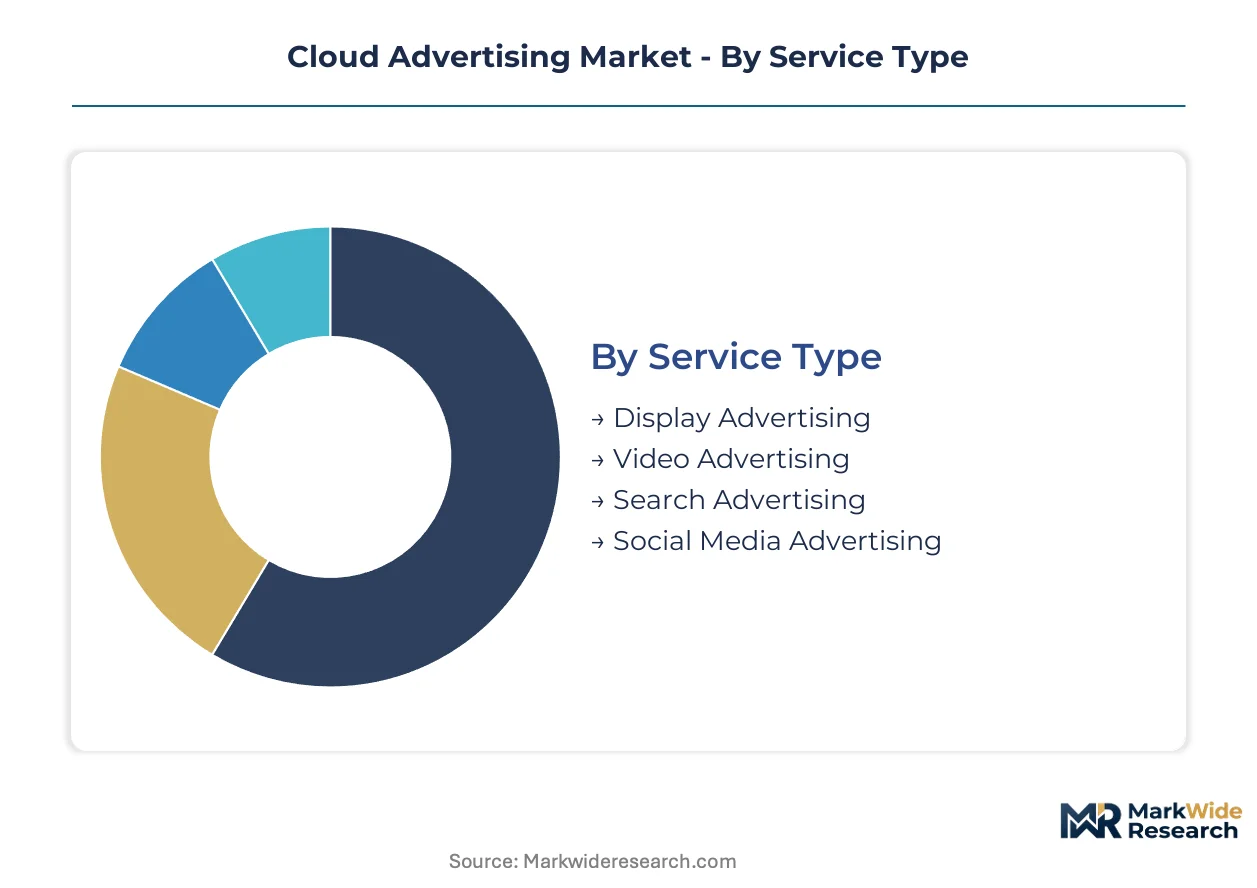
Cloud advertising segmentation reveals how infrastructure choices, service configurations, and commercial terms reshape competitive positioning. Buyers select across multiple dimensions simultaneously—deployment architecture constrains data sovereignty options while pricing models determine risk allocation between advertiser and platform.
Service Type:
Application focus distinguishes how advertisers allocate creative production and measurement resources across channels.
- Search Advertising:Keyword-triggered text placements capture high-intent commercial queries. Retail and financial services advertisers in the United States concentrate spend here for bottom-funnel conversion efficiency.
- Social Media Advertising:Native feed placements leverage demographic and behavioral signals for awareness campaigns. Direct-to-consumer brands building first-party data assets drive demand for interactive formats.
- Display Advertising:Banner and rich media units across publisher networks.
- Video Advertising:Pre-roll, mid-roll, and connected television inventory.
Search advertising commands the established base. The steepest expansion runs through video advertising.
Deployment Model:
Cost tier and data control requirements segment buyers by compliance sensitivity and latency tolerance.
- Public Cloud:Shared infrastructure delivers elastic compute for real-time bidding at lowest unit cost. Programmatic trading desks in Seattle and New York prioritize this model for auction participation speed.
- Hybrid Cloud:Split workloads isolate sensitive consumer data on private nodes while bursting auction logic to public capacity. European agencies navigating GDPR consent complexity favor this architecture.
- Private Cloud:Dedicated single-tenant environments.
- Multi-Cloud:Orchestrated workloads across AWS, Azure, and Google Cloud.
Public cloud deployments command the established base. The steepest expansion runs through hybrid cloud configurations.
End User:
Customer type determines contract structure, platform access tier, and service-level agreement terms.
- Large Corporations:Direct platform contracts with dedicated customer engineering and bespoke API integrations. Fortune 500 advertisers in Northern Virginia negotiate annual minimum commitments exceeding eight figures.
- Agencies:Multi-client management tools and consolidated billing. Holding companies operating across London, Paris, and Frankfurt require cross-border campaign orchestration capabilities.
- Medium Enterprises:Self-serve platforms with managed service overlays.
- Small Enterprises:Automated campaign builders with simplified targeting.
Large corporations command the established base. The steepest expansion runs through agencies.
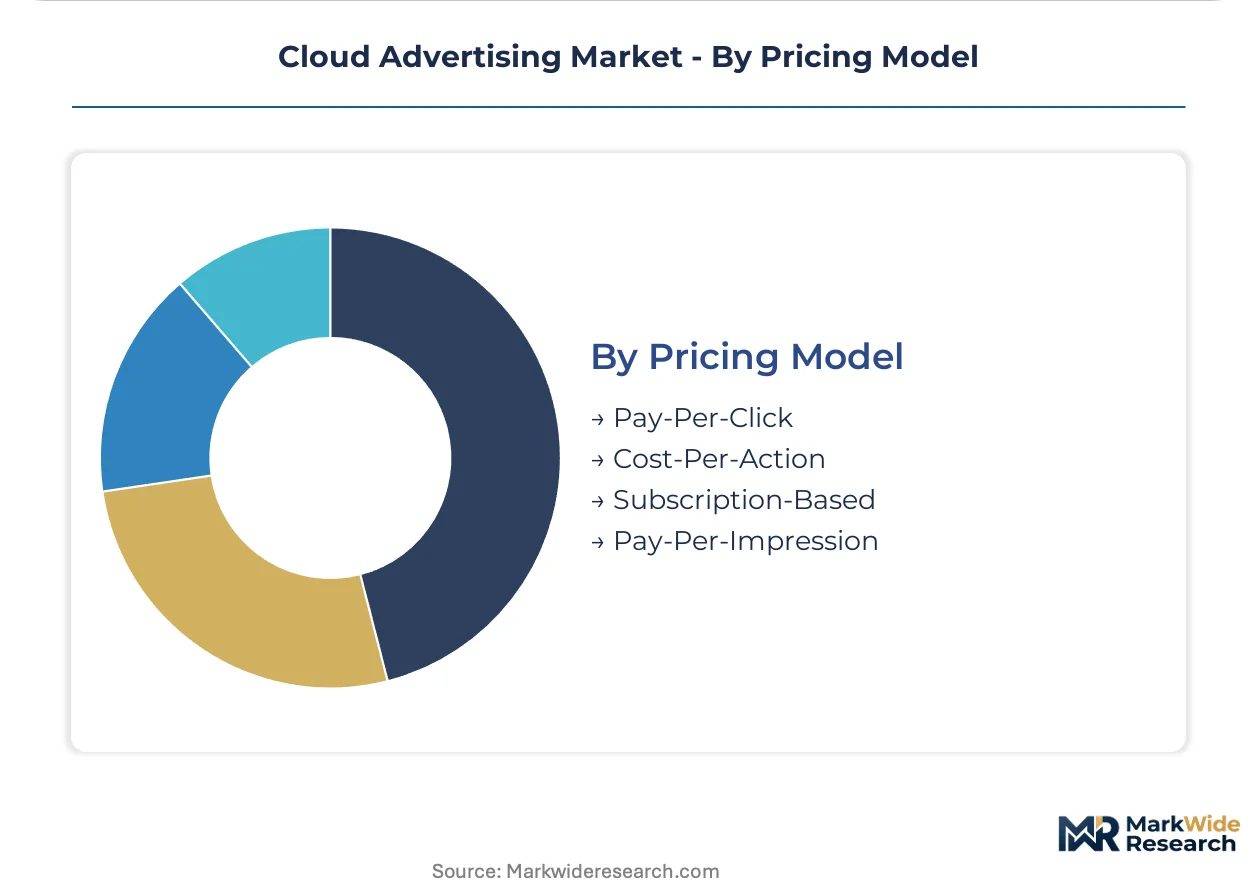
Pricing Model:
Risk allocation between impression delivery and outcome realization shapes advertiser-platform relationships.
- Pay-Per-Click:Billing triggers on verified engagement events, transferring performance risk to the platform. Search and social auctions operate predominantly on this model.
- Cost-Per-Action:Fees settle on attributable conversions—purchases, sign-ups, or qualified leads. Retail media networks and performance agencies align incentives with closed-loop measurement.
- Pay-Per-Impression:Traditional CPM billing for brand awareness campaigns.
- Subscription-Based:Fixed recurring fees for platform access and tooling.
Pay-per-click commands the established base. The steepest expansion runs through cost-per-action structures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The MAREA cable system landing at Virginia Beach anchors transatlantic data capacity for real-time bidding infrastructure. Subsea fiber routes from this hub distribute auction traffic to European exchanges with sub-50-millisecond latency. This physical layer concentration shapes where cloud advertising compute clusters deploy.
United States
Hyperscaler data centers in Northern Virginia, Seattle, and New York host the majority of North American programmatic trading volume. FCC guidelines on consumer privacy require consent management platforms for cross-state campaigns. AWS operates adjacent facilities in Loudoun County to minimize round-trip latency for auction participation.
Germany
Frankfurt's DE-CIX internet exchange anchors continental European traffic exchange for demand-side platforms. GDPR consent frameworks mandate granular opt-in mechanisms for behavioral targeting. Media agencies in Berlin and Munich maintain hybrid cloud configurations to isolate sensitive consumer data while bursting auction logic to public capacity.
United Kingdom
London's Docklands subsea cable landing stations connect transatlantic and transpacific routes for global ad exchange connectivity. The UK Information Commissioner's Office enforces GDPR-aligned consent standards post-Brexit. Programmatic trading desks cluster in the City and Shoreditch to access low-latency connectivity to European and North American markets.
Japan
Tokyo's Otemachi financial district hosts dense fiber interconnects for real-time bidding infrastructure serving East Asian markets. METI guidelines on data localization influence where consumer profiles reside for domestic campaigns. Yahoo Japan and domestic ad-tech operators maintain private cloud nodes in Kanto to satisfy sovereignty requirements.
India
Mumbai's cable landing stations at Versova and Mahim distribute subsea capacity across South Asian markets. TRAI regulations on data protection and content moderation shape platform compliance architecture. Bengaluru's technology corridor hosts engineering centers for global platforms adapting auction systems to local latency and regulatory conditions.
Cloud Advertising Market Vendor Landscape
On the supply side, the industry is consolidating around vertically integrated technology stacks with independent intermediaries occupying specialized niches. Hyperscale cloud providers anchor infrastructure layers while specialized platforms compete on algorithmic optimization and data independence. Three archetypes dominate: walled-garden operators controlling buy-side and sell-side technology, independent demand-side platforms emphasizing neutrality, and enterprise software vendors integrating advertising modules into broader marketing clouds. Competitive moves center on first-party data infrastructure acquisition and privacy-enhancing technology development.
Among hyperscale infrastructure operators, Amazon Web Services and Google LLC exemplify the vertically integrated archetype, anchoring auction compute while operating adjacent advertising businesses. The Trade Desk occupies the independent platform position, representing demand-side specialization without media ownership conflicts. Adobe Inc. and Salesforce Inc. sit within the enterprise marketing cloud tier, integrating advertising workflows with customer data management and creative production tools.
| Leading Market Players |
|---|
| Adobe Inc. |
| Salesforce Inc. |
| Amazon Web Services Inc. |
| Meta Platforms Inc. |
| The Trade Desk Inc. |
| Google LLC |
| Oracle Corporation |
| IBM Corporation |
| Microsoft Corporation |
| Others |
Supply Flow & Price Mechanics
Regulatory chokepoint exposure across EU Digital Services Act compliance and GDPR consent enforcement determines both auction technology tier spreads and cloud infrastructure deployment patterns. Advertisers face divergent cost structures based on whether their data pipelines route through Northern Virginia hyperscaler nodes or hybrid configurations isolating European consumer profiles.
Pricing Analysis
Volume-discount tiering structures separate Fortune 500 advertisers negotiating eight-figure annual commitments from mid-market buyers on self-serve platforms. Price differentiation hinges on latency guarantees and first-party data clean room access. Cost compression in the mid-market tier is intensifying because AWS, Google Cloud, and Microsoft Azure compete on auction compute unit pricing. Agencies demonstrate highest price sensitivity due to margin pressure from client procurement consolidation, while large corporations prioritize performance SLAs over unit cost.
Supply Chain Analysis
Tariff exposure between United States and European Union data routing dominates supply chain risk assessment for cross-border campaign infrastructure. Compute capacity concentrates in Northern Virginia, Seattle, and Frankfurt DE-CIX nodes. Raw material dependencies include subsea fiber cable capacity, hyperscaler GPU allocation, and consent management platform licensing. Single-source vulnerability exists for transatlantic latency optimization through the MAREA cable system. Distribution runs through programmatic trading desks and agency holding companies to end advertisers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cloud advertising operations demand fluency at the intersection of programmatic auction mechanics and data engineering pipelines. Talent scarcity at this intersection constrains expansion timelines for buyers and sellers alike.
For Market Incumbents: Harden first-party data infrastructure against regulatory fragmentation by isolating EU traffic stacks to satisfy GDPR consent mandates without degrading North American auction performance. Acquire privacy-enhancing technology capabilities—differential privacy and secure multi-party computation—to defend margin position as third-party cookie deprecation accelerates. Channel control through direct retailer media network partnerships offers defensive moats against independent DSP commoditization.
For New Entrants and Emerging Players: Build out specialized audio and podcast programmatic capabilities where dynamic ad insertion technology remains underdeployed relative to video and display saturation. Connected television migration presents white-space opportunity for yield optimization tools serving broadcast publishers transitioning inventory to programmatic pipes. Go-to-market positioning should emphasize closed-loop attribution for retail media networks where CPG brands redirect search budgets.
For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors platforms with independent demand-side specialization and clean room technology assets. Long-term viability over the coming decade hinges on first-party data infrastructure ownership rather than intermediary auction access. Acquisition target archetypes include privacy-enhancing technology developers and retail media network operators. The signal to watch is antitrust enforcement action against vertically integrated walled gardens reshaping platform pricing and data portability terms.
| Strategic Initiative | Industry Significance |
|---|---|
| Privacy-Enhancing Technology Acquisition | Clean room and differential privacy capabilities satisfy GDPR consent mandates without degrading targeting precision. |
| Retail Media Network Partnership | First-party purchase data from grocery and electronics retailers enables closed-loop attribution for CPG advertisers. |
| Hybrid Cloud Infrastructure Deployment | Split workloads isolate sensitive consumer data on private nodes while bursting auction logic to public capacity. |
| Audio Programmatic Capability Buildout | Dynamic ad insertion unlocks undermonetized streaming music and podcast inventory for addressable campaigns. |
| Outcome-Based Compensation Structure | Fee alignment with attributable sales displaces traditional CPM billing in measurable verticals like financial services. |
Methodological Framework
Cross-validation between demand-side platform operator disclosures and hyperscaler infrastructure investment reports anchors the qualitative findings. Primary interviews with programmatic trading desk directors, agency holding company procurement leads, cloud customer engineers, and regulatory compliance officers combined with secondary validation against SEC filings, hyperscaler capex disclosures, and EU regulatory filings. Bottom-up triangulation across service type, deployment model, and end user segments reconciles with top-down market sizing.
Calibration against historical auction volume growth rates and infrastructure deployment patterns shapes the analytical framework across the projection horizon. Segmentation dimensions modeled include service type, deployment architecture, end user scale, and pricing model risk allocation. CAGRs derive from elasticity analysis of media budget migration to cloud-based channels and latency-driven compute demand. Industry-specific forecast inputs incorporate connected television inventory migration velocity and first-party data infrastructure investment cycles.
The forecast holds incumbent behavior within observed patterns; aggressive moves by hyperscalers into adjacent buy-side technology or regulatory enforcement accelerating data portability mandates would shift outcomes. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
Military Sensors Software Market
Others
United States Indoor LBS Market
Others
Global Magnetic Flow Meters Market
Others
High-Performance Films Market
Others
South America Halal Food and Beverages Market
Others
High Voltage Measuring Equipment Market
Others
Global B2B Enterprise and Industrial Wearables Market
Others
Dandelion Market
Others
Textile Composites Market
Others
Air Separation Module Kit Market
Others
Prunes Market
Others
Water and Waste Water Treatment Chemicals Market
Others
Italy Smart Home Market
Others
North America Industrial Wearable Devices Market
Others
Medium-Voltage Switchgear Market
Others
Global Car Wax Market