
 Dandelion Market | 2026-2036
Dandelion Market Size, Share, and Industry Trends Forecast 2026-2036
Dandelion Market Analysis
Multi-source botanical sourcing is expanding across the dandelion supply chain as extractors diversify away from single-origin dependencies. Traditional Medicinals leverages long-term grower contracts across multiple temperate zones to secure raw material continuity. Starwest Botanicals sustains organic certification density that anchors its wholesale position to formulators. Nature's Way Products competes through vertical integration into capsule manufacturing, controlling quality from harvest to finished goods.
Dandelion comprises the perennial herb Taraxacum officinale, whose roots contain inulin levels reaching 40% dry weight and leaves deliver vitamins A, C, and K alongside potassium and beta-carotene; industrial processors extract these actives through aqueous or ethanol methods for nutraceutical and functional food applications. Medicinal extracts lead product type revenue pools due to standardized polyphenol content commanding formulation premiums, while herbal supplements represent the fastest-growing segment as direct-to-consumer brands reduce traditional retail friction. Distribution through health stores still occupies the largest channel share, though online retail is displacing regional specialty shops as fulfillment infrastructure matures.
The FDA maintains dietary supplement labeling requirements under DSHEA that constrain structure-function claims for dandelion products entering US commerce, while the EU's EFSA evaluates novel food safety dossiers before permitting expanded ingredient applications across member states. Organic certifiers including USDA and EU regulatory bodies impose residue limits that filter non-compliant harvests from premium supply tiers. Stakeholders must monitor evolving botanical drug monograph developments that could either restrict or elevate dandelion's therapeutic positioning in regulated channels.
Market Dynamics
Herbal supplement manufacturers are consolidating procurement contracts around certified organic dandelion root as EFSA novel food dossier backlogs create approval bottlenecks for competing botanicals. This sourcing concentration is reshaping competitive access to premium raw material tiers.
Growth Catalysts
- Digestive wellness formulations:Formulators are expanding dandelion root inulin content in prebiotic blends as gut microbiome science validates traditional applications. German health food retailers report sustained offtake velocity for certified organic SKUs.
- EU Organic Regulation 2018/848:Stricter residue limits and traceability mandates are filtering non-compliant harvests from premium supply tiers, elevating contract values for certified growers across temperate cultivation zones.
- Ethanol extraction methods:Industrial processors are deploying advanced solvent recovery systems that improve polyphenol yield rates while reducing waste streams, lowering unit costs for standardized extracts.
Market Restraints
- Raw material seasonality:Dandelion root harvest windows concentrate in late autumn across northern temperate zones, creating annual supply squeezes that elevate spot market pricing for extractors without forward contracts.
- Substitution by artichoke inulin:Functional food formulators are pivoting toward artichoke-derived prebiotics where supply continuity exceeds dandelion's agricultural volatility, compressing addressable volume in mass-market channels.
- DSHEA claim constraints:The FDA's structure-function claim limitations prevent dandelion products from referencing specific therapeutic outcomes, forcing reliance on consumer education and traditional use positioning.
Strategic Opportunities
- Direct-to-consumer herbal supplements:Subscription wellness platforms are bypassing health store intermediaries, capturing margin pools previously allocated to retail distributors and enabling personalized dosing formats.
- South Korean functional food approval:MFDS regulatory pathways for novel botanical ingredients remain less congested than EFSA queues, offering first-mover positioning for standardized extract dossiers.
- Capsule manufacturing backward integration:Extractors with captive encapsulation capacity are capturing value-add stages previously outsourced to contract manufacturers, tightening quality control from harvest to finished goods.
Industry Challenges
- Phytochemical standardization expertise:Analytical chemists capable of validating polyphenol and inulin content consistency across harvest batches command premium compensation, constraining mid-tier processor expansion.
- Organic certification timeline compression:USDA and EU organic certifier field inspection backlogs extend approval cycles by 8-14 months, delaying new grower onboarding and contract fulfillment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Dandelion Market |
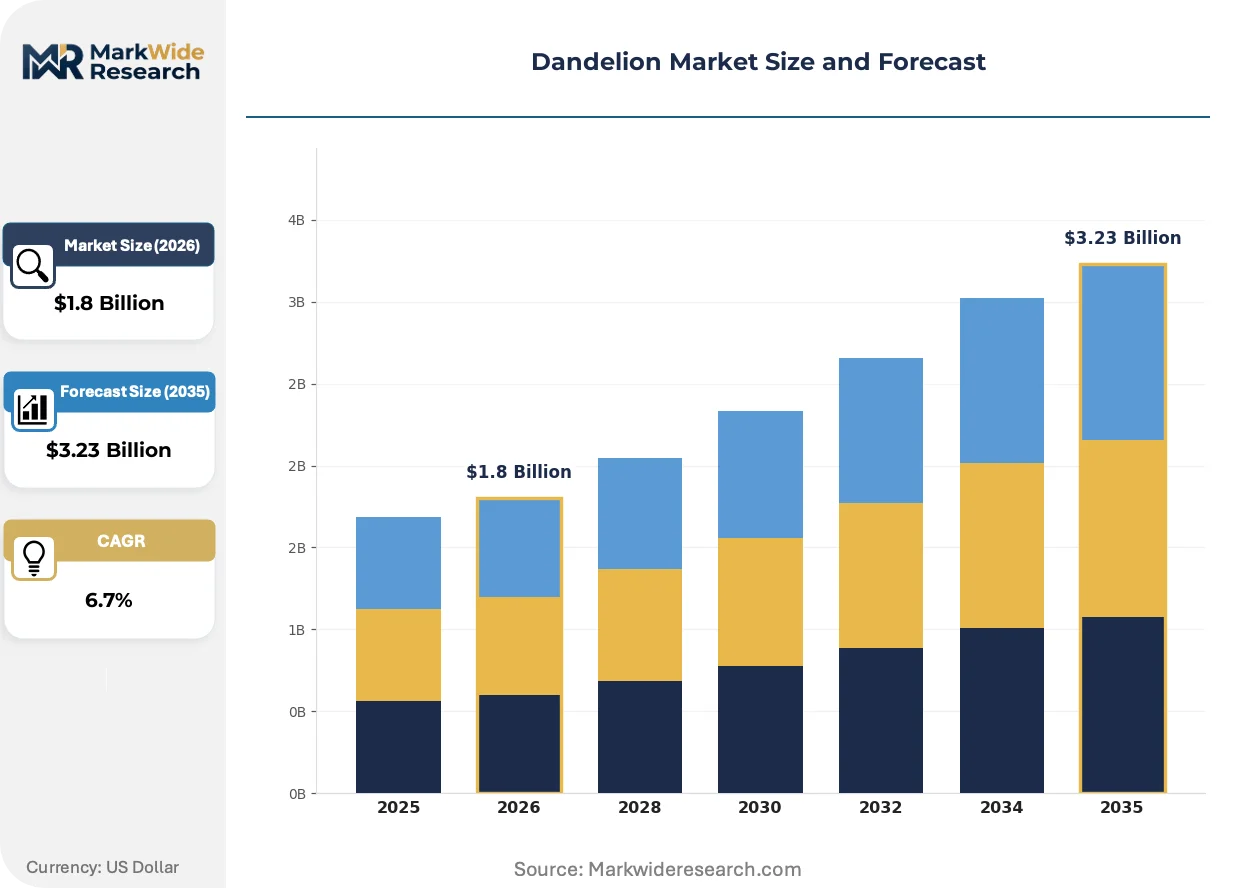
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Edible Dandelion, Medicinal Extract, Herbal Supplements, Dandelion Tea End User: Health Enthusiasts, Herbalists, Food Manufacturers, Wellness Centers Distribution Channel: Online Retail, Health Stores, Farmers Markets, Specialty Shops Application: Nutrition, Beauty Products, Traditional Medicine, Culinary Uses |
| Companies Covered | Traditional Medicinals, Inc., Starwest Botanicals, Inc., Nature’s Way Products, LLC, Bio-Botanica Inc., HawaiiPharm LLC, Gaia Herbs, LLC, A.Vogel, Herb Pharm, Mountain Rose Herbs, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Dandelion Market Emerging Trajectories
Processing automation and regulatory data requirements are converging to reshape how dandelion extracts move from field to formulation, with quality verification replacing origin storytelling as the primary competitive signal.
Supercritical CO2 extraction systems are automating the separation of dandelion root actives with precision that aqueous methods cannot replicate. Mid-scale processors in Germany and Poland are adopting these units to meet EFSA novel food dossier requirements for contaminant-free characterization. This automation is compressing the analytical validation timeline from harvest to commercial release.
EFSA's evolving botanical safety assessment framework is requiring comprehensive toxicological data packages for novel food approvals. European extractors are investing in in-house toxicology screening to preempt regulatory objections during dossier review. Medicinal extract segments face the steepest compliance burden as polyphenol standardization claims trigger enhanced scrutiny.
Health store buyers are consolidating supplier relationships around vertically integrated processors with captive organic certification. Regional specialty shops that previously sourced through wholesale distributors are being displaced by direct procurement arrangements that guarantee batch-level traceability. This channel consolidation is most visible in Germany's traditional medicine retail network.
Dandelion Market Segmentation
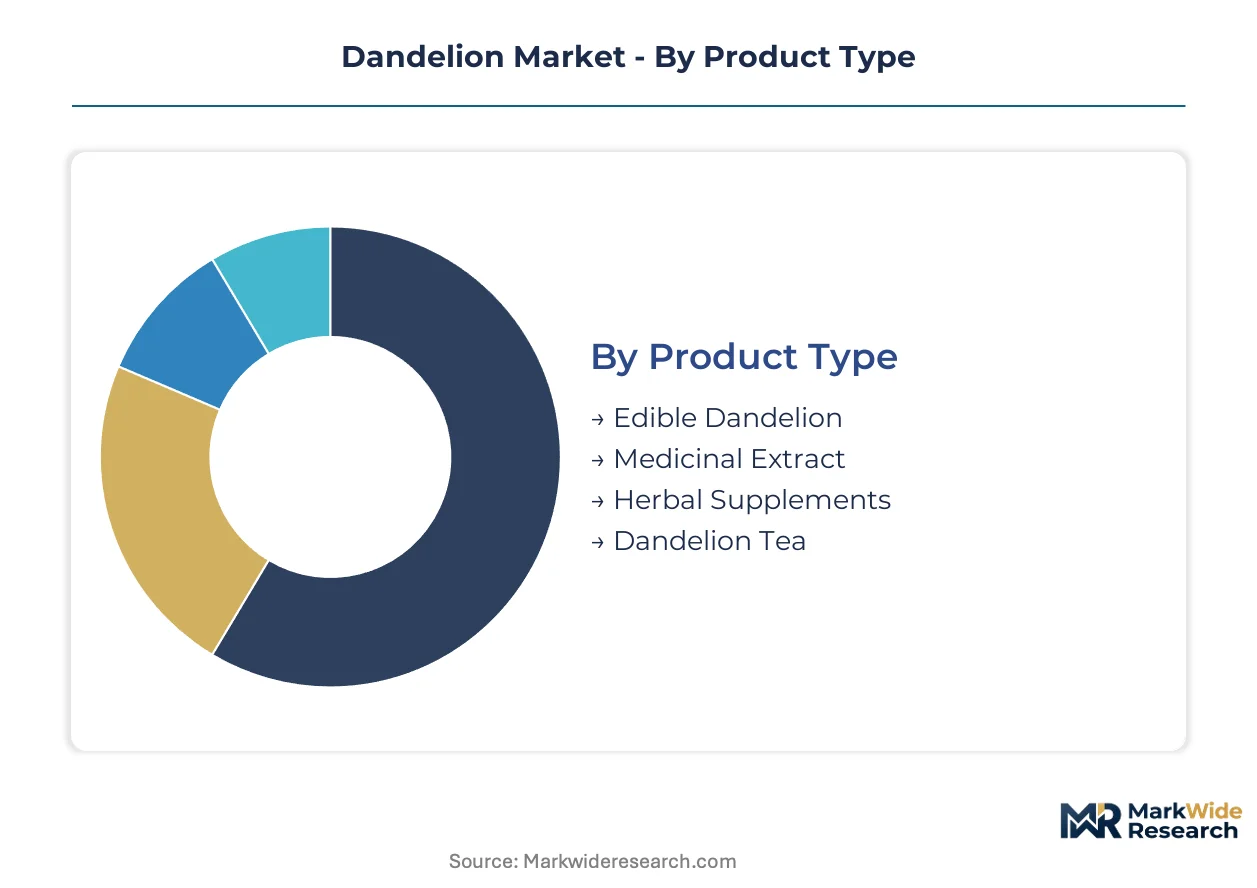
Dandelion market segmentation reveals divergent value capture between commodity-grade edible products and standardized therapeutic extracts. Procurement patterns differ sharply across these tiers, with extractors commanding formulation premiums while fresh product vendors compete on harvest logistics and organic certification density.
Product Type:
Integration depth separates standalone consumables from embedded functional ingredients that enter multi-component formulations.
- Medicinal Extract:Standardized polyphenol and inulin concentrates derived through aqueous or ethanol extraction methods. German formulators dominate procurement for digestive wellness applications, paying premiums for EFSA-compliant contaminant profiles.
- Herbal Supplements:Capsule and tablet formats delivering measured dandelion root or leaf actives. Direct-to-consumer subscription platforms in South Korea and Germany are displacing traditional health store distribution, capturing margin pools through personalized dosing regimens.
- Dandelion Tea:Dried leaf or root infusions positioned for daily wellness routines. USDA organic certification anchors pricing power in North American natural product channels.
- Edible Dandelion:Fresh greens and flowers for culinary incorporation. Farmers markets and restaurant supply chains concentrate demand in France and Italy, where seasonal harvest windows constrain year-round availability.
Volume placements concentrate in Medicinal Extract; the faster expansion belongs to Herbal Supplements.
End User:
Cost tier stratification distinguishes premium therapeutic seekers from commodity-scale food manufacturing buyers.
- Herbalists:Practitioners specifying certified organic roots for custom tincture preparations. Traditional medicine networks in Germany sustain contract demand for traceable harvest batches with validated phytochemical profiles.
- Health Enthusiasts:Self-directed consumers purchasing finished supplements through online channels. Subscription retention rates exceed single-purchase conversion, driving brand investment in personalized wellness platforms.
- Food Manufacturers:Industrial buyers incorporating dandelion leaf into functional food formulations. Artichoke inulin substitution threatens volume retention where supply continuity outweighs botanical provenance.
- Wellness Centers:Spa and retreat operators sourcing bulk dried material for on-site preparation. Organic certification mandates filter supplier eligibility for premium service positioning.
Revenue concentration sits with Herbalists; Health Enthusiasts are climbing the fastest as direct channels mature.
Distribution Channel:
Geographic reach and fulfillment infrastructure determine competitive access across fragmented retail architectures.
- Health Stores:Established natural product retailers with trained staff and certified organic inventory requirements. Germany's traditional medicine retail network maintains the densest point-of-sale presence for dandelion therapeutics.
- Online Retail:E-commerce platforms and subscription services bypassing physical intermediaries. Fulfillment infrastructure investments in Poland and the Czech Republic are compressing delivery timelines for Central European consumers.
- Specialty Shops:Regional botanical and apothecary retailers with curated supplier relationships. Batch-level traceability requirements are consolidating procurement around vertically integrated processors.
- Farmers Markets:Direct producer-to-consumer sales of fresh and dried material. Seasonal concentration in late autumn harvest windows limits year-round revenue stability.
Transaction volume still flows through Health Stores; Online Retail is gaining share fastest as logistics networks deepen.
Application:
Margin structure differentiates pharmaceutical-adjacent therapeutic positioning from commodity nutrition and cosmetic incorporation.
- Traditional Medicine:Formulations referencing historical use patterns for digestive and hepatic support. EFSA novel food dossier requirements constrain expanded health claims in European commerce.
- Nutrition:Prebiotic inulin delivery for gut microbiome modulation. Functional food manufacturers in South Korea are pursuing MFDS approval pathways less congested than EFSA queues.
- Beauty Products:Topical applications leveraging antioxidant and anti-inflammatory properties. Clean beauty certification standards in France and California filter ingredient sourcing for premium cosmetic lines.
- Culinary Uses:Fresh and preserved preparations for gastronomic incorporation. Italian and French restaurant supply chains sustain seasonal procurement despite harvest window constraints.
Revenue pools concentrate in Traditional Medicine; Nutrition applications show the steepest expansion trajectory as microbiome science advances.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Temperate cultivation zones in Germany, Poland, and the Czech Republic anchor raw material supply for European extractors. North American demand concentrates around USDA-certified organic channels, while South Korean regulators open faster approval pathways for functional food entrants.
Germany
Traditional medicine retail networks sustain contract demand for certified organic dandelion root with validated phytochemical profiles. EFSA novel food dossier requirements constrain expanded health claims, forcing reliance on historical use positioning. Bavarian processing clusters deploy supercritical CO2 extraction systems to meet contaminant-free characterization standards for medicinal extract exports.
United States
Health enthusiasts drive direct-to-consumer subscription velocity for herbal supplement formats. FDA structure-function claim limitations under DSHEA prevent therapeutic outcome references, compelling consumer education investments. Pacific Northwest cultivation cooperatives maintain organic certification density that anchors wholesale supply to national formulators.
South Korea
Functional food manufacturers pursue gut microbiome positioning for prebiotic inulin applications. MFDS regulatory pathways for novel botanical ingredients remain less congested than EFSA queues, attracting standardized extract dossier submissions. Seoul-based wellness platforms are displacing traditional retail intermediaries through personalized dosing subscription models.
Poland
Mid-scale processors adopt automated solvent recovery systems to improve polyphenol yield rates while reducing waste streams. EU Organic Regulation 2018/848 traceability mandates filter non-compliant harvests from premium supply tiers. Warsaw logistics hubs compress delivery timelines for Central European online retail fulfillment.
France
Clean beauty certification standards filter ingredient sourcing for premium cosmetic lines leveraging antioxidant applications. ANSM oversight of botanical drug monograph developments shapes therapeutic positioning in regulated channels. Provence seasonal harvest windows constrain year-round availability for fresh edible product vendors serving restaurant supply chains.
Dandelion Market Vendor Landscape
Global majors compete with regional champions across certification density and captive cultivation capacity. Market structure tilts toward vertically integrated processors with in-house organic certification and backward integration into capsule manufacturing. Three archetypes dominate: long-term contract holders securing multi-zone raw material continuity, wholesale-certified suppliers anchoring formulator relationships, and direct-to-consumer brands capturing subscription margin pools. Competitive moves concentrate on geographic diversification of grower contracts and toxicology screening investments to preempt regulatory objections.
Among North American botanical specialists, Traditional Medicinals, Inc., Starwest Botanicals, Inc., and Nature's Way Products, LLC exemplify distinct strategic positions. Traditional Medicinals represents the contract-holding archetype through multi-temperate-zone grower relationships. Starwest Botanicals occupies wholesale-certified supplier positioning with organic certification density anchoring formulator access. Nature's Way Products sits within backward-integrated manufacturing, controlling quality from harvest through finished goods production.
| Leading Market Players |
|---|
| Traditional Medicinals, Inc. |
| Starwest Botanicals, Inc. |
| Nature's Way Products, LLC |
| Bio-Botanica Inc. |
| HawaiiPharm LLC |
| Gaia Herbs, LLC |
| A.Vogel |
| Herb Pharm |
| Mountain Rose Herbs |
| Others |
Supply Flow & Price Mechanics
Certified organic dandelion root spot pricing in Bavarian auction markets cascades through three distinct value tiers as harvest seasonality and EFSA compliance costs compound at each processing stage. German extractors with captive organic certification capture margin premiums that commodity-grade suppliers cannot access, while forward-contracted volume locks in price stability for integrated formulators.
Pricing Analysis
Batch-level traceability guarantees anchor the premium tier, with EFSA-compliant contaminant profiles and validated polyphenol standardization bundled into contract values. Mid-tier pricing rests on USDA organic certification without novel food dossier completion, serving North American health store channels. Economy-tier spot market transactions serve culinary and tea applications where phytochemical validation is unbundled. Price differentiation intensifies as EU Organic Regulation 2018/848 residue limits filter non-compliant harvests from premium supply tiers. Cost compression runs through mid-tier processors lacking in-house toxicology screening capacity. Food manufacturers exhibit highest price sensitivity, pivoting toward artichoke inulin where supply continuity outweighs botanical provenance premiums.
Supply Chain Analysis
Direct-to-formulator channels handle standardized extract demand from German and South Korean digestive wellness manufacturers, bypassing wholesale intermediaries. Raw material supply concentrates in Germany, Poland, and the Czech Republic, where temperate cultivation zones anchor organic certification density. Processing depends on inulin-rich rootstock and ethanol solvent systems, with supercritical CO2 extraction equipment constituting a capital-intensive bottleneck. Single-source vulnerability persists for analytical chemists capable of validating polyphenol consistency across harvest batches. Distribution runs through vertically integrated processors with captive encapsulation capacity, displacing regional specialty shops that previously sourced through wholesale distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Organic certification inspection backlogs stretching 8-14 months constrain new grower onboarding, propping contract values for incumbent certified suppliers across temperate cultivation zones.
For Market Incumbents: Anticipate artichoke inulin substitution threats in mass-market functional food channels by deepening backward integration into capsule manufacturing and toxicology screening capacity. Secure multi-zone grower contracts across Poland and the Czech Republic to dilute Bavarian harvest concentration risk. Prioritize EFSA novel food dossier completion ahead of competing botanicals to defend formulation access in European traditional medicine networks. For New Entrants and Emerging Players: Wellness centers and spa operators represent an underserved buyer archetype with organic certification mandates but fragmented supplier relationships. South Korean MFDS approval pathways offer faster market entry than EFSA queues for standardized extract entrants. Direct-to-consumer subscription platforms enable margin capture previously allocated to health store intermediaries, with personalized dosing formats differentiating against incumbent capsule suppliers. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-scale Polish processors with automated solvent recovery systems and pending EU organic certification. Long-term viability hinges on captive cultivation capacity and in-house analytical validation expertise rather than outsourced quality control. Watch EFSA botanical drug monograph developments as the inflection signal for therapeutic positioning expansion or restriction in regulated European channels.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Capsule Manufacturing | Captures value-add stages previously outsourced to contract manufacturers while tightening harvest-to-finished-goods quality control. |
| EFSA Novel Food Dossier Submission | Secures expanded ingredient applications across EU member states ahead of competing botanicals facing approval bottlenecks. |
| Multi-Zone Grower Contract Diversification | Reduces single-origin dependency as climate volatility concentrates in specific temperate cultivation windows. |
| Supercritical CO2 Extraction Deployment | Meets EFSA contaminant-free characterization requirements while automating polyphenol separation precision. |
| Direct-to-Consumer Subscription Launch | Bypasses health store intermediaries in Germany and South Korea to capture margin pools through personalized dosing retention. |
Methodological Framework
USDA organic certification databases, EFSA novel food submission records, and German health food retail audit data formed the secondary backbone for supply-side and regulatory validation. Primary interviews with herbal supplement formulators, organic certifier field inspectors, and extraction plant managers in Bavaria and Poland combined with secondary source triangulation to ground procurement pattern assessments. Bottom-up volume estimates from cultivation zone surveys and top-down value reconstructions from channel pricing analysis were cross-validated for consistency.
Historical trendline analysis of certified organic dandelion root contract values and extract export volumes established baseline growth trajectories across the projection horizon. The analytical framework modeled segmentation across product type, end user archetype, distribution channel, and application area, with regional regulatory cluster as an additional dimension. CAGRs were derived from curve-fitting approaches applied to validated historical series, incorporating gut microbiome science advancement rates and MFDS approval pathway congestion as botanical market inputs.
Revisions become necessary when EFSA botanical safety assessment frameworks tighten, EU organic certifier inspection backlogs extend, or artichoke inulin substitution accelerates in functional food manufacturing. Forecasts reflect documented assumptions regarding cultivation yield stability and regulatory approval timelines. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
Spinner Flask Market
Others
Paper Shredder Market
Others
Heat Treatment Furnace Market
Others
Global Military Lighting Market
Others
North America Enterprise Video Market
Others
Global Extruded Plastics Market
Others
North America Machine Vision Systems Market
Others
Global Bio-Based Chemicals Market
Others
India 3D Printing Construction Market
Others
Europe Transportation Management Systems Market
Others
Africa Cotton Market
Others
Telecom Transformers Market
Others
Edible Insects for Animal Feed Market
Others
Kuwait Retail Market
Others
Tunnel Lighting Market
Others
Fabric Based Computing Market