
 UK Aluminum Door and Window Market | 2026-2036
UK Aluminum Door and Window Market Size, Share, and Industry Trends Forecast 2026-2036
UK Aluminum Door and Window Market Insights
Aftermarket service revenue is fragmenting across installation networks, maintenance contracts, and warranty extensions as fabricators seek recurring income beyond original equipment sales. Schüco leverages its technical specification support to anchor premium commercial projects across London's skyline developments. Reynaers Aluminium competes through modular system architectures that simplify contractor installation workflows. Senior Architectural Systems dominates trade supply into social housing retrofit programmes, where standardization reduces procurement complexity.
UK aluminum doors and windows are thermally broken extruded aluminum frame assemblies, typically incorporating polyamide strips between inner and outer aluminum profiles to achieve U-values below 1.4 W/m²K, designed for structural glazing, weather resistance, and acoustic performance in building envelopes. Bi-fold doors lead residential margin pools due to premium positioning and complex hardware requirements, while tilt and turn windows sustain volume in multi-storey apartment specifications where inward opening meets safety codes. Commercial facilities anchor demand for curtain wall-adjacent door systems, with property developers driving specification consolidation through framework agreements.
Building Regulations Part L and Approved Document Q shape product compliance thresholds for thermal performance and security, while British Standards Institution kitemark certification governs weather tightness and structural load testing for market access. The UK's Net Zero Strategy and Future Homes Standard are forcing material transitions toward lower-embodied-carbon aluminum sourcing and improved glazing specifications. Stakeholders must monitor how upcoming changes to Part F ventilation requirements interact with airtight aluminum frames to avoid condensation liability in new-build warranties.
Market Dynamics
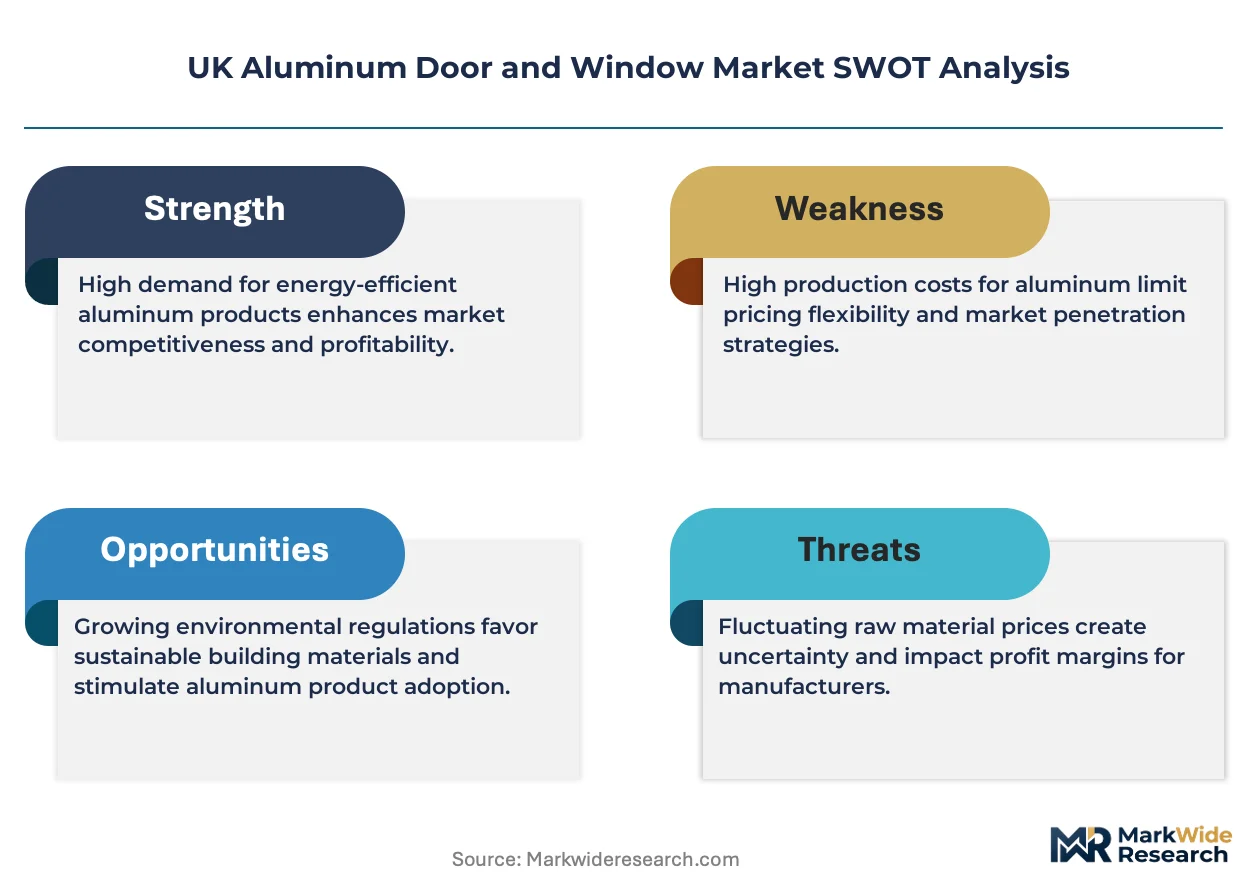
Building Regulations Part L updates on fabric energy efficiency are compressing specification cycles across the UK aluminum door and window market, forcing rapid transitions from legacy timber and uPVC systems toward thermally broken aluminum profiles that meet stricter U-value thresholds.
Growth Catalysts
- Residential Retrofit Momentum:Homeowners across Greater London and the South East are replacing aging frames with high-performance aluminum systems to improve thermal efficiency and property values.
- Future Homes Standard:This regulatory mandate is accelerating material transitions toward lower-embodied-carbon aluminum sourcing and advanced glazing specifications in new-build developments.
- Conservation Area Planning:Planning constraints in heritage-sensitive boroughs favor slimline aluminum aesthetics, creating specification pull for premium profile systems.
Market Restraints
- Aluminum Input Cost Volatility:Primary aluminum pricing fluctuations on the London Metal Exchange compress fabricator margins and complicate project bidding.
- Supply Concentration Risk:Polyamide thermal break strip production concentrates among a limited supplier base, creating vulnerability in high-performance profile availability.
- Technical Limitation:Cold bridging risks in poorly installed thermally broken frames create condensation liability that dampens warranty confidence among risk-averse developers.
Strategic Opportunities
- Social Housing Retrofit Scale:Standardized procurement frameworks across UK local authorities create volume anchors for fabricators capable of meeting PAS 24 security certification.
- Bi-fold Door Premium Positioning:Complex hardware requirements and installation specialization sustain margin pools in residential extensions and garden room specifications.
- Aftermarket Service Unbundling:Maintenance contracts and warranty extensions represent recurring revenue streams beyond original equipment sales for installation networks.
Industry Challenges
- Certification Timeline Compression:British Standards Institution kitemark testing for weather tightness and structural load creates bottlenecks for new product launches.
- Installer Skill Scarcity:Proper thermal break installation and airtight sealing techniques require specialized training that outpaces current apprenticeship pipeline output.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | UK Aluminum Door and Window Market |
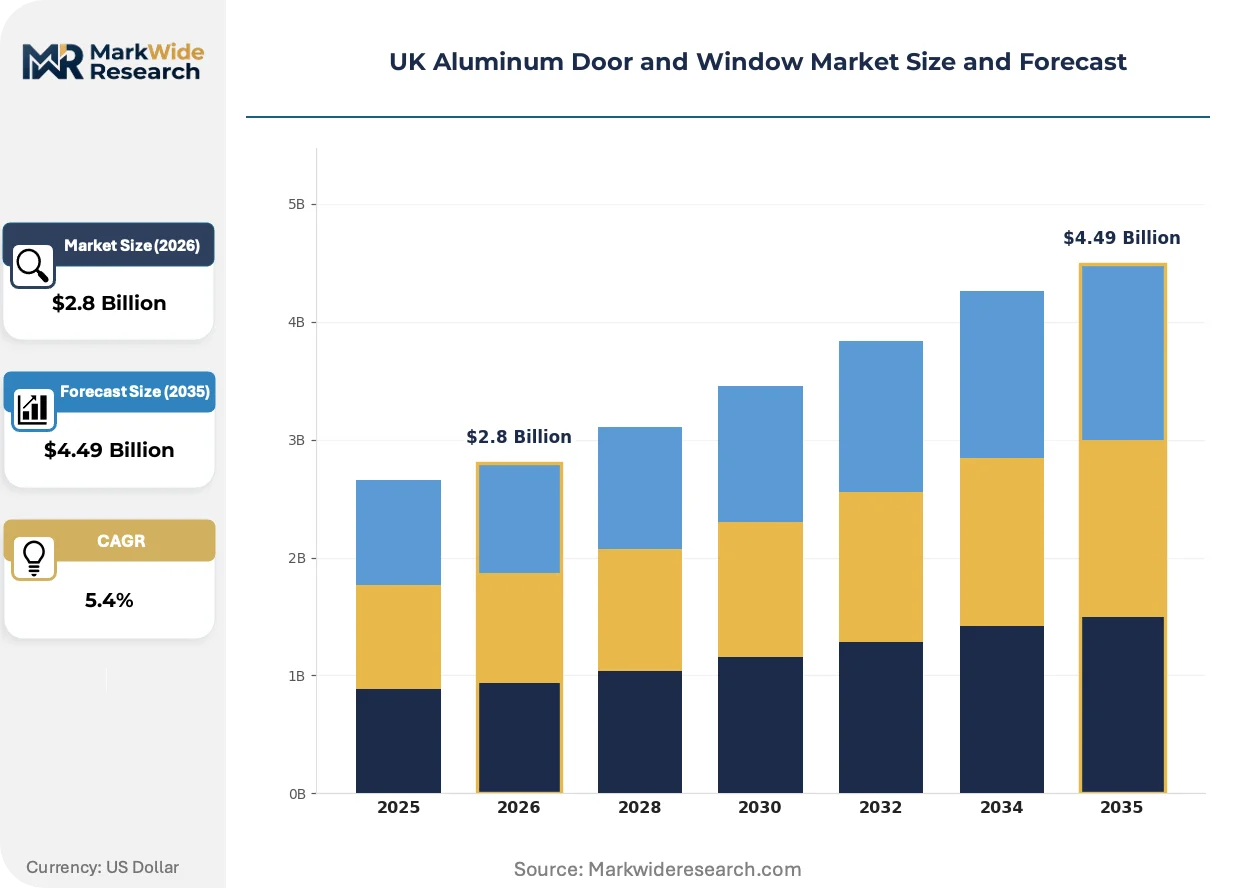
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.49 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Casement Windows, Sliding Doors, Bi-Fold Doors, Awning Windows, Tilt and Turn Windows Application: Residential Buildings, Commercial Facilities, Institutional Structures, Recreational Centers, Hospitality Venues Installation Type: New Construction, Renovation, Retrofit Projects, Replacement Installations, Modular Assembly Customer Type: Property Developers, Architectural Firms, Construction Contractors, Facility Managers, Homeowners |
| Companies Covered | Schüco, Reynaers Aluminium, Senior Architectural Systems, Anglian Home Improvements, Everest 2020 Ltd, SGM Windows, SOLIDOR, Britelite Windows, Kone plc, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
UK Aluminum Door and Window Market Trends and Innovations
Thermally efficient glazing technologies and modular system architectures are actively reshaping competitive positioning in the UK aluminum door and window market, compressing traditional supply relationships and enabling new specification pathways.
Triple-glazed units with warm-edge spacer technology are rendering obsolete conventional double-glazed specifications in high-end residential retrofits across Surrey and Buckinghamshire. Developers targeting Passivhaus certification are specifying these systems as standard, compressing the viable performance window for mid-tier glazing suppliers.
Building Regulations Part F ventilation requirements are interacting with airtight aluminum frame specifications to create condensation risk management obligations. Developers in Manchester and Birmingham are responding with integrated trickle-vent and mechanical ventilation with heat recovery combinations to maintain warranty compliance.
Specification consolidation through developer framework agreements is displacing traditional merchant-based procurement in multi-unit residential schemes. Housebuilders in the South East are centralizing aluminum system selection at group level, reducing trade counter influence and compressing regional fabricator autonomy.
UK Aluminum Door and Window Market Segmentation
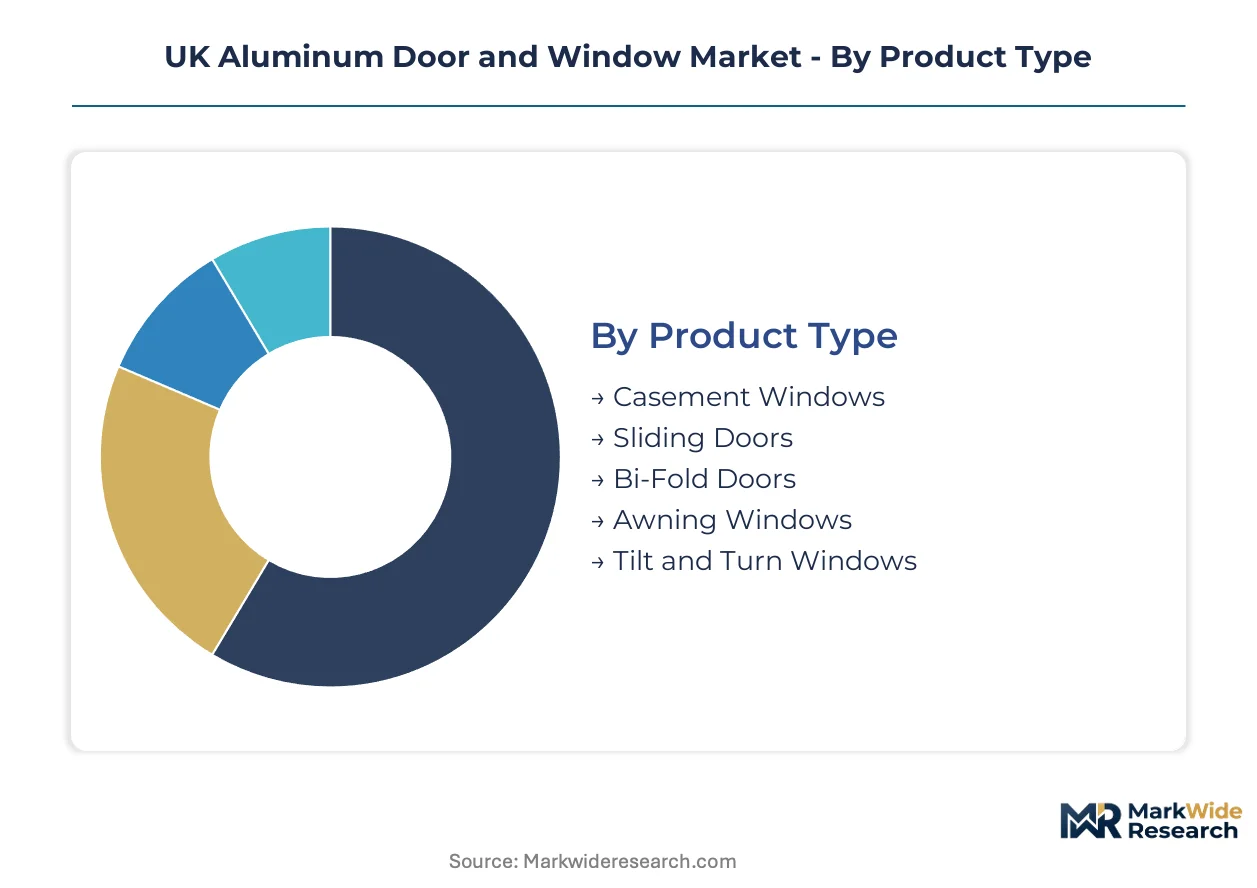
Segmentation in the UK aluminum door and window market reveals how specification authority flows through distinct procurement channels, each demanding differentiated technical support and warranty structures. Fabricators must align product portfolios with the decision-making logic of five customer types while navigating divergent performance requirements across residential, commercial, and institutional end-uses.
Product Type:
After-sales-service intensity varies sharply across product categories, with complex hardware systems requiring specialized maintenance networks that fabricators are only now building out.
- Bi-Fold Doors:Multi-panel track systems with precision-engineered roller mechanisms and low-threshold drainage solutions. Demand concentrates in Greater London residential extensions where planning constraints favor slimline aluminum aesthetics and garden room specifications drive premium positioning.
- Tilt and Turn Windows:Dual-action hardware enabling inward tilting for secure ventilation and full side-hung opening for cleaning access. Multi-storey apartment developments across Manchester and Birmingham specify these systems to meet Approved Document Q safety codes while satisfying Part F ventilation requirements.
- Casement Windows:Side-hung or top-hung single-action frames with compression seal technology.
- Sliding Doors:Inline or lift-and-slide track systems prioritizing uninterrupted sightlines.
- Awning Windows:Top-hung projection frames with rain-shedding geometry.
Bi-fold doors hold the largest share; momentum sits with tilt and turn configurations.
Application:
Cost tier differentiation separates specification pathways, with institutional procurement favoring lifecycle costing over upfront capital expenditure.
- Residential Buildings:Single-family homes and multi-unit schemes requiring thermal performance compliance with Part L fabric efficiency standards. Retrofit activity across the South East drives replacement of aging timber and uPVC frames with thermally broken aluminum systems.
- Commercial Facilities:Office developments and mixed-use schemes demanding curtain wall-adjacent door systems with acoustic performance certification. Property developers in London's skyline projects consolidate specifications through framework agreements that reduce regional fabricator autonomy.
- Institutional Structures:Schools, hospitals, and public buildings with extended warranty requirements.
- Recreational Centers:Sports facilities and community buildings with high-traffic durability specifications.
- Hospitality Venues:Hotels and restaurants prioritizing aesthetic differentiation and acoustic isolation.
Residential applications anchor volume; commercial facilities are expanding most quickly.
Installation Type:
Volume concentration tilts toward replacement activity as Building Regulations Part L updates compress specification cycles for existing building stock.
- Retrofit Projects:Whole-building envelope upgrades integrating aluminum systems with improved glazing specifications. Social housing programmes across UK local authorities create standardized procurement anchors for fabricators meeting PAS 24 security certification.
- Replacement Installations:Single-unit frame swaps responding to failure or efficiency improvement triggers. Homeowners in conservation-sensitive boroughs specify slimline profiles to satisfy planning constraints while upgrading thermal performance.
- New Construction:Ground-up developments with integrated aluminum specification from design stage.
- Renovation:Partial envelope upgrades with retention of existing structural elements.
- Modular Assembly:Offsite-manufactured building components with pre-installed fenestration.
Retrofit projects command the greatest share; replacement installations are gaining share fastest.
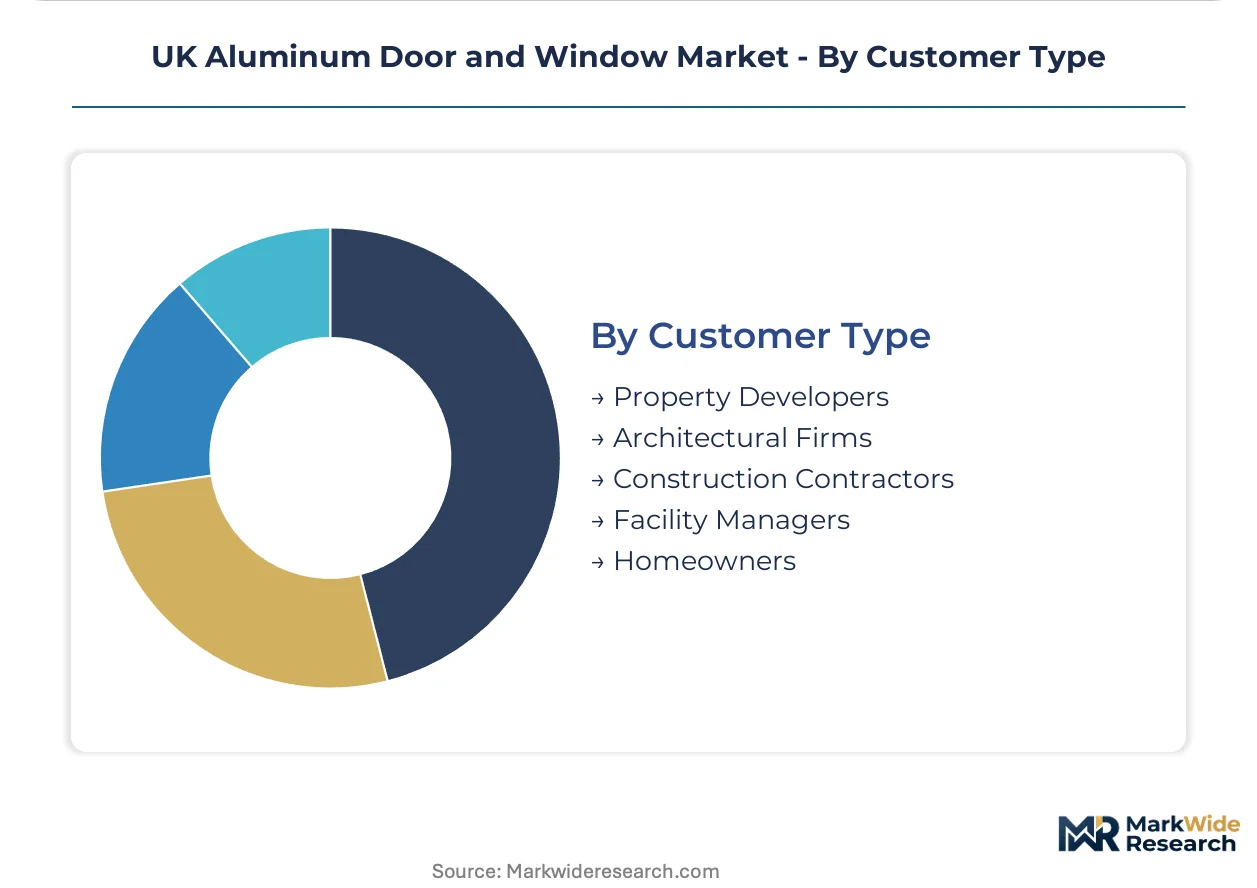
Customer Type:
Margin structure varies by decision-maker sophistication, with architectural firms extracting specification influence that compresses trade counter margins.
- Property Developers:Multi-unit scheme sponsors consolidating aluminum system selection at group level. South East housebuilders centralize procurement decisions to reduce supply chain complexity and secure volume pricing.
- Architectural Firms:Design practices specifying high-performance profiles for conservation-sensitive developments. Greater London practices leverage technical specification support from premium system suppliers to anchor commercial projects.
- Construction Contractors:Installation specialists prioritizing modular system architectures that simplify workflow efficiency.
- Facility Managers:Building operators seeking maintenance contract structures for lifecycle cost control.
- Homeowners:Individual purchasers responding to energy efficiency and property value improvement triggers.
Property developers hold the largest share; architectural firms show the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price sensitivity varies sharply across UK sub-regions. Homeowners in Greater London accept premium positioning for slimline aesthetics, while Midlands and Northern England buyers prioritize thermal performance per pound spent.
London and South East
Conservation area planning constraints drive specification toward premium thermally broken profiles. Building Regulations Part L updates compress replacement cycles for aging timber frames. Skyline developments in Canary Wharf and Nine Elms anchor commercial demand for curtain wall-adjacent systems.
Midlands
Social housing retrofit programmes across Birmingham and Coventry create standardized procurement volume. Local authorities prioritize PAS 24 security certification and lifecycle costing over upfront capital expenditure. Fabricators serving this channel emphasize modular installation workflows.
North England
Industrial conversion projects in Manchester and Leeds generate demand for acoustic performance certification. Approved Document Q safety codes tilt multi-storey apartment specifications toward tilt-and-turn configurations. Installer skill scarcity creates bottlenecks for airtight sealing compliance.
Scotland
Net Zero Strategy mandates accelerate transitions from uPVC toward lower-embodied-carbon aluminum sourcing. Edinburgh and Glasgow conservation-sensitive developments favor slimline profiles meeting heritage officer requirements. Future Homes Standard implementation runs ahead of English timelines.
Wales
Rural retrofit activity concentrates in Cardiff and Swansea commuter belts. Part F ventilation requirements interact with airtight frame specifications to create condensation risk management obligations. Welsh Government procurement frameworks favor local fabricator networks.
UK Aluminum Door and Window Market Competitive Landscape
Capability concentration sits with premium system suppliers; scale advantage sits with trade-focused fabricators. The vendor base organizes around three tiers: international system houses with technical specification support, mid-market fabricators serving standardized procurement, and installation networks unbundling aftermarket services. Strategic moves center on framework agreement consolidation and backward integration into thermal break supply.
Among premium-tier system suppliers, Schüco and Reynaers Aluminium occupy positions anchored by technical specification relationships with architectural practices. Senior Architectural Systems exemplifies the trade-supply archetype serving social housing retrofit volume. These three names represent distinct competitive vectors: specification influence, modular system architecture, and standardized procurement compliance.
| Leading Market Players |
|---|
| Schüco |
| Reynaers Aluminium |
| Senior Architectural Systems |
| Anglian Home Improvements |
| Everest 2020 Ltd |
| SGM Windows |
| SOLIDOR |
| Britelite Windows |
| Kone plc |
| Others |
Pricing and Supply Chain Analysis
Overcapacity in Midlands fabricator networks is compressing spot pricing for standard thermal break profiles while simultaneously forcing premium system suppliers toward extended payment terms to defend distributor relationships. This utilization asymmetry between trade-focused and specification-grade supply tiers is reshaping how procurement teams balance upfront capital outlay against lifecycle service bundling.
Pricing Analysis
Aftermarket service revenue tiers—spanning planned maintenance contracts, emergency repair callouts, and extended warranty buy-ups—now drive lifetime value realization for installation networks serving the residential retrofit channel. Pricing stratifies across premium architect-specified systems, standard PAS 24-certified trade supply, and economy direct-to-installer profiles. Cost compression in the standard tier is intensifying because polyamide thermal break strip availability fluctuates with European polymer feedstock markets. Social housing procurement teams exhibit highest price sensitivity, while conservation-area developers in Greater London accept substantial premiums for slimline aesthetics.
Supply Chain Analysis
Extended payment terms from 60 to 90 days are becoming standard for trade fabricators serving volume retrofit programmes, with supply-chain finance facilities increasingly bridging working capital gaps for mid-tier extruders. Primary aluminum smelting concentrates in Norway, Iceland, and the United Arab Emirates, while polyamide thermal break production draws from German and Belgian polymer specialists. Single-source vulnerability in high-performance thermal break strip supply creates bottlenecks during specification surges. Distribution runs through merchant trade counters, direct contractor relationships, and developer framework agreements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The UK aluminum door and window market is experiencing high-growth disruption as Future Homes Standard mandates force material transitions toward lower-embodied-carbon sourcing and compress specification cycles for legacy building stock.
For Market Incumbents: Pre-empt margin erosion in standard-grade trade supply by securing captive polyamide thermal break production capacity or exclusive offtake agreements with European polymer specialists. Anchor specification influence through Building Regulations Part L compliance tooling that simplifies U-value documentation for architectural practices facing compressed project timelines.
For New Entrants and Emerging Players: Establish a beachhead in modular offsite assembly partnerships where pre-installed fenestration creates specification stickiness with housebuilders centralizing procurement decisions. Target social housing retrofit frameworks in the Midlands and North England where standardized PAS 24 compliance reduces incumbent brand advantage. Lead with installation workflow efficiency rather than product differentiation.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among installation networks unbundling maintenance contracts and warranty extensions from original equipment sales. Five-to-ten-year viability hinges on regulatory compliance infrastructure rather than manufacturing scale alone. Target acquisition archetypes: regional fabricators with dormant PAS 24 certification capabilities awaiting volume activation. The signal to watch is local authority framework consolidation velocity as procurement centralization accelerates.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Thermal Break Supply | Captive polyamide strip production insulates margins from European polymer feedstock volatility. |
| PAS 24 Certification Investment | Security certification unlocks social housing framework access across Midlands and North England local authorities. |
| Aftermarket Service Unbundling | Maintenance contract structures convert one-time installation revenue into recurring lifecycle income streams. |
| Framework Agreement Consolidation | Developer-level procurement centralization reduces trade counter influence and secures multi-year volume commitments. |
| Low-Carbon Aluminum Sourcing Transition | Hydro-powered primary metal sourcing satisfies Future Homes Standard embodied carbon thresholds for new-build specifications. |
Research Methodology
A standing panel of fenestration system technical directors, social housing procurement leads, architectural specification managers, and merchant trade counter operators provided ongoing calibration across the research cycle. Primary interviews with these stakeholders combined with secondary validation from Building Regulations Part L compliance documentation, British Standards Institution kitemark certification records, and London Metal Exchange aluminum pricing data. Bottom-up volume estimates from fabricator capacity assessments triangulated against top-down construction output projections from UK housing starts and commercial development pipelines.
Scenario-bracketing around regulatory implementation timelines and aluminum price volatility bands anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include product type, application end-use, installation channel, and customer procurement authority. CAGRs were derived from installed base replacement cycles intersecting with new-build regulatory compliance deadlines. Forecast inputs incorporated thermal performance standard adoption curves and local authority retrofit programme commitment levels.
Sensitivities concentrate around Building Regulations Part F ventilation requirement interactions with airtight frame specifications, polyamide thermal break supply disruptions, and primary aluminum price volatility on the London Metal Exchange. Forecasts reflect assumptions about regulatory implementation pacing and material substitution elasticity. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building Materials
Concrete Admixtures Market
Building Materials
Africa Aluminum Door and Window Market
Building Materials
Low-E Construction Glass Market
Building Materials
United States White Cement Market
Building Materials
North America Architectural Coatings Market
Building Materials
Refractory Cement Market
Building Materials
Masonry Cement Market
Building Materials
Solar Control Window Film Market
Building Materials
US Facade Market
Building Materials
Steel Sleepers Market
Building Materials
North America Engineered Stone Market
Building Materials
Indonesia Concrete Admixtures Market
Building Materials
United States Construction Materials Market
Building Materials
Indonesia Dry Mix Mortar Market
Building Materials
Drywall Joint Tape Market
Building Materials
Asia-Pacific Kinetic Tiles Market