
 Medical Device Testing Services Market | 2026-2036
Medical Device Testing Services Market Size, Share, and Industry Trends Forecast 2026-2036
Medical Device Testing Services Market Outlook
Market Dynamics
Germany is rewriting the competitive map for European medical device testing through expanded laboratory capacity in Munich and Berlin. SGS SA leverages its multi-site network to sustain turnaround advantages for sterilization validation workflows. Eurofins Scientific anchors high-throughput biocompatibility screening across Western Europe, while TÜV SÜD competes on regulatory breadth spanning FDA, CE marking, and IEC 60601 pathways.
Technical Scope and Segment Structure
Medical device testing services encompass the analytical and validation protocols that verify safety, performance, and regulatory conformity of instruments, implants, and active therapeutic equipment before commercial release. These services apply biocompatibility screening per ISO 10993, mechanical load testing, electrical safety verification against IEC 60601, and sterilization efficacy confirmation using biological indicators. Biocompatibility testing leads service revenue due to prolonged validation cycles for implantable devices, while electrical safety testing extends fastest as active device portfolios multiply. Device manufacturers represent the deepest end-user margin pool because they bundle pre-submission testing with ongoing lot-release programs.
Regulatory Environment and Outlook
FDA premarket notification requirements, EU MDR technical documentation mandates, and ISO 13485 quality management standards collectively shape laboratory accreditation demand and client retention economics. The EU AI Act and updated MDR vigilance rules are forcing testing providers to expand software validation capabilities for algorithm-enabled devices. Stakeholders must monitor how dual regulatory track records become the primary filter for manufacturer procurement decisions.
Market Dynamics
Implantable device manufacturers are consolidating testing contracts around laboratories with dual ISO 13485 and FDA accreditation, compressing vendor selection criteria to regulatory track record above geographic proximity.
Growth Catalysts
- EU MDR biocompatibility mandates:The expanded technical documentation requirements for implantable devices under the Medical Device Regulation are extending validation cycles and deepening laboratory engagement.
- Active therapeutic device proliferation:Algorithm-enabled pacemakers, infusion pumps, and neurostimulators are multiplying demand for IEC 60601 electrical safety verification and software validation protocols.
- Swissmedic and TGA mutual recognition:Streamlined approval pathways between Switzerland and Australia are creating cross-border testing economies for manufacturers targeting multiple premium markets simultaneously.
Market Restraints
- Reference standard material scarcity:Biological indicator shortages and certified reference material bottlenecks are inflating sterilization validation costs and extending lead times.
- German laboratory concentration:Munich and Berlin capacity expansion is creating geographic dependency, with procurement teams facing limited fallback options during peak demand windows.
- ISO 10993-1 interpretive variance:Divergent notified body readings of biocompatibility evaluation endpoints are forcing redundant testing cycles and documentation revisions.
Strategic Opportunities
- Software as a Medical Device (SaMD) validation:The EU AI Act and FDA's predetermined change control plans are opening dedicated algorithm verification service lines for diagnostic imaging and clinical decision support tools.
- Latin American regulatory alignment:ANVISA's convergence with MDR technical standards is creating first-mover advantages for testing providers establishing Brazilian accreditation.
- Real-time release testing integration:Continuous manufacturing adoption by pharmaceutical-device combination product makers is enabling embedded analytical services within production workflows.
Industry Challenges
- ISO 13485 auditor scarcity:Qualified lead assessors for quality management system certification are concentrated among a handful of European registrars, creating inspection backlog risks.
- Legacy equipment validation:Laboratories maintaining aging mechanical load frames and electrical safety analyzers face capital replacement cycles while defending current throughput commitments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Medical Device Testing Services Market |
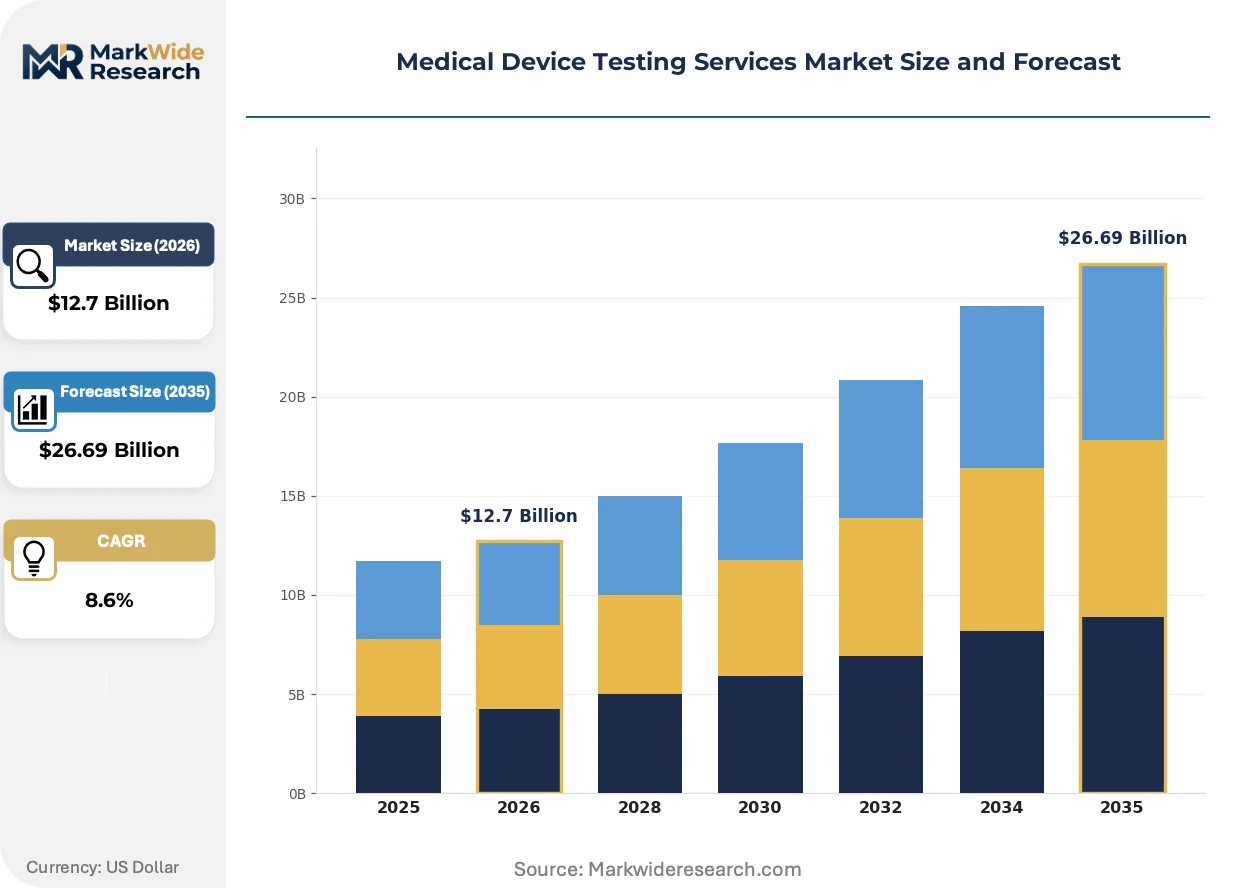
| Market Size in 2026 | $12.7 Billion |
| Market Size in 2035 | $26.69 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Biocompatibility Testing, Mechanical Testing, Sterilization Validation, Electrical Safety Testing End User: Hospitals, Clinics, Laboratories, Device Manufacturers Regulatory Compliance: ISO 13485, FDA Compliance, CE Marking, IEC 60601 Product Type: Implantable Devices, In Vitro Diagnostics, Surgical Instruments, Active Devices |
| Companies Covered | SGS SA, Nelson Laboratories, LLC, Laboratory Corporation of America Holdings, TÜV SÜD, Charles River Laboratories, Eurofins Scientific, Element Minnetonka, Pace Analytical Services LLC, Intertek Group Plc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Medical Device Testing Services Market Strategic Shifts
In vitro testing methodologies are displacing traditional animal studies as the primary biocompatibility validation pathway, compressing timelines and reshaping laboratory capability investments across the sector.
Computational toxicology and QSAR modeling is migrating from supplementary screening tools to primary hazard identification methods for cytotoxicity and sensitization endpoints. Implantable device divisions at major manufacturers are adopting these in silico approaches for early-phase material selection, reducing downstream animal study dependencies. The shift is compressing preclinical validation timelines from months to weeks for select biocompatibility endpoints.
The EU AI Act's risk classification framework for algorithm-enabled devices is mandating expanded software lifecycle documentation and post-market performance monitoring. Testing providers are building dedicated SaMD validation teams to address conformity assessment gaps that notified bodies have not historically staffed. Active device manufacturers targeting European market access are accelerating software verification partnerships ahead of 2025 enforcement windows.
Manufacturer procurement functions are unbundling pre-submission testing from ongoing lot-release programs, creating distinct vendor relationships for project-based validation versus recurring analytical services. Large device OEMs are consolidating premarket testing with dual-accredited laboratories while dispersing routine quality control across regional analytical networks. The bifurcation is most pronounced among orthopedic and cardiovascular implant manufacturers with high-volume production footprints in Ireland and Costa Rica.
Medical Device Testing Services Market Segmentation
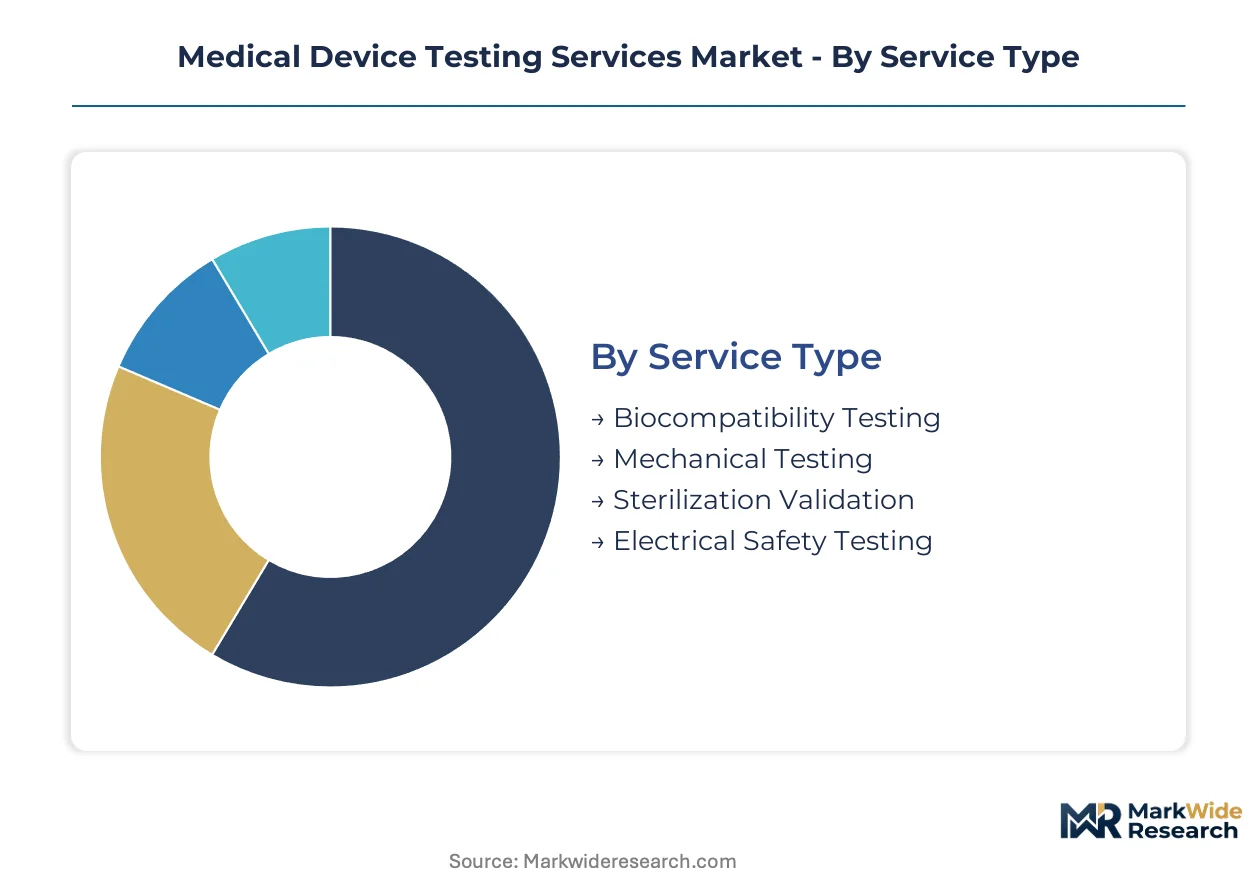
Testing service segmentation reveals divergent margin profiles across validation workflows. Laboratories configure capacity and staffing around service-specific equipment utilization patterns and regulatory documentation intensity.
Service Type:
After-sales engagement intensity varies sharply across testing modalities, with biocompatibility validation requiring sustained client liaison through iterative protocol amendments.
- Biocompatibility Testing:ISO 10993-guided cytotoxicity, sensitization, and irritation screening for implantable materials. Demand concentrates at device manufacturers in Germany and Switzerland facing expanded EU MDR technical documentation mandates for permanent implants.
- Mechanical Testing:Load, fatigue, and wear characterization of orthopedic and cardiovascular constructs. German automotive suppliers diversifying into medical polymers are driving tensile validation demand for structural implant components.
- Sterilization Validation:Biological indicator challenge studies and sterility assurance level verification per ISO 11135/11137. Contract manufacturers in Ireland and Costa Rica require recurring ethylene oxide and gamma irradiation confirmation.
- Electrical Safety Testing:IEC 60601 leakage current, dielectric strength, and electromagnetic compatibility protocols. Active device manufacturers in the United States and Japan are multiplying demand for algorithm-enabled therapeutic hardware verification.
By volume, biocompatibility testing leads. By growth pace, electrical safety testing is climbing the fastest.
End User:
Customer archetypes segment by procurement sophistication, with device manufacturers bundling multi-year testing contracts versus hospitals issuing spot analytical requests.
- Device Manufacturers:OEMs and contract manufacturers requiring premarket submission packages and ongoing lot-release programs. Orthopedic and cardiovascular implant divisions in Ireland represent the deepest margin pool due to high-volume production footprints and bundled service procurement.
- Laboratories:Reference laboratories and clinical testing facilities requiring analytical method validation and quality control support. German hospital networks are consolidating outsourced pathology device verification to specialized testing providers.
- Hospitals:Acute care facilities requiring point-of-care device calibration and safety verification. Swiss university hospitals drive demand for novel surgical robot acceptance testing prior to clinical deployment.
- Clinics:Ambulatory and specialty practices with limited in-house biomedical engineering capacity. United States dermatology and ophthalmology clinics require periodic laser and energy-based device safety confirmation.
Device manufacturers command the largest contract values. Clinics are expanding most quickly as point-of-care diagnostics proliferate.
Regulatory Compliance:
Accreditation portfolios determine laboratory addressable market, with dual-certified facilities capturing cross-border manufacturer procurement.
- ISO 13485:Quality management system certification for medical device supply chain participants. Swiss and German laboratories anchor European testing capacity expansion under this standard.
- FDA Compliance:United States premarket notification and quality system regulation adherence. Testing providers in Massachusetts and Minnesota leverage geographic proximity to FDA submission consultants.
- CE Marking:European Economic Area conformity assessment for market access. Notified body partnerships in Germany and the Netherlands structure validation workflow sequencing.
- IEC 60601:International electrical safety and essential performance standards for active medical devices. Japanese manufacturers targeting European and United States markets simultaneously drive multi-jurisdiction certification demand.
ISO 13485 certification is most prevalent. FDA compliance is gaining share fastest as United States market access remains priority for Asian and European manufacturers.
Product Type:
Device complexity tiers separate one-time validation projects from recurring analytical relationships, with implantables requiring extended biocompatibility monitoring.
- Implantable Devices:Permanent and long-term implantable constructs requiring comprehensive ISO 10993 biological evaluation and fatigue validation. Cardiovascular and orthopedic divisions in Ireland and Switzerland are extending validation cycles under tightened EU MDR vigilance requirements.
- Active Devices:Powered therapeutic and diagnostic equipment with electrical safety and software lifecycle documentation obligations. Algorithm-enabled pacemakers and infusion pumps from United States and Japanese manufacturers multiply IEC 60601 and SaMD validation demand.
- In Vitro Diagnostics:Reagent-based and instrument-based diagnostic systems requiring analytical performance verification. German laboratory networks are consolidating IVD instrument qualification to specialized testing providers.
- Surgical Instruments:Reusable and single-use mechanical instruments requiring sterilization validation and material characterization. Costa Rican contract manufacturers serving United States OEMs drive recurring biological indicator testing demand.
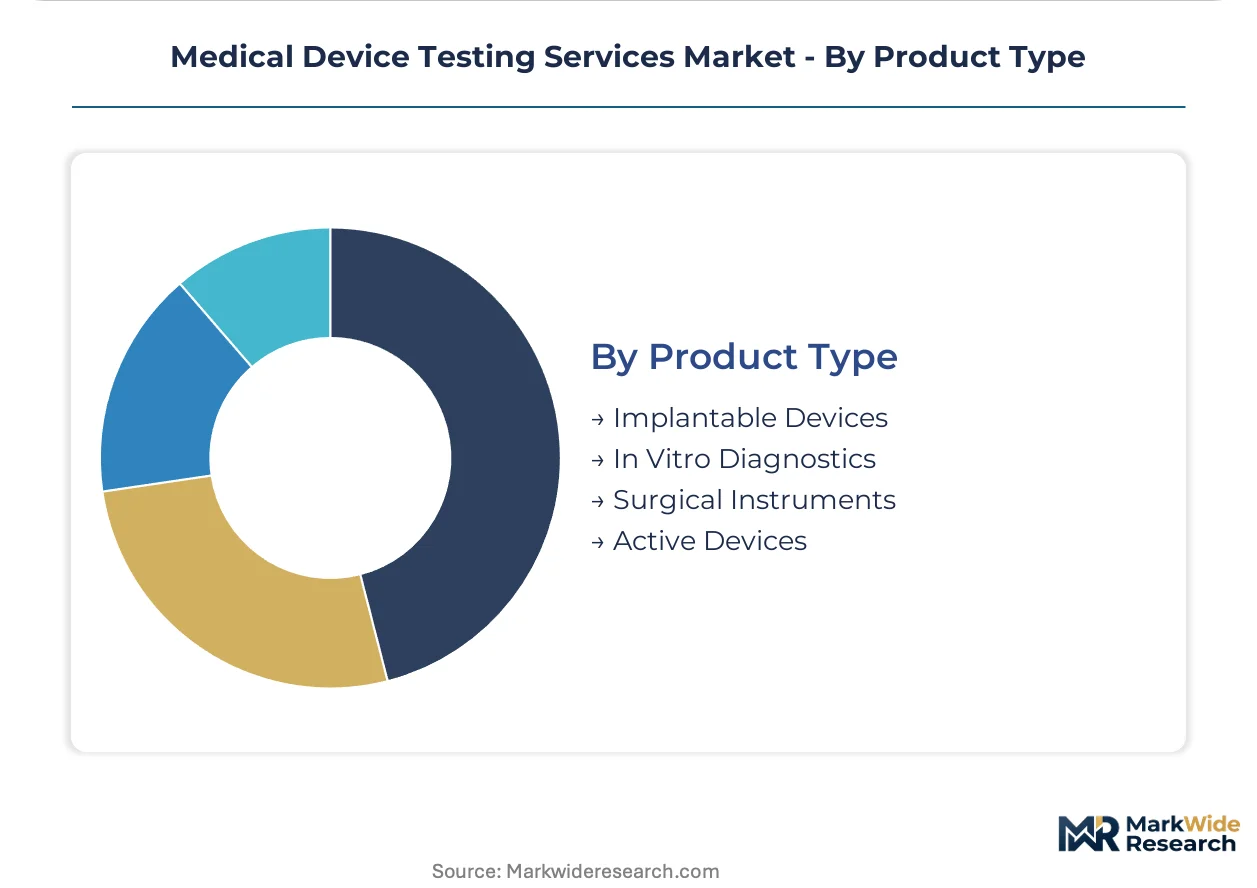
Implantable devices generate the highest per-project revenue. Active devices are expanding most quickly as software-enabled therapeutics multiply.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Frankfurt-Rotterdam rail freight corridor underwrites Germany's centrality in European medical device logistics, while the Port of Rotterdam's cold-chain infrastructure anchors transatlantic testing sample flows. Laboratory capacity expansion along these transport arteries is redrawing procurement geography.
United States
FDA premarket notification volume from Massachusetts and Minnesota device clusters is intensifying demand for electrical safety verification. The FDA's predetermined change control plans for algorithm-enabled devices are mandating expanded software lifecycle documentation. Greater Boston's contract research organizations are building dedicated SaMD validation teams ahead of enforcement windows.
Germany
EU MDR technical documentation mandates for implantable devices are extending validation cycles at Munich and Berlin laboratories. ECHA's REACH substance restrictions are forcing material requalification for polymer-based implants. The Munich-Berlin corridor now concentrates over half of German biocompatibility screening capacity.
Switzerland
Swissmedic's mutual recognition agreement with TGA is creating cross-border testing economies for manufacturers targeting Australian and European markets simultaneously. ISO 13485-accredited laboratories in Basel and Zurich are capturing dual-market submission packages. The Basel biotech cluster is driving demand for combination product validation.
Ireland
Orthopedic and cardiovascular implant manufacturers in Galway and Dublin are bundling multi-year testing contracts with dual-accredited providers. The IDA's medical technology investment program is expanding cleanroom manufacturing footprints requiring recurring sterilization validation. Irish contract manufacturers serving US OEMs are dispersing routine quality control across regional analytical networks.
Japan
PMDA's convergence with IEC 60601 standards is multiplying electrical safety verification demand for algorithm-enabled therapeutic hardware. METI's medical device regulatory harmonization initiative is streamlining multi-jurisdiction certification pathways. Tokyo-Osaka medical device corridors are consolidating premarket testing with laboratories holding FDA and CE marking credentials.
Medical Device Testing Services Market Competitive Environment
Platform integrators command the system tier; component specialists sit upstream in discrete validation workflows. The vendor base organizes around three structural tiers: multi-site networks with dual accreditation portfolios, regional specialists concentrated in single regulatory jurisdictions, and niche laboratories focused on specific modality validation. Strategic differentiation flows through M&A-driven accreditation expansion and geographic footprint extension into manufacturing clusters.
Within the multi-site network tier, SGS SA and Eurofins Scientific exemplify platform-scale positioning through distributed laboratory infrastructure. TÜV SÜD anchors the regulatory breadth archetype, spanning notified body functions alongside testing operations. These Switzerland-based and Luxembourg-based entities occupy positions where dual ISO 13485 and FDA accreditation filters procurement decisions.
| Leading Market Players |
|---|
| SGS SA |
| Nelson Laboratories, LLC |
| Laboratory Corporation of America Holdings |
| TÜV SÜD |
| Charles River Laboratories |
| Eurofins Scientific |
| Element Minnetonka |
| Pace Analytical Services LLC |
| Intertek Group Plc |
| Others |
Value Chain & Pricing Dynamics
The Frankfurt-Rotterdam rail freight corridor's capacity constraints and cold-chain reliability premiums are concentrating testing procurement around Munich and Berlin laboratories, compressing price differentiation between dual-accredited providers and single-jurisdiction competitors while elevating logistics costs for peripheral manufacturers.
Pricing Analysis
Volume-discount tiering structures separate enterprise device manufacturers bundling multi-year premarket and lot-release contracts from mid-tier contract manufacturers purchasing project-by-project validation services. Price differentiation rests on dual ISO 13485 and FDA accreditation status versus single-standard certification, with geographic proximity to manufacturing clusters commanding modest premiums. Cost compression in standard biocompatibility screening is intensifying because in vitro methodology adoption reduces per-study labor intensity. Contract manufacturers in Ireland and Costa Rica exhibit highest price sensitivity due to margin pressure from OEM procurement teams, while Swiss and German implant divisions prioritize accreditation breadth over unit cost.
Supply Chain Analysis
Tariff exposure between the United States and China dominates supply chain risk planning for reference standard materials and biological indicators used in sterilization validation workflows. Laboratory capacity concentrates in Germany, Switzerland, and the United States, with biological indicator manufacturing drawing from United States and Japanese suppliers. Single-source vulnerability in certified reference materials for polymer characterization is forcing laboratories to maintain dual-qualified vendor relationships. Distribution runs through specialized cold-chain logistics providers serving the Frankfurt-Rotterdam corridor and transatlantic sample flows via the Port of Rotterdam.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Qualified ISO 13485 lead assessor scarcity is constraining laboratory expansion timelines, making accreditation velocity the decisive competitive variable for testing providers seeking manufacturer procurement decisions.
For Market Incumbents: Build regulatory moat through preemptive FDA 510(k) third-party review accreditation and expanded Swissmedic-TGA mutual recognition coverage. Defend against emerging software-focused competitors by integrating SaMD validation capabilities ahead of EU AI Act enforcement. Prioritize capacity addition in the Munich-Berlin corridor to capture EU MDR-driven demand concentration. For New Entrants and Emerging Players: Pursue Brazilian ANVISA accreditation as Latin American regulatory alignment with MDR standards creates first-mover positioning. Target SaMD validation services for algorithm-enabled diagnostic imaging tools, where notified body staffing gaps exceed current provider capacity. Establish go-to-market partnerships with FDA submission consultants in Greater Boston to penetrate United States active device manufacturer clusters. For Investors and Strategic Acquirers: Regional specialists with single-accreditation portfolios and established notified body relationships present asymmetric upside as dual-certification requirements consolidate procurement decisions. Long-term viability hinges on software validation capability depth rather than traditional analytical testing scale. Watch FDA predetermined change control plan submission volumes as inflection indicator for SaMD service line maturity.| Strategic Initiative | Industry Significance |
|---|---|
| Dual Accreditation Expansion | ISO 13485 and FDA certification unlocks cross-border manufacturer procurement from German implant divisions. |
| SaMD Validation Capability Buildout | EU AI Act software lifecycle mandates create dedicated service lines for algorithm-enabled pacemaker verification. |
| Real-Time Release Testing Integration | Continuous manufacturing adoption by Irish combination product makers embeds analytical services within production workflows. |
| Latin American Regulatory Alignment | ANVISA convergence with MDR technical standards enables first-mover laboratory accreditation in Brazil. |
| In Vitro Methodology Transition | QSAR modeling adoption for cytotoxicity endpoints compresses timelines and reduces animal study dependencies. |
Study Parameters
Desk research of FDA 510(k) submission databases, EU MDR notified body guidance documents, and ISO standard revision records preceded structured interviews with laboratory operations directors, regulatory affairs managers at device manufacturers, and GPO contracts managers at hospital systems. Primary fieldwork with biocompatibility testing coordinators and sterilization validation specialists was cross-referenced against secondary trade data from customs records and laboratory accreditation registries. Bottom-up testing volume estimates were triangulated against top-down market size calculations derived from manufacturer R&D expenditure disclosures.
Assumptions held fixed across the modeling period include sustained EU MDR enforcement intensity, continued Swissmedic-TGA mutual recognition operation, and stable REACH substance restriction scope for polymer-based implants. Segmentation dimensions modeled encompass service type, regulatory compliance tier, device complexity class, and geographic manufacturing cluster. CAGRs were derived from regression analysis of historical testing volume trends against implantable device approval trajectories, with electrical safety testing growth calibrated to active therapeutic device pipeline data from PMDA and FDA filings.
Macroeconomic conditions sit as an overlay; deviation in freight corridor capacity utilization or reference material import costs would shift the trajectory. Forecasts reflect documented assumptions regarding regulatory harmonization pace and laboratory capacity expansion timelines. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Testing Services
Outsourced Testing Services Market
Testing Services
Leukocyte Count Testing Market
Testing Services
Gamma Glutamyl Transferase Testing Market
Testing Services
Europe Endotoxin and Pyrogen Testing Market
Testing Services
Cell Line Authentication and Characterization Tests Market
Testing Services
Global Mosquito Borne Infections Testing Market
Testing Services
Fertility Testing Market
Testing Services
United States Testing, Inspection, and Certification (TIC) Market
Testing Services
Biological Indicator Vials Market
Testing Services
Pharmaceutical Analytical Testing Market
Testing Services
North America Antimicrobial Susceptibility Testing Market
Testing Services
Pharmaceutical Sterility Testing Market
Testing Services
Cerebrospinal Fluid (CSF) Testing Market
Testing Services
Arthropod-Borne Viral Infections Testing Market
Testing Services
Mono Rapid Testing Market
Testing Services
Toxicology Drug Screening Market