
 Medical IoT Software Market | 2026-2036
Medical IoT Software Market Size, Share, and Industry Trends Forecast 2026-2036
Medical IoT Software Market Insights
The EU Medical Device Regulation is hardening cybersecurity and post-market surveillance obligations for connected health software. EPAM Systems leverages its FDA-registered quality management system to anchor enterprise contracts with US health networks. Andersen specializes in HIPAA-compliant cloud architectures that sustain recurring revenue from Midwest hospital chains. Azilen Technologies competes on Bluetooth Low Energy protocol expertise, dominating wearable integration projects for cardiology clinics.
Medical IoT software encompasses embedded systems, middleware platforms, and analytics layers that enable real-time data exchange between clinical devices, patient endpoints, and electronic health record systems through standardized protocols such as HL7 FHIR and IEEE 11073. Its primary purpose is to transform physiological signals into actionable clinical intelligence while maintaining sub-second latency for alarm-critical workflows. Remote monitoring and telehealth platforms command the largest installed base, though smart pills represent the fastest-expanding margin pool as pharmaceutical sponsors fund adherence-validation studies. Cellular connectivity segments lead average contract values where ambulatory telemetry requires uninterrupted wide-area coverage.
FDA premarket submission pathways for Software as a Medical Device, coupled with HIPAA security rule enforcement through OCR audits, shape US vendor R&D allocation toward documented risk controls. The EU AI Act and MDR Article 10 general safety requirements impose parallel conformity burdens on algorithmic diagnostic modules. Stakeholders must monitor divergence between FDA's predetermined change control plans and EMA's evolving guidance on adaptive AI to avoid duplicative validation spend.
Market Dynamics
FDA's tightening premarket validation requirements for cloud-connected Software as a Medical Device platforms are forcing vendors to restructure R&D budgets toward documented risk controls and continuous compliance architectures.
Growth Catalysts
- EU AI Act algorithmic safety mandates:Diagnostic modules embedded in connected monitoring devices now face conformity obligations that create procurement preference for pre-certified middleware vendors.
- Bluetooth Low Energy protocol maturation:Wearable integration projects for cardiology clinics are accelerating as power consumption thresholds enable multi-day continuous telemetry without patient burden.
- German university hospital networks:BfArM-supervised pilot programs for interoperable telemetry infrastructure are establishing procurement templates adopted by adjacent EU member states.
Market Restraints
- Silicon component supply concentration:Taiwan-based foundry capacity constraints for medical-grade system-on-chip designs extend lead times for embedded device manufacturers.
- HIPAA security rule enforcement:OCR audit expansion creates recurring compliance expenditure that compresses margins for mid-tier cloud platform operators.
- Cellular connectivity cost structure:Ambulatory telemetry's dependence on uninterrupted wide-area coverage locks vendors into carrier pricing frameworks that resist negotiation.
Strategic Opportunities
- Smart pill adherence validation:Pharmaceutical sponsor funding for digital therapeutics studies creates margin expansion in ingestible sensor software.
- HL7 FHIR-native architectures:Electronic health record interoperability mandates in the United States are opening replacement cycles for legacy HL7 v2 middleware.
- EMA adaptive AI guidance evolution:Divergence from FDA predetermined change control plans creates service revenue for regulatory strategy consultancies bridging both frameworks.
Industry Challenges
- Embedded systems firmware talent scarcity:Real-time operating system expertise for sub-second latency alarm workflows commands premium compensation that inflates development costs.
- ISO 13485 quality management integration:Medical device software firms acquiring SaMD capabilities face 18-24 month certification timelines that delay revenue recognition.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Medical IoT Software Market |
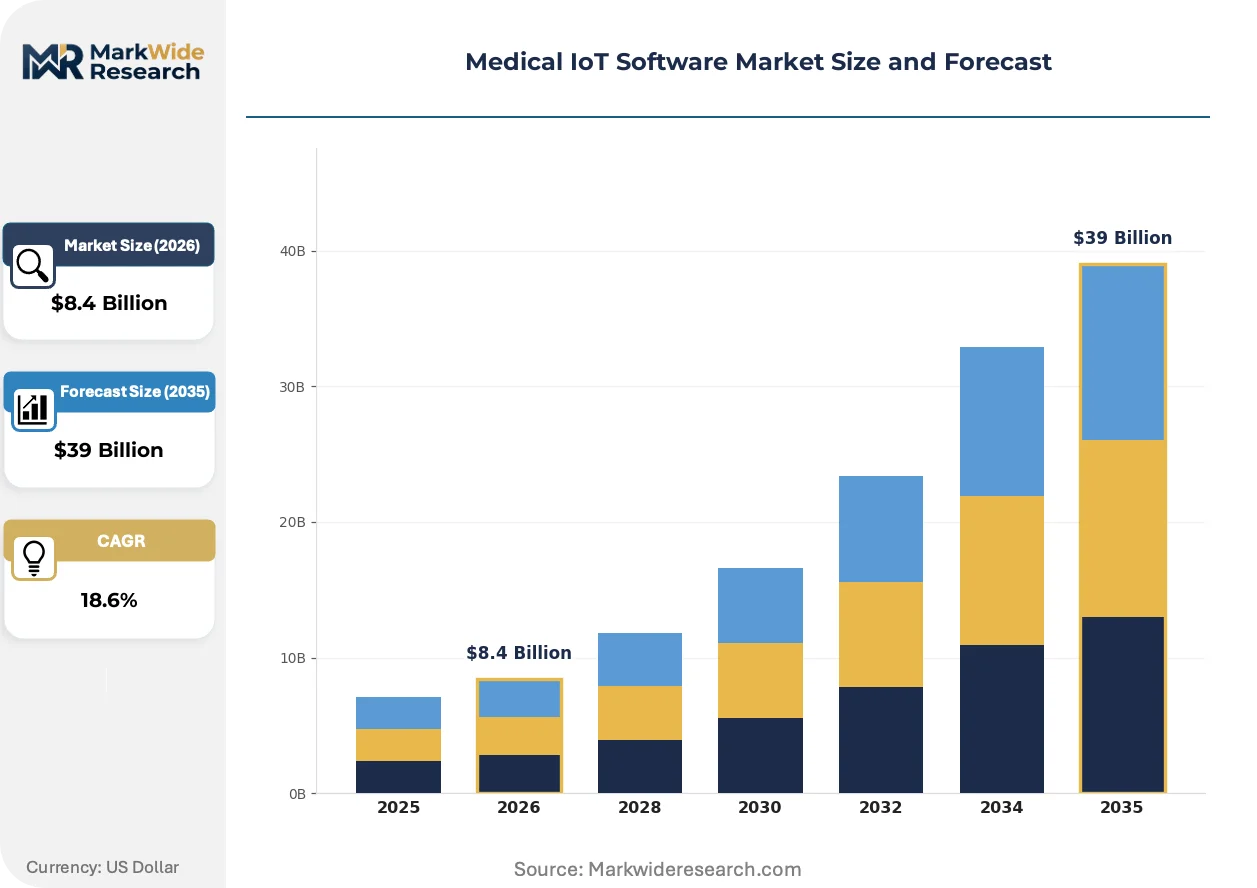
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $39 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Remote Monitoring, Wearable Devices, Smart Pills, Telehealth Platforms End User: Hospitals, Clinics, Home Care, Rehabilitation Centers Technology: Bluetooth, Wi-Fi, NFC, Cellular Application: Chronic Disease Management, Patient Monitoring, Data Analytics, Medication Adherence |
| Companies Covered | Computools, Azilen Technologies, Andersen, SumatoSoft, EPAM Systems, HQSoftware, Overcode, Netguru, Softeq, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Medical IoT Software Market Trends and Innovations
Edge computing architectures are redistributing processing loads from centralized cloud infrastructure toward bedside and wearable devices, compressing latency for alarm-critical clinical workflows while complicating cybersecurity perimeter design.
Machine learning inference engines deployed directly on patient monitoring hardware are automating arrhythmia detection and false alarm suppression. Cardiology departments in US health networks are piloting these systems at scale. The shift is automating tier-1 clinical review tasks that previously consumed nursing labor.
EMA's evolving guidance on adaptive AI algorithms is diverging from FDA predetermined change control plans. European notified bodies are demanding more frequent algorithmic performance submissions. SaMD vendors with EU market presence are responding by establishing parallel validation tracks rather than harmonized submissions.
Hospital procurement committees are consolidating vendor relationships around integrated platform providers capable of spanning embedded devices through analytics layers. Midwest health networks are terminating point-solution contracts for specialized telemetry. This consolidation pattern is most visible in the United States where health system merger activity has concentrated buying power.
Medical IoT Software Market Segmentation
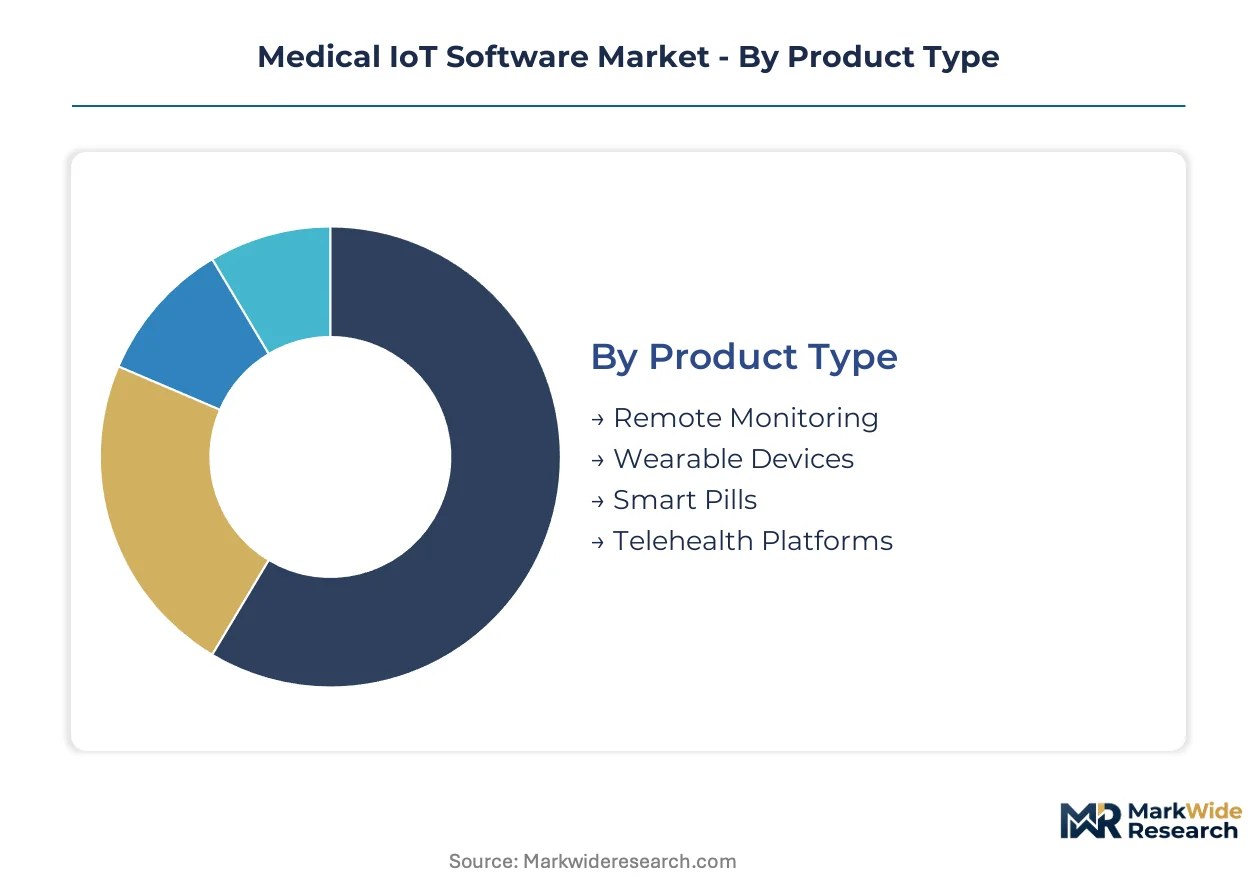
Medical IoT software procurement splits sharply between enterprise health systems demanding integrated platforms and specialized clinics seeking point solutions. Segmentation reveals where standardization yields scale economies versus where customization commands premium pricing.
Product Type:
Standardization dominates telemetry infrastructure while customization concentrates in pharmaceutical-integrated delivery systems.
- Remote Monitoring:Middleware platforms aggregate continuous physiological streams from bedside devices through cloud gateways. US health networks consolidate vendor relationships around integrated remote monitoring stacks that span embedded firmware through analytics dashboards.
- Wearable Devices:Bluetooth Low Energy protocol stacks enable multi-day cardiac telemetry with sub-second latency for arrhythmia detection. Cardiology clinics in Germany pilot interoperable wearable networks under BfArM supervision, establishing procurement templates adopted by adjacent EU member states.
- Smart Pills:Ingestible sensor firmware validates medication adherence through pharmaceutical sponsor-funded studies.
- Telehealth Platforms:Video-integrated vital sign capture sustains recurring revenue from Midwest hospital chains.
Most installed capacity flows through Remote Monitoring. Expansion is steepest in Smart Pills.
End User:
Cost tier stratification separates capital-rich health networks from budget-constrained outpatient facilities.
- Hospitals:Enterprise procurement committees demand ISO 13485-certified quality management systems spanning embedded devices through HL7 FHIR-native analytics layers. FDA premarket validation requirements for cloud-connected SaMD platforms force documented risk control architectures.
- Clinics:Specialty cardiology practices prioritize Bluetooth Low Energy integration expertise for wearable telemetry projects.
- Home Care:Cellular-dependent ambulatory monitoring locks vendors into carrier pricing frameworks.
- Rehabilitation Centers:Post-acute facilities adopt remote patient monitoring for readmission reduction programs.
Procurement volume concentrates in Hospitals. Margin expansion is most rapid in Home Care.
Technology:
Connectivity selection trades power efficiency against coverage continuity across patient mobility profiles.
- Bluetooth:Low Energy protocol maturation enables wearable integration without patient burden for multi-day telemetry.
- Wi-Fi:High-bandwidth local connectivity supports bedside video-integrated monitoring in hospital environments.
- NFC:Proximity-based pairing simplifies device onboarding for elderly patient populations.
- Cellular:Wide-area coverage sustains uninterrupted ambulatory telemetry for mobile patient monitoring.
Bluetooth dominates wearable attachment rates. Cellular commands highest average contract values.
Application:
Clinical workflow integration depth determines software architecture complexity and validation burden.
- Chronic Disease Management:Longitudinal data analytics platforms integrate glucose, blood pressure, and weight telemetry for diabetes and hypertension populations.
- Patient Monitoring:Real-time alarm-critical workflows demand sub-second latency from edge computing architectures redistributing processing loads toward bedside devices.
- Data Analytics:Machine learning inference engines automate tier-1 clinical review tasks previously consuming nursing labor.
- Medication Adherence:Digital therapeutics validation studies create margin pools in pharmaceutical sponsor-funded deployments.
Patient Monitoring carries the largest installed base. Medication Adherence is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Embedded firmware engineers and FDA regulatory specialists concentrate in the United States, while EU notified body auditors cluster in Germany and the Netherlands. This talent geography shapes where Medical IoT software vendors establish development centers and quality management operations.
United States
Hospital systems in the Midwest and Southeast are expanding procurement of connected patient monitoring infrastructure. FDA premarket guidance for Software as a Medical Device tightens validation requirements for cloud-connected platforms, forcing vendors toward documented risk control architectures. The Boston-Cambridge corridor anchors machine learning inference engine development for cardiology applications.
Germany
University hospitals pilot interoperable telemetry networks under BfArM oversight, establishing procurement templates adopted by adjacent EU member states. The EU Medical Device Regulation hardens cybersecurity and post-market surveillance obligations for connected health software. The Rhine-Ruhr and Munich clusters concentrate Bluetooth Low Energy protocol expertise for wearable integration projects.
United Kingdom
NHS England's digital transformation programs drive demand for HL7 FHIR-native middleware platforms. MHRA convergence with EU MDR requirements maintains alignment with continental conformity assessment procedures. London's health tech corridor hosts regulatory strategy consultancies bridging FDA and EMA frameworks.
India
CDSCO medical device rules increasingly align with IMDRF guidelines, attracting offshore development centers for US and EU vendors. Bangalore and Hyderabad clusters specialize in HIPAA-compliant cloud architectures sustaining recurring revenue contracts. Pharmaceutical sponsor-funded digital therapeutics studies create margin pools in ingestible sensor software development.
Switzerland
Swissmedic's streamlined SaMD approval pathways attract algorithmic diagnostic module developers seeking parallel EU market access. Basel's pharmaceutical-industrial complex funds smart pill adherence validation studies. Zurich and Geneva concentrate middleware vendors serving dual FDA-EMA regulatory strategies.
Medical IoT Software Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across the Medical IoT software value chain. The market structure fragments between enterprise platform integrators, specialized wearable firmware developers, and regulatory compliance consultancies. Three archetypes dominate: FDA-registered quality management system operators, Bluetooth Low Energy protocol specialists, and HIPAA-compliant cloud architects. Competitive moves concentrate on strategic partnerships with health networks and portfolio diversification into pharmaceutical-integrated delivery systems.
Within the FDA-registered tier, EPAM Systems anchors enterprise contracts through quality management credentials. Andersen and Azilen Technologies exemplify geography-differentiated positioning, with the former occupying HIPAA-compliant cloud architecture roles and the latter representing Bluetooth Low Energy integration specialists for cardiology clinics. These three firms collectively illustrate how regulatory certification and protocol expertise serve as primary segmentation variables in vendor selection.
| Leading Market Players |
|---|
| Computools |
| Azilen Technologies |
| Andersen |
| SumatoSoft |
| EPAM Systems |
| HQSoftware |
| Overcode |
| Netguru |
| Softeq |
| Others |
Pricing and Supply Chain Analysis
Medical-grade system-on-chip foundry pricing in Taiwan cascades through three distinct software procurement tiers, compressing margins for embedded firmware vendors while concentrating premium pricing power with FDA-registered platform integrators serving US health networks.
Pricing Analysis
Bundled platform subscriptions dominate enterprise hospital procurement, while unbundled per-device licensing persists in specialty cardiology clinics. Three-tier pricing structure across FDA-validated, ISO 13485-certified, and uncertified service levels separates EPAM Systems from Andersen and Azilen Technologies. Cost compression in mid-tier cloud middleware is intensifying because OCR audit expansion forces recurring compliance expenditure. Home care cellular connectivity buyers exhibit highest price sensitivity; hospital procurement committees demonstrate lowest sensitivity due to bundled quality management requirements.
Supply Chain Analysis
Embedded systems firmware engineers concentrate in the United States, Germany, and India, creating talent scarcity that inflates development costs for real-time operating system expertise. Bluetooth Low Energy protocol stacks draw from Taiwan-based semiconductor foundries, HIPAA-compliant cloud infrastructure feeds from Bangalore and Hyderabad development clusters, and regulatory strategy talent hinges on Boston-Cambridge and London corridors. Single-source vulnerability concentrates in medical-grade SoC fabrication. Distribution runs through direct enterprise sales teams for hospital networks and specialized channel partners for cardiology clinics.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a regulatory compounder where FDA premarket guidance tightening for Software as a Medical Device platforms continuously raises compliance barriers that favor incumbent quality management system operators.
For Market Incumbents: Hedge against Bluetooth Low Energy protocol commoditization by deepening FDA-registered quality management credentials and acquiring ISO 13485 certification timelines that delay competitor revenue recognition. Vertical integration into pharmaceutical-integrated delivery systems captures smart pill adherence validation margins.
For New Entrants and Emerging Players: Begin with HL7 FHIR-native middleware replacement cycles in US health networks where legacy v2 infrastructure creates white-space opportunity. Target rehabilitation center remote patient monitoring for readmission reduction programs as the most penetrable segment. Lead with EMA adaptive AI guidance bridging services to differentiate from FDA-predetermined change control plan specialists.
For Investors and Strategic Acquirers: Consolidation pressure builds where embedded systems firmware talent scarcity inflates development costs beyond mid-tier operator carrying capacity. Five-to-ten year viability favors platform integrators spanning embedded devices through analytics layers. Target acquisition archetypes include Bluetooth Low Energy protocol specialists with cardiology clinic relationships. Watch BfArM procurement template adoption rates across adjacent EU member states as inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| FDA Submission Pathway Investment | Documented risk control architectures anchor enterprise hospital contracts under tightening premarket guidance. |
| CE Marking Parallel Track Development | EU MDR Article 10 compliance opens procurement templates from German university hospital networks. |
| Hospital System Partnership Consolidation | Midwest health networks terminate point-solution contracts in favor of integrated platform providers. |
| Software Companion Development | Machine learning inference engines on patient monitoring hardware automate tier-1 clinical review tasks. |
| Reimbursement Strategy Alignment | Pharmaceutical sponsor funding for digital therapeutics studies creates margin pools in smart pill deployments. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary conversations with hospital purchasing committees, biomedical engineers, GPO contracts managers, and regulatory affairs specialists with secondary validation against FDA 510(k) filings, CMS Medicare reimbursement databases, hospital procurement records, and BfArM oversight documentation. Bottom-up telemetry platform deployment counts triangulated against top-down health network IT expenditure estimates.
Historical reference periods anchored the projection horizon through documented FDA guidance evolution and EU MDR implementation timelines. Segmentation dimensions modeled include connectivity technology, end-user facility type, clinical application workflow, and regional regulatory cluster. CAGRs derived from compound growth trajectory analysis across the modeling period, incorporating pharmaceutical sponsor funding flows for digital therapeutics and health system merger activity concentration patterns.
Several conditions sit outside the modeled scope, including unannounced FDA guidance revisions, geopolitical disruption to Taiwan foundry capacity, and abrupt EMA adaptive AI framework divergence. Forecasts reflect documented assumptions about Bluetooth Low Energy protocol maturation rates and cellular carrier pricing negotiation leverage. Material deviation in FDA premarket validation timeline acceleration or EU notified body audit backlogs warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Healthcare IT
Healthcare Smart Card Reader Market
Healthcare IT
North America Long-Term Care Software Market
Healthcare IT
Healthcare Claims Management Software Market
Healthcare IT
Global Medical Practice Management Software Market
Healthcare IT
Healthcare Survey Software Market
Healthcare IT
Global Dental Software Market
Healthcare IT
Integrated Operating Room Management Systems Market
Healthcare IT
Prior Authorization Software Market
Healthcare IT
US Long Term Care Software Market
Healthcare IT
Europe Healthcare Information Technology (IT) Market
Healthcare IT
Global Pharma Knowledge Management Software Market
Healthcare IT
Healthcare Contact Center Solution Market
Healthcare IT
Global Personal Health Records Software Market
Healthcare IT
Veterinary Practice Management Software Market
Healthcare IT
Global Dermatology EMR Software Market
Healthcare IT
Pharmaceutical Quality Management Systems Market