
 North America Organ-On-Chip Market | 2026-2036
North America Organ-On-Chip Market Size, Share, and Industry Trends Forecast 2026-2036
North America Organ-On-Chip Market Insights
Platform licensing revenue is reconfiguring how Organ-On-Chip developers capture value across the drug development lifecycle. Emulate, Inc. leverages its Human Emulation System to anchor partnerships with top pharmaceutical companies seeking predictive toxicology data. Hesperos, Inc. specializes in multi-organ systems that sustain long-term compound interaction studies, while SynVivo controls niche microfluidic vessel networks for blood-brain barrier applications.
Organ-On-Chip technology integrates living human cells with microfluidic channels to replicate organ-level physiology, typically operating at microliter-scale volumes with precise shear stress and nutrient gradient control. These systems serve primarily to predict human drug responses before clinical trials, reducing late-stage failure rates. Microfluidic Devices lead product category revenue due to their ubiquity in liver and kidney models, while Personalized Medicine applications expand fastest as biobank-linked patient-derived cells enable indication-specific screening. Pharmaceutical Companies dominate end-user spending, though Contract Research Organizations capture accelerating outsourcing flows from mid-cap drug developers.
FDA guidelines on New Approach Methodologies and EPA mandates under the Toxic Substances Control Act reshape validation requirements for non-animal testing platforms in the United States. Health Canada and the country's national pharmaceutical regulator advance parallel acceptance frameworks that influence cross-border protocol harmonization. Stakeholders must monitor evolving qualification pathways for Organ-On-Chip data in regulatory submissions across North American jurisdictions.
Market Dynamics
FDA Modernization Act 2.0 is dismantling decades-old animal testing mandates, forcing pharmaceutical sponsors to validate human-relevant predictive models before IND submission. This regulatory inflection point concentrates investment around Boston and San Diego biotech clusters where Organ-On-Chip developers co-locate with top-20 drug makers.
Growth Catalysts
- EMA parallel qualification pathways:Health Canada and the country's national pharmaceutical regulator are advancing acceptance frameworks that harmonize with FDA New Approach Methodology guidelines, accelerating cross-border protocol adoption for toxicology data.
- Patient-derived cell biobanking:Academic medical centers in the United States are scaling living cell repositories that feed indication-specific screening pipelines, expanding Personalized Medicine applications.
- Multi-organ system maturation:Long-term compound interaction studies now sustain 28-day pharmacokinetic windows, displacing single-organ liver and kidney models in safety pharmacology workflows.
Market Restraints
- PDMS material standardization lock-in:Polydimethylsiloxane microfluidic substrates dominate installed bases, creating technical debt that slows adoption of thermoplastic alternatives with superior optical clarity.
- Primary human cell supply volatility:Donor tissue availability fluctuates seasonally, constraining production scale-up for contract research organizations serving mid-cap drug developers.
- Cross-jurisdictional validation fragmentation:EPA mandates under the Toxic Substances Control Act diverge from FDA qualification timelines, forcing dual-track evidence generation for industrial chemical versus pharmaceutical applications.
Strategic Opportunities
- Texas and Research Triangle expansion:Underpenetrated United States biotech corridors offer lower cost-per-square-foot wet lab space for Organ-On-Chip foundries serving regional pharmaceutical outsourcing demand.
- AI-physiology model convergence:Machine learning platforms trained on microfluidic output data are compressing compound ranking cycles, creating integrated prediction-as-a-service offerings.
- CDER breakthrough therapy designation incentives:FDA commitment to expedited review for human-relevant safety data is steering sponsor investment toward Organ-On-Chip validation studies prior to Phase I initiation.
Industry Challenges
- Microfluidic engineering talent scarcity:Cross-trained biologists with cleanroom fabrication expertise command 40% salary premiums, constraining scale-up timelines for emerging developers.
- Good Laboratory Practice certification lag:Contract research organizations face 18-24 month qualification periods for Organ-On-Chip data inclusion in regulatory submissions, delaying revenue recognition.
- Legacy LIMS integration friction:Pharmaceutical quality systems require custom API development to ingest unstructured microfluidic sensor outputs, extending deployment cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Organ-On-Chip Market |
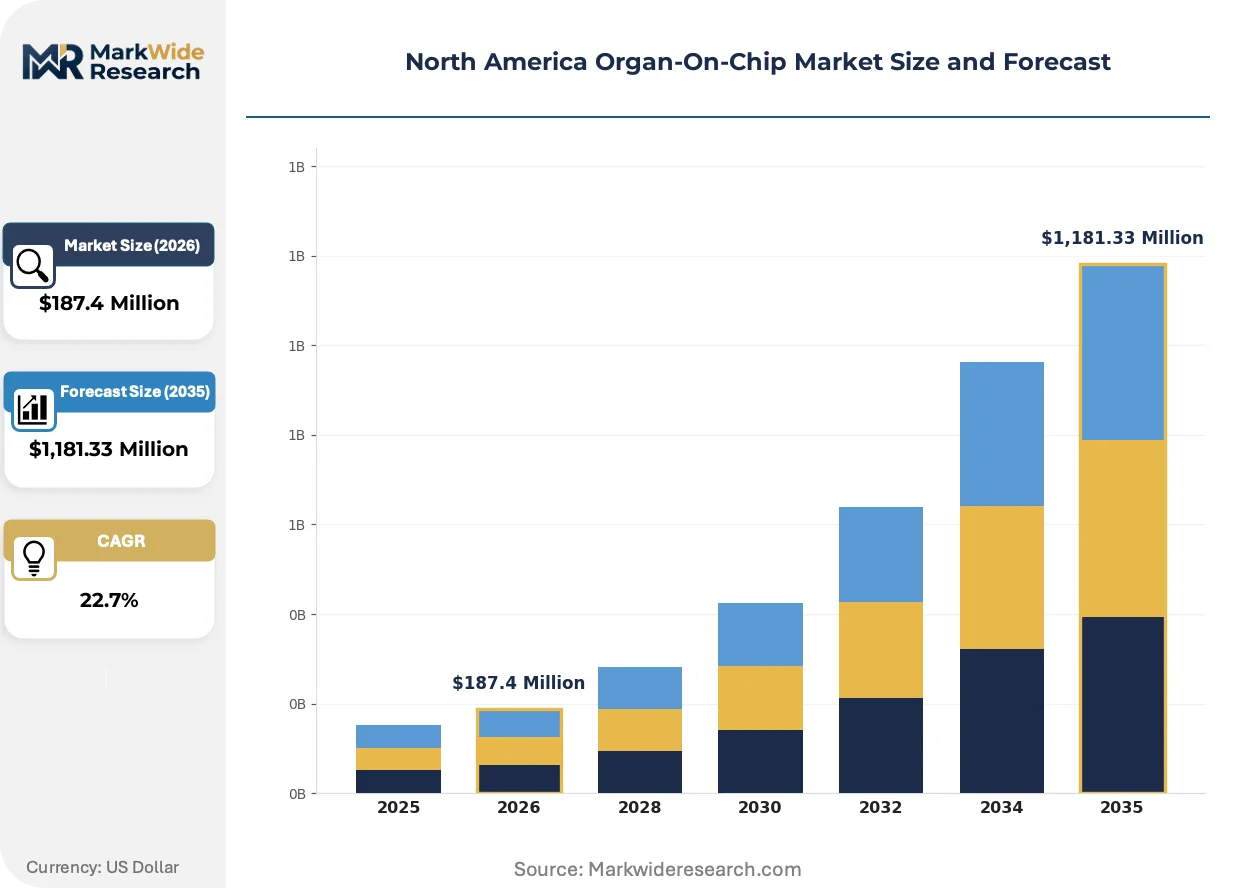
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $1,181.33 Million |
| CAGR (2026 – 2036) | 22.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Microfluidic Devices, Bioreactors, Sensors, Culture Systems Application: Drug Development, Toxicity Testing, Disease Modeling, Personalized Medicine End User: Pharmaceutical Companies, Academic Institutions, Research Organizations, Contract Research Organizations Technology: 3D Bioprinting, Microfabrication, Cell Culture, Computational Modeling |
| Companies Covered | Emulate, Inc., Hesperos, Inc., SynVivo, Insphero, Nortis Inc., AxoSim Technologies, Organovo, Altis Biosystems, TARA Biosystems, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Organ-On-Chip Market Trends and Innovations
Organ-On-Chip platforms are hybridizing with computational modeling to compress preclinical validation timelines. Three convergent forces are restructuring how living human cell systems integrate into pharmaceutical R&D workflows.
Microphysiological systems are hybridizing organ-level function with machine learning inference layers. Liver-chip platforms now generate continuous metabolite profiles that feed pharmacokinetic prediction algorithms. Top-20 pharmaceutical sponsors are embedding these hybrid systems into lead optimization stages, collapsing traditional 12-week safety pharmacology cycles into 21-day automated runs.
FDA New Approach Methodology qualification programs are formalizing evidentiary standards for microphysiological system data in IND packages. The industrial consequence is a bifurcation between qualified platform providers and unvalidated laboratory-scale systems. United States-based contract research organizations are consolidating around three qualified vendors to de-risk regulatory submission pathways.
Pharmaceutical procurement patterns are migrating from capital equipment purchases toward per-assay service contracts. Mid-cap drug developers lacking internal microfluidic expertise are outsourcing entire toxicology workflows to specialized foundries. This shift concentrates most visibly in Massachusetts and California, where platform developers operate captive service laboratories adjacent to sponsor R&D campuses.
North America Organ-On-Chip Market Segmentation
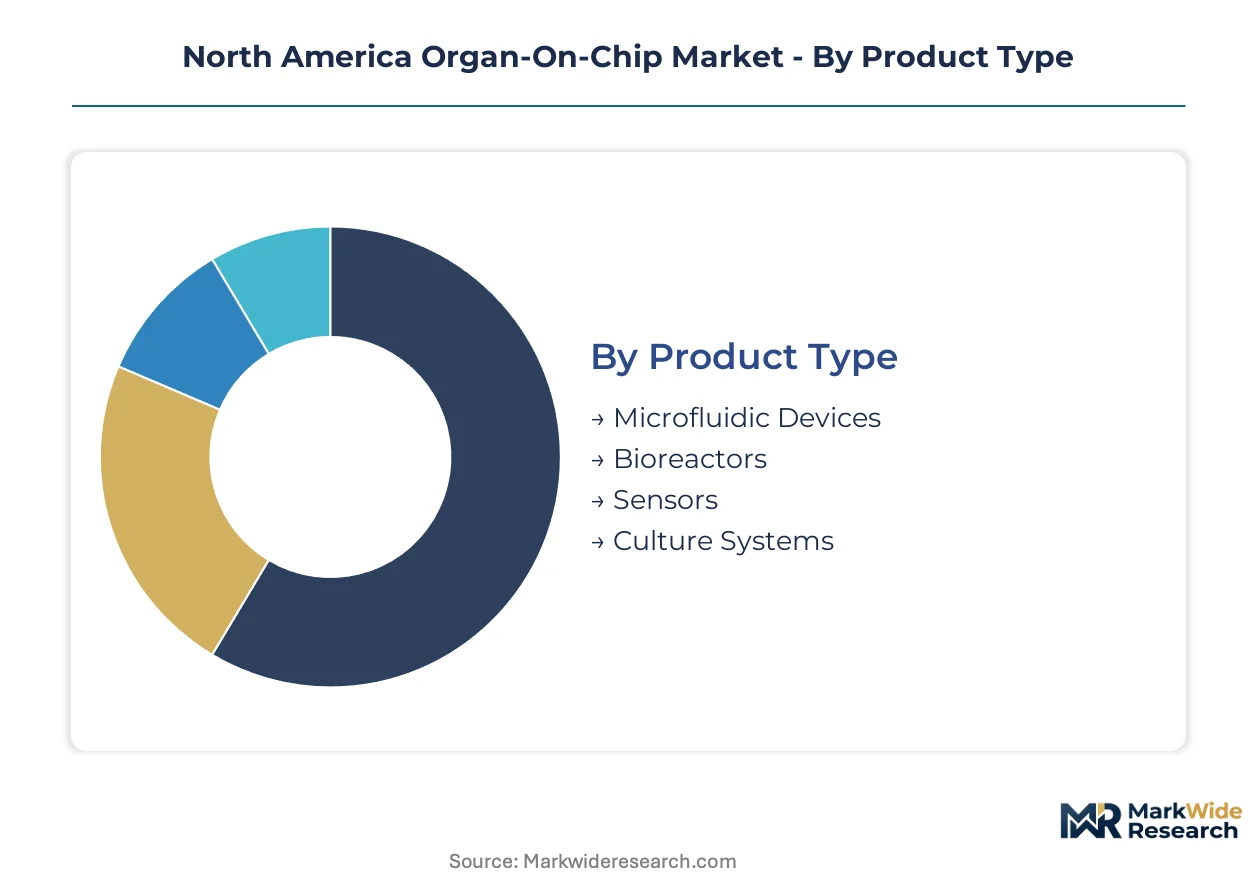
Organ-On-Chip technology fragments across four distinct classification axes, each revealing different commercial dynamics. Product architecture determines manufacturing complexity and regulatory qualification pathways. Application focus shapes customer procurement patterns and pricing power. End-user concentration drives geographic clustering and partnership structures. Technology modality influences IP defensibility and talent requirements.
Product Type:
Mature microfluidic platforms anchor installed bases while emerging bioreactor formats capture next-generation multi-organ workflows.
- Microfluidic Devices:Polydimethylsiloxane and thermoplastic substrates form the physical scaffold for cell culture chambers, with channel geometries engineered for precise shear stress control. Demand concentrates in liver and kidney single-organ models serving Boston and San Diego pharmaceutical R&D clusters, driven by FDA New Approach Methodology qualification timelines. These devices retain volume leadership; bioreactors hold the steepest expansion curve.
- Bioreactors:Perfusion-based systems sustain 28-day compound interaction studies across interconnected organ modules, enabling pharmacokinetic profiling absent in static well plates. Academic medical centers in the United States scale living cell repositories that feed indication-specific screening pipelines, expanding personalized medicine applications.
- Sensors:Integrated electrochemical and optical readouts capture real-time metabolite and protein secretion profiles.
- Culture Systems:Complete media and matrix solutions optimize cell viability across diverse tissue types.
Microfluidic devices dominate procurement volumes; bioreactor systems are climbing the fastest as multi-organ protocols displace single-organ workflows.
Application:
Cost tier stratification separates capital-intensive drug development contracts from standardized toxicity screening services.
- Drug Development:Lead optimization and candidate selection workflows embed Organ-On-Chip data into IND-enabling safety packages. Top-20 pharmaceutical sponsors in Massachusetts and California compress traditional 12-week safety pharmacology cycles into 21-day automated runs, collapsing preclinical timelines.
- Toxicity Testing:Hepatotoxicity and cardiotoxicity screens replace animal studies under FDA Modernization Act 2.0 mandates. Contract research organizations face 18-24 month Good Laboratory Practice qualification periods for data inclusion in regulatory submissions, delaying revenue recognition.
- Disease Modeling:Patient-derived cells replicate pathophysiology for mechanism-of-action studies.
- Personalized Medicine:Biobank-linked indication-specific screening enables precision therapeutic matching.
Drug development commands premium pricing; personalized medicine is gaining share fastest as academic medical centers scale living cell repositories.
End User:
Customer type fragmentation separates integrated pharmaceutical sponsors from outsourced research service providers.
- Pharmaceutical Companies:Internal microfluidic capabilities anchor predictive toxicology workflows prior to Phase I initiation. FDA commitment to expedited review for human-relevant safety data steers sponsor investment toward Organ-On-Chip validation studies.
- Contract Research Organizations:Mid-cap drug developers lacking cleanroom fabrication expertise outsource entire toxicology workflows to specialized foundries. Texas and Research Triangle corridors offer lower cost-per-square-foot wet lab space for regional pharmaceutical outsourcing demand.
- Academic Institutions:Basic research programs advance multi-organ system maturation and protocol standardization.
- Research Organizations:Non-profit and government laboratories validate cross-jurisdictional evidentiary standards.
Pharmaceutical companies dominate direct procurement; contract research organizations show the steepest expansion trajectory as mid-cap developers accelerate outsourcing.
Technology:
Supply concentration clusters around microfabrication expertise while computational modeling emerges as a differentiation layer.
- Microfabrication:Cleanroom-based photolithography and soft lithography processes define channel resolution and reproducibility. Cross-trained biologists with fabrication expertise command 40% salary premiums, constraining scale-up timelines for emerging developers.
- Cell Culture:Primary human cell sourcing and matrix optimization determine physiological fidelity. Donor tissue availability fluctuates seasonally, constraining production scale-up for contract research organizations.
- 3D Bioprinting:Scaffold-free and scaffold-based deposition methods construct vascularized tissue architectures.
- Computational Modeling:Machine learning platforms trained on microfluidic output data compress compound ranking cycles into integrated prediction-as-a-service offerings.
Microfabrication anchors technical differentiation; computational modeling is expanding most quickly as AI-physiology convergence accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Contract research organizations in Texas and the Research Triangle demonstrate highest price elasticity, while integrated pharmaceutical sponsors in Greater Boston and San Diego absorb premium pricing for qualified platforms. Demand concentrates where FDA Modernization Act 2.0 enforcement is strongest and biotech infrastructure is most mature.
United States
FDA New Approach Methodology qualification programs and CDER breakthrough therapy designation incentives concentrate procurement around Massachusetts and California biotech corridors. The FDA Modernization Act 2.0 removes mandatory animal study requirements, accelerating human-relevant model validation. Boston and San Diego clusters host captive service laboratories adjacent to sponsor R&D campuses.
Canada
Health Canada advances parallel acceptance frameworks that harmonize with FDA toxicology data standards, enabling cross-border protocol adoption for pharmaceutical sponsors. The country's national pharmaceutical regulator coordinates with EPA-aligned industrial chemical assessment pathways. Toronto and Vancouver academic medical centers scale living cell repositories feeding indication-specific screening pipelines.
California
Top-20 pharmaceutical sponsors embed hybrid AI-physiology systems into lead optimization stages, collapsing traditional safety pharmacology cycles. FDA regional offices in San Francisco accelerate qualification timelines for microphysiological system data in IND packages. San Diego biotech clusters concentrate multi-organ system developers serving West Coast outsourcing demand.
Massachusetts
Platform developers operate captive service laboratories adjacent to Cambridge and Boston sponsor R&D campuses, capturing per-assay service contract migration. Massachusetts General Hospital and Harvard Medical School biobanks supply patient-derived cells for personalized medicine applications. The concentration of microfluidic engineering talent commands salary premiums constraining emerging developer scale-up.
Texas
Underpenetrated wet lab space in Houston and Dallas-Fort Worth offers lower cost-per-square-foot for Organ-On-Chip foundries serving regional pharmaceutical outsourcing. Mid-cap drug developers lacking internal microfluidic expertise contract entire toxicology workflows to specialized service providers. Texas Medical Center academic partnerships advance multi-organ system maturation protocols.
North America Organ-On-Chip Market Competitive Landscape
Platform licensors and multi-organ specialists split the market between predictive toxicology anchoring and long-term pharmacokinetic study capabilities. The vendor base concentrates around qualified providers capable of FDA New Approach Methodology evidentiary standards, with unvalidated laboratory-scale systems facing procurement exclusion. Three archetypes dominate: integrated platform developers with captive service laboratories, specialized multi-organ system fabricators, and contract research organizations consolidating around qualified vendor relationships. Competitive moves center on strategic partnerships with top-20 pharmaceutical sponsors and geographic expansion into underpenetrated United States biotech corridors.
Among platform-focused developers, Emulate, Inc. and Hesperos, Inc. exemplify the divergence between single-system anchoring and multi-organ specialization. SynVivo occupies a position within the niche microfluidic vessel network segment, particularly for blood-brain barrier applications. These three represent distinct strategic postures: platform licensing revenue capture, long-term compound interaction study sustainment, and targeted physiological barrier replication.
| Leading Market Players |
|---|
| Emulate, Inc. |
| Hesperos, Inc. |
| SynVivo |
| Insphero |
| Nortis Inc. |
| AxoSim Technologies |
| Organovo |
| Altis Biosystems |
| TARA Biosystems |
| Others |
Pricing and Supply Chain Analysis
Undercapacity in polydimethylsiloxane cleanroom fabrication across Massachusetts and California biotech corridors is elevating platform licensing premiums while compressing per-assay service margins. Pharmaceutical sponsors absorb these premiums for FDA-qualified systems, whereas mid-cap developers migrate toward Texas-based contract research organizations seeking cost relief.
Pricing Analysis
Per-assay service contracts now generate lifetime value exceeding capital equipment sales by anchoring recurring revenue streams across multi-year toxicology workflows. Three-tier pricing structure across qualified-platform, standard-lab, and economy-outsourcing levels separates top-20 pharmaceutical sponsors from mid-cap developers and academic researchers. Pricing pressure stems from Good Laboratory Practice certification delays extending revenue recognition timelines for contract research organizations. Mid-cap drug developers lacking internal microfluidic expertise exhibit highest price sensitivity, while integrated sponsors in Boston and San Diego absorb premiums for regulatory-qualified data packages.
Supply Chain Analysis
Upstream feedstock concentration in United States polydimethylsiloxane substrates, German precision molding equipment, and Japanese optical-grade thermoplastics anchors microfluidic device manufacturing. Primary human cell sourcing draws from academic medical center biobanks in Massachusetts, California, and Texas, with donor tissue availability fluctuating seasonally. Single-source vulnerability in cleanroom fabrication talent commands salary premiums constraining scale-up timelines. Distribution runs through captive service laboratories adjacent to sponsor R&D campuses in biotech clusters, supplemented by regional contract research organization foundries in underpenetrated corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform developers are pivoting toward service-attach revenue as per-assay contracts expand faster than hardware sales, with recurring toxicology workflows capturing multi-year customer lifetime value.
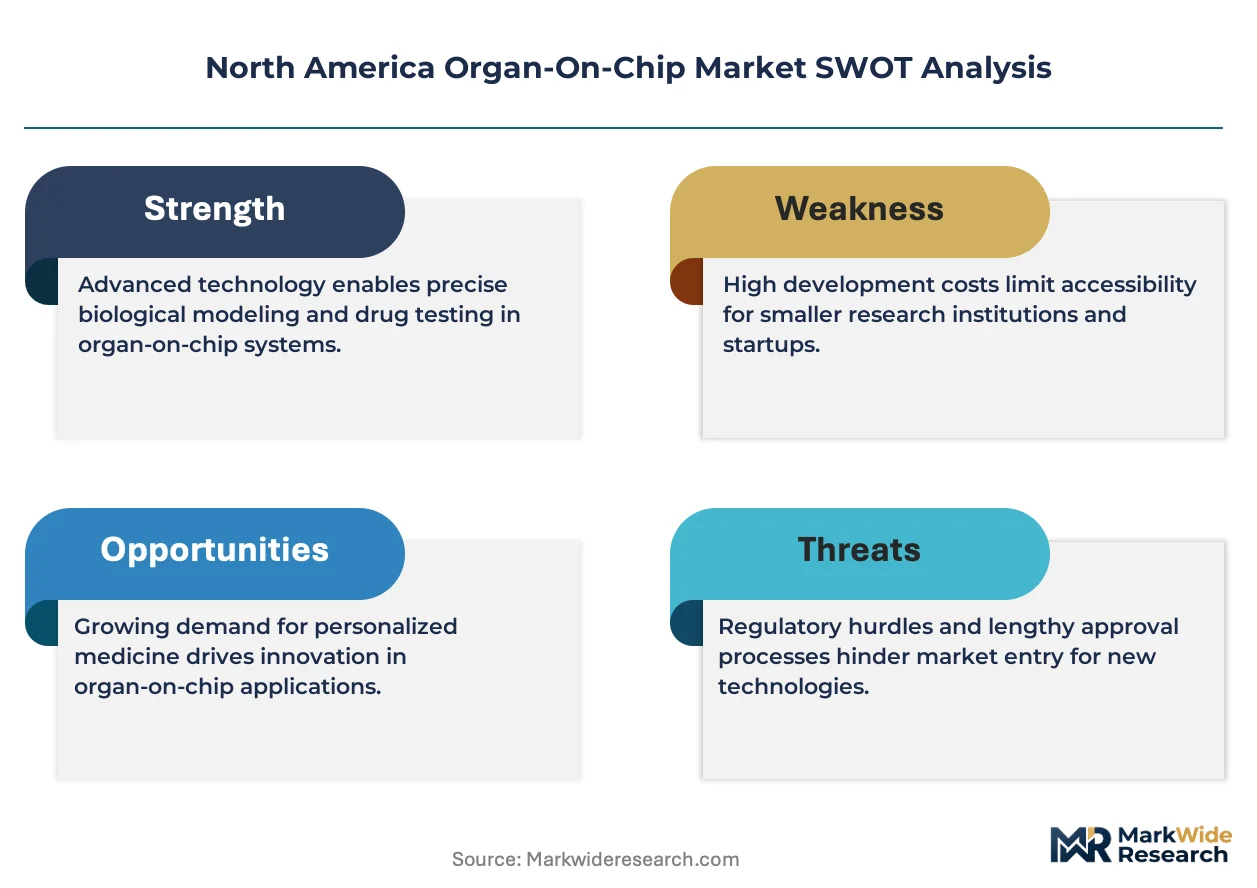
For Market Incumbents: Build regulatory qualification moats by accelerating FDA New Approach Methodology evidentiary packages before emerging entrants achieve Good Laboratory Practice certification. Defensive consolidation around multi-organ system capabilities counters single-organ commoditization, while backward integration into patient-derived cell biobanking secures input supply against academic medical center capacity constraints. For New Entrants and Emerging Players: Build out specialized foundry capacity in Texas and Research Triangle corridors where cost-per-square-foot wet lab space undercuts Massachusetts and California benchmarks. Blood-brain barrier applications and 28-day pharmacokinetic study protocols represent most penetrable white-space segments, with AI-physiology model convergence offering differentiated go-to-market positioning against established platform licensors. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across computational modeling layers as machine learning platforms compress compound ranking cycles without cleanroom infrastructure. Long-term viability over the next decade favors hybrid AI-physiology developers with regulatory-qualified data pipelines over pure hardware fabricators. Acquisition targets should demonstrate captive service laboratory revenue exceeding equipment sales; the signal to watch is contract research organization consolidation around qualified vendor relationships.| Strategic Initiative | Industry Significance |
|---|---|
| FDA New Approach Methodology Qualification | Secures evidentiary pathway for microphysiological system data in IND submissions ahead of competitors. |
| Multi-Organ System Maturation | Enables 28-day pharmacokinetic windows that displace single-organ liver and kidney models in safety workflows. |
| AI-Physiology Model Convergence | Compresses compound ranking cycles through machine learning platforms trained on microfluidic metabolite profiles. |
| Regional Foundry Expansion | Captures mid-cap pharmaceutical outsourcing demand in Texas and Research Triangle cost-advantaged corridors. |
| Patient-Derived Cell Biobanking | Anchors personalized medicine applications through academic medical center partnerships scaling living cell repositories. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with drug development executives, regulatory affairs leads at FDA and Health Canada, contract research organization operations directors, and academic medical center biobank managers. Secondary validation drew from FDA New Approach Methodology guidance documents, EPA Toxic Substances Control Act filings, Health Canada acceptance framework publications, and SEC 10-K disclosures from listed platform developers. Bottom-up segment sizing triangulated against top-down market envelope estimates derived from pharmaceutical R&D spending patterns.
Calibration against historical adoption curves for microphysiological systems informed growth trajectory assumptions across the projection horizon. Segmentation dimensions modeled include product architecture, application focus, end-user concentration, and technology modality, with regional regulatory cluster effects incorporated for United States and Canadian jurisdictions. CAGRs were derived from slope analysis of qualified platform penetration rates and per-assay contract velocity trends, with cross-checking against pharmaceutical outsourcing expenditure patterns.
Stress conditions across primary human cell supply volatility, Good Laboratory Practice certification timeline extensions, and EPA-FDA regulatory divergence were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding FDA Modernization Act enforcement pace and multi-organ system technical maturation. Cross-checking against pharmaceutical industry preclinical outsourcing survey benchmarks is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Anterior Cervical Plating Market
Medical Devices
North America Medical Device Regulatory Affairs Outsourcing Market
Medical Devices
Flow Diverters Market
Medical Devices
Zygomatic and Pterygoid Implants Market
Medical Devices
Vaginal Inserts Market
Medical Devices
Manometry System Market
Medical Devices
Non-Invasive Ultrasound Stimulation Market
Medical Devices
Ultrasonic Electrosurgical Devices Market
Medical Devices
France Contraceptive Devices Market
Medical Devices
Surgical Incision Closure Devices Market
Medical Devices
Wearable Insulin Pump Market
Medical Devices
Pipette Controllers Market
Medical Devices
Global Robotic Wheelchairs Market
Medical Devices
Organ Preservation Solutions Market
Medical Devices
Global Limb Prosthetics Market
Medical Devices
Global Portable Ventilators Market