
 Toxicology Testing Services Market | 2026-2036
Toxicology Testing Services Market Size, Share, and Industry Trends Forecast 2026-2036
Toxicology Testing Services Market Intelligence
The integration of high-throughput screening and computational toxicology is reconfiguring the preclinical testing workflow for new chemical entities. This shift enables faster, more predictive safety assessments earlier in the development cycle. Charles River Laboratories leverages its extensive portfolio of in-vitro models to serve global pharmaceutical clients. WuXi AppTec specializes in integrated testing platforms for the Chinese and American markets, while Eurofins Scientific dominates the environmental and food toxicology testing segments with its vast laboratory network.
Toxicology testing services encompass the scientific evaluation of a substance's potential harm to living organisms and ecosystems. These services utilize methodologies like dose-response analysis and genotoxicity assays to establish safety limits for human exposure and environmental release. Drug development services for pharmaceutical companies represent the largest and fastest-growing source of revenue. Within the technology stack, mass spectrometry remains a cornerstone for its sensitivity in bioanalytical testing and forensic analysis applications.
Regulatory mandates from agencies like the US FDA, the European Medicines Agency (EMA), and China's NMPA are primary demand drivers. These bodies require comprehensive toxicology data packages for new drug approvals and chemical registrations under frameworks like the EU's REACH. Navigating the complex validation and regulatory acceptance of New Approach Methodologies will determine future competitive positioning for all service providers.
Market Dynamics
The central force shaping the toxicology testing services market is the direct conflict between accelerated drug development timelines and the stringent, time-consuming data requirements of global regulatory bodies. This creates a powerful incentive for adopting more predictive, high-throughput technologies.
Growth Catalysts
- Regulatory Mandates:The EU's REACH regulation continues to compel chemical manufacturers to provide extensive toxicological data for new and existing substances, creating a consistent demand stream for contract research organizations specializing in chemical safety assessment.
- Biopharmaceutical Pipeline Expansion:Rapid expansion of the biopharmaceutical sector, particularly within research clusters in China, requires extensive preclinical toxicology studies for a large volume of novel biologics and cell therapies before they can enter clinical trials.
- Technology Adoption:The integration of high-throughput screening and automated liquid handling into preclinical workflows enables pharmaceutical companies to test more compounds faster, outsourcing this scaled-up activity to specialized service providers.
Market Restraints
- High Capital Investment:The acquisition and maintenance of advanced analytical instruments, such as high-resolution mass spectrometers and next-generation sequencing platforms, represent a significant capital expenditure that limits market entry for smaller laboratories.
- Regulatory Validation Lag:The slow pace at which regulatory agencies like the EMA and US FDA validate and formally accept New Approach Methodologies (NAMs) creates commercial risk for CROs investing in these technologies.
- In-Vitro Model Limitations:Certain complex toxicological endpoints, such as systemic toxicity or developmental and reproductive toxicity (DART), remain difficult to fully replicate with current in-vitro models, necessitating continued reliance on more costly and lengthy animal studies.
Strategic Opportunities
- Emerging Testing Segments:Growing public and regulatory focus on endocrine-disrupting chemicals (EDCs) in consumer goods and environmental contaminants opens a new service line for specialized assays beyond traditional pharmaceutical testing.
- Predictive Toxicology Platforms:The convergence of artificial intelligence with large-scale toxicogenomics datasets presents an opportunity to develop powerful in-silico models that can predict toxicity with higher accuracy, offering a premium service.
- Geographic Expansion:Nascent pharmaceutical and biotechnology industries in Southeast Asian nations offer an underpenetrated market for toxicology services as local companies begin to target international drug approvals.
Industry Challenges
- Specialized Talent Scarcity:A persistent shortage of board-certified toxicologists and technicians skilled in both computational modeling and advanced in-vitro techniques constrains the capacity of service providers to scale innovative testing services.
- Data Interoperability:The lack of standardized formats for reporting data from diverse sources like genomics, proteomics, and high-content imaging complicates the integration and submission of comprehensive data packages to regulatory authorities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Toxicology Testing Services Market |
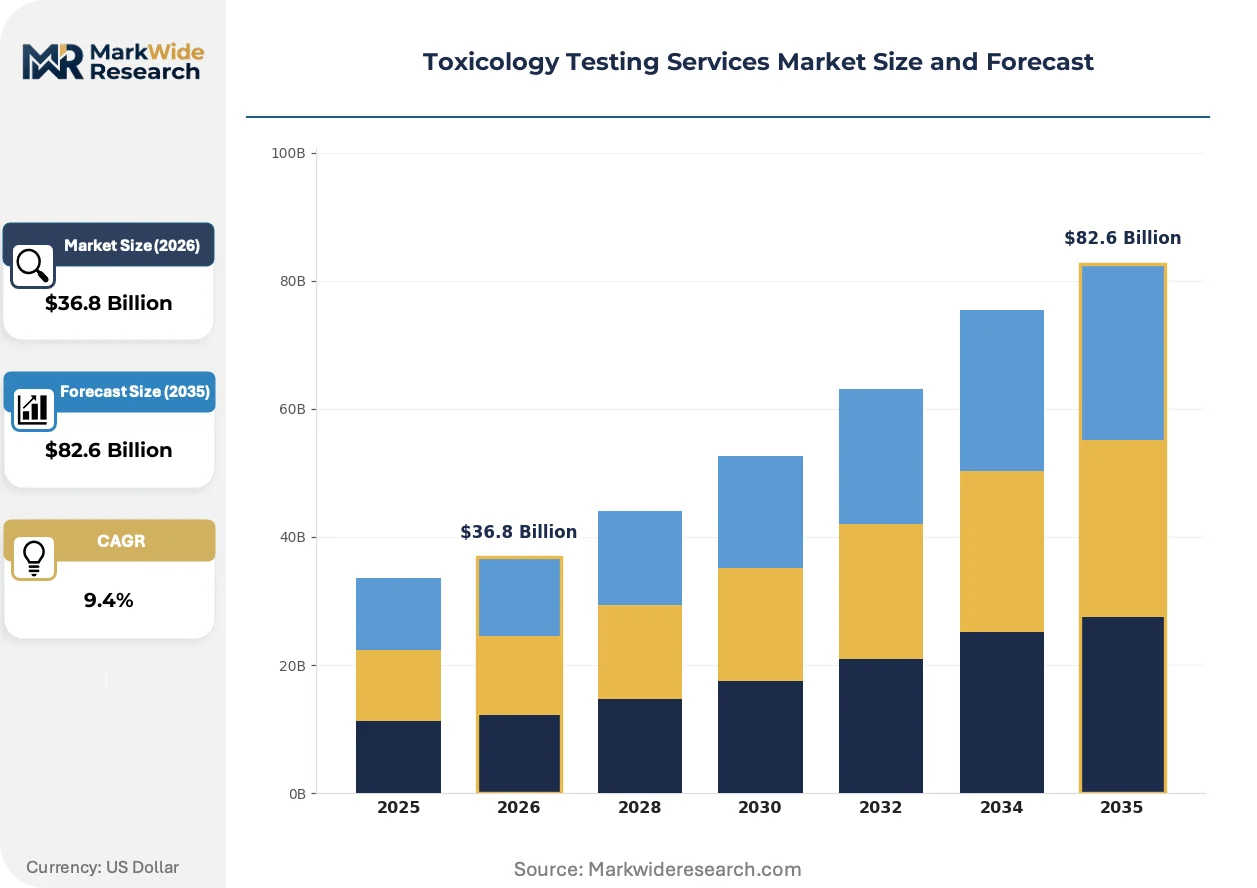
| Market Size in 2026 | $36.8 Billion |
| Market Size in 2035 | $82.6 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Clinical Trials, Environmental Assessment, Drug Development, Forensic Analysis Technology: Mass Spectrometry, Immunoassay, Chromatography, Bioanalytical Testing End User: Pharmaceutical Companies, Contract Research Organizations, Academic Institutions, Government Agencies Application: Drug Safety, Environmental Testing, Occupational Health, Clinical Research |
| Companies Covered | WuXi AppTec, Thermo Fisher Scientific Inc., Laboratory Corporation of America Holdings, Merck KGaA, Abbott Laboratories, Charles River Laboratories, Inc., SGS Group, Evotec AG, Eurofins Scientific, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Toxicology Testing Services Market Strategic Shifts & Innovations
The toxicology field is undergoing a fundamental transformation toward data-intensive, systems-based safety science. This evolution prioritizes mechanistic understanding and predictive power over observational endpoints, enabled by computational tools and advanced biological models that better recapitulate human physiology.
Organ-on-a-chip (OOC) technology provides micro-physiological systems that mimic human organ functions for more relevant toxicity screening. Pharmaceutical and specialty chemical firms are adopting OOCs for early-stage de-risking of lead compounds before committing to expensive in-vivo studies. This technology is hybridizing traditional cell cultures with animal models, creating a more predictive intermediate step in the preclinical assessment workflow.
The US FDA's Modernization Act 2.0 now allows drug sponsors to submit safety and efficacy data derived from qualified non-animal testing methods. This legislative shift directly incentivizes investment in and validation of NAMs, including computational toxicology and advanced in-vitro assays. The biologics and small molecule drug development segments are most affected, prompting a re-evaluation of preclinical strategies to reduce animal use.
A move toward integrated, full-service toxicology partnerships is gaining traction among biopharmaceutical clients. This model displaces transactional, single-assay purchasing with strategic collaborations where a CRO manages the entire preclinical safety program, from discovery screening to IND-enabling studies. This demand pattern is most visible in the US and European biotech hubs, where emerging companies outsource to conserve capital and access specialized regulatory expertise.
Toxicology Testing Services Market Segmentation
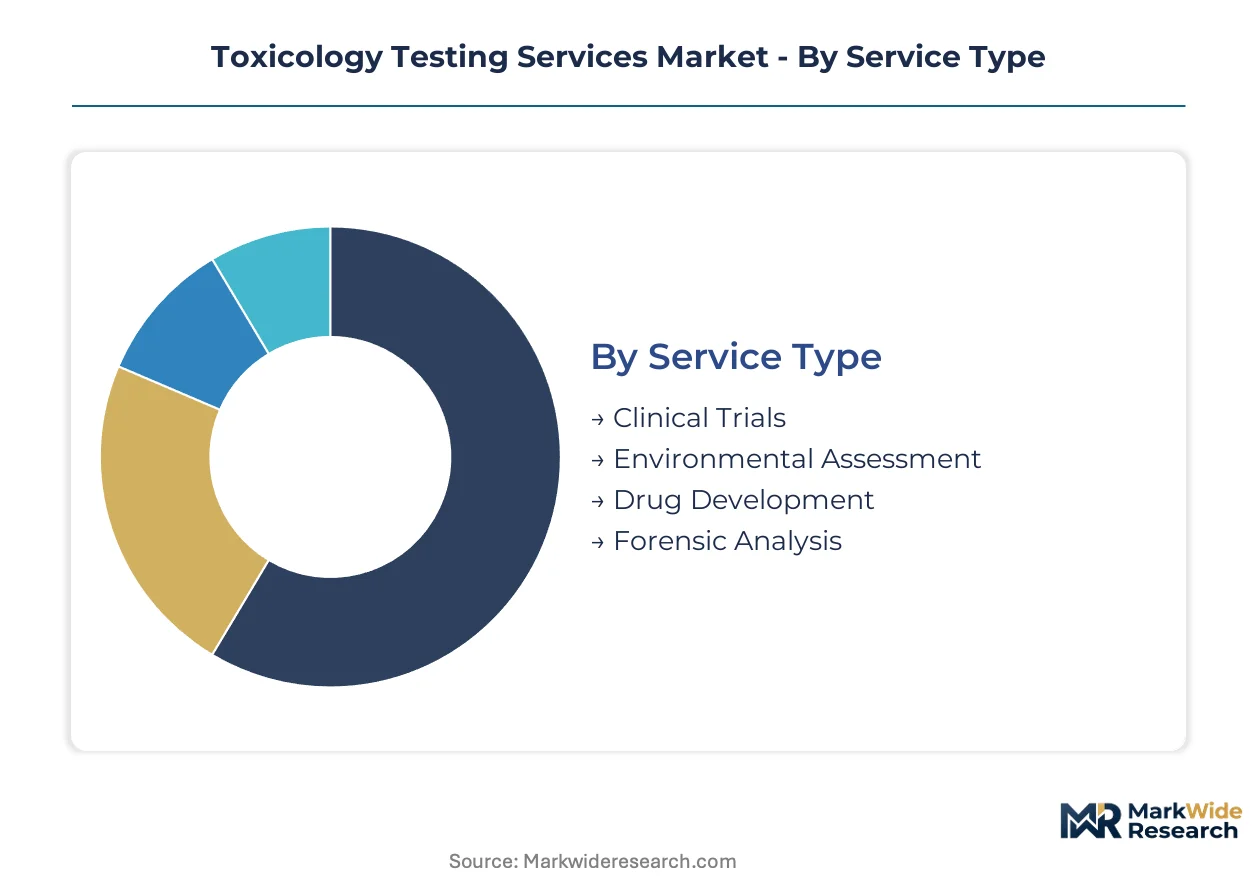
The toxicology testing services market segments reflect diverse client needs and evolving scientific capabilities. Understanding these divisions helps illuminate where demand concentrates and how technological advancements are reshaping service delivery. Each segment addresses specific regulatory requirements and industry challenges, driving specialized service offerings.
Service Type:
The service type segmentation reveals a spectrum of market maturity, from well-established pharmaceutical testing to emerging environmental compliance demands.
- Drug Development:These services support pharmaceutical companies by conducting preclinical safety assessments for novel compounds. Revenue concentration is high due to stringent regulatory requirements from agencies like the US FDA and EMA, necessitating extensive toxicology data packages before clinical trials.
- Environmental Assessment:This segment evaluates chemical impacts on ecosystems and human health, driven by regulations such as the EU's REACH and various national environmental protection agencies. Demand is concentrating in industrial regions requiring compliance for chemical manufacturing and waste management.
- Clinical Trials:These services involve toxicology monitoring and safety assessments during human clinical trials, ensuring patient safety and drug efficacy evaluation.
- Forensic Analysis:This includes toxicological investigations for legal or public health purposes, often involving post-mortem analysis or substance identification for law enforcement.
Drug Development handles the majority of throughput; Environmental Assessment is the fastest mover on share.
Technology:
Technology segmentation highlights the precision required for diverse analytical applications within toxicology testing.
- Mass Spectrometry:This cornerstone technology offers high sensitivity and specificity for identifying and quantifying compounds, critical for bioanalytical testing and forensic analysis. Its demand is strongest in pharmaceutical research for metabolite identification and pharmacokinetic studies.
- Bioanalytical Testing:These services quantify drugs and their metabolites in biological samples, essential for ADME (absorption, distribution, metabolism, excretion) studies and drug safety assessments. Global pharmaceutical clients drive demand, particularly for novel biologics and small molecule therapeutics.
- Immunoassay:This technique utilizes antibody-antigen reactions for rapid detection and quantification of specific substances, widely used in clinical diagnostics and drug screening.
- Chromatography:This separation technique isolates components from complex mixtures, crucial for purity analysis and quantitative measurements in environmental and pharmaceutical toxicology.
Mass Spectrometry contributes the largest analytical volume; Bioanalytical Testing shows the most significant expansion.
End User:
End user segmentation reflects distinct customer types and their strategic engagement with toxicology service providers.
- Pharmaceutical Companies:These entities represent the largest end-user segment, outsourcing preclinical safety evaluations and IND-enabling studies to accelerate drug development timelines. Regulatory mandates from the US FDA and EMA compel extensive toxicology data generation for new drug approvals.
- Contract Research Organizations:CROs both consume and provide toxicology services, often partnering with smaller biotech firms or managing specialized studies for larger pharmaceutical clients. Their expertise in regulatory navigation and advanced in-vitro models attracts significant investment.
- Academic Institutions:Research universities and medical schools utilize toxicology services for basic scientific inquiry, drug discovery, and mechanistic studies of chemical toxicity.
- Government Agencies:Regulatory bodies and public health organizations commission toxicology testing for chemical registration, environmental monitoring, and public safety assessments.
Pharmaceutical Companies command the largest revenue share; Contract Research Organizations exhibit the most dynamic growth.
Application:
Application segmentation illustrates the diverse societal impact and regulatory focus driving toxicology testing demands.
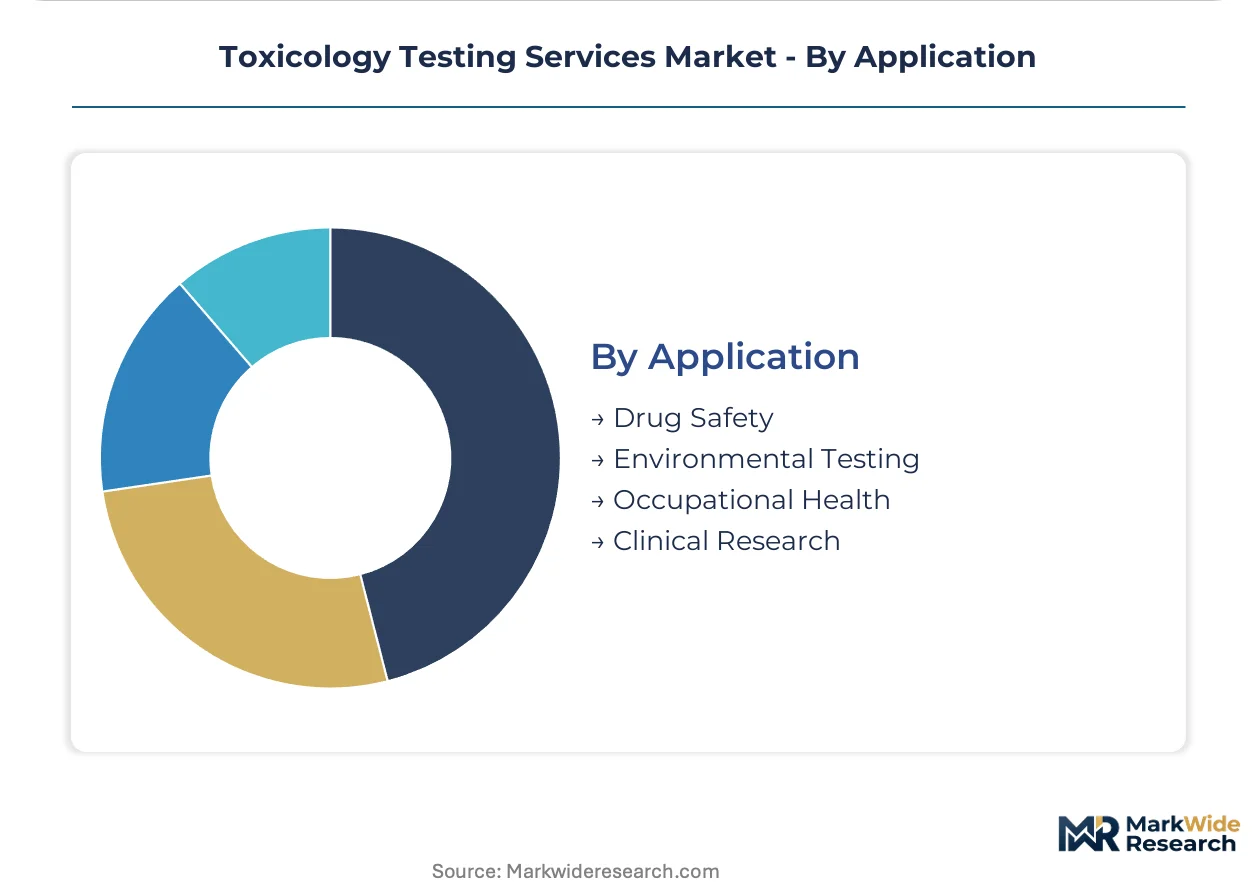
- Drug Safety:This core application ensures the safety profile of new drug candidates before human trials, encompassing genotoxicity, carcinogenicity, and reproductive toxicity studies. Regulatory bodies like China's NMPA and the US FDA require comprehensive data packages for drug approvals.
- Environmental Testing:This application assesses the ecological impact of chemicals and pollutants, vital for compliance with regulations such as the EU's REACH and national environmental protection acts. Demand is strong in industrial and agricultural sectors across Europe and Asia.
- Occupational Health:This involves monitoring workplace exposure to hazardous substances and assessing their potential health effects on employees, ensuring industrial safety standards.
- Clinical Research:Toxicology testing in clinical research supports patient safety monitoring during drug trials and evaluates adverse drug reactions, contributing to post-market surveillance.
Drug Safety applications hold the largest market share; Environmental Testing demonstrates the strongest growth potential.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand for toxicology testing services concentrates heavily among pharmaceutical and biotechnology companies globally. These entities drive substantial outsourcing for preclinical safety assessments and regulatory compliance. Research hubs and industrial clusters across various nations exhibit distinct needs and regulatory frameworks.
United States
The United States market for toxicology testing services is propelled by extensive biopharmaceutical research and development. The US FDA Modernization Act 2.0 directly encourages the adoption of New Approach Methodologies, influencing investment in advanced in-vitro assays. The Boston-Cambridge biotech cluster remains a focal point for novel drug discovery, requiring comprehensive preclinical toxicology studies.
China
China's rapidly expanding biopharmaceutical sector and chemical manufacturing industries fuel significant demand for toxicology testing. NMPA regulations for new drug approvals and GB standards for chemical registrations necessitate robust safety data. The Yangtze River Delta region, particularly Shanghai, is a major hub for contract research organizations conducting preclinical assessments.
Germany
Germany's toxicology testing market is driven by stringent chemical safety assessments under the EU's REACH regulation and a strong pharmaceutical presence. The European Medicines Agency (EMA) requires extensive data packages for drug candidates, fostering demand for specialized services. The Rhine-Main region, including Frankfurt, is a center for pharmaceutical research and advanced in-vitro model development.
United Kingdom
The United Kingdom sees sustained demand from its vibrant biotech startup ecosystem and established pharmaceutical companies. Regulatory frameworks, influenced by EMA guidelines and national Health and Safety Executive (HSE) requirements, mandate thorough toxicological evaluations. The London-Oxford-Cambridge "golden triangle" attracts significant investment in specialized toxicology services for early-stage drug development.
Japan
Japan's toxicology testing market is characterized by a mature pharmaceutical industry and a focus on environmental protection. The Pharmaceuticals and Medical Devices Agency (PMDA) enforces rigorous safety standards for drug approvals, driving demand for preclinical studies. The Tokyo metropolitan area is a key region for pharmaceutical research, where companies seek advanced bioanalytical and genotoxicity testing.
Toxicology Testing Services Market Key Industry Players
Channel-controlling players compete with product-specialist players across the toxicology testing services market. This market exhibits a mix of large, integrated service providers and specialized niche players. Strategic archetypes include global contract research organizations, technology-focused analytical service providers, and regional environmental compliance specialists. Mergers and acquisitions, alongside continuous investment in advanced technology platforms, represent dominant competitive moves.
Global integrated service providers, such as Charles River Laboratories, exemplify the comprehensive outsourcing model, offering end-to-end preclinical safety assessments. WuXi AppTec occupies a position as a leading integrated testing platform, particularly for the Chinese and American biopharmaceutical markets. Eurofins Scientific anchors its presence through a vast global laboratory network, specializing in environmental and food toxicology segments.
| Leading Market Players |
|---|
| WuXi AppTec |
| Thermo Fisher Scientific Inc. |
| Laboratory Corporation of America Holdings |
| Merck KGaA |
| Abbott Laboratories |
| Charles River Laboratories, Inc. |
| SGS Group |
| Evotec AG |
| Eurofins Scientific |
| Others |
Cost & Logistics Intelligence
Undercapacity in specialized bioanalytical testing facilities across Europe drives both supplier behavior and pricing posture for complex toxicology studies. This market dynamic encourages investment in new infrastructure while allowing established contract research organizations to command premium rates for their validated platforms.
Pricing Analysis
Cost-plus contract patterns with indexation to labor and specialized reagent costs dominate project-based toxicology testing. Price differentiation stems from the complexity of assays and the level of regulatory certification required for data packages. Pricing softness reflects intense competition for routine testing services, particularly from emerging Asian providers. Pharmaceutical companies outsourcing early-stage discovery screening represent the most price-sensitive buyers, while those requiring IND-enabling studies for regulatory submission are least price-sensitive.
Supply Chain Analysis
Contract-manufacturing concentration with WuXi AppTec and Charles River Laboratories holding significant bioanalytical capacity anchors the toxicology services supply chain. Geographic supply concentration for advanced testing services centers on the United States, China, and Germany. Raw material dependencies include specialized cell lines, high-purity reagents, and mass spectrometry consumables. Single-source vulnerability for niche reagents presents a structural supply chain risk. Distribution runs through direct client engagement and long-term service agreements with pharmaceutical and biotechnology firms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market sits as a platform-economics inflection play because the US FDA Modernization Act 2.0 encourages a shift towards non-animal testing, creating a new ecosystem for validated New Approach Methodologies.
For Market Incumbents: Entrench market position by investing heavily in the regulatory validation of New Approach Methodologies, addressing the threat from specialized technology providers. Acquire smaller firms with proprietary organ-on-a-chip technologies to deepen in-vitro model portfolios. Build out advanced computational toxicology platforms to offer more predictive safety assessments, mitigating margin pressure on traditional animal studies.
For New Entrants and Emerging Players: Pursue niche opportunities in predictive toxicology platforms leveraging AI and large toxicogenomics datasets. Target the endocrine-disrupting chemicals (EDCs) testing segment, which remains underpenetrated by traditional pharmaceutical CROs. A go-to-market angle focusing on rapid turnaround times and cost-effective, high-throughput screening for specialty chemical firms offers a clear entry point.
For Investors and Strategic Acquirers: Long-term, this sits as a capability-driven consolidation play because the market requires deep scientific expertise and significant capital investment in advanced instrumentation. Target specialist CROs with validated New Approach Methodologies or proprietary in-silico models. The signal to watch is the regulatory acceptance rate of non-animal testing methods by agencies like the EMA and NMPA.
| Strategic Initiative | Industry Significance |
|---|---|
| Invest in Organ-on-a-Chip Development | This enhances the predictive power of preclinical models, reducing reliance on animal testing for drug safety. |
| Expand Computational Toxicology Capabilities | This accelerates early-stage compound screening, enabling faster identification of potential toxicities. |
| Acquire Niche In-Vitro Testing Specialists | This broadens service portfolios and integrates advanced non-animal testing methodologies for clients. |
| Geographic Expansion into Southeast Asia | This taps into nascent biopharmaceutical markets, securing new revenue streams for toxicology services. |
| Develop Integrated Data Reporting Platforms | This streamlines regulatory submissions, addressing data interoperability challenges for clients. |
Research Approach
A spread of perspectives from regulatory affairs leads, toxicology research directors, pharmaceutical procurement officers, and biotechnology R&D heads converged on the working assumptions for this analysis. Primary interviews were combined with secondary validation from sources including US FDA filings, EMA submissions, and chemical industry association reports. This approach ensured bottom-up and top-down triangulation of market data.
The demand-supply-balance framing informed the analytical framework across the analysis window, modeling market dynamics. Segmentation dimensions included service type, technology, end user, and application, alongside a regional regulatory cluster dimension. Compound annual growth rates were derived from historical data trends and projected future demand, incorporating inputs such as biopharmaceutical pipeline expansion and regulatory mandate changes.
The forecast holds incumbent behavior within observed patterns; aggressive moves by global contract research organizations or technology-focused analytical service providers would shift outcomes. Forecasts reflect assumptions regarding regulatory acceptance of New Approach Methodologies and the pace of biopharmaceutical R&D. Cross-checking against OECD guidelines for chemical testing is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Testing Services
Cerebrospinal Fluid (CSF) Testing Market
Testing Services
Special Coagulation Tests Market
Testing Services
Pneumococcal Testing Market
Testing Services
US Viral Clearance Market
Testing Services
Creatinine Testing Market
Testing Services
Global Lipid Panel Testing Market
Testing Services
Urine Sediment Testing Market
Testing Services
Fertility Testing Market
Testing Services
Fecal Pancreatic Elastase Testing Market
Testing Services
Drug Tester Market
Testing Services
Bioprocess Integrity Testing Systems Market
Testing Services
Carbapenem-Resistant Enterobacteriaceae Testing Market
Testing Services
Germany Testing, Inspection and Certification Market
Testing Services
Nipah Virus (Niv) Infection Testing Market
Testing Services
Medical Device Testing, Inspection, and Certification Market
Testing Services
Lipase Testing Reagents Market