
 Nicotine Replacement Product Market | 2026-2036
Nicotine Replacement Product Market Size, Share, and Industry Trends Forecast 2026-2036
Nicotine Replacement Product Market Insights
Combination therapy bundling is restructuring how consumers and clinicians approach smoking cessation, moving single-product regimens toward paired patch-and-lozenge protocols that improve quit rates. Johnson & Johnson Services, Inc. leverages its heritage in transdermal nicotine delivery to sustain brand loyalty across pharmacy and clinical channels. Haleon Group of Companies anchors the oral NRT segment through broad retail distribution of gum and lozenge formats. Pfizer Inc. competes with prescription varenicline adjacency, positioning its portfolio to capture patients who fail over-the-counter pharmacotherapy.
Nicotine replacement products are dosage-controlled delivery systems that administer measured quantities of nicotine through transdermal, oral, or inhalation routes to alleviate withdrawal symptoms during tobacco cessation protocols. These formulations typically employ polacrilex resin matrices, acrylic adhesive layers, or aerosolized propellants to achieve steady-state plasma nicotine concentrations between 10 and 25 nanograms per milliliter. The transdermal patch category dominates value contribution due to extended wear duration and higher per-unit pricing, while the inhaler segment represents the fastest-growing delivery mode as consumers seek behavioral substitutes that mimic hand-to-mouth ritual. Oral formulations including gum and lozenge occupy the volume leadership position in emerging markets where pharmacy infrastructure remains limited.
The FDA regulates all nicotine replacement products as drug-device combinations under New Drug Application pathways, while the EMA enforces Good Manufacturing Practice standards through centralized marketing authorization procedures that constrain new entrant timelines. REACH compliance in Europe governs excipient chemical safety, adding formulation testing burdens that favor established manufacturers with dedicated toxicology departments. Stakeholders must monitor evolving classification debates around synthetic nicotine and reduced-risk product boundaries, as regulatory reclassification would reshape competitive access and reimbursement eligibility across multiple jurisdictions.
Market Dynamics
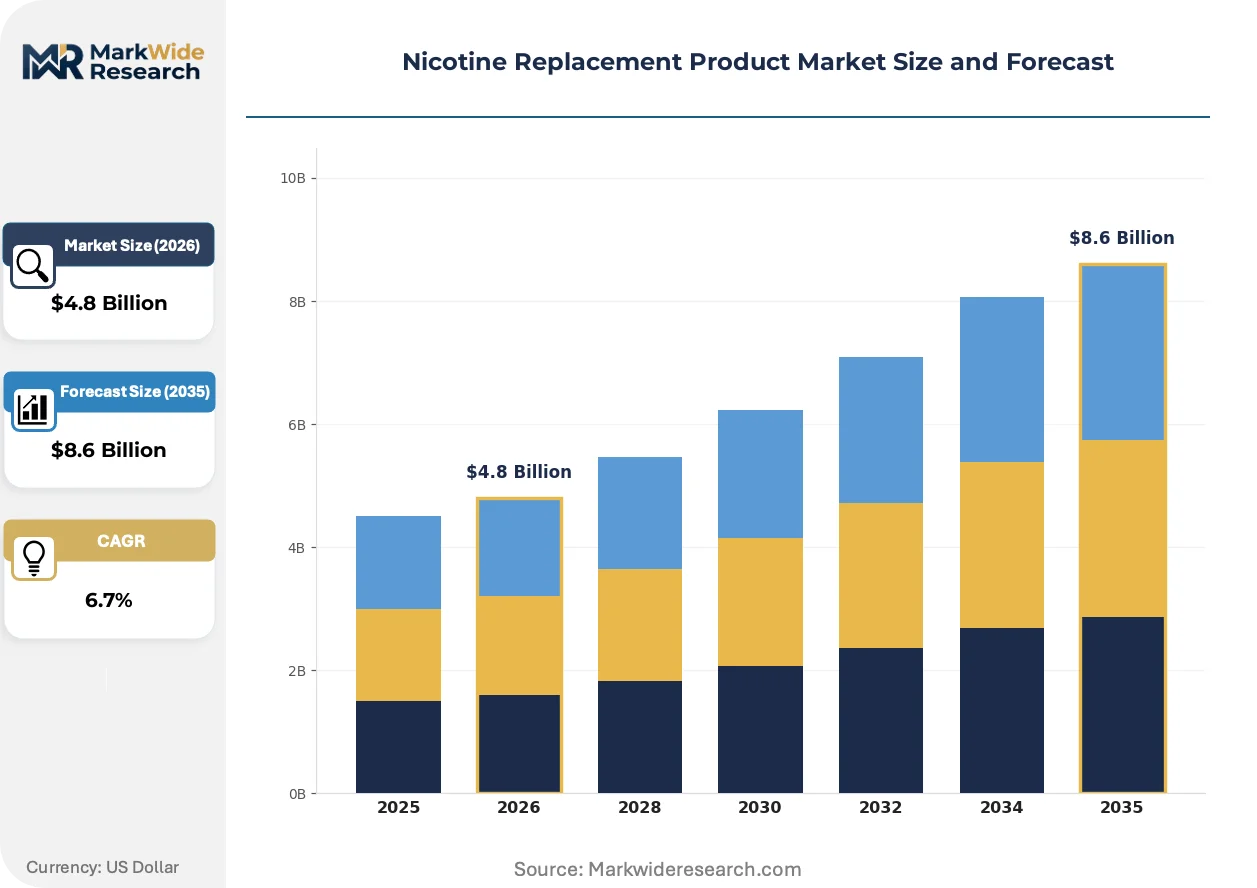
Combination therapy protocols are restructuring prescribing patterns across clinical and retail channels, pushing single-product regimens toward paired patch-and-lozenge bundles that improve cessation outcomes and expand average transaction values.
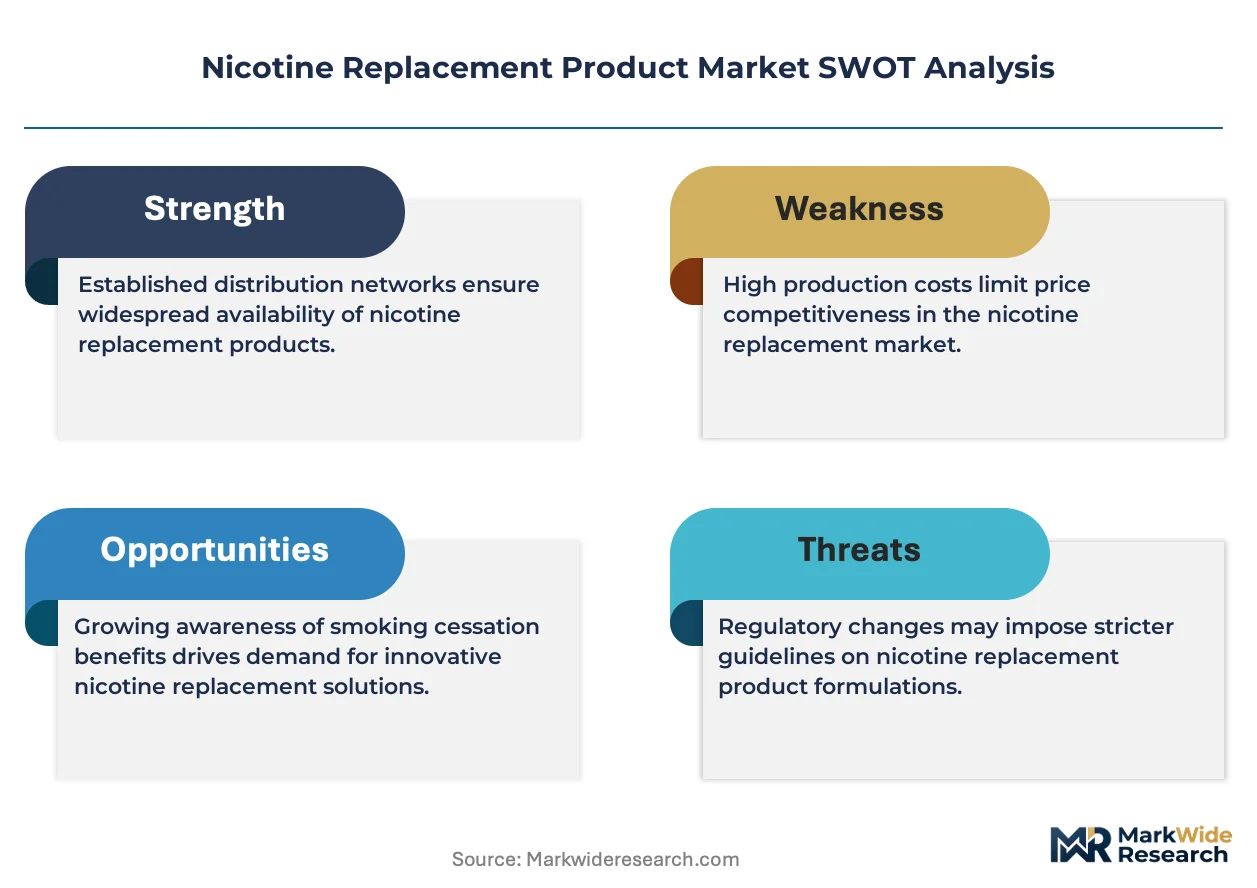
Growth Catalysts
- Workplace wellness integration:Employer-sponsored health plans in the United States now routinely include over-the-counter nicotine replacement products in preventive care formularies, expanding reimbursement coverage beyond traditional prescription channels.
- REACH compliance elevation:The European Chemicals Agency's tightening standards for excipient safety testing have paradoxically legitimized established pharmacotherapy options by raising barriers to unregulated alternatives.
- Behavioral mimicry demand:Consumers seeking hand-to-mouth ritual substitutes are accelerating inhaler segment adoption, particularly among populations with high psychological dependence on smoking gestures.
Market Restraints
- Acrylic adhesive input volatility:Transdermal patch manufacturing depends on petroleum-derived acrylic polymers subject to feedstock price swings that compress margin stability.
- Synthetic nicotine classification uncertainty:Regulatory ambiguity around non-tobacco-derived nicotine sources threatens to reclassify product categories and invalidate existing marketing authorizations.
- Polacrilex resin supply concentration:Oral formulation production relies on ion-exchange resin suppliers concentrated in East Asian chemical manufacturing clusters, creating single-source vulnerability.
Strategic Opportunities
- Pharmacy infrastructure gaps in emerging markets:Brazil and Mexico present underpenetrated territories where limited retail pharmacy density favors gum and lozenge formats requiring minimal cold-chain handling.
- Digital therapeutics convergence:Mobile cessation coaching applications paired with connected dosing devices create adherence-tracking ecosystems that differentiate commoditized hardware.
- Private insurer formulary expansion:United States commercial payers are adding combination therapy protocols to preferred drug lists, reducing patient out-of-pocket exposure and expanding addressable volume.
Industry Challenges
- Toxicology expertise scarcity:REACH and FDA excipient safety documentation requirements demand specialized analytical chemistry capabilities that smaller manufacturers struggle to staff.
- New Drug Application timeline compression:Centralized EMA marketing authorization procedures create 18-24 month approval windows that delay product launches and tie up capital.
- Legacy distribution system integration:Direct-to-consumer subscription models clash with established wholesale-pharmacy relationships, forcing channel conflict resolution.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Nicotine Replacement Product Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Gum, Patch, Lozenge, Inhaler Delivery Mode: Transdermal, Oral, Inhalation, Buccal Consumer Type: Smokers, Ex-Smokers, Dual Users, Non-Smokers Formulation: Nicotine, Nicotine Salts, Herbal, Others |
| Companies Covered | Johnson & Johnson Services, Inc., Haleon Group of Companies, Perrigo Company plc, Pfizer Inc., Cipla Ltd., GlaxoSmithKline plc, GLENMARK PHARMACEUTICALS LTD., Fertin Pharma, Imperial Brands plc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Nicotine Replacement Product Market Trends and Innovations
Delivery system miniaturization and connected health integration are redefining how nicotine replacement products interface with patient behavior, shifting competitive advantage toward data-capture capabilities and adherence engineering.
Micro-needle array patches are modularizing transdermal delivery architecture by enabling programmable nicotine release curves matched to individual withdrawal pharmacokinetics. Smoking cessation clinics in Germany and the Netherlands are piloting these systems for patients with rapid metabolizer phenotypes. The technology is modularizing how manufacturers segment patient populations, compressing the historical one-size-fits-all patch paradigm into precision-dosing platforms.
EMA's Medical Device Regulation recalibration is reclassifying certain inhaler devices as drug-device combinations, triggering additional clinical evidence requirements for products previously cleared under simpler pathways. Manufacturers with existing pharmaceutical portfolios absorb these costs more readily than pure-play device entrants. The inhaler segment faces the steepest compliance burden, with several products undergoing supplemental marketing authorization reviews.
Subscription-based replenishment models are displacing episodic pharmacy purchases among digitally engaged demographics, particularly in urban United States markets where convenience prioritization outweighs price sensitivity. These programs bundle behavioral support content with automated product delivery, capturing patient relationship data that retail channels forfeit. The shift is most pronounced among adults aged 25-40 attempting first cessation attempts.
Nicotine Replacement Product Market Segmentation
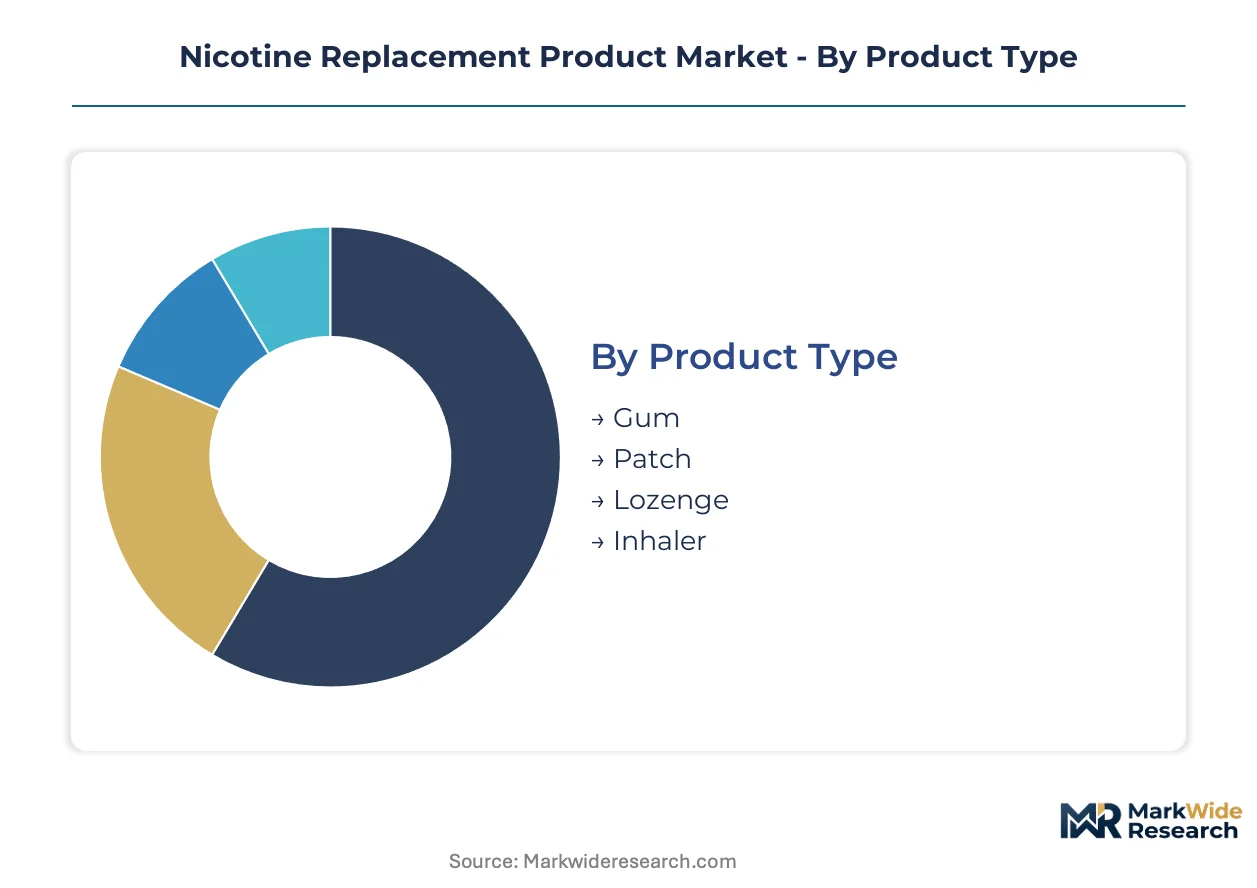
Segmentation in nicotine replacement products determines reimbursement pathways, manufacturing scale requirements, and patient adherence engineering. Each dimension—product format, delivery biology, user profile, and chemical formulation—creates distinct regulatory, pricing, and distribution constraints that shape competitive positioning.
Product Type:
Standalone formats dominate pharmacy and retail channels with established dosing protocols, while embedded combination regimens require clinical coordination and prescription integration.
- Patch:Transdermal systems employ layered acrylic adhesives and reservoir membranes to sustain steady-state plasma nicotine across 16-24 hour wear cycles. Demand concentrates in United States employer wellness programs where extended-release pharmacokinetics align with workplace adherence patterns.
- Gum:Polacrilex resin matrices enable buccal absorption with user-controlled dosing frequency, making this format the volume leader in Brazil and Mexico where cold-chain infrastructure remains limited and pharmacy density is sparse.
- Lozenge:Dissolvable hard candy formulations with buffered pH systems reduce throat irritation compared to gum; these serve patients with dental work restrictions or jaw fatigue concerns.
- Inhaler:Plastic cartridge devices with aerosolized nicotine vapor mimic hand-to-mouth behavioral rituals; this segment attracts psychological dependence-heavy users in German and Dutch smoking cessation clinics piloting precision protocols.
Patch leads volumes today; inhaler is gaining share fastest.
Delivery Mode:
Cost tier differentiation separates premium clinical-grade systems from mass-market over-the-counter formats, with reimbursement eligibility determining accessible price points.
- Transdermal:Skin-permeable nicotine delivery through adhesive patches achieves predictable pharmacokinetics with minimal user technique dependence; this mode commands premium pricing in private United States insurer formularies.
- Oral:Buccal and gastrointestinal absorption through gum and lozenge formats requires repeated dosing but offers user titration control; oral systems dominate emerging market volume due to ambient storage stability and minimal distribution infrastructure requirements.
- Inhalation:Pulmonary and oropharyngeal deposition through metered aerosol devices delivers rapid nicotine onset mimicking cigarette arterial spike profiles; EMA Medical Device Regulation recalibration is elevating compliance costs for this delivery pathway.
- Buccal:Direct mucosal absorption through films, tablets, and sublingual strips bypasses first-pass hepatic metabolism; buccal formats remain niche outside Scandinavian markets with established smokeless tobacco transition histories.
Oral delivery leads volumes today; inhalation is expanding most quickly.
Consumer Type:
Application context—clinical cessation versus harm reduction versus prevention—determines dosing strength, behavioral support bundling, and channel strategy.
- Smokers:Active tobacco users seeking complete cessation represent the core clinical indication for all pharmacotherapy formats; this population drives combination therapy protocol adoption in United States integrated health systems.
- Ex-Smokers:Former tobacco users managing relapse risk through maintenance dosing or situational craving control; ex-smoker demand sustains subscription replenishment models in urban United States markets among digitally engaged demographics.
- Dual Users:Concurrent tobacco and NRT consumers attempting gradual reduction rather than abrupt cessation; dual use patterns concentrate in European markets with permissive reduced-risk product frameworks.
- Non-Smokers:Nicotine-naive populations occasionally targeted for cognitive enhancement or appetite suppression; non-smoker segments face regulatory restriction in FDA jurisdictions and limited commercial viability.
Smokers lead volumes today; ex-smokers are climbing the fastest.
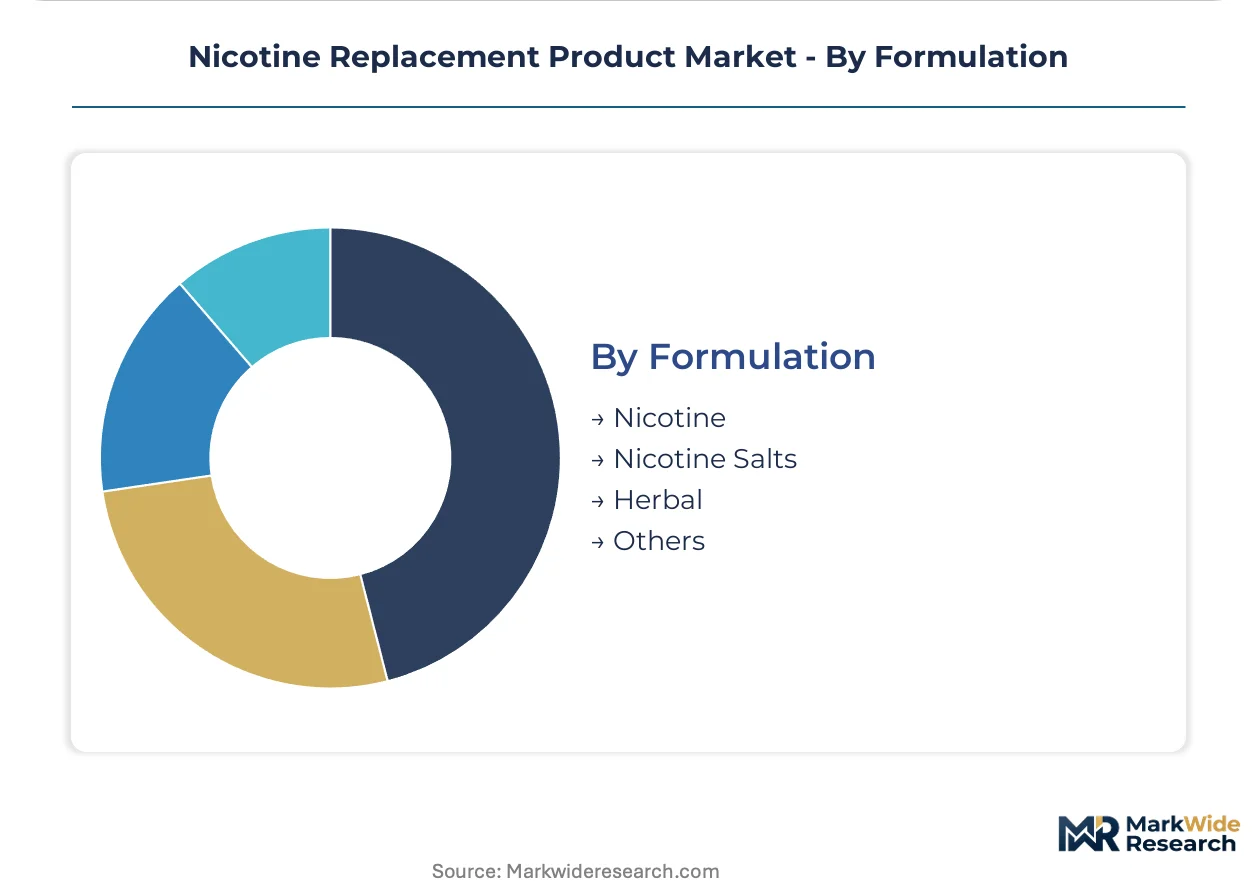
Formulation:
Maturity stage and supply concentration differentiate established pharmaceutical-grade nicotine from emerging alternatives with uncertain regulatory standing.
- Nicotine:Tobacco-derived freebase nicotine remains the standard pharmacotherapy active ingredient with decades of safety documentation and established manufacturing supply chains; this formulation anchors all major branded portfolios.
- Nicotine Salts:Protonated nicotine formulations with organic acid counterions enable higher concentration delivery with reduced throat harshness; salt formulations face classification uncertainty as FDA evaluates synthetic versus tobacco-derived sourcing distinctions.
- Herbal:Non-nicotine botanical preparations including lobeline, cytisine, and various plant extracts; herbal alternatives occupy fringe positions outside Eastern European markets with traditional cytisine acceptance.
- Others:Emerging delivery technologies including micro-encapsulated nicotine, nanoparticle suspensions, and prodrug formulations; these experimental categories remain pre-commercial in most regulatory jurisdictions.
Nicotine leads volumes today; nicotine salts show the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Transdermal nicotine patches achieved commercial scale in the United States during the early 1990s, establishing the regulatory and reimbursement templates that later diffused to European and Asia-Pacific markets. Workplace wellness programs and private insurer formularies now sustain volume concentration in North America, while emerging markets favor oral formats suited to limited pharmacy infrastructure.
United States
Employer-sponsored health plans drive demand through preventive care formularies covering over-the-counter patches and gums. FDA drug-device combination pathways govern all product approvals, with New Drug Application timelines constraining new entrant speed. Smoking cessation clinics in the Boston and Minneapolis metropolitan areas pilot combination therapy protocols pairing patches with behavioral coaching.
Germany
Statutory health insurance funds reimburse prescription nicotine replacement products, creating stable demand from clinical cessation programs. EMA centralized marketing authorization procedures and REACH excipient safety standards elevate compliance costs for manufacturers. Micro-needle array patch trials operate through university hospital networks in Berlin and Heidelberg, targeting rapid metabolizer patient subgroups.
Brazil
Limited retail pharmacy density and ambient storage requirements favor gum and lozenge formats over cold-chain-dependent alternatives. ANVISA pharmaceutical registration procedures govern import and domestic manufacturing, with registration timelines averaging 18-24 months. São Paulo and Rio de Janeiro metropolitan areas concentrate distribution infrastructure for multinational brand portfolios.
Japan
PMDA pharmaceutical approval pathways and stringent labeling requirements constrain product variety relative to Western markets. METI industrial policy supports domestic manufacturing capacity for transdermal adhesive technologies. Osaka-based pharmaceutical clusters specialize in modified-release formulations for the domestic smoking cessation market.
United Kingdom
NHS smoking cessation services provide subsidized access to patches, gum, and inhalers through pharmacy and primary care channels. MHRA post-Brexit regulatory autonomy maintains alignment with EMA standards while enabling faster national approval pathways for innovative formats. London and Manchester anchor clinical trial activity for next-generation delivery systems.
Nicotine Replacement Product Market Competitive Landscape
Premium-margin players sit above commodity-margin players across regulatory sophistication and clinical evidence depth, with transdermal patch portfolios commanding higher pricing power than generic oral formats. The vendor base stratifies into three tiers: diversified pharmaceutical conglomerates with legacy nicotine franchises, consumer health spin-offs focusing on retail distribution scale, and regional generics manufacturers supplying price-sensitive emerging markets. Dominant competitive moves include portfolio diversification into combination therapy bundles and strategic partnerships with digital therapeutics platforms to capture adherence data.
Within the diversified pharmaceutical tier, Johnson & Johnson Services, Inc. and Pfizer Inc. exemplify contrasting strategic positions—one anchored in over-the-counter transdermal heritage, the other adjacent through prescription pharmacotherapy. Haleon Group of Companies occupies the consumer health specialist archetype, having separated from pharmaceutical parentage to concentrate on retail channel scale and brand equity in oral formats. These three entities collectively represent the competitive spectrum from clinical-grade to mass-market positioning.
| Leading Market Players |
|---|
| Johnson & Johnson Services, Inc. |
| Haleon Group of Companies |
| Perrigo Company plc |
| Pfizer Inc. |
| Cipla Ltd. |
| GlaxoSmithKline plc |
| GLENMARK PHARMACEUTICALS LTD. |
| Fertin Pharma |
| Imperial Brands plc |
| Others |
Pricing and Supply Chain Analysis
Employer-sponsored health plans in the United States anchor procurement volume for nicotine replacement products, compressing transaction economics toward formulary-contract pricing models that reward scale and clinical evidence depth. This buyer concentration elevates compliance investment as a price-defensive mechanism while squeezing margin contribution from smaller manufacturers lacking dedicated toxicology departments.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels segments the nicotine replacement product landscape by clinical validation depth and channel positioning. Premium tiers command formulary placement through FDA New Drug Application pathways and combination therapy protocol adoption, while economy tiers compete on ambient storage stability for emerging market pharmacy channels. Price differentiation rests on REACH excipient documentation and EMA marketing authorization status, with acrylic adhesive input volatility compressing margin stability in transdermal formats. United States commercial payers exhibit lowest price sensitivity due to preventive care reimbursement mandates, whereas Brazilian retail pharmacy chains face acute cost pressure from limited cold-chain infrastructure.
Supply Chain Analysis
Single-source vulnerability sits with East Asian polacrilex resin manufacturers, where ion-exchange resin production clusters create concentrated dependency for oral gum and lozenge formulations. Raw material flows draw from petroleum-derived acrylic polymer suppliers in Japan and Germany for transdermal adhesives, alongside nicotine alkaloid extraction facilities in India and the United States. Tariff exposure on Chinese-sourced plastic inhaler components elevates landed cost uncertainty for device-format entrants. Distribution runs through wholesale-pharmacy relationships in developed markets, while direct-to-consumer subscription models clash with established channel structures in urban United States demographics.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market compounds regulatory legitimacy as FDA and EMA tighten nicotine labeling standards, with REACH compliance elevation paradoxically protecting established pharmacotherapy franchises from unregulated synthetic alternatives.
For Market Incumbents: Extend combination therapy bundling into employer wellness program formularies, pairing patch-and-lozenge protocols with adherence-tracking digital platforms to capture patient relationship data that retail channels forfeit. Deepen backward integration into polacrilex resin supply through captive manufacturing partnerships in India, insulating margin stability from East Asian chemical cluster concentration risk.
For New Entrants and Emerging Players: The price-point gap between premium FDA-approved transdermal systems and economy oral formats in Brazil and Mexico presents viable white-space entry through gum and lozenge SKUs requiring minimal cold-chain handling. Target pharmacy infrastructure gaps in São Paulo and Rio de Janeiro metropolitan distribution networks, leveraging ambient storage stability as the core go-to-market wedge against patch-format incumbents.
For Investors and Strategic Acquirers: Consumer health conglomerates with legacy nicotine franchises are the most active acquirer in this space, seeking digital therapeutics adjacency to differentiate commoditized hardware. Long-term viability favors targets with existing EMA marketing authorizations and REACH toxicology documentation, as regulatory reclassification risk around synthetic nicotine threatens asset writedowns. Watch FDA classification debates on non-tobacco-derived nicotine sources as the critical inflection signal for portfolio reallocation.
| Strategic Initiative | Industry Significance |
|---|---|
| Combination Therapy Protocol Expansion | Paired patch-and-lozenge regimens improve quit rates and expand average transaction values in United States employer wellness programs. |
| Digital Therapeutics Convergence | Mobile cessation coaching applications paired with connected dosing devices create adherence-tracking ecosystems that differentiate commoditized hardware. |
| REACH Compliance Investment | Dedicated toxicology departments and excipient safety documentation elevate barriers to unregulated alternatives, legitimizing established pharmacotherapy options. |
| Micro-Needle Array Patch Development | Programmable nicotine release curves matched to individual withdrawal pharmacokinetics enable precision-dosing platforms for rapid metabolizer subgroups. |
| Subscription-Based Replenishment Models | Automated product delivery with behavioral support content captures patient relationship data that traditional wholesale-pharmacy channels forfeit. |
Research Methodology
Coverage spans North America, Europe, Latin America, and Asia-Pacific, with primary inputs from each region combining structured interviews with regulatory affairs leads at multinational pharmaceutical manufacturers, formulary directors at United States commercial payers, and procurement managers at Brazilian retail pharmacy chains. Secondary validation draws from FDA New Drug Application filings, EMA centralized marketing authorization procedures, ANVISA pharmaceutical registration databases, and trade flow records for polacrilex resin and acrylic adhesive raw materials. Bottom-up demand modeling triangulates against top-down macroeconomic projections across the analysis window.
Rate-of-change decomposition separates volume growth from pricing dynamics across product format, delivery mode, consumer type, and formulation segmentation dimensions. CAGRs derive from patient population epidemiology, reimbursement pathway expansion trajectories, and regulatory approval timeline assumptions throughout the forecast period. Industry-specific inputs include workplace wellness program adoption rates in United States employer-sponsored health plans and EMA Medical Device Regulation recalibration impacts on inhaler device classification.
Caveats apply where synthetic nicotine reclassification or REACH excipient standard revisions could materially shift the outlook for manufacturing cost structures and marketing authorization eligibility. Forecasts reflect documented assumptions about private insurer formulary expansion and employer preventive care benefit design. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Montelukast Market
Pharmaceuticals
Filgrastim Market
Pharmaceuticals
Stanozolol Market
Pharmaceuticals
Authorized Generics Market
Pharmaceuticals
Saudi Arabia Insulin Drugs and Delivery Devices Market
Pharmaceuticals
Schizophrenia Drugs Market
Pharmaceuticals
Global Pharmerging Market
Pharmaceuticals
Brazil Diabetes Drugs Market
Pharmaceuticals
MRI Contrast Media Agents Market
Pharmaceuticals
Global Vaccine Market
Pharmaceuticals
Dual Antiplatelet Therapy Market
Pharmaceuticals
Asia-Pacific Human Papillomavirus Vaccine Market
Pharmaceuticals
Hard Empty HPMC Capsule Market
Pharmaceuticals
Global Fondaparinux Market
Pharmaceuticals
Acetylspiramycin Market
Pharmaceuticals
Fibroblast Activation Protein Inhibitors Market