
 Radiographic Testing Market | 2026-2036
Radiographic Testing Market Size, Share, and Industry Trends Forecast 2026-2036
Radiographic Testing Market Analysis
China is narrowing its technology gap in radiographic testing equipment as domestic manufacturers scale production of digital detector arrays. Waygate Technologies leverages its industrial heritage to sustain leadership in high-energy X-ray systems for heavy fabrication. Fujifilm Holdings Corporation anchors its position through proprietary digital imaging plates that compete on sensitivity and durability. Mistras Group specializes in integrated inspection services, extending its reach from equipment supply to full asset integrity management for energy clients.
Radiographic testing employs ionizing radiation to detect internal discontinuities in materials without causing damage, typically using X-ray sources operating between 10 keV and 15 MeV depending on material thickness and density. The method generates grayscale images where density variations reveal cracks, porosity, or inclusions critical to safety-critical structures. Digital radiography is displacing film-based methods across aerospace and oil and gas end users as real-time imaging and elimination of chemical processing reduce inspection cycle times. Film radiography retains a stable position in jurisdictions with legacy regulatory acceptance frameworks and in applications requiring archival traceability. X-ray sources represent the most concentrated margin pool within equipment types due to the specialized engineering and safety certification barriers protecting incumbent suppliers.
The FAA and EASA enforce stringent airworthiness directives that mandate periodic radiographic inspection of turbine components and airframe welds, creating structural demand from aerospace end users. OSHA and EPA regulations in the United States govern radiation safety and chemical waste disposal, shaping capital allocation between digital and film-based systems. ISO 17636 and ASTM E94 provide international benchmarking for weld inspection procedures, influencing procurement specifications across industrial manufacturers. Stakeholders must monitor evolving AI-assisted defect recognition standards and decide whether to build in-house algorithmic capabilities or partner with specialized software vendors.
Market Dynamics
Digital radiography is compressing inspection cycle times while regulators in aerospace and energy sectors tighten defect-detection mandates, forcing capital reallocation from film-based systems toward real-time imaging infrastructure.
Growth Catalysts
- FAA and EASA airworthiness directives:Mandated turbine component inspection creates structural demand from aerospace manufacturers in the United States and Germany.
- Pipeline integrity management:Refinery turnaround cycles in Texas and Louisiana sustain heavy investment in weld inspection services for energy infrastructure.
- Digital detector array scaling:Domestic manufacturers in China are narrowing technology gaps and expanding production capacity for flat-panel detectors.
Market Restraints
- X-ray source supply concentration:Specialized engineering and safety certification barriers protect a limited pool of incumbent suppliers in Japan and Germany.
- Legacy regulatory acceptance frameworks:Film radiography retains position in jurisdictions with archival traceability requirements that delay digital adoption.
- High-purity selenium and germanium input costs:Digital detector manufacturing depends on semiconductor-grade materials subject to price volatility.
Strategic Opportunities
- AI-assisted defect recognition standards:Emerging algorithmic capabilities create white space for software vendors to partner with inspection houses.
- Offshore wind foundation inspection:North Sea and Baltic Sea installations require subsea weld verification using portable radiographic systems.
- India's PLI scheme for advanced manufacturing:Domestic production incentives for precision engineering are expanding NDT service demand in Gujarat and Tamil Nadu.
Industry Challenges
- Radiation safety officer certification timelines:OSHA and state-level licensing requirements create bottlenecks for inspection workforce expansion in the United States.
- ISO 17636 procedure harmonization:Divergent national implementations of weld inspection standards complicate multinational qualification protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Radiographic Testing Market |
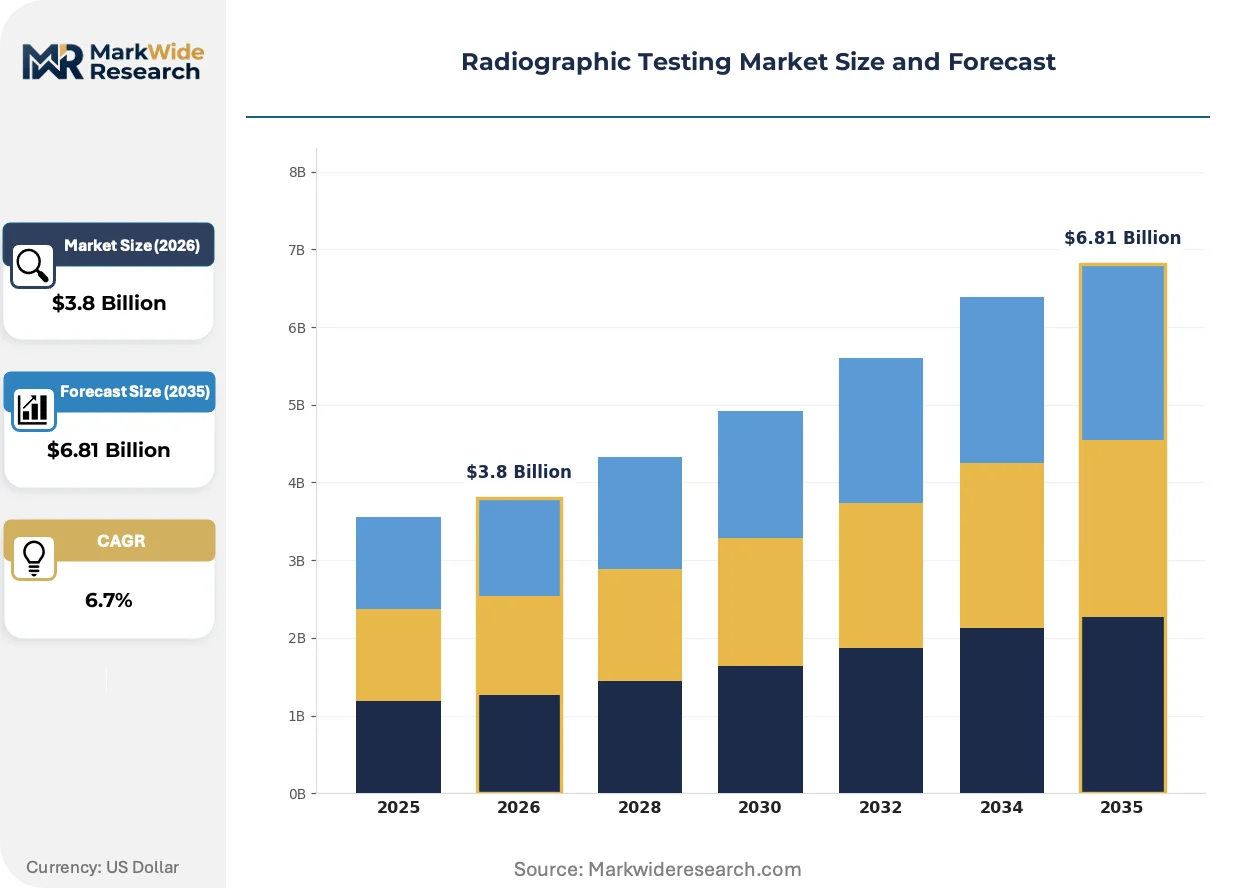
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technique: X-Ray, Computed Radiography, Digital Radiography, Film Radiography End User: Industrial Manufacturers, Aerospace, Oil & Gas, Construction Application: Quality Control, Structural Integrity, Weld Inspection, Non-Destructive Testing Equipment Type: Radiographic Film, Imaging Systems, X-Ray Sources, Scanner Systems |
| Companies Covered | TÜV Rheinland, Mistras Group, SGS, Waygate Technologies, Element Materials Technology, Bureau Veritas, Applus+, Fujifilm Holdings Corporation, Intertek, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Radiographic Testing Market Emerging Trajectories
Computed tomography is penetrating thick-section inspection while regulatory pressure on chemical processing accelerates digital adoption across heavy fabrication and energy verticals.
Computed radiography is hybridizing phosphor plate technology with digital workflow integration, allowing inspection houses in Germany and Japan to bridge legacy film protocols with automated archiving. Aerospace MRO providers in France and the United Kingdom are adopting these transitional systems to satisfy EASA traceability requirements without full detector array investment. The technology is hybridizing quality assurance documentation, compressing the gap between analog inspection heritage and fully digital infrastructure.
REACH chemical restrictions on silver halide processing effluents are forcing European inspection houses to eliminate wet chemistry from radiographic workflows. Industrial service providers in the Netherlands and Belgium face accelerated capital replacement cycles as environmental compliance deadlines approach. The regulation is reshaping equipment procurement specifications, with rental and lease structures displacing outright purchase for mid-size fabrication shops.
Inspection service unbundling is fragmenting traditional equipment-plus-operator contracts into discrete hardware, software, and analysis components. Energy sector buyers in Texas and Alberta are separating detector procurement from interpretive services, pressuring OEM margins while opening specialist algorithm vendors. This pattern is concentrating most visibly in pipeline integrity programs where internal engineering teams assume image analysis responsibility.
Radiographic Testing Market Segmentation
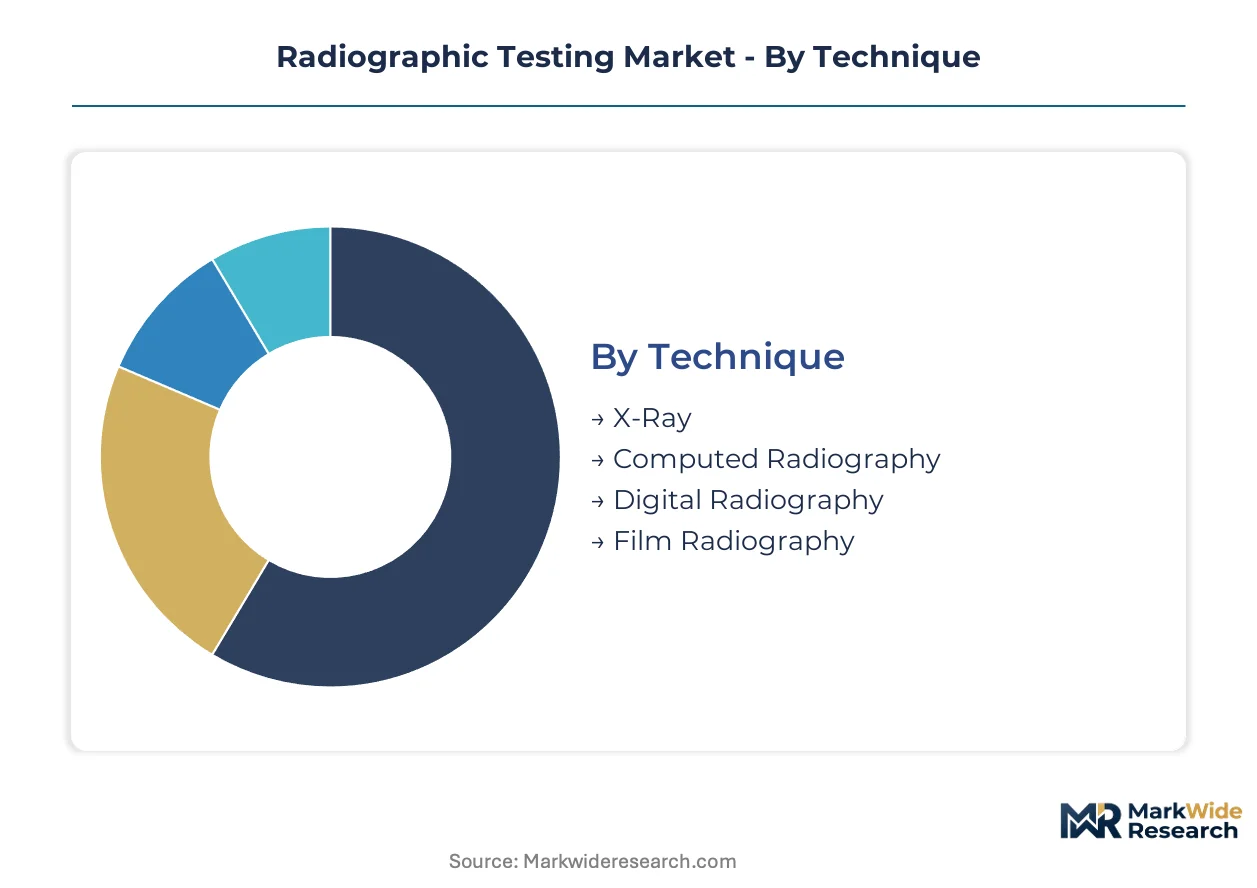
Radiographic testing equipment generates substantial recurring revenue through detector replacement cycles, software licensing, and calibration services. Segmentation reveals how after-sales intensity varies across technique maturity and equipment complexity. Understanding these patterns helps vendors allocate service infrastructure and pricing models.
Technique:
After-sales service intensity peaks with digital radiography systems requiring annual calibration, software updates, and detector panel replacements every 5-7 years. Computed radiography demands moderate service touchpoints for phosphor plate refurbishment. Film-based methods minimize ongoing vendor engagement outside chemical supply logistics.
- X-Ray:High-energy sources operating between 10 keV and 15 MeV penetrate dense steel sections in heavy fabrication. Demand concentrates in German and Japanese shipyards where thick-section weld verification dominates inspection protocols. Specialized tube replacement cycles and radiation safety certification create captive service relationships.
- Digital Radiography:Flat-panel detector arrays capture real-time grayscale images without chemical processing. Aerospace manufacturers in the United States and France are displacing film methods to meet compressed FAA and EASA turnaround mandates. Detector panel fragility and firmware dependencies sustain premium service contracts.
- Computed Radiography:Phosphor imaging plates bridge analog capture with digital workflow integration. European inspection houses in the Netherlands and Belgium adopt these systems to satisfy REACH chemical restrictions while preserving archival traceability. Plate erasure and reader maintenance generate predictable service revenue.
- Film Radiography:Silver halide emulsion sheets retain regulatory acceptance in jurisdictions with legacy qualification frameworks. Pipeline operators in Texas and Louisiana maintain film protocols for weld documentation subject to PHMSA archival requirements. Chemical supply and processor maintenance represent minimal service attachment.
Digital radiography holds the largest share; momentum sits with computed radiography as a transitional bridge for regulated industries.
End User:
Cost tier stratification separates capital-intensive aerospace programs from price-sensitive construction contractors. Volume concentration and procurement sophistication determine margin capture across these verticals.
- Industrial Manufacturers:Automated production lines integrate inline radiographic stations for casting and forging verification. Automotive powertrain plants in Germany and Japan deploy high-throughput systems with robotic part handling. Preventive maintenance contracts and throughput guarantees dominate commercial terms.
- Aerospace:Turbine blade and airframe weld inspection mandates create non-discretionary demand from OEMs and MRO providers. Boeing and Airbus supply chains in Washington State and Toulouse specify digital radiography for defect traceability. Regulatory qualification overhead elevates service intensity and supplier switching costs.
- Oil & Gas:Refinery turnaround cycles and pipeline integrity management programs sustain project-based inspection demand. Gulf Coast operators in Texas and Louisiana contract weld verification services during scheduled maintenance windows. Rental equipment models predominate given intermittent utilization patterns.
- Construction:Structural steel fabrication and precast concrete verification drive portable system deployment. Infrastructure projects in India and Saudi Arabia adopt radiographic testing for bridge and high-rise weld quality assurance. Price competition and equipment rental favor low-service-intensity procurement.
Aerospace commands premium pricing; construction is expanding most quickly in emerging infrastructure markets.
Application:
Customer type differentiation separates integrated asset owners from outsourced inspection service providers. Procurement authority and technical capability shape vendor relationships across these use cases.
- Quality Control:Foundry and forging operations employ radiographic testing to detect porosity, shrinkage, and inclusion defects before machining. German automotive suppliers integrate inline inspection for powertrain component release. Real-time feedback loops minimize scrap and rework costs.
- Structural Integrity:Bridge, pressure vessel, and offshore platform assessment requires periodic re-inspection over asset lifecycles. North Sea wind farm operators in the United Kingdom and Denmark deploy subsea radiographic systems for foundation weld monitoring. Long-term service agreements align vendor incentives with asset performance.
- Weld Inspection:Pipeline girth welds and pressure vessel seams represent the largest application volume by inspection count. PHMSA regulations in the United States mandate 100% radiographic coverage for high-consequence area pipelines. Technician certification bottlenecks constrain service capacity expansion.
- Non-Destructive Testing:General NDT service providers offer radiographic testing alongside ultrasonic and eddy current methods. Independent inspection houses in Japan and South Korea compete on turnaround time and digital reporting capabilities. Equipment utilization rates drive profitability in fragmented competitive landscapes.
Weld inspection holds the largest share; structural integrity is gaining share fastest from offshore wind deployment.
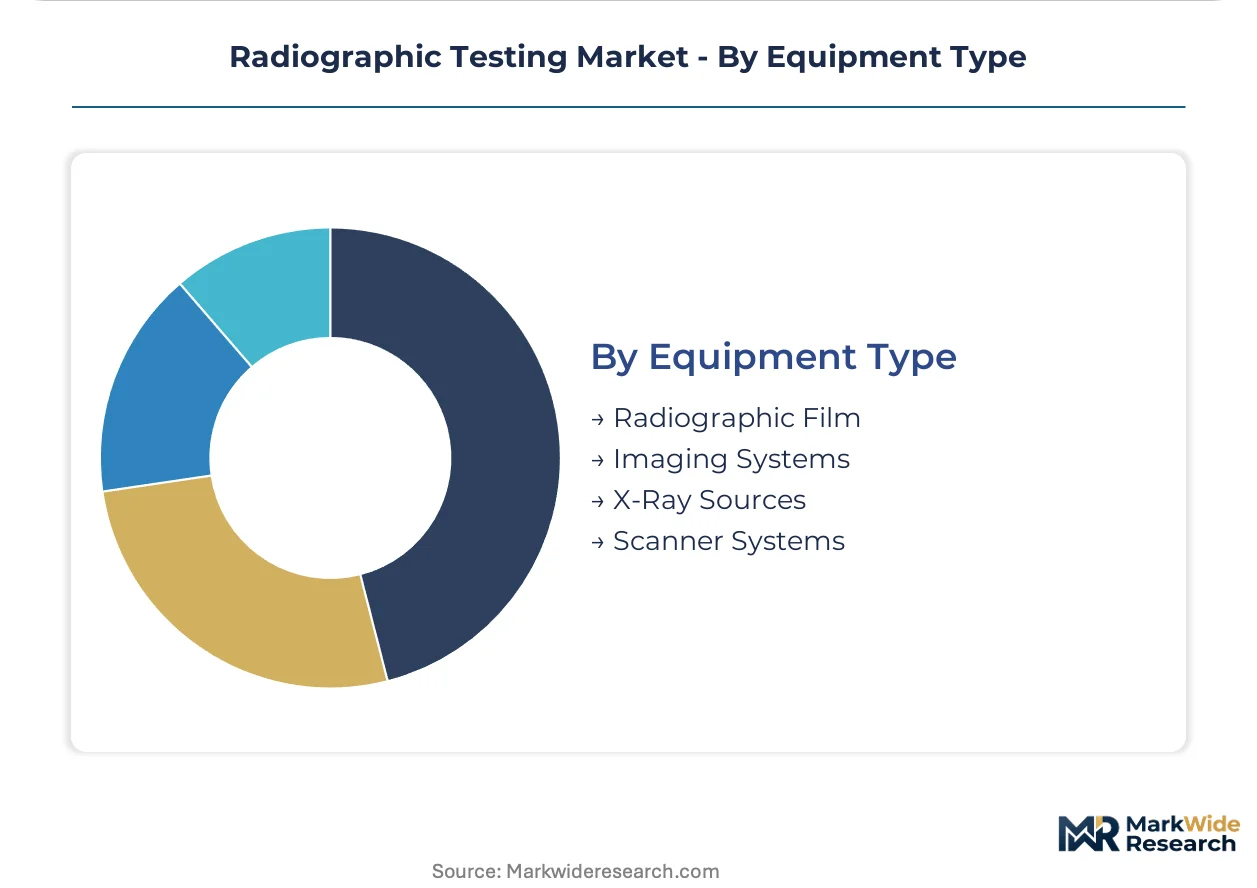
Equipment Type:
Supply concentration varies dramatically across equipment categories, with X-ray source manufacturing protected by specialized engineering barriers while scanner assembly faces commoditization pressure.
- Radiographic Film:Silver halide emulsion sheets in standard and high-resolution grades serve legacy inspection protocols. Agfa and Fujifilm production facilities in Belgium and Japan supply global demand. Declining volume concentrates procurement power among remaining large-scale users.
- Imaging Systems:Detector arrays, phosphor plate readers, and digital acquisition software form integrated capture platforms. Flat-panel manufacturers in South Korea and China are narrowing technology gaps with Japanese and German incumbents. Software licensing and detector replacement sustain recurring revenue.
- X-Ray Sources:Sealed tubes and linear accelerators generate ionizing radiation across energy ranges. Specialized ceramics and vacuum engineering protect a limited supplier base in Japan and Germany. Tube replacement cycles and safety recertification create high-margin service opportunities.
- Scanner Systems:Automated part handling, robotic positioning, and conveyor integration enable high-throughput inspection. Automotive and aerospace tier-one suppliers in the United States and Germany specify custom configurations. System integration complexity elevates project-based service revenue.
Imaging systems hold the largest share; X-ray sources show the steepest expansion trajectory from security and industrial demand convergence.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply across geographies: aerospace mandates in the United States and Germany prioritize digital detector sensitivity, while pipeline operators in China and India balance regulatory compliance against capital constraints.
United States
Pipeline integrity programs and refinery turnaround cycles sustain weld inspection demand across Texas and Louisiana. PHMSA regulations mandate 100% radiographic coverage for high-consequence area pipelines, creating structural service requirements. Houston hosts the densest concentration of independent inspection contractors serving Gulf Coast energy infrastructure.
Germany
Automotive powertrain plants and shipyards in Hamburg and Bremen deploy high-throughput systems for thick-section verification. REACH chemical restrictions on silver halide processing effluents accelerate digital adoption among Dutch and Belgian service providers operating near German borders. Bavarian industrial clusters integrate inline radiographic stations for casting quality assurance.
China
Domestic manufacturers scale production of flat-panel detectors, narrowing technology gaps with Japanese and German incumbents. The country's national standards regulator publishes updated non-destructive testing protocols aligning with ISO benchmarks. Yangtze River Delta fabrication centers adopt portable radiographic systems for infrastructure weld verification.
Japan
Specialized ceramics and vacuum engineering capabilities protect a concentrated supplier base for high-energy X-ray sources. METI industrial standards govern radiation safety certification for fabrication facilities in Nagoya and Osaka. Automotive tier-one suppliers in Aichi Prefecture specify automated scanner configurations with robotic part handling.
India
Domestic production incentives under the PLI scheme expand precision engineering capacity in Gujarat and Tamil Nadu. The Bureau of Indian Standards mandates weld inspection protocols for bridge and high-rise construction projects. Mumbai-Pune industrial corridors attract NDT service providers targeting infrastructure quality assurance contracts.
Radiographic Testing Market Vendor Landscape
Capability concentration sits with specialized X-ray source manufacturers protected by vacuum engineering barriers; scale advantage sits with diversified inspection service houses operating across multiple geographies. The market structures around three tiers: integrated asset integrity managers, equipment-focused technology vendors, and regional inspection contractors. Strategic moves center on detector array partnerships and service unbundling into discrete hardware, software, and analysis components.
Within the diversified inspection services tier, Mistras Group and Element Materials Technology exemplify asset integrity managers extending from equipment supply to full lifecycle monitoring. Waygate Technologies occupies a position among industrial heritage technology vendors leveraging high-energy system expertise. Fujifilm Holdings Corporation anchors the imaging technology segment through proprietary digital plate development.
| Leading Market Players |
|---|
| TÜV Rheinland |
| Mistras Group |
| SGS |
| Waygate Technologies |
| Element Materials Technology |
| Bureau Veritas |
| Applus+ |
| Fujifilm Holdings Corporation |
| Intertek |
| Others |
Supply Flow & Price Mechanics
Overcapacity in Chinese flat-panel detector manufacturing is compressing margins across mid-tier digital radiography systems while elevating pricing power for specialized X-ray source suppliers in Japan and Germany. This utilization asymmetry rewards inspection houses that lock in long-term service contracts with OEMs facing detector replacement cycles.
Pricing Analysis
Project-based contracting dominates weld inspection services for Gulf Coast energy infrastructure, while subscription licensing anchors software-dependent digital radiography platforms. Price differentiation separates FAA-certified aerospace systems from standard industrial configurations. Cost compression in portable detector arrays intensifies as Chinese manufacturers scale production. Construction contractors in India exhibit highest price sensitivity, whereas aerospace MRO providers in France accept premium pricing for regulatory qualification overhead.
Supply Chain Analysis
Tariff exposure between the United States and China disrupts flat-panel detector procurement for mid-size inspection houses. Manufacturing concentrates in Japan, Germany, and South Korea for high-energy X-ray sources and vacuum tubes. Digital detector production draws from semiconductor-grade selenium and germanium supplies subject to price volatility. Single-source vulnerability persists for specialized ceramics used in tube housings. Distribution runs through authorized service networks rather than direct OEM sales for safety-critical equipment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat arena where regulatory entrenchment protects incumbents. FAA and EASA qualification protocols create switching costs that lock aerospace end users into established supplier relationships.
For Market Incumbents: Entrench position through captive control over detector refurbishment capacity in Texas and Louisiana energy corridors. Deepen backward integration into phosphor plate manufacturing to offset REACH-driven chemical processing restrictions. Emerging Chinese flat-panel producers threaten mid-tier pricing; respond with premium service bundling for aerospace qualification overhead. For New Entrants and Emerging Players: India's PLI scheme for precision engineering in Gujarat and Tamil Nadu represents the most penetrable entry point for inspection service expansion. Subsea weld verification for North Sea offshore wind foundations offers specialized equipment deployment opportunities. Partner with established algorithm vendors for AI-assisted defect recognition rather than building proprietary capabilities. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across portable digital radiography as detector manufacturing scales. Long-term viability favors asset-light inspection service models over equipment-heavy OEM positions. Target regional contractors with established radiation safety officer certification pipelines. Monitor FAA adoption timelines for AI-assisted defect recognition standards as inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Detector Array Partnership | Flat-panel supply agreements with Chinese manufacturers reduce procurement costs for mid-tier inspection houses. |
| AI Defect Recognition Licensing | Algorithm vendors gain foothold as EASA evaluates automated interpretation standards for turbine blade inspection. |
| Subsea Equipment Certification | Portable system validation for North Sea offshore wind expands addressable market for foundation weld monitoring. |
| Radiation Safety Training Expansion | OSHA-compliant certification programs alleviate technician bottlenecks constraining Gulf Coast service capacity. |
| Phosphor Plate Manufacturing Scale-Up | Computed radiography bridge products satisfy REACH restrictions while preserving archival traceability for European clients. |
Methodological Framework
A standing panel of NDT service directors, radiation safety officers, aerospace quality assurance managers, and energy sector procurement leads provided ongoing calibration throughout the study. Primary interviews with equipment OEMs and inspection contractors combined with secondary validation against FAA airworthiness directives, EASA certification protocols, PHMSA pipeline regulations, and ISO 17636 weld inspection standards. Bottom-up equipment shipment analysis and top-down end-user spending estimates underwent iterative reconciliation.
Scenario-bracketing around digital adoption rates and regulatory timeline variations shaped projections across the analysis window. Segmentation dimensions modeled include technique maturity, end-user vertical, application type, and equipment complexity tier. CAGRs derived from equipment replacement cycle analysis and service contract renewal patterns. Forecast inputs incorporated refinery turnaround schedules and offshore wind installation pipelines.
Practitioners should monitor FAA AI-assisted defect recognition standard finalization and REACH chemical restriction enforcement deadlines for early signals. Forecasts reflect assumptions regarding regulatory adoption timelines and detector manufacturing scale trajectories. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Testing Services
Global Forensic Testing Services Market
Testing Services
Global Cholesterol Testing Products and Services Market
Testing Services
Mycological Testing Market
Testing Services
Fecal Occult Testing Market
Testing Services
Hemotransmissive Infections Testing Market
Testing Services
Global Immunoprecipitation Testing Market
Testing Services
Global Newborn Screening Market
Testing Services
Procalcitonin Reagent Test Kit Market
Testing Services
Active B12 Test Market
Testing Services
Influenza a/B Combo Testing Market
Testing Services
Hospital Acquired Disease Testing Market
Testing Services
Endocrine Peptides Test Market
Testing Services
Medical Device Testing Services Market
Testing Services
Aerospace and Life Sciences TIC Market
Testing Services
North America Newborn Screening Market
Testing Services
Blood Pressure Test Market