
 Blood Sugar Tester Market | 2026-2036
Blood Sugar Tester Market Size, Share, and Industry Trends Forecast 2026-2036
Blood Sugar Tester Market Analysis
Homecare patients are redrawing procurement patterns for blood sugar testers as remote patient monitoring programs expand reimbursement for self-use devices. Abbott Laboratories leverages integrated sensor-to-app ecosystems that sustain recurring revenue streams. DexCom, Inc. anchors its position through continuous glucose monitor specialization and direct-to-consumer channel control. Medtronic competes via diabetes care platform breadth that extends beyond monitoring into insulin delivery coordination.
A blood sugar tester is a diagnostic device that measures glucose concentration in capillary blood or interstitial fluid, typically employing electrochemical enzymatic reactions with precision thresholds of ±15% per ISO 15197 standards for clinical reliability. Its primary purpose is enabling glycemic management decisions by patients and clinicians to prevent hypo- and hyperglycemic events. Continuous glucose monitors command premium positioning due to real-time data streams and reduced fingerstick burden, while fingerstick meters occupy economy tiers through pharmacy and supermarket volume distribution. Electrochemical technology dominates manufacturing scale and cost efficiency, though biosensor platforms represent the fastest-growing segment as non-invasive optical prototypes advance toward commercial validation.
FDA 510(k) clearance requirements and ISO 15197 accuracy standards shape product development costs and timeline barriers for new market entrants across the United States and Europe. The EU MDR reclassification of glucose monitoring devices intensifies clinical evidence demands and notified body capacity constraints for manufacturers seeking CE marking. Stakeholders must monitor reimbursement parity between continuous and intermittent monitoring modalities as health technology assessment bodies recalibrate value frameworks.
Market Dynamics
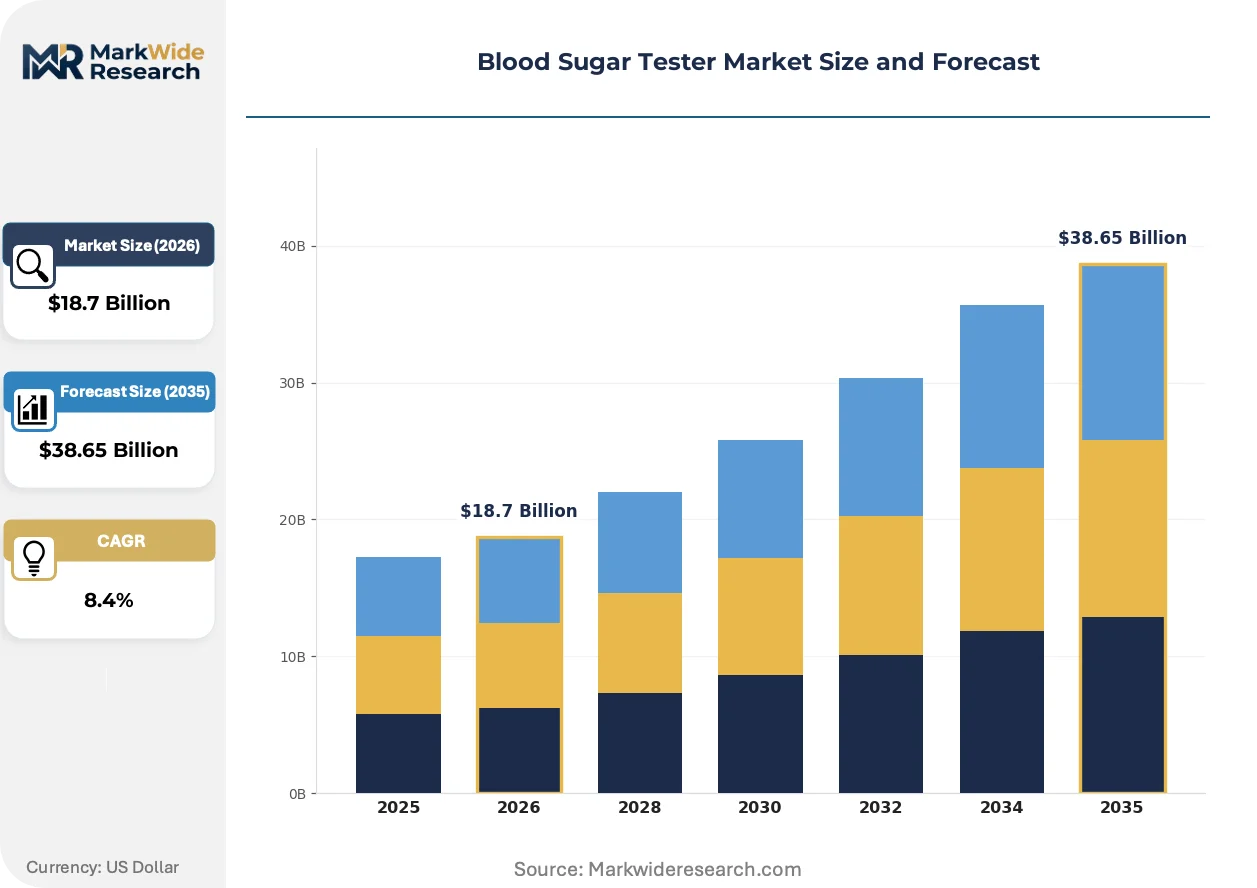
Reimbursement compression for fingerstick meters alongside expanding coverage for continuous glucose monitors is bifurcating device procurement across homecare and clinical channels, forcing manufacturers to recalibrate portfolio economics between premium sensor ecosystems and economy test strip volumes.
Growth Catalysts
- Homecare reimbursement expansion:CMS and private payers in the United States are extending coverage for self-monitoring devices under remote patient monitoring codes, accelerating patient-owned device procurement outside hospital settings.
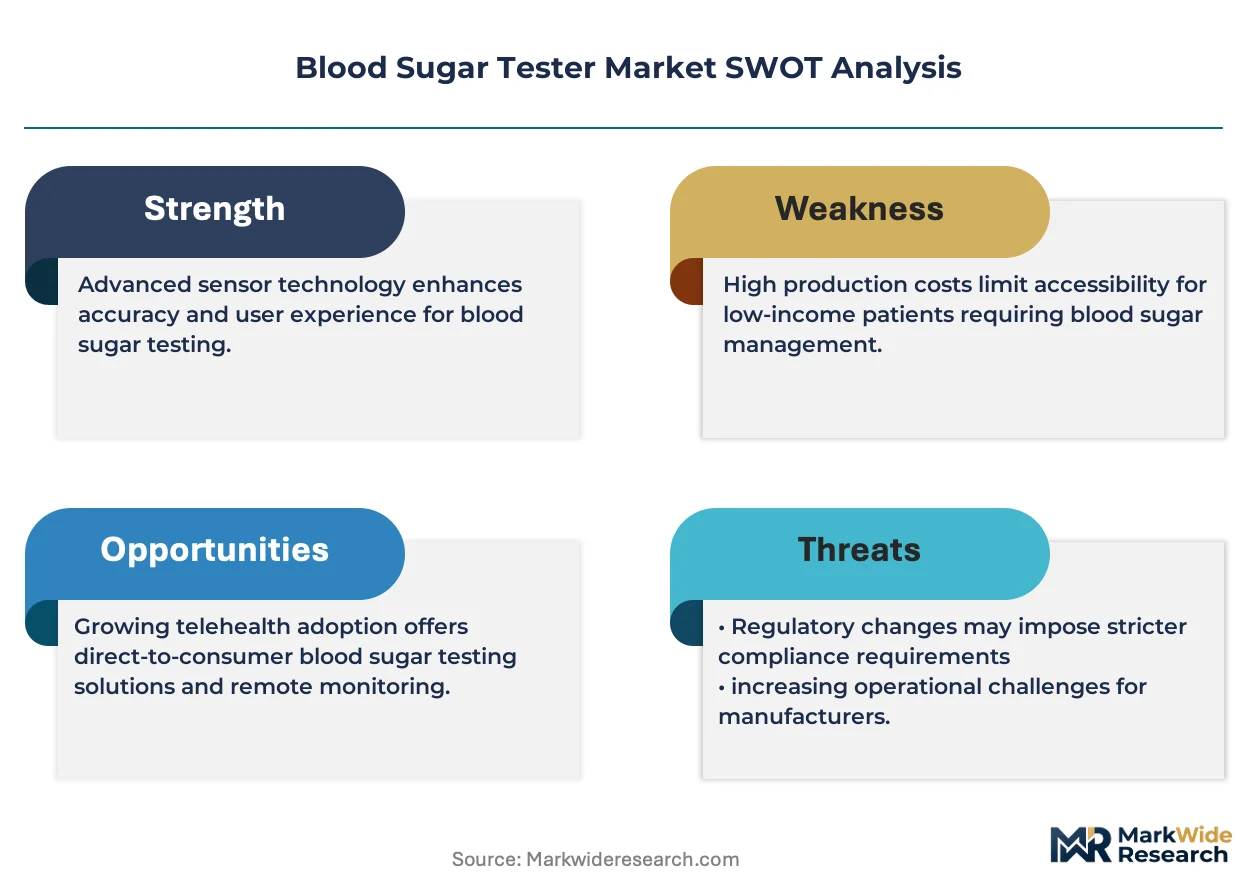
- EU MDR clinical evidence pathways:The reclassification of glucose monitoring devices under the EU Medical Device Regulation is streamlining post-market surveillance requirements for established manufacturers with robust clinical data portfolios.
- Optical biosensor maturation:Non-invasive glucose detection using near-infrared spectroscopy and photoacoustic methods is approaching ISO 15197 accuracy thresholds, opening regulatory clearance pathways previously blocked by electrochemical dominance.
Market Restraints
- Test strip commodity pricing:Volume purchasing contracts by pharmacy benefit managers in the United States have compressed margins on consumables to single-digit percentages, eroding profitability for manufacturers dependent on recurring strip revenue.
- Notified body capacity constraints:EU MDR implementation has created bottlenecks at designated conformity assessment bodies, extending CE marking timelines for glucose monitoring devices by 12-18 months versus prior Medical Device Directive cycles.
- Interstitial fluid lag limitation:Continuous glucose monitors measuring subcutaneous glucose concentrations exhibit physiological delays of 5-15 minutes versus capillary blood readings, restricting adoption in acute care settings requiring real-time glycemic precision.
Strategic Opportunities
- Underpenetrated rural India:The country's national diabetes screening program and Jan Aushadhi generic drug initiative are creating distribution infrastructure for affordable glucose meters in tier-3 cities and village health sub-centers.
- Insulin pump convergence:Integration of continuous glucose monitor data streams with automated insulin delivery algorithms is enabling closed-loop artificial pancreas systems that command premium positioning in Type 1 diabetes management.
- Direct-to-consumer channel expansion:Pharmacy bypass models using telehealth prescriptions and subscription-based sensor shipments are capturing patient lifetime value previously extracted by retail intermediaries.
Industry Challenges
- Biocompatibility engineering scarcity:Specialized expertise in long-wear adhesive formulations and minimally invasive microneedle arrays is concentrated among a limited pool of materials scientists, constraining sensor development timelines.
- FDA 510(k) predicate divergence:The Center for Devices and Radiological Health is increasingly requiring novel clinical studies for next-generation continuous glucose monitors citing substantial equivalence gaps with legacy electrochemical predicates.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Blood Sugar Tester Market |
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $38.65 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fingerstick, Continuous Glucose Monitor, Smart Glucose Meter, Portable Glucose Meter End User: Homecare, Hospitals, Diabetes Clinics, Long-Term Care Facilities Technology: Electrochemical, Optical, Non-Invasive, Biosensor Distribution Channel: Pharmacies, Online Retail, Supermarkets, Medical Supply Stores |
| Companies Covered | Abbott Laboratories, DexCom, Inc., Medtronic, F. Hoffmann-La Roche Ltd., Ascensia Diabetes Care Holdings AG, LifeScan IP Holdings, LLC, B. Braun SE, Sinocare, Terumo Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Blood Sugar Tester Market Emerging Trajectories
Non-invasive sensing modalities and algorithmic glucose prediction are displacing traditional enzymatic measurement architectures, while regulatory frameworks recalibrate safety thresholds for wearable biosensor permanence.
Optical glucose sensing using Raman spectroscopy and dielectric impedance measurement is fragmenting the historical electrochemical monopoly on accurate glucose quantification. Early-stage adopters in wellness and prediabetes management segments are piloting wrist-worn and ear-worn prototypes despite clinical accuracy gaps. This technological pluralism is compressing R&D timelines as venture funding flows toward multi-modal sensing approaches that bypass fingerstick calibration entirely.
The EU MDR reclassification of active implantable glucose sensors is tightening clinical evidence requirements for devices with >30-day wear durations. Manufacturers must now submit post-market follow-up data demonstrating adhesive biocompatibility and infection risk profiles across diverse skin types. Smaller notified bodies are withdrawing from glucose monitoring device certification, concentrating conformity assessment among high-capacity institutions in Germany and the Netherlands.
Patients with Type 2 diabetes are consolidating device selection authority through online peer communities and social media platforms, displacing traditional physician-directed prescribing patterns. Pharmacy chains are responding with private-label continuous glucose monitor partnerships that undercut branded sensor pricing by 30-40 percent. This channel disintermediation is most pronounced in the United States and United Kingdom, where direct-to-consumer advertising regulations permit patient-initiated brand awareness campaigns.
Blood Sugar Tester Market Segmentation
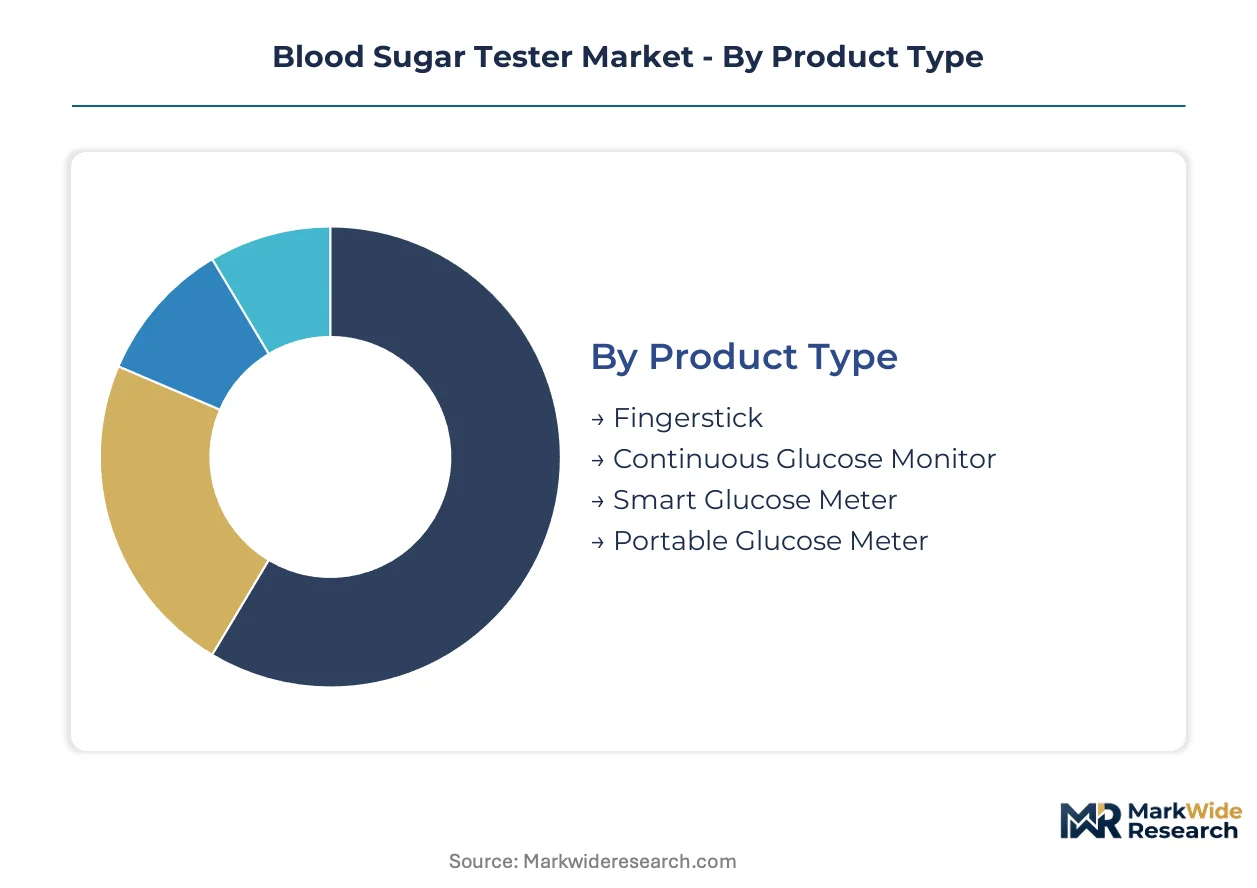
Channel economics and reimbursement pathways fragment the blood sugar tester market into distinct procurement ecosystems. Each segment category carries specific margin structures, regulatory burdens, and patient access dynamics that determine manufacturer portfolio priorities.
Product Type:
Channel mix varies sharply across device architectures, with continuous systems flowing through specialty distributors and fingerstick meters dominating pharmacy volume.
- Continuous Glucose Monitor:Subcutaneous sensor-to-transmitter systems measure interstitial glucose every 1-5 minutes with smartphone connectivity. Demand concentrates among Type 1 diabetes patients in Germany and the United States where private and public payers cover 80-100% of device costs under durable medical equipment benefits.
- Fingerstick:Portable electrochemical meters using enzymatic test strips remain the default for Medicare-covered Type 2 populations. Volume flows through retail pharmacy chains and supermarket health aisles, though reimbursement compression has shifted profitability toward private-label strip contracts.
- Smart Glucose Meter:Connected devices with cloud data integration and insulin dose calculators appeal to digitally engaged patients paying out-of-pocket for enhanced features.
- Portable Glucose Meter:Compact battery-operated units without connectivity target travel and backup use cases through medical supply stores and online channels.
By volume, fingerstick leads. By growth pace, continuous glucose monitor is ahead.
End User:
Cost tier stratification separates premium device procurement in institutional settings from economy-tier homecare adoption.
- Homecare:Self-monitoring patients purchase devices through retail and direct-to-consumer channels with varying insurance coverage. CMS remote patient monitoring codes now reimburse continuous glucose monitors for qualifying homebound beneficiaries, accelerating patient-owned sensor adoption.
- Hospitals:Acute care settings require capillary blood verification for insulin dosing decisions, sustaining demand for laboratory-grade meters with barcoding and EMR integration despite continuous monitor penetration.
- Diabetes Clinics:Outpatient specialty practices prescribe continuous systems and train patients on interpretation, serving as gatekeepers for prior authorization workflows.
- Long-Term Care Facilities:Nursing homes balance fingerstick cost control with staff efficiency, driving interest in non-invasive alternatives that reduce lancet disposal burdens.
By patient population, homecare dominates. By revenue per user, hospitals command premium positioning.
Technology:
Maturity curves separate proven electrochemical platforms from optical and biosensor approaches still seeking ISO 15197 validation.
- Electrochemical:Enzymatic glucose oxidase reactions on disposable strips deliver ±15% accuracy at mass-manufactured cost points. Production scale concentrates in China and Malaysia, supplying global meter OEMs with commoditized consumables.
- Optical:Near-infrared spectroscopy and Raman methods aim to eliminate fingersticks entirely. Wellness segment pilots in the United States and Japan are absorbing early hardware costs despite clinical accuracy gaps.
- Non-Invasive:Dielectric impedance and tear fluid sampling approaches target prediabetes screening markets with consumer electronics form factors.
- Biosensor:Microneedle and tattoo-based platforms merge continuous monitoring with minimal invasiveness, attracting venture funding for next-generation wearable integration.
By installed base, electrochemical leads. By patent filing velocity, biosensor is climbing the fastest.
Distribution Channel:
Margin structures diverge between high-touch medical supply relationships and self-service retail volume.
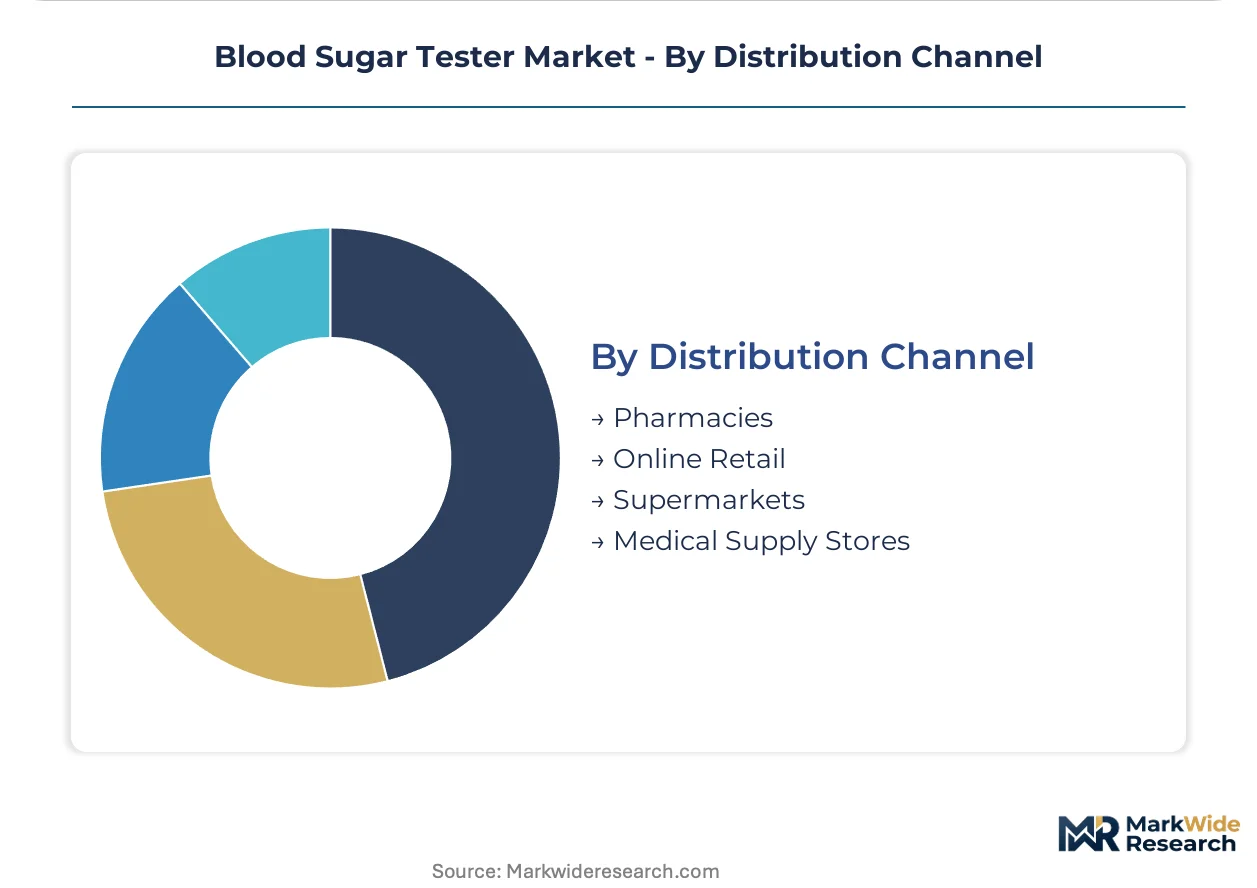
- Pharmacies:Chain and independent drugstores handle 60% of fingerstick meter and strip volume through prescription and over-the-counter counters. Pharmacy benefit manager contracts determine shelf placement and generic substitution rates.
- Online Retail:Direct-to-consumer platforms bypass retail markups for continuous glucose monitor subscriptions, capturing patient lifetime value through recurring sensor shipments.
- Supermarkets:Mass merchandisers compete on price for basic meter kits, often loss-leading to drive traffic and pharmacy conversions.
- Medical Supply Stores:Durable medical equipment dealers handle Medicare billing for continuous systems and insulin pump integrations, requiring specialized reimbursement expertise.
By transaction volume, pharmacies lead. By revenue growth rate, online retail is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany exports precision glucose monitoring components to United States health systems, establishing the dominant transatlantic trade corridor for continuous monitoring hardware.
United States
Medicare remote patient monitoring codes and private payer coverage expansion drive patient-owned continuous glucose monitor procurement. FDA 510(k) clearance pathways for next-generation biosensors compress development timelines for domestic manufacturers. The Minneapolis medical device cluster anchors insulin pump integration development.
Germany
Statutory health insurance reimbursement for continuous systems among Type 1 patients sustains premium device demand. EU MDR notified body concentration in Berlin and Munich accelerates CE marking for established manufacturers. The Baden-Württemberg precision engineering corridor supplies sensor microfabrication components.
China
National diabetes screening programs and tiered diagnosis infrastructure expand fingerstick meter volume in provincial hospitals. NMPA streamlined approval for Class II glucose monitoring devices reduces registration timelines. The Shenzhen electronics manufacturing cluster dominates electrochemical test strip production scale.
India
Jan Aushadhi generic initiatives and national non-communicable disease programs create distribution reach into tier-3 cities and village sub-centers. CDSCO medical device rules harmonization with IMDRF standards simplifies import registration. The Gujarat pharmaceutical manufacturing belt hosts contract production for affordable meter assembly.
Japan
Aging demographics and government-mandated diabetes management protocols sustain homecare device replacement cycles. PMDA Sakigake designation for breakthrough glucose sensing technologies accelerates priority review. The Osaka-Kobe medical technology corridor specializes in miniaturized optical sensor development.
Blood Sugar Tester Market Vendor Landscape
Listed leaders compete with private specialists across reimbursement access and sensor platform specialization. The market exhibits tiered concentration with integrated health conglomerates commanding premium positioning and regional manufacturers capturing volume through pharmacy channels. Three archetypes dominate: sensor-to-app ecosystem builders, continuous monitor pure-plays, and diversified diabetes care platforms. Competitive moves center on insulin pump convergence partnerships and direct-to-consumer channel bypass strategies.
Within the ecosystem-builder tier, Abbott Laboratories exemplifies integrated sensor-to-transmitter-to-application architectures. DexCom, Inc. occupies the continuous glucose monitor specialization position. Medtronic anchors the diversified diabetes care platform archetype, extending beyond monitoring into delivery coordination. These three represent distinct strategic vectors without implying specific market share or performance claims.
| Leading Market Players |
|---|
| Abbott Laboratories |
| DexCom, Inc. |
| Medtronic |
| F. Hoffmann-La Roche Ltd. |
| Ascensia Diabetes Care Holdings AG |
| LifeScan IP Holdings, LLC |
| B. Braun SE |
| Sinocare |
| Terumo Corporation |
| Others |
Supply Flow & Price Mechanics
ISO 15197 certification tiers gate both supplier qualification and price differentiation in blood sugar testers, forcing manufacturers to align electrochemical accuracy investments with reimbursement-eligible premium positioning against uncertified economy alternatives.
Pricing Analysis
Next-generation continuous glucose monitors command subscription pricing three to five times above prior-generation fingerstick meter hardware, while optical biosensor prototypes occupy preclinical valuation tiers awaiting FDA clearance. Pricing stratifies across premium sensor ecosystems, standard connected meters, and economy test strip bundles. Certification grade and volume scale drive price differentiation, with pharmacy benefit manager contracts compressing strip margins downward. Cost compression in fingerstick consumables is intensifying because of consolidated purchasing power among United States retail chains.
Supply Chain Analysis
China and Malaysia anchor electrochemical test strip production at mass scale, while Germany and the United States concentrate precision sensor microfabrication for continuous systems. Raw material dependencies center on glucose oxidase enzymes, noble metal electrode coatings, and medical-grade adhesive polymers. Single-source vulnerability concentrates in specialty biocompatibility formulations for long-wear sensors. Distribution runs through pharmacy chains for fingerstick volume and durable medical equipment dealers for continuous monitor Medicare billing.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Sensor subscription services and data analytics platforms are expanding recurring revenue faster than hardware sales, transforming device vendors into glycemic management service providers.
For Market Incumbents: Compound platform stickiness through insulin pump convergence partnerships that lock patients into closed-loop artificial pancreas ecosystems. Deepen backward integration into microneedle array production to secure biocompatibility engineering capacity against emerging optical sensor competitors. Prioritize direct-to-consumer channel control to capture patient lifetime value previously extracted by pharmacy intermediaries.
For New Entrants and Emerging Players: Algorithm-driven glucose prediction services represent a service-layer gap where incumbents under-serve Type 2 prediabetes populations with intermittent monitoring needs. Target rural India through Jan Aushadhi distribution infrastructure for affordable meter penetration. Pursue telehealth-integrated subscription models that bypass traditional prior authorization gatekeepers.
For Investors and Strategic Acquirers: EU MDR reclassification reshapes the acquisition landscape by concentrating conformity assessment capacity among high-capacity notified bodies in Germany and the Netherlands, elevating strategic value of manufacturers with established clinical data portfolios. Long-term viability centers on sensor-to-app ecosystem builders with demonstrated reimbursement traction. Watch FDA 510(k) predicate divergence trends as inflection indicators for regulatory timeline risk in next-generation continuous monitor development.
| Strategic Initiative | Industry Significance |
|---|---|
| Insulin Pump Integration Partnership | Closed-loop coordination with automated delivery algorithms commands premium positioning in Type 1 diabetes management. |
| Direct-to-Consumer Channel Launch | Pharmacy bypass models capture patient lifetime value through recurring sensor subscription shipments. |
| Optical Biosensor FDA Submission | Non-invasive clearance pathways unlock wellness segment pilots despite clinical accuracy gaps versus electrochemical standards. |
| Rural India Distribution Expansion | Jan Aushadhi generic initiatives create infrastructure reach into tier-3 cities and village health sub-centers. |
| EU MDR Clinical Data Investment | Robust post-market surveillance portfolios accelerate CE marking timelines amid notified body capacity constraints. |
Methodological Framework
A standing panel of continuous glucose monitor product managers, hospital biomedical engineers, pharmacy benefit manager contract specialists, and CMS reimbursement policy analysts provided ongoing calibration across primary interviews and secondary validation. Sources included FDA 510(k) clearance databases, EU MDR notified body registration records, CMS remote patient monitoring code utilization data, and GPO hospital procurement contracts. Bottom-up segment sizing triangulated against top-down epidemiological diabetes prevalence projections.
Consistency checks validated volume and value outputs against external benchmarks across the projection horizon. The analytical framework modeled segmentation across product architecture, end-use setting, technology maturity, and distribution channel, with regional reimbursement policy clusters as an industry-specific dimension. CAGRs derived from installed base growth rates and replacement cycle compression, incorporating sensor wear duration extension and fingerstick volume erosion as forecast inputs.
Forecasts assume regulatory continuity in FDA 510(k) pathways and EU MDR implementation; material policy shifts in CMS remote patient monitoring coverage or notified body capacity allocation would require re-modeling. Specific risks include optical biosensor accuracy validation failures and pharmacy benefit manager formulary exclusion actions. Recalibration cycles align with material shifts in reimbursement code utilization and CE marking timeline trends.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Testing Services
Ige Allergy Blood Tests Market
Testing Services
Human Papilloma Virus Testing Market
Testing Services
Antibiotic Susceptibility Testing Market
Testing Services
Global Multiplex Assays Market
Testing Services
North America Antimicrobial Susceptibility Testing Market
Testing Services
Global Molecular Quality Controls Market
Testing Services
Global Anti Thrombin III Testing Market
Testing Services
Global HIV Self Test Kits Market
Testing Services
Global Biologics Safety Testing Market
Testing Services
Global Enteric Disease Testing Market
Testing Services
Rapid Sterility Testing Market
Testing Services
Urine Testing Cups Market
Testing Services
Pneumococcal Testing Market
Testing Services
Thailand Point-Of-Care Testing (POCT) Market
Testing Services
Global Helicobacter Pylori (H. Pylori) Non-Invasive Testing Market
Testing Services
Indoor Allergen and Particulate Exposure Assessment Test Devices Market