
 Platelet Function Testing Market | 2026-2036
Platelet Function Testing Market Size, Share, and Industry Trends Forecast 2026-2036
Platelet Function Testing Market Analysis
Market Context
Specialized hematology technologist shortages in North American hospital networks is rotating capital budgets toward automated platelet function analyzers with minimal manual intervention. Siemens Healthineers leverages its installed base in hemostasis diagnostics to sustain recurring reagent revenue across integrated health systems. Sysmex Corporation anchors its position in Japan through dense technical service coverage and native regulatory navigation capabilities. Fresenius SE & Co. KGaA competes in European diagnostic laboratories with a broad consumables portfolio that reduces per-test operational complexity.
Technical Definition and Segment Structure
Platelet function testing encompasses laboratory and point-of-care methods that quantify platelet aggregation, secretion, and activation status under standardized agonist conditions, typically reporting results in aggregation percentage or platelet count-adjusted units to guide antiplatelet therapy decisions. Optical aggregometry remains the reference method in cardiology departments, though electrical impedance platforms are displacing legacy systems in high-throughput hospital laboratories due to reduced sample volume requirements and faster turnaround times. The analyzer segment dominates capital expenditure flows, while consumables and reagents capture the majority of lifetime value per installed unit. Flow cytometry applications in academic institutions represent the fastest-growing technology dimension, driven by research into personalized antiplatelet regimens and platelet biomarker discovery protocols.
Regulatory Framework and Outlook
FDA 510(k) pathways and EMA in vitro diagnostic regulation shape product development timelines and clinical validation requirements for platelet function assay manufacturers seeking multi-regional commercialization. The Clinical Laboratory Improvement Amendments in the United States and ISO 15189 accreditation frameworks in European diagnostic laboratories directly influence instrument design specifications, quality control protocols, and software documentation standards. Stakeholders must monitor evolving reimbursement codes for coagulation testing in major healthcare systems, as coverage determinations will dictate adoption velocity for next-generation platelet function platforms across hospital and outpatient settings.
Market Dynamics
Specialized hematology technologist shortages in North American hospital networks are rotating capital budgets toward automated platelet function analyzers with minimal manual intervention, compressing adoption cycles for integrated testing platforms.
Growth Catalysts
- Cardiac Intervention Volumes:Percutaneous coronary intervention procedures in the United States, Germany, and Japan sustain high test throughput in catheterization laboratories.
- FDA 510(k) Pathway Compression:Expedited clearance timelines for novel hemostasis diagnostics accelerate time-to-market for next-generation assay formats.
- Optical Aggregometry Standardization:Reference method status in cardiology departments drives replacement demand for legacy electrical impedance systems.
Market Restraints
- Reagent Cost Volatility:Proprietary consumables capture majority lifetime value per installed unit, locking laboratories into single-vendor supply chains.
- Technical Limitation:Sample preparation requirements for optical aggregometry limit point-of-care deployment outside centralized laboratories.
- Regulatory Friction:Clinical Laboratory Improvement Amendments quality control protocols impose documentation burdens that slow instrument validation.
Strategic Opportunities
- Flow Cytometry Convergence:Academic research into personalized antiplatelet regimens creates demand for multi-parameter platelet biomarker platforms.
- Point-of-Care Expansion:Electrical impedance technology enables decentralized testing in emergency departments and ambulatory surgical centers.
- ISO 15189 Tailwind:European diagnostic laboratory accreditation frameworks favor automated systems with embedded quality management software.
Industry Challenges
- Hematology Technologist Scarcity:Specialized personnel shortages constrain laboratory throughput and extend test turnaround times.
- Legacy System Integration:Hospital information system connectivity requirements complicate deployment of novel platelet function platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Platelet Function Testing Market |
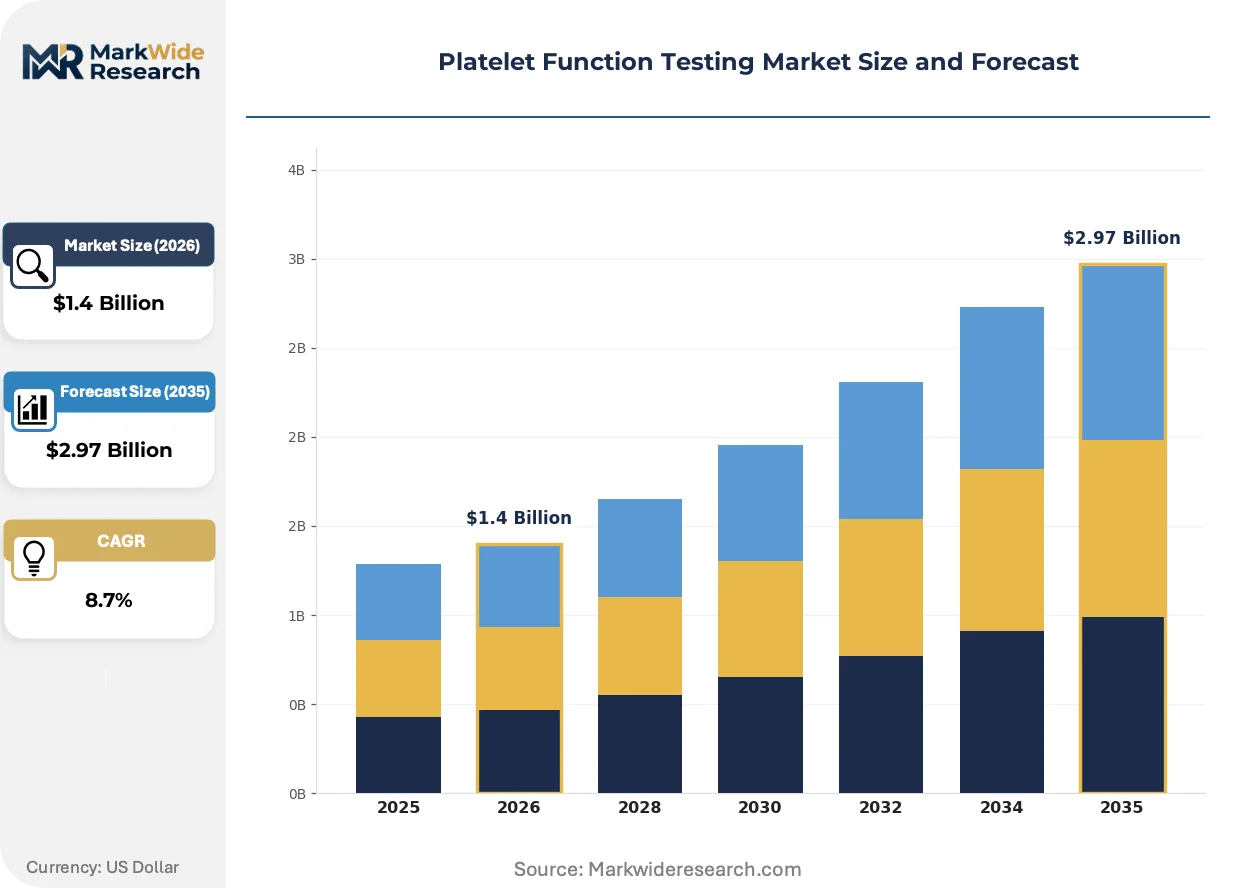
| Market Size in 2026 | $1.4 Billion |
| Market Size in 2035 | $2.97 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Analyzers, Reagents, Consumables, Software End User: Hospitals, Diagnostic Laboratories, Academic Institutions, Research Centers Technology: Optical Methods, Electrical Impedance, Aggregometry, Flow Cytometry Application: Cardiology, Hematology, Emergency Medicine, Critical Care |
| Companies Covered | F. Hoffmann-La Roche Ltd, Siemens Healthineers, Sysmex Corporation, Haemonetics Corporation, Helena Laboratories, Terumo Corporation, Fresenius SE & Co. KGaA, AggreDYNE, Thermo Fisher Scientific Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Platelet Function Testing Market Emerging Trajectories
Antiplatelet therapy personalization protocols are reshaping test menu design, with laboratories demanding platforms that bridge routine clinical diagnostics and research-grade biomarker quantification.
Multi-channel optical aggregometry is bifurcating the installed base between high-complexity reference laboratories and streamlined hospital core labs. Cardiology departments in the United States and Japan are adopting compact four-channel systems to reduce sample volume requirements. This technology is bifurcating vendor strategies between premium research-grade instruments and cost-optimized clinical platforms.
EMA In Vitro Diagnostic Regulation reclassification is compressing clinical validation timelines for platelet function assay manufacturers seeking European commercialization. Manufacturers must submit expanded performance data under the new risk-based classification system. High-throughput hospital laboratories in Germany and France are prioritizing systems with pre-validated IVDR technical documentation.
Service unbundling is disrupting traditional analyzer-reagent bundling contracts in North American health systems. Hospital procurement committees are separating capital equipment acquisition from consumables sourcing to optimize total cost of ownership. This shift is most visible in integrated delivery networks in the United States negotiating multi-vendor reagent supply agreements.
Platelet Function Testing Market Segmentation
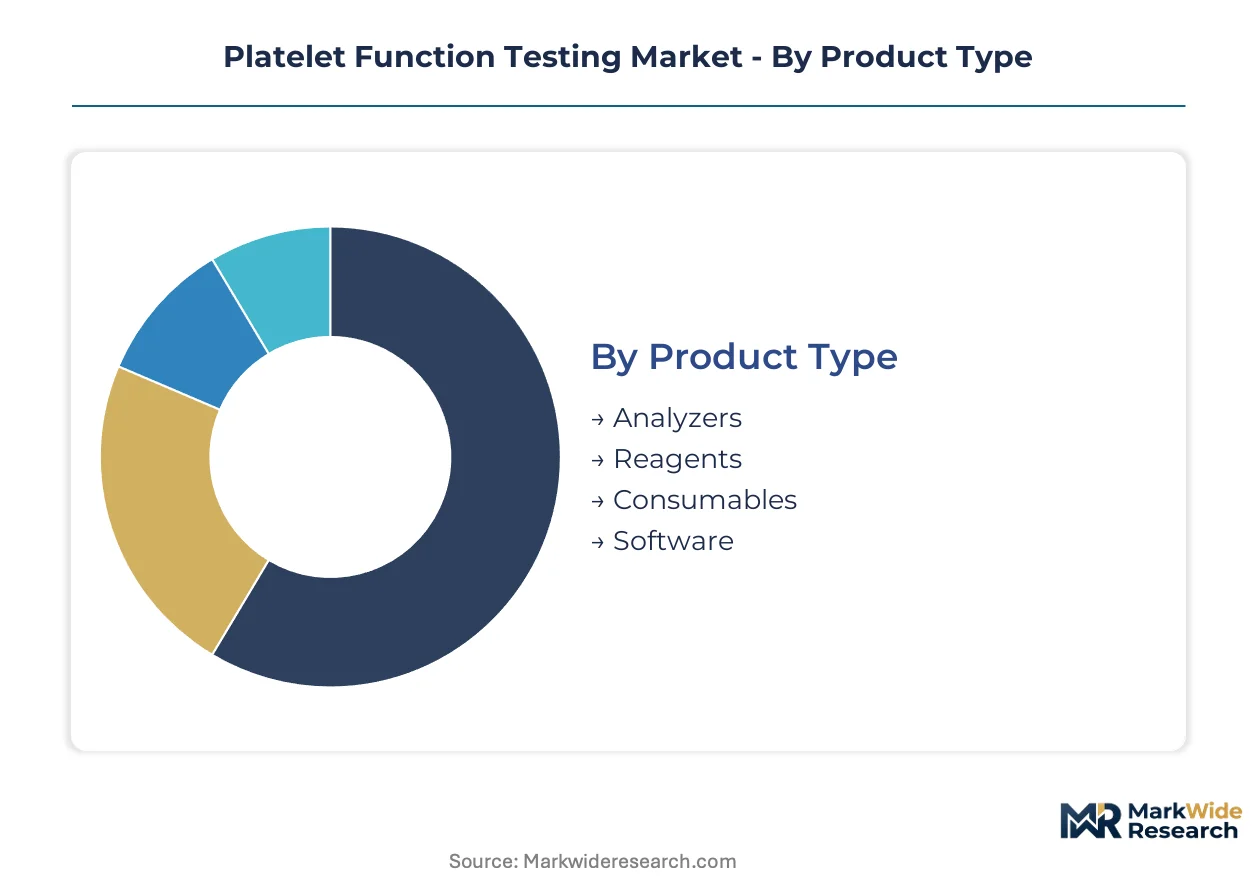
Platelet function testing segments diverge sharply by capital intensity and regulatory pathway. Product type determines margin structure, while technology choice dictates deployment setting and reimbursement eligibility.
Product Type:
FDA 510(k) clearance timelines compress fastest for analyzers with predicate device pathways, while novel reagent formulations face extended analytical validation requirements.
- Analyzers:Capital equipment incorporating optical or electrical impedance detection modules. Hospital laboratories in the United States and Germany concentrate procurement authority here, driven by CLIA-mandated quality control automation and ISO 15189 accreditation pressures.
- Reagents:Proprietary agonist cocktails and calibration materials capturing recurring revenue per installed unit. Single-vendor lock-in dominates, though North American health systems are unbundling procurement to optimize total cost of ownership.
- Consumables:Cuvettes, pipette tips, and sample preparation disposables with lower regulatory burden.
- Software:Embedded quality management and laboratory information system connectivity modules.
Established volume favors analyzers; emerging adoption favors software.
End User:
Customer concentration varies by procedure volume and technologist availability, with cardiac intervention throughput determining test menu complexity.
- Hospitals:Catheterization laboratories and core labs processing high daily volumes. Percutaneous coronary intervention centers in Japan and the United States sustain demand for rapid turnaround platforms, constrained by specialized hematology technologist shortages.
- Diagnostic Laboratories:Centralized reference facilities performing esoteric coagulation panels. German and French networks prioritize pre-validated IVDR technical documentation under EMA reclassification rules.
- Academic Institutions:Research-grade biomarker discovery and personalized antiplatelet protocol development.
- Research Centers:Multi-parameter platelet activation studies and novel agonist characterization.
Hospital procurement dominates current spend; academic adoption is climbing the fastest.
Technology:
Detection methodology determines sample volume requirements, throughput capacity, and point-of-care eligibility under CLIA waiver considerations.
- Optical Methods:Light transmission aggregometry serving as cardiology reference standard. Legacy system replacement cycles in United States academic medical centers drive demand, though sample preparation complexity limits decentralized deployment.
- Electrical Impedance:Whole blood aggregation without centrifugation. Emergency departments and ambulatory surgical centers in Germany and Japan favor this format for reduced technical labor and faster results.
- Aggregometry:Multi-channel platforms spanning four to eight simultaneous agonist tests.
- Flow Cytometry:Multi-parameter platelet activation marker quantification. Research applications in personalized antiplatelet regimens are gaining share fastest among technology categories.
Optical platforms anchor reference laboratory infrastructure; electrical impedance enables point-of-care expansion.
Application:
Clinical use case dictates agonist panel design, turnaround time requirements, and integration with therapeutic decision protocols.
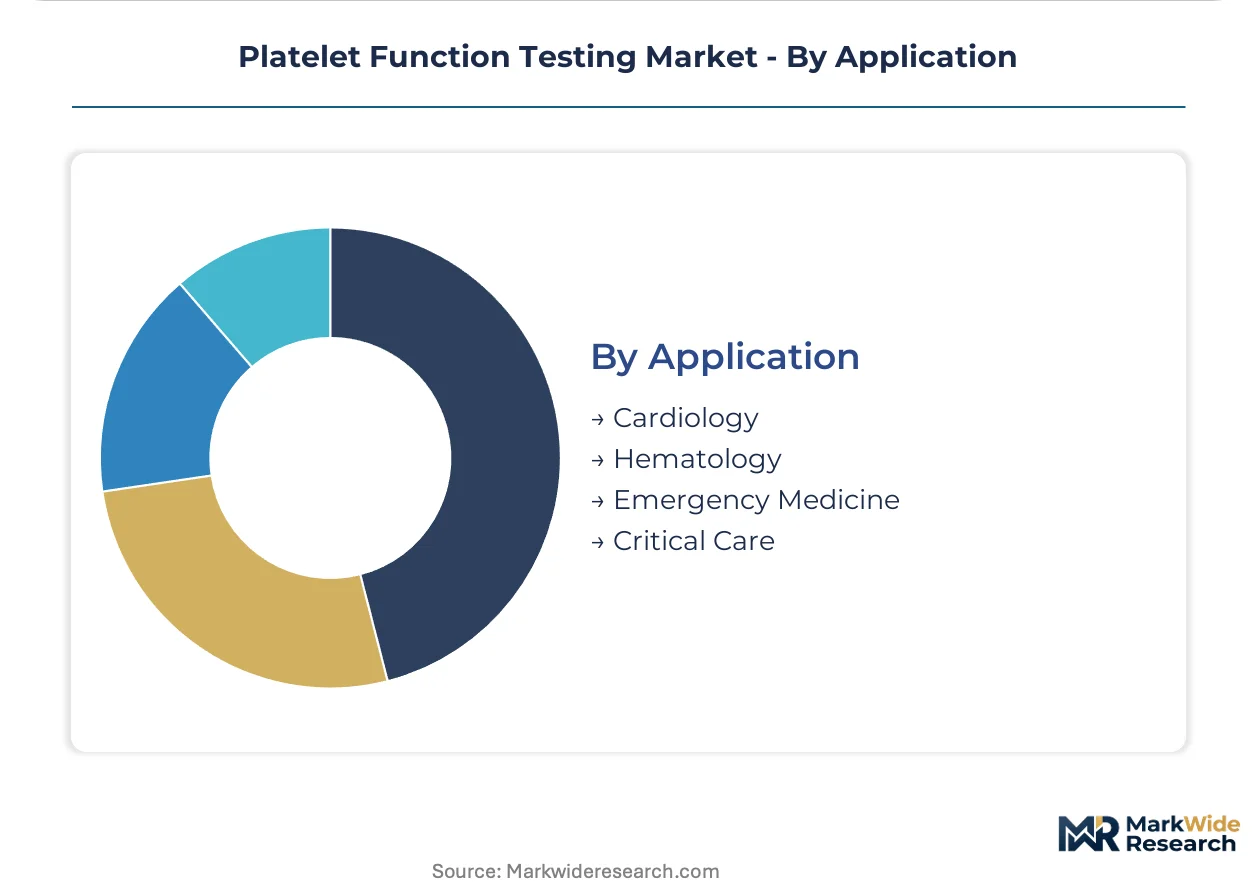
- Cardiology:Pre- and post-percutaneous coronary intervention monitoring with P2Y12 inhibitor response assessment. Catheterization laboratories in the United States, Germany, and Japan sustain highest test density per procedure volume.
- Hematology:Inherited and acquired platelet disorder characterization. Reference laboratories concentrate this work due to specialized interpretation requirements.
- Emergency Medicine:Rapid trauma coagulopathy and antiplatelet reversal assessment.
- Critical Care:ICU-based bleeding risk stratification and transfusion guidance.
Cardiology commands installed base depth; critical care represents the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in German and Japanese hospital procurement networks, where cardiac intervention volumes sustain premium analyzer placements, while cost-sensitive markets rotate toward electrical impedance platforms with lower per-test economics.
United States
Percutaneous coronary intervention centers in Cleveland Clinic and Mayo Clinic networks sustain dense test throughput, driving replacement cycles for legacy optical aggregometry systems. FDA 510(k) pathway compression accelerates clearance timelines for novel assay formats, reducing time-to-market by twelve to eighteen months versus historical averages. Hospital laboratories in the Northeast Corridor rotate capital budgets toward automated platforms as CLIA-mandated quality control documentation burdens intensify.
Germany
Catheterization laboratories in Bavaria and North Rhine-Westphalia process Europe's highest per-capita PCI volumes, anchoring demand for rapid-turnaround electrical impedance systems. EMA In Vitro Diagnostic Regulation reclassification imposes expanded performance data requirements, favoring vendors with pre-validated technical documentation. Diagnostic networks in the Eindhoven-Randstad corridor prioritize ISO 15189-accredited systems with embedded quality management software.
Japan
Acute myocardial infarction intervention protocols in Tokyo and Osaka metropolitan areas mandate point-of-care platelet function assessment, sustaining premium analyzer placements. PMDA regulatory navigation capabilities differentiate domestic vendors from foreign entrants seeking market access. Technical service density in Kanto and Kansai regions locks hospital laboratories into established vendor relationships with sub-four-hour response commitments.
China
Cardiovascular disease burden expansion in Yangtze River Delta and Pearl River Delta hospital networks drives analyzer procurement, though price sensitivity constrains premium optical system penetration. NMPA regulatory pathways for in vitro diagnostics extend clinical validation timelines versus Western markets, compressing foreign vendor margins. Domestic manufacturers in Beijing-Tianjin-Hebei cluster capture mid-tier hospital segment share through localized reagent supply chains.
United Kingdom
NHS England specialized commissioning frameworks concentrate platelet function testing in designated cardiac centers across London and the Midlands, limiting dispersed point-of-care deployment. MHRA post-Brexit regulatory autonomy introduces divergence risk from EMA IVDR implementation timelines. Academic medical centers in Greater Manchester and Scotland pioneer flow cytometry applications for personalized antiplatelet protocol development.
Platelet Function Testing Market Vendor Landscape
Technology leadership and cost leadership are held by different player archetypes, with reference-method optical aggregometry specialists commanding premium positioning while electrical impedance generalists capture volume expansion in decentralized settings. The market structure consolidates around diversified diagnostics conglomerates with hemostasis installed bases, mid-cap hematology specialists, and point-of-care platform innovators. Three archetypes dominate: integrated health system suppliers with recurring reagent revenue models, research-grade instrument specialists serving academic cardiology departments, and emergency medicine platform vendors optimizing for turnaround speed. Competitive moves concentrate on service unbundling to separate analyzer capital acquisition from consumables sourcing, and IVDR pre-validation investments to compress European commercialization timelines.
Among diversified diagnostics conglomerates, Siemens Healthineers and Sysmex Corporation occupy positions defined by installed base density and technical service infrastructure rather than product-specific differentiation. Roche Diagnostics represents the reference-laboratory archetype with aggregation technology lineage, while Haemonetics Corporation sits within the blood management specialist tier with natural adjacency to perioperative platelet monitoring applications. AggreDYNE exemplifies the point-of-care platform innovator archetype, though its market position remains contingent on CLIA waiver pathway navigation for emergency department deployment.
| Leading Market Players |
|---|
| F. Hoffmann-La Roche Ltd |
| Siemens Healthineers |
| Sysmex Corporation |
| Haemonetics Corporation |
| Helena Laboratories |
| Terumo Corporation |
| Fresenius SE & Co. KGaA |
| AggreDYNE |
| Thermo Fisher Scientific Inc. |
| Others |
Supply Flow & Price Mechanics
Installed base density in United States hospital networks creates scale economies that compress per-unit reagent manufacturing costs while simultaneously elevating price floors for specialized agonist cocktails. This concentration of analyzer placements in Cleveland Clinic and Mayo Clinic procurement networks locks laboratories into proprietary consumables sourcing, with Siemens Healthineers and Sysmex Corporation leveraging technical service density to sustain premium positioning against mid-tier electrical impedance entrants.
Pricing Analysis
The customization-premium spread separates reference-grade optical aggregometry systems from cost-optimized electrical impedance platforms, with cardiology departments in Japan and Germany absorbing premium configurations for multi-channel agonist testing. Price differentiation hinges on ISO 15189 pre-validation documentation and embedded quality management software tiers. Cost compression in the standard analyzer segment is intensifying because hospital procurement committees in North American integrated delivery networks are unbundling capital equipment from consumables sourcing. Diagnostic laboratories represent the most price-sensitive buyer archetype, while catheterization laboratories sustain lowest sensitivity due to procedure volume economics.
Supply Chain Analysis
Inventory lead times for proprietary reagent formulations extend eighteen to twenty-four weeks, forcing hospital laboratories in the United States and Germany to maintain safety stock of P2Y12 inhibitor response panels. Manufacturing concentration centers on Germany, Japan, and the United States for analyzer assembly, while agonist chemical precursors draw from Swiss and Chinese specialty chemical suppliers. Single-source vulnerability pervades the proprietary reagent tier, where FDA 510(k) predicate pathways lock formulations to specific analyzer architectures. Distribution runs through direct hospital contracting in North America and specialized diagnostic distributors in European ISO 15189-accredited networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The platelet function testing market reads as a service-attach opportunity because reagent and consumables revenue per installed unit is expanding faster than analyzer capital sales, with technical service contracts capturing recurring value beyond hardware depreciation cycles.
For Market Incumbents: Shield installed base density in United States catheterization laboratories by deepening captive reagent supply agreements before procurement unbundling spreads to integrated delivery networks. Prioritize IVDR pre-validation investments in German diagnostic networks to compress European commercialization timelines against emerging electrical impedance entrants. For New Entrants and Emerging Players: Emergency department point-of-care deployment gaps offer white-space entry, with CLIA waiver pathway navigation enabling ambulatory surgical center penetration ahead of established optical aggregometry vendors. Target mid-tier Chinese hospital networks in Yangtze River Delta clusters where domestic manufacturers under-serve rapid-turnaround electrical impedance demand. Lead with software companion development for laboratory information system connectivity as the primary go-to-market angle. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among hemostasis diagnostics conglomerates with dense reagent installed bases, positioning these archetypes for sustained cash flow quality across five-to-ten year holding periods. Monitor FDA 510(k) clearance velocity for novel assay formats as the signal indicating inflection in competitive positioning between optical and electrical impedance technology camps.| Strategic Initiative | Industry Significance |
|---|---|
| IVDR Pre-Validation Investment | EMA reclassification rules favor vendors with pre-validated technical documentation in German laboratories. |
| Reagent Supply Agreement Unbundling | Hospital procurement committees in United States integrated networks separate capital from consumables sourcing. |
| CLIA Waiver Pathway Navigation | Emergency department deployment eligibility accelerates point-of-care expansion for electrical impedance platforms. |
| Software Companion Development | Laboratory information system connectivity modules differentiate analyzer platforms in ISO 15189-accredited European networks. |
| Technical Service Density Expansion | Sub-four-hour response commitments in Kanto and Kansai regions lock Japanese hospital laboratories into vendor relationships. |
Methodological Framework
Two parallel data streams informed the analysis: structured primary interviews with hematology technologists, catheterization laboratory directors, hospital procurement managers, and biomedical engineers; and secondary validation against FDA 510(k) filings, EMA IVDR technical documentation, hospital procurement databases, and CMS Medicare reimbursement codes. Bottom-up segmentation modeling triangulated against top-down market sizing from installed base estimates and reagent consumption patterns.
Across the analysis window, the forecasting framework modeled product type, technology platform, end-user setting, and geographic regulatory cluster dimensions. CAGRs were derived from procedure volume trajectories in percutaneous coronary intervention centers and replacement cycle timing for legacy optical aggregometry systems. Forecast inputs incorporated specialized hematology technologist shortage projections and cardiac intervention volume elasticity to antiplatelet therapy protocol changes.
Forecasts assume regulatory continuity in FDA 510(k) pathways and EMA IVDR implementation; material policy shifts in CLIA quality control protocols or NMPA clinical validation timelines would require re-modeling. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Testing Services
ATP Assays Market
Testing Services
Blood Testing Market
Testing Services
Carbapenem-Resistant Enterobacteriaceae Testing Market
Testing Services
Bleeding Disorders Testing Market
Testing Services
Nucleic Acid Amplification Testing Market
Testing Services
Antibiotic Residue Test Kits Market
Testing Services
Fungal Testing Kits Market
Testing Services
North America Drug Screening Market
Testing Services
Vestibular Testing System Market
Testing Services
Asia-Pacific Hereditary Cancer Testing Market
Testing Services
Passive Dosimetry Equipment and Service Market
Testing Services
Gamma Glutamyl Transferase Testing Market
Testing Services
Service Laboratory Market
Testing Services
Cerebrospinal Fluid (CSF) Testing Market
Testing Services
Self-Testing Market
Testing Services
Global Extractables and Leachables Testing Services Market