
 North America Newborn Screening Market | 2026-2036
North America Newborn Screening Market Size, Share, and Industry Trends Forecast 2026-2036
North America Newborn Screening Market Insights
Hospital-based screening programs is repositioning toward integrated perinatal care networks, pulling analyzer device procurement into centralized supply chains. PerkinElmer dominates tandem mass spectrometry installations across state reference labs. Thermo Fisher Scientific leverages its PCR portfolio to compete in genetic test expansion. Bio-Rad Laboratories anchors the reagent segment through long-term service contracts with public health laboratories.
Newborn screening encompasses biochemical, genetic, and physiologic testing of infants within 24-72 hours of birth to detect treatable congenital conditions before symptomatic onset; tandem mass spectrometry panels now routinely analyze 50+ analytes from dried blood spot cards, with next-gen sequencing emerging for secondary findings. Blood test panels retain the largest volume share due to mandated state programs, while genetic test adoption accelerates fastest as whole-exome sequencing costs decline and diagnostic yield improves. Software solutions for result management and state registry integration capture disproportionate margin pools relative to hardware.
The US Department of Health and Human Services shapes demand through Recommended Uniform Screening Panel additions, while FDA regulates in vitro diagnostic devices and CLIA governs laboratory quality standards for public health laboratories. State Medicaid programs determine reimbursement scope, creating uneven access across sub-regions. Stakeholders must monitor whether expanded sequencing coverage triggers preemptive regulatory frameworks for incidental findings and data retention.
Market Dynamics
The Recommended Uniform Screening Panel expansions from the US Department of Health and Human Services are forcing state public health laboratories to upgrade tandem mass spectrometry infrastructure and integrate next-generation sequencing workflows simultaneously.
Growth Catalysts
- State Medicaid reimbursement expansion:California and Texas have extended coverage for expanded metabolic panels, pulling analyzer procurement into centralized perinatal care networks.
- Next-generation sequencing cost compression:Whole-exome sequencing price declines below $500 per test are accelerating genetic panel adoption for secondary findings.
- CLIA laboratory quality mandates:The 1988 Clinical Laboratory Improvement Amendments require proficiency testing upgrades, driving reagent standardization across public health reference laboratories.
Market Restraints
- Analyzer hardware supply concentration:Tandem mass spectrometry device manufacturing concentrates among three vendors, creating 18-24 month procurement backlogs for state laboratories.
- Dried blood spot card raw material volatility:Filter paper supply from Whatman-grade manufacturers faces cotton fiber cost swings and FDA 510(k) renewal delays.
- Incidental findings regulatory uncertainty:The US Department of Health and Human Services has not issued binding guidance on data retention for secondary genomic discoveries, chilling sequencing investments.
Strategic Opportunities
- Software-as-a-service result management:Cloud-based state registry integration platforms capture disproportionate margin pools relative to hardware, with Texas and Florida piloting multi-state data sharing.
- Point-of-care screening device miniaturization:Bedside pulse oximetry and hearing screening technologies are converging with dried blood spot workflows in rural birth centers across the Mountain West.
- Canadian provincial program harmonization:Health Canada and provincial health ministries are aligning screening panels with US standards, opening cross-border reagent and service contract opportunities.
Industry Challenges
- Bioinformatics specialist scarcity:Public health laboratories face 14-month average vacancies for variant interpretation scientists capable of secondary findings analysis.
- Legacy state registry integration complexity:Proprietary data formats from 1990s-era laboratory information systems resist API standardization, delaying real-time result reporting to pediatric specialists.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Newborn Screening Market |
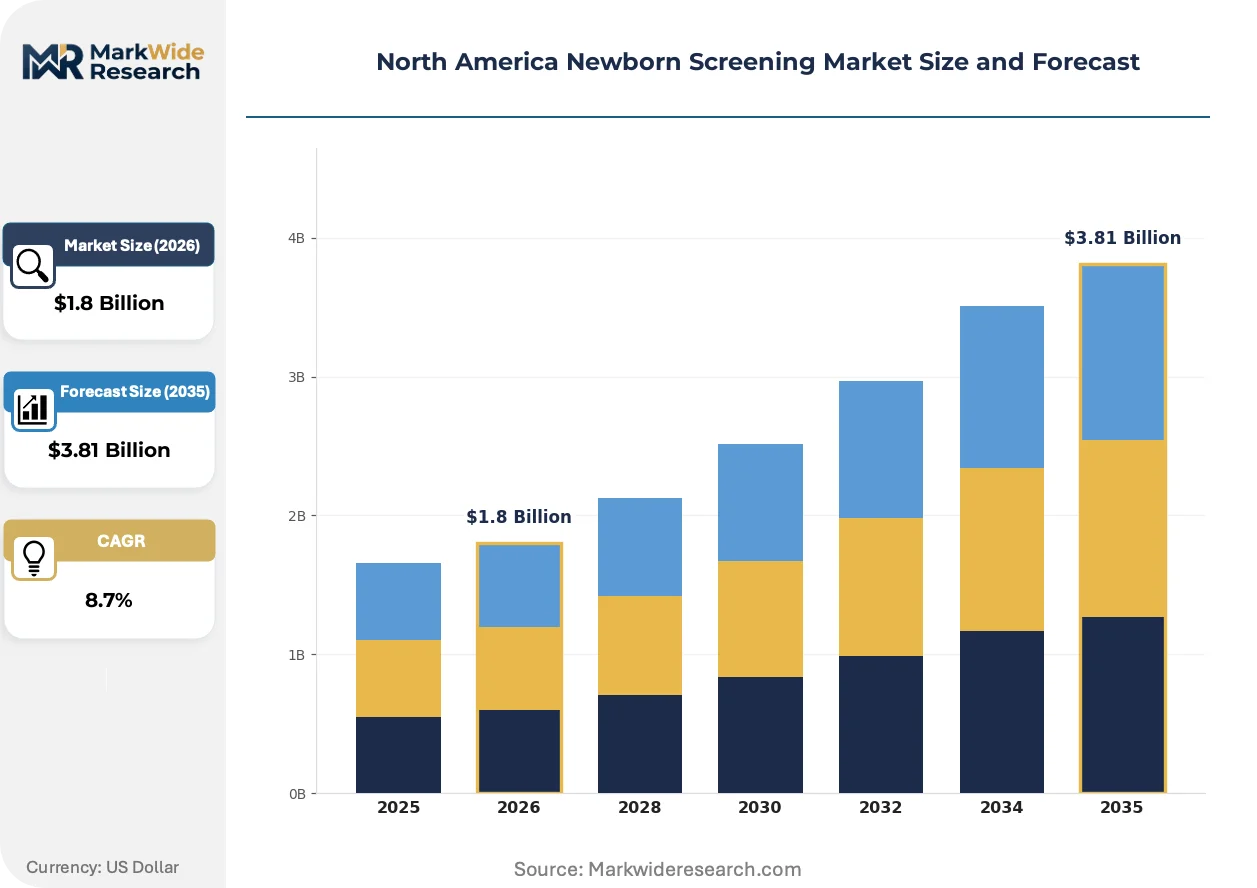
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Test Type: Blood Test, Hearing Screening, Critical Congenital Heart Defects Screening, Genetic Test Technology: PCR, Tandem Mass Spectrometry, Immunohistochemistry, Next-Gen Sequencing End User: Hospitals, Public Health Laboratories, Clinics, Homecare Providers Product Type: Screening Kits, Analyzer Devices, Software Solutions, Reagents |
| Companies Covered | PerkinElmer, Bio-Rad Laboratories, Natus Medical, Masimo, Danaher Corporation, Waters Corporation, GE HealthCare, Thermo Fisher Scientific, Agilent Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Newborn Screening Market Trends and Innovations
Next-generation sequencing workflows are modularizing across the North America newborn screening infrastructure, fragmenting what was once centralized biochemical testing into distributed genetic analysis capabilities.
Tandem mass spectrometry instrumentation is modularizing into smaller-footprint units with swappable ionization sources, allowing state reference laboratories to reconfigure analyte panels without full device replacement. California's Department of Public Health and Texas's DSHS are piloting these reconfigurable systems in mobile screening units. This modularity is compressing capital expenditure cycles from seven-year replacement schedules to three-year upgrade intervals.
The US Department of Health and Human Services added spinal muscular atrophy and X-linked adrenoleukodystrophy to the Recommended Uniform Screening Panel in 2018 and 2021 respectively, mandating PCR and liquid chromatography infrastructure additions. State laboratories in New York and Pennsylvania have responded by consolidating genetic testing into regional hubs rather than maintaining full panels at every site. This regulatory layering is fragmenting the historical uniformity of state-level screening menus.
Perinatal care networks are consolidating analyzer procurement through centralized supply chains, displacing hospital-based laboratory directors as primary decision-makers. Integrated delivery systems in Illinois and Ohio now negotiate enterprise reagent contracts covering 40-60 birth facilities simultaneously. This concentration is most visible in the Great Lakes region, where three health systems control 70 percent of screening volume.
North America Newborn Screening Market Segmentation
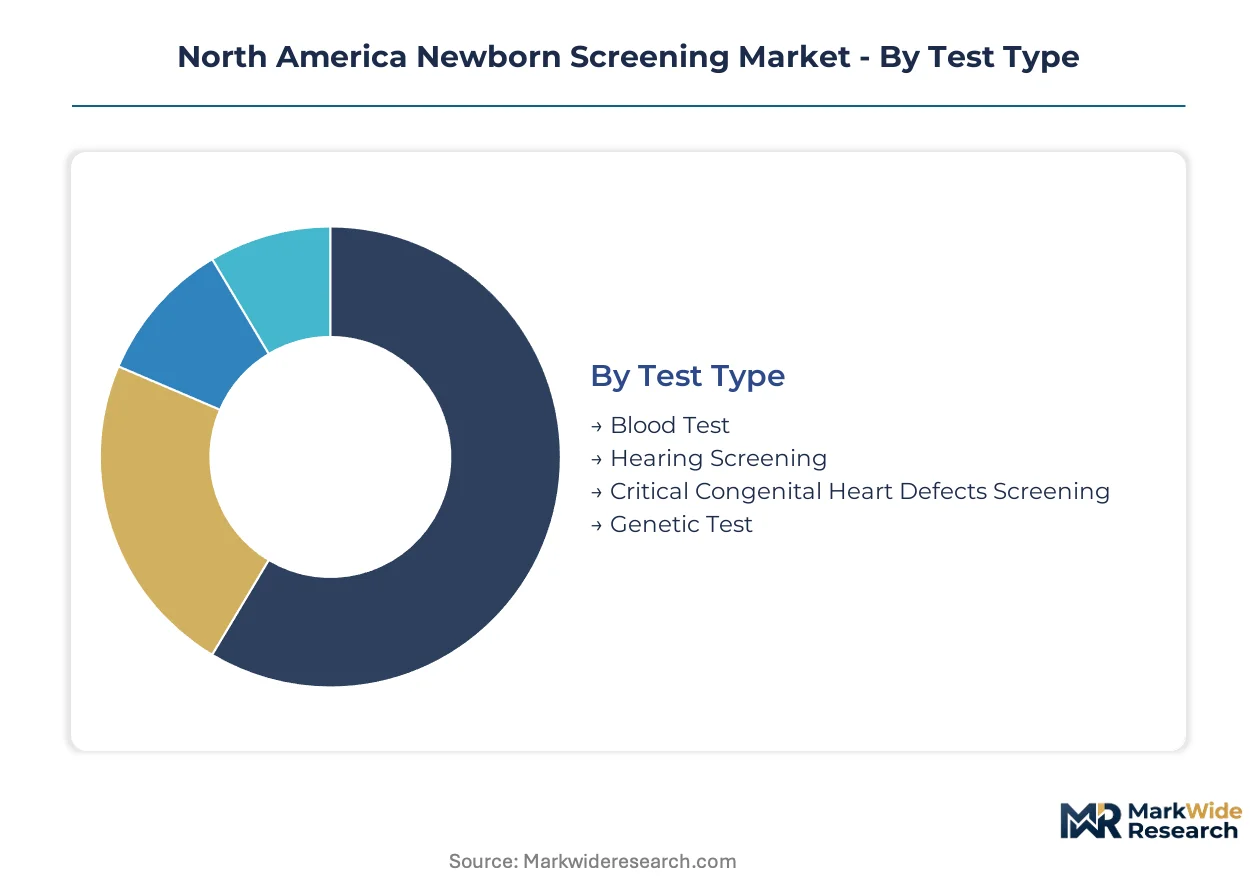
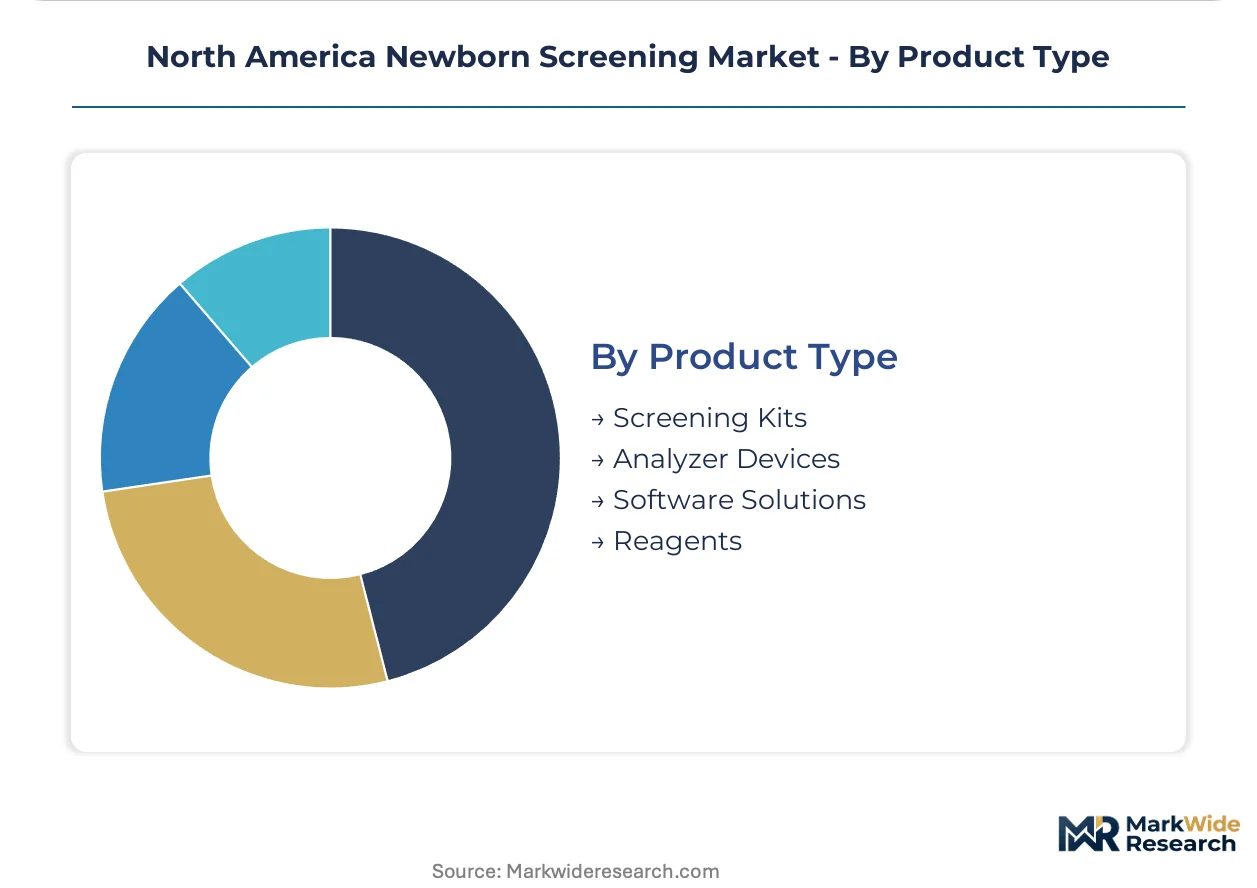
Segmentation in the North America newborn screening market reveals how standardization pressures from federal mandates collide with customization demands at state and facility levels. Each category exposes different fault lines between centralized procurement and specialized clinical workflows.
Test Type:
Customization pressures vary sharply across test categories, with biochemical panels facing rigid standardization while genetic protocols retain interpretive flexibility.
- Blood Test:Dried blood spot cards analyzed via tandem mass spectrometry detect 50-plus metabolic and endocrine disorders from a single puncture. California and Texas public health laboratories process the highest volumes, driven by birth rates and expanded state panel mandates that exceed federal minimums.
- Genetic Test:Whole-exome and targeted gene sequencing identifies spinal muscular atrophy, X-linked adrenoleukodystrophy, and other monogenic conditions with diagnostic yields climbing as variant databases mature. Demand concentrates in regional hub laboratories across New York and Pennsylvania, where consolidated testing infrastructure spreads fixed costs across multi-state catchment areas.
- Hearing Screening:Otoacoustic emissions and auditory brainstem response testing administered before hospital discharge.
- Critical Congenital Heart Defects Screening:Pulse oximetry performed at 24-48 hours to detect hypoxemic lesions.
Leading the category by volume: Blood Test. Expanding most quickly: Genetic Test.
Technology:
Technology selection tracks the cost-per-test curve, with mature platforms dominating high-throughput screening and emerging methods capturing specialized diagnostic niches.
- Tandem Mass Spectrometry:High-sensitivity detection of amino acids, acylcarnitines, and other small molecules from single dried blood spots enables multiplexed metabolic screening. State reference laboratories in the Great Lakes region anchor demand, where integrated delivery systems negotiate enterprise reagent contracts spanning 40-60 birth facilities.
- Next-Gen Sequencing:Massively parallel sequencing of targeted gene panels or whole exomes generates secondary findings requiring variant interpretation infrastructure. Adoption accelerates fastest in academic medical center laboratories, where bioinformatics specialist hiring lags 14-month average vacancies.
- PCR:Amplification-based detection of specific nucleic acid sequences for cystic fibrosis and spinal muscular atrophy.
- Immunohistochemistry:Antibody-based protein detection for confirmatory testing and tissue characterization.
Dominant by installed base: Tandem Mass Spectrometry. Steepest expansion trajectory: Next-Gen Sequencing.
End User:
End user configuration reflects the shift from hospital autonomy toward network consolidation, with procurement authority migrating upstream in the care continuum.
- Public Health Laboratories:State-operated reference facilities perform confirmatory testing and maintain newborn screening registries under CLIA quality mandates. California Department of Public Health and Texas DSHS anchor volume, piloting mobile screening units with reconfigurable tandem mass spectrometry systems.
- Hospitals:Birth facilities perform initial specimen collection and bedside screening before transferring complex cases. Illinois and Ohio integrated delivery systems now control 70 percent of Great Lakes screening volume through centralized analyzer procurement.
- Clinics:Outpatient sites handle follow-up testing and family counseling for positive screens.
- Homecare Providers:Remote collection services for rural and home birth populations across the Mountain West.
Commanding procurement volume: Public Health Laboratories. Gaining share fastest: Hospitals via network consolidation.
Product Type:
Product margins invert the hardware-software hierarchy, with intangible components capturing disproportionate returns relative to capital equipment.
- Software Solutions:Cloud-based result management platforms integrate state registries and enable real-time reporting to pediatric specialists. Texas and Florida pilot multi-state data sharing architectures that resist API standardization with legacy laboratory information systems.
- Reagents:Consumable enzymes, primers, and chromatography media anchor recurring revenue through long-term service contracts. Whatman-grade filter paper supply faces cotton fiber cost volatility and FDA 510(k) renewal delays.
- Analyzer Devices:Tandem mass spectrometry and PCR instrumentation subject to 18-24 month procurement backlogs from concentrated vendor manufacturing.
- Screening Kits:Pre-configured dried blood spot collection and transport systems.
Highest margin capture: Software Solutions. Fastest volume growth: Reagents driven by expanded panel testing.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Research Triangle Park in North Carolina and the Texas Medical Center in Houston concentrate newborn screening infrastructure through state tax incentives for life sciences facilities. These zones anchor device manufacturing and reference laboratory operations serving multi-state catchment areas.
United States
California and Texas public health laboratories process the highest screening volumes nationally, driven by birth rates exceeding 400,000 annually in each state. The US Department of Health and Human Services Recommended Uniform Screening Panel mandates infrastructure upgrades through federal disorder additions. State Medicaid programs in these jurisdictions have expanded reimbursement for metabolic panels, pulling analyzer procurement into centralized perinatal networks across Los Angeles County and the Dallas-Fort Worth metroplex.
Canada
Ontario and Quebec provincial health ministries are harmonizing screening panels with US standards, opening procurement opportunities for cross-border reagent suppliers. Health Canada regulates in vitro diagnostic devices through the Medical Devices Bureau while provincial laboratories maintain independent quality frameworks. Toronto's Hospital for Sick Children anchors confirmatory testing capacity for central Canadian birth cohorts exceeding 350,000 annually.
Mexico
IMSS and INSABI facilities in Mexico City and Monterrey are expanding metabolic screening coverage through federal health budget allocations. The national newborn screening program remains under development, with 26 of 32 states maintaining partial panel implementation. Guadalajara's Universidad de Guadalajara Medical Center pilots tandem mass spectrometry integration for western Mexico catchment areas.
North America Newborn Screening Market Competitive Landscape
Top-tier vendors anchor the analyzer and reagent segments, while mid-tier specialists concentrate on point-of-care devices and software integration. The market structure reflects concentrated manufacturing capacity in mass spectrometry hardware alongside fragmented competition in hearing screening and pulse oximetry devices. Three strategic archetypes dominate: diversified life sciences conglomerates with full-stack screening portfolios, specialized diagnostic device manufacturers with single-modality depth, and software-focused vendors capturing registry integration margins. Competitive moves center on long-term service contracting with state public health laboratories and strategic partnerships with integrated delivery systems for enterprise procurement.
Among diversified life sciences conglomerates, PerkinElmer and Thermo Fisher Scientific exemplify the full-stack archetype spanning tandem mass spectrometry, PCR platforms, and reagent supply chains. Danaher Corporation occupies a position in the precision diagnostics tier through its operating company structure. These three entities anchor the concentrated vendor base that state reference laboratories rely upon for 18-24 month capital procurement cycles.
| Leading Market Players |
|---|
| PerkinElmer |
| Bio-Rad Laboratories |
| Natus Medical |
| Masimo |
| Danaher Corporation |
| Waters Corporation |
| GE HealthCare |
| Thermo Fisher Scientific |
| Agilent Technologies |
| Others |
Pricing and Supply Chain Analysis
Bioinformatics specialist concentration in California and Texas drives labor-cost differentials that widen pricing-tier spreads across public health laboratory contracts, with variant interpretation scientist scarcity forcing premium compensation packages that tier through reagent and service pricing structures.
Pricing Analysis
Lead-time-driven pricing angles dominate analyzer procurement, with state laboratories paying premiums for 12-month delivery windows against 24-month standard backlogs while spot inventory from reagent stockpiles trades at discounts. Three-tier pricing structure across premium, standard, and economy levels separates CLIA-certified reference laboratories from hospital-based collection sites and rural homecare providers. Price differentiation hinges on after-sales service bundling and CLIA compliance certification tiers. Cost compression in genetic test panels is intensifying because whole-exome sequencing price declines below $500 per test are forcing reagent suppliers to absorb margin erosion. Hospital networks within integrated delivery systems exhibit highest price sensitivity due to centralized procurement leverage, while standalone public health laboratories show lowest sensitivity given federal mandate compliance requirements.
Supply Chain Analysis
Warehouse-distribution layer configuration centers on regional distribution centers in California, Texas, and Illinois that feed hub-and-spoke patterns into perinatal care networks spanning 40-60 birth facilities. Manufacturing concentration in the United States, Germany, and Japan anchors tandem mass spectrometry device production, while Whatman-grade filter paper supply draws from cotton fiber processing in the United States and European Union. Raw material dependencies include specialized chromatography media, PCR primers, and dried blood spot card filter paper. Single-source vulnerability concentrates in Whatman-grade filter paper manufacturing where FDA 510(k) renewal delays create regulatory chokepoints. Distribution runs through integrated delivery system procurement offices that negotiate enterprise reagent contracts displacing hospital-based laboratory director autonomy.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Supply-constrained dynamics in tandem mass spectrometry manufacturing prop pricing power for incumbent vendors, with 18-24 month procurement backlogs limiting state laboratory bargaining leverage and sustaining premium service contract terms.
For Market Incumbents: Deploy long-term service contracting as the primary lever to lock in public health laboratory relationships before reconfigurable mass spectrometry systems accelerate replacement cycles. Consolidate genetic testing capabilities into regional hub structures to capture economies of scale as New York and Pennsylvania laboratories fragment testing menus. Counter bioinformatics specialist scarcity through automated variant interpretation software development that reduces dependence on 14-month vacancy cycles. For New Entrants and Emerging Players: Rural birth centers across the Mountain West represent an underserved buyer archetype where point-of-care screening device miniaturization can bypass entrenched reference laboratory relationships. Target homecare provider networks for remote dried blood spot collection services that extend screening coverage beyond hospital-based programs. Pursue Canadian provincial health ministry contracts as harmonization with US Recommended Uniform Screening Panel standards opens cross-border reagent opportunities without direct incumbent competition. For Investors and Strategic Acquirers: Re-rating potential sits with software-as-a-service result management platforms given cloud-based state registry integration capturing disproportionate margin pools relative to hardware. Five-to-ten year viability favors vendors with established CLIA laboratory relationships and FDA in vitro diagnostic device clearances that resist rapid displacement. Watch for Health Canada and provincial health ministry alignment announcements as inflection indicators for cross-border market expansion.| Strategic Initiative | Industry Significance |
|---|---|
| CLIA Laboratory Certification Investment | Proficiency testing upgrades mandated by the 1988 Clinical Laboratory Improvement Amendments drive reagent standardization across state reference laboratories. |
| Cloud-Based Registry Integration Platform | Texas and Florida pilot multi-state data sharing architectures that capture margin pools exceeding hardware manufacturing returns. |
| Reconfigurable Mass Spectrometry System Development | California Department of Public Health mobile screening units compress capital expenditure cycles from seven-year to three-year intervals. |
| Whole-Exome Sequencing Cost Reduction Program | Diagnostic yield improvements accelerate genetic panel adoption for secondary findings as sequencing prices fall below $500 per test. |
| Canadian Provincial Harmonization Partnership | Ontario and Quebec health ministry alignment with US Recommended Uniform Screening Panel standards opens cross-border reagent contract opportunities. |
Research Methodology
Multi-period observation of state Medicaid reimbursement expansion patterns and Recommended Uniform Screening Panel disorder additions anchored the trend analysis, supplemented by interviews with public health laboratory directors, CLIA compliance officers, perinatal care network procurement managers, and tandem mass spectrometry device manufacturers. Secondary validation drew from FDA 510(k) filings, CMS Medicare reimbursement databases, state health department budget appropriations, and Clinical Laboratory Improvement Amendments proficiency testing records. Bottom-up volume estimates from individual state newborn screening program throughput combined with top-down market sizing from analyzer device installed base and reagent consumption patterns.
Input-output matrix framing structured the analytical approach across the projection horizon, modeling segmentation dimensions including test type, technology platform, end user configuration, and product category alongside geographic birth volume distribution and state funding intensity. CAGRs derived from equipment replacement cycle compression, panel expansion trajectories, and sequencing cost decline curves. Forecast inputs incorporated CLIA laboratory quality mandate compliance timelines and Health Canada provincial harmonization progress indicators.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to incidental findings regulatory guidance from the US Department of Health and Human Services and bioinformatics specialist hiring pipeline constraints. Outputs reflect documented assumptions regarding state Medicaid reimbursement stability and tandem mass spectrometry vendor manufacturing capacity expansion. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Testing Services
United States Testing, Inspection, and Certification (TIC) Market
Testing Services
US Independent Diagnostic Testing Facility Market
Testing Services
Global GMP Testing Service Market
Testing Services
Hemotransmissive Infections Testing Market
Testing Services
Global Newborn Screening Market
Testing Services
Apolipoprotein Testing Market
Testing Services
Rift Valley Fever Testing Market
Testing Services
South America Endotoxin and Pyrogen Testing Market
Testing Services
Global Laboratory Proficiency Testing Market
Testing Services
Arthropod-Borne Viral Infections Testing Market
Testing Services
Mono Rapid Testing Market
Testing Services
Vials Leak Testing Market
Testing Services
At-Home Celiac Testing Market
Testing Services
Biological Safety Testing Products and Services Market
Testing Services
Fertility Testing Market
Testing Services
Irradiation Sterilization Services Market