
 Fluid Viscous Dampers Market | 2026-2036
Fluid Viscous Dampers Market Size, Share, and Industry Trends Forecast 2026-2036
Fluid Viscous Dampers Market Insights
Buyer concentration in the fluid viscous dampers sector is pivoting toward national infrastructure agencies and large-scale engineering procurement consortia. Taylor Devices, Inc. leverages its long-standing supply relationships with North American bridge authorities to sustain repeat contracting visibility. Sumitomo Riko Company Limited anchors the Asia-Pacific supply base through integrated elastomer and damper manufacturing. GERB Vibration Control Systems competes on precision-tuned product lines for specialized industrial machinery applications.
Fluid viscous dampers are hydraulic energy-dissipation devices that convert kinetic motion into heat through the shearing of silicone-based or mineral-oil fluids constrained within precision-machined cylinder assemblies, typically operating across temperature ranges from minus forty to plus two hundred degrees Celsius. These devices primarily protect structures and mechanical systems from seismic, wind, or operational vibration damage by reducing displacement amplitude and force transmission. The seismic product category occupies the highest-value installation tier due to mandatory code compliance in earthquake zones, while bridge application demand generates the most consistent procurement cycles driven by federal replacement schedules. Double tube configurations lead unit volume in building installations where space constraints and bidirectional loading govern specification.
FEMA guidelines in the United States, EN 15129 standards in Europe, and Japan's Ministry of Land, Infrastructure, Transport and Tourism technical certification protocols collectively define performance benchmarks that determine market access for damper suppliers. Compliance with these frameworks shapes R&D allocation toward validated prototype testing and third-party witness programs. Stakeholders must monitor evolving national building code adoptions in seismically active emerging economies to anticipate procurement windows before specification lock-in occurs.
Market Dynamics
Seismic code harmonization across Japan, California, and Italy is compressing specification windows and forcing damper suppliers to validate prototypes against multiple national test protocols simultaneously, raising pre-market investment thresholds.
Growth Catalysts
- FEMA P-1050 Guidelines:Federal adoption of updated performance-based seismic design standards in the United States mandates energy-dissipation devices in new federal building construction, creating specification pull-through for bridge and high-rise applications.
- Silicone fluid formulation advances:Next-generation high-viscosity-index polymers extend operational temperature ranges, enabling deployment in arctic pipeline supports and desert solar tracking systems previously unsuitable for hydraulic damping.
- Tokyo Metropolitan retrofit mandates:Japan's 1981 Building Standard Act amendments require structural upgrades for pre-code commercial towers, generating concentrated procurement from property management consortia in the Greater Tokyo Area.
Market Restraints
- Specialized cylinder machining capacity:Precision honing equipment for bore tolerances below 10 microns concentrates in German and Japanese machine tool suppliers, creating single-source dependencies for damper OEMs.
- Mineral oil price volatility:Base stock costs for industrial hydraulic fluids fluctuate with refinery throughput decisions, compressing margin predictability for standard-grade damper product lines.
- Lead-acid battery seismic isolation substitution:Some data center operators in low-seismic zones specify elastomeric base isolation over fluid dampers to avoid hydraulic maintenance protocols.
Strategic Opportunities
- Indonesia's building code modernization:Jakarta's upcoming adoption of international seismic standards creates first-mover positioning for suppliers establishing local testing partnerships before specification lock-in.
- Wind turbine nacelle damping:Offshore turbine OEMs specify compact fluid dampers for blade pitch control vibration suppression, opening industrial applications beyond traditional civil engineering.
- EU Green Deal construction incentives:Member-state recovery funds prioritize seismic retrofit of public buildings, channeling procurement toward certified energy-dissipation devices under accelerated environmental criteria.
Industry Challenges
- Multi-protocol test engineering talent:Simultaneous validation against FEMA, EN 15129, and JIS standards requires specialized laboratory personnel capable of interpreting divergent loading protocols, creating recruitment bottlenecks.
- Legacy bridge anchor integration:Retrofit installations on 1960s-era California suspension bridges demand custom mounting bracket fabrication, extending project timelines and requiring site-specific engineering resources.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fluid Viscous Dampers Market |
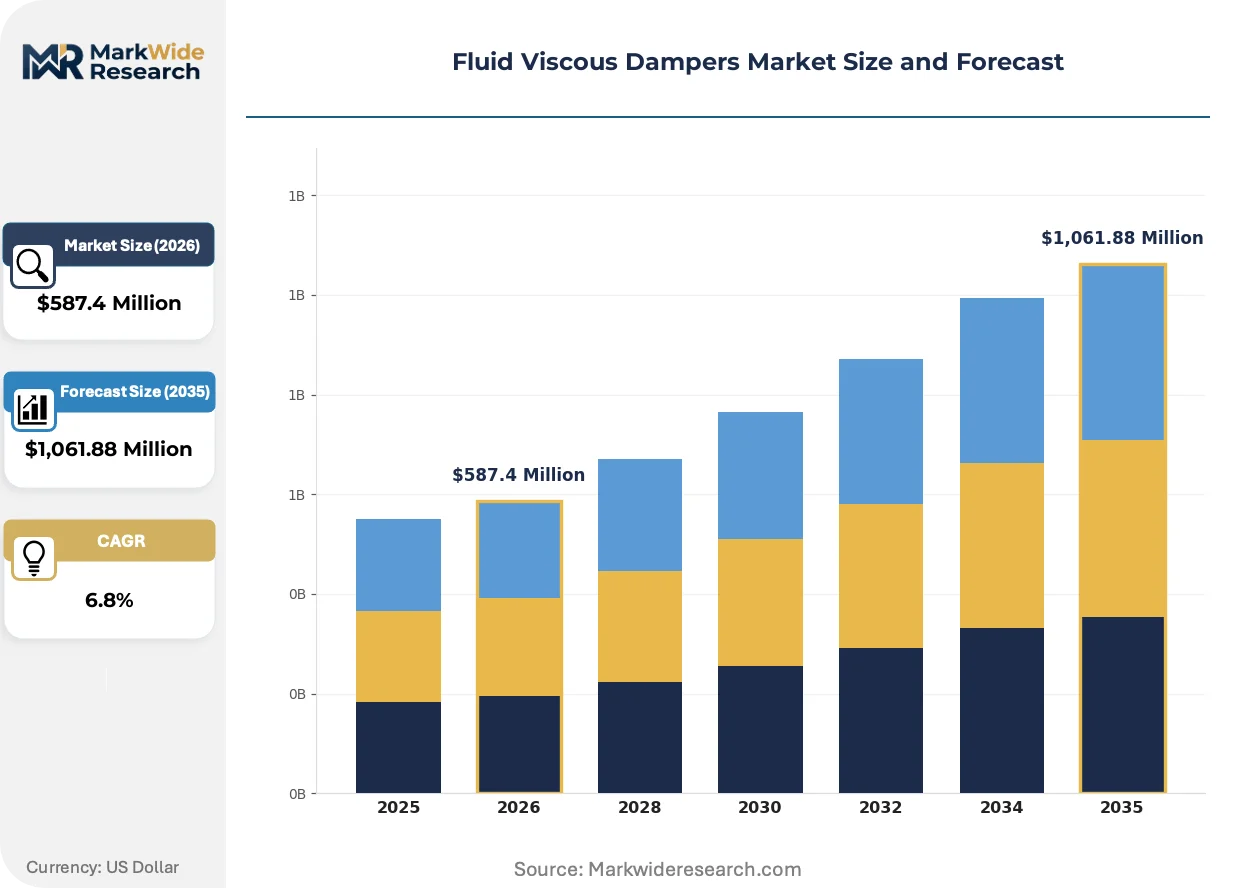
| Market Size in 2026 | $587.4 Million |
| Market Size in 2035 | $1,061.88 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single Tube, Double Tube, Piston, Seismic Application: Building, Bridge, Vehicle, Machinery End User: Construction, Automotive, Aerospace, Industrial Installation Type: Onshore, Offshore, Integrated, Standalone |
| Companies Covered | Sumitomo Riko Company Limited, Dynamic Isolation Systems, Inc., Taylor Devices, Inc., Kawakin Core-Tech Co., Ltd., Toyo Tire Corporation, Maurer SE, GERB Vibration Control Systems, Mageba SA, FIP Industriale S.p.A., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fluid Viscous Dampers Market Trends and Innovations
Active material integration and predictive maintenance architectures are displacing passive-only damper specifications, while regulatory pressure accelerates standardization of performance validation protocols across previously fragmented national codes.
Magnetorheological fluid technology is converging with traditional hydraulic architectures to enable real-time damping coefficient adjustment via electromagnetic field modulation. Wind turbine OEMs in Northern Europe specify these semi-active systems for blade pitch control. The technology is compressing the performance gap between passive dampers and fully active control systems at intermediate cost points.
EN 15129's 2023 revision tightens witness testing requirements for energy-dissipation devices sold into EU member states. Manufacturers must now submit production-line samples for third-party validation at notified bodies. Bridge applications in Italy and Romania face the steepest compliance ramps due to pending national adoptions of the updated annex.
Consolidated procurement through engineering-procurement-construction consortia displaces fragmented municipal purchasing in large-scale infrastructure. Turnkey bridge replacement projects in California now specify dampers through prime contractor package deals rather than owner-direct sourcing. This channel compression privileges suppliers with bonded surety capacity and multi-year maintenance contracting capabilities.
Fluid Viscous Dampers Market Segmentation
Fluid viscous damper procurement decisions pivot on seismic code compliance tiers, installation environment constraints, and lifecycle maintenance protocols. Specification engineers weight product configuration against structural load requirements and ambient temperature operating windows.
Product Type:
Buyers prioritize cylinder architecture based on bidirectional loading requirements and spatial envelope limitations in target structures.
- Seismic:These dampers incorporate validated stroke capacities and force-velocity curves certified under FEMA, EN 15129, or JIS protocols. Procurement concentrates in Japan's metropolitan retrofit programs and California bridge authorities where mandatory code compliance eliminates non-certified alternatives. Tokyo's 1981 Building Standard Act amendments sustain concentrated demand from property management consortia.
- Double Tube:Concentric cylinder configurations accommodate reversed loading without external re-centering mechanisms. Installations dominate high-rise building cores in space-constrained urban corridors where envelope dimensions govern specification. The architecture enables maintenance access without damper removal.
- Single Tube:Compact unidirectional designs serve wind vibration suppression in tower structures and industrial stack applications.
- Piston:Precision-machined rod-and-cylinder assemblies target industrial machinery isolation with sub-micron bore tolerances.
Volume sits with Seismic; growth tilts toward Double Tube.
Application:
Project scale and funding mechanisms differentiate procurement cycles across civil engineering versus industrial end-uses.
- Bridge:Federal replacement schedules in the United States and Japan generate the most predictable procurement cadence. California's toll bridge authorities and Japan's Ministry of Land, Infrastructure, Transport and Tourism deploy multi-year maintenance contracting that privileges suppliers with bonded surety capacity. Custom mounting bracket fabrication for 1960s-era suspension bridge retrofits extends project timelines.
- Building:High-rise seismic retrofits concentrate in Tokyo, Los Angeles, and San Francisco where pre-code commercial towers face mandatory upgrades. Double tube configurations lead specification due to bidirectional earthquake loading requirements.
- Machinery:Precision-tuned product lines serve specialized industrial vibration isolation for German and Japanese machine tool OEMs.
- Vehicle:Suspension and cab isolation applications in heavy-duty commercial trucks and rail rolling stock.
Procurement frequency peaks in Bridge; specification complexity concentrates in Building.
End User:
Capital expenditure cycles and regulatory exposure determine damper specification authority across customer categories.
- Construction:Engineering-procurement-construction consortia now consolidate procurement for turnkey infrastructure projects. California bridge replacements specify dampers through prime contractor package deals rather than owner-direct sourcing. This channel compression rewards suppliers with multi-year maintenance contracting capabilities.
- Industrial:Wind turbine OEMs in Northern Europe specify compact fluid dampers for blade pitch control vibration suppression. Offshore turbine nacelle damping opens industrial applications beyond traditional civil engineering.
- Automotive:Heavy-duty truck and specialty vehicle manufacturers specify cab and suspension isolation systems.
- Aerospace:Landing gear and flight control surface damping for commercial and defense aircraft platforms.
Contract visibility runs through Construction; technology differentiation concentrates in Industrial.
Installation Type:
Environmental exposure and integration architecture determine sealing specifications and corrosion protection requirements.
- Onshore:Standard-grade installations dominate building and bridge applications with ambient temperature ranges from minus forty to plus two hundred degrees Celsius. Silicone fluid formulations extend operational windows for arctic pipeline supports and desert solar tracking systems.
- Offshore:Marine-grade sealing and cathodic protection systems serve wind turbine foundations and coastal bridge piers. Northern European offshore turbine OEMs specify these configurations for salt spray exposure.
- Integrated:Embedded damper assemblies within structural steel moment frames or base isolation systems.
- Standalone:Externally mounted replaceable units for maintenance-accessible retrofit applications.
Unit volume concentrates in Onshore; specification premiums accrue to Offshore.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand for fluid viscous dampers concentrates in seismically active urban corridors where building code mandates drive procurement. Japan, the United States, and Italy anchor installation volume through federal retrofit programs and bridge replacement schedules.
Japan
Tokyo's metropolitan retrofit mandates and the 1981 Building Standard Act amendments sustain concentrated procurement from property management consortia. The Ministry of Land, Infrastructure, Transport and Tourism technical certification protocols govern market access. Kanto region commercial towers generate repeat contracting for seismic-grade damper suppliers.
United States
FEMA P-1050 guidelines mandate energy-dissipation devices in new federal building construction, creating specification pull-through across bridge and high-rise applications. California's toll bridge authorities deploy multi-year maintenance contracting that privileges suppliers with bonded surety capacity. Los Angeles and San Francisco concentrate building retrofit demand.
Italy
Pending national adoption of EN 15129's 2023 revision tightens witness testing requirements for bridge applications. EU Green Deal construction recovery funds prioritize seismic retrofit of public buildings. Procurement concentrates in Rome and northern industrial corridors where infrastructure age drives replacement cycles.
Germany
Precision honing equipment suppliers for cylinder bore tolerances below 10 microns anchor machine tool dependencies for damper OEMs. Industrial machinery isolation demand from German machine tool OEMs sustains specialized product lines. Bavaria and Baden-Württemberg concentrate precision manufacturing clusters.
Indonesia
Jakarta's upcoming adoption of international seismic standards creates first-mover positioning for suppliers establishing local testing partnerships. The country's national building regulator is modernizing construction codes to align with earthquake-resistant design protocols. Java-based infrastructure projects represent emerging specification windows before code lock-in occurs.
Fluid Viscous Dampers Market Competitive Landscape
Japanese producers anchor one tier; German specialists hold precision-tuned industrial applications. The vendor base fragments across seismic certification specialists, integrated elastomer manufacturers, and precision machining houses. Three archetypes dominate: bridge authority contractors with repeat visibility, industrial machinery isolation specialists, and integrated material-damper manufacturers. Competitive moves center on bonded surety capacity expansion and multi-year maintenance contracting capabilities.
Among Japanese integrated manufacturers, Sumitomo Riko Company Limited and Kawakin Core-Tech Co., Ltd. exemplify the material-damper integration archetype. Taylor Devices, Inc. occupies a position within the North American bridge contracting tier. GERB Vibration Control Systems represents the precision-tuned industrial specialization vector. These three anchors illustrate how geographic origin and corporate structure align with distinct competitive positioning in certification-heavy procurement environments.
| Leading Market Players |
|---|
| Sumitomo Riko Company Limited |
| Dynamic Isolation Systems, Inc. |
| Taylor Devices, Inc. |
| Kawakin Core-Tech Co., Ltd. |
| Toyo Tire Corporation |
| Maurer SE |
| GERB Vibration Control Systems |
| Mageba SA |
| FIP Industriale S.p.A. |
| Others |
Pricing and Supply Chain Analysis
Magnetorheological fluid integration is compressing cost economics for semi-active damper architectures while simultaneously concentrating procurement leverage among wind turbine OEMs and bridge authorities with multi-year maintenance contracting capacity. This technology shift rewards suppliers with captive silicone polymer formulation capabilities and third-party witness testing infrastructure, widening margin dispersion between integrated manufacturers and assembly-dependent competitors.
Pricing Analysis
Volume concentrates in standard-grade seismic dampers certified under FEMA and EN 15129 protocols, while margins accrue to precision-tuned industrial configurations for German machine tool OEMs. Three-tier pricing structure separates seismic-grade certified products from standard bridge replacements and economy wind-suppression units. Cost compression in the standard tier is intensifying because mineral oil base stock costs fluctuate with refinery throughput decisions. Municipal bridge authorities exhibit the highest price sensitivity due to federal replacement schedule constraints, whereas offshore wind turbine OEMs prioritize performance guarantees over unit cost.
Supply Chain Analysis
Single-source vulnerability sits with precision honing equipment suppliers in Germany and Japan for cylinder bore tolerances below 10 microns. Manufacturing gravity centers on Japan, the United States, and Germany for finished damper assemblies, while silicone fluid formulations draw from specialized polymer suppliers in the United States and Japan. Tariff exposure on precision-machined cylinder components threatens margin stability for assembly-dependent OEMs. Distribution runs through engineering-procurement-construction consortia for turnkey infrastructure projects, compressing direct municipal procurement channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is a vertical-integration race. Players are pursuing backward integration into silicone fluid formulation to escape mineral oil price volatility and secure supply continuity for arctic and desert deployment specifications.
For Market Incumbents: Anticipate specification compression from magnetorheological semi-active systems by accelerating certified prototype pipelines for EN 15129's tightened witness testing requirements. Defend position through bonded surety capacity expansion and multi-year maintenance contracting with California toll bridge authorities. Prioritize recruitment of multi-protocol test engineering talent capable of simultaneous FEMA, EN 15129, and JIS validation to compress pre-market investment thresholds. For New Entrants and Emerging Players: Digital-channel route through engineering-procurement-construction consortium procurement portals offers bypass around entrenched bridge authority relationships. Target Indonesia's building code modernization before specification lock-in occurs, establishing local testing partnerships with Jakarta's national building regulator. Prioritize compact fluid damper configurations for offshore wind turbine nacelle applications where incumbents lack dedicated product lines. For Investors and Strategic Acquirers: Exit pathways concentrate in trade sales to integrated elastomer manufacturers seeking damper assembly capabilities. Long-term viability hinges on certification infrastructure rather than manufacturing scale alone. Acquisition target archetype: precision machining houses with sub-10-micron bore tolerance capacity and existing relationships with German or Japanese machine tool OEMs. Watch EN 15129 adoption velocity across EU member states as inflection indicator for compliance-driven procurement windows.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Silicone Fluid Formulation | Captive polymer supply secures margin stability against mineral oil volatility and enables arctic deployment specifications. |
| Multi-Protocol Test Laboratory Accreditation | Simultaneous FEMA, EN 15129, and JIS validation capability compresses pre-market investment timelines for seismic-grade products. |
| Bonded Surety Capacity Expansion | California bridge authorities and Japanese MLIT procurement now require multi-year maintenance contracting guarantees. |
| Offshore Wind Turbine Nacelle Product Line Development | Northern European OEMs specify compact dampers for blade pitch control vibration suppression beyond traditional civil engineering. |
| Indonesia Local Testing Partnership Establishment | Jakarta's building code modernization creates first-mover positioning before specification lock-in occurs. |
Research Methodology
Trade association filings, customs and import-export records, and regulatory submission databases formed the secondary backbone for demand quantification and supply-side mapping. Primary interviews with bridge authority procurement officers, seismic test laboratory directors, wind turbine OEM platform engineers, and fluid viscous damper manufacturing executives validated specification trends and pricing dynamics. Bottom-up installation tracking across Japan's Kanto region, California's toll bridge inventory, and Italy's public building retrofit pipeline was cross-referenced against top-down market sizing from equipment supplier revenue disclosures.
Historical trendline analysis of federal replacement schedules and building code amendment cycles informed projection frameworks across the analysis window. Segmentation dimensions modeled include product architecture, application environment, end-user procurement authority, and installation type. CAGRs were derived from elasticity-adjusted demand curves incorporating seismic code adoption velocity and infrastructure age distribution. Forecast inputs incorporated silicone polymer supply constraints and precision machining capacity utilization at German and Japanese machine tool suppliers.
The model holds under steady regulatory enforcement of FEMA, EN 15129, and JIS certification protocols; deviation in code harmonization timelines or mineral oil price volatility spikes would shift procurement cadence and margin distribution. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Structural Engineering
Europe Structural Health Monitoring Market
Structural Engineering
Civil Engineering Market
Structural Engineering
Europe Insulated Concrete Form (ICF) Market
Structural Engineering
Structural Steel Market
Structural Engineering
Self-Compacting Concrete Market
Structural Engineering
Concrete Wind Tower Market
Structural Engineering
Self-Levelling Concrete Market
Structural Engineering
Bridge Expansion Joint Market
Structural Engineering
Southeast Asia Anchors and Grouts Market
Structural Engineering
Prestressed Concrete Market
Structural Engineering
Europe Facade Market
Structural Engineering
Structural Lightweight Concrete Market
Structural Engineering
Europe Bridge Bearings Market
Structural Engineering
North America Anchors and Grouts Market
Structural Engineering
Geotechnical Engineering Market
Structural Engineering
Asia-Pacific Structural Health Monitoring Market