
 Metal Structural Insulation Panels Market | 2026-2036
Metal Structural Insulation Panels Market Size, Share, and Industry Trends Forecast 2026-2036
Metal Structural Insulation Panels Market Analysis
Aftermarket service revenue for panel system refurbishment and thermal performance auditing is fragmenting across regional contractors and original equipment networks. Kingspan Group leverages its global manufacturing footprint to sustain specification-grade product availability across multiple climate zones. Metl-Span competes through specialized cold-storage panel architectures that anchor its position in food-chain infrastructure. Nucor Building Systems extends its steel supply chain dominance into integrated panel solutions for industrial building envelopes.
Metal structural insulation panels are factory-engineered composite assemblies comprising steel or aluminum facings bonded to rigid insulating cores, manufactured through continuous lamination or discontinuous press processes to achieve specified R-values and structural spanning capacity. These systems serve primarily as thermal envelope barriers in buildings requiring precise temperature control, structural load-bearing capacity, and rapid installation. Polyurethane-cored panels dominate specification-intensive segments due to superior thermal conductivity and fire-resistant formulations, while polystyrene variants occupy cost-sensitive agricultural and light industrial applications where moderate insulation performance suffices. Wall panels and roof panels collectively represent the primary application dimensions, with facade panels gaining specification traction in architecturally exposed commercial envelopes where aesthetic finish integration matters.
Building codes enforced by the International Code Council in the United States, the EU Green Deal framework administered through national implementation bodies in Europe, and BIS thermal performance standards in India collectively shape product certification requirements and market access conditions for panel manufacturers. These regulatory instruments mandate minimum insulation values, fire reaction classifications, and structural load ratings that determine which core materials and facing specifications qualify for permitted construction. Stakeholders must monitor evolving carbon-accounting rules for embodied energy in building materials, as these frameworks are beginning to influence procurement criteria beyond operational thermal performance metrics.
Market Dynamics
Cold storage logistics operators are expanding warehouse footprints with thermally efficient envelope systems, while stringent building energy codes in multiple jurisdictions mandate higher thermal resistance values for commercial envelopes. This dual pressure from operational demand and regulatory compliance is compressing specification cycles and favoring factory-engineered composite assemblies over field-built alternatives.
Growth Catalysts
- EU Green Deal framework:National implementation bodies across Europe enforce escalating carbon-performance standards for building envelopes, mandating panel specifications that exceed legacy insulation values.
- Data center construction clusters:Hyperscale facility operators in the United States specify high-R-value metal structural insulation panels for thermal stability in server environments.
- Polyurethane core chemistry:Fire-resistant formulations with superior thermal conductivity enable thinner wall assemblies while maintaining code-compliant fire reaction classifications.
Market Restraints
- Steel and aluminum input volatility:Facing price swings in commodity metals compress margin predictability for panel laminators operating on fixed-price construction contracts.
- Discontinuous press capacity concentration:North American and European equipment bases limit surge production capability during seasonal construction peaks.
- Polystyrene substitution ceiling:Moderate insulation performance in agricultural applications caps specification upward mobility against polyurethane alternatives.
Strategic Opportunities
- India BIS thermal performance standards:Emerging enforcement of building envelope codes creates first-mover positioning for certified panel suppliers in commercial cold chain infrastructure.
- Facade panel aesthetic integration:Architecturally exposed commercial envelopes specify integrated finish systems that command premium positioning over utilitarian industrial applications.
- Aftermarket thermal auditing services:Building owners seek envelope performance verification to validate energy code compliance and insurance risk profiles.
Industry Challenges
- Continuous lamination technician scarcity:Factory-engineered composite production requires specialized bonding process expertise that outpaces vocational training pipeline output.
- Multi-jurisdiction certification latency:Panel manufacturers face staggered approval timelines across ICC, BIS, and EU national implementation bodies for equivalent product specifications.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Metal Structural Insulation Panels Market |
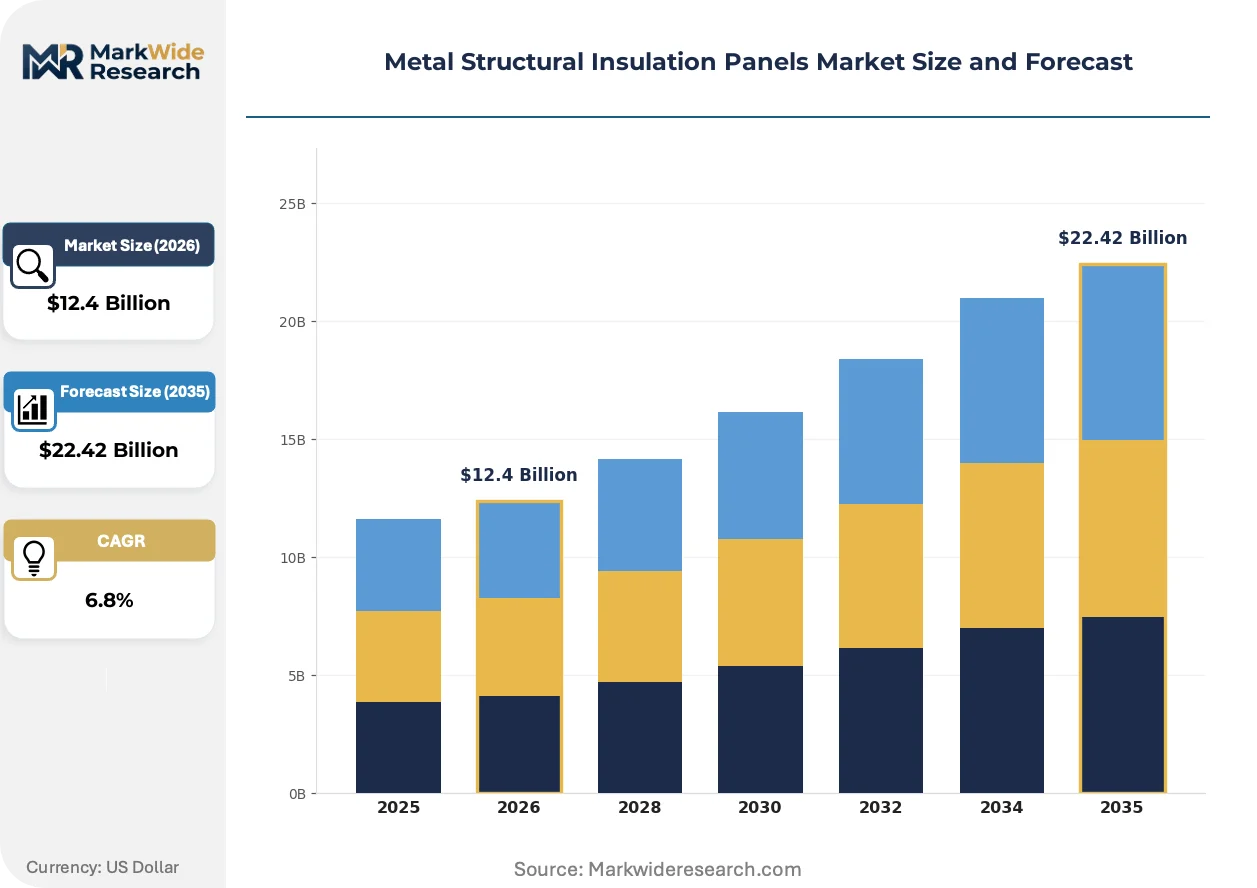
| Market Size in 2026 | $12.4 Billion |
| Market Size in 2035 | $22.42 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polystyrene, Polyurethane, Phenolic, EPS End User: Construction, Agriculture, Cold Storage, Industrial Insulation Thickness: Low, Medium, High, Ultra-High Application: Wall Panels, Roof Panels, Floor Panels, Facade Panels |
| Companies Covered | Kingspan Group, Metl-Span, Nucor Building Systems, Owens Corning, ACME Panel, American Insulated Panel, KPS Global, PFB Corp., ArcelorMittal, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Metal Structural Insulation Panels Market Emerging Trajectories
Metal structural insulation panel manufacturing is experiencing material convergence and process digitization that compress specification-to-installation timelines. Factory automation and core chemistry advances are enabling performance tiers that previously required custom engineering.
Polyurethane-polyisocyanurate hybrid core formulations is hybridizing thermal performance and fire resistance in a single factory-engineered layer. Cold storage operators in the United States specify these cores for warehouse envelopes requiring simultaneous R-value maximization and NFPA 285 compliance. The technology is compressing the traditional tradeoff between insulation depth and wall assembly thickness.
REACH chemical registration requirements in Europe now govern blowing agent chemistries used in rigid foam core production. Panel laminators reformulate formulations to eliminate hydrofluorocarbon compounds ahead of F-Gas Regulation phase-down schedules. Commercial envelope specifications in Germany and France increasingly require Environmental Product Declarations that document embodied carbon across the core material supply chain.
Building owners now unbundle envelope procurement from general contractor packages to direct relationships with certified panel fabricators. Data center developers in Virginia and Texas negotiate direct supply agreements that span manufacturing through installation supervision. This disintermediation compresses specification iteration cycles and transfers thermal performance liability to the panel system provider rather than the construction manager.
Metal Structural Insulation Panels Market Segmentation
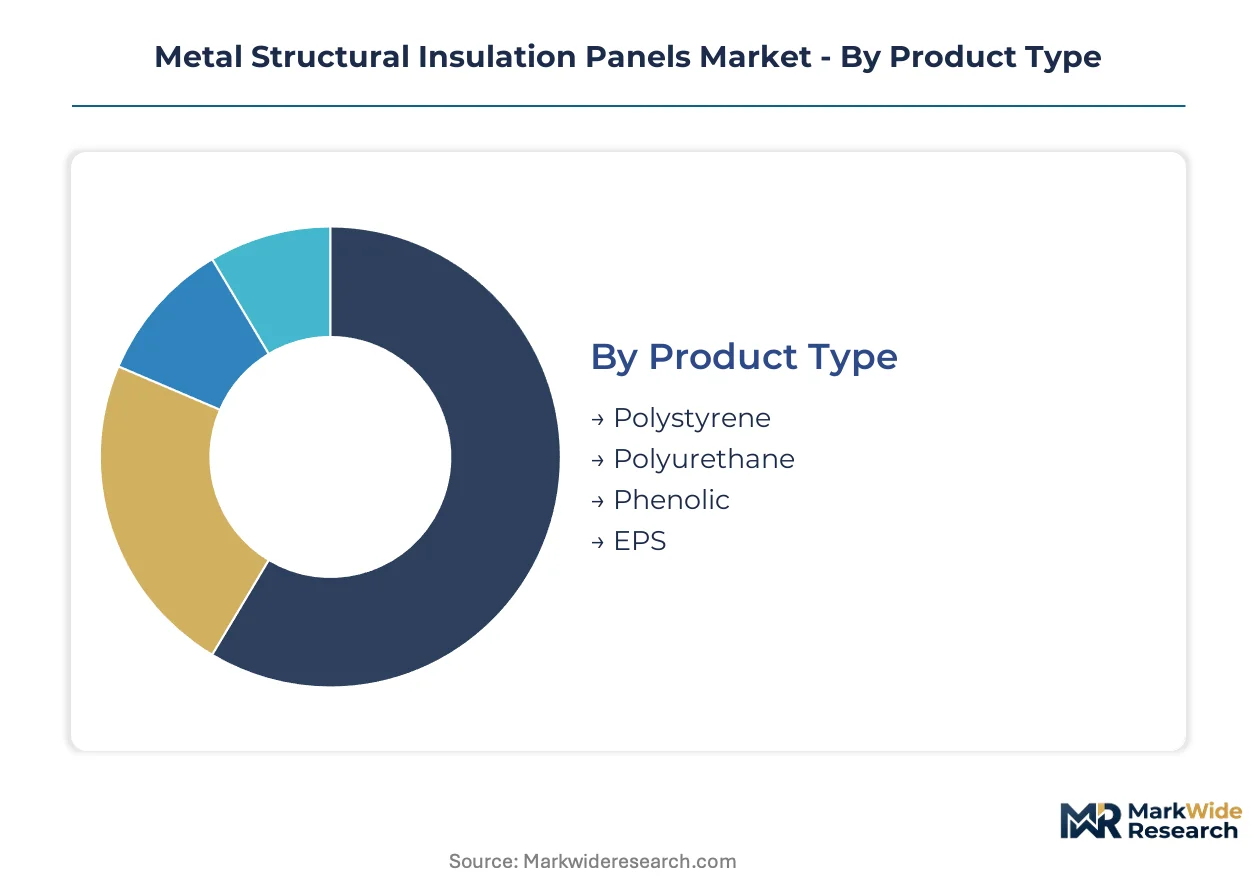
Material chemistry and installation geometry determine specification pathways in metal structural insulation panels. Procurement patterns diverge sharply between cost-driven agricultural buyers and performance-focused cold storage operators. Thickness tiers and application formats further stratify vendor positioning across commercial and industrial construction channels.
Product Type:
Core material selection maps directly to thermal conductivity requirements and fire code compliance tiers.
- Polystyrene:Expanded and extruded variants deliver moderate R-values at the lowest material cost point in the category. Agricultural building envelopes in the United States specify polystyrene-cored panels for barns and equipment shelters where thermal precision matters less than capital expenditure control.
- Polyurethane:Closed-cell formulations achieve the highest thermal resistance per inch of thickness among standard core options. Cold storage warehouse construction in Germany and France mandates polyurethane cores to meet EU Green Deal thermal performance thresholds while minimizing envelope depth.
- Phenolic:Low-smoke fire reaction properties suit transportation infrastructure and high-occupancy commercial envelopes. The material occupies niche specification territory where NFPA 285 compliance intersects with stringent smoke density limits.
- EPS:Molded bead foam provides lightweight insulation for temporary structures and modular building systems. The segment serves event infrastructure and rapid-deployment facilities across India and Southeast Asian construction markets.
Polystyrene commands the established base. The steepest expansion runs through polyurethane.
End User:
Demand concentration varies dramatically across customer categories with divergent procurement sophistication and performance requirements.
- Construction:General commercial building envelopes specify metal structural insulation panels for speed of installation and weather-tight performance. Data center developers in Virginia and Texas negotiate direct supply agreements that compress specification-to-installation timelines.
- Cold Storage:Temperature-controlled logistics infrastructure requires envelope systems maintaining precise thermal boundaries across extreme ambient differentials. Operators expanding warehouse footprints prioritize panels with verified thermal bridging performance and validated long-term R-value retention.
- Agriculture:Poultry housing, dairy facilities, and crop storage buildings select panels primarily on cost-per-square-foot metrics. Moderate insulation performance suffices where biological heat loads and ventilation rates dominate thermal management.
- Industrial:Manufacturing facilities and process plants specify panels for both envelope and internal partition applications. Fire resistance ratings and structural load capacity drive specification more than thermal optimization in heavy industrial settings.
Cold storage claims the fastest-growing trajectory. Construction retains the largest installed base.
Insulation Thickness:
Thickness tiers correlate with climate severity, energy code stringency, and lifecycle cost analysis horizons.
- Low:Two to three inches of core material serves temperate climate zones and seasonal structures. Agricultural applications in the southern United States specify this tier for cost containment in mild winter conditions.
- Medium:Four to six inches balances thermal performance with structural efficiency in standard commercial construction. This tier captures the bulk of specification activity across mixed-use developments and light industrial facilities.
- High:Seven to ten inches addresses severe climate envelopes and sub-zero cold storage requirements. Northern European markets and Arctic construction projects specify high-thickness assemblies to meet aggressive U-value targets.
- Ultra-High:Exceeding ten inches, these assemblies serve specialized scientific facilities, cryogenic storage, and passive house certification projects. The segment demands custom engineering and extended lead times from certified fabricators.
Medium thickness dominates current procurement volumes. Ultra-High is climbing the fastest as net-zero building standards proliferate.
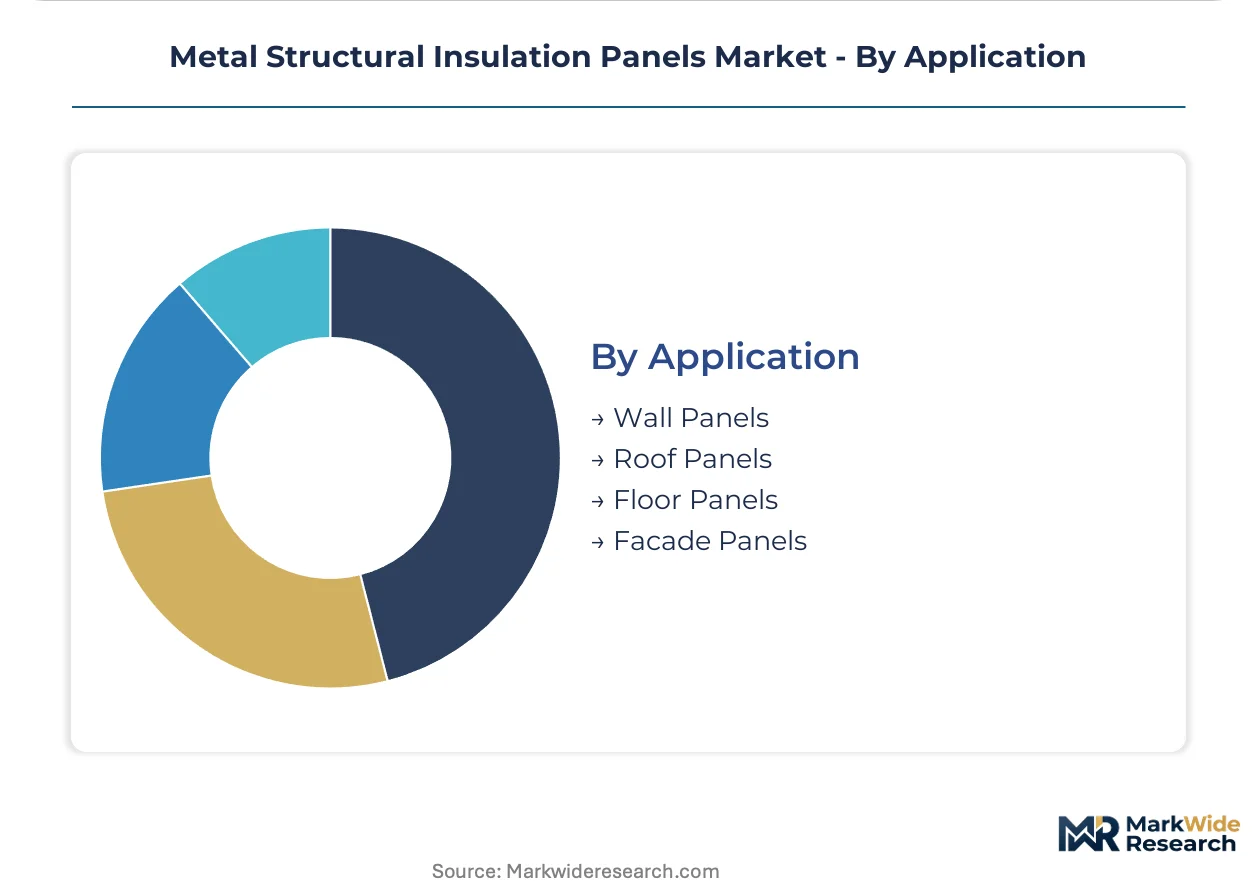
Application:
Installation geometry determines panel aspect ratios, edge detailing, and structural connection requirements.
- Wall Panels:Vertical spanning assemblies carry wind loads and transfer lateral forces to primary structural frames. Cold storage warehouses in the United States specify wall panels with integrated vapor barriers and thermal break connections.
- Roof Panels:Horizontal or sloped installations manage snow loads, ponding water, and thermal expansion across large clear spans. Industrial facilities prioritize roof panels with standing seam profiles and integrated daylighting options.
- Floor Panels:Load-bearing assemblies provide thermal isolation for raised floors in cleanrooms and temperature-sensitive production environments. Semiconductor fabrication facilities in South Korea specify floor panels with electrostatic discharge properties.
- Facade Panels:Architecturally exposed surfaces integrate decorative finishes, rainscreen configurations, and curtain wall attachment systems. Commercial developments in France and Germany increasingly specify facade panels with Environmental Product Declaration certification.
Wall panels anchor the installed base. Facade panels are gaining share fastest as aesthetic integration requirements intensify.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply across geographies: cold storage logistics drives specification in temperate markets, while data center thermal management dominates procurement in the United States. Building code stringency and industrial construction cycles create distinct regional demand profiles.
United States
Hyperscale data center construction in Virginia and Texas accelerates high-R-value panel procurement for server environment stability. The International Code Council enforces escalating thermal resistance mandates for commercial envelopes. Cold storage warehouse expansion across the Midwest and Southeast concentrates demand for verified thermal bridging performance.
Germany
EU Green Deal implementation through national bodies drives specification of polyurethane-cored panels exceeding legacy insulation values. REACH chemical registration requirements govern reformulation of blowing agent chemistries ahead of F-Gas Regulation phase-downs. Commercial envelope projects in Berlin and Munich increasingly require Environmental Product Declaration certification.
France
Agricultural building modernization and commercial cold chain infrastructure create dual demand channels for panel systems. National implementation of EU Green Deal carbon-performance standards shapes procurement criteria beyond operational thermal metrics. Lyon and Marseille construction clusters specify facade panels with integrated rainscreen configurations for architecturally exposed envelopes.
India
Emerging enforcement of BIS thermal performance standards creates positioning opportunities for certified suppliers in commercial cold chain infrastructure. National building envelope codes are tightening across metropolitan construction markets. Warehouse development in Maharashtra and Gujarat accelerates procurement of medium-thickness wall and roof assemblies.
China
Dual carbon goals and GB standards for building energy efficiency reshape specification requirements for industrial envelopes. National regulators emphasize embodied carbon accounting in construction materials procurement. Yangtze River Delta manufacturing facilities specify floor panels with electrostatic discharge properties for semiconductor fabrication environments.
Metal Structural Insulation Panels Market Vendor Landscape
Capability concentration sits with specialized fabricators commanding certification-grade production; scale advantage sits with integrated building materials conglomerates leveraging supply chain breadth. The market structures around three tiers: global specification leaders with multi-jurisdiction certification portfolios, regional specialists anchored in cold-storage or agricultural verticals, and steel mill-integrated players extending metal supply dominance into envelope systems. Dominant competitive moves include backward integration into core chemistry production and direct supply agreement negotiation with data center developers.
Among Ireland-based building materials conglomerates, Kingspan Group exemplifies global specification leadership through manufacturing footprint breadth. Metl-Span and Nucor Building Systems occupy distinct positions within the North American fabricator tier, with the former representing specialized cold-storage architecture capability and the latter anchoring steel supply chain extension strategies. These three entities collectively illustrate the competitive archetype spectrum spanning global certification management, vertical application depth, and upstream materials integration.
| Leading Market Players |
|---|
| Kingspan Group |
| Metl-Span |
| Nucor Building Systems |
| Owens Corning |
| ACME Panel |
| American Insulated Panel |
| KPS Global |
| PFB Corp. |
| ArcelorMittal |
| Others |
Supply Flow & Price Mechanics
The Yangtze River Delta manufacturing cluster anchors polyurethane core production capacity for Asian panel laminators, translating regional feedstock proximity into pricing leverage over distant European and North American fabricators facing elevated logistics and duty burdens.
Pricing Analysis
Long-term offtake agreements dominate procurement between cold storage operators and certified panel fabricators, compressing spot market liquidity. Three-tier pricing structure across specification-grade, commercial-grade, and agricultural-grade levels separates premium polyurethane-cored assemblies from polystyrene alternatives. Cost compression in the agricultural tier intensifies because buyers prioritize capital expenditure containment over lifecycle thermal performance. Data center developers exhibit lowest price sensitivity, accepting premium positioning for verified thermal bridging documentation and installation supervision bundling.
Supply Chain Analysis
Steel and aluminum feedstock draws from integrated mill complexes in China, the United States, and Germany, with specialty alloy facings sourcing from Japanese and South Korean rolling facilities. Rigid foam core chemicals hinge on petrochemical complexes in the US Gulf Coast, Rotterdam, and Singapore. Single-source vulnerability concentrates in discontinuous press equipment manufacturing, where German and Italian machinery builders command extended lead times. Distribution runs through certified fabricator networks that maintain specification-grade inventory positions near major construction clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents face substitution pressure from cross-laminated timber and mass timber envelope systems gaining code acceptance in commercial construction, requiring active defense of the thermal performance-per-dollar value proposition.
For Market Incumbents: Harden specification-grade positioning through captive polyurethane core chemistry production and accelerated BIS certification timelines for Indian market access. Defend against timber envelope substitution by quantifying lifecycle thermal performance gaps in net-zero building modeling. Prioritize direct supply agreement negotiation with hyperscale data center developers to lock out second-tier fabricators.
For New Entrants and Emerging Players: Build out regional refurbishment and thermal auditing service capabilities, capturing aftermarket revenue fragmentation currently split between uncertified contractors. Agricultural cold storage in India's Maharashtra and Gujarat corridors offers lowest certification barrier to entry. Lead with medium-thickness wall panel offerings that bypass ultra-high specification complexity while meeting emerging BIS thermal standards.
For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-compression play because building energy code escalation in the EU Green Deal framework and US ICC mandates structurally expand addressable demand regardless of construction cycle volatility. Acquisition targets should command multi-jurisdiction certification portfolios spanning ICC, BIS, and EU national implementation bodies. Watch for F-Gas Regulation phase-down acceleration as signal for core chemistry reformulation investment requirements.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Core Chemistry | Captive polyurethane production insulates margin from petrochemical volatility and REACH reformulation mandates. |
| Direct Supply Agreement Negotiation | Data center developers in Virginia and Texas disintermediate general contractors, transferring thermal liability to fabricators. |
| Multi-Jurisdiction Certification Investment | Simultaneous ICC, BIS, and EU national body approval compresses market access latency versus staggered filing. |
| Aftermarket Service Capability Buildout | Thermal performance auditing addresses building owner code compliance verification and insurance risk documentation needs. |
| Facade Panel Aesthetic Integration | Rainscreen-configured commercial envelopes in France and Germany command premium positioning over utilitarian industrial applications. |
Methodological Framework
A spread of perspectives from cold storage logistics operators, panel fabricator production managers, building envelope specification architects, and core chemistry R&D directors converged on the working assumptions driving volume and value outputs. Primary fieldwork combined structured interviews with facility operators in Germany, the United States, and India alongside secondary validation through ICC code documentation, EU Green Deal national implementation filings, BIS thermal standard drafts, and customs trade data for steel and aluminum facing materials. Bottom-up segment sizing triangulated against top-down construction spend allocation across cold storage, data center, and agricultural building categories.
Demand-supply balance modeling anchored projections across the analysis window, with segmentation dimensions spanning core material chemistry, insulation thickness tier, application geometry, and end-use vertical. CAGRs derived from elasticity-adjusted construction cycle assumptions and regulatory enforcement timeline probabilities. Industry-specific inputs included REACH F-Gas Regulation phase-down schedules, hyperscale data center capex disclosure patterns, and BIS code adoption velocity across Indian metropolitan markets.
The forecast holds incumbent behavior within observed patterns; aggressive moves by steel mill-integrated conglomerates into specification-grade panel fabrication would shift outcomes through capacity flooding and vertical price compression. Cross-checking against regional construction permit databases and cold storage warehouse development pipelines is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Structural Engineering
UK Facade Market
Structural Engineering
Steel Structure Anchor Bolt Market
Structural Engineering
Philippines Roofing Market
Structural Engineering
Asia-Pacific Structural Health Monitoring Market
Structural Engineering
Fluid Viscous Dampers Market
Structural Engineering
Southeast Asia Anchors and Grouts Market
Structural Engineering
Self-Healing Concrete Market
Structural Engineering
North America Anchors and Grouts Market
Structural Engineering
High Damping Rubber Bearing (HDRB) Market
Structural Engineering
Global Concrete Restoration Market
Structural Engineering
Structural Steel Market
Structural Engineering
North America Facade Market
Structural Engineering
Structural Lightweight Concrete Market
Structural Engineering
Civil Engineering Market
Structural Engineering
Europe Facade Market
Structural Engineering
Europe Insulated Concrete Form (ICF) Market