
 Americas Structural Insulated Panel Market | 2026-2036
Americas Structural Insulated Panel Market Size, Share, and Industry Trends Forecast 2026-2036
Americas Structural Insulated Panel Market Intelligence
A shortage of trained labor for panelized construction is reorganizing the competitive landscape. Kingspan Group leverages its extensive distribution network to serve large-scale commercial projects across the Americas. In contrast, Premier SIPs specializes in high-performance custom panels for complex architectural designs. Nucor Corp competes by integrating steel-faced panels into its broader building systems portfolio.
A structural insulated panel is a high-performance building component used for walls, roofs, and floors. It consists of a rigid foam plastic insulation core, such as expanded polystyrene, sandwiched between two structural facings, typically oriented strand board. Expanded Polystyrene (EPS) core panels lead the residential application segment due to their favorable cost-performance ratio. Polyurethane-based panels, offering higher thermal resistance, are gaining share in commercial and industrial buildings.
Building codes across the Americas, including those based on International Code Council (ICC) standards in the US, increasingly mandate higher R-values. The EPA's regulations on blowing agents also influence foam core material selection and manufacturing processes. Navigating regional code variations and securing a skilled installation workforce are critical decisions for manufacturers seeking to expand their footprint.
Market Dynamics
The imperative for faster construction timelines in the residential sector, colliding with a persistent shortage of skilled labor, is the central force shaping the Americas structural insulated panel market. This tension is amplified by increasingly stringent energy efficiency mandates from updated building codes.
Growth Catalysts
- Energy Code Evolution:Stricter building codes based on International Code Council standards in the United States and similar frameworks in Canada mandate higher R-values, directly favoring the superior thermal performance of structural insulated panels.
- Residential Construction Speed:The need for accelerated build times in high-growth residential markets across the United States drives adoption, as panelized systems significantly reduce on-site framing labor and construction schedules.
- Material Performance Gains:The adoption of polyurethane-based panels in commercial buildings is increasing due to their higher thermal resistance per inch, expanding the market beyond its traditional expanded polystyrene-based residential core.
Market Restraints
- Input Cost Volatility:Fluctuations in the price of raw materials, particularly oriented strand board (OSB) and petroleum-derived foam insulation cores, create uncertainty in project bidding and can erode manufacturer margins.
- Incumbent Method Dominance:Traditional stick-framing construction remains the default method in many regions due to a deeply entrenched supply chain, established building practices, and a larger available, albeit less specialized, labor force.
- Design Rigidity:Compared to site-built framing, structural insulated panels offer less flexibility for on-the-fly design changes and can be challenging to adapt to highly complex or curvilinear architectural plans.
Strategic Opportunities
- Latin American Expansion:Significant opportunity exists in the urban housing sectors of Brazil and Mexico, where the rapid assembly benefits of SIPs can address pressing housing deficits and support large-scale development projects.
- Prefabricated and Modular Integration:The growing modular construction industry presents a natural growth vector, with panels serving as core components for factory-built homes, accessory dwelling units (ADUs), and emergency housing solutions.
- Digital Fabrication Integration:Linking panel manufacturing directly to architectural Building Information Modeling (BIM) files allows for precision pre-cutting, reducing job site waste and streamlining the installation process for complex designs.
Industry Challenges
- Skilled Labor Scarcity:A critical shortage of installation crews with specific training in panelized construction techniques bottlenecks project completion and can limit geographic expansion for manufacturers.
- Logistical Complexity:Transporting large, bulky panels to job sites, especially in dense urban centers or remote locations, requires specialized logistics and can represent a significant portion of project costs.
- Code Compliance Variation:Navigating the fragmented landscape of local building code amendments and inconsistent enforcement across different jurisdictions in the US and Canada adds complexity and cost to projects.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Americas Structural Insulated Panel Market |
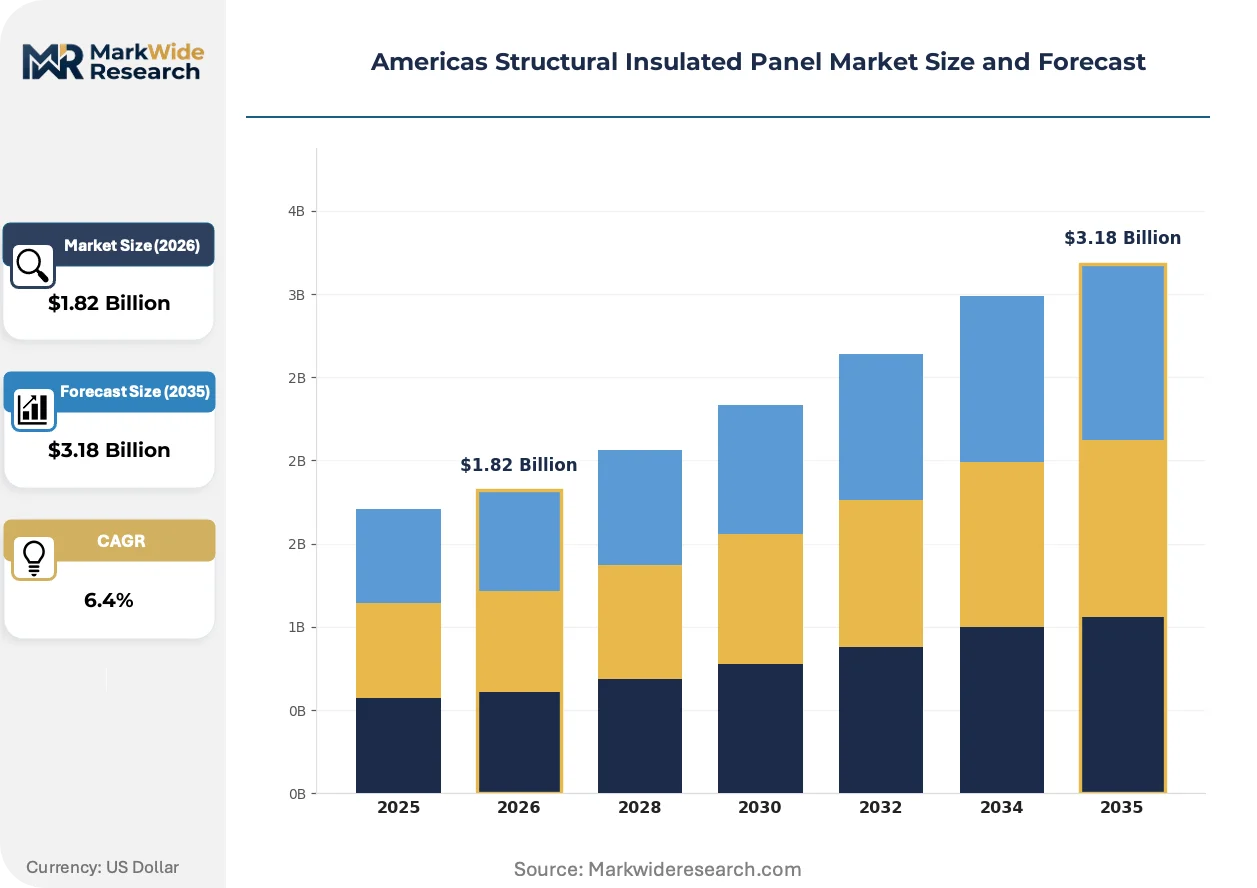
| Market Size in 2026 | $1.82 Billion |
| Market Size in 2035 | $3.18 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: EPS, XPS, Polyurethane, Others Application: Residential, Commercial, Industrial, Agricultural End User: Builders, Contractors, Architects, Homeowners Installation Type: Panelized, Modular, Custom-built, Prefabricated |
| Companies Covered | Owens Corning, Kingspan Group, Nucor Corp, PFB Corporation, Premier SIPs, ACME Panel Company, Enercept Inc., Foard Panel Inc., Extreme Panel Technologies, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Americas Structural Insulated Panel Market Strategic Shifts & Innovations
Material science advancements and digital workflow integration are fundamentally altering the product landscape. These innovations focus on enhancing sustainability, streamlining compliance with environmental regulations, and aligning panel fabrication with modern construction management practices across the Americas.
Bio-based foam cores, utilizing materials like mushroom mycelium or agricultural byproducts, provide a sustainable alternative to conventional petroleum-based insulations. Eco-conscious architects and developers in the custom residential segment are leading their adoption. This innovation is decomposing the market's historical dependence on expanded polystyrene and polyurethane, creating a premium category defined by environmental performance.
New regulations from the EPA targeting the phase-down of hydrofluorocarbons (HFCs) as blowing agents are compelling changes in foam core manufacturing. This requires manufacturers to invest in research to qualify new formulations using low global warming potential agents. Polyurethane panel producers are most affected, accelerating their shift to hydrofluoroolefin (HFO) technologies to ensure regulatory compliance.
A clear shift toward integrated project delivery models is changing how structural insulated panels are specified. This collaborative workflow, often managed through Building Information Modeling (BIM) software, replaces siloed procurement with a unified design-to-fabrication process. The trend is most visible in large-scale commercial and institutional projects throughout the United States and Canada.
Americas Structural Insulated Panel Market Segmentation
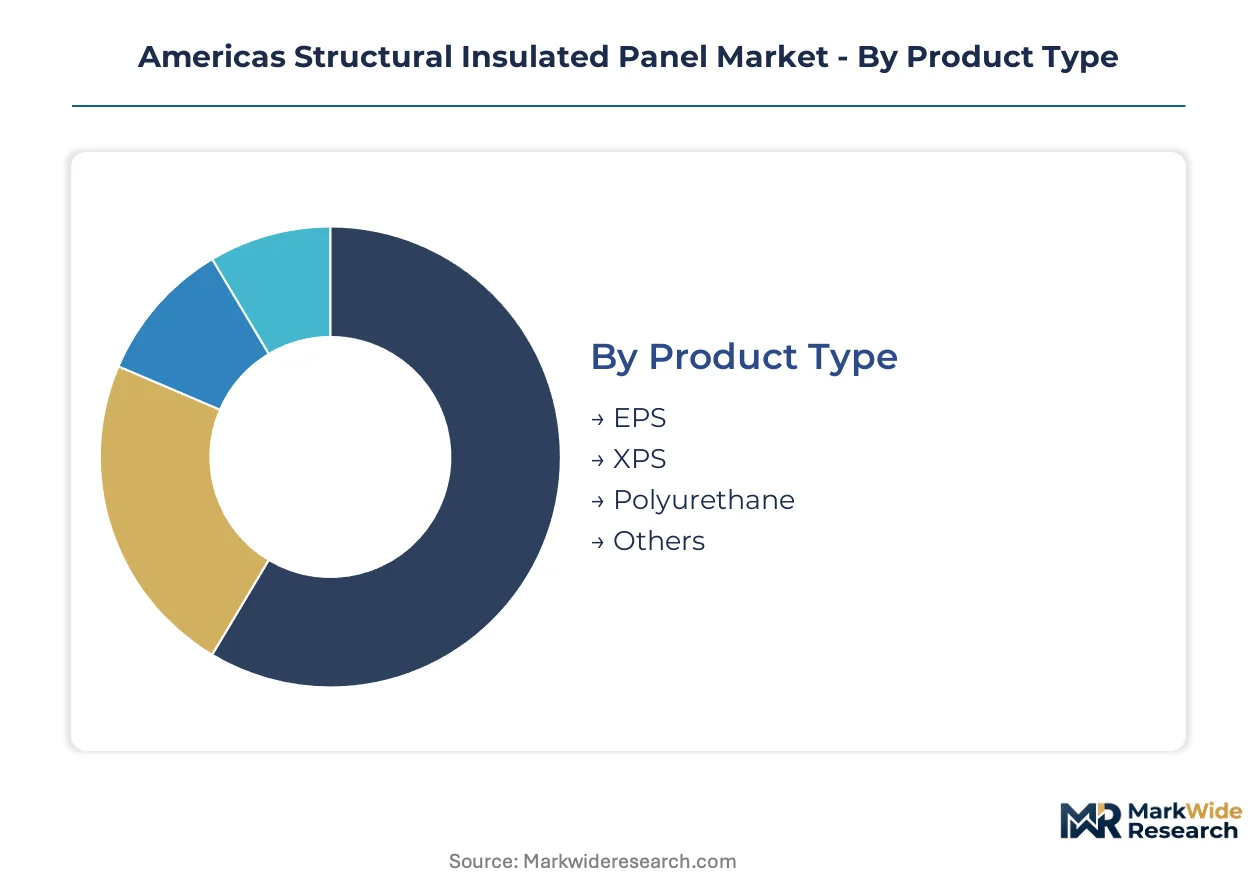
The Americas structural insulated panel market exhibits distinct segmentation across product types, applications, end-users, and installation methods. Understanding these segments is critical for manufacturers to tailor offerings, optimize distribution, and navigate competitive pressures within specific niches.
Product Type:
Substitution pressure is reorganizing the product type landscape, as newer materials challenge established foam cores.
- EPS:Expanded Polystyrene (EPS) panels consist of a rigid foam plastic insulation core. This product type leads the residential application segment due to its favorable cost-performance ratio in the Americas.
- Polyurethane:Polyurethane-based panels offer higher thermal resistance per inch compared to other foam cores. This material captures increasing share in commercial and industrial buildings across the Americas.
- XPS:Extruded polystyrene (XPS) panels provide high compressive strength and moisture resistance, making them suitable for specific foundation and below-grade applications.
- Others:This category includes various emerging or niche core materials, such as bio-based foams, which are gaining interest in eco-conscious custom residential projects.
EPS retains volume leadership; Polyurethane holds the steepest expansion curve.
Application:
Demand patterns for structural insulated panels diverge significantly across various applications.
- Residential:This segment focuses on single-family and multi-family housing projects. The need for faster construction timelines and improved energy efficiency drives adoption in the United States.
- Commercial:This application encompasses offices, retail spaces, and institutional buildings. Higher thermal resistance and quicker enclosure times are critical for large-scale projects in major Canadian cities.
- Industrial:This segment utilizes panels for factories, warehouses, and cold storage facilities, prioritizing durability and thermal control in challenging environments.
- Agricultural:This application employs structural insulated panels for barns, grow houses, and storage structures, benefiting from insulation properties and ease of sanitation.
Residential applications demonstrate market maturity, while Commercial continues to expand its market footprint.
End User:
The end-user landscape reflects diverse decision-making priorities, influencing panel specification and procurement.
- Builders:Primarily focused on cost-efficiency and accelerated project completion. These users drive large-scale residential and commercial developments across the Americas.
- Architects:Emphasize design flexibility, high-performance characteristics, and sustainable material choices. They influence custom and complex architectural projects.
- Contractors:These users manage on-site installation and logistics. They often prioritize ease of assembly and labor efficiency for project execution.
- Homeowners:Homeowners seek energy savings, improved indoor comfort, and long-term durability for new construction or renovation projects.
Builders drive significant volume, while Architects increasingly influence high-performance specifications.
Installation Type:
Different installation types reflect varying approaches to construction, each leveraging structural insulated panels uniquely.
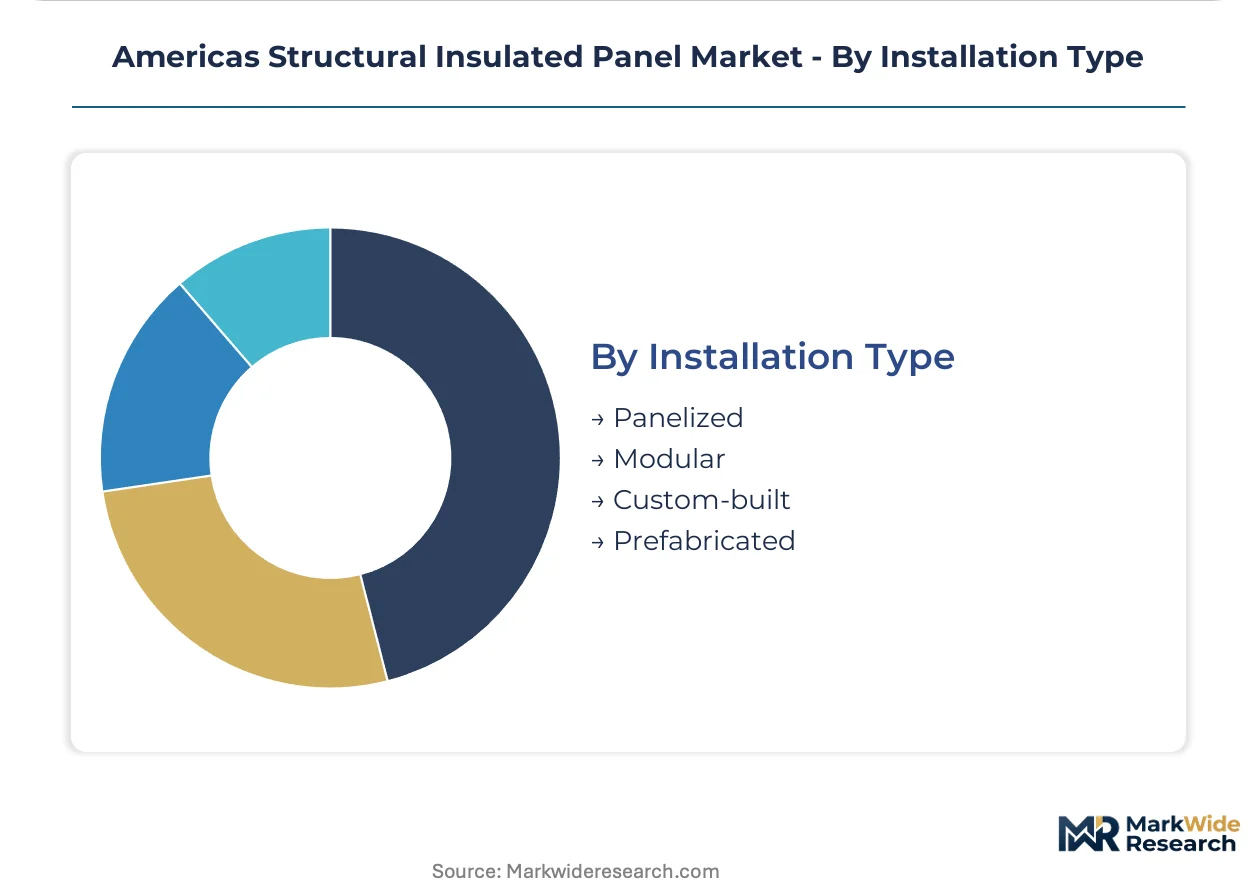
- Panelized:This method involves manufacturing panels off-site and assembling them on-site. It significantly reduces construction time and labor needs for residential builds.
- Modular:This type integrates structural insulated panels into factory-built modules. It supports the rapid expansion of accessory dwelling units and emergency housing solutions.
- Custom-built:This approach adapts panels to unique architectural designs and site-specific requirements, often for high-end residential or specialized commercial projects.
- Prefabricated:This encompasses a broader range of factory-made components beyond full modules, including wall, roof, and floor sections ready for assembly.
Panelized installation remains the dominant method, while Modular integration gains efficiency advantages.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Americas market for structural insulated panels exhibits distinct pricing power asymmetry, with robust demand in the United States allowing for higher pricing compared to emerging markets like Brazil. This regional divergence influences investment decisions and market penetration strategies. Manufacturers adapt product offerings to suit varied economic conditions across the continent.
United States
United States demand for structural insulated panels stems from accelerated residential build times and stringent energy efficiency mandates. Stricter building codes based on International Code Council (ICC) standards mandate higher R-values for new construction. High-growth residential markets across the Sun Belt states, particularly in Texas, drive significant SIP adoption.
Canada
Canada's market benefits from a strong imperative for superior thermal performance and quicker building enclosure times. Building codes, mirroring US energy efficiency goals, increasingly favor advanced insulation solutions for new developments. Major metropolitan areas like Toronto and Vancouver prioritize SIPs for commercial projects, seeking operational cost reductions.
Mexico
Mexico presents a significant opportunity in its urban housing sectors, driven by pressing housing deficits and the need for rapid assembly solutions. Government initiatives aimed at expanding affordable housing often encourage the adoption of prefabricated building systems. Large-scale development projects in Mexico City leverage SIPs for their speed and efficiency.
Brazil
Brazil’s urban housing sector requires efficient construction methods to address its substantial housing deficits. National housing programs often create frameworks that support the industrialization of building processes. Construction activities in major cities like São Paulo are increasingly exploring panelized systems for their speed and reduced labor requirements.
Argentina
Argentina's market for structural insulated panels is emerging, supported by a growing focus on energy efficiency in new infrastructure. The national government is slowly implementing energy performance standards for residential and commercial constructions. Buenos Aires is witnessing initial adoption of SIPs in specialized projects and custom residential builds.
Americas Structural Insulated Panel Market Key Industry Players
Technology leadership and cost leadership are held by different player archetypes within the Americas structural insulated panel market. The market exhibits a tiered structure, with established manufacturers alongside specialized niche providers. Strategic archetypes include large-scale integrators, custom panel specialists, and material-focused innovators. Dominant competitive moves involve geographic expansion into high-growth regions, portfolio diversification to capture new application segments, and strategic partnerships for specialized installations.
Specialists focusing on high-performance custom panels, such as Premier SIPs, cater to complex architectural designs and niche markets, emphasizing bespoke solutions. Meanwhile, Kingspan Group, a large-scale integrated manufacturer, leverages its extensive distribution network to serve commercial projects across the Americas, prioritizing scale and market reach. Nucor Corp, an industrial conglomerate, occupies a position integrating steel-faced panels into its broader building systems portfolio, capitalizing on material synergies. These companies exemplify the varied approaches to market penetration and product differentiation within the industry, from specialized engineering to broad-market supply.
| Leading Market Players |
|---|
| Owens Corning |
| Kingspan Group |
| Nucor Corp |
| PFB Corporation |
| Premier SIPs |
| ACME Panel Company |
| Enercept Inc. |
| Foard Panel Inc. |
| Extreme Panel Technologies |
| Others |
Cost & Logistics Intelligence
Bio-based foam cores, replacing conventional petroleum-derived insulations, introduce new sourcing geographies and establish a premium pricing tier for sustainable construction. This material shift impacts both input costs and market positioning.
Pricing Analysis
Configured-to-order pricing for custom panels commands a premium over standard, volume-driven offerings in the Americas structural insulated panel market. Project-based contracts dominate, with price differentiation stemming from customization level for complex designs and superior thermal performance of polyurethane panels. Pricing softness impacts the residential EPS segment due to raw material volatility in oriented strand board and foam cores. Builders prioritize cost-efficiency, making them highly price-sensitive, while architects focus on high-performance specifications.
Supply Chain Analysis
Managing inventory and lead times for large, bulky structural insulated panels presents a significant logistical challenge across the Americas, with the supply chain drawing heavily from North American OSB production and global petrochemical sources for foam cores. Geographic supply concentration for finished panels exists near high-growth residential markets in the United States and major metropolitan areas in Canada. Commodity price volatility for OSB and petroleum-derived foam represents a structural supply chain risk, impacting manufacturer margins. Distribution runs through direct manufacturer-to-project site deliveries, often requiring specialized transport.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Americas structural insulated panel market is witnessing a shift in buyer power, driven by the consolidation of large residential builders. These entities increasingly dictate terms, emphasizing faster build times and cost-efficiency.
For Market Incumbents: Consolidate market share by acquiring specialized installation firms to mitigate skilled labor scarcity, a critical bottleneck in the Americas. Invest in advanced manufacturing for precision pre-cutting, directly linking to BIM workflows for large commercial projects. This strategy defends against the entrenched dominance of traditional stick-framing methods. Diversify product offerings to include bio-based foam panels, addressing sustainability demands from eco-conscious architects.
For New Entrants and Emerging Players: Differentiate on advanced material science and digital integration to capture niche segments in the Americas. Target the underpenetrated urban housing sectors of Brazil and Mexico, leveraging rapid assembly for large-scale development projects. Partner with modular construction firms to supply factory-built homes and accessory dwelling units. Offer BIM-integrated design-to-fabrication services, streamlining complex architectural projects and reducing job site waste.
For Investors and Strategic Acquirers: The market sits at a sustained growth phase that favors vertically integrated panel manufacturers with strong regional installation networks. Long-term viability is supported by persistent energy efficiency mandates and the imperative for faster construction. Focus acquisition strategies on regional specialists possessing proprietary bio-based foam technologies or established skilled installation crews. The signal to watch is the accelerated adoption of hydrofluoroolefin (HFO) blowing agents in polyurethane panels, indicating regulatory compliance and market readiness.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion | Increases production volume to meet rising demand in US Sun Belt residential markets. |
| Digital Fabrication Integration | Reduces job site waste and streamlines installation for complex architectural designs through BIM. |
| Latin American Market Entry | Addresses pressing housing deficits in Brazil and Mexico with rapid assembly solutions. |
| Bio-based Material R&D | Develops sustainable foam cores, aligning with eco-conscious developer preferences and EPA regulations. |
| Skilled Installer Training Programs | Mitigates the critical shortage of panelized construction labor, accelerating project completion. |
Research Approach
A standing panel of builders, architects, contractors, and material suppliers provided ongoing calibration for market sizing and forecasting, integrating primary insights with secondary data. This approach included in-depth interviews with industry stakeholders and validation against published reports. Secondary sources comprised International Code Council standards, EPA regulatory documents, national construction statistics, and company financial filings. Bottom-up data aggregation and top-down market validation ensured robust market estimates.
Market outputs were rigorously validated against external benchmarks to ensure consistency across the analysis window. The quantitative framework modeled market dynamics by product type, application, end-user, and installation method, alongside thermal resistance R-value. Compound Annual Growth Rates were derived from historical trends and projected market drivers. Key forecast inputs included residential housing starts, commercial construction expenditure, and evolving energy efficiency mandates.
Material uncertainties — such as raw material price volatility, shifts in building code enforcement, and skilled labor availability — sit outside the modeled envelope of this study. Forecasts reflect assumptions about market stability and regulatory continuity over the projection horizon. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Structural Engineering
Steel Structure Anchor Bolt Market
Structural Engineering
Global Concrete Restoration Market
Structural Engineering
Bridge Expansion Joint Market
Structural Engineering
Global Structural Health Monitoring Market
Structural Engineering
Geotechnical Engineering Market
Structural Engineering
Civil Engineering Market
Structural Engineering
FRP Bridge Market
Structural Engineering
Self-Healing Concrete Market
Structural Engineering
Philippines Roofing Market
Structural Engineering
Southeast Asia Anchors and Grouts Market
Structural Engineering
Prestressed Concrete Market
Structural Engineering
High Damping Rubber Bearing (HDRB) Market
Structural Engineering
Structural Lightweight Concrete Market
Structural Engineering
Fluid Viscous Dampers Market
Structural Engineering
India Structural Steel Fabrication Market
Structural Engineering
Europe Bridge Bearings Market