
 Sedation in ICU Setting Market | 2026-2036
Sedation in ICU Setting Market Size, Share, and Industry Trends Forecast 2026-2036
Sedation in ICU Setting Market Intelligence
Aftermarket service revenue for infusion pump maintenance and sedation protocol consulting is fragmenting across hospital networks and third-party vendors. Fresenius Kabi anchors its position through captive manufacturing of propofol emulsions and parenteral delivery systems. Pfizer competes via vertical control over midazolam supply chains and hospital formulary contracts. Teva differentiates through generic dexmedetomidine portfolios that undercut originator pricing in cost-sensitive procurement environments.
Sedation in ICU setting encompasses the pharmacological induction of controlled consciousness reduction in critically ill patients, typically achieved through intravenous agents titrated to validated sedation scales such as the Richmond Agitation-Sedation Scale or RASS. The practice enables mechanical ventilation tolerance, reduces oxygen consumption, and prevents ventilator-induced lung injury in hemodynamically unstable populations. Propofol and dexmedetomidine command the dominant share of agent selection where rapid awakening and delirium minimization represent clinical priorities, while benzodiazepines retain residual use in status epilepticus and alcohol withdrawal protocols. Intravenous delivery mode generates the majority of value capture given the need for precise titration in hemodynamically labile patients, though inhalational adjuncts occupy niche roles in specific European anesthesia services.
FDA guidance on boxed warnings for propofol infusion syndrome shapes dosing thresholds and monitoring obligations in US intensive care units, while EMA pharmacovigilance requirements for dexmedetomidine cardiovascular effects influence labeling across European markets. The Joint Commission sedation standards and ISO 80601-2-24 infusion device specifications further constrain product design and hospital accreditation pathways. Stakeholders must monitor evolving ICU Liberation Bundle guidelines and their downstream impact on agent selection protocols and length-of-sedation metrics.
Market Dynamics
Mechanical ventilation protocols in tertiary hospitals are compressing sedation targets from deep to lighter states, forcing pharmaceutical and device suppliers to recalibrate dosing formulations and monitoring interfaces around rapid-awakening endpoints.
Growth Catalysts
- FDA infusion guidance:Updated boxed warning protocols for propofol are mandating enhanced monitoring infrastructure, pulling new pump installations and software upgrades into hospital capital cycles.
- ICU Liberation Bundle adoption:The ABCDEF implementation framework is embedding daily sedation interruption into standard workflow, expanding consumption of short-acting agents titratable to RASS targets.
- Sepsis protocol expansion:Rising severe sepsis caseloads in high-bed-density markets are sustaining continuous infusion demand for hemodynamic stability during mechanical ventilation.
Market Restraints
- Propofol supply concentration:Captive manufacturing of lipid emulsion formulations ties availability to single-source API and excipient suppliers, exposing formularies to batch shortage risk.
- Dexmedetomidine cardiovascular monitoring burden:EMA pharmacovigilance requirements for bradycardia and hypotension surveillance add nursing labor cost that offsets agent premium pricing.
- Benzodiazepine residual protocols:Status epilepticus and alcohol withdrawal guidelines preserve midazolam and lorazepam niches that fragment protocol standardization and dilute next-agent adoption.
Strategic Opportunities
- Generic dexmedetomidine penetration:Cost-sensitive procurement environments in Medicaid-dominant hospital systems are opening volume contracts for multi-source IV sedative supply.
- Inhalational sedation adjuncts:European anesthesia services are piloting volatile anesthetic delivery for ICU sedation, creating device upgrade pathways outside saturated IV pump markets.
- Aftermarket service unbundling:Third-party vendors are capturing infusion pump maintenance and sedation protocol consulting revenue streams that OEMs previously monopolized.
Industry Challenges
- ISO 80601-2-24 compliance timeline:Infusion device recertification for electromagnetic compatibility and dose error reduction is extending product development cycles and freezing hospital procurement decisions.
- Delirium assessment skill gaps:CAM-ICU and ICDSC screening competency requirements are outpacing critical care nursing training capacity, creating protocol adherence variance across shifts.
- Interoperability fragmentation:Proprietary data protocols between pump networks and EMR systems are forcing hospitals into single-vendor lock-in or expensive middleware development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sedation in ICU Setting Market |
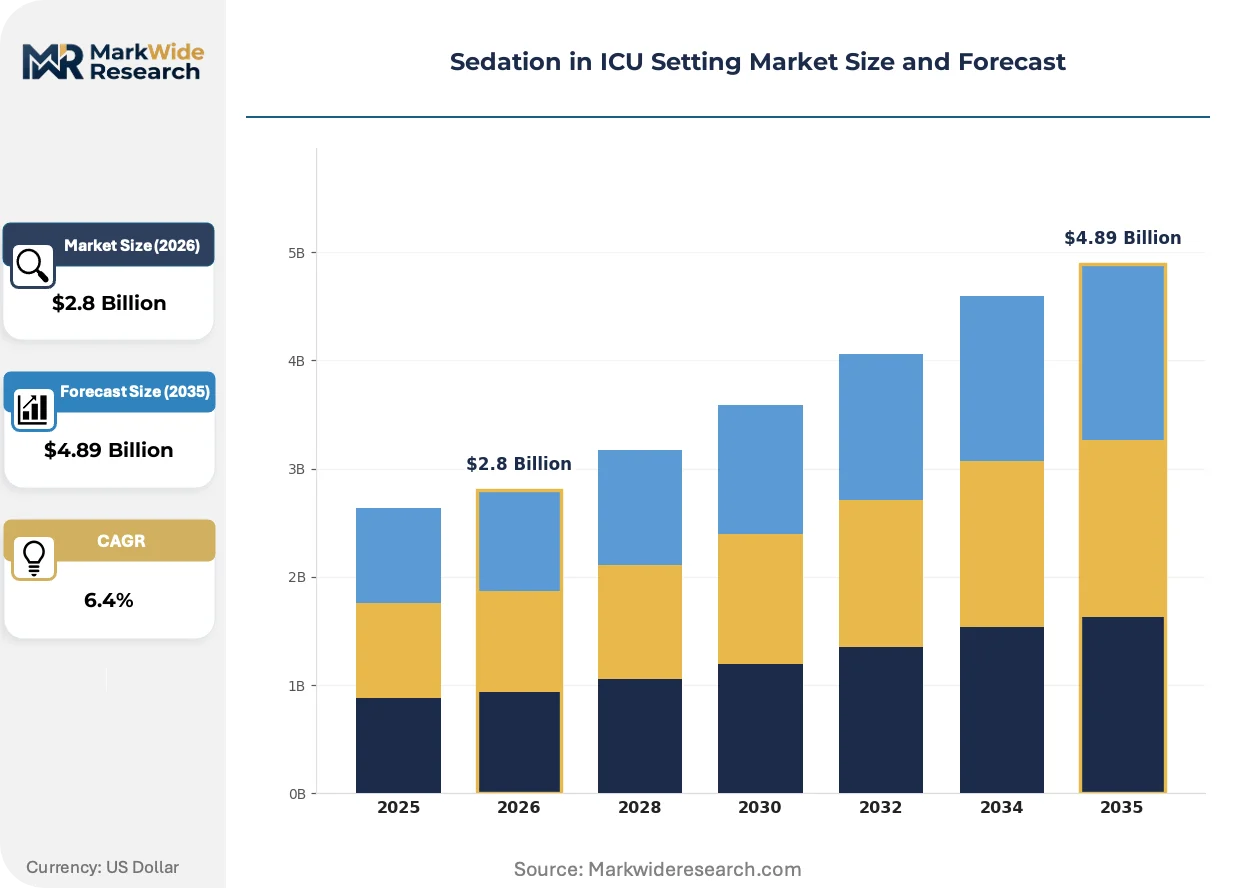
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.89 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Benzodiazepines, Propofol, Dexmedetomidine, Barbiturates, Ketamine Therapy Area: Mechanical Ventilation, Postoperative Care, Neurological Conditions, Trauma Management, Severe Infections End User: Intensive Care Units, Emergency Departments, Surgical Centers, Respiratory Care Units, Anesthesia Services Delivery Mode: Intravenous, Oral, Inhalational, Transdermal, Subcutaneous |
| Companies Covered | AstraZeneca, GlaxoSmithKline, Mylan, Fresenius Kabi, Teva, B. Braun Medical, Pfizer, Sanofi, Abbott Laboratories, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sedation in ICU Setting Market Strategic Shifts & Innovations
Closed-loop sedation systems and algorithm-driven titration are compressing the role of manual nursing adjustment, while regulatory pressure on infusion safety and hospital consolidation are reshaping vendor selection criteria.
Target-controlled infusion algorithms paired with processed EEG monitoring are collapsing the traditional gap between anesthesiology precision and ICU nursing workflow. Tertiary academic medical centers in the United States and Germany are piloting these systems for post-operative ventilation weaning. The technology is collapsing variance in time-to-extubation and reducing propofol total dose exposure.
The Joint Commission's updated sedation standards are mandating capnography for moderate-to-deep sedation cases beyond the operating room, forcing device manufacturers to integrate respiratory monitoring modules into standard infusion platforms. Hospital accreditation surveys are now flagging non-compliant pump configurations. Critical access hospitals and ambulatory surgical centers face the steepest retrofit cost burden.
Formulary committees are consolidating agent selection around protocols that prioritize next-day awakening, displacing benzodiazepine-first order sets in favor of propofol and dexmedetomidine default pathways. This preference shift is visible most acutely in United States health systems participating in ICU Liberation collaborative networks. Generic substitution is accelerating where multi-source supply contracts are available.
Sedation in ICU Setting Market Segmentation
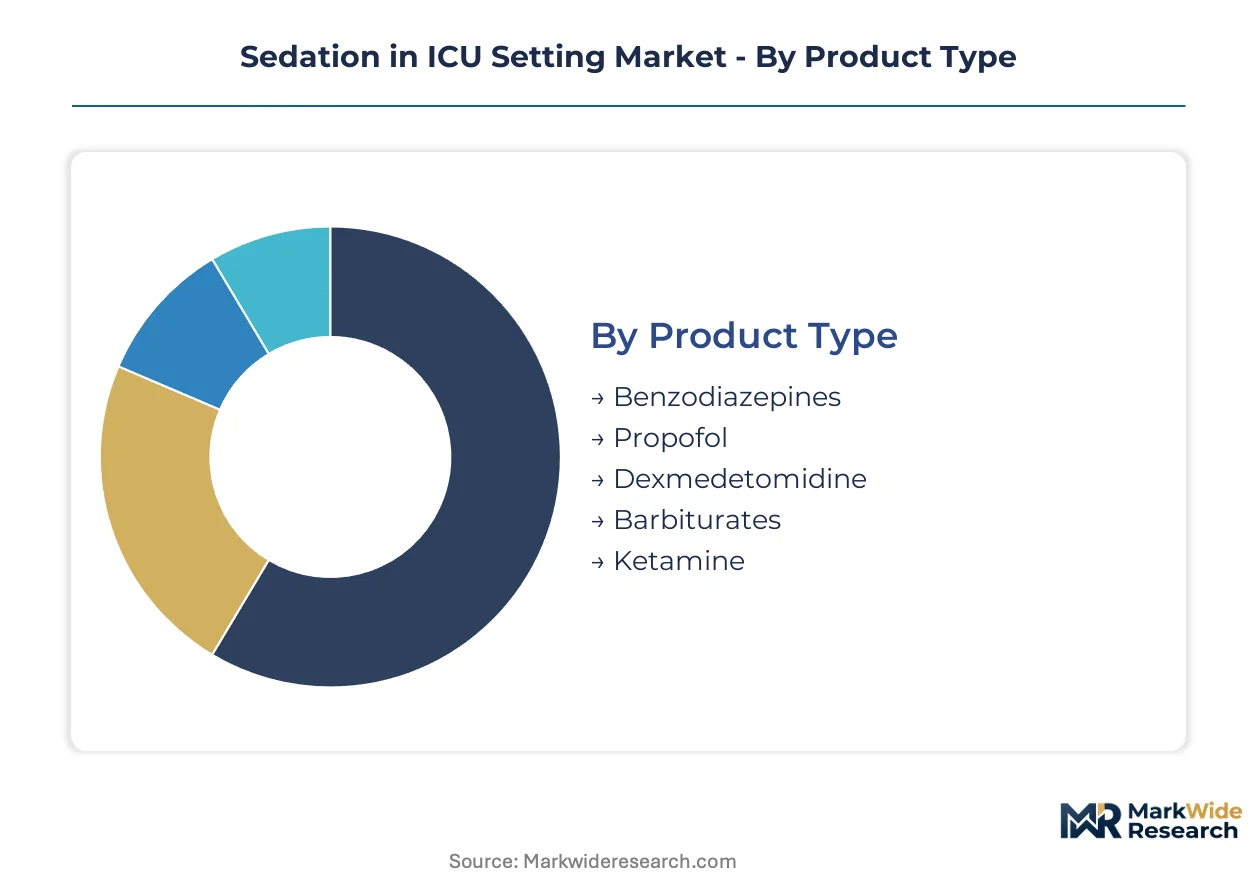
Segmentation in the ICU sedation market reveals distinct procurement rhythms and clinical utility patterns across pharmaceutical classes, therapeutic applications, and delivery modalities. Understanding these divides exposes where formulary committees concentrate purchasing power versus where protocol experimentation creates entry opportunities for new agents and device formats.
Product Type:
Cycle times vary sharply across this category, with short-acting agents turning over in days to weeks while long-duration formulations sit in inventory for months. Propofol and dexmedetomidine command the most frequent replenishment schedules due to continuous infusion protocols.
- Propofol:Lipid emulsion formulation enables rapid redistribution and awakening, making it the default for mechanical ventilation weaning and daily sedation interruption protocols. United States tertiary hospitals with high ventilator census drive concentrated consumption, though FDA boxed warning requirements for propofol infusion syndrome monitoring add nursing labor overhead that constrains dosing thresholds.
- Dexmedetomidine:Selective alpha-2 agonist preserves respiratory drive while providing anxiolysis, positioning it for non-intubated ICU populations and delirium-sparing protocols. German academic medical centers and United States health systems participating in ICU Liberation networks represent the densest demand clusters, with EMA cardiovascular surveillance requirements creating documentation burdens that slow adoption in cost-constrained European markets.
- Benzodiazepines:Midazolam and lorazepam retain residual formulary presence for status epilepticus and alcohol withdrawal management where GABA-A modulation remains clinically necessary.
- Barbiturates:Pentobarbital and thiopental occupy refractory intracranial hypertension and burst-suppression EEG targeting niches with infrequent but high-dose utilization.
- Ketamine:NMDA antagonist properties support analgesic-sparing sedation in hemodynamically unstable trauma and burn populations where sympathetic preservation matters.
Propofol anchors the volume base while dexmedetomidine gains share at the steepest rate.
Therapy Area:
Cost tier stratification dominates this dimension, with mechanical ventilation commanding premium agent pricing and monitoring infrastructure investment while postoperative care operates on compressed margins.
- Mechanical Ventilation:Continuous infusion requirements for ventilator synchrony and lung-protective strategies sustain the highest pharmaceutical consumption intensity per patient-day. United States ICU bed density and sepsis protocol expansion concentrate demand in tertiary and quaternary hospitals.
- Postoperative Care:Shorter sedation horizons and accelerated awakening targets favor rapid-offset agents, with ambulatory surgical centers and short-stay units driving generic substitution pressure.
- Neurological Conditions:ICP management and burst-suppression protocols require specialized EEG-integrated dosing that sustains premium pricing for barbiturate and propofol high-dose regimens.
- Trauma Management:Hemodynamic instability and multi-system injury patterns create demand for ketamine and etomidate-sparing protocols in level I trauma centers.
- Severe Infections:Sepsis-induced delirium and multi-organ dysfunction shape agent selection toward dexmedetomidine-first pathways in United States health systems adopting ICU Liberation bundles.
Mechanical ventilation captures the largest revenue pool while severe infections applications expand most quickly as sepsis protocols proliferate.
End User:
Customer type heterogeneity shapes purchasing authority and formulary control, with intensive care units retaining centralized pharmacy governance while emergency departments and surgical centers fragment decision-making.
- Intensive Care Units:Closed-loop sedation pilots and protocol standardization initiatives concentrate in academic medical center ICUs with dedicated critical care pharmacy services.
- Emergency Departments:Rapid sequence intubation and procedural sedation volumes drive ketamine and etomidate consumption, with formulary independence from ICU committees creating agent selection variance.
- Surgical Centers:Cost-containment imperatives and shorter procedure mixes favor benzodiazepine-opioid combinations over premium continuous infusion platforms.
- Respiratory Care Units:Step-down ventilation weaning creates intermediate sedation needs between ICU intensity and ward-level monitoring capacity.
- Anesthesia Services:Inhalational sedation pilot programs in European centers and processed EEG integration create device upgrade demand outside standard IV pump markets.
Intensive care units dominate procurement volume while emergency departments generate the steepest expansion trajectory for short-acting dissociative agents.
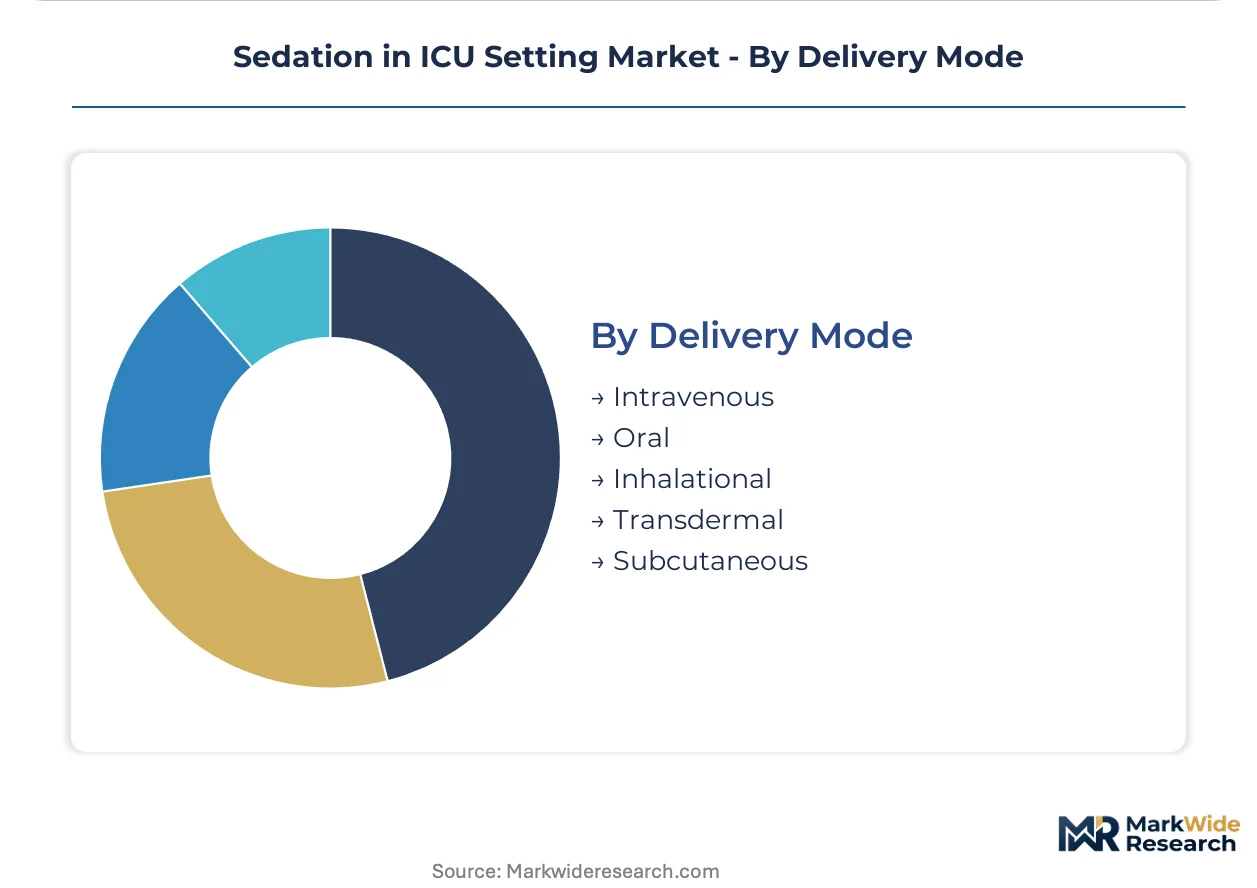
Delivery Mode:
Supply concentration and device ecosystem lock-in define competitive dynamics here, with intravenous platforms consolidating around incumbent pump manufacturers while alternative modes fragment across niche vendors.
- Intravenous:Precision titration requirements for hemodynamically labile patients sustain IV dominance, with ISO 80601-2-24 compliance timelines and EMR interoperability constraints freezing hospital procurement around established pump networks.
- Oral:Enteral conversion protocols for ventilator weaning and delirium management create step-down demand that competes with IV continuation on nursing labor efficiency grounds.
- Inhalational:Volatile anesthetic delivery for ICU sedation pilots in German and United Kingdom anesthesia services creates device upgrade pathways for anesthesia machine manufacturers.
- Transdermal:Fentanyl and clonidine patches occupy chronic pain and alcohol withdrawal adjunct roles with limited ICU penetration.
- Subcutaneous:Palliative sedation and terminal weaning protocols in hospice-integrated ICUs sustain niche demand for alternative delivery routes.
Intravenous delivery anchors the volume base while inhalational modes gain share at the steepest rate as European anesthesia services pilot volatile ICU sedation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand elasticity varies sharply across geographies: United States purchasers absorb premium pricing for advanced monitoring integration, while European procurement offices and Medicaid-dominant hospital systems enforce aggressive generic substitution.
United States
ICU bed density and sepsis protocol expansion sustain the highest per-capita pharmaceutical consumption intensity. FDA boxed warning requirements for propofol infusion syndrome monitoring pull capital expenditure into pump infrastructure upgrades. Tertiary academic medical centers in Boston and the Research Triangle pilot closed-loop sedation systems.
Germany
Academic medical centers in Bavaria and North Rhine-Westphalia anchor European adoption of processed EEG-integrated delivery platforms. EMA pharmacovigilance requirements for dexmedetomidine cardiovascular surveillance create documentation burdens that slow nursing workflow efficiency. Heidelberg and Berlin clusters drive inhalational sedation pilot programs for post-operative ventilation weaning.
United Kingdom
NHS Integrated Care Systems consolidate formulary control around ICU Liberation Bundle protocols, favoring short-acting agents with rapid awakening profiles. NICE technology appraisal processes create reimbursement lag for novel delivery devices. London and Manchester teaching hospitals concentrate closed-loop algorithm development partnerships.
India
CDSCO regulatory pathways for generic IV sedative approval accelerate multi-source supply contracts in cost-constrained tertiary hospitals. Maharashtra and Karnataka state health missions expand ICU bed capacity in public sector facilities. Mumbai and Bengaluru private hospital chains import premium infusion platforms for medical tourism segments.
Japan
PMDA post-market surveillance requirements for infusion pump safety sustain extended product registration timelines. METI reimbursement pricing reviews compress margin structures for originator sedative agents. Tokyo and Osaka metropolitan hospital networks concentrate demand for delirium-sparing protocols in aging patient populations.
Sedation in ICU Setting Market Key Industry Players
Capability concentration sits with specialized anesthesia and critical care pharmaceutical developers; scale advantage sits with diversified parenteral delivery system manufacturers. The market structures around three tiers: originator drug developers with formulary lock-in, generic manufacturers with cost-based procurement penetration, and infusion device OEMs with ecosystem control over hospital capital cycles. Dominant competitive moves include strategic partnerships between pharmaceutical and device developers for integrated protocol offerings, and geographic expansion through multi-source supply contracts in emerging markets.
Within the originator-specialist tier, AstraZeneca and GlaxoSmithKline represent pharmaceutical developers with historical critical care portfolios. Among diversified parenteral delivery manufacturers, Fresenius Kabi occupies a position exemplifying captive manufacturing integration across drug and device segments. Teva sits within the generic penetration archetype, anchoring cost-sensitive procurement strategies in Medicaid-dominant and European austerity environments.
| Leading Market Players |
|---|
| AstraZeneca |
| GlaxoSmithKline |
| Mylan |
| Fresenius Kabi |
| Teva |
| B. Braun Medical |
| Pfizer |
| Sanofi |
| Abbott Laboratories |
| Others |
Cost & Logistics Intelligence
Single-source propofol lipid emulsion dependency determines both three-tier pricing spreads across originator-generic-biosimilar tiers and supply chain shape, as FDA-mandated monitoring infrastructure bundles pull pump maintenance revenue into pharmaceutical procurement cycles while concentrated API manufacturing in India and China exposes formularies to batch shortage risk.
Pricing Analysis
Aftermarket service contracts for infusion pump calibration and sedation protocol consulting drive lifetime value capture beyond per-vial pharmaceutical sales. Pricing stratifies across premium closed-loop systems with processed EEG integration, standard programmable pumps with EMR interoperability, and economy-tier basic infusion platforms without respiratory monitoring modules. Cost compression in the economy tier intensifies as Medicaid-dominant hospital systems consolidate generic dexmedetomidine contracts. Emergency departments exhibit the highest price sensitivity due to formulary independence and rapid turnover of short-acting dissociative agents, while academic medical center ICUs absorb premium pricing for algorithm-driven titration systems.
Supply Chain Analysis
Extended payment terms from hospital GPOs to device OEMs compress working capital cycles for mid-tier pump manufacturers. Active pharmaceutical ingredient production concentrates in India and China, with lipid emulsion excipient sourcing anchored in European chemical processing hubs. Soybean oil and egg lecithin dependencies for propofol formulation create agricultural commodity exposure that amplifies batch-to-batch cost variance. Single-source vulnerability for dexmedetomidine API ties availability to limited fermentation capacity. Distribution runs through hospital group purchasing organizations in the United States and regional pharmacy cooperatives in European markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
ICU Liberation Bundle adoption fragments protocol standardization across health systems, creating entry niches for specialized sedation technology vendors and generic pharmaceutical suppliers as formulary committees diverge on daily interruption workflows.
For Market Incumbents: Insulate pump ecosystem lock-in through proprietary EMR data protocols that force middleware investment for multi-vendor hospitals, while backward integration into propofol API manufacturing reduces exposure to Indian and Chinese excipient supply shocks. Captive production of lipid emulsion formulations defends margin position against generic substitution pressure in cost-sensitive procurement environments.
For New Entrants and Emerging Players: Inhalational sedation device penetration in German and United Kingdom anesthesia services represents the most penetrable white-space target, as volatile anesthetic delivery pilots for ICU ventilation weaning sit outside established IV pump vendor relationships. A go-to-market angle through anesthesia machine upgrade partnerships bypasses incumbent infusion platform procurement freezes.
For Investors and Strategic Acquirers: The market sits at a protocol transition phase that favors generic pharmaceutical manufacturers with multi-source supply contracts and device developers with closed-loop algorithm capabilities. Acquisition targets should demonstrate formulary penetration in ICU Liberation collaborative networks or proprietary EEG-processing integration. The signal to watch is FDA guidance evolution on continuous infusion monitoring thresholds that would accelerate pump replacement cycles.
| Strategic Initiative | Industry Significance |
|---|---|
| Closed-Loop Algorithm Development | Processed EEG-integrated titration collapses variance in time-to-extubation at Boston and Research Triangle academic centers. |
| Generic Dexmedetomidine Scale-Up | Multi-source supply contracts penetrate Medicaid-dominant hospital systems with originator undercutting. |
| Inhalational Sedation Device Pilot | Volatile anesthetic delivery partnerships in Heidelberg and Berlin anesthesia services bypass IV pump saturation. |
| EMR Interoperability Certification | ISO 80601-2-24 compliance unlocks hospital capital cycles frozen by electromagnetic compatibility requirements. |
| Aftermarket Service Unbundling | Third-party pump maintenance capture fragments revenue streams previously monopolized by Fresenius Kabi and B. Braun. |
Research Approach
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with critical care pharmacists, ICU nursing directors, biomedical engineering managers, and anesthesia department chairs, cross-referenced against FDA 510(k) filings, EMA pharmacovigilance databases, hospital GPO contract repositories, and ISO 80601-2-24 certification records. Bottom-up pharmaceutical consumption modeling triangulated with top-down device installation tracking across tertiary hospital networks.
Calibration against historical ICU bed expansion rates and sepsis protocol adoption curves anchored volume projections across the analysis window. Segmentation dimensions included agent pharmacokinetic class, mechanical ventilation dependency, delivery mode technology tier, and regional regulatory cluster. CAGRs derived from pharmaceutical consumption intensity per patient-day and capital equipment replacement cycles. Forecast inputs incorporated FDA boxed warning enforcement trajectories and EMA cardiovascular surveillance documentation burdens.
The forecast holds incumbent behavior within observed patterns; aggressive moves by closed-loop algorithm developers or inhalational sedation device manufacturers would shift outcomes. Macroeconomic contraction in hospital capital expenditure, regulatory acceleration of propofol infusion syndrome monitoring requirements, or technological breakthrough in non-invasive sedation depth assessment would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Anesthesiology
Anaesthesia Machines Market
Anesthesiology
Inhalation Anesthetics Market
Anesthesiology
Anesthesia CO2 Absorbent Market
Anesthesiology
Anesthesia Delivery Units Market
Anesthesiology
Global Inhalation Anesthesia Market
Anesthesiology
Smart Anesthesia System Market
Anesthesiology
Vasopressin for Vasoplegic Shock Market
Anesthesiology
Epinephrine Market
Anesthesiology
Anesthesia Breathing Circuits Market
Anesthesiology
Endotracheal Tube Cuffs Market
Anesthesiology
Global Anesthesia and Respiratory Devices Market
Anesthesiology
Artificial Airway Holders Market
Anesthesiology
Global Anesthesia Delivery Systems Market
Anesthesiology
Anesthetics Market
Anesthesiology
Delirium Market
Anesthesiology
Global Anesthesia Endotracheal Tubes Market