
 Kidney Dialysis Equipment Market | 2026-2036
Kidney Dialysis Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Kidney Dialysis Equipment Market Outlook
Market Context
Single-source procurement of dialysis consumables is consolidating into multi-year, multi-vendor agreements as hospital systems seek supply security. Fresenius Medical Care AG & Co leverages captive manufacturing of dialyzers and concentrates to anchor its integrated care model across clinical and home settings. Baxter International, Inc. competes through peritoneal dialysis specialization, while Asahi Kasei Corporation dominates hollow-fiber membrane technology for high-flux dialyzer production.
Technical Definition and Segment Structure
Kidney dialysis equipment encompasses electromechanical systems and disposable assemblies that extracorporeally filter blood or exchange peritoneal fluid to substitute for failed renal function, typically operating with blood flow rates of 200-500 mL/min and ultrafiltration precision within 10 mL/hour. Hemodialysis machines retain the largest installed base, though wearable devices represent the fastest-expanding technology segment as miniaturization and biocompatibility advances reduce treatment burden. Home care as an end-user channel is deepening margin pools for manufacturers capable of delivering remote monitoring integration and patient training infrastructure alongside hardware.
Regulatory Environment
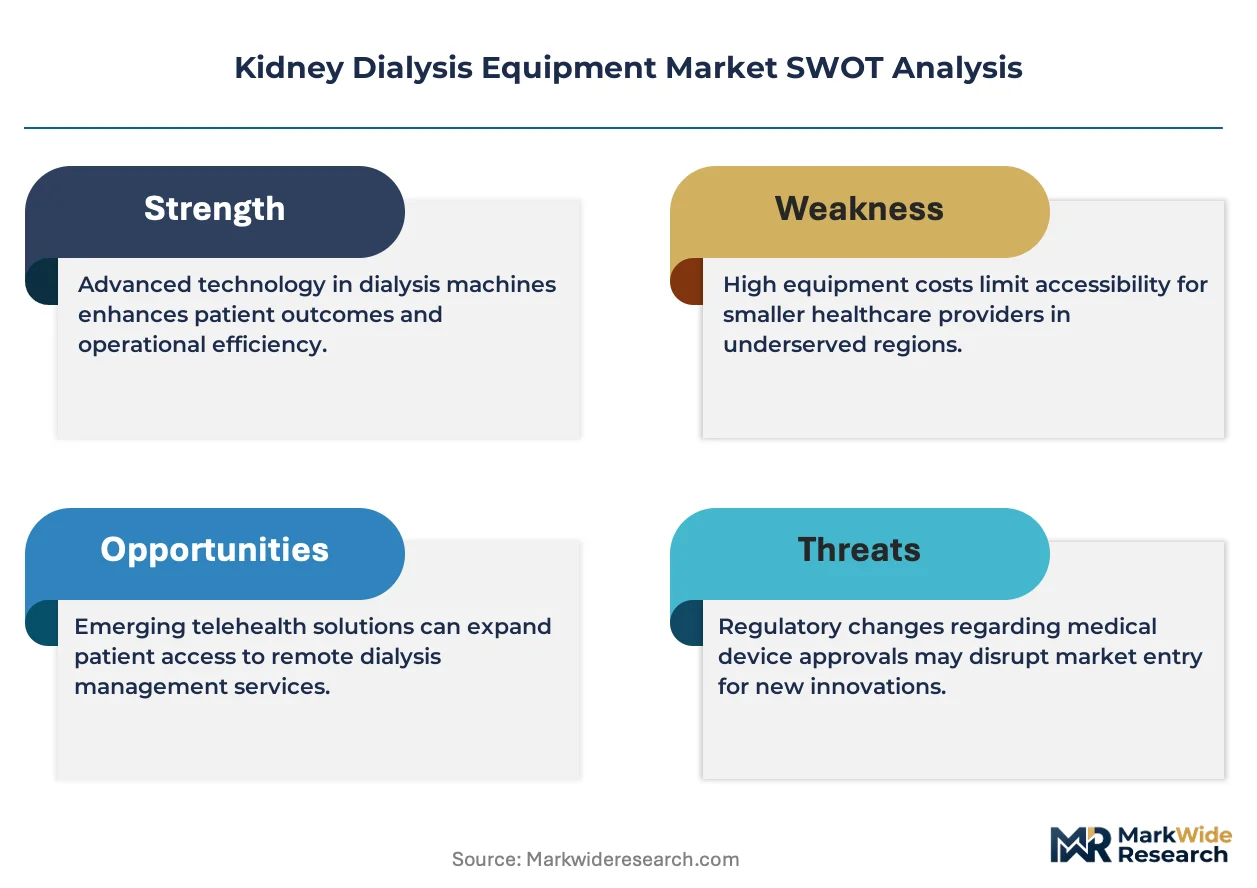
The FDA governs device safety and efficacy through premarket notification and PMA pathways for novel dialysis systems, while the EU Medical Device Regulation imposes strengthened clinical evidence requirements for class IIb and III renal replacement products. Japan's PMDA maintains distinct biocompatibility testing protocols that shape market entry timelines for membrane and tubing innovations. Stakeholders must monitor reimbursement coding decisions for home hemodialysis and wearable modalities, as these determine whether technology advances translate into addressable commercial opportunity.
Market Dynamics
Medicare reimbursement policy is compressing treatment economics toward home-based modalities, forcing manufacturers to reengineer hardware for unsupervised operation while maintaining clinical equivalence to in-center systems.
Growth Catalysts
- Home hemodialysis reimbursement expansion:CMS payment parity for home and in-center treatments removes financial disincentives for patient migration to residential settings.
- Wearable artificial kidney miniaturization:Advances in sorbent regeneration and battery efficiency enable continuous ambulatory filtration without fixed infrastructure.
- End-stage renal disease prevalence trajectories:Diabetes and hypertension epidemics in aging populations sustain replacement therapy demand across developed healthcare systems.
Market Restraints
- Polymer supply concentration:Hollow-fiber membrane production depends on specialized polysulfone and polyethersulfone resin suppliers concentrated in Germany and Japan.
- Biocompatibility testing burden:FDA and PMDA require extended thrombogenicity and complement activation studies that extend development timelines for new membrane chemistries.
- Peritoneal dialysis infection risk:Peritonitis incidence limits patient candidacy and creates liability exposure that constrains modality switching.
Strategic Opportunities
- Remote patient monitoring integration:Cloud-connected devices with automated data transmission to nephrology teams enable proactive intervention and reduce hospitalization.
- India dialysis infrastructure deficit:Penetration rates below 10 percent of estimated need create addressable market for cost-optimized portable systems.
- Sorbent cartridge subscription models:Recurring revenue from consumable replacement transforms capital equipment sales into predictable annuity streams.
Industry Challenges
- Biomedical technician scarcity:Home program expansion requires training infrastructure for patient self-care and caregiver support that outpaces workforce supply.
- Legacy EMR interoperability:Proprietary data formats from incumbent manufacturers obstruct seamless integration with hospital information systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Kidney Dialysis Equipment Market |
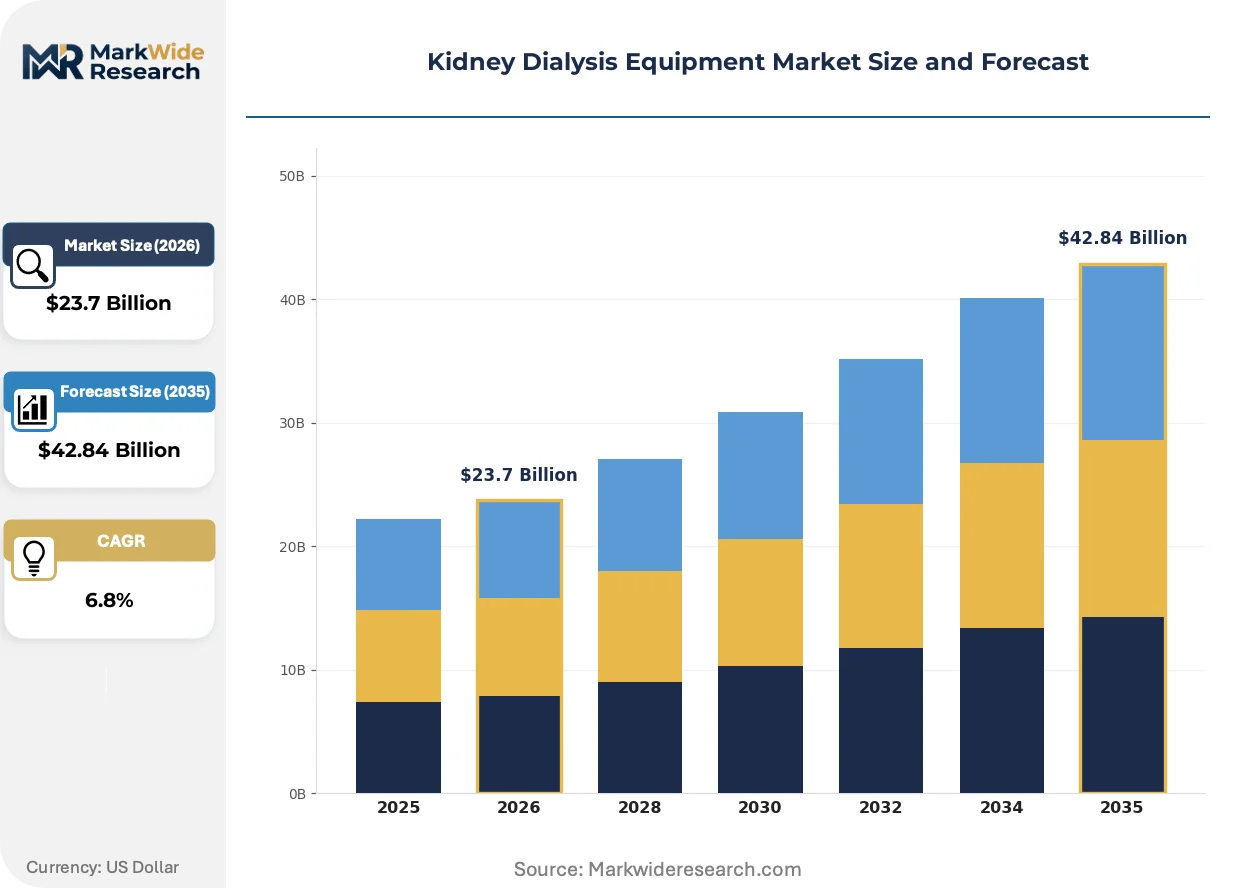
| Market Size in 2026 | $23.7 Billion |
| Market Size in 2035 | $42.84 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
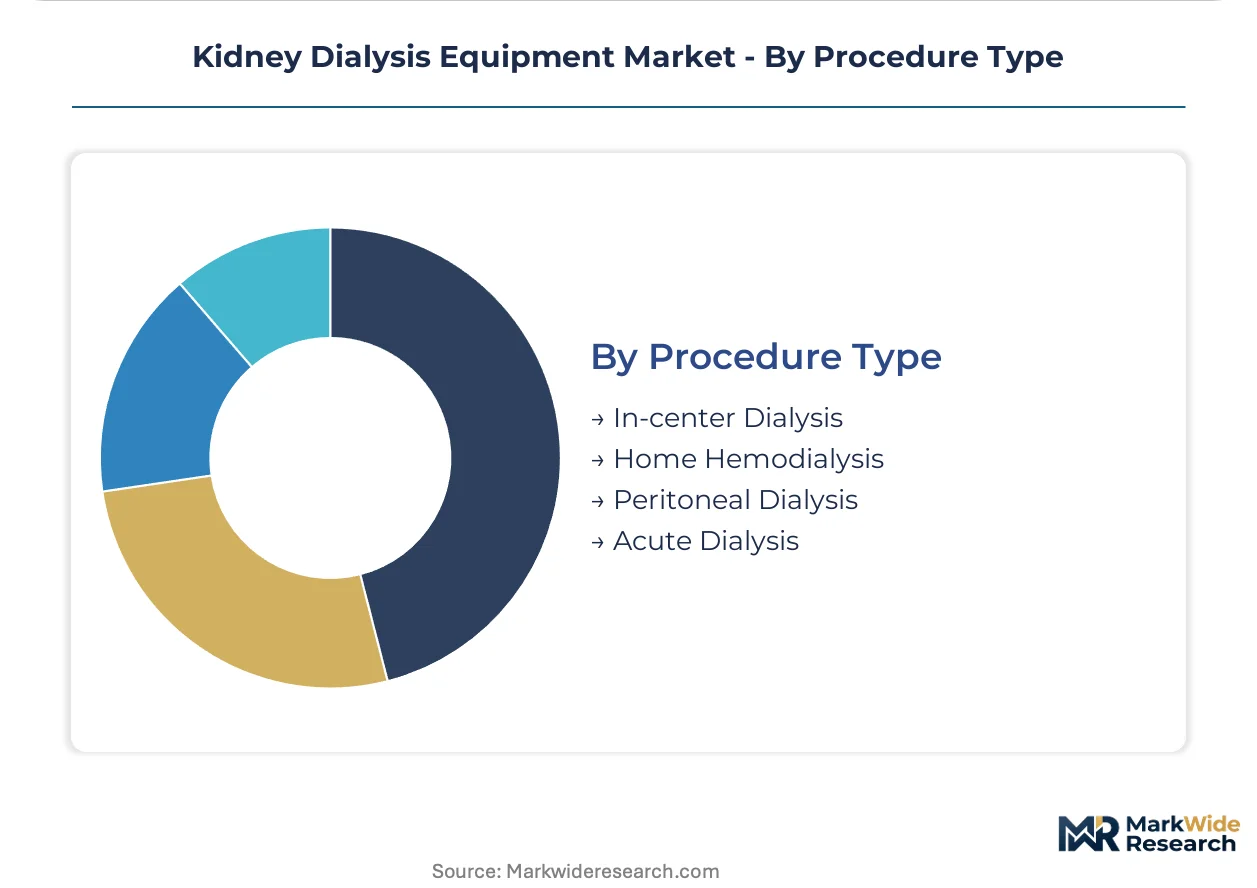
| Segmentation | Product Type: Hemodialysis Machines, Peritoneal Dialysis Equipment, Dialyzers, Dialysis Kits End User: Hospitals, Dialysis Centers, Home Care, Long-term Care Facilities Technology: Conventional Dialysis, Continuous Renal Replacement Therapy, Automated Peritoneal Dialysis, Wearable Devices Procedure Type: In-center Dialysis, Home Hemodialysis, Peritoneal Dialysis, Acute Dialysis |
| Companies Covered | B. Braun Melsungen AG, Asahi Kasei Corporation, Fresenius Medical Care AG & Co, DaVita Inc., Toray Medical Co., Ltd., Baxter International, Inc., Nikkiso Co., Ltd., Medtronic PLC, Nipro Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Kidney Dialysis Equipment Market Strategic Shifts
Device architecture is converging toward closed-loop automation, with sensor feedback replacing manual parameter adjustment and artificial intelligence filtering alarm noise to reduce cognitive burden on operators.
Miniaturized sorbent-based systems are absorbing the function of traditional dialysate preparation, eliminating water treatment infrastructure and enabling true portability. Home program coordinators are deploying these systems to patients with limited home modification capacity. The technology is absorbing capital requirements from clinical settings into disposable consumable economics.
The EU Medical Device Regulation's strengthened clinical evidence requirements for class IIb renal replacement products are extending time-to-market for novel dialyzers. Manufacturers must generate post-market surveillance data that demonstrates sustained biocompatibility across diverse patient phenotypes. High-flux membrane categories face the steepest documentation burden, compressing innovation pipelines toward incremental rather than breakthrough improvements.
Hospital system procurement is consolidating dialysis consumables into multi-year framework agreements that bundle machines, disposables, and technical service. Integrated delivery networks are displacing individual facility purchasing autonomy with centralized supply chain governance. This concentration is most visible in United States regional health systems seeking Medicare Advantage contract efficiencies through standardized modality protocols.
Kidney Dialysis Equipment Market Segmentation
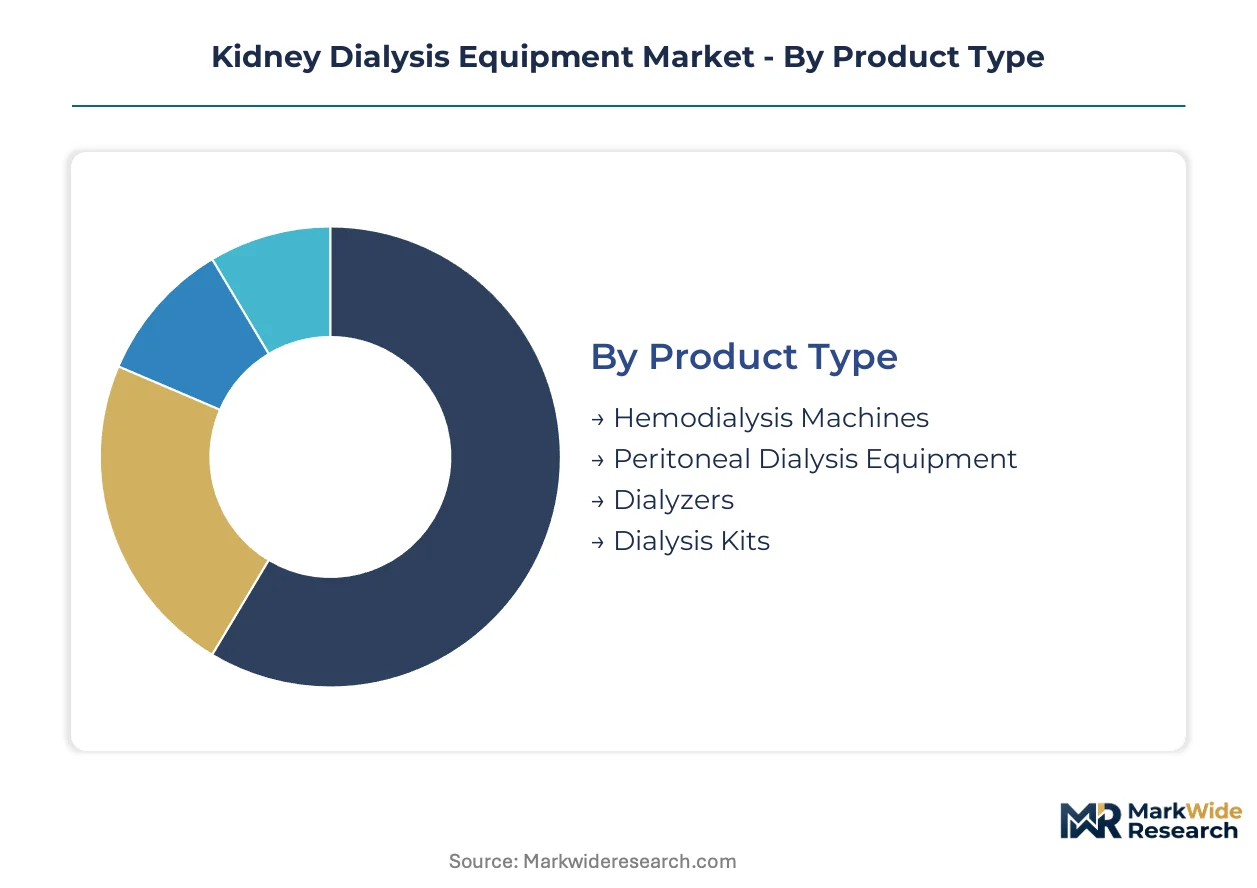
Dialysis equipment segmentation reveals divergent margin structures across clinical and residential settings. Product architecture, reimbursement pathways, and patient risk profiles determine where manufacturers capture value versus where commoditization pressures concentrate.
Product Type:
Volume economics favor disposable consumables, while premium returns attach to integrated system platforms that lock in recurring cartridge revenue.
- Hemodialysis Machines:Electromechanical platforms delivering controlled blood flow, ultrafiltration, and dialysate composition for 4-5 hour treatment cycles. Demand clusters in United States hospital systems pursuing Medicare Advantage efficiency through standardized modality protocols, constrained by biomedical technician scarcity for home program expansion.
- Peritoneal Dialysis Equipment:Cyclers and solution delivery systems enabling fluid exchange through the peritoneal membrane without vascular access. Penetration concentrates in markets with limited infrastructure investment capacity, particularly where water treatment for hemodialysis proves prohibitive.
- Dialyzers:Hollow-fiber membrane cartridges performing solute clearance and fluid removal. Specialized polysulfone and polyethersulfone resin dependencies in Germany and Japan shape supply security planning.
- Dialysis Kits:Pre-assembled disposable sets bundling bloodlines, needles, and anticoagulant delivery. Procurement consolidation into multi-year framework agreements is compressing pricing autonomy.
Mature deployment sits with Hemodialysis Machines. Newer deployment is concentrated in Dialysis Kits as bundled consumable economics displace capital equipment sales.
End User:
Reimbursement parity between settings is redistributing patient volumes toward lower-acuity environments.
- Hospitals:Acute renal failure management and complex comorbidity cases requiring intensive monitoring. United States inpatient capacity constraints are pushing stable patients toward alternative venues.
- Dialysis Centers:Dedicated outpatient facilities delivering scheduled hemodialysis with nursing oversight. Freestanding units face margin compression from Medicare bundled payment rates.
- Home Care:Residential settings where patients or caregivers perform self-dialysis with remote nephrology support. CMS payment parity removes financial disincentives for modality migration, though training infrastructure lags demand.
- Long-term Care Facilities:Skilled nursing environments managing end-stage renal disease among elderly populations with limited mobility. Regulatory complexity across state-level survey requirements constrains program expansion.
Established revenue concentration remains with Dialysis Centers. Steepest expansion trajectory attaches to Home Care as cloud-connected devices enable proactive clinical intervention.
Technology:
Automation depth and portability define competitive differentiation as treatment burden reduction becomes the primary purchase criterion.
- Conventional Dialysis:Three-times-weekly intermittent hemodialysis with fixed infrastructure and water treatment requirements. Dominates installed base but faces displacement from more frequent modalities.
- Continuous Renal Replacement Therapy:24-hour slow filtration for hemodynamically unstable patients in intensive care. Demand concentrates in tertiary hospital systems with cardiac surgery and trauma specialization.
- Automated Peritoneal Dialysis:Cycler-mediated nocturnal exchanges freeing daytime activity. Miniaturization and sorbent regeneration advances are reducing equipment footprint for home deployment.
- Wearable Devices:Ambulatory systems enabling continuous filtration without fixed infrastructure. FDA clearance pathway evolution is reshaping development priorities for sorbent cartridge and battery efficiency optimization.
Technology leadership currently resides with Automated Peritoneal Dialysis. Device architecture is converging toward Wearable Devices as biocompatibility and power management breakthroughs reduce treatment burden.
Procedure Type:
Modality selection determines capital intensity, consumable throughput, and reimbursement coding complexity.
- In-center Dialysis:Facility-based hemodialysis with direct nursing supervision and immediate complication response. United States regional health systems are standardizing protocols across integrated delivery networks.
- Home Hemodialysis:Patient-performed treatments with remote monitoring and periodic clinic review. Infrastructure requirements for water treatment and space allocation limit candidacy.
- Peritoneal Dialysis:Daily fluid exchanges via indwelling catheter without vascular access construction. Peritonitis risk creates liability exposure that constrains switching from hemodialysis.
- Acute Dialysis:Emergency renal replacement for sudden kidney injury in hospitalized patients. Volumes correlate with sepsis and cardiac surgery incidence patterns.
Procedure volume concentrates in In-center Dialysis. Patient migration is accelerating toward Home Hemodialysis as hardware reengineering enables unsupervised operation with clinical equivalence.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized polysulfone and polyethersulfone resin production concentrates in Germany and Japan, anchoring hollow-fiber membrane supply chains for dialyzer manufacturing. These feedstock localities shape where equipment makers establish captive production and where biocompatibility testing protocols achieve regulatory harmonization.
United States
Medicare reimbursement parity for home and in-center dialysis removes financial barriers to residential treatment migration. The FDA governs wearable and portable system clearances through evolving PMA pathways that reshape manufacturer development priorities. Boston and Minneapolis medical device clusters host concentrated nephrology engineering talent and venture capital for sorbent regeneration startups.
Germany
Integrated care models bundle dialysis machines with consumables and technical service across hospital networks seeking supply security. The EU Medical Device Regulation imposes strengthened clinical evidence requirements for class IIb renal replacement products. Baden-Württemberg's precision polymer industry supplies specialized membrane resins that dialyzer manufacturers depend upon.
Japan
Aging demographics sustain replacement therapy demand with end-stage renal disease prevalence trajectories exceeding OECD averages. PMDA maintains distinct biocompatibility testing protocols for thrombogenicity and complement activation studies. Tokyo-Osaka industrial corridors concentrate hollow-fiber spinning technology and automated dialyzer assembly lines.
India
Dialysis infrastructure penetration remains below ten percent of estimated clinical need, creating addressable market for cost-optimized portable systems. CDSCO device registration pathways are streamlining for renal replacement products as domestic manufacturing incentives expand. Hyderabad and Bengaluru medical technology parks attract foreign joint ventures targeting tier-two city deployment.
Brazil
Public health system procurement consolidates dialysis consumables into multi-year framework agreements with standardized modality protocols. ANVISA regulates device safety through premarket notification pathways that extend timelines for novel membrane chemistries. São Paulo's healthcare distribution networks anchor equipment import and technical service infrastructure for South American markets.
Kidney Dialysis Equipment Market Competitive Environment
Global majors compete with regional champions across integrated care models versus specialized component supply. Market structure tilts toward consolidation as multi-year procurement frameworks favor vendors with captive manufacturing and service infrastructure. Three archetypes dominate: diversified healthcare conglomerates with dialysis divisions, pure-play renal replacement specialists, and membrane technology component suppliers. Competitive moves concentrate on backward integration into polymer resin supply and cloud-connected remote monitoring platform development.
Within the diversified healthcare conglomerate tier, Fresenius Medical Care AG & Co and Baxter International, Inc. occupy positions defined by integrated care model breadth. Among membrane technology specialists, Asahi Kasei Corporation exemplifies the component supplier archetype that anchors high-flux dialyzer production through hollow-fiber expertise. These three entities represent distinct strategic postures: full vertical control versus peritoneal specialization versus materials science dominance.
| Leading Market Players |
|---|
| B. Braun Melsungen AG |
| Asahi Kasei Corporation |
| Fresenius Medical Care AG & Co |
| DaVita Inc. |
| Toray Medical Co., Ltd. |
| Baxter International, Inc. |
| Nikkiso Co., Ltd. |
| Medtronic PLC |
| Nipro Corporation |
| Others |
Value Chain & Pricing Dynamics
Hospital system consolidation into multi-year framework agreements is compressing pricing autonomy for consumables while forcing manufacturers to absorb service costs into bundled contracts. This procurement shift rewards vendors with captive dialyzer production and technical service infrastructure, widening spreads between integrated suppliers and component specialists.
Pricing Analysis
Equipment-plus-service bundling dominates hemodialysis machine contracts, while consumable pricing separates into unbundled per-treatment fees for dialyzers and kits. Price differentiation hinges on FDA clearance tier and remote monitoring integration depth. Cost compression in standard dialyzers intensifies as Asian membrane producers expand capacity, though premium high-flux categories retain pricing power. Dialysis centers exhibit highest price sensitivity due to Medicare bundled payment pressures, while hospital systems prioritize supply security over unit cost.
Supply Chain Analysis
CE marking and FDA 510(k) qualification requirements gate hollow-fiber membrane supply to specialized polysulfone and polyethersulfone resin producers in Germany and Japan. Dialyzer assembly draws from Baden-Württemberg precision polymer feedstock and Tokyo-Osaka spinning technology, with final equipment integration concentrating in United States and German manufacturing clusters. Single-source vulnerability in specialized resin grades creates supply chain risk amid geopolitical trade restrictions. Distribution runs through regional healthcare distributors with technical service capabilities, anchored by GPO contracts in United States hospital systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The kidney dialysis equipment market sits at a technology-transition inflection as wearable sorbent-based systems displace conventional three-times-weekly hemodialysis infrastructure. Miniaturization and biocompatibility advances are collapsing the hardware footprint required for residential treatment.
For Market Incumbents: Deploy backward integration into hollow-fiber membrane resin production to secure supply against German and Japanese feedstock concentration. Consolidate technical service networks to defend against emerging portable system competitors threatening in-center modality dominance. Lock hospital systems into multi-year consumable framework agreements before wearable devices achieve reimbursement parity. For New Entrants and Emerging Players: The premium-economy price gap in home hemodialysis hardware creates white-space opportunity for cost-optimized portable systems targeting India's sub-ten-percent penetration market. Prioritize sorbent cartridge subscription economics over capital equipment sales to align with recurring revenue models. Partner with regional distributors in Brazil and India to bypass entrenched GPO relationships in developed markets. For Investors and Strategic Acquirers: The window for entry favors membrane technology specialists with hollow-fiber spinning capabilities that incumbent conglomerates lack. Long-term viability hinges on FDA clearance pathway evolution for wearable modalities and CMS reimbursement coding decisions. Watch for sorbent regeneration breakthroughs as the signal indicating acceleration toward continuous ambulatory filtration.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Submission for Wearable Systems | Clearance pathway evolution determines whether sorbent miniaturization translates into commercial addressable market. |
| Hospital System Partnership | Integrated delivery network contracts lock in multi-year consumable revenue and displace competitor installed base. |
| Backward Integration into Membrane Resins | Captive polysulfone supply secures dialyzer production against German and Japanese feedstock concentration. |
| Software Companion Development | Cloud-connected remote monitoring platforms enable proactive clinical intervention and reduce hospitalization rates. |
| Reimbursement Strategy | CMS coding decisions for home hemodialysis and wearable modalities determine technology adoption economics. |
Study Parameters
Multi-period observation of Medicare reimbursement policy shifts and FDA clearance pathway evolution anchored the trend analysis, supplemented by interviews with nephrology practice administrators, biomedical engineering directors, hospital GPO contract managers, and dialysis center operations leads. Secondary validation drew from CMS Medicare cost reports, FDA 510(k) and PMA databases, hospital procurement databases, and EU MDR technical documentation. Bottom-up equipment shipment tracking and top-down healthcare expenditure analysis were triangulated against manufacturer revenue disclosures.
Segment-weighting approaches applied product type, end-user channel, technology modality, and procedure type dimensions across the modeling period. CAGRs were derived from installed base replacement cycles, patient prevalence trajectories, and modality migration assumptions. Forecast inputs incorporated CMS payment parity policy persistence, sorbent regeneration technology maturation curves, and regional infrastructure penetration gaps.
Inputs from FDA premarket notification databases and CMS reimbursement coding decisions were available through the study window; gaps in real-time wearable device clinical trial outcomes introduce uncertainty bands around adoption timing assumptions. Stakeholders should weight assumptions against their own operating context and regulatory engagement timelines.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nephrology
Peritoneal Dialysis Market
Nephrology
Dialysis Service Market
Nephrology
Global Acute Kidney Injury Treatment Market
Nephrology
Plasmapheresis Market
Nephrology
Global Dialysis Market
Nephrology
Kidney Fibrosis Treatment Market
Nephrology
Glomerulonephritis Treatment Market
Nephrology
US Dialysis Market
Nephrology
Global Hemodialysis Market
Nephrology
Hemodialysis Vascular Graft Market
Nephrology
Renal Artery Stenosis Treatment Market
Nephrology
Hemodialysis and Peritoneal Dialysis Market
Nephrology
South Africa Hemodialysis and Peritoneal Dialysis Market
Nephrology
Global Dialyzer Market
Nephrology
Kidney Transplant Market
Nephrology
Ketoanalogue for Kidney Disease Market