
 North America General Aviation Market | 2026-2036
North America General Aviation Market Size, Share, and Industry Trends Forecast 2026-2036
North America General Aviation Market Analytics
Canadian turboprop manufacturing is expanding as Pilatus Aircraft extends its North American assembly footprint and Bombardier sustains its Montreal-based business jet production. Textron Inc. leverages its Wichita, Kansas manufacturing complex to dominate the light aircraft segment with Cessna and Beechcraft brands. Cirrus Design Corporation anchors the single-engine piston market through its Duluth, Minnesota facility and differentiated whole-airframe parachute systems.
General aviation encompasses all civil aircraft operations excluding scheduled commercial air service, typically involving fixed-wing aircraft with maximum takeoff weights below 12,500 pounds, helicopters, and business jets operating under visual or instrument flight rules for private, corporate, or specialized commercial purposes. The business jets category leads value generation due to transcontinental range requirements and cabin customization premiums, while the electric engine type represents the fastest-growing segment as battery energy density improvements enable urban air mobility prototypes. Turboprops occupy the mature utility niche where short-field performance and operating economics sustain regional charter and cargo demand across remote Canadian and Alaskan destinations.
The FAA mandates airworthiness standards under Part 23 and Part 25 regulations while Transport Canada Civil Aviation enforces equivalent certification through its Canadian Aviation Regulations, with both agencies accelerating eVTOL integration pathways through new powered-lift aircraft categories. Environmental pressure from EPA emissions guidelines and emerging state-level carbon policies is forcing piston engine manufacturers toward unleaded avgas alternatives and hybrid propulsion architectures. Stakeholders must monitor how FAA reauthorization priorities and municipal noise ordinances reshape airport access for next-generation aircraft designs.
Market Dynamics
FAA certification reforms for powered-lift aircraft are compressing development timelines while Part 91 corporate flight departments accelerate fleet renewals, creating simultaneous demand pull and regulatory pressure on airframe manufacturers.
Growth Catalysts
- Advanced Air Mobility Certification:FAA's new powered-lift aircraft category under Part 23 reforms is unlocking urban air mobility prototypes for commercial deployment.
- Corporate Fleet Expansion:Part 91 flight departments are expanding owned and managed fleets as fractional ownership models mature and C-suite travel policies favor controlled mobility.
- Southwestern Infrastructure:Arizona, Texas, and New Mexico hangar construction and favorable weather patterns are enabling year-round utilization rates that justify new aircraft acquisitions.
Market Restraints
- 100LL Avgas Phase-Out:EPA emissions guidelines targeting leaded aviation gasoline are forcing costly engine retrofits or airframe obsolescence for legacy piston fleets.
- Pilot Labor Scarcity:Certified flight instructor pipeline constraints and ATP hour requirements are limiting fleet utilization rates for charter operators.
- Supply Concentration:Wichita, Kansas and Montreal, Quebec manufacturing clusters create geographic vulnerability to weather disruptions and labor actions.
Strategic Opportunities
- Canadian Remote Access:Turboprop utility demand across northern Alberta, Yukon, and Nunavut remains underpenetrated for medevac and resource extraction transport.
- Hybrid-Electric Convergence:Battery energy density improvements combined with turbine range extension architectures are opening regional air mobility corridors.
- Municipal Noise Ordinance Adaptation:Quieter propulsion systems are securing airport access in noise-restricted California and Florida communities that previously banned piston operations.
Industry Challenges
- Certification Timeline Compression:FAA and Transport Canada Civil Aviation parallel review processes for novel aircraft designs are creating documentation bottlenecks and engineering resource strain.
- Avionics Integration Complexity:Next-generation glass cockpit systems require specialized technician training that outpaces current A&P mechanic certification pathways.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America General Aviation Market |
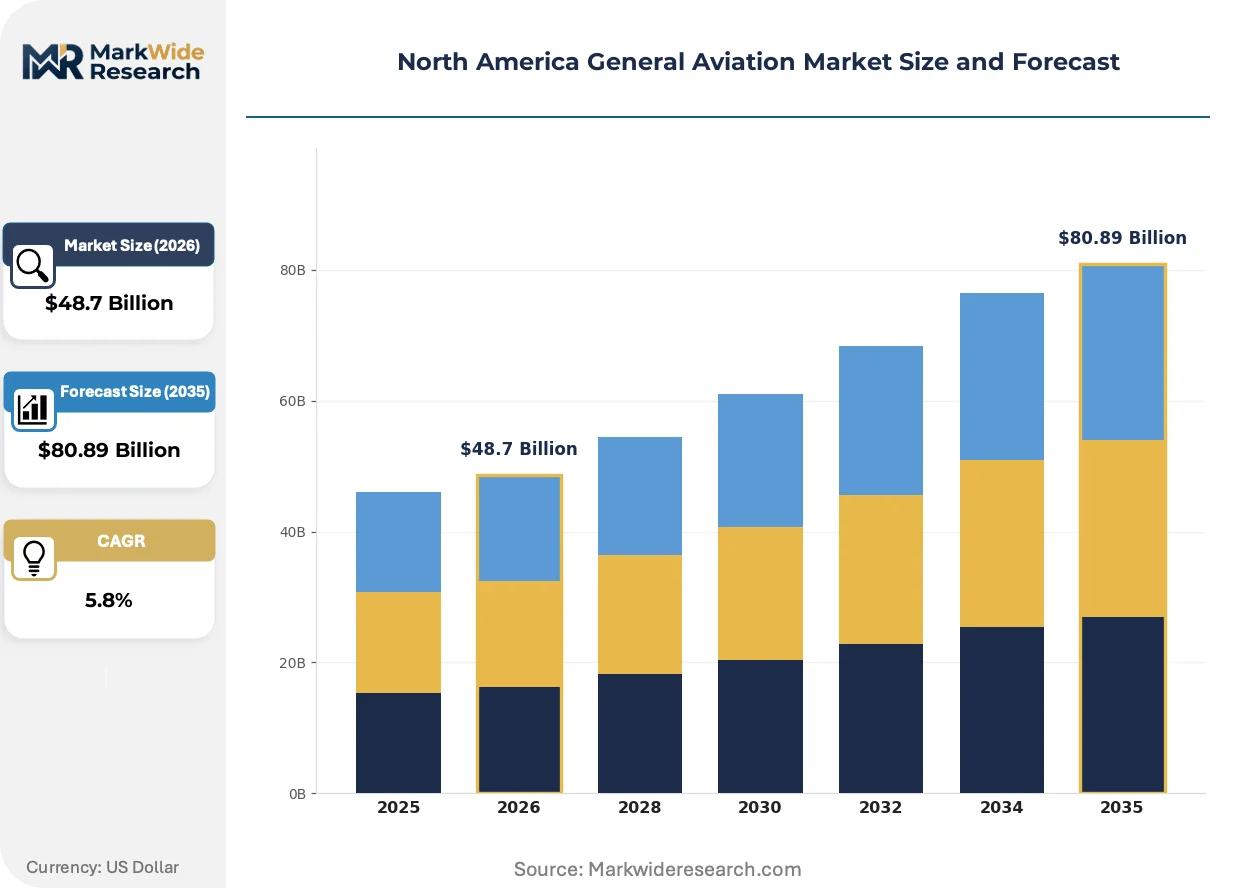
| Market Size in 2026 | $48.7 Billion |
| Market Size in 2035 | $80.89 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Aircraft Type: Light Aircraft, Business Jets, Helicopters, Turboprops End User: Private Owners, Corporate Entities, Flight Schools, Government Agencies Operation Type: Charter Services, Air Ambulance, Personal Use, Flight Training Engine Type: Piston, Turbine, Electric, Hybrid |
| Companies Covered | Textron Inc., Bombardier Inc., Embraer S.A., General Dynamics Corporation, Dassault Aviation, Airbus SE, Cirrus Design Corporation, Leonardo S.p.A., Pilatus Aircraft, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America General Aviation Market Evolving Landscape
Propulsion electrification and autonomous flight systems are converging to redefine aircraft architecture, while regulatory frameworks race to accommodate designs that blur traditional category boundaries.
Electric propulsion architectures are electrifying the light aircraft segment as battery pack energy density crosses threshold levels for 100-mile urban missions. Regional charter operators in California and Florida are piloting electric trainers to reduce hourly operating costs. This shift is compressing the addressable market for traditional piston engine manufacturers and forcing unleaded avgas alternatives to accelerate.
Transport Canada Civil Aviation and FAA harmonization efforts on powered-lift certification are creating dual-approval pathways for eVTOL developers. The industrial consequence is consolidated flight testing programs that reduce duplicate engineering validation. Urban air mobility manufacturers targeting Toronto-Pearson and Dallas-Fort Worth corridors are responding with parallel submission strategies to capture cross-border operational rights.
Fractional ownership platforms are fragmenting the traditional aircraft sales channel as digital marketplaces connect flight departments with underutilized Part 91 assets. Charter brokers in Arizona and Texas are displacing traditional dealership relationships with app-based availability matching. This pattern is most visible in the light jet segment where hourly utilization transparency enables spot-market pricing that undercuts fixed management contracts.
North America General Aviation Market Segmentation
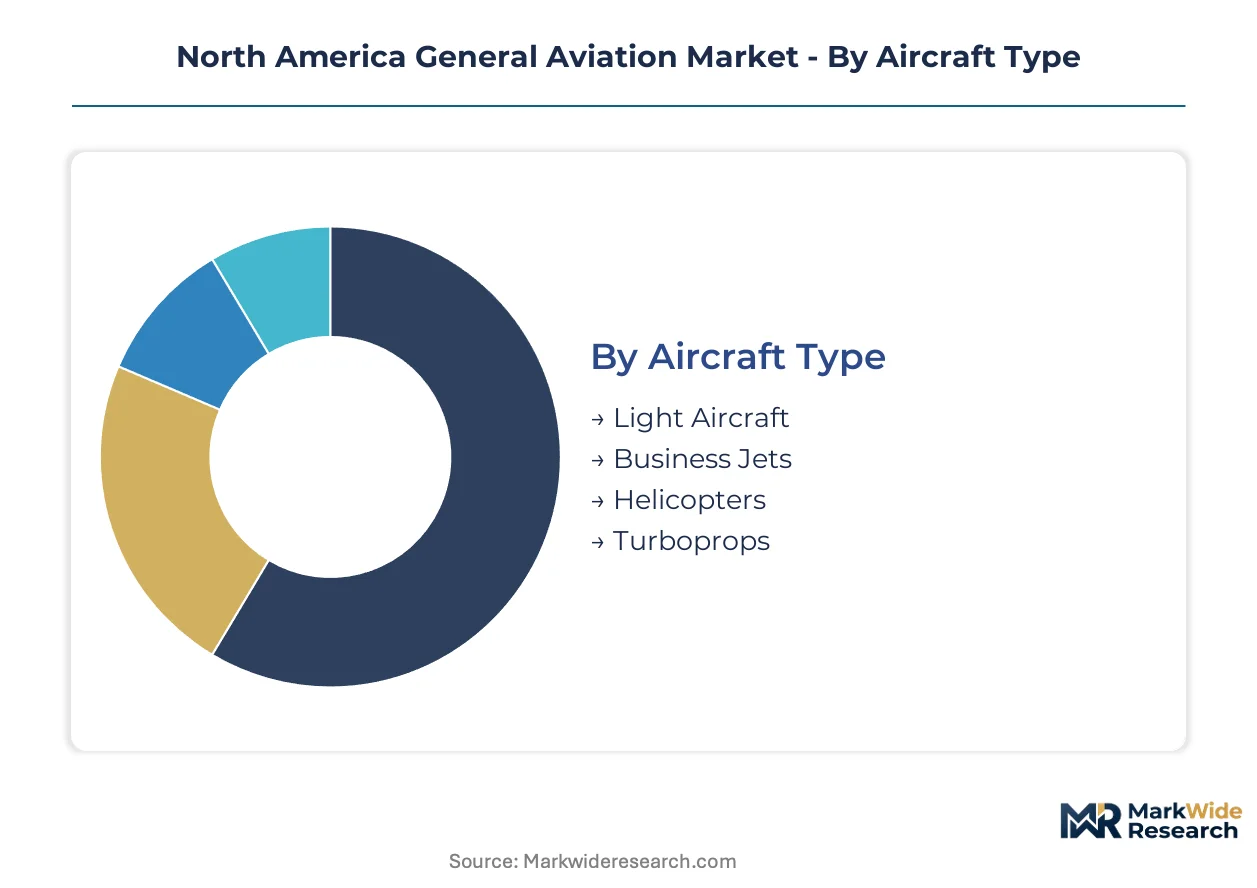
General aviation manufacturers navigate divergent certification pathways that fragment production economics. FAA Part 23 governs light aircraft while Part 25 applies to business jets, creating distinct engineering resource allocations across segments.
Aircraft Type:
Certification burden concentrates heaviest on business jets requiring Part 25 transport-category validation, while light aircraft operate under streamlined Part 23 amendments that reduce compliance timelines.
- Business Jets:Long-range pressurized cabins with transcontinental capability command premium pricing through bespoke interior configurations. Demand clusters in southwestern United States flight departments where hangar infrastructure supports year-round Part 91 operations under favorable weather patterns.
- Light Aircraft:Single-engine piston and light sport configurations dominate flight training pipelines with lower acquisition thresholds. Private owners in Arizona and Texas drive replacement cycles as unleaded avgas alternatives reach commercial viability.
- Turboprops:Short-field performance sustains utility demand across remote Canadian and Alaskan destinations where runway infrastructure limits jet access.
- Helicopters:Vertical lift capability serves offshore energy and urban air mobility prototypes under emerging powered-lift certification frameworks.
Leading the category by volume: Light Aircraft. Growing fastest: Business Jets.
End User:
Procurement patterns diverge sharply between price-sensitive individual buyers and fleet-scale corporate purchasers with dedicated acquisition teams.
- Corporate Entities:Part 91 flight departments deploy capital through fractional ownership platforms and direct management contracts. Fleet renewals accelerate in Texas and California where C-suite mobility policies prioritize schedule control over commercial airline alternatives.
- Private Owners:Individual pilots acquire single-engine piston aircraft for recreational and personal transport missions. Hangar availability constraints in Florida and Arizona communities limit addressable demand despite favorable operating economics.
- Flight Schools:Certified flight instructor pipelines depend on trainer aircraft availability and insurance accessibility for student solos.
- Government Agencies:Federal and provincial contracts for surveillance, patrol, and administrative transport sustain specialized turboprop and helicopter procurement.
Corporate Entities dominate absolute dollar volume. Private Owners represent the broadest addressable base.
Operation Type:
Revenue model architecture separates capital-intensive asset ownership from utilization-based service provision.
- Charter Services:Part 135 operators monetize underutilized Part 91 assets through digital marketplace platforms. Arizona and Texas brokers displace traditional dealership relationships with app-based availability matching that compresses pricing transparency.
- Personal Use:Owner-flown operations under Part 91 generate lowest hourly utilization but highest per-flight satisfaction metrics. Southwestern United States weather patterns enable year-round activity that justifies acquisition economics.
- Air Ambulance:Medevac configurations serve remote Canadian territories where ground transport infrastructure remains undeveloped.
- Flight Training:Ab initio and instrument rating pipelines feed commercial airline pilot demand through structured curricula.
Charter Services capture the steepest expansion trajectory. Personal Use maintains the largest installed base.
Engine Type:
Propulsion architecture determines regulatory jurisdiction, fuel infrastructure dependency, and noise ordinance compliance.
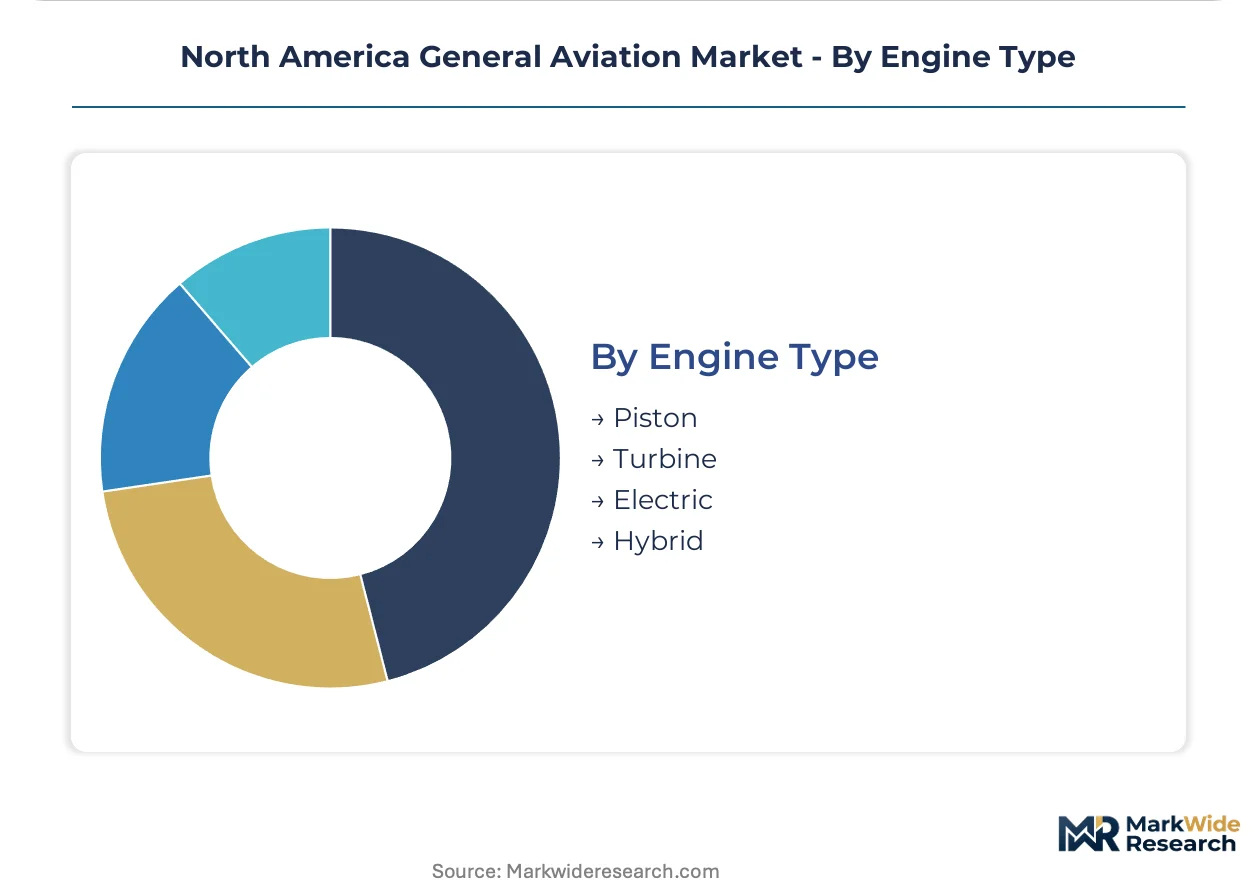
- Electric:Battery-electric architectures cross threshold energy density for 100-mile urban missions. California and Florida operators pilot electric trainers to reduce hourly operating costs and secure airport access in noise-restricted communities.
- Piston:Traditional internal combustion engines face EPA emissions pressure targeting 100LL avgas phase-out. Legacy fleet obsolescence risks accelerate as unleaded alternatives reach certification.
- Turbine:Turbofan and turboshaft configurations dominate business jet and helicopter segments where power-to-weight ratios justify fuel consumption premiums.
- Hybrid:Series-hybrid architectures combine battery electric propulsion with turbine range extension for regional air mobility corridors.
Piston engines retain installed base dominance. Electric propulsion is climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Aluminum and titanium feedstock corridors from the Great Lakes to the Gulf Coast anchor North American airframe manufacturing. Composite precursor supply chains concentrate in California and South Carolina. FAA and Transport Canada Civil Aviation harmonization efforts accelerate cross-border certification timelines for new propulsion architectures.
United States
Southwestern flight departments in Arizona, Texas, and New Mexico drive business jet demand through year-round utilization economics. FAA Part 23 reforms for powered-lift aircraft compress development timelines for urban air mobility entrants. Wichita, Kansas anchors light aircraft production through clustered manufacturing infrastructure serving Cessna and Beechcraft assembly lines.
Canada
Northern Alberta, Yukon, and Nunavut sustain turboprop utility demand for medevac and resource extraction missions where runway infrastructure limits jet access. Transport Canada Civil Aviation enforces Canadian Aviation Regulations equivalent to FAA standards while accelerating eVTOL integration pathways. Montreal, Quebec concentrates business jet production through Bombardier's sustained manufacturing footprint.
Mexico
Querétaro and Chihuahua aero clusters supply structural components and subassemblies to US-based original equipment manufacturers under bilateral aviation safety agreements. Mexico's Directorate General of Civil Aviation aligns certification processes with FAA standards to maintain cross-border supply chain fluidity. Baja California maintenance, repair, and overhaul facilities capture seasonal demand from US-registered aircraft seeking cost-competitive labor rates.
North America General Aviation Market Competitive Landscape
Global majors compete with regional champions across certification authority relationships and manufacturing scale. The market structures around tiered production economics where Part 25 transport-category validation creates higher barriers than Part 23 light aircraft pathways. Three archetypes dominate: diversified aerospace conglomerates with defense offsets, specialized business jet pure-plays, and vertically integrated light aircraft manufacturers. Capacity expansion in southwestern US hangar infrastructure and strategic partnerships for electric propulsion development represent the dominant competitive moves.
Within the diversified conglomerate tier, Textron Inc. and General Dynamics Corporation exemplify scale-driven positioning across military and civil aviation portfolios. Among specialized business jet manufacturers, Bombardier Inc. and Dassault Aviation occupy positions differentiated by cabin architecture and transcontinental range capabilities. Cirrus Design Corporation represents the innovation-focused archetype through its Minnesota-based single-engine piston specialization.
| Leading Market Players |
|---|
| Textron Inc. |
| Bombardier Inc. |
| Embraer S.A. |
| General Dynamics Corporation |
| Dassault Aviation |
| Airbus SE |
| Cirrus Design Corporation |
| Leonardo S.p.A. |
| Pilatus Aircraft |
| Others |
Value Network & Pricing Analysis
Captive aluminum and titanium forging operations in Wichita and Montreal anchor both cost predictability and pricing power for airframe manufacturers, insulating Part 25 transport-category producers from commodity volatility while compressing margins for outsourced Part 23 light aircraft assemblers. This integration choice concentrates bargaining leverage with conglomerates possessing in-house metallurgy capabilities.
Pricing Analysis
Warranty and airframe service bundling separates business jet transactions from light aircraft sales, with Textron and Bombardier embedding 5-year scheduled maintenance into Part 25 purchase agreements while Cirrus unbundles parachute system inspections. Three-tier pricing structure across premium long-range, standard mid-cabin, and economy light jet levels reflects certification burden differentials. Cost compression in the piston segment intensifies as EPA 100LL phase-out deadlines force engine retrofit pricing transparency. Private owners in Arizona and Texas exhibit highest price sensitivity, whereas Part 91 flight departments prioritize schedule control over acquisition cost.
Supply Chain Analysis
Single-source vulnerability sits with Canadian and Alaskan turboprop operators dependent on Pratt & Whitney Canada PT6 engine families, where factory backlog extends delivery timelines. Aluminum sheet and titanium billet feedstock draws from Great Lakes smelters and Gulf Coast processors, while composite precursors hinge on South Carolina and California chemical plants. Tariff exposure on Canadian aluminum disrupts cross-border fuselage component flows under USMCA automotive-style rules of origin. Distribution runs through Wichita and Montreal OEM direct sales teams for business jets, with light aircraft channeling through Arizona and Texas fractional ownership platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Hangar infrastructure scarcity in the southwestern United States props pricing power for aircraft delivery slots, as construction permit delays and municipal noise ordinances constrain fleet expansion capacity faster than manufacturing output can satisfy demand.
For Market Incumbents: Anchor defensive positioning through captive MRO network expansion in Arizona and Texas, securing aftermarket revenue streams against electric propulsion entrants. Deepen backward integration into composite precursor production to offset South Carolina supply concentration. Prioritize FAA Part 23 powered-lift certification investment to capture urban air mobility corridor rights before Transport Canada harmonization accelerates cross-border competition.
For New Entrants and Emerging Players: Enter via Canadian remote access turboprop services across northern Alberta and Nunavut, where medevac and resource extraction demand outpaces Pilatus and Bombardier field presence. Target electric trainer penetration in noise-restricted California communities that previously banned piston operations. Pursue app-based fractional ownership matching to displace traditional Arizona and Texas charter broker relationships.
For Investors and Strategic Acquirers: Exit pathways concentrate in aerospace conglomerate divestiture of civil aviation portfolios under defense offset pressure. Long-term viability favors vertically integrated manufacturers with captive metallurgy and certification authority relationships. Watch FAA reauthorization timing as inflection indicator for advanced air mobility regulatory clarity and eVTOL valuation resets.
| Strategic Initiative | Industry Significance |
|---|---|
| Powered-Lift Certification Investment | FAA Part 23 reform pathways unlock urban air mobility commercial deployment in Dallas-Fort Worth corridors. |
| Southwestern Hangar Infrastructure Expansion | Arizona and Texas construction permits enable year-round Part 91 fleet utilization economics. |
| Hybrid-Electric Propulsion Development | Battery-turbine architectures open regional air mobility corridors for medevac and charter operators. |
| Canadian Remote Access Service Buildout | Northern Alberta and Nunavut turboprop demand sustains utility margins where jet access remains limited. |
| Unleaded Avgas Alternative Certification | EPA emissions compliance preserves piston engine installed base and flight school trainer availability. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with FAA certification engineers, Part 135 charter operators, flight school fleet managers, and fractional ownership platform executives. FAA type certificate databases, Transport Canada Civil Aviation service difficulty reports, and GAMA shipment statistics provided demand-side validation. Bottom-up aircraft delivery tallies triangulated against top-down fleet utilization surveys.
Granularity-level modeling disaggregated volume and value across aircraft type, end user archetype, operation mode, and engine architecture throughout the projection horizon. CAGRs derived from log-linear trend fitting to historical delivery cycles, adjusted for regulatory phase-in schedules and infrastructure buildout assumptions. Forecast inputs incorporated battery energy density improvement curves, pilot certification pipeline constraints, and municipal noise ordinance adoption patterns.
Forecast precision tightens around the base case; tail outcomes carry wider variance under FAA reauthorization delays or accelerated 100LL avgas phase-out enforcement. Forecasts reflect documented assumptions regarding certification timeline compression and southwestern hangar construction permitting. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft
Vietnam Business Jets and Helicopters Market
Aircraft
Winglets Market
Aircraft
US Business Jet Market
Aircraft
Fixed Wing Turbine Aircraft Market
Aircraft
Commercial Aircraft Overhead Stowage Bins Market
Aircraft
Japan Aviation Market
Aircraft
Asia-Pacific Light and Very Light Jets Market
Aircraft
North America Light and Very Light Jets Market
Aircraft
Aircraft Window Frame Market
Aircraft
United States Aerospace and Defense Market
Aircraft
North America Business Jet Market
Aircraft
Helicopter Flight Management System Market
Aircraft
Commercial Aerospace Market
Aircraft
Strategic Bomber Market
Aircraft
Aircraft Galley Equipment Market
Aircraft
Wireless in-Flight Entertainment Market