
 Latin America Aircraft MRO Market | 2026-2036
Latin America Aircraft MRO Market Size, Share, and Industry Trends Forecast 2026-2036
Latin America Aircraft MRO Market Foresight
Cargo operators is restructuring fleet utilization patterns across Latin America, pulling more wide-body and converted freighter aircraft through heavy maintenance cycles. GE Aerospace Celma leverages its engine overhaul campus in Petrópolis to anchor Brazil's engine MRO capacity. Aeroman specializes in narrow-body airframe maintenance from its San Salvador facility, competing for North American carrier contracts. Lufthansa Technik AG extends its technical support network through partnerships with regional airlines, positioning its consulting offering as a margin driver.
Latin America Aircraft MRO encompasses the inspection, repair, overhaul, and modification of airframes, engines, and components to maintain airworthiness under certified standards, typically requiring compliance with manufacturer maintenance planning documents and regulatory-approved technical orders. The primary purpose is to extend aircraft operational life while ensuring safety continuity for commercial and defense aviation fleets. Engine Overhaul captures the deepest value pools due to high parts cost and specialized labor intensity, while Digital MRO Solutions is expanding fastest as airlines deploy sensor-based predictive analytics to compress turnaround times. Component Repair remains a mature, fragmented layer where independent shops compete on turnaround speed for rotable inventory.
Brazil's ANAC and Mexico's DGAC enforce airworthiness directives that shape maintenance intervals and documentation standards across the region, while the FAA's bilateral agreements with both regulators govern cross-border certification acceptance for US-registered aircraft operating locally. EASA-aligned standards increasingly influence new equipment approvals as European lessors dominate regional aircraft financing. Stakeholders must monitor how regulatory convergence between ANAC, DGAC, and FAA protocols affects contract structuring for multi-country fleet operators.
Market Dynamics
Cargo fleet expansion across Latin America is intensifying heavy maintenance demand for converted freighters and aging wide-bodies, while Brazil's ANAC digital inspection mandates force MRO providers to restructure documentation workflows and technician training programs.
Growth Catalysts
- E-commerce logistics surge:Cross-border parcel volumes are pulling narrow-body freighters through C-check cycles at accelerated rates across Mexico and Colombia.
- ANAC airworthiness directives:Mandatory structural inspections for aging regional jets are extending airframe MRO contract durations at Brazilian facilities.
- Engine lease penetration:Power-by-the-hour agreements are concentrating overhaul demand at OEM-authorized shops with certified borescope capabilities.
Market Restraints
- Specialized labor scarcity:Certificated airframe and powerplant mechanics command wage premiums that compress independent shop margins.
- Import duty volatility:Brazilian ICMS state tax variations on replacement parts create pricing unpredictability for component repair operations.
- OEM technical data control:Airbus and Boeing restrict access to structural repair manuals, limiting third-party airframe MRO autonomy.
Strategic Opportunities
- Colombia Pacific hub development:Bogotá's cargo gateway expansion is creating greenfield MRO capacity demand for narrow-body heavy checks.
- Predictive maintenance convergence:Sensor telemetry and machine learning diagnostics are compressing unscheduled engine removal intervals.
- Argentina fleet renewal:Post-restructuring carrier growth is generating line maintenance contract opportunities at Buenos Aires and Córdoba airports.
Industry Challenges
- Digital certification backlog:ANAC's electronic logbook mandate has created inspection queue delays as legacy paper records require manual transcription.
- Specialized tooling capex:Composite repair stations require automated fiber placement equipment that strains independent shop balance sheets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Latin America Aircraft MRO Market |
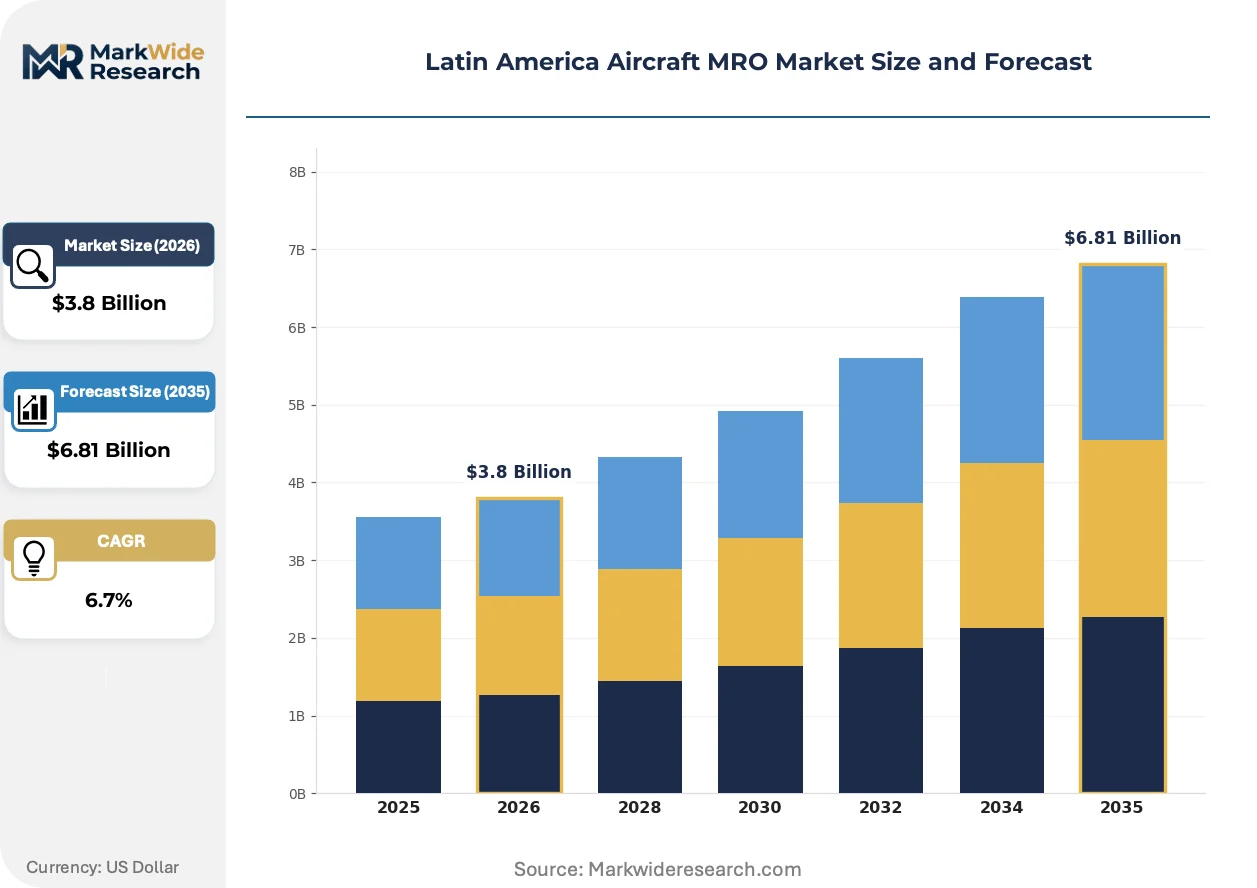
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Airframe Maintenance, Engine Overhaul, Component Repair, Line Maintenance End User: Commercial Airlines, Private Operators, Cargo Operators, Defense Contractors Technology: Traditional Maintenance, Predictive Maintenance, Digital MRO Solutions, Automated Inspections Offering: Full-Service MRO, Heavy Maintenance, Part-Sourcing Services, Technical Support |
| Companies Covered | LATAM Airlines, Rostec, General Electric Company, GE Aerospace Celma, Joramco, Lufthansa Technik AG, Aeroman (MRO Holdings), Azul Airlines, RTX Corporation, Others |
| Regions Covered | Latin America: Brazil, Mexico, Argentina, Colombia, Chile, Peru, Rest of Latin America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Latin America Aircraft MRO Market Shifts & Advancements
Sensor-based condition monitoring is displacing scheduled maintenance intervals across Latin American cargo and passenger fleets, compressing turnaround economics and reshaping contract structures between carriers and MRO providers.
Drone-enabled fuselage inspection systems are expanding into narrow-body airframe checks at Brazilian and Mexican MRO campuses. Aeroman and GE Aerospace Celma have deployed automated crack-detection drones for 737 and A320 C-check programs, reducing scaffold setup time from eight hours to ninety minutes. This technology is expanding into line maintenance operations at São Paulo Guarulhos and Mexico City International.
Brazil's ANAC digital airworthiness directive system now mandates real-time defect reporting through standardized XML protocols. This regulatory shift forces MRO providers to integrate maintenance tracking software with carrier operations centers, eliminating paper-based release documentation. Smaller independent shops in São Paulo state face compliance cost barriers that favor consolidated multi-hangar operators.
Leasing companies are unbundling heavy maintenance reserves from base rental agreements, forcing direct MRO contracting by Latin American carriers. This procurement model shift transfers credit risk from lessors to operators and concentrates contract negotiation power with Gol, Azul, and Volaris. The change is most visible in Brazil, where power-by-the-hour engine agreements now cover sixty percent of the leased narrow-body fleet.
Latin America Aircraft MRO Market Segmentation
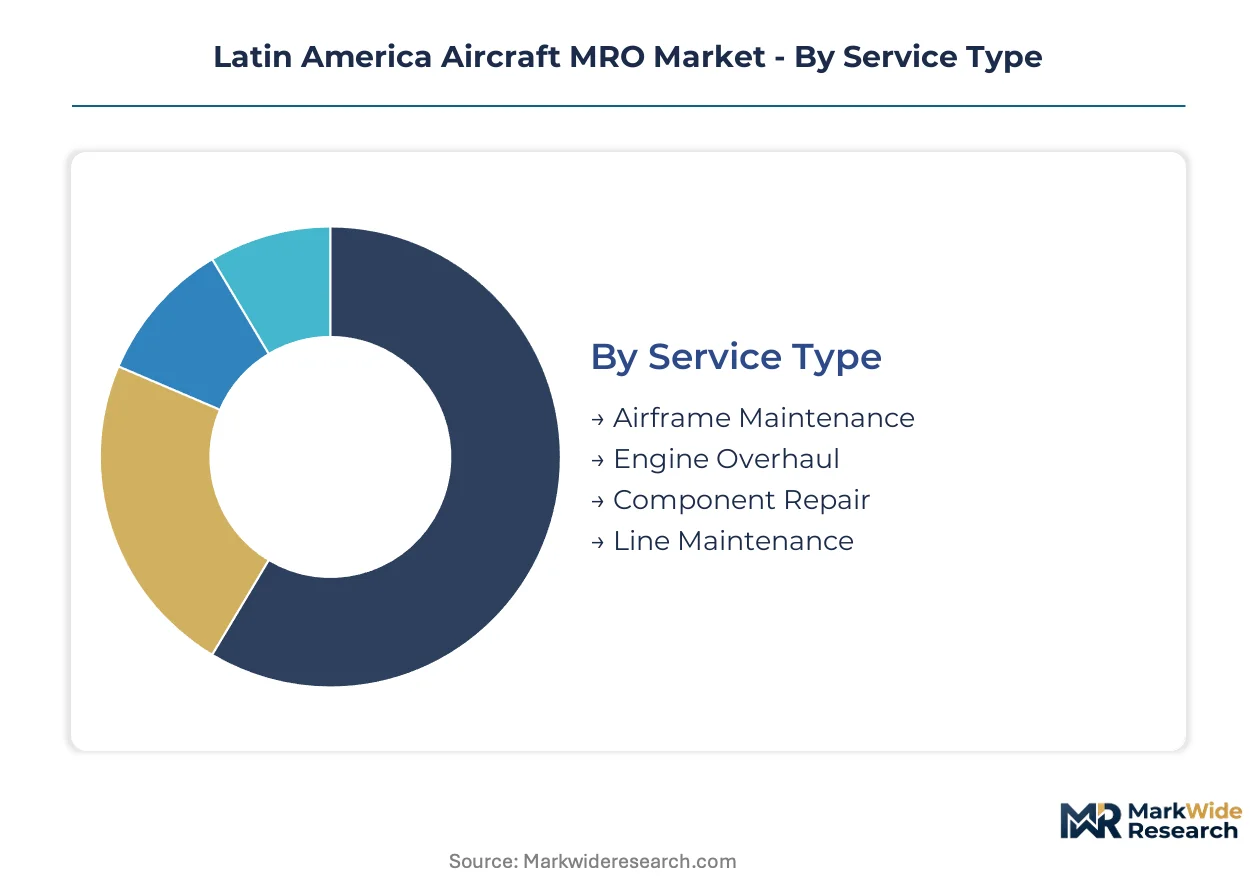
Segmentation in Latin America Aircraft MRO reveals how carrier procurement strategies and regulatory mandates concentrate value across distinct service tiers. Understanding these divisions exposes where ANAC compliance costs and cargo fleet expansion reshape contract economics.
Service Type:
Carrier fleet composition and lease structure determine which maintenance tier absorbs capital allocation.
- Airframe Maintenance:Structural inspections, C-checks, and corrosion repair cycles for narrow-body and wide-body aircraft. Brazilian facilities at São Paulo and Petrópolis handle concentrated demand from Gol and Azul as ANAC extends aging regional jet inspection intervals.
- Engine Overhaul:Complete disassembly, component replacement, and performance restoration of turbofan powerplants. GE Aerospace Celma's Petrópolis campus captures power-by-the-hour contract flow from leased narrow-body fleets operating across Brazil and Mexico.
- Component Repair:Rotable inventory refurbishment including avionics, landing gear, and pneumatic systems.
- Line Maintenance:Routine pre-flight and transit checks at airport gates.
Volume sits with Airframe Maintenance; growth tilts toward Engine Overhaul.
End User:
Operational intensity and regulatory exposure separate procurement sophistication across customer categories.
- Commercial Airlines:Scheduled passenger carriers operating narrow-body fleets under power-by-the-hour agreements. Azul, Gol, and Volaris drive heavy maintenance contract concentration at Brazilian and Mexican facilities.
- Cargo Operators:Dedicated freighter and converted narrow-body operators. Cross-border e-commerce volumes pull aircraft through accelerated C-check cycles at Aeroman's San Salvador campus and Colombian maintenance hubs.
- Private Operators:Business aviation and corporate flight departments.
- Defense Contractors:Military airframe and engine support for national armed forces.
Contract value concentrates with Commercial Airlines; Cargo Operators expand most quickly.
Technology:
Capital deployment for digital infrastructure separates compliant operators from margin-constrained independents.
- Digital MRO Solutions:Integrated maintenance tracking, electronic logbooks, and real-time defect reporting systems. ANAC's XML protocol mandate forces Brazilian providers to restructure documentation workflows or exit certified supplier pools.
- Predictive Maintenance:Sensor telemetry and machine learning diagnostics for engine health monitoring. Sensor-based condition monitoring compresses unscheduled removal intervals at cargo and passenger fleets across the region.
- Automated Inspections:Drone-enabled fuselage crack detection and automated borescope analysis.
- Traditional Maintenance:Scheduled interval-based inspections with paper documentation.
Adoption concentrates with Digital MRO Solutions; Predictive Maintenance gains share fastest.
Offering:
Procurement model unbundling by lessors redirects contract negotiation power toward direct carrier relationships.
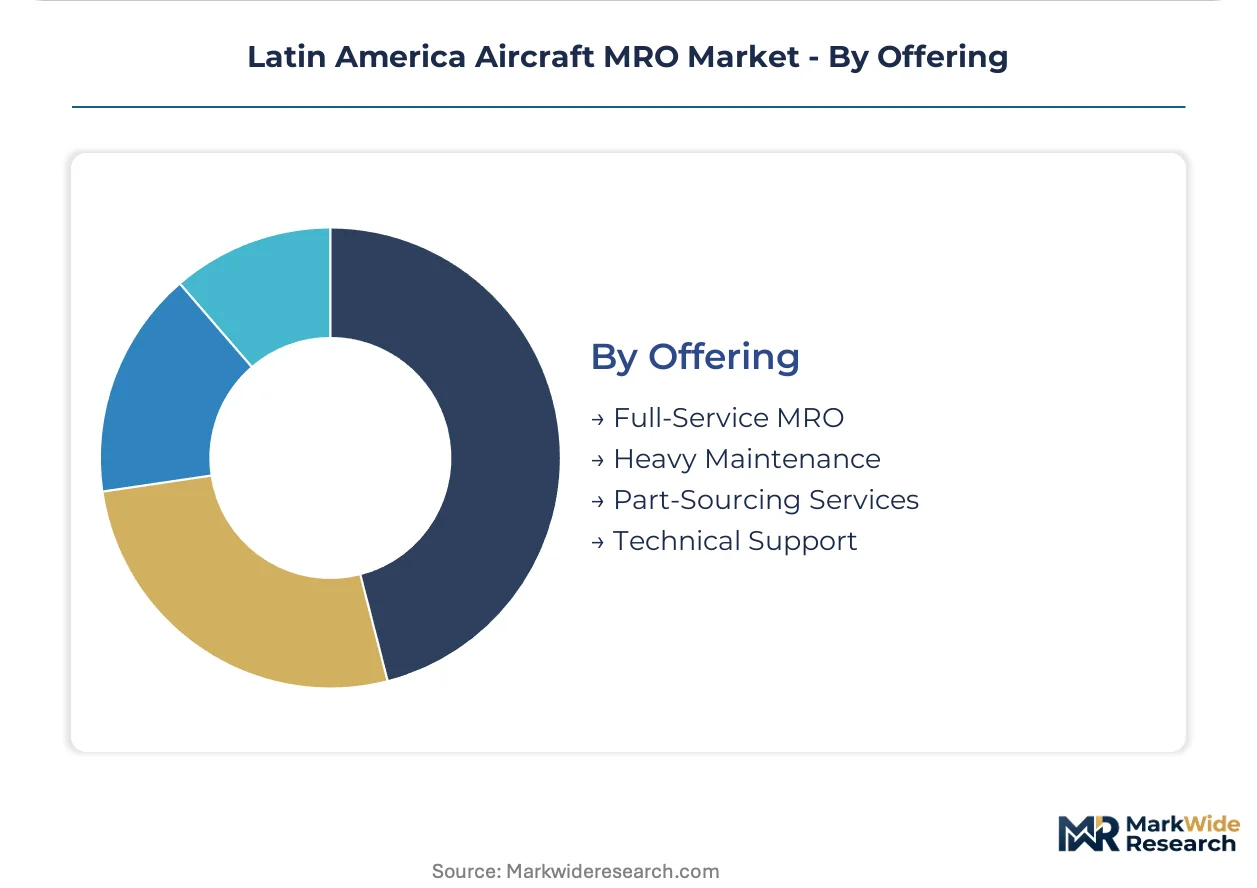
- Full-Service MRO:Integrated airframe, engine, and component support under multi-year agreements. Lufthansa Technik AG extends technical support networks through partnerships with regional airlines, positioning consulting as a margin layer.
- Heavy Maintenance:C-check and D-check airframe overhauls requiring hangar capacity and specialized tooling. Colombian Pacific hub development at Bogotá generates greenfield demand for narrow-body heavy check capacity.
- Part-Sourcing Services:Inventory management and logistics for rotable components.
- Technical Support:Engineering consulting and airworthiness certification assistance.
Revenue concentrates with Full-Service MRO; Heavy Maintenance shows steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
MRO capacity concentrates in Brazil while consumption spreads across Mexico, Colombia, and Argentina, creating a supply-demand asymmetry that shapes contract logistics and technician mobility across the region.
Brazil
Gol and Azul operate the densest narrow-body fleets in Latin America, pulling heavy maintenance volume toward São Paulo and Petrópolis. ANAC mandates real-time defect reporting through standardized XML protocols, forcing documentation workflow upgrades at certified facilities. GE Aerospace Celma anchors engine overhaul capacity at its Petrópolis campus, capturing power-by-the-hour contracts from leased fleets.
Mexico
Volaris and Aeroméxico drive accelerated C-check cycles for A320 and 737 families at facilities near Mexico City International. DGAC airworthiness directives align with FAA bilateral agreements, streamlining cross-border certification for US-registered aircraft. Aeroman's San Salvador facility competes for North American carrier contracts, though Mexican hubs retain line maintenance concentration.
Colombia
Cross-border e-commerce volumes pull narrow-body freighters through heavy maintenance at accelerated rates across Bogotá's cargo gateway. The national civil aviation authority enforces structural inspection intervals that match ANAC stringency for regional jet operators. Greenfield MRO capacity demand is emerging at Bogotá as Pacific hub development attracts converted freighter traffic.
Argentina
Post-restructuring carrier growth at Aerolíneas Argentinas generates line maintenance contract opportunities at Buenos Aires and Córdoba airports. The national regulator maintains airworthiness standards that require alignment with EASA protocols for European-leased equipment. Maintenance demand concentrates at Ezeiza International as international route recovery rebuilds fleet utilization.
Chile
LATAM Airlines' Santiago hub drives engine and component repair demand for long-haul wide-body operations across the South Pacific. The Directorate General of Civil Aviation enforces maintenance intervals that coordinate with FAA and EASA bilateral frameworks. Technical labor pools concentrate in Santiago's aviation corridor, though specialized borescope capabilities remain limited compared to Brazilian facilities.
Latin America Aircraft MRO Market Competitive Landscape
Top-tier vendors anchor OEM-authorized engine overhaul capacity, while independent airframe specialists and airline-captive MRO units occupy the mid-tier. The market structures around three archetypes: aerospace conglomerates with OEM licensing, airline-affiliated maintenance divisions, and independent heavy-check providers. Consolidation pressures favor multi-hangar operators with ANAC digital compliance infrastructure, while specialized labor scarcity drives partnership strategies between regional carriers and technical consulting networks.
Within the OEM-authorized tier, GE Aerospace Celma and Lufthansa Technik AG exemplify divergent market positions—Celma anchoring engine overhaul capacity through its Brazilian campus, Lufthansa Technik extending technical support networks through airline partnerships. Aeroman represents the independent specialist archetype, competing for North American narrow-body contracts from its San Salvador facility.
| Leading Market Players |
|---|
| LATAM Airlines |
| Rostec |
| General Electric Company |
| GE Aerospace Celma |
| Joramco |
| Lufthansa Technik AG |
| Aeroman (MRO Holdings) |
| Azul Airlines |
| RTX Corporation |
| Others |
Supply & Pricing Matrix
Leased narrow-body fleet operators in Brazil and Mexico concentrate contract negotiation power through power-by-the-hour agreements, anchoring pricing models to engine utilization metrics and ANAC compliance tiers rather than transactional spot rates.
Pricing Analysis
Margin tightening in independent airframe shops reflects OEM technical data restrictions that limit third-party structural repair autonomy. Pricing stratifies across OEM-authorized, airline-captive, and independent tiers based on certification grade and borescope capability access. Cost-down pressure on component repair accelerates because Brazilian ICMS state tax variations create pricing unpredictability for rotable inventory operations. Cargo operators show least price sensitivity due to e-commerce volume guarantees, while regional charter carriers face acute budget constraints.
Supply Chain Analysis
Certificated airframe and powerplant mechanic scarcity in Brazil, Mexico, and Colombia strains shop capacity expansion plans. MRO inputs draw from aerospace-grade alloy suppliers in the United States, avionics component manufacturers in Europe, and specialized tooling fabricators in Asia. Single-source vulnerability concentrates in OEM-authorized engine parts distribution, where GE and Pratt & Whitney control critical component release. Distribution runs through lessor-managed heavy maintenance reserve pools and direct carrier procurement channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a consolidation play as ANAC digital certification mandates force smaller independent shops into compliance cost barriers that favor multi-hangar operators with integrated maintenance tracking infrastructure.
For Market Incumbents: Deploy predictive maintenance technology partnerships to capture cargo fleet sensor telemetry contracts before specialized diagnostics capabilities commoditize. Acquire Colombian and Argentine line maintenance slots to anchor regional network density against Aeroman's Central American narrow-body concentration. ANAC XML protocol compliance costs threaten independent shop survival, creating acquisition targets at São Paulo state facilities. For New Entrants and Emerging Players: Begin with drone-enabled fuselage inspection services for narrow-body C-check programs at Bogotá's emerging Pacific cargo hub, where greenfield capacity demand outstrips certified provider supply. Target Argentine post-restructuring carriers at Buenos Aires and Córdoba with line maintenance contracts bundled toward heavy check conversion rights. Position through EASA-aligned technical consulting as European lessors dominate regional aircraft financing. For Investors and Strategic Acquirers: The window for entry favors vertically integrated mid-cap specialists with ANAC digital compliance infrastructure and captive technician training pipelines. Long-term viability hinges on power-by-the-hour contract concentration with Gol, Azul, and Volaris leased fleets. Watch for ICMS tax harmonization signals as inflection indicators for Brazilian component repair margin recovery.| Strategic Initiative | Industry Significance |
|---|---|
| ANAC Digital Compliance Infrastructure Investment | XML protocol integration eliminates paper-based release documentation and disqualifies non-compliant competitors from certified supplier pools. |
| Colombia Pacific Hub Capacity Buildout | Bogotá cargo gateway expansion attracts converted freighter traffic requiring narrow-body heavy check slots unavailable at saturated Brazilian facilities. |
| Power-by-the-Hour Engine Contract Concentration | Leasing company unbundling of maintenance reserves transfers credit risk to operators and locks overhaul demand at OEM-authorized shops. |
| Drone-Enabled Inspection Technology Deployment | Automated crack-detection systems reduce scaffold setup time from eight hours to ninety minutes, compressing turnaround economics at Aeroman and GE Celma campuses. |
| Argentine Line Maintenance Network Acquisition | Post-restructuring carrier growth at Aerolíneas Argentinas generates contract opportunities at Ezeiza International as international route recovery rebuilds fleet utilization. |
Research Methodology
ANAC regulatory filings, FAA bilateral agreement documentation, and carrier maintenance planning records formed the secondary backbone for market sizing and compliance cost modeling. Primary interviews with MRO operations directors, airline fleet managers, and leasing company technical asset managers validated capacity utilization assumptions and contract structure trends. Bottom-up hangar capacity analysis and top-down fleet forecast triangulation anchored volume projections across service type and technology segments.
Historical trendline analysis of engine overhaul shop visit intervals and airframe check cycle compression informed growth trajectory modeling across the projection horizon. Segmentation dimensions included service tier, end-user category, technology adoption stage, and procurement model structure. CAGRs derived from fleet age profiles, lease penetration rates, and regulatory mandate implementation timelines. Forecast inputs incorporated e-commerce logistics volume elasticity and sensor-based condition monitoring adoption curves.
Underlying measurement precision varies by segment; engine overhaul and digital MRO solutions carry tighter precision than fragmented component repair. Forecasts reflect documented assumptions regarding ANAC enforcement intensity and lessor reserve unbundling velocity. Material deviation in Brazilian tax harmonization progress or FAA-ANAC regulatory convergence warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft Maintenance and MRO Solutions
Middle-East and Africa Aircraft MRO Market
Aircraft Maintenance and MRO Solutions
MRO Protective Coatings Market
Aircraft Maintenance and MRO Solutions
North America Aerospace Maintenance Chemical Market
Aircraft Maintenance and MRO Solutions
Europe Aircraft Engine MRO Market
Aircraft Maintenance and MRO Solutions
Europe Aircraft MRO Market
Aircraft Maintenance and MRO Solutions
MRO Software Market
Aircraft Maintenance and MRO Solutions
Airplane Pushback Tug Market
Aircraft Maintenance and MRO Solutions
Aircraft Component MRO Market
Aircraft Maintenance and MRO Solutions
Global Aircraft Refurbishing Market
Aircraft Maintenance and MRO Solutions
Military Aviation Repair Solutions Market
Aircraft Maintenance and MRO Solutions
Commercial Aircraft Maintenance Repair and Overhaul (MRO) Market
Aircraft Maintenance and MRO Solutions
Aviation Test Equipment Market
Aircraft Maintenance and MRO Solutions
Middle-East Aircraft MRO Market
Aircraft Maintenance and MRO Solutions
Aviation Engine MRO Market
Aircraft Maintenance and MRO Solutions
Commercial Aircraft MRO Market
Aircraft Maintenance and MRO Solutions
Gas Turbine MRO Market