
 Latin America Commercial Aircraft Market | 2026-2036
Latin America Commercial Aircraft Market Size, Share, and Industry Trends Forecast 2026-2036
Latin America Commercial Aircraft Market Foresight
Power-by-the-hour maintenance contracts is realigning how airlines acquire and budget for fleet assets across Latin America. Airbus SE leverages its regional service network to lock in long-term aftermarket revenue with Mexican and Colombian flag carriers. Embraer SA anchors the regional jet segment through its São José dos Campos manufacturing complex and deep ties to Azul and Sky Airline. Boeing competes on widebody positioning for premium long-haul routes connecting São Paulo to Madrid and Miami.
Latin America commercial aircraft encompasses fixed-wing jet and turboprop platforms certified for passenger and cargo operations above 5,700 kg maximum takeoff weight, typically constructed from aluminum-lithium alloys and carbon-fiber-reinforced polymer composites to optimize fuel burn on thin routes. These assets serve the primary commercial purpose of connecting secondary cities across the Andes and Amazon basins where surface infrastructure remains underdeveloped. Commercial jets dominate current order backlogs as LATAM and Gol prioritize single-aisle replacements, while regional aircraft retains structural importance for Bolivia's and Ecuador's mountain airports with short runways. Turboprop demand within the powerplant type category shows renewed interest as fuel-price volatility prompts reassessment of sub-500 nautical mile economics.
Brazil's ANAC and Mexico's DGAC enforce overlapping airworthiness and emissions protocols that elevate compliance costs for non-compliant legacy fleets, while EASA bilateral agreements facilitate European-manufactured aircraft entry without redundant certification. Argentina's ANAC and Chile's DGAC maintain convergent standards that simplify cross-border lessor transitions but restrict rapid import of older-generation equipment. Stakeholders must monitor how ANAC's advancing noise-stage requirements and DGAC's anticipated sustainable aviation fuel blending mandates reshape residual value curves and fleet retirement timing across the region's leasing portfolios.
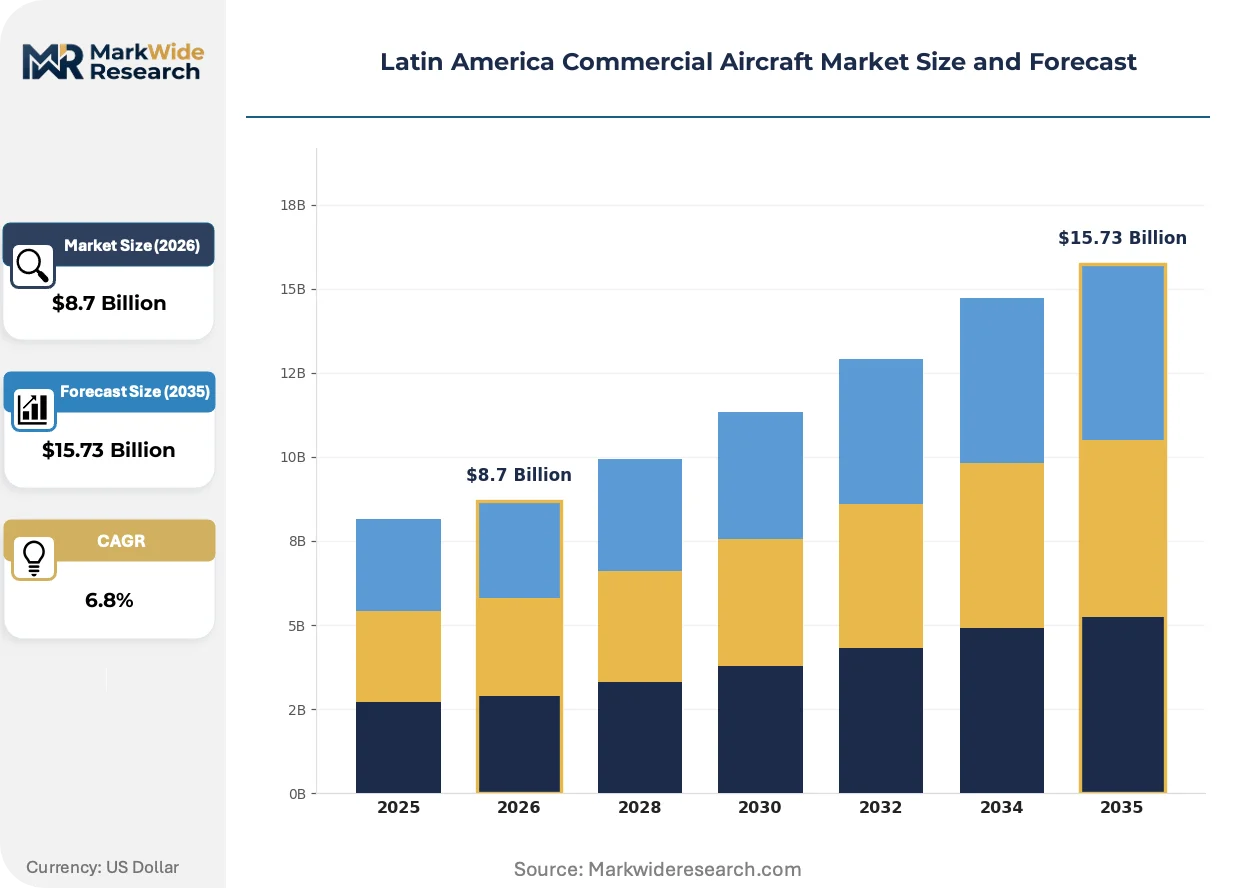
Market Dynamics
Power-by-the-hour maintenance contracts are restructuring how Latin American airlines acquire and budget for fleet assets, shifting capital allocation from upfront acquisition toward lifecycle cost management and locking in long-term aftermarket revenue streams for regional service providers.
Growth Catalysts
- ANAC Emissions Standards:Brazil's advancing noise-stage requirements and fuel-efficiency mandates are accelerating retirement of older-generation powerplants and redirecting procurement criteria toward newer narrowbody platforms.
- Low-Cost Carrier Expansion:Brazilian and Mexican budget airlines are scaling narrowbody fleets to capture rising leisure travel demand across the southeastern corridor anchored by São Paulo-Guarulhos hub expansion.
- Carbon-Fiber Composites:Airframe manufacturers are incorporating aluminum-lithium alloys and carbon-fiber-reinforced polymers to optimize fuel burn on thin Andean and Amazon basin routes where surface infrastructure remains underdeveloped.
Market Restraints
- Jet Fuel Price Volatility:Sub-500 nautical mile route economics face persistent pressure from fluctuating aviation fuel costs, prompting reassessment of turboprop versus jet operating models.
- Overlapping Compliance Costs:Brazil's ANAC and Mexico's DGAC enforce intersecting airworthiness and emissions protocols that elevate certification expenses for legacy fleet operators seeking cross-border lessor transitions.
- Mountain Airport Limitations:Bolivia's and Ecuador's high-altitude short-runway facilities impose structural operational constraints that restrict viable aircraft types and compress yield potential on regional segments.
Strategic Opportunities
- Sustainable Aviation Fuel Mandates:DGAC's anticipated SAF blending requirements will reshape residual value curves and create early-mover advantages for carriers with modernized fleets positioned for compliance.
- Secondary City Connectivity:Underpenetrated Andean secondary markets present white space for regional jet deployment on routes where road and rail infrastructure gaps persist.
- EASA Bilateral Pathways:European-manufactured aircraft entry facilitated by bilateral agreements avoids redundant certification, streamlining lessor portfolio rotations across Argentina's ANAC and Chile's DGAC jurisdictions.
Industry Challenges
- Specialized Maintenance Labor:Powerplant overhaul and composite repair capabilities concentrate in São José dos Campos and select Mexican MRO clusters, creating geographic skill scarcity for distributed fleet operations.
- Cross-Border Certification Alignment:Convergent but non-identical standards between Argentina's ANAC and Chile's DGAC complicate rapid fleet repositioning and extend transition timelines for leased assets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Latin America Commercial Aircraft Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Aircraft Type: Commercial Jets, Regional Aircraft, Cargo Planes, Business Jets Manufacturer: Boeing, Airbus, Embraer, Bombardier Usage Type: Scheduled Flights, Charter Services, Cargo Transport, VIP Transport Powerplant Type: Turbofan, Turboprop, Electric, Hybrid |
| Companies Covered | Airbus SE, The Boeing Company, Embraer SA, ATR, Rostec, COMAC, United Aircraft Corporation, Lockheed Martin Corporation, Textron Inc., Others |
| Regions Covered | Latin America: Brazil, Mexico, Argentina, Colombia, Chile, Peru, Rest of Latin America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Latin America Commercial Aircraft Market Shifts & Advancements
Technological, regulatory, and procurement forces are converging to reshape fleet composition and ownership structures across Latin American aviation. These shifts favor operational flexibility over asset ownership and environmental compliance over legacy platform longevity.
Advanced turboprop architectures are consolidating sub-regional route economics as fuel-price volatility prompts reassessment of sub-500 nautical mile operations. Colombian and Peruvian regional carriers are accelerating adoption of next-generation turboprop platforms for thin Andean routes. This technology is consolidating market share in segments previously served by aging regional jets, compressing the viable operating envelope for 50-seat jet equipment.
ANAC's advancing noise-stage requirements and DGAC's emissions protocols are tightening operational parameters for non-compliant legacy fleets. These overlapping Brazilian and Mexican standards are elevating compliance costs and accelerating retirement timelines for older-generation narrowbodies. Carriers operating across both jurisdictions are prioritizing newer powerplants to avoid segmented fleet complexity and residual value degradation.
Airlines are unbundling heavy maintenance from ownership, with Mexican and Colombian flag carriers favoring long-term service agreements over captive MRO investment. This procurement evolution is transferring balance-sheet risk to OEM-affiliated service networks and concentrating aftermarket revenue with regional hub facilities. The shift is most visible in Brazil's southeastern corridor where São Paulo-Guarulhos anchoring carriers are outsourcing powerplant management to specialized providers.
Latin America Commercial Aircraft Market Segmentation
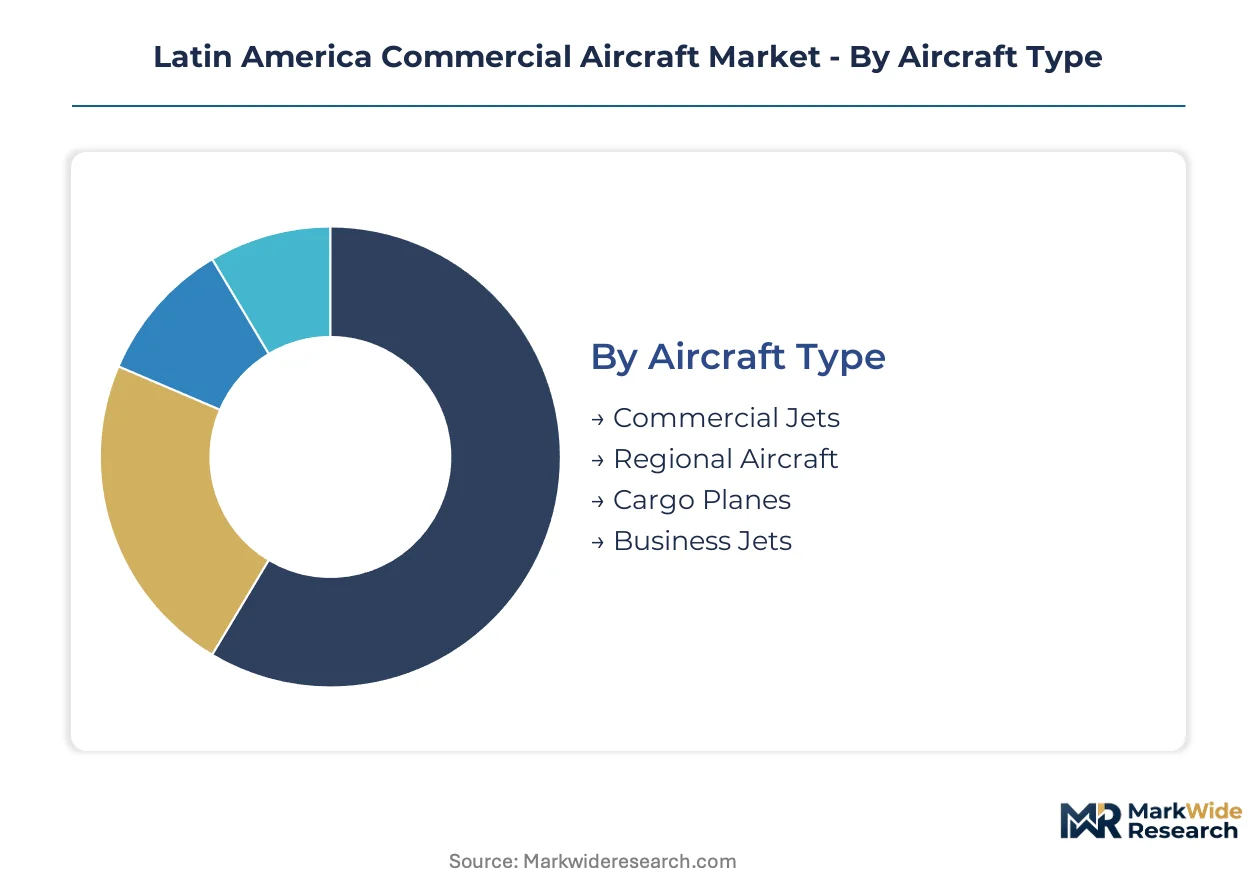
Fleet composition across Latin America reflects divergent route economics, from thin Andean corridors to dense southeastern Brazil trunk markets. Procurement patterns cluster around operational flexibility, with carriers prioritizing platforms that navigate regulatory overlap between ANAC and DGAC jurisdictions.
Aircraft Type:
Standardization dominates high-volume segments, while customization persists in specialized mountain operations and executive configurations.
- Commercial Jets:Narrowbody platforms certified above 5,700 kg maximum takeoff weight anchor fleet renewal programs at São Paulo-Guarulhos and Rio de Janeiro-Galeão. Brazilian and Mexican low-cost carriers concentrate orders here to capture leisure travel expansion across the southeastern corridor, though ANAC emissions standards accelerate retirement timelines for older-generation powerplants.
- Regional Aircraft:Embraer-built platforms from the São José dos Campos complex serve Bolivia's and Ecuador's high-altitude short-runway facilities where jet performance degrades. Azul and Sky Airline anchor demand, with residual value curves tightening as composite repair capabilities concentrate in select MRO clusters.
- Cargo Planes:Converted narrowbody freighters dominate e-commerce trunk routes from Mexico City to regional distribution hubs.
- Business Jets:VIP configurations serve São Paulo-Miami premium corridors with specialized completions from Brazilian modification centers.
Leading the category by volume: Commercial Jets. Expanding most quickly: Regional Aircraft.
Manufacturer:
Supply concentration shapes aftermarket access and residual value stability across leasing portfolios.
- Boeing:Widebody positioning for São Paulo-Madrid and São Paulo-Miami long-haul premium routes dominates the manufacturer's regional footprint. LATAM's fleet decisions anchor demand, though power-by-the-hour maintenance contracts transfer balance-sheet risk to specialized service networks.
- Airbus:Single-aisle replacements at Gol and Volaris leverage the manufacturer's regional service network for long-term aftermarket revenue capture. Colombian and Mexican flag carriers favor these platforms for DGAC compliance pathways.
- Embraer:São José dos Campos production anchors the regional jet segment with deep carrier ties across Brazil, Colombia, and Chile.
- Bombardier:Legacy regional platforms persist in secondary Andean markets where replacement cycles lag primary hubs.
Highest aftermarket revenue capture: Airbus. Steepest fleet renewal pressure: Boeing.
Usage Type:
Operational model selection determines capital structure, with scheduled operators favoring ownership and charter services preferring lease flexibility.
- Scheduled Flights:Network carriers and low-cost operators across Brazil and Mexico anchor capacity deployment at São Paulo-Guarulhos and Mexico City hubs. ANAC and DGAC emissions protocols reshape procurement criteria toward newer-generation narrowbodies with superior fuel burn on thin routes.
- Charter Services:Seasonal leisure demand from Argentine and Colombian vacation markets drives turboprop utilization for sub-500 nautical mile segments where road infrastructure gaps persist. Operators favor power-by-the-hour contracts to manage utilization volatility.
- Cargo Transport:E-commerce growth concentrates freighter demand on Mexico City-Guadalajara-Bogotá triangle routes.
- VIP Transport:Corporate shuttle services link São Paulo financial centers to secondary extraction sites in Brazil's interior.
Dominant revenue share: Scheduled Flights. Fastest margin compression: Charter Services.
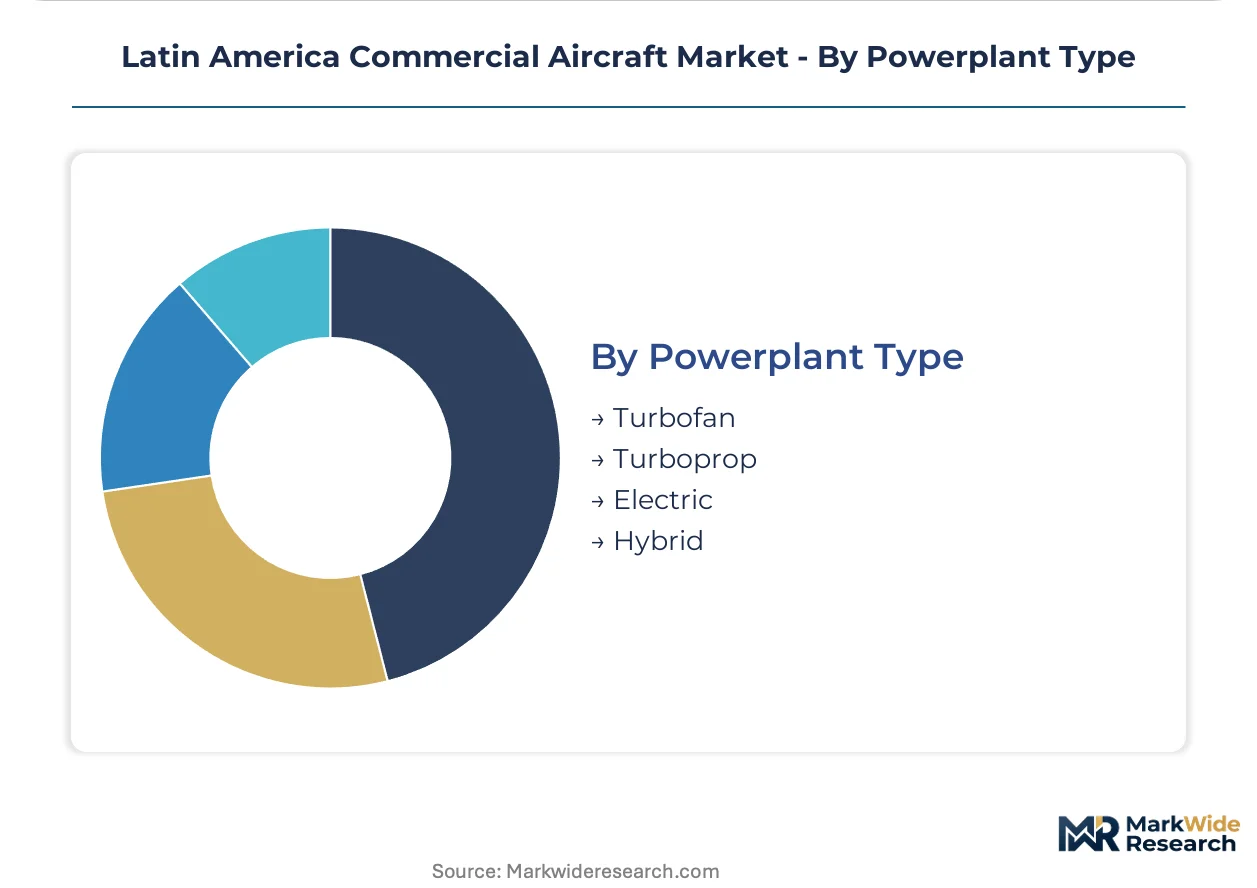
Powerplant Type:
Fuel-price volatility and regulatory compliance timelines drive technology selection across route networks.
- Turbofan:High-bypass architectures dominate commercial jet backlogs as LATAM and Gol prioritize single-aisle replacements. ANAC's advancing noise-stage requirements accelerate retirement of older-generation equipment, redirecting procurement toward newer powerplants with carbon-fiber composite integration.
- Turboprop:Next-generation platforms gain share on Colombian and Peruvian Andean routes where fuel-price volatility prompts reassessment of sub-500 nautical mile economics. These assets displace aging 50-seat regional jets at carriers serving Bolivia's and Ecuador's mountain airports.
- Electric:Experimental certification pathways progress through ANAC and DGAC frameworks for sub-19 seat urban air mobility prototypes.
- Hybrid:Technology demonstrators target regional route segments below 300 nautical miles for entry into service.
Current fleet dominance: Turbofan. Gaining share fastest: Turboprop.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
São Paulo-Guarulhos anchors fleet deployment across Latin America's southeastern aviation corridor, with narrowbody procurement concentrating at this hub as Brazilian low-cost carriers scale capacity to capture leisure travel expansion.
Brazil
Gol and Azul drive narrowbody and regional jet demand respectively, with Azul maintaining deep ties to Embraer's São José dos Campos manufacturing complex. ANAC's advancing noise-stage requirements and fuel-efficiency mandates accelerate retirement of older-generation powerplants. São Paulo-Guarulhos and Rio de Janeiro-Galeão concentrate hub expansion activity where carriers outsource powerplant management to specialized MRO providers.
Mexico
Volaris and Viva Aerobus expand single-aisle fleets to capture cross-border leisure flows and domestic trunk route growth. DGAC emissions protocols and anticipated sustainable aviation fuel blending mandates reshape residual value curves for leased assets. Mexico City International anchors scheduled flight capacity, with Guadalajara and Monterrey serving as secondary distribution nodes for e-commerce cargo operations.
Argentina
Aerolíneas Argentinas maintains fleet renewal pressure amid macroeconomic constraints, prioritizing newer-generation narrowbodies for Buenos Aires hub operations. ANAC standards converge with Chilean DGAC protocols to simplify cross-border lessor transitions. Seasonal leisure demand from Argentine vacation markets drives turboprop utilization for sub-500 nautical mile segments to Patagonian and coastal destinations.
Chile
Sky Airline anchors regional jet demand through Embraer ties, serving high-altitude short-runway facilities across the Andes where jet performance degrades. DGAC standards maintain convergent alignment with Argentine ANAC regulations. Santiago's Arturo Merino Benítez International concentrates premium long-haul connectivity to Madrid and Miami, with secondary city turboprop links penetrating underdeveloped surface infrastructure in the northern mining regions.
Colombia
Avianca and LATAM Colombia prioritize single-aisle replacements for Bogotá-El Dorado hub expansion, while regional carriers accelerate next-generation turboprop adoption for thin Andean routes. Colombian DGAC frameworks align with broader Latin American emissions trajectories. Medellín and Cali secondary markets present white space for regional jet deployment where road and rail infrastructure gaps persist across mountainous terrain.
Latin America Commercial Aircraft Market Competitive Landscape
Capital-heavy airframe producers compete with asset-light service integrators across Latin America's commercial aircraft ecosystem. The market structure consolidates around three OEMs controlling narrowbody and regional jet supply, with aftermarket revenue concentrating in specialized MRO networks. Strategic archetypes include full-service platform manufacturers, regional jet specialists, and power-by-the-hour service providers. Competitive moves center on long-term maintenance contract capture and fleet standardization campaigns targeting multi-carrier lessor portfolios.
Within the full-service tier, Airbus SE and The Boeing Company occupy positions as the dominant narrowbody and widebody suppliers respectively, with Boeing anchoring premium long-haul positioning and Airbus leveraging regional service networks for aftermarket capture. Embraer SA exemplifies the regional specialist archetype through its São José dos Campos manufacturing concentration and carrier ties across Brazil, Colombia, and Chile. These three entities represent the core competitive anchors shaping fleet composition and procurement criteria across ANAC and DGAC jurisdictions.
| Leading Market Players |
|---|
| Airbus SE |
| The Boeing Company |
| Embraer SA |
| ATR |
| Rostec |
| COMAC |
| United Aircraft Corporation |
| Lockheed Martin Corporation |
| Textron Inc. |
| Others |
Supply & Pricing Matrix
Composite repair technicians concentrated in São José dos Campos and select Mexican MRO clusters command wage premiums that propagate through maintenance contract pricing tiers. Labor-cost differentials between these specialized hubs and distributed fleet operations widen pricing spreads across power-by-the-hour agreements.
Pricing Analysis
Yield-per-available-seat-mile performance anchors value-based pricing for narrowbody acquisitions across Brazilian and Mexican low-cost carrier fleets. Three-tier pricing structure across premium long-haul configurations, standard single-aisle platforms, and economy regional equipment reflects certification grade and after-sales bundling intensity. Cost compression in the regional jet segment is intensifying because Embraer's aftermarket capture concentrates service revenue. Charter operators exhibit highest price sensitivity due to utilization volatility, while network carriers at São Paulo-Guarulhos prioritize total cost of ownership over upfront acquisition.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale buyer demand from LATAM and Gol fleet renewal programs, bypassing distributor markups on narrowbody powerplants. Manufacturing concentration rests on Brazil's São José dos Campos complex for regional jets, Toulouse for Airbus single-aisle deliveries, and Seattle-area facilities for Boeing widebody equipment. Titanium forgings, carbon-fiber prepreg, and avionics suites draw from Japanese, European, and North American specialist suppliers. Single-source vulnerability in engine OEM aftermarket networks threatens operational continuity for carriers locked into exclusive power-by-the-hour contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Latin America commercial aircraft market sits in a technology-transition phase as next-generation turboprop architectures displace aging 50-seat regional jets on sub-500 nautical mile Andean routes.
For Market Incumbents: Anticipate residual value compression for non-compliant legacy fleets by accelerating retirement timelines ahead of ANAC's advancing noise-stage requirements. Prioritize backward integration into composite repair capabilities at São José dos Campos to capture maintenance revenue migrating from distributed operators. Defend market position through long-term power-by-the-hour contract lock-in with Mexican and Colombian flag carriers.
For New Entrants and Emerging Players: Capture white space in secondary city connectivity across Colombia's Medellín and Cali markets where road infrastructure gaps persist. Target turboprop deployment for thin Andean routes currently underserved by jet equipment. Penetrate through power-by-the-hour service partnerships that transfer balance-sheet risk from utilization-volatile charter operators.
For Investors and Strategic Acquirers: Re-rating potential sits with specialized MRO providers given DGAC's anticipated SAF blending mandates and associated fleet modernization catalysts. Long-term viability favors asset-light service integrators over capital-heavy airframe exposure. Monitor ANAC-DGAC regulatory convergence as the inflection signal for cross-border lessor portfolio rotations.
| Strategic Initiative | Industry Significance |
|---|---|
| Power-by-the-Hour Contract Expansion | Locks long-term aftermarket revenue with Mexican and Colombian flag carriers. |
| Composite Repair Capability Buildout | Captures maintenance demand concentrating in São José dos Campos clusters. |
| SAF-Ready Fleet Modernization | Positions carriers for DGAC blending mandates ahead of residual value shifts. |
| Secondary City Turboprop Deployment | Penetrates underdeveloped Andean markets where surface infrastructure gaps persist. |
| EASA Bilateral Certification Pathway | Streamlines European-manufactured aircraft entry across ANAC and DGAC jurisdictions. |
Research Methodology
Independent corroboration across fleet planning executives, MRO operations directors, and aviation regulatory specialists underwrites the qualitative findings. Primary interviews with airline procurement leads, lessor portfolio managers, and ANAC certification engineers combined with secondary validation from ANAC filings, DGAC airworthiness directives, and manufacturer order backlogs. Bottom-up triangulation across individual carrier fleet plans and top-down cross-checks against OEM delivery schedules anchor the analytical framework.
Rate-of-change decomposition across the projection horizon separates volume growth from mix-shift effects and price-escalation components. Segmentation dimensions span aircraft type, manufacturer platform, usage model, and powerplant technology across the modeling period. CAGRs derive from logistic adoption curves fitted to fleet replacement cycles and regulatory compliance timelines. Forecast inputs incorporate ANAC emissions trajectory assumptions and DGAC SAF mandate probability weights.
The model holds under stable regulatory convergence between Brazil and Mexico; deviation in bilateral agreement timelines or fuel-price volatility spikes would shift fleet renewal pacing. Forecasts reflect documented assumptions regarding low-cost carrier expansion rates and mountain airport operational constraints. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft
Search and Rescue Aircraft Market
Aircraft
Aircraft Anchoring System Market
Aircraft
Japan Aviation Market
Aircraft
North America Aircraft Manufacturing Market
Aircraft
Aircraft Exterior Mounts Market
Aircraft
Vietnam Business Jets and Helicopters Market
Aircraft
Commercial Aircraft Overhead Stowage Bins Market
Aircraft
Global Aircraft De-Icing Market
Aircraft
Aero Wing Market
Aircraft
Aircraft Mounts Market
Aircraft
Drone Turbojet Engine Market
Aircraft
Middle-East and Africa Freighter Aircraft Market
Aircraft
Middle-East and Africa Commercial Aircraft Market
Aircraft
Autonomous Aircraft Propulsion Systems Market
Aircraft
North America Aircraft Band Clamps Market
Aircraft
Europe Light and Very Light Jets Market